
 Global Ballast Water Treatment Systems Market | 2026-2036
Global Ballast Water Treatment Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ballast Water Treatment Systems Market Analysis
Shipyard-direct procurement is reconfiguring how ballast water treatment systems reach vessel owners. Alfa Laval leverages its marine aftermarket network to sustain service revenue across installed fleets. Wärtsilä anchors its position through integrated automation packages that bundle treatment controls with engine management. Optimarin competes on compact footprint designs that fit crowded engine rooms on older vessels.
Ballast water treatment systems are engineered assemblies that combine filtration, disinfection, and monitoring subsystems to neutralize aquatic organisms carried in ship ballast tanks, typically achieving biological efficacy standards through UV irradiation at specified dosage levels or chemical dosing at controlled concentrations. Physical treatment technologies dominate current retrofit demand where space constraints favor modular skid-mounted UV and filtration units over bulkier chemical storage systems. Hybrid technology configurations are capturing margin pools in new-build contracts as shipyards specify multi-barrier approaches that reduce single-point compliance risk across varying port-state discharge requirements.
The International Maritime Organization's Ballast Water Management Convention, administered by flag states and enforced through port state control inspections under the Paris MoU and Tokyo MoU frameworks, mandates type-approved system installation and operational compliance. The US Coast Guard maintains separate approval standards that exclude some IMO-certified systems from US waters, fragmenting certification requirements for global operators. Stakeholders must monitor divergence between IMO revision cycles and unilateral national standards that could strand installed equipment or trigger replacement demand.
Market Dynamics
Retrofit installation deadlines under the IMO Ballast Water Management Convention are compressing demand into concentrated procurement windows, forcing shipyards and system integrators to scale capacity rapidly while managing certification bottlenecks across fragmented port-state requirements.
Growth Catalysts
- IMO Convention Phase-In Schedules:Mandatory installation timelines for existing vessels are creating predictable replacement cycles that system manufacturers can plan production around.
- UV Dosage Optimization:Advancements in medium-pressure lamp efficiency are reducing energy draw and footprint, expanding retrofit feasibility on older vessels with constrained engine room space.
- China Shipbuilding Concentration:New-build orders at yards in Shanghai, Dalian, and Guangzhou are embedding treatment systems at hull construction stage rather than post-delivery retrofit.
Market Restraints
- Titanium Electrode Supply Concentration:Electrochlorination systems depend on specialized titanium anode supply chains concentrated in Japanese and German specialty metal processors, creating input cost volatility.
- USCG Type Approval Exclusion:Systems certified only under IMO guidelines face market access barriers in US waters, fragmenting product portfolios and raising compliance costs for global operators.
- Chemical Storage Footprint Requirements:Active substance systems require bulk tankage that conflicts with space constraints on Panamax and Handysize bulk carriers, limiting addressable retrofit demand.
Strategic Opportunities
- Indonesia Fleet Modernization:The archipelago's aging domestic shipping fleet presents underpenetrated retrofit potential as port state control enforcement tightens under regional MoU frameworks.
- Remote Monitoring Integration:Convergence of UV dosage sensors with satellite telemetry enables predictive maintenance contracts and compliance documentation automation for flag state audits.
- EU Green Deal Alignment:Treatment system energy efficiency metrics are increasingly qualifying vessels for preferential port fee structures under EU port authority sustainability incentive programs.
Industry Challenges
- Marine Electrical Technician Scarcity:UV system commissioning and troubleshooting requires specialized high-voltage marine electrical skills that shipyard labor pools in Vietnam and Philippines lack at sufficient scale.
- Legacy Ballast Pump Integration:Retrofit installations must interface with aging pump control architectures from the 1990s, extending commissioning timelines and raising warranty exposure for system integrators.
- Port State Control Documentation Variance:Inspectors under Tokyo MoU and Paris MoU apply divergent evidentiary standards for operational compliance, creating administrative burden for multi-jurisdiction operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ballast Water Treatment Systems Market |
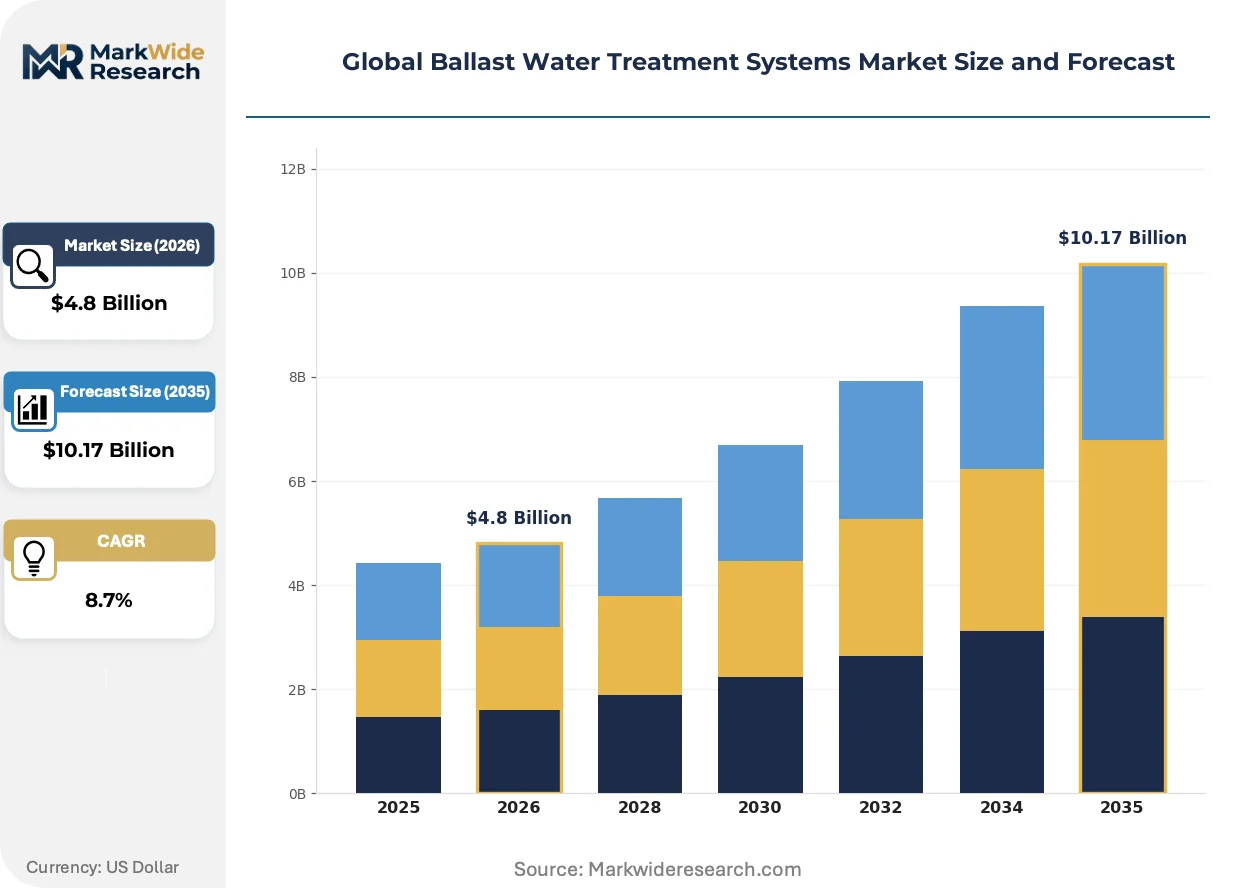
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: UV Systems, Chemical Treatment, Filtration Systems, Electrochemical Treatment Technology: Physical, Biological, Hybrid, Advanced Oxidation End User: Commercial Vessels, Fishing Boats, Cargo Ships, Offshore Support Installation: Retrofit, New Build, Onboard Systems, Land-Based Solutions |
| Companies Covered | Optimarin, Panasia, Alfa Laval, Mitsubishi Heavy Industries, NEI Treatment Systems, Wärtsilä, Techcross, Headway Technology Group, Veolia Water Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ballast Water Treatment Systems Market Emerging Trajectories
Equipment manufacturers are pivoting from standalone treatment units toward integrated vessel water management platforms that combine ballast, bilge, and scrubber washwater functions under unified control architectures.
Advanced oxidation process technology is migrating from experimental pilot status to commercial deployment on cruise vessels and expedition ships. Norwegian and Finnish yards are specifying these systems for new-build polar-class vessels facing stringent Antarctic Treaty discharge protocols. The shift is compressing market space for conventional UV-only configurations in premium segments while opening service revenue streams for consumables-based maintenance contracts.
The US Coast Guard's amended ballast water discharge standards are forcing recertification of installed systems that previously met only IMO criteria. Shipowners operating US-flagged vessels or calling regularly at US ports must now budget for system replacement or upgrade rather than grandfathered compliance. This regulatory friction is redirecting procurement decisions toward dual-certified systems even where initial cost premiums exceed single-approval alternatives.
Charter party clauses are increasingly mandating treatment system operational readiness as a condition of hire. Greek and Singapore-based ship managers report that major commodity traders now embed compliance verification into pre-fixture questionnaires, displacing price-only competition with total-cost-of-ownership calculations. The behavioral shift is most visible in Capesize bulk carrier segments where spot market exposure concentrates buyer leverage among a handful of trading houses.
Global Ballast Water Treatment Systems Market Segmentation
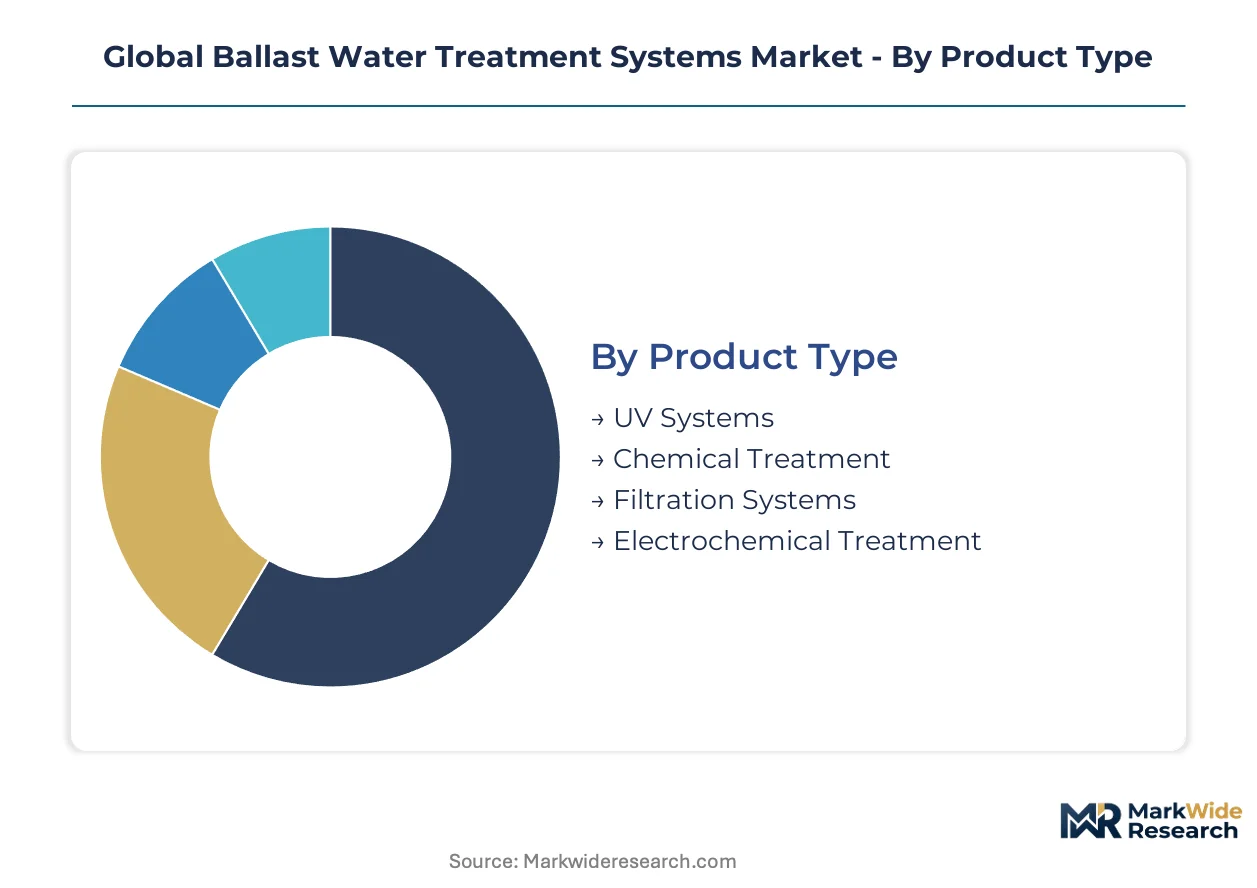
Ballast water treatment systems vary sharply in service intensity across product categories. UV installations demand lamp replacement schedules and dosage calibration contracts. Chemical systems require consumables logistics and storage safety audits that reshape vendor-customer relationships.
Product Type:
After-sales service intensity diverges dramatically across treatment chemistries and physical configurations, with consumables-based models locking in recurring revenue streams that pure hardware sales cannot replicate.
- UV Systems:Medium-pressure and low-pressure lamp arrays dominate new-build specifications at Korean and Chinese yards. Shanghai shipbuilders specify integrated UV skids with automated self-cleaning mechanisms to reduce crew maintenance burden during Pacific routes.
- Chemical Treatment:Active substance dosing with sodium hypochlorite or chlorine dioxide requires bulk tankage and residual monitoring. Panamax bulk carriers face space constraints that limit retrofit feasibility, concentrating demand on larger vessel classes with dedicated chemical storage rooms.
- Filtration Systems:Coarse and fine screen assemblies serve as primary barriers upstream of UV or chemical stages.
- Electrochemical Treatment:In-situ chlorine generation via electrolytic cells eliminates shoreside chemical logistics but demands specialized titanium electrode supply chains concentrated in Japanese and German processors.
UV Systems holds the largest share; momentum sits with Electrochemical Treatment as shipowners seek to eliminate chemical procurement complexity.
Technology:
Cost tier stratification separates proven physical methods from emerging multi-barrier approaches that command premium pricing in polar-class and cruise vessel specifications.
- Physical:Filtration and UV irradiation combinations represent the baseline compliance configuration for bulk carrier retrofits. Tokyo MoU port state control inspectors favor physical systems for their straightforward operational documentation and minimal crew training requirements.
- Biological:Deoxygenation and heat treatment methods see limited commercial deployment due to extended treatment times that conflict with rapid ballast exchange schedules at Singapore and Rotterdam hubs.
- Hybrid:Multi-barrier configurations combining filtration, UV, and chemical stages reduce single-point compliance risk. Norwegian yards specify hybrid packages for expedition vessels facing Antarctic Treaty discharge protocols.
- Advanced Oxidation:Hydroxyl radical generation through ozone or UV-peroxide combinations targets emerging contaminants beyond conventional biological efficacy standards.
Physical technology commands the installed base; Hybrid configurations are gaining share fastest in premium new-build contracts.
End User:
Application-specific operating profiles dictate system selection, with voyage patterns and port rotation frequencies determining feasible treatment windows.
- Commercial Vessels:Ferries and passenger ships with predictable schedules favor UV systems with lower operational complexity. Mediterranean operators prioritize compact footprints to preserve passenger amenity space.
- Fishing Boats:Small-tonnage vessels below IMO Convention thresholds face voluntary compliance pressure from seafood certification schemes rather than regulatory mandate.
- Cargo Ships:Dry bulk, tanker, and container fleets generate concentrated procurement volume through coordinated fleet-wide retrofit programs managed by Greek and Singapore-based ship managers.
- Offshore Support:Platform supply vessels and anchor handlers require explosion-proof certifications for UV electrical components operating in hazardous zone classifications.
Cargo Ships represent the dominant revenue pool; Offshore Support shows the steepest expansion trajectory as North Sea and Gulf of Mexico drilling activity resumes.
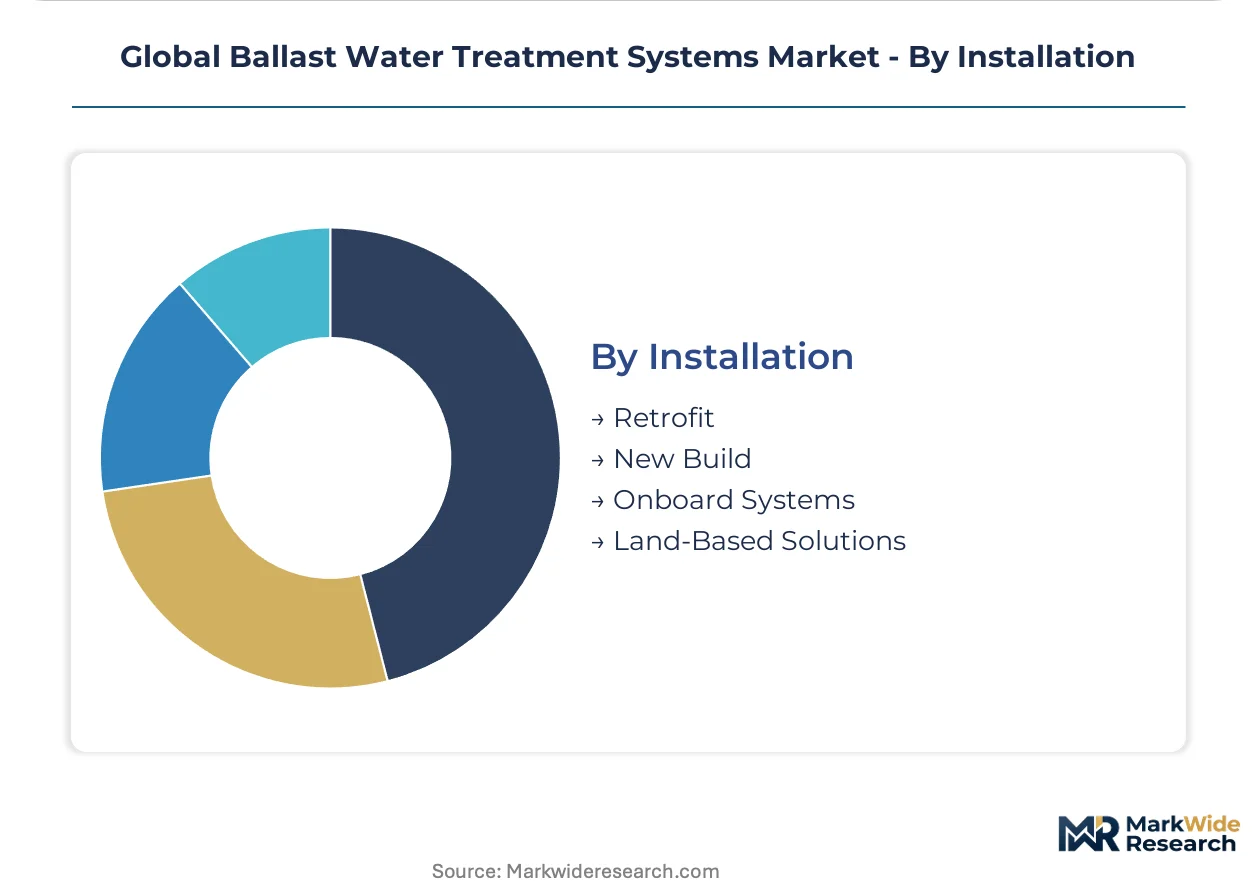
Installation:
Customer type bifurcation separates shipyard-embedded new-build demand from aftermarket retrofit urgency driven by regulatory deadline compression.
- Retrofit:Existing vessel modifications demand modular skid-mounted designs that navigate congested engine rooms on 1990s-built Panamax vessels. Vietnamese and Philippine shipyards struggle with marine electrical technician scarcity that extends commissioning timelines.
- New Build:Hull-stage integration at Chinese yards in Dalian and Guangzhou enables optimized piping runs and unified control architecture with engine management systems.
- Onboard Systems:Self-contained treatment units for vessels without permanent ballast water infrastructure.
- Land-Based Solutions:Port reception facilities and mobile treatment barges serve vessels with inoperable onboard systems during repair periods.
New Build captures margin premiums through design integration; Retrofit drives volume concentration as IMO deadline windows compress procurement into finite periods.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's ballast water reception facilities anchor European compliance infrastructure, while Singapore's Tuas megaport integrates treatment system staging into its vessel service matrix. These assets concentrate regulatory enforcement and supplier technical support across their respective hinterlands.
China
Dalian, Shanghai, and Guangzhou shipyards embed treatment systems during hull construction for new-build contracts. The Ministry of Ecology and Environment enforces port state control inspections under the Tokyo MoU framework. Yangtze River Delta clusters coordinate fleet-wide retrofit programs for domestic bulk carriers facing IMO deadline compression.
South Korea
Ulsan and Geoje shipbuilders specify UV-integrated skids with automated self-cleaning for export tankers. The Korean Register administers type-approval certification parallel to IMO standards. Busan port authorities tightened ballast water documentation requirements for transshipment vessels in 2024.
Japan
Imabari and Oshima shipyards dominate new-build integration for liquefied natural gas carriers. METI coordinates titanium electrode supply chain security for domestic electrochlorination system manufacturers. Yokohama-based classification societies influence regional technical interpretation of UV dosage calibration protocols.
United States
Gulf Coast repair yards in Houston and New Orleans handle retrofit installations for Jones Act tankers. US Coast Guard type-approval standards exclude IMO-only certified systems from US waters, fragmenting procurement decisions. Port of Long Beach sustainability incentive programs reward energy-efficient treatment configurations with preferential fee structures.
Norway
Ulstein and Vard yards specify hybrid multi-barrier systems for expedition vessels facing Antarctic Treaty discharge protocols. The Norwegian Maritime Authority enforces stringent documentation standards for polar-class operational compliance. Bergen and Stavanger clusters develop remote monitoring telemetry integration for predictive maintenance contracts.
Global Ballast Water Treatment Systems Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in filtration media, UV lamp arrays, and titanium electrode supply. The vendor base stratifies across three tiers: diversified marine engineering conglomerates with engine management integration capabilities; pure-play treatment system specialists competing on footprint optimization; and regional fabricators serving domestic fleet retrofit windows. Consolidation pressure concentrates among mid-scale specialists lacking aftermarket service networks. Dominant competitive moves include backward integration into consumables supply and technology licensing partnerships for dual IMO-USCG certification.
Among Nordic-based diversified engineering groups, Alfa Laval and Wärtsilä exemplify platform integrators that bundle treatment controls with broader vessel automation architectures. Optimarin occupies a position within the pure-play specialist tier, representing compact footprint design competition for crowded engine room retrofits. These three anchors illustrate the competitive spectrum: conglomerate-scale integration capability versus specialist agility in space-constrained installations.
| Leading Market Players |
|---|
| Optimarin |
| Panasia |
| Alfa Laval |
| Mitsubishi Heavy Industries |
| NEI Treatment Systems |
| Wärtsilä |
| Techcross |
| Headway Technology Group |
| Veolia Water Technologies |
| Others |
Supply Flow & Price Mechanics
Shipyard capacity utilization at Dalian and Guangzhou facilities is running above 85 percent, compressing procurement timelines for treatment system integrators and amplifying pricing leverage among qualified suppliers with dual IMO-USCG certification portfolios.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates dual-certified hybrid systems from IMO-only UV configurations and basic filtration skids. Price differentiation hinges on certification grade and after-sales service bundling, with premium tiers commanding substantial markups for predictive maintenance contracts. Cost compression in the standard tier is intensifying because Korean and Chinese yards are consolidating procurement volumes through framework agreements. Charter party compliance requirements have rendered economy-tier IMO-only systems virtually unsellable to US-trading fleets, making large bulk carrier operators the most price-sensitive segment while polar-class expedition vessel managers show minimal sensitivity.
Supply Chain Analysis
Contract manufacturing for UV lamp arrays concentrates at specialized facilities in Germany and Japan, with secondary assembly nodes emerging in South Korea for medium-pressure systems. Geographic supply concentration centers on Japan, Germany, and China for titanium electrodes, UV lamps, and filtration media respectively. Raw material dependencies draw from specialized borosilicate glass, rare-earth phosphors, and marine-grade titanium feedstock. Single-source vulnerability around Japanese titanium anode processors creates exposure to export licensing delays. Distribution runs through shipyard-direct channels for new-build contracts and aftermarket service networks for retrofit installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment moat where dual certification standards create switching costs that lock vessel operators into approved supplier relationships across multi-year compliance cycles.
For Market Incumbents: Harden defensive positions through backward integration into titanium electrode supply and captive UV lamp manufacturing to neutralize input cost volatility from Japanese processors. Expand certification engineering teams to accelerate parallel IMO-USCG approval pathways before regulatory divergence widens. Consolidate aftermarket service networks in Southeast Asian ship repair hubs to preempt emerging specialist competitors. For New Entrants and Emerging Players: Indonesian domestic bulk carrier retrofits represent the most penetrable entry point given enforcement tightening under Tokyo MoU frameworks and limited incumbent service presence. Mid-tier chemical system refurbishment for aging Panamax vessels offers secondary white-space where footprint constraints have excluded pure-play UV specialists. A port-authority partnership model delivering mobile treatment barges during dry-dock periods provides differentiated go-to-market access without shipyard integration requirements. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electrochemical treatment sub-segments as titanium electrode supply security demands captive smelting investments. Long-term viability favors diversified marine engineering conglomerates with engine management integration capabilities over pure-play hardware specialists lacking consumables recurring revenue. Acquisition target archetypes include regional fabricators with established shipyard relationships in Vietnam and Philippines. The signal to watch is USCG recertification volume for previously IMO-only systems as a demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | Parallel IMO-USCG approval pathways unlock access to US-flagged vessel procurement pools. |
| Backward Integration into Titanium Supply | Captive electrode manufacturing neutralizes cost volatility from Japanese specialty metal processors. |
| Remote Monitoring Platform Development | UV dosage telemetry integration enables predictive maintenance contracts with Greek and Singapore ship managers. |
| Shipyard Service Network Expansion | Dalian and Guangzhou embedded technical teams compress commissioning timelines for new-build contracts. |
| Hybrid System Technology Licensing | Multi-barrier configurations reduce single-point compliance risk for Antarctic Treaty vessel specifications. |
Methodological Framework
The analysis maps UV system configurations, electrochemical platforms, and hybrid multi-barrier designs, each validated through shipyard procurement directors, marine electrical contractors, classification society surveyors, and fleet technical managers. Primary fieldwork combined structured interviews with secondary validation against IMO type-approval databases, US Coast Guard certification records, Tokyo MoU and Paris MoU port state control inspection protocols, and customs trade data for titanium electrode and UV lamp imports. Bottom-up vessel fleet analysis triangulates against top-down shipyard order book aggregation.
Assumption sets held regulatory enforcement intensity and certification timeline divergence fixed while varying shipbuilding output, retrofit deadline compression, and titanium supply chain disruption scenarios across the projection horizon. Segmentation dimensions modeled include treatment chemistry, technology tier, vessel class, installation type, and regional regulatory cluster. CAGRs derive from installed base turnover rates and new-build penetration curves calibrated to shipyard capacity forecasts. Industry-specific inputs incorporate ballast pump integration complexity indices and marine electrical technician availability by ship repair geography.
Practitioners should monitor USCG-IMO certification divergence, titanium export licensing from Japanese processors, and charter party clause standardization for early signals of forecast revision. Quarterly review of port state control detention rates for ballast water deficiencies and shipyard order book cancellation indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Control Solutions
Gas Cleaning Technologies Market
Environmental Control Solutions
Global Flue Gas Treatment Systems Market
Environmental Control Solutions
CO2 Injector (CO2 Bubbler) Market
Environmental Control Solutions
Modular Energy Control System Market
Environmental Control Solutions
Scrubber Market
Environmental Control Solutions
Oil Water Separator Market
Environmental Control Solutions
Vapor Recovery Services Market
Environmental Control Solutions
Flue Gas Analyzers Market
Environmental Control Solutions
Electrostatic Precipitator Market
Environmental Control Solutions
Emission Control Technology Market
Environmental Control Solutions
Ozone Generator Market
Environmental Control Solutions
Enclosed Waste Gas Flares Market
Environmental Control Solutions
Residential Water Softening Systems Market
Environmental Control Solutions
North America Nitrogen Oxide Control Systems Market
Environmental Control Solutions
Flue Gas Desulfurization Systems Market
Environmental Control Solutions
Global Portable Emissions Measurement Systems (PEMS) Market