
 Global Industrial Emission Control Systems Market | 2026-2036
Global Industrial Emission Control Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Emission Control Systems Market Intelligence
A shift from procuring individual components to outsourcing complete, integrated emission control solutions is pivoting the market's supply chain dynamics. This trend favors large-scale engineering firms capable of managing complex projects. Siemens leverages its extensive portfolio in industrial automation to offer end-to-end system management. Mitsubishi Heavy Industries specializes in high-capacity systems for power generation, while Babcock & Wilcox Enterprises competes on its deep expertise in combustion technologies.
Industrial emission control systems comprise engineered technologies designed to reduce or eliminate harmful pollutants from industrial exhaust streams. These systems often utilize catalytic converters or scrubbers that achieve specific removal efficiencies, such as 99% particulate matter reduction, before venting gases. Their primary purpose is to enable industrial facilities like power plants and chemical plants to comply with air quality regulations. Electrostatic precipitators and fabric filters represent mature product segments, while demand for Selective Catalytic Reduction (SCR) systems is accelerating in regions with strict NOx emission limits.
Regulatory frameworks are the primary market driver, with mandates from bodies like the US Environmental Protection Agency (EPA) and the European Union's Industrial Emissions Directive setting stringent limits. China's Ministry of Ecology and Environment (MEE) enforces similar standards to achieve its dual carbon goals, shaping technology choices for new industrial projects. The key decision for operators now centers on balancing capital expenditure for new systems against the operational costs and compliance risks of existing equipment.
Market Dynamics
The market's central dynamic is the regulatory enforcement of stringent air quality standards, compelling industrial operators to move beyond minimum compliance. This pressure, exemplified by China's MEE mandates, forces investment in higher-efficiency systems over piecemeal component upgrades.
Growth Catalysts
- Stringent Emission Mandates:Policies like China's dual carbon goals and the US EPA's cross-state air pollution rules require significant reductions in NOx, SOx, and particulate matter, directly driving investment in advanced filtration and catalytic systems.
- Power Sector Modernization:The global power generation industry is upgrading aging coal-fired plants and building new gas-fired facilities, both of which require state-of-the-art emission controls like SCR systems to meet new environmental performance standards.
- Technology Efficiency Gains:Advances in catalyst materials and scrubber designs are improving pollutant removal rates and reducing operational costs, making system upgrades more economically viable for chemical plants and refineries seeking to improve their environmental footprint.
Market Restraints
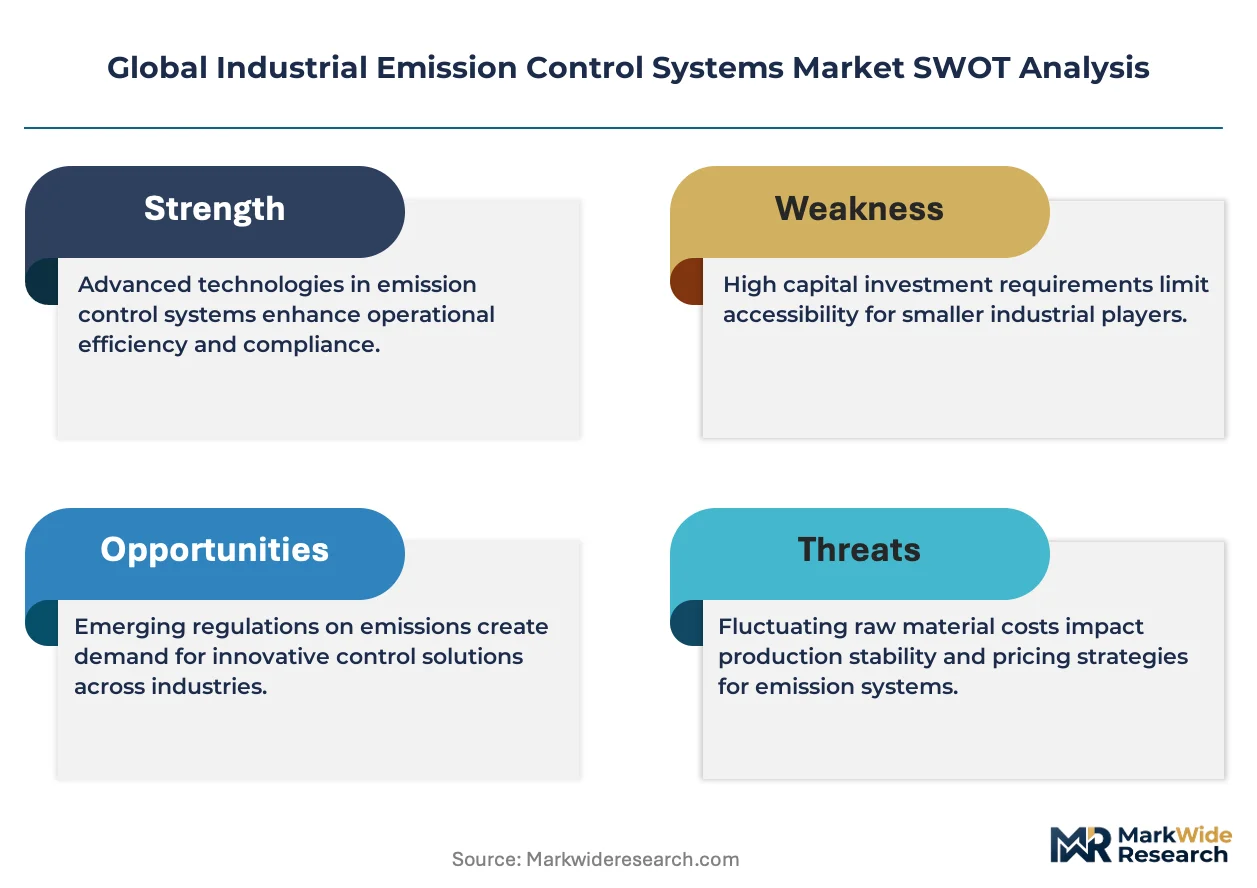
- High Capital Expenditure:The initial procurement and installation costs for comprehensive systems, particularly high-performance Flue Gas Desulfurization (FGD) and SCR technologies, represent a significant financial barrier for operators of smaller or older industrial facilities.
- Operational Cost Volatility:The ongoing expense of consumables, such as ammonia for SCR systems and sorbents for scrubbers, exposes plant operators to commodity price fluctuations, impacting the total cost of ownership and budget predictability.
- Technical Integration Complexity:Retrofitting modern emission control equipment into existing industrial plants with space constraints and legacy infrastructure presents significant engineering challenges, often leading to extended downtime and project delays.
Strategic Opportunities
- Digitalization of Compliance:Integrating emission control hardware with Industrial IoT platforms and predictive analytics software creates an opportunity for offering real-time monitoring, reporting, and maintenance services, shifting revenue toward recurring software and service models.
- Marine and Shipping Sector:New International Maritime Organization (IMO) regulations limiting sulfur and nitrogen oxide emissions from ship engines open a significant new end-market for compact scrubber and SCR systems designed for marine applications.
- Emerging Industrial Economies:Industrializing nations across Southeast Asia and Latin America represent underpenetrated markets where upcoming air quality regulations will create substantial demand for new emission control system installations over the next decade.
Industry Challenges
- Specialized Engineering Talent Gap:A shortage of chemical and process engineers with expertise in commissioning and optimizing complex systems like SCR and electrostatic precipitators creates project execution bottlenecks and increases labor costs for engineering firms.
- Legacy System Interoperability:Ensuring new digital control modules and sensor packages can interface seamlessly with decades-old plant control systems (DCS) is a major technical hurdle that can complicate modernization projects and limit performance gains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Emission Control Systems Market |
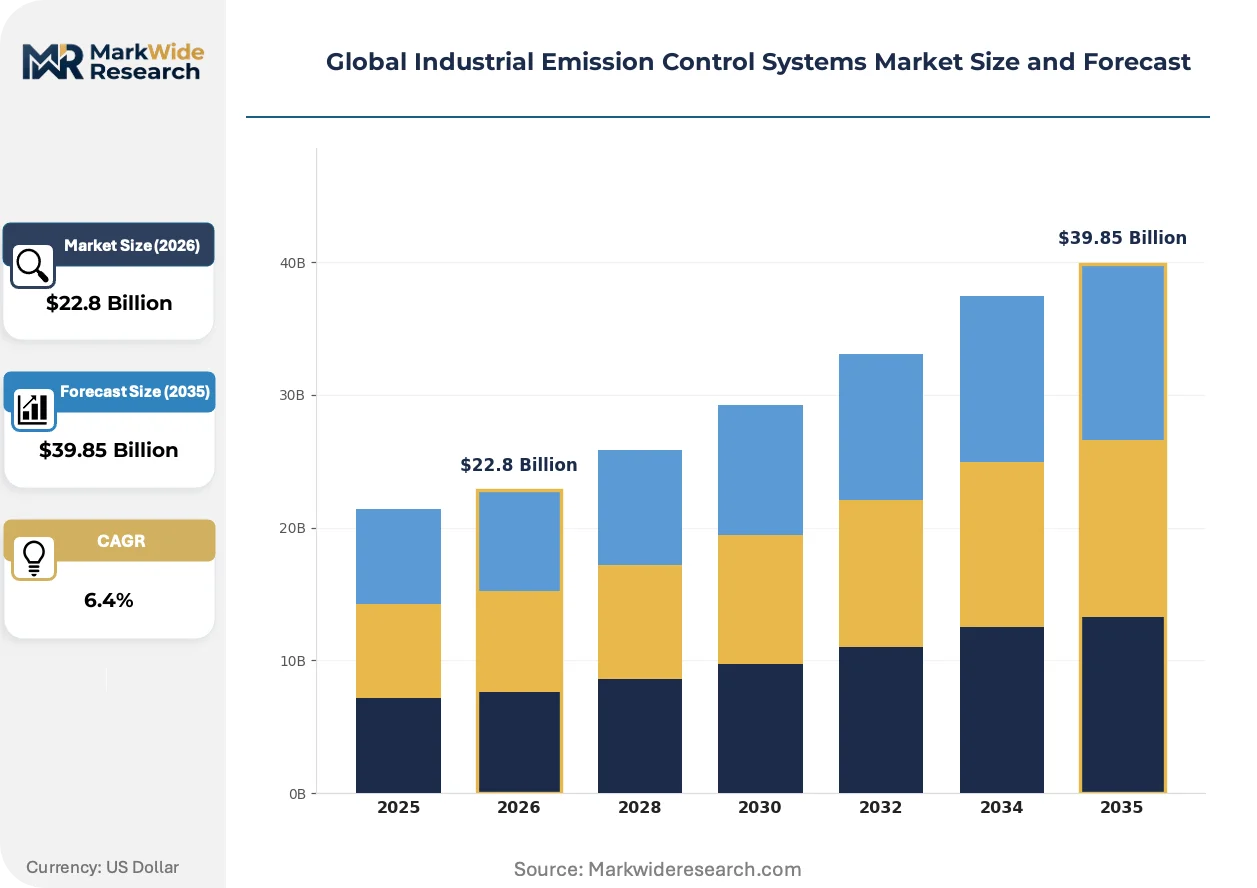
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $39.85 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrostatic Precipitators, Fabric Filters, Scrubbers, Selective Catalytic Reduction, Thermal Oxidizers, Biofilters Technology: Catalytic, Non-Catalytic, Wet Scrubbing, Dry Scrubbing, Activated Carbon, Membrane Filtration Application: Power Generation, Petrochemical Processing, Cement Manufacturing, Waste Management, Food Processing, Textile Production End User: Steel Mills, Chemical Plants, Paper Production Facilities, Semiconductor Manufacturing, Mining Operations, Pharmaceutical Units |
| Companies Covered | Honeywell International, Mitsubishi Heavy Industries, Siemens, General Electric Company, Babcock & Wilcox Enterprises, ABB, Thermo Fisher Scientific, Thermax Limited, Emerson Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Emission Control Systems Market Strategic Shifts & Innovations
The convergence of digital monitoring with physical filtration hardware defines the market's innovation trajectory. This shift is driven by regulatory demand for verifiable, continuous emissions data, pushing technology beyond simple pollutant capture toward intelligent system management and predictive compliance.
Advanced sensor networks and predictive analytics software provide real-time data on system performance and pollutant levels. Power generation and chemical processing plants are the primary adopters, seeking to optimize operational efficiency and ensure constant compliance. This software layer is integrating disparate hardware like scrubbers and fabric filters into a unified, centrally managed platform for enhanced control.
The European Union's Industrial Emissions Directive (IED) is a key regulatory driver shaping technology choices. It mandates the use of Best Available Techniques (BAT) and establishes strict emission limit values for pollutants across major industrial sectors. This forces operators of large combustion plants and refineries in Europe to invest in upgrades, accelerating demand for Selective Catalytic Reduction and advanced scrubber systems.
A move away from purchasing discrete components toward contracting for guaranteed emission reduction outcomes is altering commercial models. This trend disrupts the traditional equipment sales channel, creating an advantage for large-scale engineering firms that can bundle hardware, installation, and long-term operational services. This service-based approach is most visible in new infrastructure projects across India and China.
Global Industrial Emission Control Systems Market Segmentation
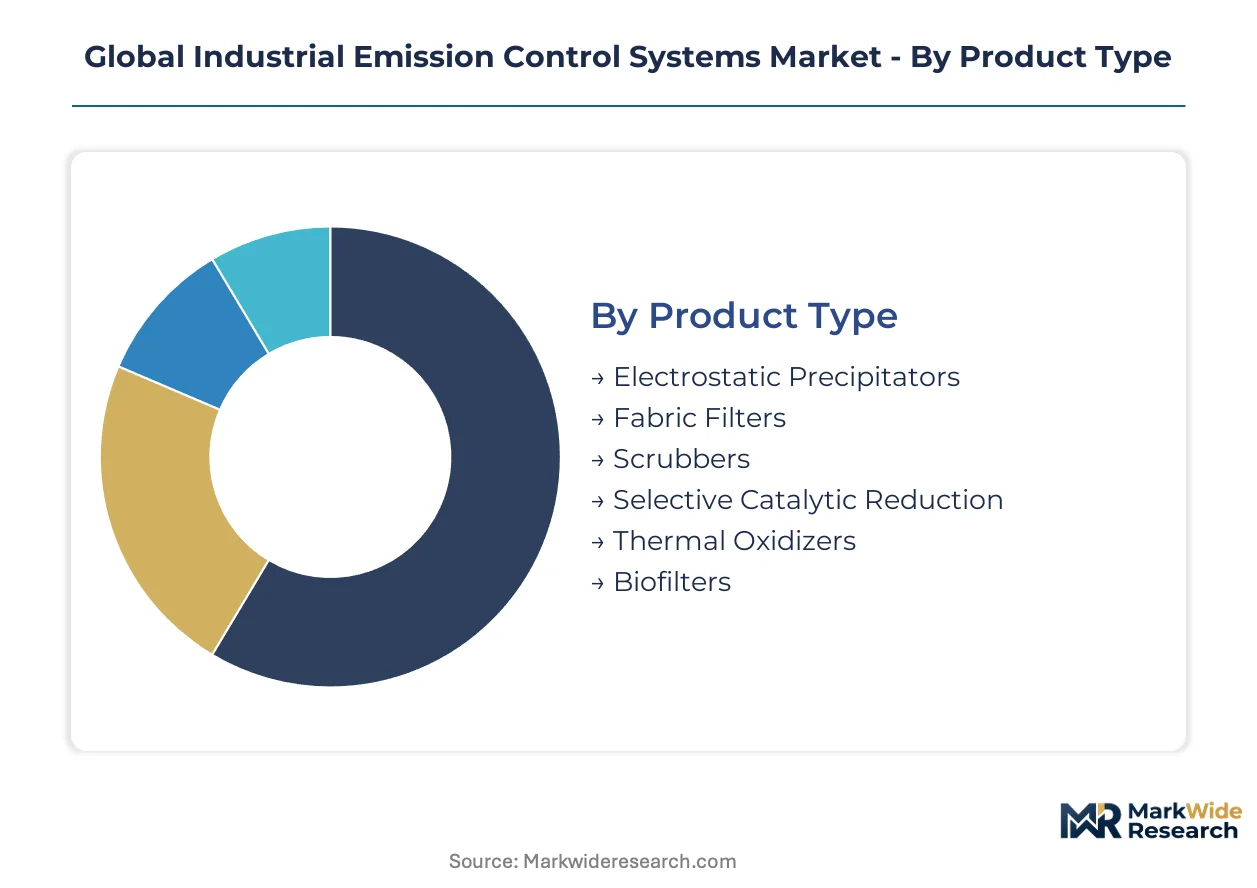
Understanding the segmentation of the industrial emission control systems market is crucial for identifying areas of concentrated investment and evolving compliance priorities. This granular view reveals how different technologies and product types address specific pollutant challenges across diverse industrial applications and end-user requirements, influencing procurement strategies.
Product Type:
The upgrade and replacement cycle for industrial emission control systems significantly influences product type demand, as operators seek more efficient and compliant solutions.
- Selective Catalytic Reduction:These systems utilize a catalyst and a reducing agent, typically ammonia, to convert nitrogen oxides (NOx) into diatomic nitrogen and water. Demand is strong in power generation and petrochemical sectors across China and Europe due to stringent NOx emission limits.
- Fabric Filters:Employing fabric bags to capture particulate matter from gas streams, these systems offer high collection efficiency for fine dust. Modernization projects in cement manufacturing and steel mills in India are driving demand for advanced fabric filter designs.
- Electrostatic Precipitators:These devices remove particulates from exhaust gases by using an induced electrostatic charge to separate dust from gas.
- Scrubbers:Systems that remove pollutants from exhaust gas streams by bringing the gas into contact with a scrubbing liquid.
- Thermal Oxidizers:Used to destroy hazardous air pollutants and volatile organic compounds by heating them to a high temperature.
- Biofilters:Employ biological media to break down volatile organic compounds and odors present in industrial emissions.
Volume placements concentrate in Fabric Filters; the faster expansion belongs to Selective Catalytic Reduction.
Technology:
Technology choices often reflect a balance between capital expenditure, operational costs, and required removal efficiencies for specific pollutants.
- Catalytic:These technologies employ chemical catalysts to convert harmful pollutants, such as NOx and VOCs, into less toxic substances at lower temperatures. Power plants and chemical facilities increasingly adopt catalytic solutions to meet strict air quality standards imposed by the US EPA.
- Wet Scrubbing:This process removes pollutants by contacting exhaust gases with a liquid, typically water or a chemical solution, to absorb or react with contaminants. Large-scale industrial facilities in Germany and Japan utilize wet scrubbing for flue gas desulfurization.
- Non-Catalytic:These systems rely on physical or chemical reactions without a catalyst to remove pollutants.
- Dry Scrubbing:Pollutants are removed by injecting a dry sorbent into the gas stream, reacting with contaminants to form a solid.
- Activated Carbon:Utilizes porous carbon material to adsorb gaseous pollutants and odors from industrial exhaust streams.
- Membrane Filtration:Employs semi-permeable membranes to separate particulate matter or specific gaseous components from an air stream.
Demand for advanced pollutant removal primarily drives Catalytic technology, while Wet Scrubbing addresses bulk gas treatment.
Application:
Regulatory mandates and sector-specific emission targets dictate the type and scale of emission control systems required across various industrial applications.
- Power Generation:This sector includes coal-fired, gas-fired, and biomass power plants, requiring extensive systems for NOx, SOx, and particulate matter reduction. Modernization efforts in existing infrastructure across the US and new plant constructions in Southeast Asia drive significant demand.
- Petrochemical Processing:Refineries and chemical production facilities utilize emission controls to manage volatile organic compounds, sulfur compounds, and other hazardous air pollutants. Compliance with EU Industrial Emissions Directive standards necessitates advanced systems in European petrochemical hubs.
- Cement Manufacturing:Industrial emission control systems manage particulate matter, NOx, and SOx emissions from kiln operations.
- Waste Management:Facilities like incinerators and landfills require controls to manage dioxins, furans, and other gaseous pollutants.
- Food Processing:Emission control systems address odors, volatile organic compounds, and particulate matter generated during various food production processes.
- Textile Production:These facilities utilize systems to manage VOCs, odors, and particulate emissions from dyeing and finishing processes.
Specific environmental regulations underpin demand in Power Generation; Petrochemical Processing experiences growth from expansion projects.
End User:
The operational scale and process complexity of industrial end users significantly influence the design and integration of emission control solutions.
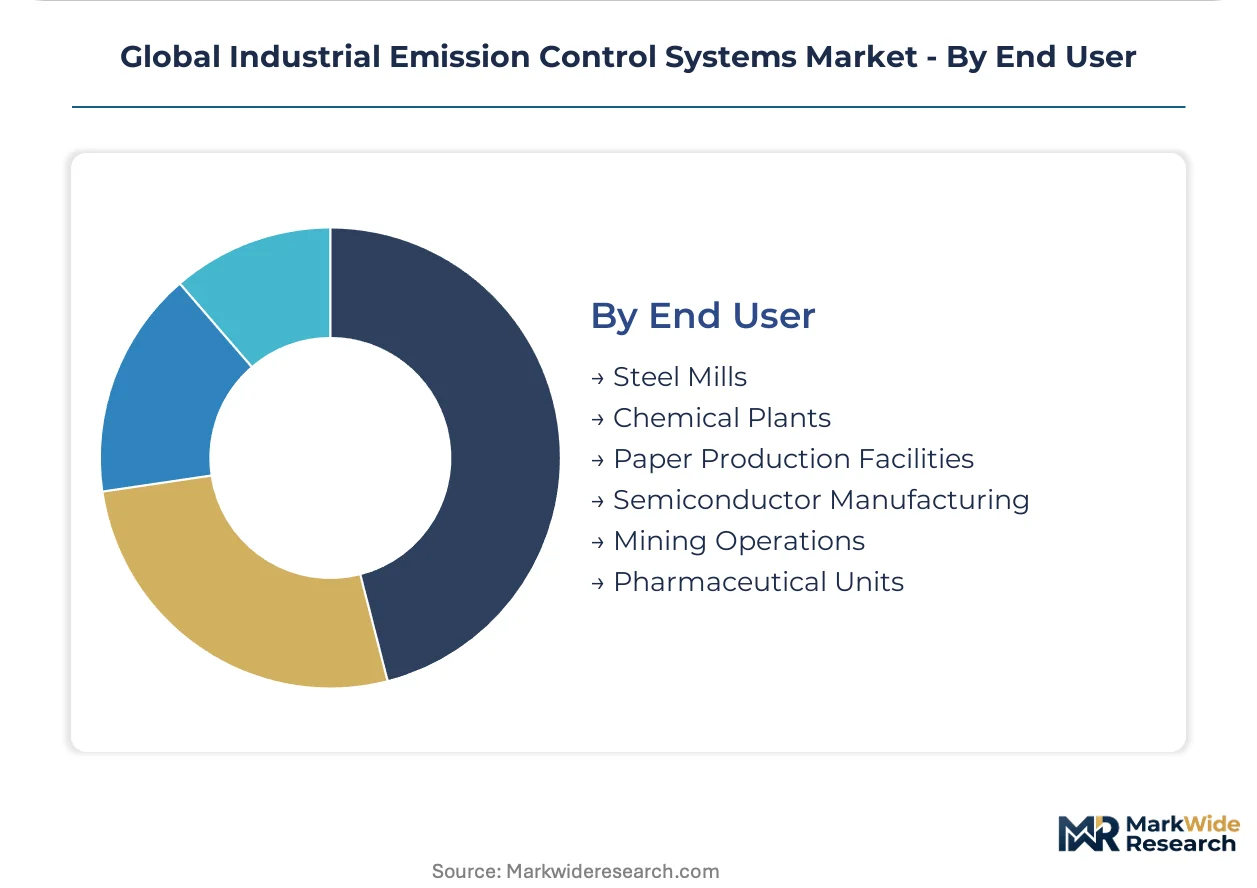
- Chemical Plants:These facilities require highly specialized emission control systems to manage a diverse range of hazardous air pollutants, including VOCs, acid gases, and toxic particulate matter. The strict environmental regulations in China's industrial zones compel significant investment in advanced abatement technologies for chemical manufacturers.
- Steel Mills:Integrated steel production processes generate substantial particulate matter, sulfur dioxide, and nitrogen oxides, necessitating robust flue gas treatment and dust collection systems. Modernization projects in Japanese and Korean steel industries focus on higher efficiency and lower operational costs for emission controls.
- Paper Production Facilities:These plants utilize emission controls to manage odors, particulate matter, and sulfur compounds from pulp and paper manufacturing.
- Semiconductor Manufacturing:Emission control systems are critical for abating highly toxic and corrosive gases used in chip fabrication processes.
- Mining Operations:Controls are employed to manage dust, particulate matter, and diesel exhaust emissions from heavy machinery and processing.
- Pharmaceutical Units:These facilities require systems to control VOCs, hazardous air pollutants, and odors from synthesis and manufacturing processes.
Compliance with air quality standards is paramount for Chemical Plants, with Steel Mills focusing on process-specific pollutant abatement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for industrial emission control systems concentrates heavily within established and emerging industrial zones globally. Stringent air quality mandates and industrial modernization initiatives drive significant investment. Operators prioritize higher-efficiency systems to meet evolving environmental performance standards.
China
Industrial expansion and environmental protection efforts accelerate demand for advanced emission control systems in China. The Ministry of Ecology and Environment (MEE) enforces strict air quality standards, including dual carbon goals. Heavy industrial clusters in the Yangtze River Delta are investing in Selective Catalytic Reduction (SCR) and fabric filters.
India
Modernization of existing infrastructure and new projects fuel demand for emission control solutions in India. The Central Pollution Control Board (CPCB) mandates stricter emission norms for power generation and manufacturing. Key industrial corridors around Gujarat and Maharashtra are implementing advanced scrubbers and fabric filters.
United States
Aging power generation infrastructure and chemical processing facilities require continuous upgrades for emission control systems. The US Environmental Protection Agency (EPA) regulations, including cross-state air pollution rules, drive investment. Industrial facilities in the Ohio River Valley and Gulf Coast regions deploy state-of-the-art catalytic and scrubbing systems.
Germany
Europe's stringent environmental regulations and focus on sustainability spur demand for high-efficiency emission control systems in Germany. The European Union's Industrial Emissions Directive (IED) mandates Best Available Techniques (BAT) for large combustion plants. Industrial parks in North Rhine-Westphalia adopt advanced wet scrubbing and SCR technologies.
Japan
Industrial modernization and a strong focus on clean manufacturing processes drive consistent demand for emission control technologies in Japan. The Ministry of Economy, Trade and Industry (METI) promotes environmental performance across key industries. Steel mills and petrochemical complexes in the Kansai region invest in advanced electrostatic precipitators and catalytic solutions.
Global Industrial Emission Control Systems Market Key Industry Players
Portfolio diversification dominates the current landscape as firms aim to offer comprehensive emission control solutions rather than discrete components. The market structure increasingly favors large-scale engineering firms capable of managing complex, integrated projects. Strategic archetypes include global industrial conglomerates, specialized technology providers, and regional system integrators. Key competitive moves involve strategic partnerships to expand solution offerings and geographic expansion into emerging industrial economies.
Among the integrated solution providers, Siemens AG exemplifies a global industrial conglomerate leveraging its extensive automation portfolio to offer end-to-end system management. This German-based firm anchors a segment focused on digital integration and holistic project execution. Mitsubishi Heavy Industries, a Japan-based industrial giant, represents a specialist in high-capacity systems for power generation applications, focusing on large-scale infrastructure projects. US-based Babcock & Wilcox Enterprises occupies a position as a technology expert with deep expertise in combustion technologies and flue gas treatment, serving diverse heavy industrial clients.
| Leading Market Players |
|---|
| Honeywell International |
| Mitsubishi Heavy Industries |
| Siemens |
| General Electric Company |
| Babcock & Wilcox Enterprises |
| ABB |
| Thermo Fisher Scientific |
| Thermax Limited |
| Emerson Electric |
| Others |
Cost & Logistics Intelligence
The shift towards integrated emission control solutions reshapes cost economics by bundling hardware, software, and services. This transition simultaneously concentrates supply among large-scale engineering firms capable of managing complex projects.
Pricing Analysis
Service-level agreements now frequently bundle hardware warranties with long-term operational support, shifting the pricing model towards project-based outcomes. Price differentiation drivers include the customization level for specific industrial processes and the comprehensiveness of after-sales service packages. Pricing pressure stems from the high capital expenditure of advanced systems, particularly for Flue Gas Desulfurization (FGD) and Selective Catalytic Reduction (SCR) technologies. Smaller or older industrial facilities demonstrate the highest price sensitivity, whereas large power generation plants prioritize compliance and operational reliability.
Supply Chain Analysis
Single-source vulnerability sits with specialized catalyst manufacturers, particularly for Selective Catalytic Reduction (SCR) systems, creating dependency on specific suppliers. Geographic supply concentration for advanced components centers on Germany, Japan, and China. Raw material dependencies include ammonia for SCR systems and specialized sorbents for scrubbers, exposing operators to commodity price volatility. Distribution runs through direct sales from large engineering firms to industrial end-users, often involving long-term service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial emission control systems market is poised for consolidation, driven by the increasing technical integration complexity of advanced solutions. This pressure forces smaller, less specialized players out, favoring large engineering firms.
For Market Incumbents:Hedge against evolving regulatory frameworks by investing in modular system designs that allow for easy upgrades and compliance with future mandates. Expand service offerings to include real-time monitoring and predictive maintenance through Industrial IoT platforms, mitigating the threat of operational cost volatility for clients. Deepen vertical integration into critical component manufacturing, such as advanced catalyst materials, to secure supply chains.
For New Entrants and Emerging Players:Launch via specialized engineering consultancies targeting underpenetrated industrial economies across Southeast Asia and Latin America. Focus on developing compact, cost-effective scrubber and SCR systems tailored for the marine and shipping sector, leveraging new IMO regulations. Penetrate the small-to-medium industrial facility segment with simplified, high-efficiency solutions where capital expenditure is a primary concern.
For Investors and Strategic Acquirers:Exit pathways concentrate in strategic acquisitions by global industrial conglomerates seeking to broaden their solution portfolios or geographic footprint. The market exhibits strong long-term viability over the next decade, underpinned by persistent regulatory enforcement and industrial modernization. Target specialized technology providers in areas like advanced catalyst development or regional system integrators with strong local compliance expertise. Watch for increased M&A activity among top-tier players as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Expanding production for advanced SCR catalysts addresses growing demand from power generation and petrochemical sectors. |
| Joint Venture | Forming joint ventures for digital compliance platforms integrates hardware with real-time monitoring and analytics. |
| Technology Licensing | Licensing advanced scrubber designs allows regional players to meet stringent SOx emission limits efficiently. |
| Geographic Expansion | Expanding operations into Southeast Asia captures new demand from industrializing nations and upcoming air quality regulations. |
| Green Manufacturing Transition | Adopting green manufacturing processes for system components enhances sustainability credentials and reduces operational footprint. |
Research Approach
Document review covered regulatory filings from the US EPA and China MEE, alongside industry association reports, complemented by interviews with key stakeholders. Primary interviews included plant managers, environmental compliance officers, and R&D directors for catalyst materials. This approach integrated insights from government environmental agency publications and corporate financial disclosures. Bottom-up data collection and top-down market sizing provided triangulation for robust analysis.
The quantitative model produced volume and value forecasts across the analysis window, integrating various market dynamics. Segmentation dimensions modeled included product type, technology, application, end-user, and regional regulatory stringency. Compound annual growth rates were derived from historical trends, projected regulatory impacts, and technological adoption rates. Key industry-specific inputs included industrial output growth rates and planned power plant modernizations.
Policy changes, economic downturns, and rapid technological breakthroughs are the dominant revision risks for future projections. Forecasts reflect underlying assumptions regarding regulatory enforcement and industrial investment cycles. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Control Solutions
Enclosed Waste Gas Flares Market
Environmental Control Solutions
Scrubber Market
Environmental Control Solutions
Gas Cleaning Technologies Market
Environmental Control Solutions
North America Industrial Emission Control Systems Market
Environmental Control Solutions
Electrostatic Precipitator Market
Environmental Control Solutions
Flue Gas Desulfurization Systems Market
Environmental Control Solutions
CO2 Injector (CO2 Bubbler) Market
Environmental Control Solutions
Global Flue Gas Treatment Systems Market
Environmental Control Solutions
North America Nitrogen Oxide Control Systems Market
Environmental Control Solutions
Global Leak Detection and Repair (LDAR) Market
Environmental Control Solutions
Global Flue Gas Desulphurization Market
Environmental Control Solutions
Flue Gas Analyzers Market
Environmental Control Solutions
Vapor Recovery Services Market
Environmental Control Solutions
Manufacturing Scale Electrostatic Precipitator Market
Environmental Control Solutions
Modular Energy Control System Market
Environmental Control Solutions
Ozone Generator Market