
 Liquid Light Guides Market | 2026-2036
Liquid Light Guides Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Light Guides Market Analytics
Asset-light leasing models for precision optical equipment is narrowing the competitive field for capital-constrained entrants. Thorlabs leverages its vertically integrated manufacturing footprint across North American and European facilities to sustain pricing power in glass-based liquid light guides. Edmund Optics anchors its position through deep catalog breadth and same-day fulfillment capabilities that dominate research and prototyping channels. Lumencor specializes in LED-coupled liquid light guide systems for fluorescence microscopy, competing on spectral purity rather than commodity volume.
Liquid light guides are cylindrical conduits filled with transparent liquid cores—typically high-purity mineral oils or specialized silicone fluids—encased in reflective tubing that transmits broadband or monochromatic light with minimal attenuation over distances up to several meters, serving applications requiring flexible, cool illumination delivery in confined spaces. Glass liquid light guides command premium positioning in medical and aerospace end uses where thermal stability and UV transmission precision define performance thresholds, while plastic variants occupy cost-sensitive industrial lighting segments with shorter duty cycles. Fiber optic technology leads the technology segmentation through mature coupling protocols with laser and LED sources, though nano-coating surface treatments represent the fastest-growing technology subset as manufacturers seek to reduce Fresnel losses at liquid-core interfaces.
FDA 510(k) clearance requirements and the EU Medical Device Regulation impose biocompatibility and optical output stability standards that filter subscale suppliers from healthcare applications. Japan's PMDA and METI coordinate on photonics equipment certifications that govern import eligibility for surgical illumination components. Stakeholders must monitor evolving material restrictions under REACH and RoHS frameworks that could disqualify certain liquid core formulations from European medical device supply chains.
Market Dynamics
Medical device manufacturers in Germany, Japan, and the United States are consolidating procurement around glass and hybrid liquid light guides as tightening optical performance standards under the EU Medical Device Regulation and FDA 510(k) pathways filter subscale suppliers from surgical illumination supply chains.
Growth Catalysts
- Surgical robotics expansion:Minimally invasive procedures requiring flexible, cool illumination delivery are driving specification upgrades in Bavaria's precision healthcare clusters and Minnesota's medical technology corridor.
- REACH and RoHS material compliance:European medical device supply chains are disqualifying certain liquid core formulations, creating replacement demand for certified high-purity mineral oils and specialized silicone fluids.
- Nano-coating surface treatments:Manufacturers are reducing Fresnel losses at liquid-core interfaces through advanced surface engineering, improving transmission efficiency in fluorescence microscopy and aerospace applications.
Market Restraints
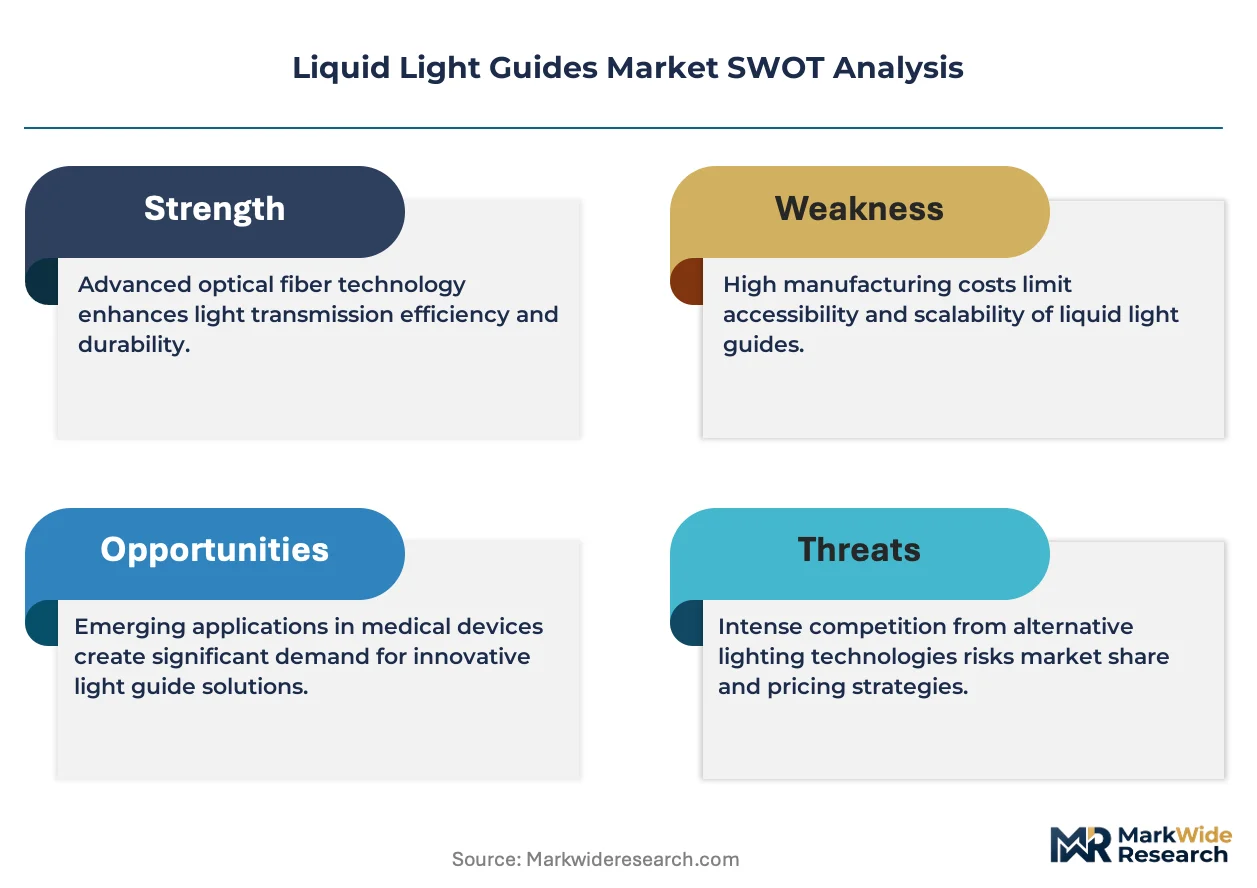
- High-purity mineral oil price volatility:Input costs for transparent liquid cores fluctuate with petrochemical feedstock markets, compressing margins for mid-tier manufacturers without captive supply.
- Glass liquid light guide supply concentration:Production of thermally stable, UV-transmission-grade glass variants clusters among specialized European and Japanese suppliers, creating bottleneck risk for medical and aerospace end uses.
- Fiber optic substitution in industrial segments:Plastic liquid light guides face displacement in cost-sensitive industrial lighting with shorter duty cycles as solid-state fiber alternatives achieve cost parity.
Strategic Opportunities
- LED-coupled system integration:Convergence of solid-state illumination with liquid light guide architectures opens spectral purity positioning in fluorescence microscopy and life science instrumentation.
- Asset-light leasing models:Precision optical equipment rental programs are narrowing the competitive field for capital-constrained entrants in research and prototyping channels.
- Japan's PMDA-METI coordination:Streamlined photonics equipment certifications for surgical illumination components are reducing import eligibility friction for compliant foreign suppliers.
Industry Challenges
- Biocompatibility certification timelines:FDA 510(k) clearance requirements for optical output stability are extending product launch cycles and freezing working capital in regulatory review.
- Optical performance standard divergence:Misalignment between EU Medical Device Regulation specifications and Japan's JIS standards forces manufacturers to maintain multiple product variants, inflating inventory complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Light Guides Market |
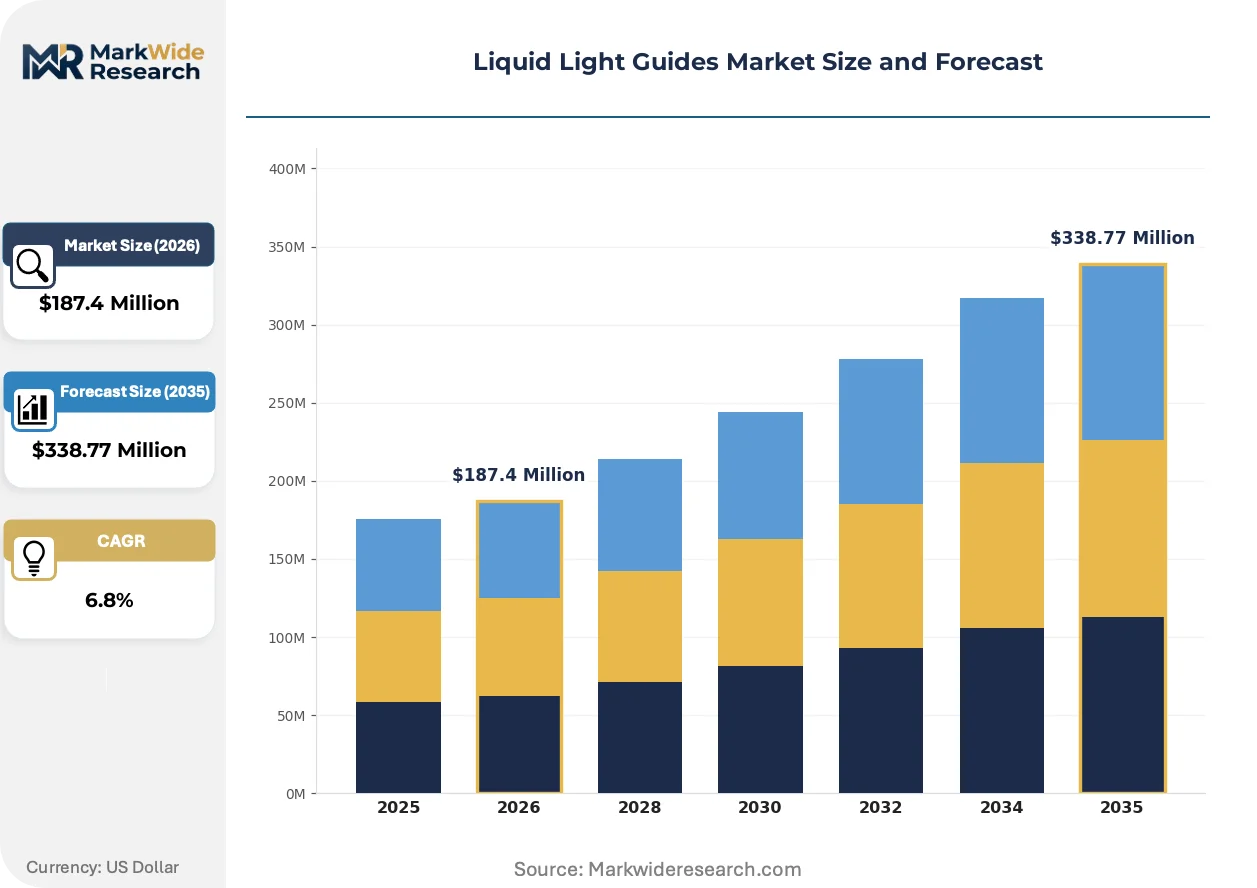
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Glass, Fiberglass, Hybrid Application: Medical Devices, Industrial Lighting, Optical Communications, Sensors Technology: Fiber Optic Technology, LED Technology, Laser Technology, Nano-coating End User: Healthcare, Telecommunications, Manufacturing, Aerospace |
| Companies Covered | Lumatec, Thorlabs, Edmund Optics, Newport, Excelitas Technologies, Lumencor, Olympus, CoolLED, Dymax, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Light Guides Market Evolving Landscape
Active reshaping in liquid light guides centers on three vectors: nano-engineered surface treatments compressing optical losses, regulatory harmonization pressures accelerating material transitions, and procurement model evolution favoring flexible access over ownership in capital equipment.
Nano-coating deposition on liquid-core interfaces is collapsing the performance gap between commodity plastic guides and premium glass variants. Surgical illumination system manufacturers in Germany and the United States are fast-tracking qualification of these treated surfaces for fluorescence microscopy applications. The structural consequence is a compression of the traditional three-tier material hierarchy into two performance bands.
Japan's PMDA and METI coordination on photonics equipment certifications is tightening import eligibility criteria for surgical illumination components. This regulatory convergence is forcing non-domestic manufacturers to establish local testing partnerships or regional assembly presence. Medical device OEMs in Osaka Prefecture are responding by consolidating supplier audits under unified JIS-ISO hybrid protocols.
Research laboratories and prototyping facilities are unbundling after-sales service from equipment acquisition, favoring subscription-based access to calibrated liquid light guide systems. Edmund Optics and catalog distributors are capturing this shift through same-day fulfillment capabilities that displace traditional capital purchase cycles. North American academic and government research institutions represent the leading edge of this behavioral transition.
Liquid Light Guides Market Segmentation
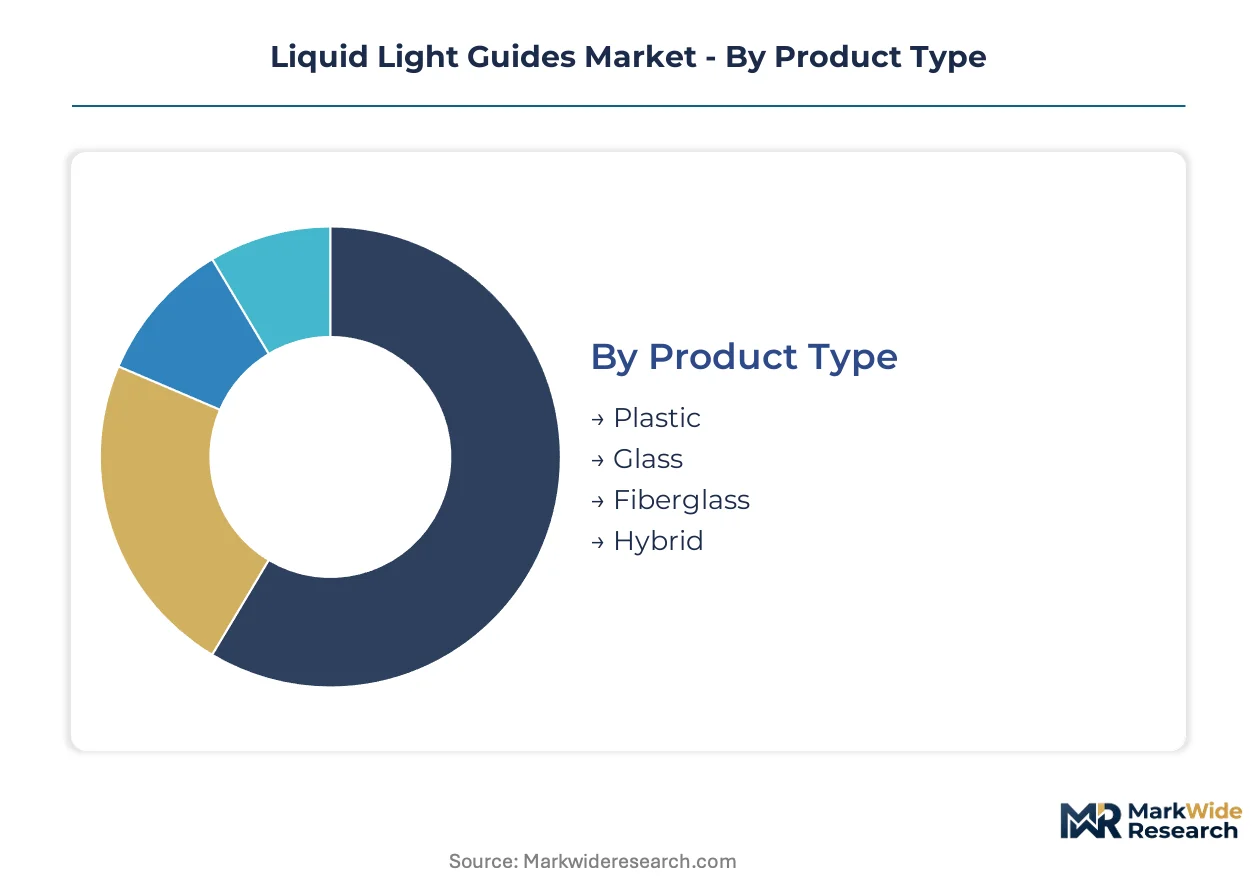
Liquid light guide architectures diverge sharply across performance tiers, with material selection and coupling technology determining addressable end-use markets. Segmentation reveals where premium specifications command pricing power versus where cost-optimized variants capture volume scale.
Product Type:
Use-case spectrum spans from disposable surgical accessories to multi-year aerospace installations, with material thermal limits and transmission precision defining deployment boundaries.
- Plastic:Polymer-based conduits with acrylic or polycarbonate cores serve cost-sensitive industrial lighting and short-duty-cycle applications. Manufacturing clusters in China's Guangdong Province dominate volume production for automotive assembly line illumination.
- Glass:Fused silica and borosilicate variants deliver UV transmission precision and thermal stability above 200°C. Bavaria's precision healthcare manufacturers specify these for fluorescence microscopy and surgical robotics where optical output stability is non-negotiable under FDA 510(k) pathways.
- Fiberglass:Reinforced composite structures combine mechanical durability with moderate optical performance for harsh-environment sensors and telecommunications field equipment.
- Hybrid:Multi-material architectures merge glass core purity with polymer cladding flexibility, targeting life science instrumentation requiring both spectral precision and routing adaptability.
Established volume favors Plastic; emerging adoption favors Hybrid.
Application:
Customer procurement patterns separate capital equipment integrators from consumable purchasers, with certification requirements filtering supplier eligibility.
- Medical Devices:Surgical illumination systems and endoscopic light delivery demand biocompatibility certification under EU MDR and FDA 510(k) frameworks. German and Japanese OEMs in Bavaria and Osaka Prefecture consolidate procurement around glass and hybrid variants.
- Industrial Lighting:Machine vision and assembly line illumination prioritize cost-per-meter and rapid replacement cycles. Chinese and Mexican manufacturing facilities drive volume procurement of plastic guides with sub-1000 hour duty ratings.
- Optical Communications:Signal transmission applications leverage liquid core flexibility for temporary routing in data center reconfigurations and telecommunications test environments.
- Sensors:Process monitoring and spectroscopic detection systems integrate liquid light guides for remote sample illumination in chemical and pharmaceutical quality control.
Medical Devices commands premium pricing; Industrial Lighting dominates unit volume.
Technology:
Source coupling architecture determines spectral output characteristics and system integration complexity, with solid-state convergence reshaping competitive positioning.
- Fiber Optic Technology:Mature coupling protocols with laser and LED sources anchor installed base across research and industrial segments. Standardized SMA and FC connectors reduce integration friction for OEMs.
- LED Technology:Solid-state illumination convergence with liquid light guide architectures opens spectral purity positioning in fluorescence microscopy. Lumencor and specialized vendors compete on wavelength stability rather than commodity volume.
- Laser Technology:High-irradiance delivery for photocoagulation and materials processing requires thermal management that glass cores uniquely satisfy.
- Nano-coating:Surface engineering at liquid-core interfaces reduces Fresnel losses and is climbing the fastest among technology subsets as manufacturers seek transmission efficiency gains without full material upgrades.
Fiber Optic Technology holds installed base; Nano-coating is gaining share fastest.
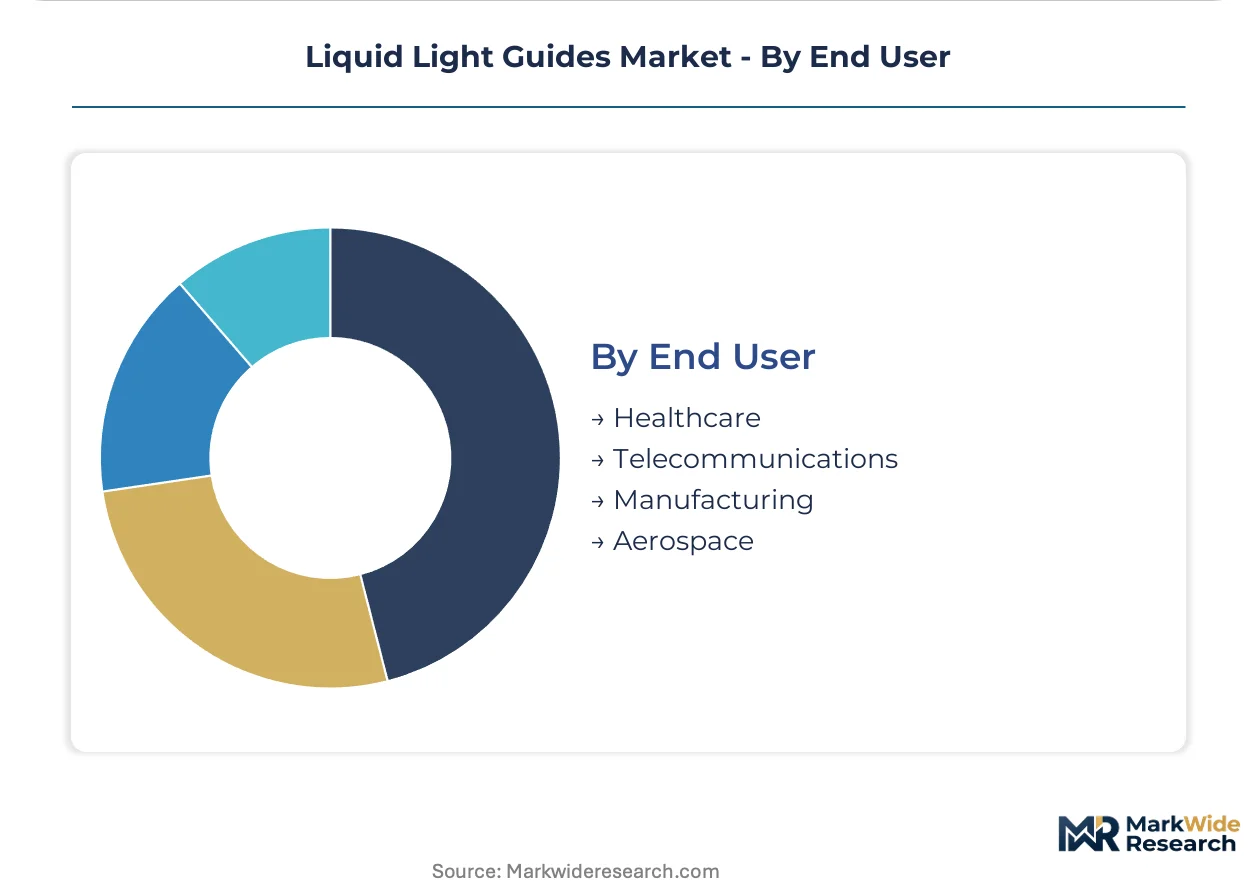
End User:
Industry-specific regulatory frameworks and performance thresholds create distinct procurement specifications that segment supplier capabilities.
- Healthcare:Hospitals, surgical centers, and diagnostic laboratories drive demand for sterilizable, biocompatible light delivery systems. REACH and RoHS compliance filters European supply chain eligibility.
- Telecommunications:Network equipment manufacturers and service providers utilize liquid light guides for temporary fiber routing and test access points in central office environments.
- Manufacturing:Automotive, electronics, and consumer goods producers deploy industrial lighting solutions where plastic variants achieve target lux levels at minimum capital outlay.
- Aerospace:Aircraft interior lighting and avionics applications specify thermally stable glass guides meeting FAA flammability and outgassing standards for cabin and equipment bay installations.
Healthcare concentrates premium revenue; Manufacturing distributes volume scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Medical Device Regulation enforcement and FDA 510(k) pathway refinements are redirecting procurement toward certified glass and hybrid liquid light guides. German, Japanese, and American medical device manufacturers are consolidating supplier relationships around precision healthcare clusters that meet these optical performance standards.
Germany
Bavaria's surgical robotics OEMs are driving specification upgrades for fluorescence microscopy systems. EU MDR biocompatibility requirements are filtering subscale suppliers from European medical device supply chains. The Munich-Erlangen precision healthcare corridor concentrates procurement of thermally stable glass liquid light guides for minimally invasive procedures.
United States
Minnesota's medical technology corridor anchors North American demand for LED-coupled surgical illumination systems. FDA 510(k) clearance timelines are extending product launch cycles and freezing working capital in regulatory review. Rochester and Minneapolis-based OEMs are consolidating vendor audits under unified ISO-FDA hybrid protocols.
Japan
Osaka Prefecture's endoscopic equipment manufacturers are scaling procurement of hybrid liquid light guide architectures. METI and PMDA coordination on photonics equipment certifications is tightening import eligibility for surgical illumination components. The Kansai region's diagnostic imaging cluster is driving qualification of nano-coated surfaces for reduced Fresnel losses.
China
Guangdong Province's automotive assembly line manufacturers dominate volume production of plastic liquid light guides for industrial lighting. MIIT standards for optical communications equipment are governing temporary fiber routing applications in data center reconfigurations. Shenzhen and Dongguan manufacturing facilities are capturing cost-sensitive segments with sub-1000 hour duty ratings.
Switzerland
Swissmedic oversight of medical device optical output stability is elevating material purity requirements for life science instrumentation. REACH and RoHS compliance frameworks are disqualifying certain liquid core formulations from European supply chains. The Basel-Zurich biopharma corridor is sourcing certified high-purity mineral oils for spectroscopic detection systems.
Liquid Light Guides Market Competitive Landscape
On the supply side, the industry is bifurcating between vertically integrated precision optics specialists and catalog distributors with fulfillment scale. Glass liquid light guide production clusters among specialized European and Japanese suppliers, while plastic variants concentrate in Chinese manufacturing hubs. Three archetypes dominate: component-integrated system builders, wavelength-specialized fluorescence vendors, and broad-catalog distributors. Competitive moves center on nano-coating technology licensing and regional assembly partnerships to satisfy PMDA-METI certification requirements.
Among North American precision optics vendors, Thorlabs and Edmund Optics occupy distinct positioning tiers. Thorlabs exemplifies the vertically integrated archetype with captive manufacturing control over glass-based architectures. Edmund Optics anchors the catalog breadth strategy through same-day fulfillment capabilities that dominate research and prototyping channels. Lumencor represents the wavelength-specialized tier, competing on spectral purity in LED-coupled systems rather than commodity volume scale.
| Leading Market Players |
|---|
| Lumatec |
| Thorlabs |
| Edmund Optics |
| Newport |
| Excelitas Technologies |
| Lumencor |
| Olympus |
| CoolLED |
| Dymax |
| Others |
Value Network & Pricing Analysis
High-purity mineral oil price volatility determines both tier spreads and supply chain shape. Petrochemical feedstock fluctuations compress margins for mid-tier manufacturers lacking captive supply, forcing a bifurcation between premium glass-based systems and cost-optimized plastic variants.
Pricing Analysis
Certification level creates the primary spread between EU MDR/FDA-grade glass guides and uncertified plastic alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects biocompatibility investment and thermal stability thresholds. Cost compression in plastic industrial segments is intensifying because fiber optic substitutes achieve cost parity. Manufacturing buyers in Guangdong Province exhibit highest price sensitivity, while Bavarian surgical robotics OEMs prioritize optical output stability over unit cost.
Supply Chain Analysis
Extended payment terms from German and Japanese medical device OEMs strain working capital for subscale suppliers. Production of thermally stable glass variants concentrates in Germany, Japan, and Switzerland, while plastic volume manufacturing clusters in China. Raw material dependencies include high-purity mineral oils, fused silica substrates, and specialized silicone fluids. Single-source vulnerability runs through Japanese suppliers of UV-transmission-grade borosilicate. Distribution runs through catalog distributors for research channels and direct OEM contracts for medical device integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment forms a defensive moat in this market. FDA 510(k) clearance timelines and EU MDR biocompatibility requirements create switching costs that freeze out subscale competitors.
For Market Incumbents: Build certification moats through accelerated FDA 510(k) pathway investments and EU MDR technical documentation depth. Deepen backward integration into high-purity mineral oil sourcing to neutralize petrochemical volatility. Acquire nano-coating technology licenses to collapse the performance gap between glass and treated plastic surfaces. Channel control through same-day fulfillment capabilities protects research segment share against catalog distributor encroachment. For New Entrants and Emerging Players: Mid-market industrial lighting in Mexico and Southeast Asia represents the most penetrable entry point, as fiber optic substitution lags in cost-sensitive assembly line applications. Subscription-based equipment access models for North American academic laboratories bypass capital purchase cycle barriers. Partner with Shenzhen manufacturing facilities for plastic guide production, then qualify hybrid architectures through Osaka Prefecture testing partnerships to access Japanese surgical illumination supply chains. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated precision optics specialists with captive glass manufacturing. Long-term viability hinges on regulatory certification asset accumulation rather than commodity volume scale. Target acquisition archetypes include nano-coating technology developers and regional distributors with PMDA-METI certification relationships. Watch for inflection in LED-coupled system integration rates as spectral purity positioning displaces traditional fiber optic protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Nano-coating Technology Licensing | Reduces Fresnel losses at liquid-core interfaces, collapsing traditional three-tier material hierarchy. |
| Regional Assembly Partnership | Satisfies Japan's PMDA-METI certification requirements for surgical illumination component import eligibility. |
| Backward Integration into Mineral Oils | Neutralizes petrochemical feedstock volatility compressing mid-tier manufacturer margins. |
| Subscription Equipment Access Model | Captures behavioral shift in North American research institutions favoring service unbundling. |
| Hybrid Architecture Qualification | Targets life science instrumentation requiring both spectral precision and routing adaptability. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearance databases, EU MDR technical documentation, and photonics equipment certification records from Japan's METI. Surgical robotics procurement managers, biomedical engineers at Bavarian precision healthcare clusters, and GPO contracts managers at North American hospital systems provided operational perspective. SEC filings from precision optics vendors, customs trade data on high-purity mineral oil imports, and REACH compliance frameworks supplied validation anchors. Bottom-up demand modeling across application segments triangulates against top-down market sizing from supplier revenue aggregation.
Forecast inputs include surgical robotics installation trajectories, LED source adoption rates in fluorescence microscopy, and regulatory harmonization progress between EU MDR and Japan's JIS standards. Segmentation dimensions span material architecture, coupling technology, end-use certification tier, and regional healthcare cluster density. CAGRs derive from weighted scenario analysis across the projection horizon, incorporating nano-coating penetration curves and fiber optic substitution elasticities in industrial segments.
Macroeconomic conditions sit as an overlay; deviation in petrochemical feedstock pricing or medical device capital expenditure cycles would shift the trajectory. Forecasts reflect documented assumptions on regulatory clearance timelines and material substitution elasticities. Technological breakthroughs in solid-state illumination or REACH/RoHS material restriction expansions would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Picosecond and Femtosecond Fiber Lasers Market
Optical Components
Duplication Disc Market
Optical Components
Erbium-Doped Fiber Amplifier Market
Optical Components
Global Optical Connectivity Solutions Market
Optical Components
CW Fiber Amplifier Market
Optical Components
Optical Fiber Array Market
Optical Components
High Speed Fiber Optic Sensor Market
Optical Components
Spectroradiometers Market
Optical Components
High Power Double-Clad Fiber Bragg Grating Market
Optical Components
Optical Fiber and Plastic Conduit Market
Optical Components
Optical Time-Domain Reflectometer Market
Optical Components
Optical Instruments and Lenses Market
Optical Components
Optical Sensor Market
Optical Components
Global Optical Coating Equipment Market
Optical Components
Fogless Mirror Market
Optical Components
Optical Encoder Market