

High Power Double-Clad Fiber Bragg Grating Market Size, Share, and Industry Trends Forecast 2026-2036
High Power Double-Clad Fiber Bragg Grating Market Insights
Defense organizations is repositioning toward high-power fiber laser architectures for directed-energy and counter-UAS applications, pulling demand for thermal-load-tolerant gratings. FBGS Technologies leverages vertical integration across photosensitive fiber drawing to finished grating packaging, sustaining cost discipline. Proximion anchors Nordic supply for chirped gratings in telecom amplification chains. TeraXion competes on femtosecond-inscribed designs that tolerate kilowatt-class thermal cycling.
High Power Double-Clad Fiber Bragg Grating denotes a periodic refractive-index modulation written into rare-earth-doped double-clad fiber, typically ytterbium-doped silica with a low-index polymer or fluorine-doped secondary cladding, enabling core-pumped operation at outputs exceeding one kilowatt with narrow linewidth feedback. Pulsed Fiber Bragg Grating dominates revenue as master-oscillator power-amplifier architectures displace solid-state alternatives in materials processing. Femtosecond Laser Writing is displacing ultraviolet inscription for hydrogen-free gratings that resist thermal degradation in kilowatt amplifiers. Sensing and Monitoring lags in value but occupies the fastest expansion slot as structural health monitoring penetrates wind turbine blades and composite airframes.
FDA laser product performance standards, EU RoHS restricted substance thresholds for rare-earth processing residues, and China's GB standards on industrial laser safety collectively shape product certification burdens and factory audit requirements for cross-border shipments. ISO 11146 beam quality documentation and IEC 60825 safety classifications further gate market access for unvalidated suppliers. Stakeholders must monitor how REACH chemical registration deadlines and China's dual carbon enforcement timelines recalibrate dopant precursor costs and foundry location decisions.
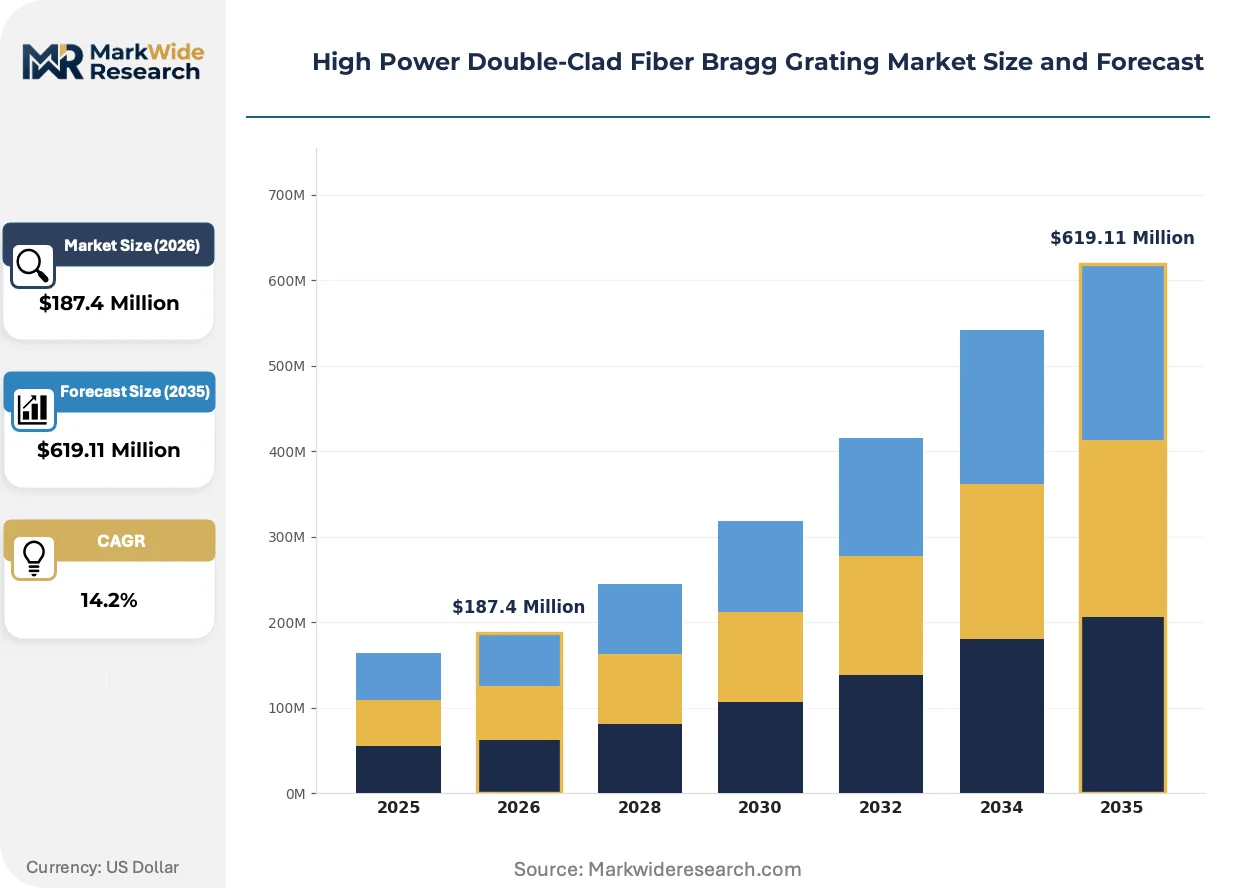
Market Dynamics
Femtosecond laser inscription is compressing grating fabrication timelines while hydrogen-free processes eliminate thermal degradation risks in kilowatt-class amplifiers, forcing incumbent ultraviolet-inscription suppliers to retool or exit.
Growth Catalysts
- Directed-energy defense procurement:Aerospace integrators in the US and Germany are scaling wavelength-stabilized fiber laser orders for counter-UAS and shipboard laser platforms, pulling demand for thermal-load-tolerant grating architectures.
- REACH chemical registration:EU enforcement timelines for rare-earth processing residues are accelerating domestic European dopant precursor refining investments, reducing import dependency on Chinese supply chains.
- Femtosecond inscription adoption:Hydrogen-free grating production is automating quality consistency and extending service intervals in industrial cutting systems, displacing legacy UV-written alternatives in materials processing.
Market Restraints
- Rare-earth concentrate volatility:Ytterbium oxide and erbium precursor spot pricing swings of 40-60% annually compress foundry margins and force long-term supply contracts with penalty clauses.
- Jena-Munich supply concentration:German photonics cluster dependency creates single-point-of-failure risk for precision-drawn photosensitive fiber and packaged grating subassemblies.
- GB standard harmonization gaps:China's industrial laser safety certification requirements diverge from IEC 60825-1, forcing dual-testing protocols for cross-border shipments.
Strategic Opportunities
- India PLI scheme leverage:Domestic value-addition mandates for telecom and defense electronics create tariff-advantaged manufacturing slots for grating-integrated fiber laser modules.
- Wind turbine structural health monitoring:Embedded FBG strain sensing in blade composites represents an emerging volume application with 15-20 year service contract potential.
- EU F-Gas Regulation phase-down:Fluorine-doped secondary cladding formulations face substitution pressure, opening market share for polymer-clad alternatives with simplified environmental compliance.
Industry Challenges
- Fiber Bragg grating design specialization:The intersection of photosensitive fiber physics, thermal management modeling, and femtosecond process control creates acute talent scarcity in European and North American labor pools.
- ISO 11146 beam quality documentation:Extended validation timelines for M² measurement protocols delay product release cycles by 8-14 weeks for new grating designs.
- Legacy amplifier integration:Retrofitting kilowatt-class solid-state systems with fiber seed sources requires custom mechanical adapters and control interface bridges that fragment engineering resources.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Power Double-Clad Fiber Bragg Grating Market Trends and Innovations
Grating fabrication is pivoting from batch UV exposure to continuous femtosecond writing, while regulatory chemical controls and defense procurement consolidation reshape competitive entry barriers and customer concentration patterns.
Femtosecond laser inscription systems are automating refractive-index modulation precision at throughput rates matching mechanical drawing speeds. Defense contractors in Germany and the US are qualifying these gratings for directed-energy weapons programs requiring 10,000+ thermal cycles without spectral drift. The technology is automating yield consistency and compressing foundry capital intensity versus hydrogen-loaded UV alternatives.
China's dual carbon enforcement through MEE is tightening rare-earth mining and smelting emissions permits, constraining ytterbium precursor export volumes. European grating manufacturers are responding by qualifying Australian and Canadian rare-earth concentrate suppliers under REACH-compliant refining arrangements. The policy shift is accelerating supply chain geographic diversification among precision fiber draw towers.
Systems integrators are consolidating vendor panels to single-source grating-amplifier subassemblies with 15-year service commitments. This behavior compresses spot-market spot buying for discrete gratings and elevates qualification barriers for new entrants. The pattern is most visible in German machine tool OEM supply chains, where FBGS Technologies and TeraXion anchor approved vendor lists with captive packaging capabilities.
High Power Double-Clad Fiber Bragg Grating Market Segmentation
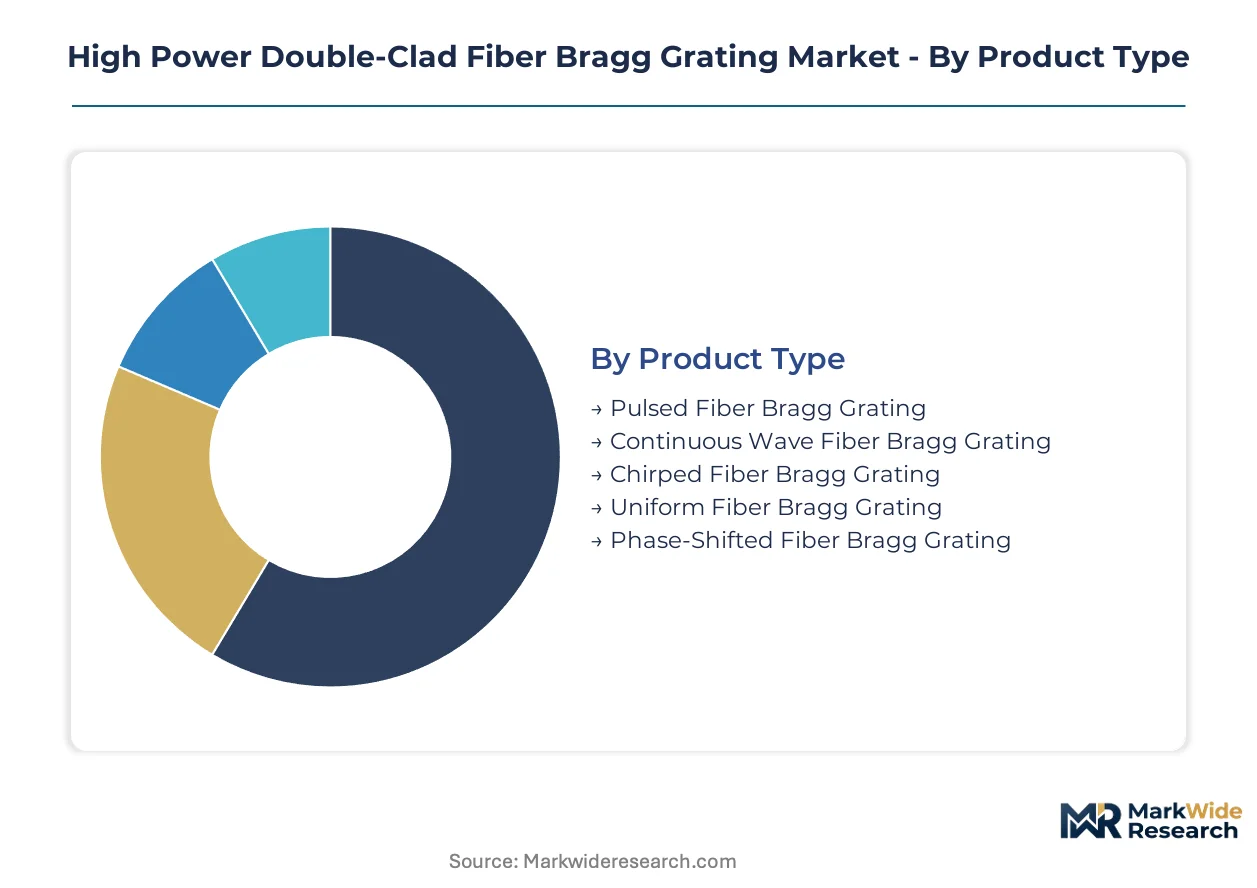
Segmentation in this market exposes divergent certification burdens across defense, medical, and industrial laser applications. Grating specifications must align with IEC 60825 safety classifications, FDA laser product standards, and China's GB standards simultaneously for cross-border equipment shipments.
Product Type:
Pulsed Fiber Bragg Grating dominates procurement volumes from aerospace integrators requiring IEC 60825-1 certification for directed-energy platforms. Chirped and uniform variants face lighter documentation loads for industrial cutting applications.
- Pulsed Fiber Bragg Grating:Engineered for master-oscillator power-amplifier architectures with nanosecond pulse durations and peak powers exceeding 10 kW. German machine tool OEMs in Jena and Munich specify these gratings for materials processing systems requiring thermal-load tolerance across 10,000+ cycles.
- Chirped Fiber Bragg Grating:Features linearly varying pitch that stretches or compresses optical pulses in chirped pulse amplification chains. Nordic telecom infrastructure projects in Sweden and Norway pull demand for dispersion-compensating designs in submarine cable amplification nodes.
- Continuous Wave Fiber Bragg Grating:Optimized for steady-state emission in industrial cutting heads with simplified thermal management.
- Uniform Fiber Bragg Grating:Maintains constant refractive-index modulation period for narrow-linewidth feedback in scientific laser systems.
- Phase-Shifted Fiber Bragg Grating:Incorporates discrete phase discontinuities for single-frequency operation in coherent beam combining arrays.
Pulsed Fiber Bragg Grating sits at the top of the volume ranking, with Chirped Fiber Bragg Grating climbing the fastest.
Technology:
Cost tiers separate hydrogen-loaded ultraviolet processes from capital-intensive femtosecond systems, with electric-arc methods occupying the economy tier for sensing applications.
- Femtosecond Laser Writing:Deploys near-infrared pulses for hydrogen-free refractive-index modulation that withstands kilowatt-class thermal cycling without spectral drift. Defense contractors in the US and Germany are qualifying these gratings for directed-energy weapons programs requiring extended service intervals.
- Ultraviolet Inscription:Relies on 248 nm or 193 nm excimer laser exposure through phase masks, historically dominant but now constrained by hydrogen-loading requirements that degrade under thermal load. Legacy foundries in Germany retain installed base advantages for telecom amplification gratings.
- Photosensitivity:Exploits germanium-doped silica defect centers for low-cost grating fabrication in sensing networks.
- Electric-Arc Discharge:Generates periodic micro-tapers through localized heating for temperature-tolerant gratings in harsh environments.
- Thermal Annealing:Stabilizes inscribed structures through controlled heat treatment, extending service life in high-power amplifiers.
Femtosecond Laser Writing commands the premium pricing tier, while Photosensitivity retains the largest installed base across distributed sensing deployments.
Application:
Customer type concentration varies sharply: defense procurement drives wavelength stabilization volumes, while industrial manufacturers filter into optical filtering segments with shorter qualification cycles.
- High-Power Laser Systems:Core application for kilowatt-class fiber amplifiers in materials processing and directed-energy platforms. China's NMPA tightening of rare-earth dopant sourcing rules is pushing European integrators toward Australian concentrate suppliers.
- Sensing and Monitoring:Fastest-expanding application as embedded strain sensors penetrate wind turbine blade composites and composite airframes for structural health monitoring with 15-20 year service contract potential.
- Wavelength Stabilization:Locks emitter spectra in pump diodes and seed lasers for amplifier chains.
- Optical Filtering:Rejects amplified spontaneous emission in telecom and scientific laser systems.
- Fiber Amplification:Provides feedback in erbium-doped and ytterbium-doped amplifier stages.
High-Power Laser Systems anchors revenue concentration, with Sensing and Monitoring gaining share fastest through renewable energy infrastructure buildout.
End User:
Margin structures diverge across customer tiers: defense organizations accept 15-year service commitments at premium pricing, while industrial manufacturers drive commoditization in standard cutting applications.
- Defense Organizations:Procurement of wavelength-stabilized architectures for counter-UAS and shipboard laser platforms requires REACH-compliant rare-earth supply chains and IEC 60825-1 extended validation protocols. US and German aerospace integrators are consolidating vendor panels to single-source grating-amplifier subassemblies.
- Aerospace Integrators:Demand thermal-load-tolerant gratings for directed-energy weapons with qualification barriers that exclude unvalidated suppliers.
- Telecommunication Providers:Specify chirped gratings for submarine and terrestrial amplification chains with standardized reliability metrics.
- Research Laboratories:Drive customization requirements for novel grating designs in scientific laser development.
- Industrial Manufacturers:Prioritize cost discipline and rapid availability for materials processing equipment.
Defense Organizations represent the highest-margin customer tier, with Aerospace Integrators expanding procurement most aggressively through directed-energy platform deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping foundry location decisions as REACH chemical registration costs and China's dual carbon enforcement create divergent cost-of-compliance tiers across major production bases.
Germany
Defense procurement from Diehl Defence and Rheinmetall drives wavelength-stabilized grating volumes for directed-energy platforms. ECHA REACH enforcement timelines for rare-earth processing residues accelerate domestic ytterbium precursor refining investments. The Jena-Munich photonics corridor anchors precision manufacturing with FBGS Technologies and TeraXion operating captive draw towers and packaging facilities.
United States
Aerospace integrators including Lockheed Martin and Northrop Grumman scale counter-UAS laser contracts requiring IEC 60825-1 extended validation protocols. FDA laser product performance standards and ITAR export controls shape certification burdens for cross-border shipments. The Albuquerque-Phoenix defense corridor concentrates subsystem qualification activity with Sandia National Laboratories anchoring femtosecond inscription R&D.
China
Domestic fiber laser OEMs expand materials processing equipment output despite NMPA tightening of rare-earth dopant sourcing rules under dual carbon goals. MEE emissions permits for ytterbium mining and smelting constrain precursor export volumes. The Wuhan-Beijing industrial laser belt houses vertically integrated amplifier manufacturers accelerating import substitution for grating subassemblies.
Canada
Telecom infrastructure investment in Arctic submarine cables pulls chirped grating demand from TeraXion's Quebec operations. Health Canada alignment with IEC 60825-1 reduces dual-testing protocols versus GB standard markets. The Quebec City photonics cluster leverages French-language technical talent pools and EU regulatory familiarity for European export positioning.
Sweden
Proximion anchors Nordic supply for chirped gratings in telecom amplification chains serving Ericsson and Nokia submarine cable programs. Swedish environmental permitting for fluorine-doped secondary cladding aligns with EU F-Gas Regulation phase-down timelines. The Kista-Stockholm corridor concentrates fiber sensing R&D with wind turbine structural health monitoring applications emerging as a volume driver.
High Power Double-Clad Fiber Bragg Grating Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with defense procurement consolidating around qualified subassembly suppliers while industrial applications sustain spot-market fragmentation. The vendor base organizes into three tiers: vertically integrated draw-to-package specialists, femtosecond inscription technology licensors, and regional contract foundries serving sensing networks. Dominant competitive moves include captive rare-earth supply chain qualification under REACH compliance frameworks and strategic partnerships between grating fabricators and amplifier OEMs for 15-year service commitments.
Among German fabricators, FBGS Technologies GmbH and TeraXion occupy positions exemplifying the vertically integrated archetype, combining photosensitive fiber drawing with finished grating packaging. Proximion represents the Nordic specialist tier focused on telecom amplification applications. These three entities anchor approved vendor lists for German machine tool OEMs and US defense contractors consolidating procurement to single-source subassemblies.
| Leading Market Players |
|---|
| FBGS Technologies GmbH |
| Technica Optical Components |
| HBM FiberSensing |
| Micron Optics |
| Smart Fibres |
| Proximion |
| ITF Technologies |
| TeraXion |
| AOS GmbH |
| Others |
Pricing and Supply Chain Analysis
Defense procurement consolidation toward single-source grating-amplifier subassemblies with 15-year service commitments is compressing spot-market spot buying and elevating qualification barriers, forcing suppliers to absorb extended warranty costs into upfront pricing or cede share to vertically integrated German specialists.
Pricing Analysis
Distributor markups on discrete gratings for industrial sensing applications run 12-18% above direct OEM contract pricing for defense-qualified subassemblies. Three-tier pricing structure separates femtosecond-inscribed defense-grade gratings from ultraviolet-inscribed telecom variants and economy-tier electric-arc sensing products. Cost compression in standard industrial cutting applications intensifies as Chinese fiber laser OEMs scale domestic grating production. Industrial manufacturers exhibit highest price sensitivity, while defense organizations accept 40-60% premiums for REACH-compliant rare-earth supply chains and extended validation protocols.
Supply Chain Analysis
Photonics engineering talent scarcity in Jena, Munich, and Quebec City constrains expansion of precision fiber draw tower operations beyond incumbent specialists. Manufacturing gravity centers on Germany, China, and Canada, with ytterbium-doped preform fabrication drawing from Australian and Canadian rare-earth concentrate suppliers under REACH-compliant refining arrangements. Single-source vulnerability concentrates in German photosensitive fiber drawing capacity, where FBGS Technologies and TeraXion operate captive facilities. Distribution runs through direct OEM contracts for defense and telecom amplification chains, with spot-market distributors serving fragmented sensing network deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Femtosecond inscription automation and hydrogen-free process adoption are compressing production costs for premium-tier gratings while defense procurement consolidation sustains pricing power, expanding margin capture for qualified suppliers.
For Market Incumbents: Anchor defensive positioning through backward integration into rare-earth precursor refining under REACH compliance frameworks and captive femtosecond inscription capacity expansion. Lockheed Martin and Rheinmetall vendor panel consolidation threatens unqualified suppliers with exclusion from 15-year service contracts. Prioritize ISO 11146 beam quality documentation investment to compress 8-14 week validation delays. For New Entrants and Emerging Players: Enter via wind turbine structural health monitoring applications in Sweden and Norway, where embedded FBG strain sensing contracts offer 15-20 year service potential with lighter IEC 60825 certification burdens than defense markets. Target Nordic telecom infrastructure projects for chirped grating qualification. Pursue partnership routes with established amplifier OEMs rather than direct qualification with defense primes. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap specialists possessing femtosecond inscription IP and established REACH-compliant rare-earth supply chains. Five-to-ten year viability favors entities combining draw-to-package capabilities with defense vendor list placement. Monitor China's MEE emissions permit enforcement for ytterbium precursor export volume constraints as inflection signal for European supply chain repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Femtosecond Inscription Capacity Expansion | Automates hydrogen-free grating production for kilowatt-class thermal cycling tolerance in directed-energy platforms. |
| REACH-Compliant Rare-Earth Supply Agreement | Secures ytterbium precursor sourcing from Australian and Canadian concentrate suppliers, reducing Chinese import dependency. |
| Defense Vendor Panel Qualification | Unlocks 15-year service contracts with Diehl Defence and Rheinmetall for wavelength-stabilized subassemblies. |
| Wind Turbine SHM Partnership | Captures embedded sensor deployment in blade composites through Proximion-style Nordic supply positioning. |
| ISO 11146 Validation Investment | Compresses M² measurement protocol timelines to accelerate new grating design release cycles. |
Research Methodology
Direct dialogue with fiber laser OEM procurement directors, defense subsystem integrators, rare-earth concentrate traders, femtosecond inscription equipment suppliers, and ECHA regulatory affairs consultants grounded qualitative findings. Secondary validation drew from IEC 60825-1 certification databases, REACH registration filings, SEC 10-K disclosures by listed photonics firms, German customs trade statistics, and China MEE emissions permit records. Bottom-up grating shipment estimates triangulated against top-down fiber amplifier production forecasts.
Segment-level value outputs across product type, inscription technology, application, and end-user dimensions were modeled over the projection horizon. CAGRs derived from regression analysis against defense procurement budget trajectories, industrial laser system installation rates, and renewable energy infrastructure deployment schedules. Rare-earth oxide spot pricing volatility bands and femtosecond equipment cost decline curves fed sensitivity testing.
The model holds under sustained defense procurement consolidation and REACH enforcement timelines; deviation in China's dual carbon permit issuance rates or ytterbium export quota restrictions would shift supply chain cost assumptions. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.