
 Global Electrochromic Glass and Devices Market | 2026-2036
Global Electrochromic Glass and Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electrochromic Glass and Devices Market Analysis
Thin-film oxide coatings are recalibrating cost-performance benchmarks across the electrochromic value chain. Gentex Corporation leverages its automotive mirror dominance to extend proprietary dimming technology into architectural applications. Saint-Gobain S.A. anchors European supply through integrated float-glass and coating capabilities. View, Inc. competes on full-stack building automation integration, controlling hardware, installation, and cloud-based tint management.
Electrochromic glass and devices comprise multilayer thin-film assemblies—typically tungsten oxide cathodes, nickel oxide anodes, and lithium-based solid electrolytes—deposited onto conductive substrates, enabling reversible optical transmission modulation under applied voltage. These systems modulate solar heat gain and visible light transmission for energy conservation and occupant comfort in buildings and vehicles. Smart Windows command the dominant share of product-type value as commercial retrofit volumes climb, while Aviation applications represent the fastest-growing end-user segment driven by cabin dimming mandates from Boeing and Airbus programs. Solid-State technology leads on durability metrics, though Polymer variants gain ground in cost-sensitive residential markets where manufacturing simplicity outweighs cycle-life requirements.
Building energy codes enforced by the EPA and state-level regulators in the United States, alongside the EU Green Deal and F-Gas Regulation in Europe, are mandating lower solar heat gain coefficients that electrochromic glazing satisfies without fixed-tint compromises. Japan's METI sets efficiency benchmarks that favor dynamic facades in commercial new-builds. Stakeholders must monitor electrolyte material supply constraints and evolving certification reciprocity between ECHA REACH compliance and EPA toxicity evaluations as production scales beyond pilot volumes.
Market Dynamics
Thin-film deposition cost curves and solid-state electrolyte durability improvements are compressing electrochromic system economics faster than conventional glazing alternatives, forcing specification architects to recalculate lifecycle energy returns.
Growth Catalysts
- Net-zero building mandates:Germany's EnEV and the United States' state-level stretch codes mandate dynamic solar heat gain management that electrochromic facades satisfy without mechanical shading systems.
- Aviation cabin dimming programs:Boeing and Airbus fleet retrofit schedules specify electrochromic window assemblies for passenger thermal comfort and fuel efficiency gains.
- Tungsten oxide cathode refinement:Sputtering process improvements reduce switching voltage requirements and extend cycle life beyond 100,000 operations.
Market Restraints
- Lithium electrolyte supply concentration:Battery-grade lithium salt production concentrates in Chile and Australia, creating input cost volatility for solid-state electrochromic stack manufacturers.
- High capital intensity:Vacuum deposition chambers and cleanroom infrastructure require 18-24 month commissioning timelines that deter mid-scale market entrants.
- Electrochromic-to-thermochromic substitution:Passive thermochromic vanadium dioxide coatings compete on zero-energy operation in cost-sensitive residential retrofits.
Strategic Opportunities
- India commercial new-build penetration:Bureau of Energy Efficiency ECBC-R compliance deadlines create first-mover advantage for dynamic glazing suppliers in Mumbai and Bangalore development corridors.
- Automotive sunroof integration:OEM tier-1 suppliers seek electrochromic roof panel partnerships as panoramic glass area expands in electric vehicle architectures.
- EU Green Deal renovation wave:The F-Gas Regulation phase-down accelerates electrochromic adoption as static low-emissivity alternatives lose refrigerant-dependent manufacturing pathways.
Industry Challenges
- Thin-film process engineering talent scarcity:PVD and CVD specialists command premium compensation in semiconductor and display sectors, diverting human capital from electrochromic manufacturing scale-up.
- Multi-jurisdiction certification reciprocity gaps:ECHA REACH substance evaluations and EPA toxicity assessments proceed on asynchronous timelines, delaying product launch synchronization across Atlantic markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electrochromic Glass and Devices Market |
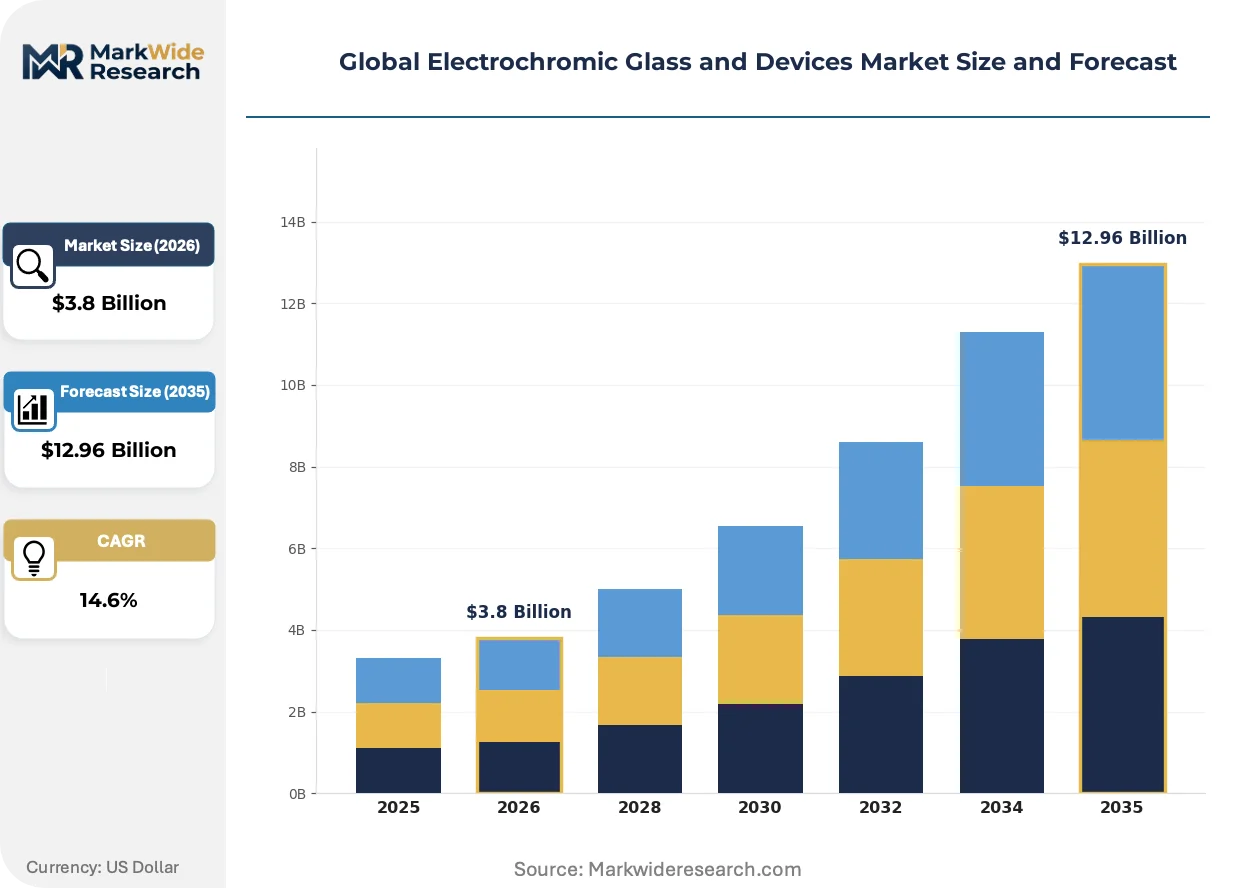
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Windows, Rearview Mirrors, Displays, Lighting Technology: Solid-State, Polymer, Thin-Film, Liquid Crystal End User: Residential, Commercial, Automotive, Aviation Application: Energy Conservation, Privacy Control, Temperature Regulation, Aesthetic Design |
| Companies Covered | View, Inc., Gentex Corporation, SAGE Electrochromics, Inc., ChromoGenics AB, AGC Inc., PPG Industries, Saint-Gobain S.A., Guardian Industries, EControl-Glas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electrochromic Glass and Devices Market Emerging Trajectories
Solid-state lithium-ion conductor architectures and roll-to-roll manufacturing adaptations are collapsing the cost-performance gap between electrochromic and conventional glazing, enabling specification in mid-market construction segments previously priced out.
Roll-to-roll sputtering of tungsten-nickel oxide multilayers onto flexible polymer substrates is expanding into curved automotive glazing and aircraft cabin window retrofits. Tier-1 suppliers in Japan and Germany are qualifying these assemblies for 15-year warranty coverage. The shift collapses tooling costs versus batch vacuum deposition and enables just-in-time supply to regional glass fabricators.
The EU F-Gas Regulation and United States EPA SNAP program are phasing down hydrofluorocarbon-dependent manufacturing processes for static low-emissivity coatings. Electrochromic systems bypass these refrigerant inputs entirely. Commercial building developers in France and California are specifying dynamic glazing specifically to avoid supply chain exposure to phasedown compliance costs.
Architects and facility managers are consolidating specification authority through building automation system integrators rather than independent glazing contractors. View, Inc. and comparable full-stack providers capture this channel shift by bundling hardware, installation, and cloud-based tint management. The pattern concentrates procurement volume in Germany, the United States, and Japan where net-zero mandates drive early technology refresh cycles.
Global Electrochromic Glass and Devices Market Segmentation
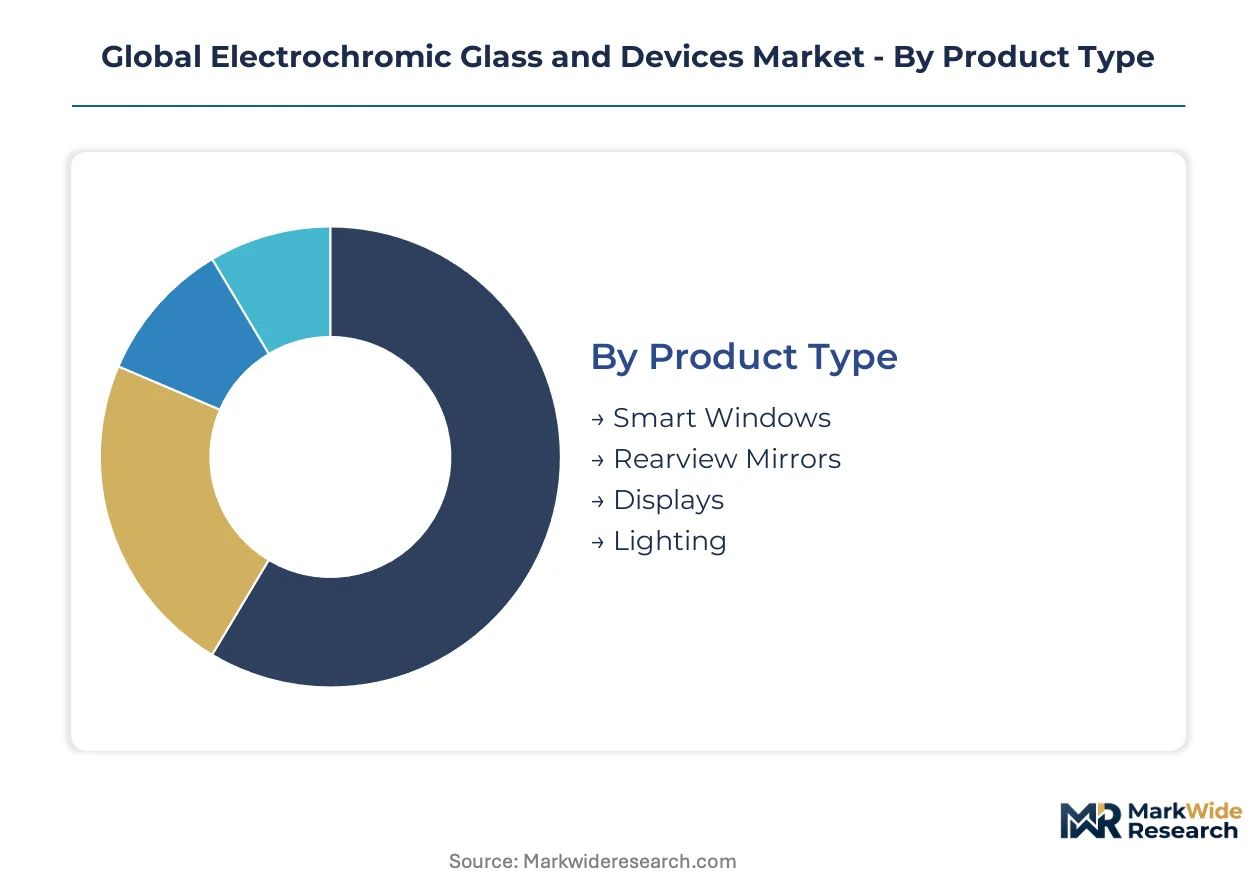
Electrochromic glass and devices segment across four distinct axes that reshape procurement patterns and manufacturing scale. Product type determines deposition process requirements. Technology choice dictates durability thresholds and switching voltage profiles. End-user concentration drives warranty terms and channel strategy.
Product Type:
Architectural specification volume clusters around facade-scale installations where thermal performance metrics dominate procurement criteria.
- Smart Windows:Multilayer tungsten oxide and nickel oxide stacks deposited onto conductive glass substrates modulate solar heat gain and visible transmission. Commercial building retrofits in Germany and the United States specify these assemblies for LEED certification and net-zero compliance, with architects controlling procurement through building automation integrators rather than independent glazing contractors.
- Rearview Mirrors:Gentex Corporation dominates automotive dimming mirror supply through proprietary electrochromic gel technology integrated with camera and sensor systems. OEM integration programs in Japan and the United States specify these units for glare reduction and advanced driver assistance compatibility.
- Displays:Small-format electrochromic cells serve electronic shelf labels and low-power signage applications.
- Lighting:Tunable electrochromic filters adjust color temperature in architectural and automotive cabin illumination.
Mature deployment sits with Smart Windows. Newer deployment is concentrated in Displays.
Technology:
Cost tier alignment separates premium durability specifications from residential retrofit accessibility.
- Solid-State:Lithium-ion conductor architectures between tungsten oxide cathodes and nickel oxide anodes deliver cycle life exceeding 100,000 switching operations. Aviation cabin dimming programs from Boeing and Airbus mandate this technology for 15-year warranty coverage, with Japan and Germany hosting qualification facilities.
- Polymer:Gel-based electrolyte systems reduce manufacturing complexity and capital intensity for cost-sensitive residential markets. Cycle life trade-offs below 50,000 operations limit deployment to seasonal-use applications where manufacturing simplicity outweighs durability requirements.
- Thin-Film:Sputtered metal oxide multilayers on flexible polymer substrates enable curved automotive glazing and aircraft retrofits.
- Liquid Crystal:Electrically switchable privacy glass operates on lower voltages without color-tint modulation capability.
Specification authority concentrates with Solid-State. Volume expansion is accelerating most quickly in Polymer.
End User:
Customer type determines installation complexity and service contract structure.
- Commercial:Building developers specify electrochromic facades for energy code compliance across California, France, and Germany. The EU F-Gas Regulation phase-down accelerates specification as static low-emissivity alternatives lose refrigerant-dependent manufacturing pathways.
- Automotive:OEM tier-1 suppliers seek electrochromic roof panel partnerships as panoramic glass area expands in electric vehicle architectures from manufacturers in Japan, Germany, and the United States.
- Aviation:Fleet retrofit schedules from Boeing and Airbus specify electrochromic window assemblies for passenger thermal comfort and fuel efficiency gains.
- Residential:Cost-sensitive retrofits compete with passive thermochromic vanadium dioxide coatings on zero-energy operation.
Procurement volume concentrates with Commercial. Steepest expansion trajectory belongs to Aviation.
Application:
Functional use case reshapes performance specification and pricing differentiation.
- Energy Conservation:Dynamic solar heat gain management satisfies EPA state-level stretch codes and Germany's EnEV without mechanical shading systems. Facility managers calculate lifecycle energy returns against conventional glazing alternatives.
- Temperature Regulation:Cabin climate control in aviation and automotive applications reduces HVAC load and extends electric vehicle range.
- Privacy Control:Switchable opacity serves healthcare and corporate environments where instant visual screening outweighs thermal performance.
- Aesthetic Design:Uniform facade appearance without external shading hardware supports architect vision in high-visibility commercial projects.
Specification frequency peaks with Energy Conservation. Emerging demand clusters around Aesthetic Design.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Bavaria and California concentrate electrochromic manufacturing investment through accelerated depreciation schedules and clean-tech tax credits. These incentive structures pull vacuum deposition equipment and thin-film engineering talent away from conventional glass hubs.
Germany
Net-zero commercial building mandates under the EnEV 2020 revision drive facade-scale procurement in Frankfurt and Munich development corridors. The EU F-Gas Regulation phase-down eliminates refrigerant-dependent low-emissivity alternatives, pushing specification toward dynamic glazing. Bavaria's Ingolstadt automotive cluster hosts qualification facilities for electrochromic roof panel integration with electric vehicle OEMs.
United States
California's Title 24 energy code and EPA state-level stretch codes mandate solar heat gain coefficients that electrochromic glazing satisfies without mechanical shading. The Inflation Reduction Act commercial building deduction accelerates retrofit timelines in Los Angeles and San Francisco. Seattle's tech campus expansion concentrates specification authority with building automation integrators rather than independent glazing contractors.
Japan
METI efficiency benchmarks for commercial new-builds favor dynamic facades in Tokyo and Osaka central business districts. Aviation cabin dimming programs from domestic aerospace suppliers create qualification demand in Nagoya's manufacturing corridor. Solid-state electrolyte durability testing facilities concentrate in Kanagawa Prefecture near Yokohama port logistics.
France
The EU Green Deal renovation wave channels public procurement toward electrochromic retrofits in Paris commercial stock. ANSM building material certification reciprocity with ECHA REACH compliance streamlines Atlantic market entry for stack manufacturers. Lyon and Grenoble host thin-film process engineering programs that feed deposition specialist demand.
India
Bureau of Energy Efficiency ECBC-R compliance deadlines for commercial new-builds create first-mover windows in Mumbai and Bangalore. CDSCO material safety evaluations proceed in parallel with BIS standards harmonization, delaying but not blocking multinational product registration. Gujarat's special economic zones attract vacuum equipment imports through duty exemptions.
Global Electrochromic Glass and Devices Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-stack providers capturing building automation procurement while component suppliers serve automotive tier-1 integration. The vendor base organizes around three strategic archetypes: integrated glass-coating conglomerates with float-line assets, pure-play electrochromic technology developers, and automotive mirror specialists extending into architectural markets. Dominant competitive moves include backward integration into solid-state electrolyte production and geographic expansion through regional glass fabricator partnerships.
Within the automotive-to-architecture extension archetype, Gentex Corporation and View, Inc. occupy positions that exemplify divergent channel strategies. Saint-Gobain S.A. anchors the integrated conglomerate tier through captive float-glass and coating capabilities. SAGE Electrochromics, Inc. sits within the pure-play technology developer segment, representing specialization without upstream glass manufacturing. These three patterns—mirror-based extension, full-stack building automation, and integrated materials conglomerate—structure competitive rivalry across end-use verticals.
| Leading Market Players |
|---|
| View, Inc. |
| Gentex Corporation |
| SAGE Electrochromics, Inc. |
| ChromoGenics AB |
| AGC Inc. |
| PPG Industries |
| Saint-Gobain S.A. |
| Guardian Industries |
| EControl-Glas |
| Others |
Supply Flow & Price Mechanics
Captive electrolyte production anchors both supply security and margin defense for electrochromic stack manufacturers confronting lithium salt volatility. Backward integration into solid-state ion conductor manufacturing insulates producers from Chilean and Australian battery-grade material swings while preserving pricing power in aviation and commercial building segments where 15-year warranty terms command premium positioning.
Pricing Analysis
Volume splits between project-scale commercial retrofits and unit-based automotive mirror shipments. Three-tier pricing structure across premium aviation-certified, standard commercial-building, and economy residential polymer tiers separates buyers by cycle-life requirements. Pricing pressure stems from thermochromic vanadium dioxide coatings in cost-sensitive residential retrofits where zero-energy operation eliminates wiring costs. Residential renovators exhibit highest price sensitivity; aviation OEMs tolerate premiums for 100,000-cycle solid-state durability.
Supply Chain Analysis
Freight costs for vacuum deposition chambers and cleanroom infrastructure from Germany and Japan inflate landed equipment expenses for regional glass fabricators in India and the United States. Sputtering targets and lithium electrolyte precursors draw from Japanese and German specialty chemical suppliers, creating single-source vulnerability for tungsten oxide cathode refinement. Distribution runs through building automation integrators in Germany, the United States, and Japan rather than independent glazing contractors, concentrating procurement leverage with full-stack providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Control over solid-state electrolyte production represents the decisive upstream lever separating margin-defensible positions from input-cost exposure.
For Market Incumbents: Lock in lithium electrolyte supply through captive production or long-term offtake with Chilean and Australian producers to neutralize the primary input volatility threat. Extend warranty coverage terms beyond 15 years for aviation and commercial segments where cycle-life certification creates switching costs against polymer-based challengers. For New Entrants and Emerging Players: Roll-to-roll sputtering onto flexible polymer substrates offers a technology-first wedge into curved automotive glazing and aircraft cabin retrofits where incumbent batch deposition tooling lacks agility. Target India's Mumbai and Bangalore commercial corridors where ECBC-R compliance deadlines outpace established supplier qualification timelines; partner with regional glass fabricators for just-in-time assembly rather than capital-intensive captive manufacturing. For Investors and Strategic Acquirers: Exit pathways concentrate in automotive-to-architecture technology extensions and full-stack building automation acquisitions. Five-to-ten year viability hinges on qualification facility access in Japan, Germany, or the United States for aviation certification. Monitor ECHA REACH and EPA toxicity assessment synchronization as the inflection signal—regulatory reciprocity gaps that persist beyond pilot-scale production will strand capital in single-jurisdiction players.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrolyte Production | Captive lithium-ion conductor supply insulates margin from Chilean and Australian salt volatility. |
| Roll-to-Roll Manufacturing Scale-Up | Flexible substrate sputtering collapses tooling costs versus batch vacuum deposition for automotive retrofits. |
| Aviation Certification Facility Investment | Boeing and Airbus 15-year warranty mandates require qualification access in Nagoya or Ingolstadt clusters. |
| Building Automation System Partnership | Channel control through integrators in Seattle and Frankfurt concentrates procurement volume away from glazing contractors. |
| Regional Fabricator Alliance Network | Just-in-time supply partnerships in Gujarat and Bavaria bypass 18-month cleanroom commissioning timelines. |
Methodological Framework
Trade publications, customs filings, and aviation certification databases formed the secondary backbone, supplemented by primary interviews with thin-film process engineers, commercial building automation integrators, and automotive Tier-1 procurement directors. Bottom-up triangulation across deposition equipment shipment records and top-down validation against building energy code adoption timelines anchored volume estimates.
Historical trendline analysis of commercial retrofit permit data and automotive sunroof content-per-vehicle trajectories informed the projection framework. Segmentation modeling spanned product type, technology architecture, end-user vertical, and regional regulatory cluster. CAGRs derived from fitted growth curves adjusted for net-zero mandate enforcement schedules and F-Gas Regulation phase-down compliance deadlines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under lithium supply disruption or thermochromic coating performance breakthroughs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Flip-Chip VCSEL Market
Optical Components
Planar Lightwave Circuit Splitter Market
Optical Components
Optical Cross Connect Market
Optical Components
Optical Dome Market
Optical Components
Acousto Optical Cavity Dumper Market
Optical Components
Electro-Optic Modulators Market
Optical Components
Optical Instruments and Lenses Market
Optical Components
Japan Lithium Niobate Modulator Market
Optical Components
Picosecond and Femtosecond Fiber Lasers Market
Optical Components
High Speed Fiber Optic Sensor Market
Optical Components
Co-Packaged Optics Market
Optical Components
Silicon Focus Ring Market
Optical Components
UAE Lithium Niobate Modulator Market
Optical Components
Optical Position Sensors Market
Optical Components
Spectroradiometers Market
Optical Components
US Optical Sensors Market