
 Europe Eye Tracking Solutions Market | 2026-2036
Europe Eye Tracking Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Eye Tracking Solutions Market Insights
Market Context
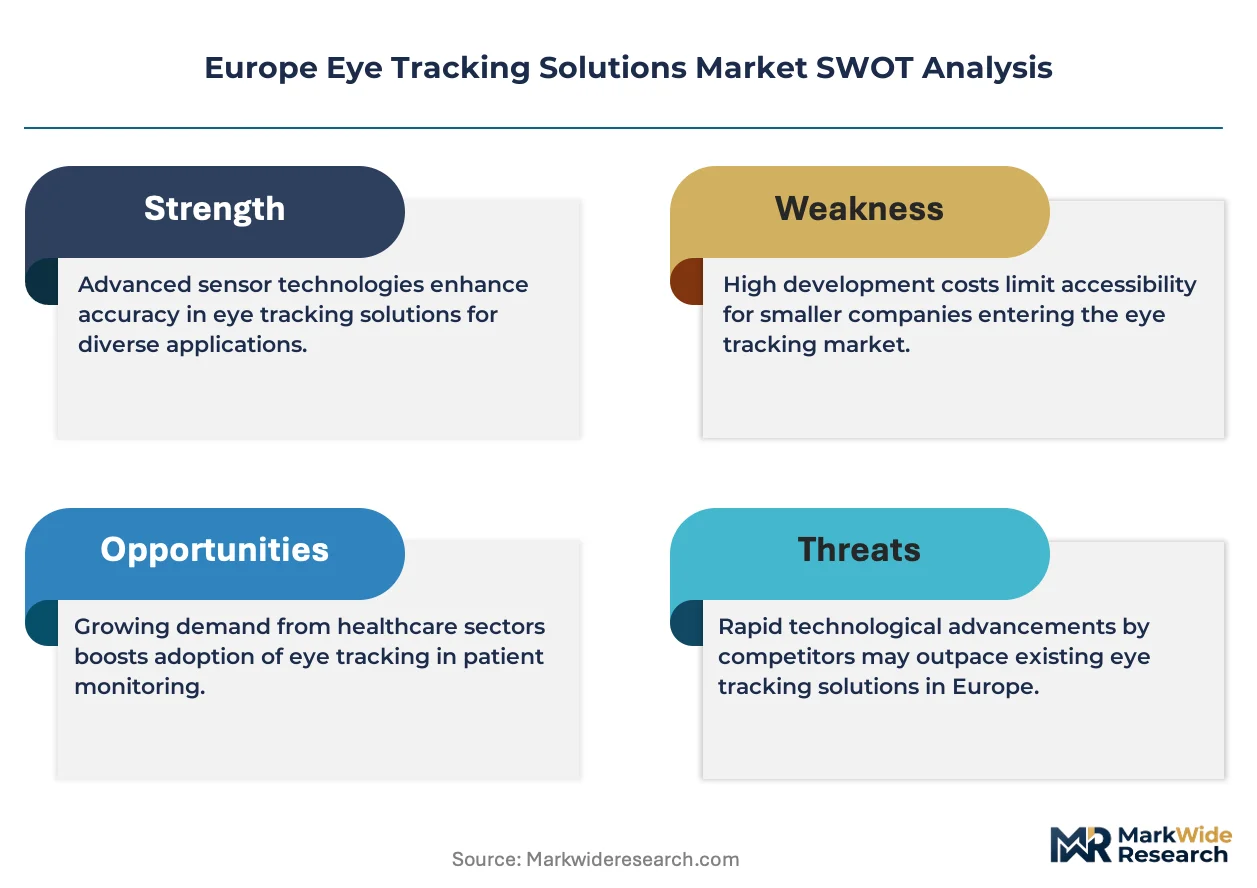
The EU AI Act's risk classification for biometric identification systems is realigning procurement criteria across European automotive and healthcare buyers. Tobii AB leverages its Stockholm-based R&D infrastructure to sustain leadership in integrated automotive eye tracking modules. Smart Eye AB dominates the driver monitoring segment through its Gothenburg engineering base and long-standing OEM relationships. Seeing Machines anchors commercial traction in heavy vehicle safety applications across continental Europe.
Technical Definition and Segment Structure
Eye tracking solutions comprise optical sensor arrays, infrared illuminators, and pupil-corneal reflection algorithms that measure gaze position, fixation duration, and saccade patterns at sampling rates typically exceeding 60 Hz for research-grade hardware. The primary commercial purpose centers on quantifying visual attention allocation for usability validation, safety-critical operator state detection, and cognitive load assessment. Hardware claims the largest revenue share due to specialized camera and illuminator component costs, while services revenue expands fastest as European enterprises outsource analytics interpretation and GDPR-compliant data governance. Remote eye tracking technology leads volume deployment in market research and academic settings, whereas wearable and integrated modalities capture premium pricing in automotive cockpit and clinical diagnostic applications.
Regulatory Frame and Outlook
The EMA's clinical evidence requirements for ophthalmic diagnostic devices, combined with GDPR's biometric data processing constraints and the EU AI Act's conformity assessment obligations, collectively elevate compliance expenditure for vendors seeking European market access. REACH chemical regulations further govern the material composition of infrared LED components used in headset-mounted hardware. Stakeholders must monitor the evolving interplay between automotive type-approval standards under UNECE regulations and emerging neurotechnology ethical guidelines from the OECD.
Market Dynamics
EU AI Act conformity assessments and GDPR biometric data processing rules are forcing hardware-software integration redesigns across European automotive and healthcare procurement pipelines.
Growth Catalysts
- EU Green Deal automotive mandates:Driver monitoring system requirements under vehicle safety regulations are pulling embedded eye tracking modules into German and Swedish OEM production lines.
- GDPR-compliant analytics services:European enterprises are outsourcing data governance and gaze-pattern interpretation to specialized vendors rather than building in-house biometric compliance teams.
- Nordic research infrastructure:Stockholm and Gothenburg academic clusters sustain demand for high-frequency sampling hardware in cognitive science and human-computer interaction studies.
Market Restraints
- Specialized infrared LED supply concentration:REACH chemical regulations constrain component sourcing for headset-mounted illuminator arrays, with limited qualified European suppliers.
- Biometric data processing friction:GDPR Article 9 special-category data rules impose documentation burdens that extend sales cycles for clinical and automotive deployments.
- Research-grade hardware cost structure:Precision optical sensor arrays and pupil-corneal reflection algorithms carry component costs that price out mid-tier usability consultancies.
Strategic Opportunities
- UNECE automotive type-approval alignment:Harmonized driver monitoring standards across EU member states create cross-border certification efficiencies for cockpit-integrated systems.
- Heavy vehicle safety applications:Fleet operators in France and Poland present underpenetrated demand for operator fatigue detection in commercial trucking and logistics.
- Remote eye tracking channel expansion:Cloud-based screen-integrated solutions bypass hardware distribution constraints and reach small-scale UX researchers in Southern and Eastern Europe.
Industry Challenges
- Embedded systems integration complexity:Automotive OEMs require real-time gaze-data fusion with existing cabin electronics, demanding specialized firmware engineering scarce in European labor markets.
- EMA clinical evidence timelines:Ophthalmic diagnostic device approvals require longitudinal validation studies that compress vendor cash conversion cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Eye Tracking Solutions Market |
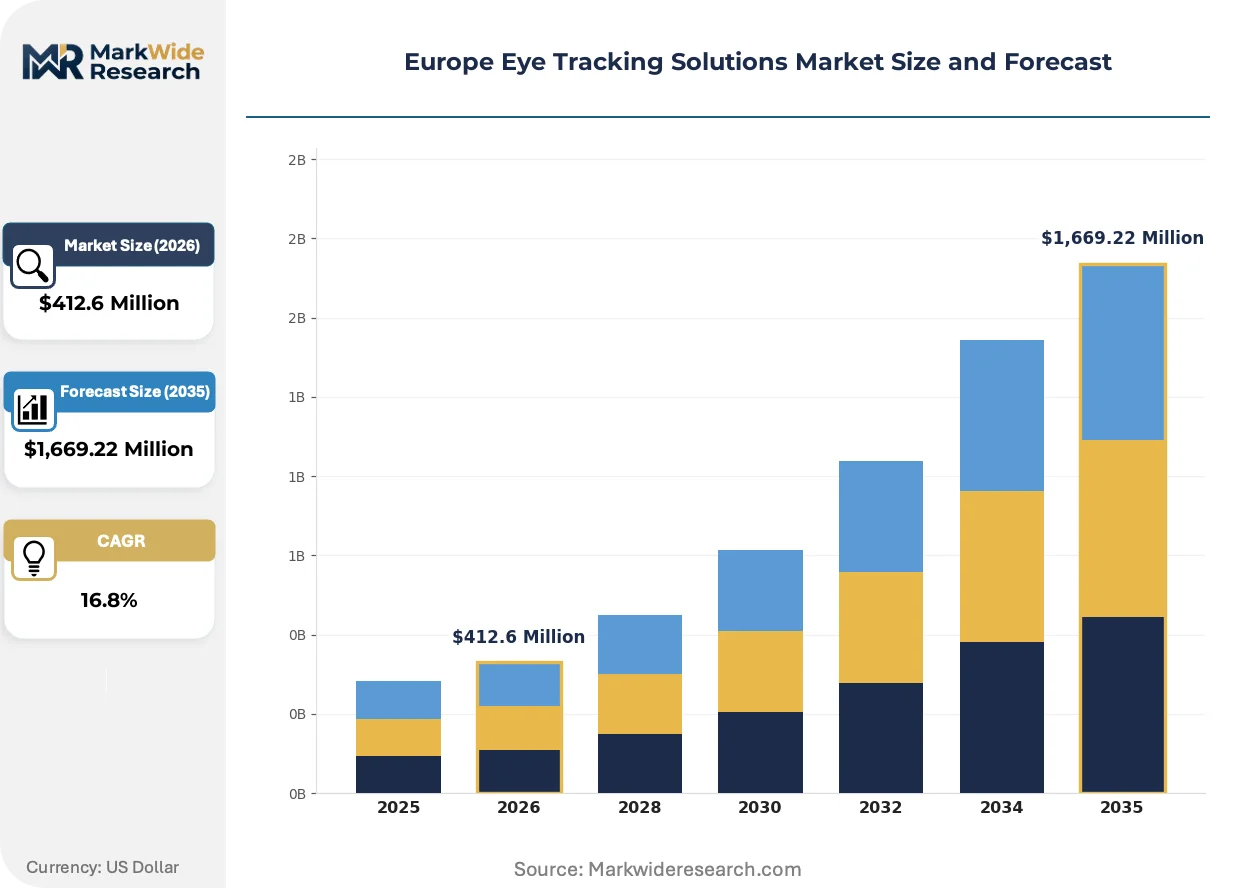
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $1,669.22 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Services, Kits Application: Market Research, Healthcare, Gaming, Automotive Testing End User: Academia, Corporate, Government, NGOs Technology: Remote, Mobile, Integrated, Wearable |
| Companies Covered | Tobii AB, Smart Eye AB, Seeing Machines, iMotions A/S, SR Research, EyeTech Digital Systems, Ergoneers GmbH, Gazepoint, EyeTracking, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Eye Tracking Solutions Market Trends and Innovations
Edge computing architectures and on-device AI inference are compressing latency requirements for safety-critical gaze detection, while regulatory harmonization efforts reshape vendor certification strategies across the continent.
Event-based vision sensors with microsecond temporal resolution are automating saccade detection for drowsiness identification in automotive applications. German Tier-1 suppliers are piloting these neuromorphic cameras for driver monitoring systems. The technology is automating real-time operator state classification that previously required post-hoc video analysis, collapsing feedback loops from minutes to milliseconds.
EU AI Act high-risk system obligations are mandating conformity assessment procedures for biometric identification deployments in healthcare and transport. Vendors must now maintain technical documentation and human oversight protocols that parallel medical device quality management systems. Swedish and Finnish healthcare procurement offices are revising tender specifications to embed these requirements.
Subscription-based analytics platforms are displacing perpetual-license software sales in European academic and corporate research segments. Buyers in Denmark and the Netherlands favor operational expenditure models that bundle hardware refreshes with GDPR-compliant data processing. This shift concentrates vendor relationships with cloud infrastructure providers and compresses margins on standalone device sales.
Europe Eye Tracking Solutions Market Segmentation
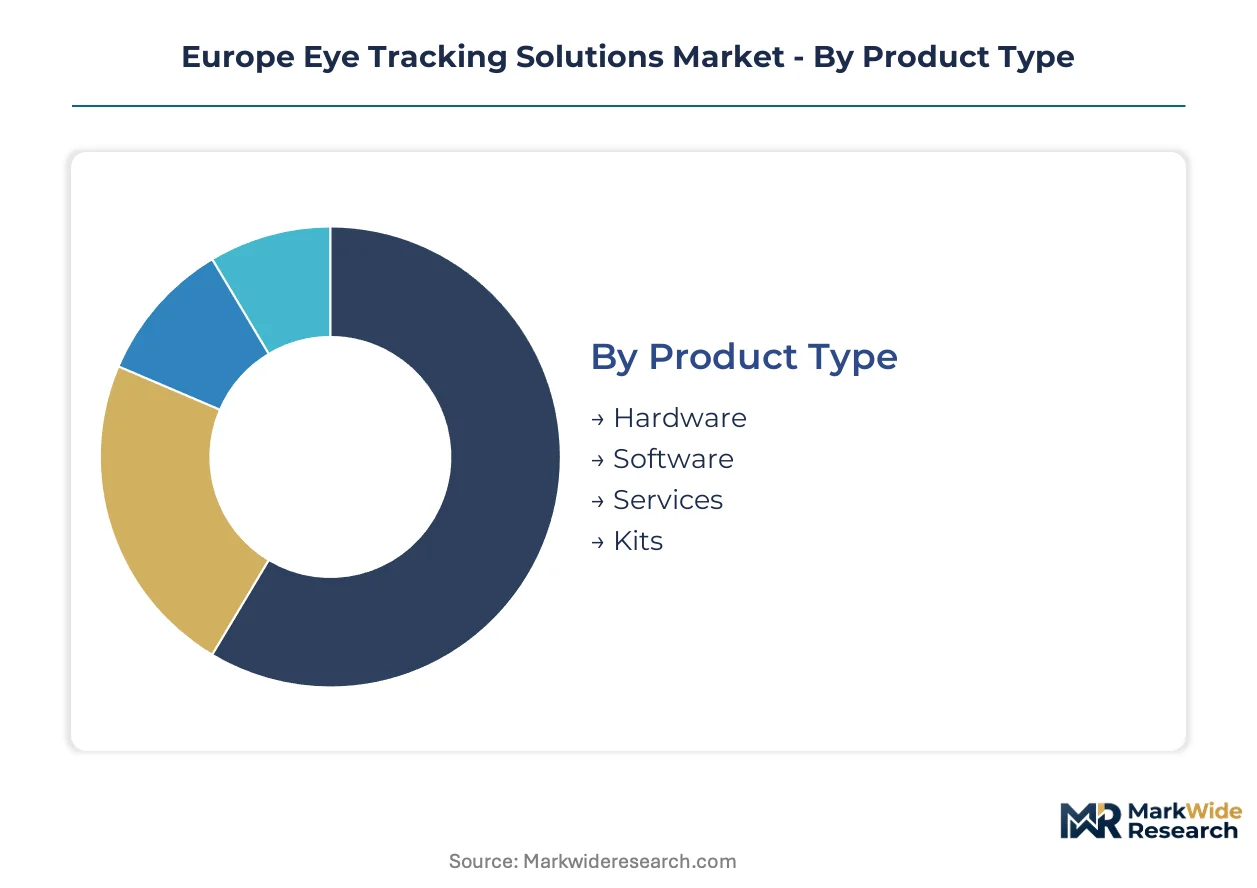
Eye tracking solutions fragment across hardware-software boundaries and deployment modalities, with each axis carrying distinct regulatory and integration requirements. European procurement patterns diverge sharply between automotive embedded systems and academic research installations.
Product Type:
Component architecture determines compliance pathways, with hardware facing REACH chemical regulations and services navigating GDPR biometric processing constraints.
- Hardware:Optical sensor arrays, infrared illuminators, and precision camera modules constitute the core physical layer. German automotive clusters and Nordic academic centers absorb the highest volumes of research-grade and automotive-embedded units, constrained by specialized infrared LED supply concentration under REACH regulations.
- Software:Pupil-corneal reflection algorithms and gaze-data analytics platforms run on local or cloud infrastructure. GDPR Article 9 documentation burdens extend sales cycles for clinical and automotive deployments across EU member states.
- Services:Outsourced analytics interpretation and GDPR-compliant data governance. Danish and Dutch buyers favor subscription models bundling hardware refreshes with compliance management.
- Kits:Bundled hardware-software packages for rapid deployment in usability labs and pilot automotive programs.
Mature deployment sits with Hardware. Newer deployment is concentrated in Services.
Application:
End-use context dictates sampling rate requirements and regulatory scrutiny levels.
- Market Research:Screen-integrated remote tracking for advertising and UX validation. Cloud-based solutions bypass hardware distribution constraints to reach Southern and Eastern European researchers.
- Healthcare:Clinical diagnostics and ophthalmic assessments face EMA evidence requirements and longitudinal validation timelines. Swedish and Finnish procurement offices are revising tender specifications to embed EU AI Act conformity obligations.
- Gaming:Consumer-facing gaze interaction systems. Lower regulatory barriers attract mid-tier European developers.
- Automotive Testing:Driver monitoring system validation under UNECE type-approval standards. German and Swedish OEM production lines pull embedded modules through Green Deal safety mandates.
Established demand concentrates in Market Research. Steepest expansion trajectory appears in Automotive Testing.
End User:
Budget cycles and procurement authority shape vendor relationship structures.
- Academia:Stockholm and Gothenburg cognitive science clusters sustain demand for high-frequency sampling hardware. Subscription analytics platforms are displacing perpetual-license sales.
- Corporate:UX consultancies and automotive Tier-1 suppliers. Research-grade hardware costs price out mid-tier usability practices.
- Government:Transport safety agencies and healthcare systems. Heavy vehicle fleet operators in France and Poland present underpenetrated fatigue detection demand.
- NGOs:Accessibility and assistive technology deployments. Limited procurement scale constrains vendor prioritization.
Volume leadership rests with Academia. Procurement momentum is shifting toward Corporate.
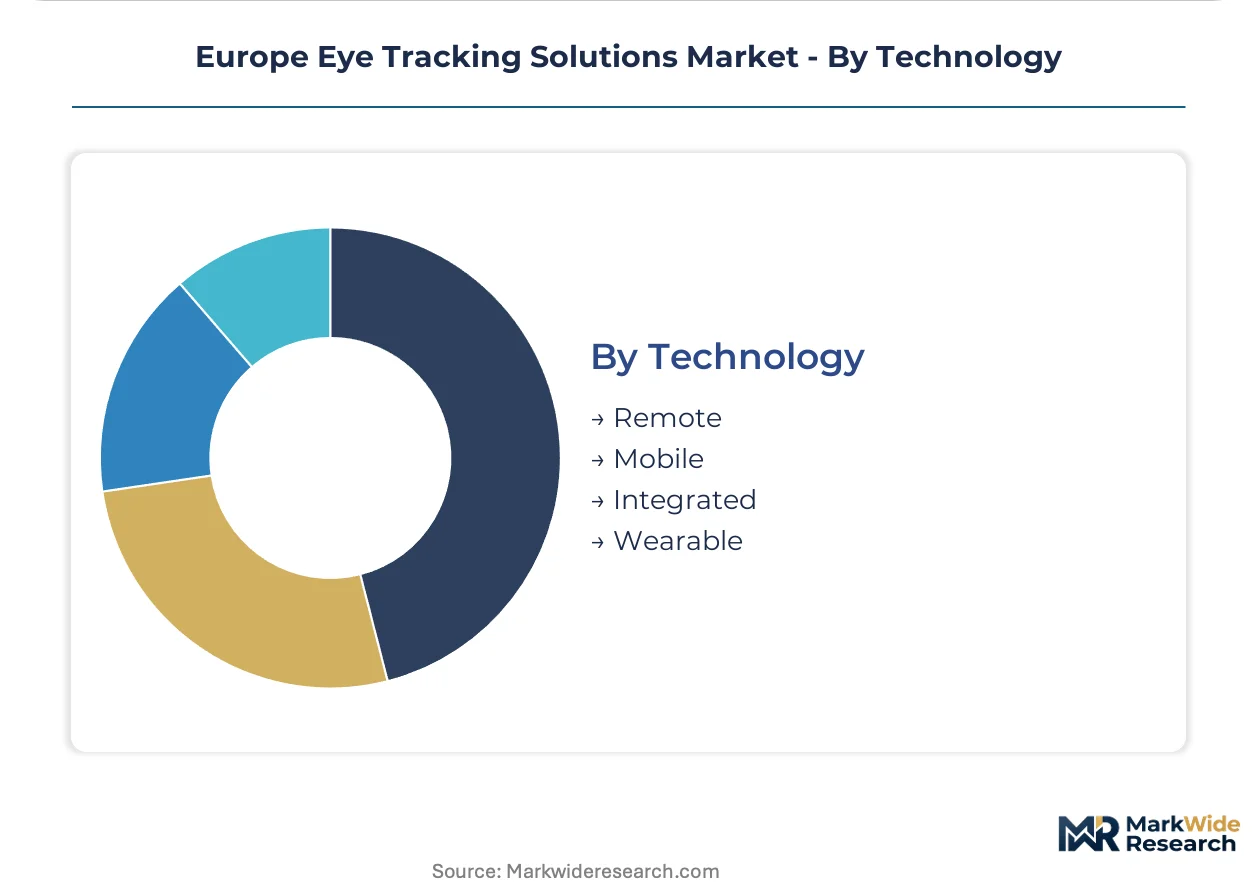
Technology:
Physical form factor determines integration complexity and latency performance.
- Remote:Screen-mounted or standalone camera arrays for non-contact gaze capture. Dominates market research and academic settings through lower per-unit cost and simplified deployment.
- Mobile:Tablet and smartphone-integrated sensors. Edge computing architectures compress latency for portable applications.
- Integrated:Cockpit-embedded modules for automotive driver monitoring. German Tier-1 suppliers pilot event-based vision sensors with microsecond temporal resolution for real-time drowsiness detection.
- Wearable:Headset-mounted glasses and VR/AR devices. REACH chemical regulations constrain infrared LED component sourcing for European manufacturing.
Volume concentration favors Remote. Premium pricing and fastest share gains concentrate in Integrated.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gothenburg and Stockholm anchor European eye tracking demand through automotive OEM partnerships and academic research infrastructure. These Nordic clusters concentrate embedded driver monitoring development and high-frequency sampling hardware procurement. The regional landscape fragments across automotive engineering hubs, healthcare procurement centers, and research-intensive metropolitan zones.
Germany
Automotive Tier-1 suppliers in Stuttgart and Munich drive embedded eye tracking module demand for driver monitoring systems. The KBA enforces UNECE type-approval standards that shape cockpit-integrated hardware specifications. Bavarian engineering clusters pilot event-based vision sensors with microsecond temporal resolution for real-time drowsiness detection.
Sweden
Gothenburg's automotive OEM relationships and Stockholm's cognitive science infrastructure sustain dual demand streams for safety-critical and research-grade systems. GDPR Article 9 compliance requirements extend sales cycles for clinical and automotive deployments. The Stockholm-Uppsala corridor concentrates high-frequency sampling hardware procurement for human-computer interaction studies.
United Kingdom
Heavy vehicle fleet operators in the Midlands and Southeast present underpenetrated demand for operator fatigue detection in commercial logistics. The Medicines and Healthcare products Regulatory Agency governs ophthalmic diagnostic device standards that parallel EMA requirements. Oxford and Cambridge academic clusters maintain research-grade hardware installations for usability validation studies.
France
Paris-based healthcare procurement offices and Lyon-region transport safety agencies drive clinical and heavy vehicle applications. ANSM and CNIL jointly oversee biometric data processing frameworks that reshape vendor compliance strategies. The Île-de-France region concentrates subscription-based analytics platform adoption among corporate UX research teams.
Netherlands
Eindhoven's high-tech systems sector and Amsterdam's digital health infrastructure support integrated wearable and remote tracking deployments. Dutch buyers favor operational expenditure models bundling hardware refreshes with GDPR-compliant data governance. The Randstad metropolitan corridor leads cloud-based screen-integrated solution adoption for mid-tier usability consultancies.
Europe Eye Tracking Solutions Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory compliance depth and automotive integration complexity. The vendor base stratifies between integrated automotive module specialists, research-grade hardware fabricators, and subscription analytics platforms. Three archetypes dominate: Stockholm-based automotive-embedded specialists, Nordic academic hardware suppliers, and cloud-native analytics services. Competitive moves concentrate on UNECE type-approval alignment and GDPR-compliant data governance outsourcing.
Among Nordic-origin specialists, Tobii AB, Smart Eye AB, and Seeing Machines exemplify distinct archetype positioning. Tobii AB anchors the integrated automotive module tier through its Stockholm-based R&D infrastructure and long-standing OEM relationships. Smart Eye AB occupies the driver monitoring systems specialization with its Gothenburg engineering concentration. Seeing Machines represents the heavy vehicle safety application segment with commercial traction across continental European fleet operators. These three entities collectively illustrate how geographic proximity to automotive clusters and regulatory expertise create defensive positioning against commodity-margin competition.
| Leading Market Players |
|---|
| Tobii AB |
| Smart Eye AB |
| Seeing Machines |
| iMotions A/S |
| SR Research |
| EyeTech Digital Systems |
| Ergoneers GmbH |
| Gazepoint |
| EyeTracking |
| Others |
Pricing and Supply Chain Analysis
Captive in-house production of infrared illuminator arrays by Stockholm-based specialists anchors supply security and sustains premium pricing power for automotive-embedded modules. This vertical integration pattern insulates Tier-1 suppliers from REACH chemical regulation disruptions while compressing margins for hardware-assemblers dependent on spot-market LED sourcing.
Pricing Analysis
Outcome-based pricing tied to driver safety incident reduction anchors automotive procurement contracts. Three-tier pricing structure across premium, standard, and economy levels separates EU AI Act-certified integrated modules from research-grade hardware and basic remote tracking units. Cost compression in mid-tier wearable devices is intensifying because Nordic academic buyers are consolidating purchases through subscription analytics platforms. Corporate UX consultancies exhibit the highest price sensitivity, whereas German OEMs prioritize certification-grade reliability over unit cost.
Supply Chain Analysis
Regional distribution centers in Stuttgart and Gothenburg operate hub-and-spoke patterns feeding automotive clusters across Germany, Sweden, and France. Infrared LED components draw from qualified European suppliers constrained by REACH chemical regulations, while precision optical sensors rest on German and Japanese fabrication capacity. Single-source vulnerability sits with specialized neuromorphic camera substrates piloted by Bavarian Tier-1 suppliers. Distribution runs through direct OEM integration contracts for embedded systems and academic procurement consortia for research hardware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Event-based vision sensors with microsecond temporal resolution are displacing frame-based camera architectures in safety-critical automotive applications. This technology transition compresses feedback loops from minutes to milliseconds and reshapes vendor competitive positioning.
For Market Incumbents: To counter margin erosion from cloud-native analytics platforms, deepen firmware engineering capacity in Gothenburg and Stockholm automotive clusters. Secure UNECE type-approval alignment ahead of harmonized driver monitoring standards across EU member states. Prioritize backward integration into event-based sensor substrate sourcing to lock in neuromorphic camera supply. For New Entrants and Emerging Players: EU AI Act conformity obligations in Swedish and Finnish healthcare procurement open a window for specialized GDPR-compliant data governance services. Heavy vehicle fleet operators in France and Poland represent the most penetrable demand pocket for operator fatigue detection systems. Lead with subscription-based analytics bundling hardware refreshes to bypass capital expenditure barriers among mid-tier usability consultancies. For Investors and Strategic Acquirers: Exit pathways concentrate in automotive-embedded module specialists with established OEM relationships and regulatory certification depth. Long-term viability hinges on sustained R&D intensity through the technology transition window. Watch for EMA clinical evidence timeline compression as the inflection signal for healthcare diagnostic device vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| UNECE Type-Approval Alignment | Harmonized certification across EU member states reduces cross-border friction for cockpit-integrated systems. |
| GDPR-Compliant Analytics Platform Launch | Subscription models bundling data governance capture procurement momentum from Danish and Dutch corporate buyers. |
| Event-Based Vision Sensor Integration | Microsecond temporal resolution automates real-time drowsiness detection for German Tier-1 suppliers. |
| Heavy Vehicle Fleet Partnership | French and Polish logistics operators present underpenetrated demand for operator state monitoring. |
| Nordic Academic Research Alliance | Stockholm-Uppsala corridor procurement sustains volume demand for high-frequency sampling hardware. |
Research Methodology
Multi-period observation of embedded module deployment rates and subscription analytics adoption anchored the trend analysis, supplemented by interviews with automotive platform engineers, Tier-1 supplier procurement leads, hospital purchasing committee members, GDPR compliance officers, and academic lab directors. Secondary validation drew from UNECE regulatory filings, EMA ophthalmic device submissions, EU AI Act conformity assessment documentation, and automotive production databases. Bottom-up vendor revenue triangulation against top-down segment sizing checked estimate consistency.
Segment-weighting across hardware, software, services, and kits product types combined with application splits in automotive testing, healthcare, market research, and gaming shaped the analytical framework. Deployment modality segmentation by remote, mobile, integrated, and wearable technology captured integration complexity differentials. CAGRs were derived from logistic adoption curve fitting against regulatory mandate timelines and OEM production plan disclosures.
The model assumes a particular technology adoption path; alternative pathways for event-based vision sensors would alter the outlook if frame-based architectures achieve comparable latency through edge computing optimization. Forecasts reflect documented assumptions about EU AI Act implementation pacing and REACH chemical regulation enforcement consistency. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Global Electrochromic Glass and Devices Market
Optical Components
Optical Encoder Market
Optical Components
CVD Sic Ring Market
Optical Components
Silicon Photonics Market
Optical Components
Co-Packaged Optics Market
Optical Components
Acousto Optic Devices Market
Optical Components
Global Optical Diode Market
Optical Components
Flexible Glass for Flexible Electronics Market
Optical Components
Infrared Filter Market
Optical Components
ROADM WSS Component Market
Optical Components
Waveguide Phase Shifter Market
Optical Components
High Speed Fiber Optic Sensor Market
Optical Components
Fiber Optic Collimating Lens Market
Optical Components
Raman Amplifier Market
Optical Components
High Power Double-Clad Fiber Bragg Grating Market
Optical Components
Laser Photomask Market