
 Optical Fiber and Plastic Conduit Market | 2026-2036
Optical Fiber and Plastic Conduit Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Fiber and Plastic Conduit Market Outlook
China is rewriting the competitive map for optical fiber and plastic conduit production through massive capacity additions in Hubei and Jiangsu provinces. Corning Incorporated leverages its proprietary low-loss fiber process to sustain premium positioning in data center interconnects. The Prysmian Group anchors European supply security through integrated cable-conduit bundling for submarine and terrestrial projects. Sterlite Technologies Ltd. dominates Indian domestic procurement through backward integration into optical fiber preform manufacturing.
Optical fiber and plastic conduit encompasses silica-based waveguides and thermoplastic or thermoset piping systems engineered to protect, route, and manage fiber optic cables across diverse environments. Single-mode fiber, with core diameters of 8–10 micrometers and attenuation below 0.2 dB/km at 1550 nm, enables long-haul transmission, while multi-mode fiber serves shorter-reach enterprise and data center links. Rigid PVC conduit commands mature, price-sensitive construction utility share, whereas flexible polyethylene conduit captures faster growth in directional drilling and microtrenching deployments where bend radius tolerance and moisture resistance determine specification. Glass fiber reinforced with specialized coatings and buffer layers remains the value concentration point, with margin pools shifting toward low-PMD (polarization mode dispersion) fibers for coherent transmission.
FCC broadband deployment mandates and the EU Green Deal's circular economy requirements for plastic materials are tightening conduit recyclability and flame-retardant standards across North American and European procurement. India's BIS certification for optical fiber cables and the country's PLI scheme for telecom equipment are accelerating indigenization of both fiber draw and extrusion capabilities. China's MIIT 5G infrastructure targets and GB standards for ducting systems enforce domestic sourcing ratios that reshape import dependency. Stakeholders must monitor evolving national security screening of submarine cable landing stations and the interplay between fiber density requirements and conduit sizing standards in next-generation metro builds.
Market Dynamics
India's BharatNet rural broadband expansion and Smart Cities Mission are compressing deployment timelines for last-mile fiber infrastructure, forcing simultaneous procurement of high-density conduit systems and low-attenuation single-mode fiber at unprecedented scale.
Growth Catalysts
- 5G Infrastructure Mandates:China's MIIT deployment targets for mid-band and millimeter-wave networks require fiber backhaul density that multiplies conduit trenching requirements in urban corridors.
- Submarine Cable Security Screening:Enhanced national security protocols for landing station infrastructure in multiple jurisdictions are accelerating replacement cycles for coastal fiber and armored conduit systems.
- Coherent Transmission Upgrades:Telecommunications operators are specifying low-PMD fiber grades to support 400G and 800G optical transport, creating specification premiums in long-haul routes.
Market Restraints
- Preform Supply Concentration:Optical fiber preform manufacturing clusters in Hubei and Jiangsu provinces create geographic dependency risk for downstream draw towers.
- Petrochemical Input Volatility:HDPE and PVC resin prices track naphtha and ethylene feedstock swings that compress conduit extrusion margins without passthrough mechanisms.
- Silica Purity Requirements:Semiconductor-grade silicon tetrachloride scarcity limits expansion of ultra-low-loss fiber capacity regardless of capital availability.
Strategic Opportunities
- Microtrenching Deployment Surge:Urban fiber densification in Indian metros is displacing open-cut trenching with narrow-slot microtrenching that specifies flexible PE conduit.
- EU Circular Economy Compliance:The EU Green Deal's recyclability mandates for construction plastics are creating specification premiums for post-consumer recycled content in conduit systems.
- Data Center Interconnect Convergence:Hyperscale cloud operators are bundling fiber and conduit procurement for campus builds, compressing vendor qualification cycles.
Industry Challenges
- Specialized Splicing Technician Scarcity:Fusion splicing for low-PMD fiber requires certification levels that outpace vocational training pipeline output in emerging deployment markets.
- Multi-Standard Certification Overlap:India's BIS cable certification, TEC approvals, and Smart Cities Mission specifications create redundant testing timelines that delay project commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Fiber and Plastic Conduit Market |
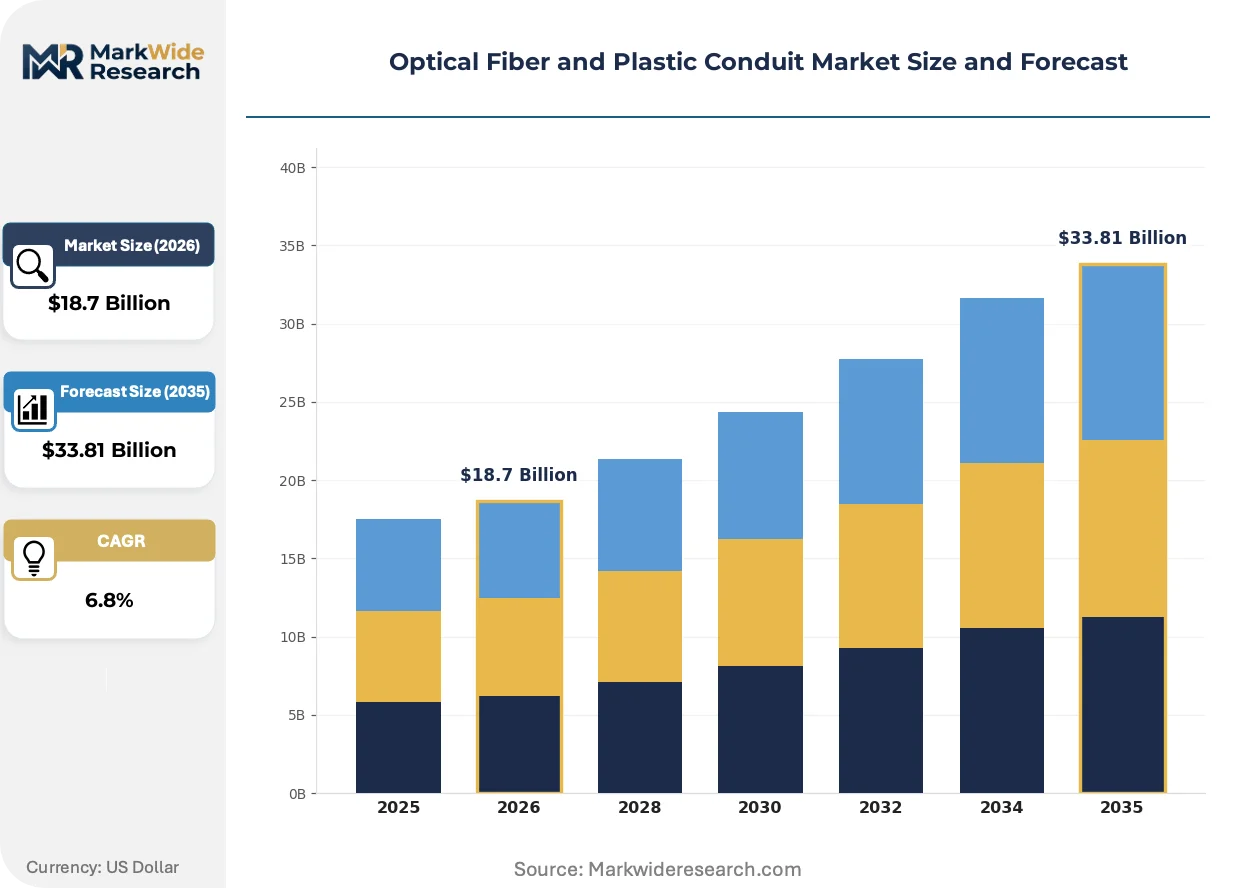
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-mode Fiber, Multi-mode Fiber, Rigid Conduit, Flexible Conduit Material: Glass, Plastic, PVC, Polyethylene End User: Telecommunications, IT Services, Construction, Utilities Installation Type: Above Ground, Below Ground, Indoor, Outdoor |
| Companies Covered | Furukawa Electric Co., Ltd., Emtelle, Corning Incorporated, Dura-Line, Hexatronic Cables & Interconnect Systems, The Prysmian Group, Sterlite Technologies Ltd., Atkore International, Fujikura Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Fiber and Plastic Conduit Market Strategic Shifts
Material science advances and deployment methodology shifts are compressing the traditional separation between fiber performance tiers and conduit mechanical specifications, forcing integrated system design.
Multi-fiber pushable cable is hybridizing conventional blown fiber installation with direct-bury mechanical protection, enabling distribution network builders to collapse two construction phases into one. Rural electrification utilities in India are adopting this combined approach for BharatNet last-mile extensions. The technology is hybridizing procurement patterns by eroding the historical separation between cable and conduit specification committees.
The EU Green Deal's circular economy requirements for plastic construction materials are mandating recyclability disclosures and recycled content minimums that reshape conduit compound formulation. European infrastructure funds now screen bids for environmental product declarations. HDPE conduit grades with post-consumer recycled content are capturing specification share in German and French utility corridor projects.
Hyperscale data center operators are consolidating fiber and conduit purchasing under single-source contracts that unbundle traditional distributor markups. Cloud campus developers in Virginia and Oregon are qualifying direct manufacturer relationships for multi-year supply security. This concentration is most visible in North American markets where Meta, Amazon, and Microsoft account for disproportionate metro fiber demand.
Optical Fiber and Plastic Conduit Market Segmentation
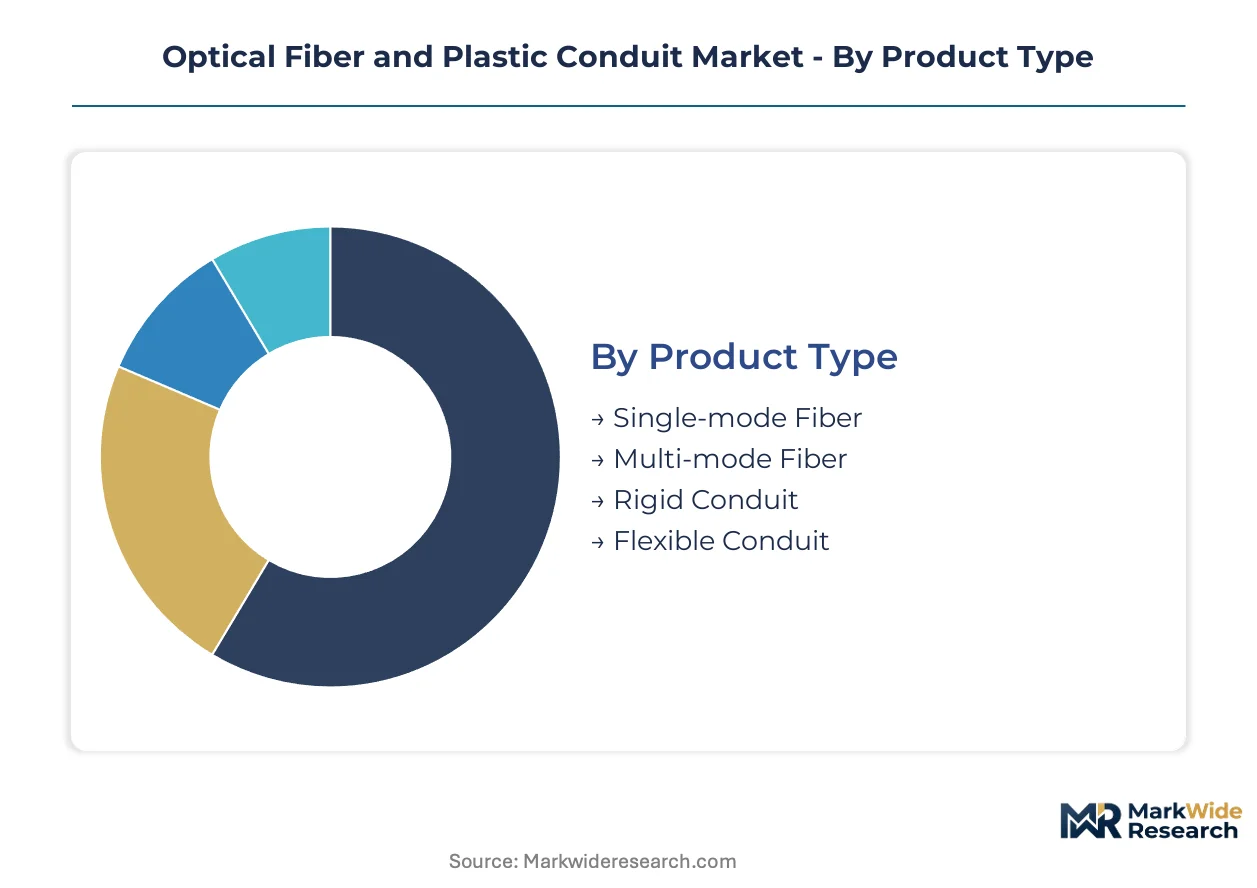
Optical fiber and plastic conduit procurement splits across transmission physics, mechanical protection needs, and deployment environment constraints. Specification committees rarely align on single hierarchies, forcing vendors to qualify across overlapping taxonomies.
Product Type:
Use-case spectrum spans long-haul photonics through short-reach enterprise switching to utility-grade mechanical protection systems.
- Single-mode Fiber:Silica waveguides with 8–10 micrometer cores and sub-0.2 dB/km attenuation at 1550 nm enable coherent 400G/800G transmission. BharatNet rural backhaul and submarine cable rebuilds concentrate demand for ultra-low-loss grades.
- Flexible Conduit:High-density polyethylene formulations tolerate directional drilling bend radii below 10× outer diameter. Indian metro microtrenching deployments favor these specifications over rigid alternatives for last-mile fiber densification.
- Multi-mode Fiber:50–62.5 micrometer core diameters serve data center interconnects under 550 meters.
- Rigid Conduit:PVC formulations dominate mature construction utility markets with price-sensitive procurement.
Established volume favors rigid conduit; emerging adoption favors flexible conduit.
Material:
Cost tier separation runs from semiconductor-grade silica through commodity thermoplastics to recycled-content compounds.
- Glass:Doped silica cores with germanium or fluorine profiles determine refractive index engineering. Coherent transmission upgrades concentrate premium demand in submarine and long-haul terrestrial routes.
- Polyethylene:HDPE grades with UV stabilizers and recycled content minimums capture EU Green Deal-compliant utility corridor specifications in Germany and France.
- Plastic:Generic thermoplastic compounds serve cost-optimized construction markets without performance premiums.
- PVC:Rigid formulations with flame-retardant additives dominate indoor riser and plenum installations.
Glass commands margin concentration; polyethylene gains specification share fastest.
End User:
Customer type fragmentation separates capex-heavy infrastructure owners from opex-optimized service operators.
- Telecommunications:Tier-1 operators specify low-PMD fiber for coherent transport and armored conduit for submarine landing stations. TRAI's BharatNet procurement timelines compress vendor qualification cycles.
- IT Services:Hyperscale cloud operators bundle fiber and conduit under single-source campus contracts in Virginia and Oregon.
- Construction:General contractors source rigid PVC through distributor channels with limited technical specification.
- Utilities:Rural electrification boards in India adopt pushable cable-conduit hybrids for BharatNet extensions.
Telecommunications anchors volume commitment; IT services drives pricing compression.
Installation Type:
Deployment environment dictates mechanical specification, environmental sealing, and regulatory compliance pathways.
- Below Ground:Direct-bury and microtrenching deployments specify moisture-barrier HDPE conduit with crush resistance exceeding 1,250 N. Indian Smart Cities Mission corridors concentrate demand.
- Indoor:Plenum-rated PVC with low-smoke zero-halogen formulations serves data center and enterprise riser applications.
- Above Ground:Aerial lashings and pole-mounted assemblies dominate rural extensions with limited trenching access.
- Outdoor:UV-stabilized jackets and armored overlays protect coastal and industrial exposure zones.
Below ground commands capital intensity; indoor captures recurring upgrade cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT's 5G infrastructure mandates anchor the dominant geography, with China's deployment targets cascading through regional supply chains and procurement patterns. Capacity additions in Hubei and Jiangsu provinces reshape import dependencies across Asia-Pacific markets.
China
Mid-band and millimeter-wave network buildouts multiply fiber backhaul density requirements in urban corridors. MIIT enforces domestic sourcing ratios through GB standards for ducting systems that limit foreign supplier participation. Hubei province hosts concentrated optical fiber preform manufacturing clusters serving downstream draw towers.
India
BharatNet rural broadband expansion and Smart Cities Mission compress deployment timelines for last-mile infrastructure at unprecedented scale. TRAI procurement timelines and BIS cable certification accelerate indigenization of fiber draw and extrusion capabilities. Maharashtra and Gujarat host Sterlite Technologies' backward-integrated preform operations serving domestic procurement.
United States
FCC broadband deployment mandates tighten conduit recyclability and flame-retardant standards across procurement programs. National security screening protocols for submarine cable landing stations accelerate replacement cycles for coastal infrastructure. Virginia and Oregon data center campuses concentrate hyperscale fiber and conduit bundling demand.
Germany
EU Green Deal circular economy requirements mandate recyclability disclosures and recycled content minimums for construction plastics. ECHA oversight of REACH compliance reshapes HDPE compound formulation for utility corridor specifications. Industrial clusters in North Rhine-Westphalia pilot post-consumer recycled content conduit for infrastructure funds.
Japan
Coherent transmission upgrades to 400G and 800G optical transport specify low-PMD fiber grades for long-haul routes. METI industrial policy supports domestic silica purification capabilities for ultra-low-loss fiber production. Kanto region submarine cable manufacturing maintains armored conduit integration for landing station security protocols.
Optical Fiber and Plastic Conduit Market Competitive Environment
Vertically integrated fiber-conduit bundlers and specialized component suppliers split the market along capability depth versus portfolio breadth. The vendor base concentrates around three strategic archetypes: upstream preform manufacturers with captive fiber draw, integrated cable-conduit system bundlers, and regional extrusion specialists serving price-sensitive construction utility procurement. Dominant competitive moves include backward integration into optical fiber preform manufacturing and strategic bundling of cable-conduit systems for infrastructure project tenders.
Among the integrated system bundlers, Corning Incorporated and The Prysmian Group exemplify archetypes combining proprietary process technology with project-scale procurement relationships. Sterlite Technologies Ltd. anchors the upstream-integrated tier through captive preform production serving Indian domestic markets. These three occupy positions that span the value concentration points from semiconductor-grade silica through finished conduit system deployment.
| Leading Market Players |
|---|
| Furukawa Electric Co., Ltd. |
| Emtelle |
| Corning Incorporated |
| Dura-Line |
| Hexatronic Cables & Interconnect Systems |
| The Prysmian Group |
| Sterlite Technologies Ltd. |
| Atkore International |
| Fujikura Ltd. |
| Others |
Value Chain & Pricing Dynamics
Hubei province's concentrated preform manufacturing clusters wield asymmetric pricing power over downstream fiber draw towers worldwide. Capacity additions in Jiangsu and Hubei compress margins for non-integrated converters while amplifying premium capture for captive producers.
Pricing Analysis
Price spreads between Chinese export grades and EU-certified product tiers exceed 40% on delivered basis. Three-tier pricing structure across premium, standard, and economy levels separates submarine-grade low-PMD fiber from BharatNet rural specifications and generic construction conduit. Cost compression in rigid PVC conduit intensifies because petrochemical feedstock volatility lacks passthrough mechanisms. Construction contractors exhibit highest price sensitivity; hyperscale data center operators show least.
Supply Chain Analysis
Export-control regimes on semiconductor-grade silicon tetrachloride purification technology restrict capacity expansion outside authorized jurisdictions. Supply concentrates in China, Japan, and USA for optical fiber; HDPE resin feeds from South Korea, Saudi Arabia, and Singapore. Raw material dependencies center on high-purity silica, germanium tetrachloride dopants, and naphtha-derived ethylene. Single-source vulnerability pervades preform supply. Distribution runs through project-integrated bundlers and regional extrusion specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards service-attach strategies as fusion splicing certification programs and long-term maintenance contracts expand faster than commodity fiber and conduit hardware sales.
For Market Incumbents: Harden supply security through captive preform production or exclusive offtake agreements with Hubei cluster operators. Deepen certification moats by embedding BIS and TEC compliance into bundled project offerings before TRAI procurement timelines compress further. Threat substitution from wireless backhaul alternatives demands fiber performance premiums that only low-PMD grades can sustain.
For New Entrants and Emerging Players: Establish a beachhead in EU Green Deal-compliant recycled-content conduit formulations where ECHA oversight creates qualification barriers for incumbent compounders. Target German and French utility corridor projects screening for environmental product declarations. Go-to-market leverage rests on circular economy certification partnerships with infrastructure fund technical advisors.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with stranded optical fiber assets lacking scale to serve coherent transmission upgrades. Five-to-ten-year viability hinges on backward integration depth. Watch for MIIT domestic sourcing enforcement tightening as inflection signal for import-dependent converter distress.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Preform Manufacturing | Sterlite Technologies' captive Hubei supply secures Indian BharatNet procurement preference. |
| Recycled Content Conduit Formulation | EU Green Deal mandates force HDPE compound reformulation for German utility corridor eligibility. |
| Microtrenching Deployment Partnership | Maharashtra Smart Cities Mission specifies flexible PE conduit for narrow-slot urban fiber densification. |
| Low-PMD Fiber Grade Qualification | Coherent 400G/800G transport upgrades concentrate premium demand in submarine and long-haul routes. |
| Single-Source Campus Supply Contract | Hyperscale operators in Virginia bundle fiber and conduit procurement, eliminating distributor markups. |
Study Parameters
A standing panel of fiber draw tower operators, conduit extrusion plant managers, TRAI procurement officers, and Smart Cities Mission technical consultants provided ongoing calibration against secondary validation. Primary interviews combined with customs trade data, BIS certification registries, SEC 10-K filings from listed fiber manufacturers, and MIIT infrastructure deployment disclosures enabled bottom-up and top-down triangulation.
Scenario bracketing around petrochemical input volatility, MIIT domestic sourcing enforcement intensity, and BharatNet timeline compression anchored the analytical framework across the analysis window. Segmentation dimensions modeled include fiber transmission physics, conduit mechanical specifications, installation environment constraints, and end-user procurement archetypes. CAGRs derived from installed base replacement cycles and greenfield deployment pipelines, with specific weighting for 5G backhaul density multipliers and submarine cable security screening replacement demand.
Stress conditions across silica tetrachloride supply disruption, ethylene feedstock price bands, and TRAI procurement timeline slippage were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about coherent transmission upgrade adoption curves and EU circular economy enforcement timing. Material shifts in MIIT export control expansion or FCC national security screening protocol extension would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
South Korea Optical Detector Market
Optical Components
Optical Encoder Market
Optical Components
Bio-Optics Market
Optical Components
Optical Spectrum Analyzer (OSA) Market
Optical Components
Optical Image Stabilization (OIS) Actuators Market
Optical Components
Pancake Optical Module Market
Optical Components
Ring Panel Filters Market
Optical Components
Co-Packaged Optics Market
Optical Components
Liquid Lenses Market
Optical Components
Polarizer Film Market
Optical Components
Ellipsometer Market
Optical Components
Planar Lightwave Circuit Splitter Market
Optical Components
Fiber-Optic Attenuator Market
Optical Components
Microchannel Plates Market
Optical Components
Optical Position Sensors Market
Optical Components
Global Wavelength Division Multiplexing (WDM) Equipment Market