
 PFC Control IC Market | 2026-2036
PFC Control IC Market Size, Share, and Industry Trends Forecast 2026-2036
PFC Control IC Market Insights
Server power supplies and EV charging infrastructure is pivoting toward higher-efficiency architectures, pulling demand for advanced PFC control solutions. STMicroelectronics leverages its European manufacturing base to sustain leadership in automotive-grade PFC controllers. Infineon Technologies anchors its position through silicon carbide integration, while Texas Instruments competes aggressively on digital control architectures for data center applications.
A PFC Control IC is an active semiconductor device that shapes input current waveforms to match sinusoidal voltage, typically operating at switching frequencies between 50 kHz and 200 kHz to minimize harmonic distortion and maximize power factor. Integrated circuits within the component segment command the deepest margin pools due to their firmware-programmable compensation networks and multi-mode operation. Active PFC technology leads absolute volume, though digital control is displacing analog architectures in applications above 1 kW where adaptive algorithms reduce component count.
The U.S. Department of Energy and the EU Ecodesign Directive shape demand through mandatory minimum efficiency thresholds and standby power limits. IEC 61000-3-2 Class D compliance requirements force redesigns in consumer electronics and industrial equipment, tightening market access for non-compliant suppliers. Stakeholders must monitor how wide-bandgap semiconductor pairing with digital PFC controllers reshapes cost structures and design cycles.
Market Dynamics
Wide-bandgap semiconductor pairing with digital PFC controllers is compressing design cycles and forcing analog-centric suppliers toward firmware-programmable architectures. This technological inflection concentrates margin capture among integrated device manufacturers with captive SiC or GaN supply.
Growth Catalysts
- EU Ecodesign Directive:Mandatory standby power limits and minimum efficiency thresholds in server power supplies are mandating active PFC deployment across data center infrastructure.
- China EV production:Domestic electric vehicle manufacturing expansion is pulling demand for automotive-grade PFC controllers into high-volume supply contracts.
- IEC 61000-3-2 Class D:Harmonic distortion compliance requirements in consumer electronics are forcing redesigns that displace passive PFC solutions.
Market Restraints
- Silicon carbide wafer supply:Tightness in 150mm SiC substrate availability from Wolfspeed and Coherent is constraining controller-die pairing for high-frequency designs.
- Analog engineering talent:Scarcity of power electronics specialists with mixed-signal compensation network expertise is elongating development timelines.
- GaN reliability qualification:Extended HV-H3TRB testing requirements for automotive gate drivers are adding eighteen months to product release cycles.
Strategic Opportunities
- India power supply manufacturing:PLI scheme incentives for electronics manufacturing are attracting PFC controller design-in activity for export-oriented adapter production.
- Digital-analog convergence:Hybrid architectures combining digital loops with analog comparators are opening mid-power appliance segments previously locked to analog-only solutions.
- V2G bidirectional charging:Vehicle-to-grid infrastructure mandates in California and Germany are creating demand for PFC stages with reactive power capability.
Industry Challenges
- Firmware security certification:IEC 62443 compliance for digitally controlled power stages is requiring embedded cryptography expertise that analog-era teams lack.
- Multi-mode compensation tuning:Transitioning between CRM and CCM operation across load ranges is demanding automated calibration equipment that raises capex thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PFC Control IC Market |
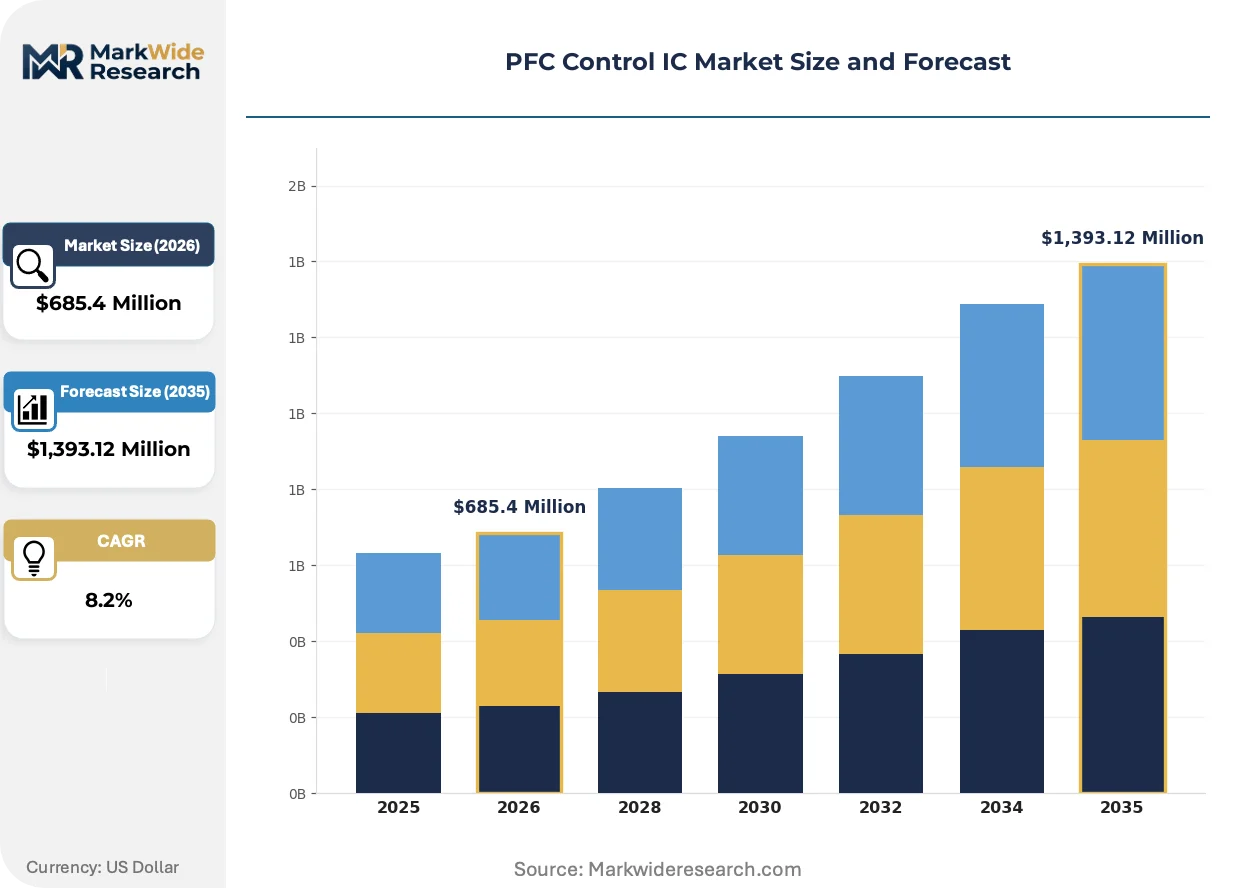
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,393.12 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Integrated Circuits, Discrete Components, Controllers, Modules Application: Consumer Electronics, Industrial Equipment, Renewable Energy, Automotive Power Systems Technology: Active PFC, Passive PFC, Hybrid PFC, Digital Control End User: OEMs, Aftermarket Providers, System Integrators, Component Distributors |
| Companies Covered | STMicroelectronics, Power Integrations, NXP Semiconductors, Microchip Technology, Infineon Technologies, ON Semiconductor, Monolithic Power Systems, Sanken Electric, Texas Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PFC Control IC Market Trends and Innovations
Active semiconductor materials and control firmware are converging to redefine efficiency benchmarks and design methodologies. These shifts are compressing traditional analog supply chains while elevating software-defined power architecture.
Silicon carbide MOSFETs paired with digital PFC controllers are absorbing switching losses that previously limited frequency scaling in CCM boost stages. Data center power supply designers at hyperscale operators are adopting these pairings for 3kW+ server PSU designs. This absorption of thermal constraints is enabling planar magnetics and reducing core volumes by half versus silicon superjunction alternatives.
The U.S. Department of Energy efficiency mandates for external power supplies are tightening no-load consumption limits below 100mW. These rules are forcing adapter manufacturers toward active PFC even in sub-75W products historically served by passive circuits. China-based power supply exporters are responding with integrated controller-MOSFET combinations that minimize external component counts.
Direct procurement of reference designs from semiconductor vendors is displacing traditional distributor-led technical support models. Mid-tier power supply houses in Taiwan and South Korea are licensing complete digital PFC firmware stacks rather than developing proprietary algorithms. This channel compression is most visible in 500W-2kW industrial adapter segments where time-to-certification dominates purchasing criteria.
PFC Control IC Market Segmentation
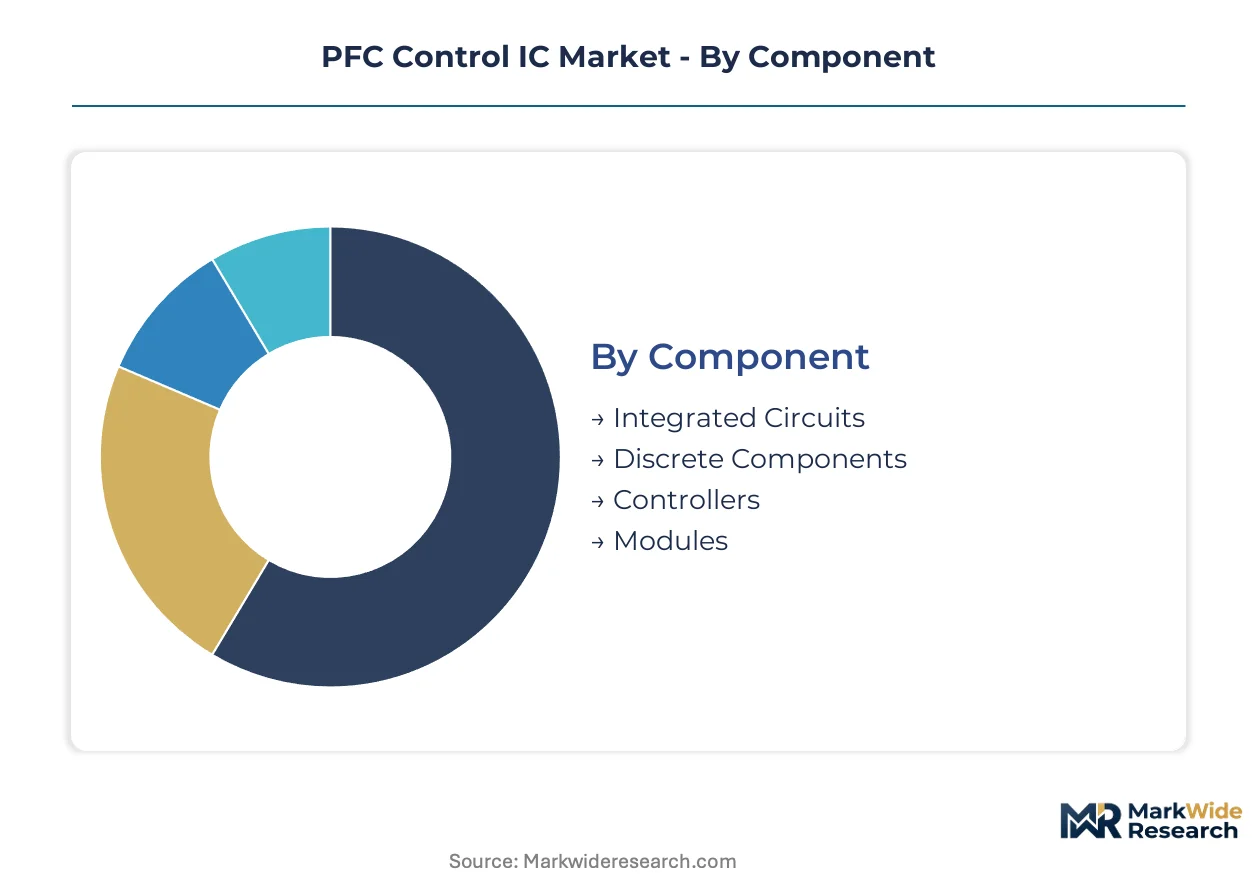
PFC control IC procurement decisions pivot on power density targets, certification requirements, and switching frequency demands. Component selection cascades through system architecture choices, determining whether designs employ analog compensation networks or firmware-programmable digital loops.
Component:
Standardization dominates at the die level, while customization intensifies at the module and subsystem tier where thermal management and gate drive integration vary by application.
- Integrated Circuits:Monolithic devices embed PWM engines, error amplifiers, and protection logic on single silicon. Demand concentrates in server power supplies where the U.S. Department of Energy mandates push designs toward active PFC even in sub-100W adapters. Firmware-programmable compensation networks command premium positioning.
- Discrete Components:Standalone controllers paired with external MOSFETs and gate drivers offer flexibility for multi-kilowatt industrial designs. Procurement from China-based power supply manufacturers dominates volume, driven by domestic EV charging infrastructure buildout and export-oriented adapter production.
- Controllers:Dedicated PFC state machines without power integration serve cost-sensitive appliance segments.
- Modules:Pre-integrated power stages combining controller, driver, and wide-bandgap switches accelerate time-to-market for automotive onboard chargers.
Most installed capacity flows through Integrated Circuits. Expansion is steepest in Modules.
Application:
Volume concentrates in consumer-facing products, while margin pools deepen in automotive and industrial segments where qualification cycles extend eighteen to thirty-six months.
- Consumer Electronics:External adapters, LED drivers, and white goods represent high-volume, price-sensitive demand. IEC 61000-3-2 Class D compliance requirements in the EU and equivalent GB standards in China force redesigns away from passive solutions.
- Automotive Power Systems:Onboard chargers, DC-DC converters, and traction inverters demand AEC-Q100 qualified controllers with functional safety support. Germany's KBA and California's V2G infrastructure mandates pull demand for bidirectional-capable PFC stages with reactive power control.
- Industrial Equipment:Motor drives, welding systems, and UPS units require robust operation across wide input voltage ranges.
- Renewable Energy:Solar inverters and energy storage systems prioritize efficiency at partial load conditions.
Consumer Electronics absorbs the highest unit volumes. Automotive Power Systems is gaining share fastest.
Technology:
Analog architectures retain footholds below 500W, while digital control displaces incumbent solutions above 1kW where adaptive algorithms reduce magnetic component counts.
- Active PFC:Boost-derived topologies with continuous or critical conduction mode operation dominate above 75W. Data center operators at hyperscale facilities specify these for 3kW+ server PSU designs paired with silicon carbide MOSFETs.
- Digital Control:Firmware-implemented loops enable multi-mode operation, automatic compensation tuning, and telemetry reporting. Reference design licensing from semiconductor vendors is displacing proprietary algorithm development among Taiwan and South Korea adapter manufacturers.
- Passive PFC:Valley-fill circuits and inductor-based solutions persist only in lowest-cost, non-regulated markets.
- Hybrid PFC:Analog comparators combined with digital state machines target mid-power appliance segments.
Active PFC commands the largest installed base. Digital Control is expanding most quickly.
End User:
Direct procurement patterns diverge sharply: OEMs engage semiconductor vendors for reference designs, while distributors serve fragmented aftermarket demand with technical support margins.
- OEMs:Original equipment manufacturers in power supply, appliance, and automotive sectors specify controllers at the platform architecture phase. India's PLI scheme incentives are attracting design-in activity for export-oriented adapter production.
- System Integrators:Industrial automation and renewable energy project developers source PFC stages as subassemblies.
- Component Distributors:Arrow, Avnet, and regional equivalents stock standard analog controllers for replacement and repair markets.
- Aftermarket Providers:Repair services and refurbishment operations demand pin-compatible substitutes.
OEMs channel the majority of volume. System Integrators are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is shifting PFC controller procurement toward jurisdictions with subsidized compliance infrastructure and concentrated power electronics manufacturing ecosystems. Cost-of-compliance gaps between mature and emerging production bases are accelerating design-in activity migration.
China
Domestic EV production and server power supply exports dominate volume demand for PFC control ICs. GB standards harmonized with IEC 61000-3-2 Class D mandate active PFC in consumer electronics and industrial equipment. The Yangtze River Delta and Pearl River Delta clusters host captive controller design centers serving tier-one adapter manufacturers and automotive tier suppliers.
Germany
Automotive onboard chargers and industrial drives anchor demand for AEC-Q100 qualified controllers with functional safety support. The KBA mandates bidirectional charging capability for V2G infrastructure, forcing PFC stage redesigns with reactive power control. Bavaria and Baden-Württemberg concentrate automotive semiconductor R&D and qualification facilities.
United States
Hyperscale data center operators specify digital PFC controllers for 3kW+ server PSU designs under Department of Energy efficiency mandates. The EPA and FERC efficiency rules tighten no-load consumption limits below 100mW for external adapters. Texas and California host power supply design houses licensing reference firmware stacks from semiconductor vendors.
India
Export-oriented adapter production and domestic appliance manufacturing pull demand for cost-optimized PFC solutions. PLI scheme incentives for electronics manufacturing attract controller design-in activity from multinational power supply houses. Gujarat and Tamil Nadu industrial corridors concentrate EMS facilities serving European and North American OEMs.
Japan
Industrial motor drives and high-reliability power supplies sustain demand for analog-compensation PFC controllers with extended temperature ratings. METI efficiency standards and JIS certification requirements enforce harmonic limits in factory automation equipment. The Chubu and Kansai regions maintain precision manufacturing clusters for industrial power electronics.
PFC Control IC Market Competitive Landscape
Strategic partnerships dominate the current landscape as integrated device manufacturers secure captive wide-bandgap semiconductor supply. The vendor base stratifies across three tiers: diversified semiconductor conglomerates with automotive qualification infrastructure, pure-play power management specialists, and regional analog controller houses. European and Japanese conglomerates anchor the premium tier through AEC-Q100 portfolios. Digital-analog convergence and SiC controller pairing represent the two dominant competitive vectors reshaping R&D allocation.
Within the diversified semiconductor tier, STMicroelectronics exemplifies European automotive-grade positioning, while Infineon Technologies occupies a position centered on wide-bandgap integration. Texas Instruments represents the digital control architecture archetype targeting data center applications. These three anchors illustrate how geographic manufacturing bases and technology roadmaps segment competitive positioning across server, automotive, and industrial end markets.
| Leading Market Players |
|---|
| STMicroelectronics |
| Power Integrations |
| NXP Semiconductors |
| Microchip Technology |
| Infineon Technologies |
| ON Semiconductor |
| Monolithic Power Systems |
| Sanken Electric |
| Texas Instruments |
| Others |
Pricing and Supply Chain Analysis
Hyperscale data center operators and automotive tier-one suppliers concentrate procurement power, anchoring contract-based long-term offtake agreements that compress margins for analog-centric controller houses while rewarding firmware-programmable suppliers with volume commitments.
Pricing Analysis
Distributor margins of 15-25% on standard analog controllers face compression as direct-to-OEM licensing of digital firmware stacks displaces traditional channel support. Three-tier pricing structure across automotive-grade, industrial-grade, and consumer-grade certification levels captures AEC-Q100 qualification premiums. Pricing pressure stems from China's integrated controller-MOSFET combinations flooding sub-75W adapter segments. Consumer electronics OEMs exhibit highest price sensitivity; automotive onboard charger manufacturers accept premiums for functional safety documentation.
Supply Chain Analysis
Refurbishment flows for obsolete analog controllers create secondary supply channels that undercut authorized distribution in industrial repair markets. Manufacturing concentrates in China, Taiwan, and South Korea, with Yangtze River Delta clusters hosting captive design centers. Silicon carbide wafers from Wolfspeed and Coherent, plus 150mm GaN-on-silicon substrates, constitute critical input dependencies. Single-source vulnerability in automotive-grade SiC substrate qualification creates allocation risk. Distribution runs through Arrow and Avnet for fragmented aftermarket demand, while direct licensing accelerates among Taiwan and South Korea adapter houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PFC Control IC demand compounds steadily as IEC 61000-3-2 harmonics enforcement and DOE efficiency mandates tighten compliance thresholds across server, automotive, and consumer electronics verticals.
For Market Incumbents: Anticipate displacement of analog compensation networks by firmware-programmable architectures in applications above 1kW. Defensive moves center on captive SiC supply agreements and automated calibration equipment for multi-mode CRM/CCM operation. The threat of digital-native entrants from Taiwan's adapter ecosystem demands counter-investment in reference design licensing platforms. For New Entrants and Emerging Players: Begin with India's PLI-subsidized adapter manufacturing corridors, where export-oriented production lacks established digital PFC firmware suppliers. White-space targets include V2G bidirectional charging stages for California and Germany infrastructure mandates, plus mid-power appliance segments locked to analog-only solutions. Go-to-market leverage rests on automated compensation tuning tools that reduce customer capex thresholds. For Investors and Strategic Acquirers: Integrated device manufacturers with captive wide-bandgap semiconductor supply are the most active acquirer in this space, seeking firmware-programmable controller portfolios to complement SiC MOSFET roadmaps. Long-term viability favors targets with AEC-Q100 infrastructure and embedded cryptography expertise for IEC 62443 compliance. Monitor Wolfspeed and Coherent substrate allocation announcements as inflection signals for controller-die pairing economics.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Supply Agreement | Captive substrate access from Wolfspeed secures controller-die pairing for 3kW+ server PSU designs. |
| Digital Firmware Licensing Platform | Reference design stacks reduce Taiwan adapter house time-to-certification and displace proprietary development. |
| AEC-Q100 Qualification Investment | Automotive-grade certification opens onboard charger contracts with Germany's KBA-mandated V2G infrastructure. |
| Automated Calibration Equipment | Multi-mode CRM/CCM tuning tools address firmware security certification gaps that analog-era teams face. |
| India PLI Corridor Design Center | Gujarat and Tamil Nadu EMS facilities attract export-oriented adapter production with cost-optimized controller integration. |
Research Methodology
Coverage spans China, Germany, the United States, India, and Japan, with primary inputs from each region combining interviews with power supply design engineers, automotive tier-one procurement managers, semiconductor vendor application specialists, and industrial EMS facility directors. Secondary validation draws from IEC 61000-3-2 compliance filings, U.S. Department of Energy efficiency rulemakings, EPA external power supply standards, and SEC 10-K disclosures from diversified semiconductor conglomerates. Bottom-up segment sizing triangulates against top-down regulatory mandate impact assessments.
Rate-of-change decomposition separates volume expansion from value-per-unit shifts across the projection horizon. Segmentation dimensions modeled include component tier, application vertical, technology architecture, and end-user procurement channel, with additional granularity on switching frequency requirements and wide-bandgap semiconductor pairing intensity. CAGRs derive from regression against historical efficiency mandate adoption curves and EV production forecasts. Industry-specific inputs encompass hyperscale data center capex disclosures and KBA V2G infrastructure deployment schedules.
Several conditions sit outside the modeled scope, including unforeseen tariff reconfigurations on SiC substrates, abrupt shifts in analog engineering talent availability, and GaN reliability qualification timeline compressions. Forecasts reflect documented assumptions about regulatory enforcement consistency and wide-bandgap semiconductor cost reduction trajectories. Practitioners should monitor FERC efficiency rulemaking, China GB standards harmonization announcements, and automotive gate driver HV-H3TRB testing backlog reports for early signals of forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
China Analog IC Market
IC (Integrated Circuits)
Global Application Specific Automotive Analog IC Market
IC (Integrated Circuits)
Analog IC Market
IC (Integrated Circuits)
Bluetooth IC Market
IC (Integrated Circuits)
Mixed Signal IC Market
IC (Integrated Circuits)
Global Application Specific Industrial Analog IC Market
IC (Integrated Circuits)
APAC Analog IC Market
IC (Integrated Circuits)
Isolated Interface Chip Market
IC (Integrated Circuits)
Global Power Management Integrated Circuit (PMIC) Market
IC (Integrated Circuits)
Asia Pacific Integrated Circuit (IC) Market
IC (Integrated Circuits)
Global Application Specific Computer Analog IC Market
IC (Integrated Circuits)
Mixed-Signal Microcontroller Market
IC (Integrated Circuits)
Battery Fuel Gauge IC Market
IC (Integrated Circuits)
Global Special Purpose Logic IC Market
IC (Integrated Circuits)
Gate Driver IC Market
IC (Integrated Circuits)
Reset Integrated Circuit (IC) Market