
 Flexible Glass for Flexible Electronics Market | 2026-2036
Flexible Glass for Flexible Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible Glass for Flexible Electronics Market Foresight
The EU Green Deal is pivoting substrate selection criteria across European display supply chains toward lower-carbon glass manufacturing. Corning Incorporated leverages its fusion draw process to sustain thickness uniformity below 100 micrometers for roll-to-roll processing. Schott AG anchors German production capacity for chemically strengthened variants used in automotive curved displays. BOE Technology Group dominates Chinese supply through integrated float-to-thinning lines serving domestic panel makers.
Flexible glass for flexible electronics denotes alkali-aluminosilicate or borosilicate substrates processed to sub-200 micrometer thicknesses, typically via fusion draw or slot-drawing followed by ion exchange chemical strengthening, enabling repeated bending radii below 5 millimeters without fracture for conformable display and sensor architectures. Ultra-thin glass leads volume shipments due to mature fusion draw economics, while foldable glass commands premium positioning in smartphone cover applications where million-cycle bend endurance proves mandatory. Ion exchange technology occupies the largest installed strengthening base, though atomic layer deposition garners R&D investment for barrier-layer integration against moisture ingress in organic electronics.
REACH compliance through ECHA governs chromium-free strengthening salt chemistries in European manufacturing, while China's GB standards through SAMR mandate thickness tolerance specifications for imported display substrates. FDA scrutiny of glass encapsulation in wearable medical sensors shapes biocompatibility testing protocols for US-bound products. Stakeholders must monitor evolving dual carbon goals from China's MEE, as embodied carbon thresholds threaten non-integrated importers lacking captive melting capacity or renewable energy sourcing.
Market Dynamics
Fusion draw processing economics now govern competitive positioning as thickness uniformity below 100 micrometers becomes the baseline specification for roll-to-roll manufacturing. Korean and Chinese panel makers are consolidating procurement around suppliers with captive melting and ion exchange strengthening capabilities.
Growth Catalysts
- EU Green Deal material efficiency mandates:Substrate recycling requirements are accelerating closed-loop glass recovery investments across European display supply chains.
- Foldable smartphone cover glass:Million-cycle bend endurance specifications are pulling ultra-thin chemically strengthened variants into high-volume consumer electronics.
- Seoul-Shenzhen electronics clusters:Concentrated panel manufacturing is creating localized demand density that justifies dedicated fusion draw capacity investments.
Market Restraints
- Fusion draw furnace capex intensity:Billion-dollar melting and forming installations create barriers to entry for non-integrated substrate suppliers lacking captive demand.
- South Korean procurement concentration:Samsung Display and LG Display account for dominant flexible glass offtake, creating customer dependency risk for specialty substrate makers.
- Polyimide film substitution:Lower-cost polymer alternatives continue displacing glass in cost-sensitive wearable and curved automotive applications where optical clarity requirements permit.
Strategic Opportunities
- Automotive curved display penetration:Dashboard integration requirements for seamless HMI surfaces are opening new volume channels beyond consumer electronics.
- Atomic layer deposition barrier integration:Convergence of ultra-thin glass with ALD moisture sealing is enabling organic electronics encapsulation for flexible sensors.
- India PLI scheme localization:Display manufacturing incentives are creating greenfield substrate demand from emerging panel assembly investments in Gujarat and Tamil Nadu.
Industry Challenges
- Ion exchange salt chemistry compliance:REACH chromium-free strengthening mandates through ECHA are forcing reformulation of established chemical strengthening processes.
- Thickness tolerance certification timelines:GB standards through SAMR require extended validation cycles for imported display substrates entering Chinese panel supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible Glass for Flexible Electronics Market |
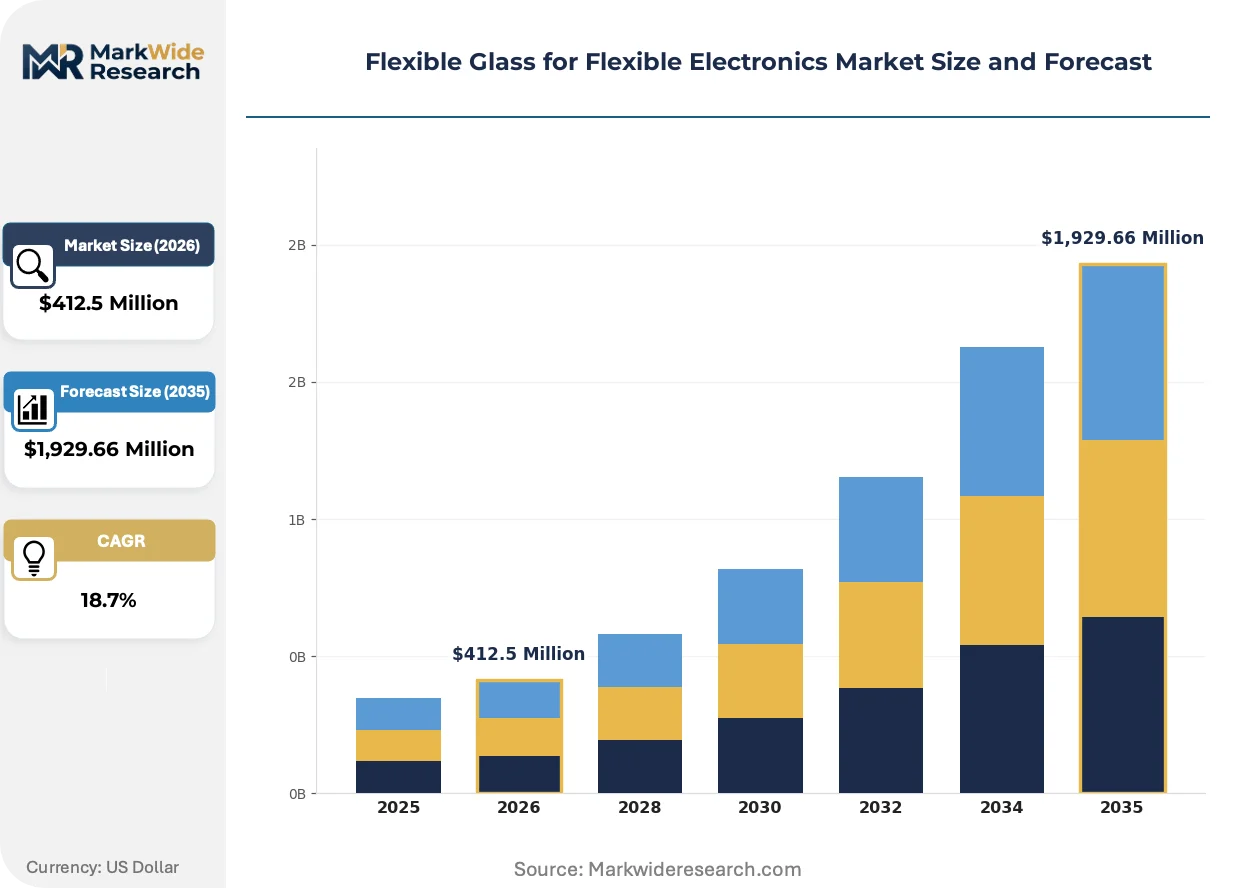
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,929.66 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultra-Thin Glass, Chemically Strengthened Glass, Bent Glass, Foldable Glass, Tempered Glass Technology: Ion Exchange, Laser Strengthening, Chemical Vapor Deposition, Plasma Enhanced CVD, Atomic Layer Deposition Application: Wearable Devices, Smartphones, Tablets, Flexible Displays, Electronic Paper End User: Consumer Electronics Manufacturers, Display Panel Makers, Semiconductor Companies, Research Institutes |
| Companies Covered | Schott AG, Asahi Glass Co. Ltd., Corning Incorporated, BOE Technology Group, Abrisa Technologies, AGC Inc., Saint-Gobain, Materion Corporation, Nippon Electric Glass, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible Glass for Flexible Electronics Market Shifts & Advancements
Roll-to-roll processing architectures are compressing manufacturing step counts and reshaping capital deployment patterns across substrate supply chains. Equipment makers are reconfiguring fusion draw lines for continuous web handling rather than sheet-based processing.
Slot-drawing as an alternative thinning method is decentralizing production geography by enabling smaller-scale capital deployment outside traditional fusion draw strongholds. Mid-size substrate suppliers in Taiwan and Japan are adopting slot-draw systems to serve regional panel makers with faster lead times. This technology is decentralizing supply chain risk away from single-source mega-facilities toward distributed manufacturing networks.
REACH compliance through ECHA is mandating chromium-free strengthening salt formulations across European manufacturing sites. Chemical suppliers are reformulating ion exchange baths to eliminate hexavalent chromium while maintaining compressive layer depth specifications. German and French substrate processors face the steepest transition costs due to legacy bath infrastructure designed around traditional chemistries.
Direct mill-to-panel procurement contracts are compressing distributor margins and reshaping commercial relationships in East Asian supply chains. Large panel makers in Seoul and Shenzhen are negotiating multi-year offtake agreements that bypass traditional substrate trading houses. Korean electronics conglomerates are most aggressive in this channel consolidation, leveraging volume commitments to secure priority allocation from fusion draw operators.
Flexible Glass for Flexible Electronics Market Segmentation
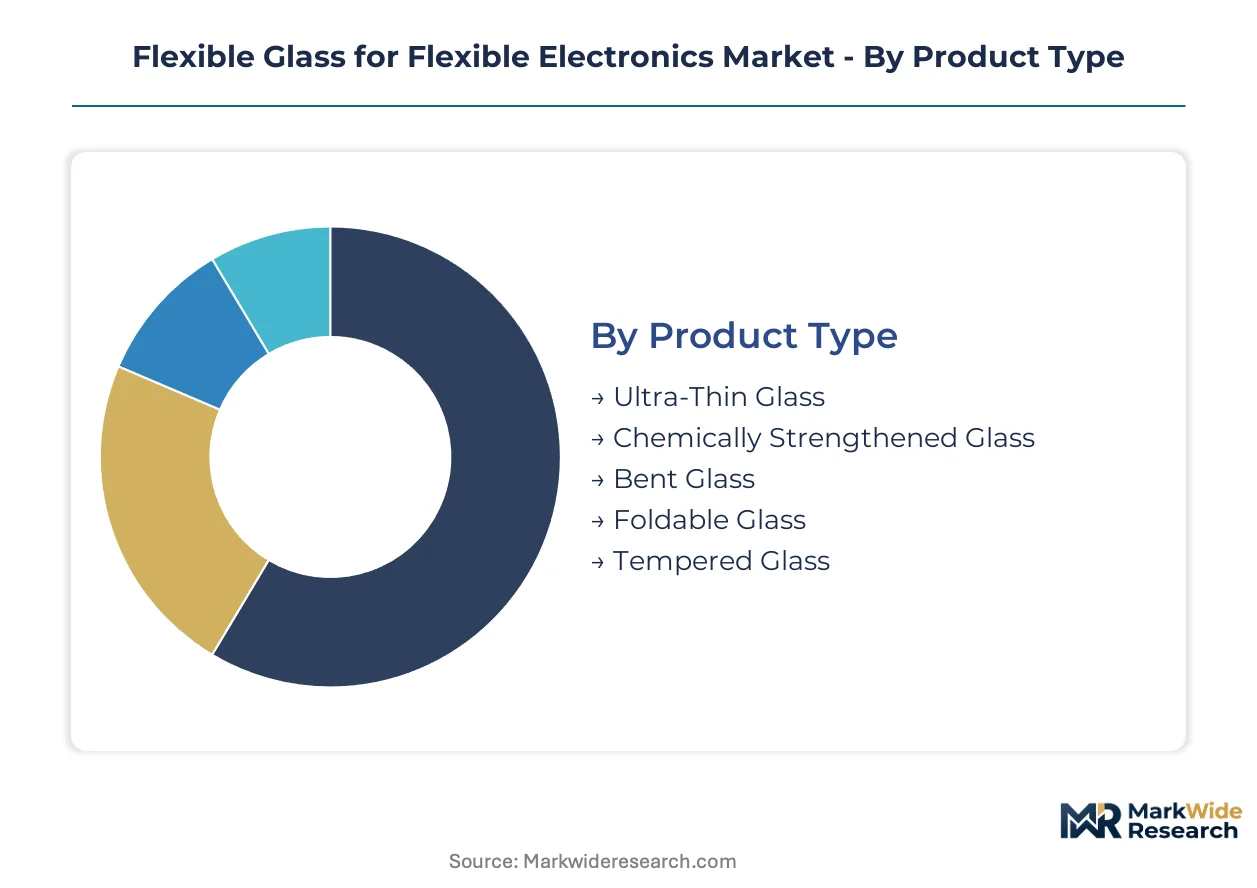
Segmentation in flexible glass tracks how substrate specifications fragment across manufacturing processes, device architectures, and supply chain tiers. Each dimension reveals distinct margin structures and captive capacity investments that reshape competitive boundaries.
Product Type:
Supply concentration in fusion draw capacity has locked in volume leadership for thickness-optimized variants, while premium positioning clusters around bend-performance specifications.
- Ultra-Thin Glass:Alkali-aluminosilicate substrates thinned below 100 micrometers via fusion draw or float-to-thinning lines, prized for roll-to-roll compatibility. Korean panel makers in Seoul and Shenzhen electronics clusters anchor procurement volumes for smartphone backplanes and sensor substrates, though thickness uniformity tolerances strain smaller-scale suppliers lacking captive melting.
- Foldable Glass:Chemically strengthened variants engineered for sub-5-millimeter bend radii and million-cycle endurance, commanding premium positioning in foldable smartphone cover applications. Samsung Display and BOE Technology Group negotiate multi-year offtake agreements that bypass traditional distributors, consolidating procurement leverage.
- Chemically Strengthened Glass:Ion-exchange treated substrates with compressive surface layers for scratch resistance and mechanical durability.
- Bent Glass:Thermoformed substrates for automotive curved displays and fixed-radius conformable electronics.
- Tempered Glass:Thermally strengthened variants for cost-sensitive protective applications where optical grade requirements are relaxed.
Ultra-thin glass absorbs the bulk of installed capacity; foldable glass is expanding most quickly.
Technology:
Strengthening method selection governs capital deployment patterns, with ion exchange dominating installed base and atomic layer deposition capturing R&D investment for barrier integration.
- Ion Exchange:Potassium-for-sodium substitution in molten salt baths creating deep compressive layers, the incumbent technology with largest installed strengthening base. REACH compliance through ECHA is forcing chromium-free bath reformulation across European processors, particularly German and French facilities with legacy infrastructure.
- Atomic Layer Deposition:Sequential self-limiting surface reactions enabling angstrom-precision moisture barrier integration for organic electronics encapsulation. Research institutes and semiconductor companies in East Asia are piloting ALD-glass hybrid architectures for flexible sensor applications.
- Laser Strengthening:Localized thermal treatment for patterned stress profiles without bulk chemical processing.
- Chemical Vapor Deposition:Gas-phase precursor reactions for dielectric coating integration on glass substrates.
- Plasma Enhanced CVD:Lower-temperature deposition variant for temperature-sensitive ultra-thin glass handling.
Ion exchange retains the deepest installed base; atomic layer deposition is climbing the fastest.
Application:
Device form factor requirements fragment demand across thickness, bend radius, and optical clarity specifications, with display-centric applications pulling highest volumes.
- Smartphones:Foldable and slab-form cover glass, touch sensor substrates, and backplane encapsulation driving highest absolute consumption. Korean and Chinese OEMs consolidate procurement around Seoul-Shenzhen supply chain corridors with dedicated fusion draw capacity.
- Wearable Devices:Ultra-thin chemically strengthened glass for smartwatch faces and fitness tracker displays, with FDA scrutiny of glass encapsulation in medical-grade wearables shaping biocompatibility testing protocols for US-bound products.
- Tablets:Larger-format substrates for foldable and conventional tablet displays.
- Flexible Displays:Substrate and encapsulation layers for OLED and emerging microLED architectures.
- Electronic Paper:Low-cost, low-bend-requirement substrates for e-reader and signage applications.
Smartphones absorb the bulk of installed capacity; wearable devices are gaining share fastest.
End User:
Customer type determines contract structure, with integrated panel makers squeezing distributor margins through direct mill-to-panel procurement.
- Display Panel Makers:Samsung Display, LG Display, and BOE Technology Group negotiate multi-year offtake agreements that compress traditional substrate trading margins. These buyers specify thickness tolerances and ion exchange depth requirements that favor suppliers with captive melting and strengthening.
- Consumer Electronics Manufacturers:Smartphone, tablet, and wearable OEMs sourcing finished cover glass and sensor substrates, with Indian PLI scheme localization creating greenfield demand from Gujarat and Tamil Nadu assembly investments.
- Semiconductor Companies:Advanced packaging and flexible sensor developers requiring ALD-integrated barrier substrates.
- Research Institutes:Pilot-scale procurement for next-generation device architecture development.
Display panel makers absorb the bulk of installed capacity; consumer electronics manufacturers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in East Asian fusion draw facilities while consumption pulls from electronics assembly clusters in South Korea, China, and India. European and North American demand relies on substrate imports, with regulatory compliance adding cost layers to cross-border supply chains.
South Korea
Samsung Display and LG Display anchor foldable glass procurement for smartphone cover applications. MFDS scrutiny of wearable medical sensors shapes biocompatibility testing protocols for US-bound products. Seoul-Suwon electronics corridor hosts concentrated panel manufacturing that justifies dedicated ultra-thin glass capacity investments from captive suppliers.
China
BOE Technology Group and domestic panel makers drive ultra-thin glass consumption for smartphone backplanes and flexible displays. GB standards through SAMR mandate thickness tolerance specifications for imported substrates, extending validation cycles. Shenzhen electronics cluster integrates float-to-thinning lines serving regional display supply chains under MEE dual carbon goals.
Japan
Specialty glass fabricators serve semiconductor packaging and sensor substrate niches requiring atomic layer deposition barrier integration. METI technology roadmaps prioritize next-generation display materials R&D. Nagoya-Osaka industrial belt hosts precision processing facilities for chemically strengthened variants used in automotive curved displays.
Germany
Schott AG anchors European production capacity for chemically strengthened glass serving automotive and industrial applications. REACH compliance through ECHA mandates chromium-free ion exchange salt formulations, forcing bath chemistry reformulation. Mainz-Rhineland cluster concentrates substrate processing under EU Green Deal material efficiency mandates accelerating closed-loop recovery investments.
United States
Corning Incorporated sustains thickness uniformity below 100 micrometers through fusion draw processing for roll-to-roll compatibility. FDA oversight of glass encapsulation in wearable medical devices shapes testing protocols for biocompatibility certification. Upstate New York manufacturing corridor supplies North American display and sensor developers with ion-exchange strengthened substrates.
Flexible Glass for Flexible Electronics Market Competitive Landscape
The competitive structure tilts toward integrated material-science conglomerates with captive melting and chemical strengthening capabilities. Korean and Chinese panel makers are consolidating procurement around suppliers offering fusion draw economics at sub-100-micrometer specifications. Three archetypes dominate: integrated glass-ceramic majors with full-process control, display-integrated Chinese conglomerates with captive demand, and specialty thin-glass processors serving niche barrier-layer applications. Capacity expansion and direct mill-to-panel procurement contracts represent the dominant competitive vectors reshaping commercial relationships.
Among German and US-based material-science majors, Schott AG and Corning Incorporated exemplify the integrated archetype with fusion draw and ion exchange capabilities spanning industrial, automotive, and consumer electronics segments. BOE Technology Group occupies a position within the display-integrated tier, leveraging captive demand from Chinese panel manufacturing to justify dedicated substrate capacity. These three anchors illustrate how geographic production concentration and end-market integration determine competitive positioning across thickness-optimized and bend-performance substrate tiers.
| Leading Market Players |
|---|
| Schott AG |
| Asahi Glass Co. Ltd. |
| Corning Incorporated |
| BOE Technology Group |
| Abrisa Technologies |
| AGC Inc. |
| Saint-Gobain |
| Materion Corporation |
| Nippon Electric Glass |
| Others |
Supply & Pricing Matrix
The EU Green Deal's material efficiency mandates gate qualified supply access and premium-tier pricing for European panel makers sourcing low-carbon flexible glass substrates. Korean and Chinese electronics conglomerates leverage direct mill-to-panel procurement to compress distributor margins while securing priority allocation from fusion draw operators with captive melting capacity.
Pricing Analysis
Million-cycle bend endurance specifications anchor value-based pricing for foldable smartphone cover glass, with Samsung Display and BOE Technology Group negotiating multi-year offtake agreements that bypass traditional substrate trading houses. Pricing stratifies across premium, standard, and economy tiers based on thickness uniformity tolerances and ion exchange depth specifications, with non-integrated suppliers facing cost compression from billion-dollar fusion draw furnace capex intensity. Display panel makers exhibit lowest price sensitivity due to captive demand concentration, while cost-sensitive wearable OEMs drive substitution toward polyimide film alternatives.
Supply Chain Analysis
Fusion draw melting capacity rests on Japanese, German, and American specialty glass producers with legacy furnace infrastructure and chemical strengthening capabilities. Raw material dependencies span high-purity silica sand, potassium nitrate strengthening salts, and chromium-free bath formulations for REACH compliance. Single-source vulnerability concentrates in South Korean procurement patterns where Samsung Display and LG Display account for dominant flexible glass offtake. Distribution feeds from captive supplier facilities through direct mill-to-panel contracts rather than distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fusion draw furnace capex intensity creates a structural capacity bottleneck that props pricing power for integrated material-science conglomerates with captive melting and ion exchange capabilities.
For Market Incumbents: Hedge against polyimide film substitution in cost-sensitive wearable applications by deepening backward integration into float-to-thinning lines serving automotive curved display demand. Prioritize chromium-free ion exchange bath reformulation to maintain European market access under ECHA mandates while defending margin position through direct procurement contracts with Seoul-Shenzhen panel makers. For New Entrants and Emerging Players: Enter via slot-drawing technology deployments serving regional panel makers in Taiwan and Japan with faster lead times than fusion draw strongholds. Target India's PLI scheme localization incentives in Gujarat and Tamil Nadu where greenfield display assembly investments create substrate demand without incumbent supplier relationships. Pursue atomic layer deposition barrier integration partnerships with semiconductor companies developing flexible sensor architectures. For Investors and Strategic Acquirers: Multi-year offtake agreement announcements from Korean electronics conglomerates are the leading indicator that captive capacity investments are achieving utilization thresholds sufficient for margin expansion. Five-to-ten year viability favors integrated glass-ceramic majors with full-process control over specialty thin-glass processors lacking melting capacity. Watch for GB standards validation cycle completions as signals of Chinese market entry readiness for imported substrate suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Float-to-Thinning | BOE Technology Group's captive lines reduce dependency on imported fusion draw supply. |
| Chromium-Free Ion Exchange Reformulation | Schott AG's bath chemistry transition maintains REACH compliance for German automotive customers. |
| Direct Mill-to-Panel Procurement | Samsung Display's multi-year agreements bypass distributors and secure priority allocation. |
| Slot-Drawing Capacity Deployment | Taiwanese suppliers decentralize supply chain risk away from single-source mega-facilities. |
| Atomic Layer Deposition Barrier Integration | East Asian research institutes pilot hybrid architectures for organic electronics encapsulation. |
Research Methodology
Document review covered SEC 10-K filings from specialty glass manufacturers, ECHA REACH compliance databases, and Korean MFDS medical device guidance documents, complemented by interviews with fusion draw plant managers, display panel procurement leads at Samsung Display and LG Display, and technical R&D directors at ion exchange chemical suppliers. Secondary validation drew from customs trade data tracking ultra-thin glass substrate movements, SAMR GB standards publications, and EU Green Deal implementation progress reports. Bottom-up capacity utilization models triangulated against top-down electronics cluster demand aggregation.
Segment-level value outputs across the projection horizon reflect discrete modeling of product type, technology, application, and end user dimensions with regional production hub differentiation. CAGRs derive from installed capacity expansion timelines, procurement contract visibility windows, and substitution elasticity parameters for polyimide film alternatives. Industry-specific inputs include fusion draw furnace commissioning schedules, ion exchange salt chemistry reformulation costs, and automotive curved display penetration curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under tariff escalation scenarios affecting Korean-Chinese substrate trade flows and MEE dual carbon goal acceleration threatening non-renewable energy-dependent importers. Forecasts reflect assumptions around REACH compliance timelines, GB standards validation cycle durations, and foldable smartphone volume ramps without warranty of regulatory or technological stability. A small set of named triggers—fusion draw furnace commissioning announcements, multi-year offtake contract disclosures, and chromium-free bath certification completions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
High Power Double-Clad Fiber Bragg Grating Market
Optical Components
Erbium Oxide Market
Optical Components
Quartz Glass Substrate Market
Optical Components
3-7mm Galvo Scanner Market
Optical Components
Global Tunable Filter Market
Optical Components
Photosensitive Glass Market
Optical Components
Italy Lithium Niobate Modulator Market
Optical Components
North America Tunable Laser Market
Optical Components
Global Electrochromic Glass and Devices Market
Optical Components
Europe Tunable Laser Market
Optical Components
Fluorophore Market
Optical Components
Low-E Glass Magnetron Sputtering Coating Line Market
Optical Components
Optical Film Market
Optical Components
Fiber Optic Collimating Lens Market
Optical Components
VCSEL for Data Communication Market
Optical Components
Optical Sensor Market