
 Silicon Photonics Wafer Market | 2026-2036
Silicon Photonics Wafer Market Size, Share, and Industry Trends Forecast 2026-2036
Silicon Photonics Wafer Market Analytics
Co-packaged optics is reshaping how hyperscalers architect compute-to-network interfaces, collapsing electrical trace lengths and power budgets. Intel Corporation leverages its integrated photonics foundry to anchor supply for internal datacenter silicon and select external customers. GlobalFoundries Inc. competes through its differentiated Fotonix platform, targeting mid-volume telecom and sensing applications. TSMC sustains process leadership by extending advanced CMOS nodes into silicon photonics integration.
A silicon photonics wafer consists of a crystalline silicon substrate with patterned waveguide structures, modulators, and photodetectors fabricated through deep-ultraviolet lithography and plasma etching, enabling optical signal generation, routing, and detection on a single chip. Its primary purpose is replacing copper interconnects with photonic pathways to overcome bandwidth-distance limitations in high-performance computing and communications systems. Transceivers dominate current volume as cloud providers deploy 400G and 800G optical links, while waveguides capture expanding margin pools in co-packaged and chip-to-chip architectures. Integration Techniques represent the fastest-growing technology dimension as heterogeneous bonding and 3D stacking mature.
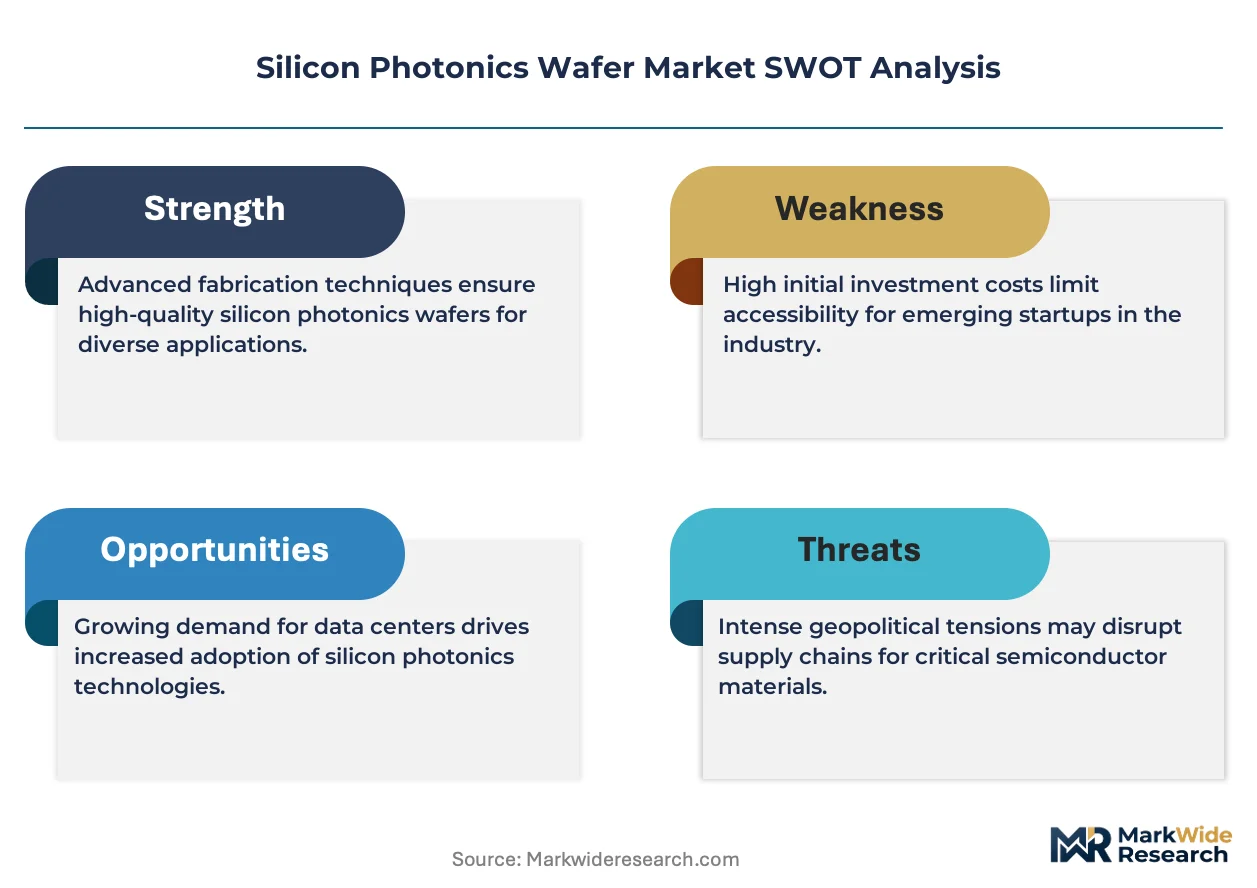
The U.S. CHIPS and Science Act directs federal funding toward domestic silicon photonics fabrication, tightening supply chain security requirements for defense and critical infrastructure applications. The EU Chips Act establishes capacity targets and IP localization rules that condition market access for non-European wafer suppliers. China's MIIT sets domestic GB standards for optical communication components, creating parallel certification pathways. Stakeholders must monitor which regulatory jurisdiction's technical specifications achieve de facto harmonization across major procurement contracts.
Market Dynamics
Co-packaged optics is collapsing electrical trace lengths in hyperscale datacenters, forcing foundries to retool for heterogeneous integration while defense procurement tightens supply chain security requirements.
Growth Catalysts
- AI Datacenter Buildouts:Hyperscalers are deploying 800G optical links to interconnect GPU clusters, pulling wafer demand from traditional telecom applications.
- EU Chips Act:Capacity targets and IP localization rules are conditioning market access for non-European suppliers, accelerating domestic fabrication investments.
- Deep-Ultraviolet Lithography:Advanced patterning techniques enable sub-micron waveguide precision, unlocking chip-to-chip optical architectures previously unattainable.
Market Restraints
- 300mm SOI Wafer Concentration:Taiwan and South Korea control critical raw substrate supply, creating single-source vulnerability for Western foundries.
- Plasma Etching Equipment Costs:Deep reactive-ion etching systems require capital outlays that exclude mid-volume entrants from cost-competitive production.
- Thermal Management Limitations:Silicon's 1.1 eV bandgap restricts high-power laser integration, forcing hybrid III-V bonding that complicates yield.
Strategic Opportunities
- Automotive Lidar Architectures:Solid-state beam steering using silicon photonic phased arrays offers a path to sub-hundred-dollar automotive perception modules.
- US CHIPS Act Funding:Federal subsidies for domestic silicon photonics fabrication create first-mover advantages for qualified facility investments.
- Biomedical Sensing Convergence:Integration of photonic biosensors with microfluidics opens disposable diagnostic cartridge markets outside traditional communications.
Industry Challenges
- Packaging Engineer Scarcity:Heterogeneous bonding and 3D stacking require skills spanning optical, electrical, and thermal domains that outpace university pipeline output.
- Foundry Qualification Timelines:Defense and automotive contracts demand 18-24 month process certification cycles that delay revenue recognition.
- Interoperability Standards Fragmentation:Competing consortiums for co-packaged optical interfaces create specification uncertainty that freezes procurement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicon Photonics Wafer Market |
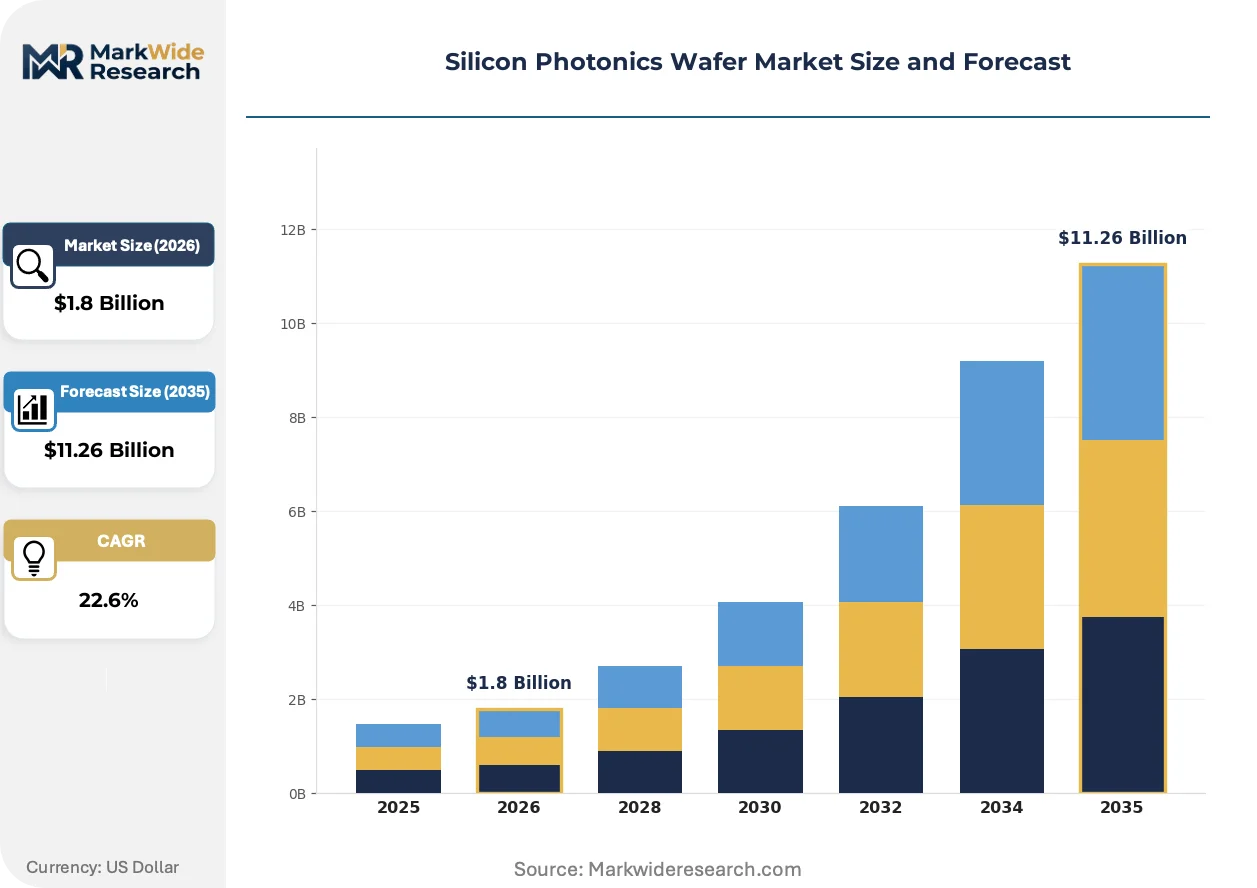
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $11.26 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Interconnects, Sensors, Transceivers, Waveguides Technology: Passive Components, Active Devices, Integration Techniques, Fabrication Methods End User: Telecommunications, Data Centers, Consumer Electronics, Automotive Application: High-Speed Data Transmission, Optical Imaging, Quantum Computing, Integrated Circuits |
| Companies Covered | Intel Corporation, Cisco Systems, Inc., GlobalFoundries Inc., TSMC, Lumentum Operations LLC, MACOM, IBM Corporation, STMicroelectronics, Tower Semiconductor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicon Photonics Wafer Market Evolving Landscape
Photonic integration is advancing through three concurrent vectors: process convergence with mainstream CMOS, regulatory conditioning of supply chain geography, and procurement centralization among hyperscale buyers.
Monolithic silicon photonics is collapsing the cost barrier between electrical and optical interconnects. The technology combines modulators, waveguides, and photodetectors on a single crystalline substrate. Hyperscale datacenter operators are adopting it for 800G transceivers at production scale. This compression is eliminating the historical premium for optical solutions in short-reach applications.
REACH and RoHS substance restrictions in Europe are tightening material compliance requirements for optical component exports. The regulations limit heavy metals and persistent organic pollutants in wafer processing chemistries. Defense and aerospace procurement contracts now mandate EU regulatory equivalence as a condition of supplier qualification. Foundries are responding by segregating production lines for compliant versus non-compliant process flows.
Hyperscaler direct sourcing is displacing traditional optical module vendor relationships. Amazon Web Services, Microsoft Azure, and Google Cloud are contracting directly with foundries for custom silicon photonic dies. This disintermediation concentrates design authority with cloud architects rather than telecom equipment manufacturers. The shift is most visible in the United States, where three buyers now account for the majority of advanced node silicon photonics tape-outs.
Silicon Photonics Wafer Market Segmentation
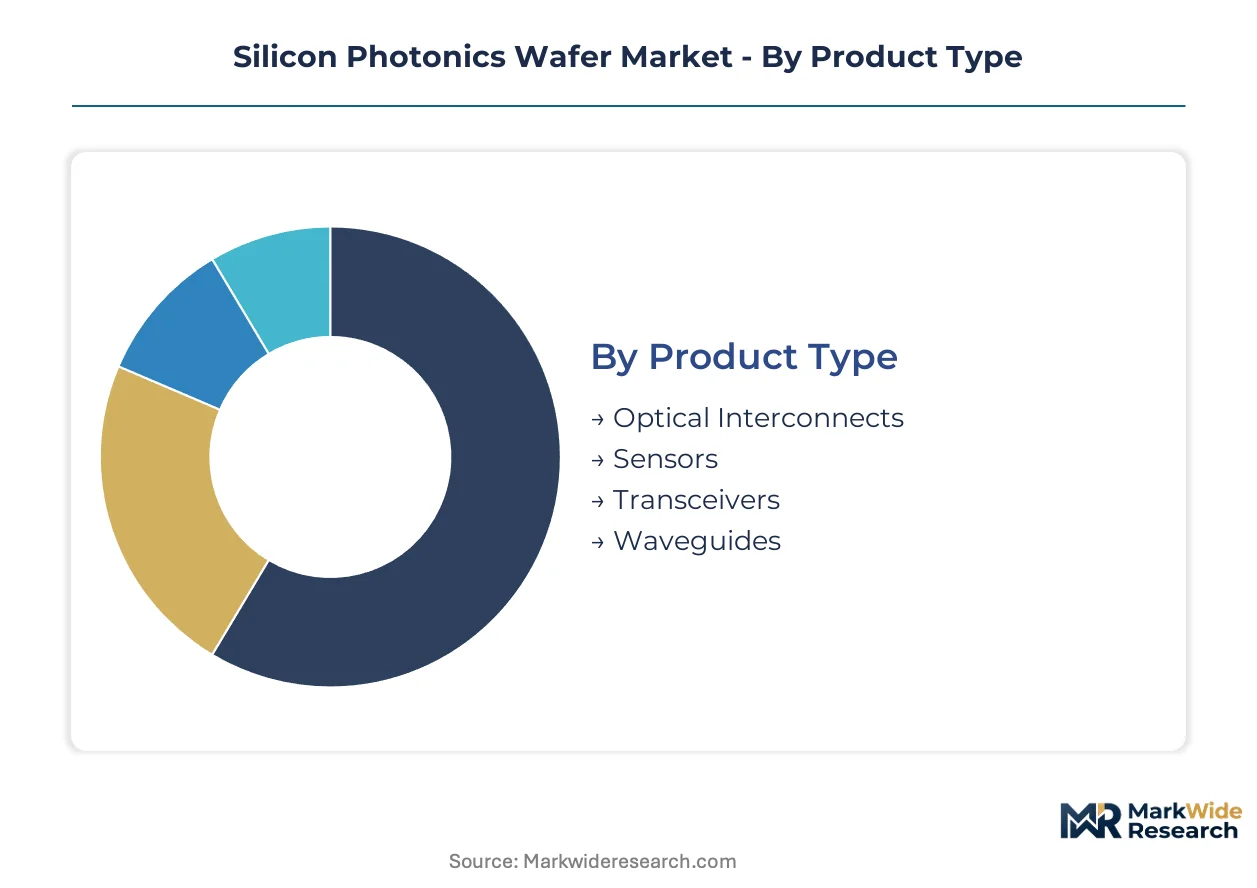
Silicon photonics wafer demand fragments across divergent technical specifications, from telecom-grade reliability standards to hyperscale cost-optimized volumes. Each segment carries distinct foundry qualification requirements and margin structures that reshape supplier competitive positioning.
Product Type:
Cost tier differentiation separates high-volume commodity wafers from premium custom silicon engineered for defense and research applications.
- Transceivers:These wafers integrate modulators, photodetectors, and passive splitters through deep-ultraviolet lithography for pluggable optical modules. Cloud providers in the United States now account for the majority of 400G and 800G tape-outs as AI cluster interconnects scale. Transceivers hold installed capacity. Waveguides is rotating up the share rankings.
- Waveguides:Patterned crystalline silicon substrates route optical signals between compute dies with sub-micron precision. Co-packaged optics architectures in Taiwan and South Korea foundries are pulling wafer demand away from traditional pluggable modules. Waveguides gain share fastest as heterogeneous integration matures.
- Optical Interconnects:Chip-to-chip and board-level photonic pathways replace copper traces in high-performance computing backplanes.
- Sensors:Structured silicon substrates enable lidar beam steering and biomedical detection through interferometric architectures.
Transceivers hold installed capacity. Waveguides is rotating up the share rankings.
Technology:
Maturity curves separate proven CMOS-compatible processes from emerging bonding techniques still qualifying for automotive and defense contracts.
- Integration Techniques:Heterogeneous bonding and 3D stacking merge silicon photonics with electronic logic through micro-bump and hybrid wafer-to-wafer attachment. Foundries in the United States are prioritizing these capabilities for CHIPS Act-funded defense programs requiring secure domestic supply chains. Integration Techniques gain share fastest as packaging complexity escalates.
- Active Devices:These wafers embed electro-optic modulators and germanium photodetectors through selective epitaxy and implantation processes. Telecom equipment manufacturers in Germany and France specify active device wafers for coherent optical transmission systems requiring 64QAM modulation fidelity. Active Devices hold installed capacity. Integration Techniques is rotating up the share rankings.
- Passive Components:Splitters, couplers, and arrayed waveguide gratings pattern through standard CMOS flows without active doping.
- Fabrication Methods:Deep reactive-ion etching and chemical-mechanical planarization define waveguide sidewalls and optical surface quality.
Active Devices hold installed capacity. Integration Techniques is rotating up the share rankings.
End User:
Customer type concentration creates divergent procurement patterns between hyperscale volume buyers and fragmented specialized equipment vendors.
- Data Centers:Hyperscale operators specify custom silicon photonic dies for 800G optical links interconnecting GPU clusters. Microsoft Azure, Amazon Web Services, and Google Cloud in the United States now contract directly with foundries, bypassing traditional optical module vendors. Data Centers hold installed capacity. Automotive is rotating up the share rankings.
- Telecommunications:Carrier-grade transceiver wafers demand 25-year reliability certification and extended temperature operation. European telecom infrastructure spending through programs backed by the EU Chips Act is sustaining demand for coherent transmission silicon in Germany, France, and the Netherlands. Telecommunications holds legacy share. Data Centers is displacing volume leadership.
- Automotive:Solid-state lidar wafers require AEC-Q100 qualification and sub-hundred-dollar cost targets for mass-market deployment.
- Consumer Electronics:Miniaturized optical sensors for biometric authentication and augmented reality drive small-format wafer demand.
Telecommunications holds legacy share. Data Centers is displacing volume leadership.
Application:
Performance requirements stratify across bandwidth-distance specifications, from meter-scale chip-to-chip links to kilometer-scale fiber transmission.
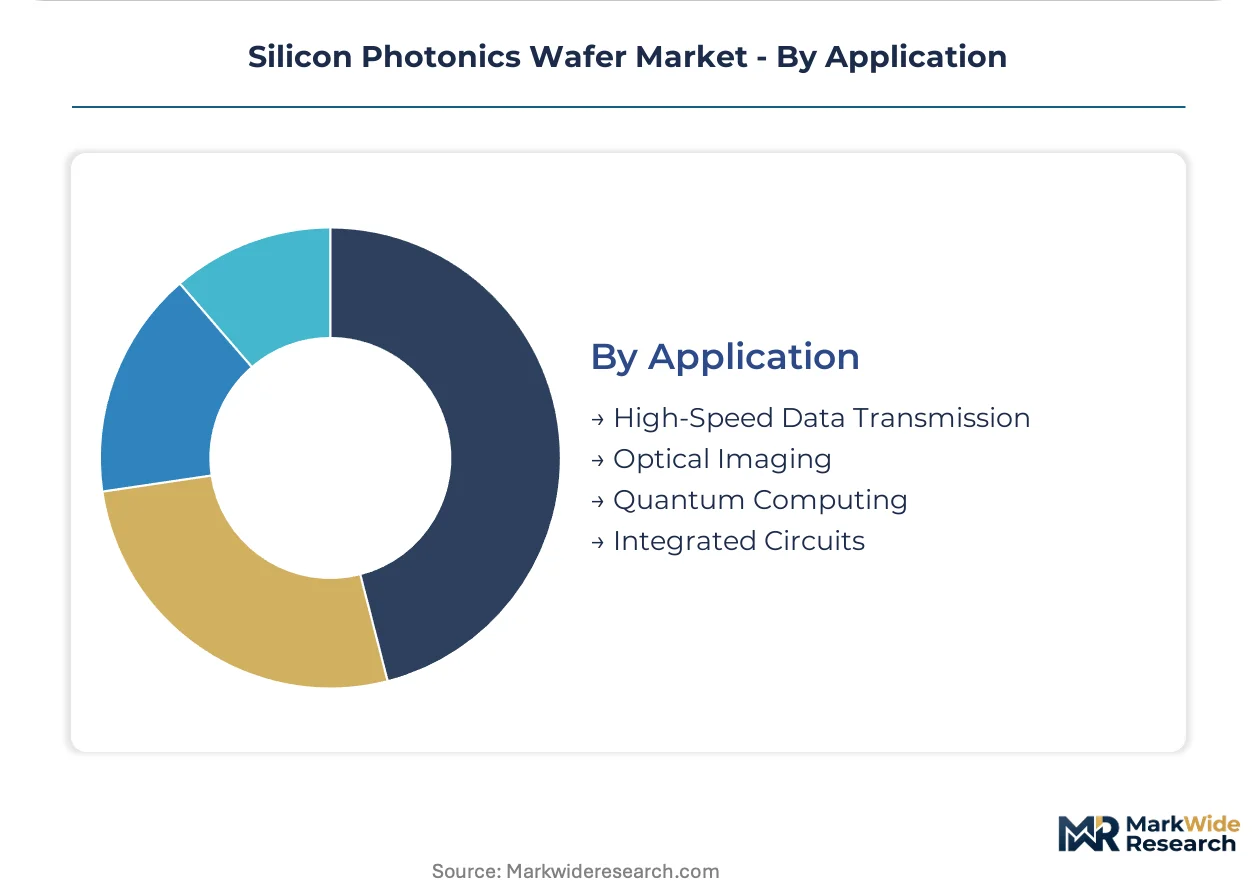
- High-Speed Data Transmission:These wafers enable 800G and 1.6T optical links through PAM4 modulation and parallel lane aggregation. AI training clusters in the United States and Taiwan are consuming wafer capacity previously allocated to telecom metro networks. High-Speed Data Transmission holds installed capacity. Quantum Computing is rotating up the share rankings.
- Integrated Circuits:Co-packaged optical I/O dies bond directly to processor packages through 2.5D and 3D integration. Intel Corporation's internal foundry and TSMC in Taiwan are qualifying integrated circuit photonics for next-generation server processors. Integrated Circuits holds process maturity. High-Speed Data Transmission dominates near-term volume.
- Optical Imaging:Structured illumination and computational imaging wafers serve biomedical and industrial inspection systems.
- Quantum Computing:Low-loss silicon nitride and cryogenic-compatible photonic circuits enable photonic qubit manipulation.
Integrated Circuits holds process maturity. High-Speed Data Transmission dominates near-term volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale cloud operators in the United States now account for the majority of advanced silicon photonics tape-outs, pulling capacity from traditional telecom hubs. Taiwan and South Korea anchor foundry supply. Germany and Japan sustain specialized coherent transmission demand.
United States
Microsoft Azure, Amazon Web Services, and Google Cloud contract directly with foundries for custom 800G optical dies, bypassing legacy module vendors. The CHIPS and Science Act directs federal subsidies toward domestic fabrication facilities with secure supply chain requirements. Intel Corporation's integrated photonics foundry in Oregon and Arizona anchors internal datacenter silicon production.
Taiwan
TSMC extends advanced CMOS nodes into silicon photonics integration for co-packaged optics architectures. The National Development Council coordinates semiconductor infrastructure investments under the Taiwan Chip Implementation Act. Hsinchu Science Park clusters epitaxy, lithography, and heterogeneous bonding capabilities within a thirty-kilometer radius.
South Korea
Samsung Electronics and SK Hynix deploy silicon photonic interconnects within AI training clusters exceeding ten thousand GPUs. The K-Chips Act provides tax credits for domestic 300mm SOI wafer capacity expansion. Pangyo Techno Valley hosts packaging engineering centers specializing in 3D optical-electrical stacking.
Germany
Deutsche Telekom and Vodafone specify coherent transmission wafers requiring 64QAM modulation fidelity for metro networks. The EU Chips Act conditions market access on IP localization and capacity targets for European suppliers. Dresden's Silicon Saxony cluster integrates GlobalFoundries' Fotonix platform with Fraunhofer photonics research institutes.
Japan
NTT and KDDI sustain demand for telecom-grade transceivers with twenty-five-year reliability certification. METI's semiconductor revitalization strategy funds domestic silicon photonics process development. Tsukuba and Yokohama concentrate active device epitaxy and precision etching equipment manufacturing.
Silicon Photonics Wafer Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. Vertically integrated semiconductor conglomerates with captive foundry capacity occupy the premium tier, while pure-play photonics specialists and diversified analog chip vendors populate the mid-market. Competitive moves concentrate on heterogeneous integration partnerships and strategic qualification for defense procurement contracts.
Within the integrated-device-manufacturer tier, Intel Corporation and IBM Corporation exemplify archetypes that combine internal wafer fabrication with end-system deployment. GlobalFoundries Inc. occupies a distinct position as a pure-play foundry with differentiated silicon photonics process offerings. Among specialized component suppliers, Lumentum Operations LLC and MACOM represent optical-engineering-focused entities that concentrate on active device design rather than substrate manufacturing.
| Leading Market Players |
|---|
| Intel Corporation |
| Cisco Systems, Inc. |
| GlobalFoundries Inc. |
| TSMC |
| Lumentum Operations LLC |
| MACOM |
| IBM Corporation |
| STMicroelectronics |
| Tower Semiconductor |
| Others |
Value Network & Pricing Analysis
Taiwan and South Korea's lock on 300mm SOI wafer supply concentrates upstream margin capture, while downstream pricing power migrates to hyperscale datacenter operators contracting directly for custom silicon photonic dies. This structural asymmetry forces foundries to absorb etching equipment depreciation while cloud architects dictate performance-to-cost ratios.
Pricing Analysis
Cost-plus contracts with silicon substrate indexation dominate procurement between foundries and defense contractors, insulating qualified suppliers from spot volatility. Pricing stratifies across defense-certified, automotive-grade, and commercial-tier specifications, with AEC-Q100 qualification commanding substantial premiums. Cost compression in high-volume transceiver wafers is intensifying because Microsoft Azure, Amazon Web Services, and Google Cloud leverage consolidated procurement volumes. Automotive lidar manufacturers exhibit highest price sensitivity due to sub-hundred-dollar module targets, while defense programs show lowest sensitivity given 18-24 month qualification timelines.
Supply Chain Analysis
300mm silicon-on-insulator feedstock draws from Taiwan, South Korea, and Japan, with epitaxial germanium and III-V laser materials sourced from Germany and the United States. Deep reactive-ion etching systems, plasma-enhanced chemical vapor deposition chambers, and heterogeneous bonding equipment constitute critical capital dependencies. Single-source vulnerability concentrates in SOI substrate supply, where Shin-Etsu and Soitec anchor global capacity. Distribution runs through direct foundry relationships with hyperscalers, bypassing traditional optical module vendor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among three United States hyperscalers, whose direct foundry contracting now displaces legacy vendor relationships and reshapes margin allocation across the value chain.
For Market Incumbents: Build process qualification moats through accelerated AEC-Q100 and defense-grade certification pipelines. Intel Corporation and GlobalFoundries Inc. should expand heterogeneous bonding capacity in Arizona and New York to capture CHIPS Act subsidies before qualification timelines lock in competitor advantage. Threats from emerging Chinese foundries with cost-structured government backing require preemptive capacity commitments. Vertical integration into epitaxial material growth secures supply continuity against SOI substrate concentration risk. For New Entrants and Emerging Players: Establish a beachhead in biomedical sensing applications where disposable diagnostic cartridge volumes remain unconstrained by telecom-grade reliability standards. Solid-state lidar for automotive perception offers the most penetrable volume trajectory, with sub-hundred-dollar cost targets creating entry wedges against established coherent transmission suppliers. Go-to-market positioning through microfluidics integration partnerships bypasses capital-intensive foundry buildout requirements. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across heterogeneous integration sub-segments as 3D stacking equipment requirements escalate. Long-term viability over the next decade rests on securing positions in co-packaged optics process flows before hyperscaler procurement centralizes. Acquisition targets should display active device design expertise married to packaging engineering capabilities. Watch for inflection signals in defense contract award velocity, which typically precedes commercial volume scaling by 24-36 months.| Strategic Initiative | Industry Significance |
|---|---|
| Heterogeneous Integration Partnership | TSMC's advanced node extension enables Intel's co-packaged optics roadmaps for AI clusters. |
| Defense Qualification Acceleration | CHIPS Act funding shortens 18-24 month certification cycles for domestic foundry revenue recognition. |
| SOI Substrate Supply Agreement | Long-term offtake contracts with Shin-Etsu mitigate single-source vulnerability for Western foundries. |
| Automotive Lidar Process Development | AEC-Q100 qualification opens sub-hundred-dollar solid-state perception module markets. |
| Biomedical Sensing Platform Launch | Microfluidics-photonics integration targets disposable diagnostic cartridge volumes outside telecom. |
Research Methodology
Two parallel data streams informed the analysis: primary fieldwork with foundry process engineers, hyperscaler silicon procurement directors, defense program managers, and packaging engineering specialists; and secondary validation through SEC 10-K filings, CHIPS Act funding disbursement records, EU Chips Act capacity target notifications, and customs trade data for 300mm SOI wafer flows. Bottom-up wafer demand modeling triangulated against top-down foundry capacity announcements.
Forecast inputs considered deployment scale of 800G and 1.6T optical links, co-packaged optics adoption curves across server processor generations, and automotive lidar penetration rates. Segmentation dimensions spanned product type, integration technology, end-user vertical, and application bandwidth-distance specifications. CAGRs derived from regression analysis of historical foundry utilization against announced capacity expansions, with AI training cluster buildout schedules as primary demand drivers.
Stress conditions across SOI substrate supply disruption, plasma etching equipment lead time extension, and hyperscaler capex cycle downturns were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts embed assumptions regarding EU Chips Act implementation pace and MIIT GB standard harmonization trajectories. Cross-checking against foundry equipment utilization rates reported by SEMI is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Liquid Light Guides Market
Optical Components
Erbium Oxide Market
Optical Components
Silicon Photonics Market
Optical Components
LGP (Light Guide Plate) for TV Market
Optical Components
Digital Optical Transmitter Market
Optical Components
Low-E Glass Magnetron Sputtering Coating Line Market
Optical Components
Mobile Optical Pluggable Market
Optical Components
Flip-Chip VCSEL Market
Optical Components
Asia-Pacific Tunable Laser Market
Optical Components
Europe Eye Tracking Solutions Market
Optical Components
Spatial Light Modulator Market
Optical Components
Global Adaptive Optics Market
Optical Components
Distributed Fiber Optic Sensor (DFOS) Market
Optical Components
Faraday Rotator Market
Optical Components
Erbium-Doped Fiber Amplifier Market
Optical Components
Global Hybrid Photonic Integrated Circuit Market