
 Planar Lightwave Circuit Splitter Market | 2026-2036
Planar Lightwave Circuit Splitter Market Size, Share, and Industry Trends Forecast 2026-2036
Planar Lightwave Circuit Splitter Market Analysis
Project finance tied to national broadband initiatives is reshaping competitive dynamics in the Planar Lightwave Circuit Splitter Market. Corning leverages its captive optical fiber supply chain to control input costs for splitter substrates. Broadex Technologies anchors its position through concentrated R&D spending on silicon photonics integration. NTT Electronics dominates Japanese carrier supply chains with qualification protocols that foreign competitors struggle to replicate.
A Planar Lightwave Circuit Splitter is a passive optical device fabricated on a flat substrate that divides a single input optical signal into multiple output channels with precise power ratios, typically achieving insertion loss below 4 dB for 1x8 configurations. Manufacturers employ photolithography and flame hydrolysis deposition on silica substrates to create waveguide arrays that serve fiber optic distribution networks. Silicon photonics technology is capturing margin pools as data center operators demand higher-density splitters with thermal stability. Fiber to the Home end users sustain volume leadership across Asia-Pacific carrier rollouts, while polymer-based splitters compete on cost for indoor wall-mount installations where environmental stress remains minimal.
FCC broadband subsidy programs in the United States and China's MIIT fiber infrastructure mandates collectively shape product certification requirements and procurement timelines for splitter vendors. REACH compliance in Europe restricts certain dopants used in silica waveguide fabrication, pushing manufacturers toward alternative deposition chemistries. Stakeholders must monitor how national security screening of optical component supply chains affects vendor qualification pathways across major deployment markets.
Market Dynamics
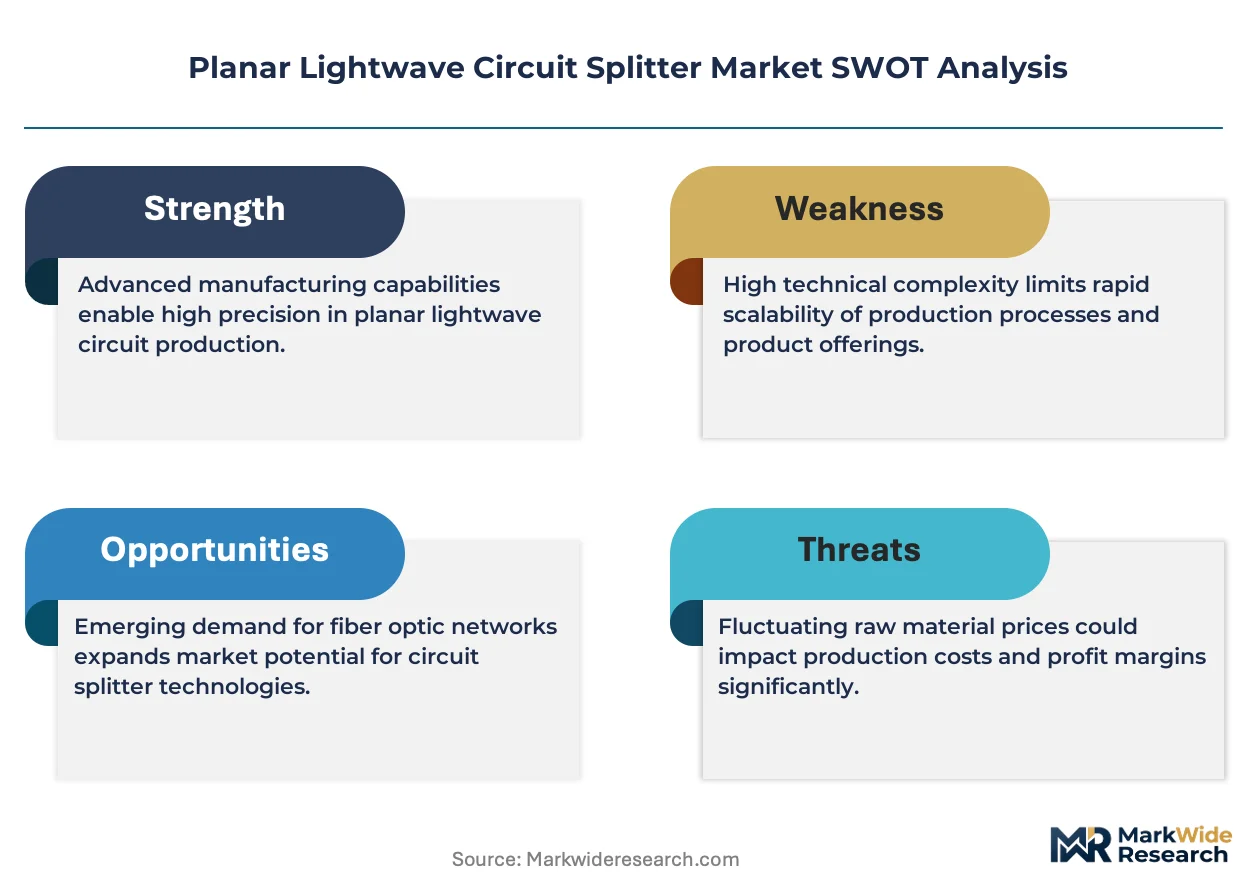
Silicon photonics integration is compressing form factors while tightening thermal specifications, forcing incumbent silica-based manufacturers to recalibrate deposition chemistries and waveguide geometries to defend process margins against semiconductor-foundry entrants.
Growth Catalysts
- FCC Rural Digital Opportunity Fund:US carrier procurement timelines for passive optical network infrastructure have compressed as subsidy disbursement windows narrow, accelerating splitter volume commitments from qualified vendors.
- 5G fronthaul densification:South Korean and Japanese equipment makers source 1x32 and 1x64 splitters for centralized RAN architectures, pulling high-channel-count configurations into volume production.
- Flame hydrolysis deposition automation:Chinese substrate fabricators have reduced waveguide defect rates through robotic handling systems, lowering per-unit inspection overhead for export-grade splitters.
Market Restraints
- Silica substrate supply concentration:Synthetic quartz ingot production clusters in Hubei and Shandong provinces, exposing splitter manufacturers to regional power rationing and logistics bottlenecks.
- REACH dopant restrictions:ECHA limitations on germanium and phosphorus compounds used in refractive index tuning force European fabricators toward alternative dopant systems with unproven long-term reliability.
- Polymer splitter cost competition:Acrylic-based optical splitters for indoor wall-mount installations capture price-sensitive residential segments where insertion loss tolerance exceeds 6 dB.
Strategic Opportunities
- India BharatNet Phase III:The country's rural broadband program mandates domestic value-add requirements, creating qualification pathways for local assembly partners of foreign splitter substrate suppliers.
- Data center co-packaged optics:Convergence of silicon photonics with electronic switching fabrics enables splitter-on-chip architectures for hyperscale interconnection fabrics.
- Japan Green Transformation bonds:METI-subsidized fiber infrastructure projects prioritize low-carbon manufacturing credentials, rewarding splitter vendors with verified supply chain emissions data.
Industry Challenges
- Photolithography technician scarcity:Waveguide patterning requires sub-micron alignment expertise that vocational programs in East Asian manufacturing clusters struggle to replenish at replacement rates.
- GB standard recertification timelines:China's updated insertion loss specifications for optical passive components force 12-18 month requalification cycles for incumbent export suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Planar Lightwave Circuit Splitter Market |
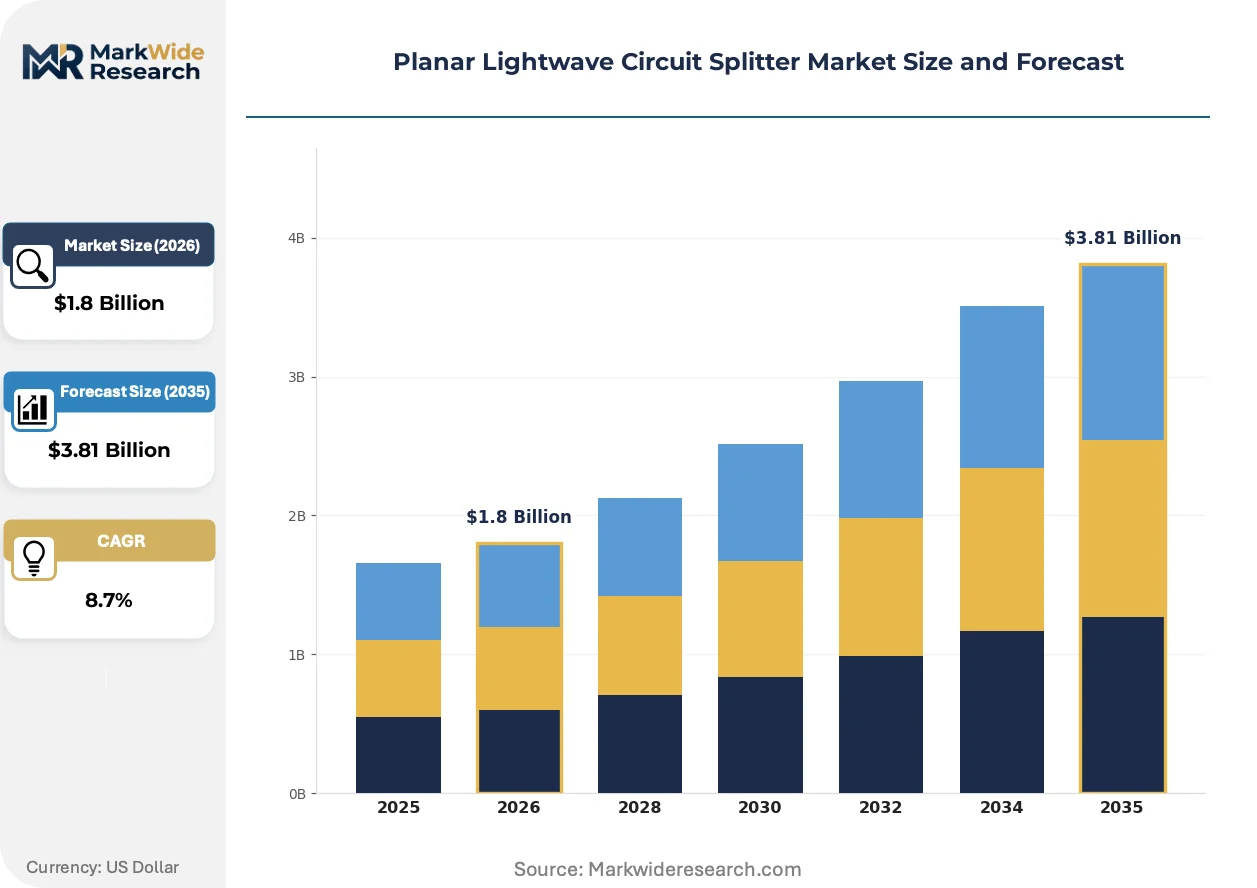
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 1x2, 1x4, 1x8, 1x16 Technology: Silicon Photonics, Lithium Niobate, Glass Fiber, Polymer End User: Telecommunications, Data Centers, CATV, Fiber to the Home Installation Type: Patch Panel, Wall Mount, Rack Mount, Standalone |
| Companies Covered | Corning, Broadex Technologies, NTT Electronics, Senko Advanced Components, Browave Corporation, Changzhou Linket Electronic Technology, Korea Optron Corp, Go Foton, T&S Communication, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Planar Lightwave Circuit Splitter Market Emerging Trajectories
Waveguide fabrication methods and procurement specifications are diverging as data center density requirements clash with carrier network cost structures, fragmenting R&D investment across incompatible technical trajectories.
Silicon photonics splitter-on-chip architectures are virtualizing discrete waveguide arrays into monolithic substrates. Hyperscale cloud operators in Ashburn and Frankfurt pilot these devices for co-packaged optical switch fabrics. The technology is virtualizing traditional silica-based supplier relationships as semiconductor foundries capture design wins previously held by optical component specialists.
China's MIIT fiber infrastructure mandates now require domestic certification for all passive optical components deployed in state-funded broadband projects. Foreign splitter manufacturers must establish local testing partnerships with MIIT-accredited laboratories to maintain procurement eligibility. Tier-1 Chinese carriers have responded by consolidating supplier panels around vendors with established in-country metrology capabilities.
Carrier procurement departments now unbundle installation support from hardware supply contracts, treating splitter deployment as commoditized infrastructure rather than turnkey solution purchases. Distributors in Seoul and Tokyo have captured this service layer, inserting themselves between substrate manufacturers and field engineering teams. This pattern is most visible in South Korea's 5G fronthaul buildouts, where equipment makers outsource logistics to specialized optical component distributors.
Planar Lightwave Circuit Splitter Market Segmentation
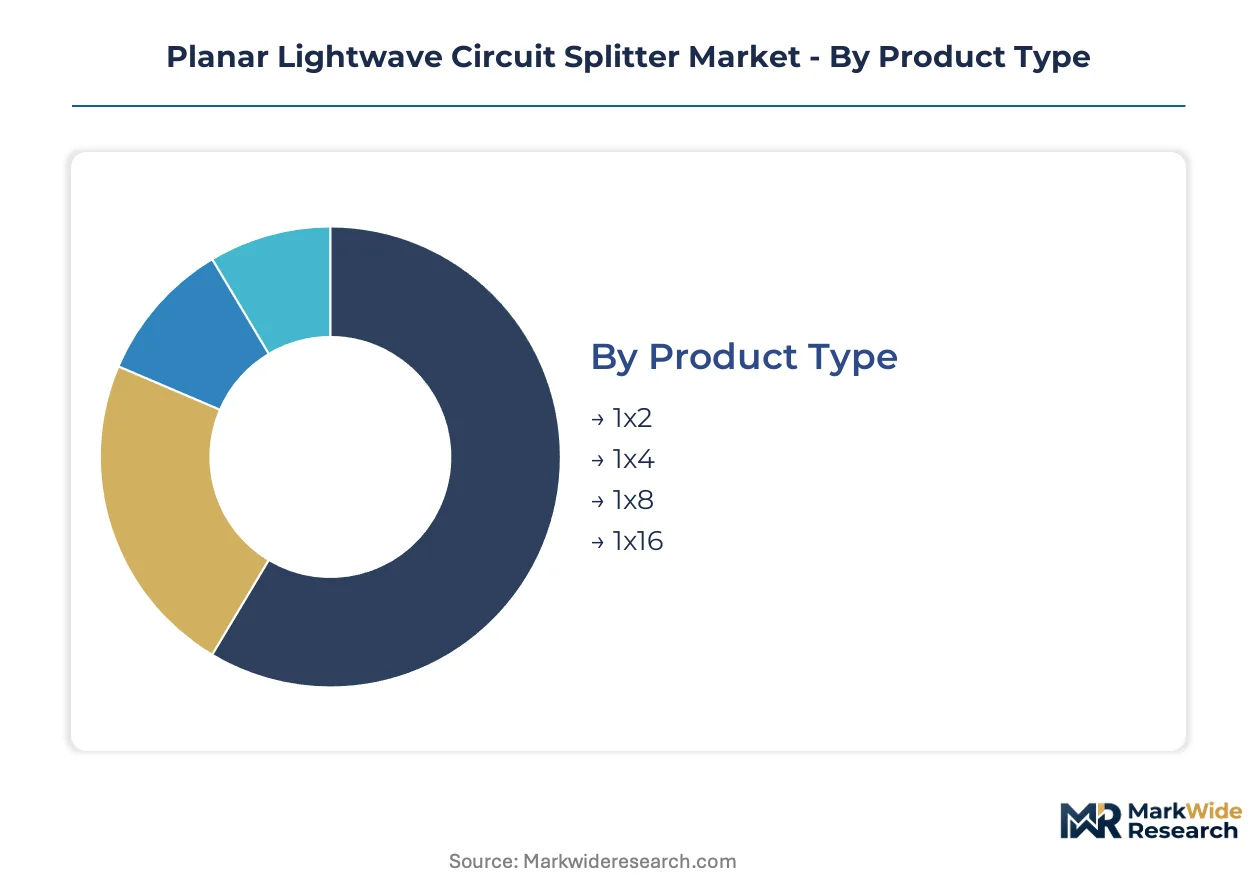
Segmentation in the Planar Lightwave Circuit Splitter Market reveals divergent procurement patterns between carrier-grade infrastructure and enterprise connectivity deployments. Each dimension—product density, substrate technology, end-use application, and physical mounting—carries distinct qualification protocols and margin structures that reshape vendor prioritization.
Product Type:
Mature 1x8 configurations dominate carrier procurement volumes while emerging 1x32 and 1x64 densities capture 5G fronthaul expansion.
- 1x2:Minimal channel division suits redundancy paths and monitoring taps in enterprise LAN backbones. Demand concentrates in Japanese corporate campus upgrades where NTT East specifications favor low-loss simplicity over density.
- 1x4:Balanced split ratios serve small-scale Fiber to the Home drops and distributed antenna system feeds. South Korean apartment complex rollouts source this configuration for basement distribution frames.
- 1x8:Silica waveguide arrays achieve insertion loss below 4 dB through flame hydrolysis deposition on synthetic quartz substrates. China's rural broadband programs under MIIT mandates accelerate procurement volumes for village-level optical line terminals.
- 1x16:Higher port density strains thermal stability in passive optical networks. Data center interconnection fabrics in Ashburn pilot these splitters for spine-leaf architectures demanding compact form factors.
1x8 retains volume leadership; 1x16 holds the steepest expansion curve.
Technology:
Cost tier stratification separates premium semiconductor-foundry outputs from commodity glass fiber alternatives.
- Silicon Photonics:Monolithic integration on CMOS-compatible substrates enables sub-micron waveguide pitch. Hyperscale operators in Frankfurt source these devices for co-packaged optical switch fabrics where thermal cycling tolerance exceeds 85°C.
- Lithium Niobate:Electro-optic modulation capability extends splitter functionality to tunable routing. Specialized telecommunications test equipment manufacturers in Tokyo specify these substrates for laboratory-grade signal distribution.
- Glass Fiber:Traditional fused biconical taper methods persist in price-sensitive CATV trunk installations.
- Polymer:Acrylic waveguides compete on material cost for indoor wall-mount scenarios with minimal environmental stress.
Glass Fiber retains volume leadership; Silicon Photonics holds the steepest expansion curve.
End User:
Application context dictates insertion loss budgets and packaging ruggedness requirements.
- Telecommunications:Carrier-grade specifications mandate Telcordia GR-1209 compliance for outdoor cabinet deployment. Verizon and AT&T procurement panels under FCC Rural Digital Opportunity Fund timelines compress supplier qualification windows.
- Data Centers:Hyperscale interconnection fabrics demand splitter-on-chip architectures with direct attach to electronic switching dies. Microsoft and Amazon Web Services pilot silicon photonics integration in Ashburn and Dublin facilities.
- CATV:Hybrid fiber-coaxial networks source 1x4 and 1x8 splitters for node segmentation.
- Fiber to the Home:Asia-Pacific carrier rollouts sustain the largest procurement volumes for residential optical network units.
Fiber to the Home retains volume leadership; Data Centers holds the steepest expansion curve.
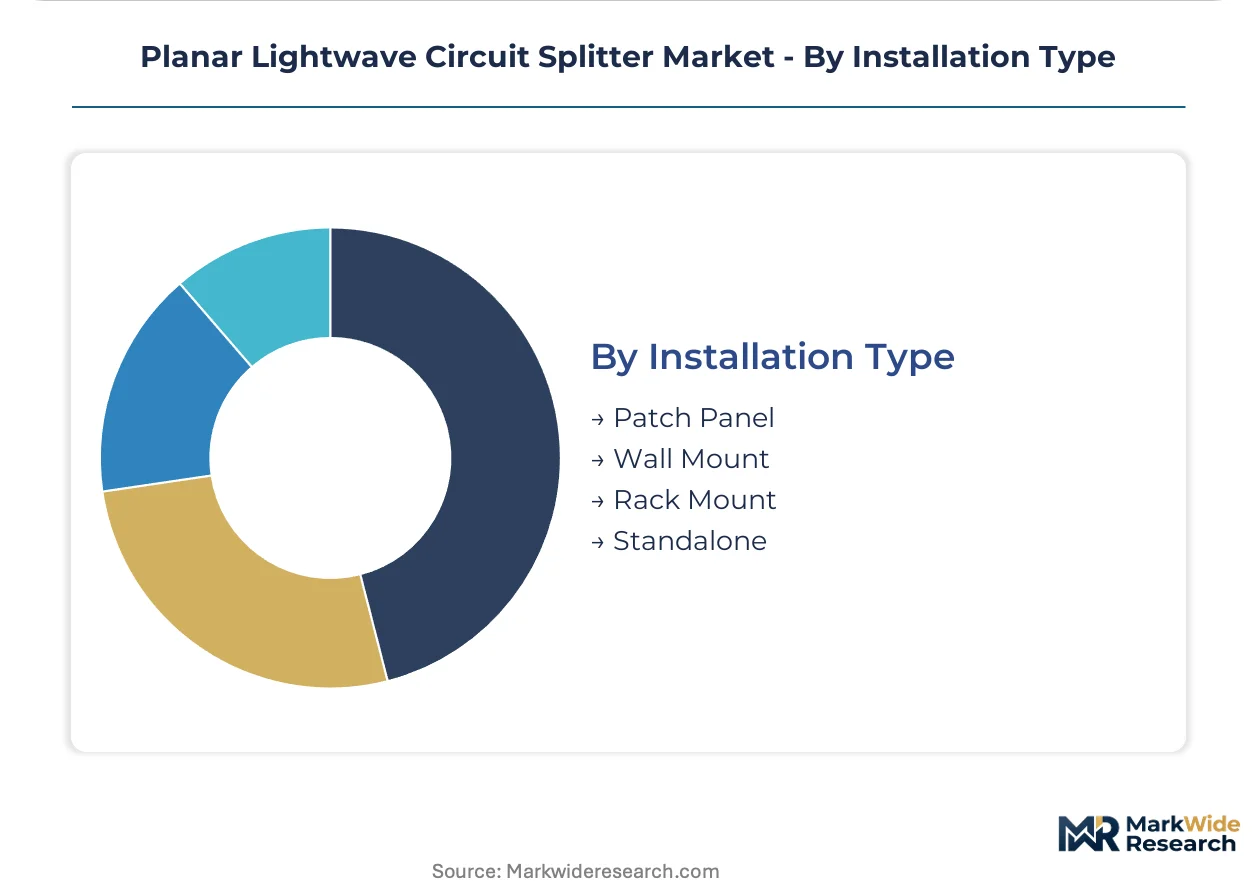
Installation Type:
Customer type differentiation separates centralized carrier facilities from distributed enterprise premises.
- Patch Panel:Modular cassette designs enable rapid reconfiguration in central office environments. NTT West standardizes these formats for Tokyo metropolitan exchange upgrades.
- Wall Mount:Compact enclosures suit residential multi-dwelling unit corridors and small business premises. China's GB standards specify ingress protection ratings for humid southern provinces.
- Rack Mount:19-inch standard chassis integrate with existing server infrastructure.
- Standalone:Weatherized housings serve outdoor cabinet deployments in rural broadband programs.
Patch Panel retains volume leadership; Wall Mount holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in East Asian manufacturing clusters where substrate fabrication achieves scale economies, while European and North American procurement faces cost premiums tied to REACH compliance and import logistics.
China
Rural broadband expansion under MIIT fiber infrastructure mandates drives procurement volumes for 1x8 and 1x16 splitters. GB standards for optical passive components now enforce tighter insertion loss specifications, forcing 12-18 month requalification cycles. Hubei and Shandong provinces host synthetic quartz ingot production clusters where robotic flame hydrolysis deposition systems have reduced waveguide defect rates.
Japan
5G fronthaul densification programs pull high-channel-count 1x32 and 1x64 splitters into volume production for centralized RAN architectures. METI Green Transformation bonds subsidize fiber infrastructure prioritizing low-carbon manufacturing credentials, rewarding vendors with verified supply chain emissions data. Tokyo and Osaka metropolitan exchanges standardize patch panel cassette formats for carrier network upgrades.
South Korea
Domestic equipment makers source splitters aggressively for 5G fronthaul buildouts, with procurement timelines compressing under carrier deployment schedules. Specialized optical component distributors in Seoul have captured installation support services, inserting themselves between substrate manufacturers and field engineering teams. Busan-Ulsan industrial corridors concentrate assembly operations for export-grade devices.
United States
FCC Rural Digital Opportunity Fund disbursement windows have compressed carrier procurement timelines for passive optical network infrastructure, accelerating volume commitments from qualified vendors. Verizon and AT&T procurement panels enforce Telcordia GR-1209 compliance for outdoor cabinet deployment. Ashburn data center clusters pilot silicon photonics splitter-on-chip architectures for hyperscale interconnection fabrics.
Germany
ECHA REACH limitations on germanium and phosphorus compounds force fabricators toward alternative dopant systems with unproven long-term reliability. Frankfurt hyperscale facilities source silicon photonics devices for co-packaged optical switch fabrics where thermal cycling tolerance exceeds 85°C. Bavaria and Baden-Württemberg host precision optics manufacturing serving European carrier supply chains.
Planar Lightwave Circuit Splitter Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream on substrate and waveguide fabrication. Market structure exhibits moderate consolidation around incumbent silica-based manufacturers defending process margins against semiconductor-foundry entrants. Three archetypes dominate: captive optical fiber suppliers controlling input costs, silicon photonics integrators capturing data center design wins, and regional qualification specialists anchoring carrier supply chains. Competitive dynamics center on M&A for metrology capabilities and strategic partnerships for local certification pathways.
Among East Asian fabricators, Corning represents the captive supply archetype through upstream control over optical fiber substrates, while NTT Electronics exemplifies regional qualification dominance through Japanese carrier supply chain anchoring. Broadex Technologies occupies a position within the silicon photonics integration tier, reflecting concentrated R&D positioning against traditional waveguide manufacturers.
| Leading Market Players |
|---|
| Corning |
| Broadex Technologies |
| NTT Electronics |
| Senko Advanced Components |
| Browave Corporation |
| Changzhou Linket Electronic Technology |
| Korea Optron Corp |
| Go Foton |
| T&S Communication |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Rotterdam maritime corridor's container rate volatility transmits cost pressures through synthetic quartz substrate flows, amplifying price spreads between flame-hydrolysis-deposition specialists in Hubei province and carrier-grade splitter assemblers serving European FTTH programs. This logistics friction concentrates procurement power with vendors holding captive ingot production, while downstream buyers face tiered pricing calibrated to GB-standard certification tiers and REACH-compliant dopant formulations.
Pricing Analysis
Configured-to-order 1x32 and 1x64 splitters command 40-60% premiums over standard 1x8 catalog configurations, reflecting photolithography setup costs and sub-micron alignment labor scarcity. Pricing stratifies across Telcordia GR-1209 certified premium tiers, MIIT-compliant standard tiers, and indoor polymer economy tiers. Cost compression in the standard tier is intensifying because Chinese substrate fabricators have automated flame hydrolysis deposition handling. Data center hyperscalers exhibit least price sensitivity due to co-packaged optics integration premiums, while rural broadband program administrators in India and Southeast Asia drive hardest procurement negotiations.
Supply Chain Analysis
Extended payment terms from South Korean equipment makers to Seoul-based optical component distributors have become a competitive weapon, with 90-120 day structures now standard for 5G fronthaul procurement. Synthetic quartz ingot supply concentrates in China's Hubei and Shandong provinces, with secondary substrate fabrication clusters in Japan's Shizuoka prefecture and South Korea's Busan-Ulsan corridor. The supply chain draws from germanium and phosphorus dopants, synthetic quartz feedstock, and precision photolithography equipment. Single-source vulnerability sits with flame hydrolysis deposition robotic handling systems sourced from Japanese automation specialists. Distribution runs through carrier-direct contracts for volume deployments and specialized optical distributors for installation-integrated projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sub-micron waveguide patterning expertise has become the constraining asset, with vocational programs in East Asian manufacturing clusters failing to replenish technician pipelines at replacement rates. This capability gap separates qualified incumbent substrate fabricators from semiconductor-foundry entrants lacking optical-specific process knowledge.
For Market Incumbents: Build process moats around flame hydrolysis deposition automation and captive synthetic quartz ingot supply. Defend against silicon photonics displacement by tightening insertion loss specifications through proprietary dopant chemistries. Add metrology capacity in MIIT-accredited Chinese laboratories to compress requalification timelines for GB-standard updates. For New Entrants and Emerging Players: Build out domestic assembly partnerships for India's BharatNet Phase III rural broadband program, where local value-add requirements create qualification pathways without full substrate fabrication investment. Target polymer-based indoor wall-mount splitters for Southeast Asian residential multi-dwelling units, where environmental stress remains minimal and acrylic waveguide cost advantages prove decisive. Lead with distributor-installation service bundling to capture procurement departments unbundling hardware from field support. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with undermonetized precision optics divisions holding Telcordia and MIIT certifications but lacking standalone growth capital. Long-term viability favors vendors bridging silica-based carrier infrastructure with silicon photonics data center migration. Watch for inflection when semiconductor foundries announce co-packaged optics splitter-on-chip design wins at Ashburn or Frankfurt hyperscale facilities, signaling technology transition acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Integration | Semiconductor foundries capture design wins from optical component specialists at hyperscale facilities. |
| MIIT Certification Partnership | Foreign manufacturers secure procurement eligibility through accredited Chinese laboratory relationships. |
| Flame Hydrolysis Automation | Robotic handling systems reduce waveguide defect rates and inspection overhead for export-grade output. |
| Distributor Service Layer Capture | Seoul and Tokyo distributors insert between substrate manufacturers and field engineering teams. |
| Green Transformation Credentialing | Verified supply chain emissions data unlocks METI-subsidized Japanese fiber infrastructure projects. |
Methodological Framework
The analysis maps silica substrate fabrication, silicon photonics integration, polymer waveguide alternatives, and installation service layers, each validated through waveguide process engineers, carrier procurement officers, optical component distributors, and regulatory compliance specialists. Primary interview data triangulates against MIIT fiber infrastructure mandate documents, ECHA REACH restriction filings, FCC Rural Digital Opportunity Fund disbursement records, and Telcordia GR-1209 qualification protocols. Bottom-up unit economics for splitter configurations reconcile with top-down carrier capex projections across the analysis window.
Assumption sets hold fixed GB-standard insertion loss specifications and REACH dopant restrictions while varying 5G fronthaul densification timelines and data center co-packaged optics adoption curves. Segmentation dimensions span product density tiers, substrate technology classes, end-use applications, and installation formats. CAGRs derive from carrier procurement pipeline visibility and equipment maker volume commitments, with sensitivity to silicon photonics yield rates and flame hydrolysis deposition throughput improvements.
Sensitivities concentrate around MIIT recertification timeline extensions, semiconductor foundry splitter-on-chip commercialization acceleration, and synthetic quartz ingot supply disruptions from Hubei power rationing. Forecasts reflect documented assumptions; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Optical Transceiver Market
Optical Components
Optical Cross Connect Market
Optical Components
North America Laser Diode Market
Optical Components
Terbium Gallium Garnet Market
Optical Components
Distributed Fiber Optic Sensor (DFOS) Market
Optical Components
Fiber-Optic Attenuator Market
Optical Components
Waveguide Phase Shifter Market
Optical Components
Electronic Digital Magnifiers Market
Optical Components
Spectroradiometers Market
Optical Components
Asia-Pacific Optical Film Market
Optical Components
Lithium Niobate Modulator Market
Optical Components
CMP Polishing Machine Market
Optical Components
Ellipsometer Market
Optical Components
Duplication Disc Market
Optical Components
Prism Coupler Market
Optical Components
Silicon Photonics Market