
 Polysilicon for Solar Semiconductor Market | 2026-2036
Polysilicon for Solar Semiconductor Market Size, Share, and Industry Trends Forecast 2026-2036
Polysilicon for Solar Semiconductor Market Insights
Modular supply agreements between polysilicon producers and wafer manufacturers is broadening procurement flexibility for solar developers. Tongwei Co., Ltd leverages its integrated polysilicon-to-cell pipeline to control cost structures across production stages. Wacker Chemie AG anchors European supply with Siemens-process specialization for semiconductor-grade material. Daqo New Energy Corp. dominates Xinjiang-based capacity expansion, competing on scale against fluidized bed reactor specialists.
Polysilicon for solar semiconductor denotes high-purity silicon feedstock with impurity levels below one part per billion, produced via chemical vapor deposition in trichlorosilane-fed reactors for subsequent crystallization into monocrystalline or multicrystalline ingots. Its primary purpose lies in converting photovoltaic energy through silicon-based p-n junctions with conversion efficiencies exceeding twenty-two percent in PERC and TOPCon architectures. G6 and G7 grades command expanding volume share as N-type cell architectures displace legacy P-type demand, while the Siemens Process retains margin concentration despite fluidized bed reactor gains in specific cost-sensitive applications. Utility Scale procurement pools now absorb the dominant share of G7 output, with Residential and Commercial segments trailing in grade-specific uptake.
China's MIIT enforces GB standards for polysilicon energy consumption per kilogram, while the EU Green Deal and F-Gas Regulation constrain fluorinated gas emissions from Siemens-process operations in European facilities. India's BIS certification requirements for solar module components are tightening import specifications for polysilicon sourced across ASEAN supply corridors. Stakeholders must track divergence between national carbon border adjustments and domestic content bonus structures as these mechanisms reshape competitive access across integrated manufacturing zones.
Market Dynamics
N-type cell architectures are compressing legacy P-type demand and concentrating procurement around G6 and G7 grade specifications, forcing feedstock suppliers to reconfigure purification lines and energy intensity profiles.
Growth Catalysts
- China's MIIT energy consumption standards:GB standards for kilowatt-hour per kilogram targets are accelerating furnace upgrades and process efficiency investments across domestic polysilicon corridors.
- Utility-scale solar procurement pools:Centralized tendering mechanisms for gigawatt-scale projects are consolidating offtake agreements around long-term G7 supply contracts with fixed-price escalators.
- TOPCon diffusion:Tunnel oxide passivated contact cell manufacturing is expanding addressable volume for ultra-high-purity feedstock with boron and phosphorus doping precision below 0.1 parts per billion.
Market Restraints
- Xinjiang concentration risk:Geographic clustering of metallurgical-grade silicon and polysilicon capacity in northwest China exposes supply chains to logistics bottlenecks and carbon border adjustment vulnerabilities.
- Silicon metal price volatility:Quartzite mining constraints and ferroalloy competition for metallurgical-grade silicon are transmitting cost shocks downstream to trichlorosilane synthesis economics.
- Fluidized bed reactor yield limitations:Granular polysilicon production remains capped at lower purity ceilings versus Siemens-process rods, restricting substitution in semiconductor-grade applications.
Strategic Opportunities
- India's BIS certification expansion:Mandatory quality standards for solar module components are creating first-mover advantages for polysilicon suppliers establishing ASEAN corridor qualification pathways.
- EU Green Deal carbon border adjustments:Import tariffs based on embedded emissions are incentivizing European Siemens-process capacity restart and low-carbon polysilicon premium positioning.
- Integrated polysilicon-to-wafer manufacturing:Captive production of ingots and wafers is expanding margin capture for feedstock producers with crystallization furnace deployment capabilities.
Industry Challenges
- High-purity chemical handling expertise:Semiconductor-grade polysilicon production requires specialized trichlorosilane distillation and corrosion-resistant reactor maintenance skills that remain scarce outside established manufacturing clusters.
- Dual certification timelines:Simultaneous qualification for solar and semiconductor grade specifications under diverging testing protocols is extending product release cycles and capital lockup periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polysilicon for Solar Semiconductor Market |
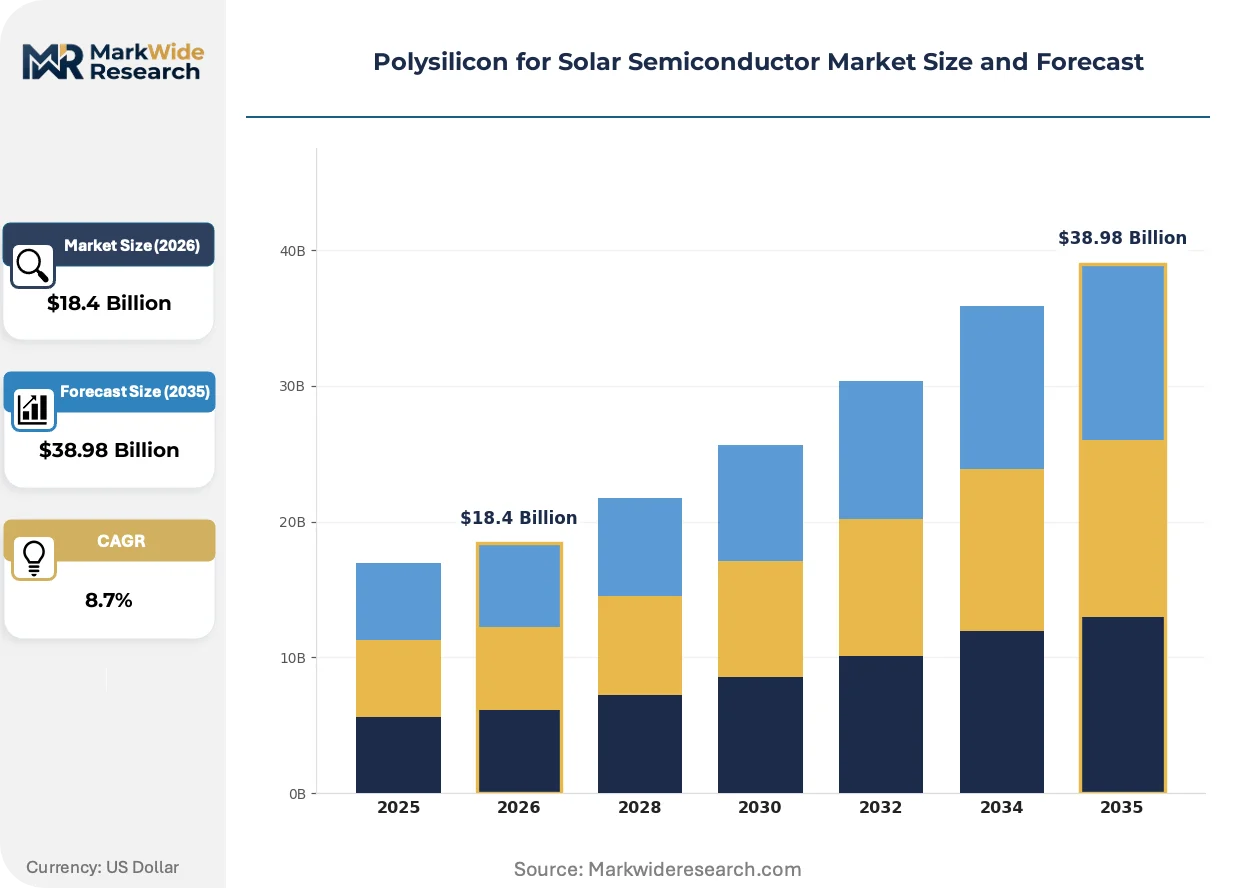
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $38.98 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: G5, G6, G7, G8 Application: Photovoltaic Cells, Solar Modules, Solar Panels, Industrial Use Production Method: Siemens Process, Fluidized Bed Reactor, Orange Process, Other Methods End User: Utility Scale, Commercial, Residential, Industrial Users |
| Companies Covered | Tongwei Co., Ltd, Daqo New Energy Corp., GCL Technology Holdings Co., Ltd., Wacker Chemie AG, Xinte Energy Co., Ltd, OCI Company Ltd, Hemlock Semiconductor Corporation, REC Silicon ASA, Tokuyama Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polysilicon for Solar Semiconductor Market Trends and Innovations
Process intensification and digital twin deployment are compressing energy consumption curves while regulatory carbon accounting is reshaping locational competitiveness for new capacity investments.
FBR-Siemens hybrid reactor configurations are expanding into utility-scale solar feedstock production as manufacturers seek to combine granular polysilicon cost advantages with rod-based purity control. Wafer producers in East Asian manufacturing corridors are piloting blended feedstock recipes that optimize crucible loading efficiency. This technology convergence is expanding into cost-sensitive applications previously reserved for conventional Siemens-process material alone.
The EU F-Gas Regulation is tightening emission caps on fluorinated compounds used in Siemens-process cleaning cycles, forcing European facilities to retrofit abatement systems or shift to alternative etching chemistries. Industrial consequence includes elevated operating expenditure for incumbent producers and accelerated process innovation timelines. Semiconductor-grade polysilicon output from German and Norwegian corridors is most affected, with producers responding through closed-loop trichlorosilane recovery investments.
Long-term offtake contracting with fixed-volume escalators is displacing spot-market purchasing among utility-scale project developers seeking supply security for multi-gigawatt deployment pipelines. Aggregated procurement through developer consortiums is consolidating buyer power and compressing supplier margins on standard-grade material. This behavioral shift is most visible in North American and Middle Eastern markets where independent power producers lack backward integration into wafer manufacturing.
Polysilicon for Solar Semiconductor Market Segmentation
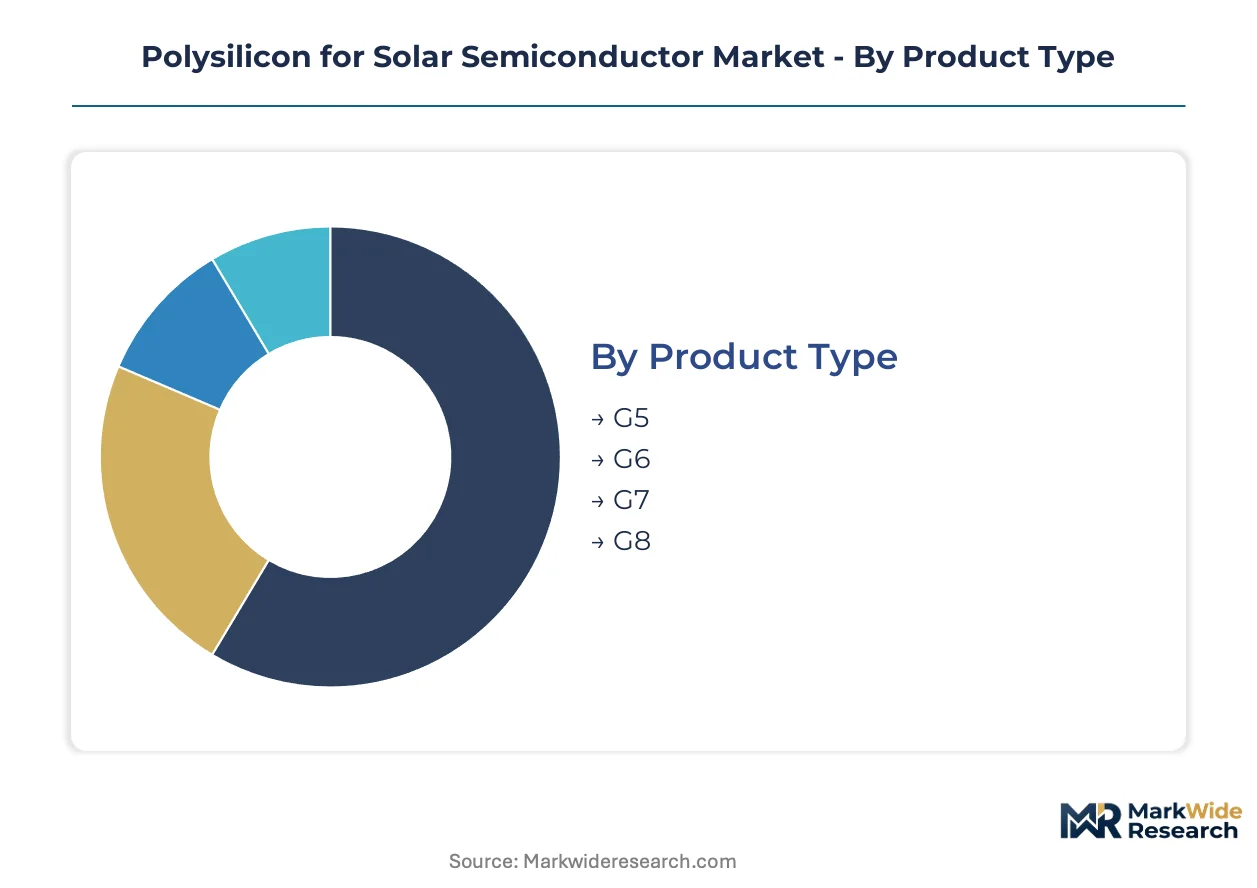
Grade purity specifications and production method economics determine procurement patterns across solar semiconductor supply chains. Segment boundaries shift as N-type cell architectures displace legacy P-type demand and carbon border adjustments reshape locational competitiveness for new capacity investments.
Product Type:
Standalone high-purity grades serve discrete certification tiers while embedded lower-purity material integrates into blended feedstock recipes for cost-sensitive applications.
- G5:Legacy solar-grade polysilicon with boron and phosphorus impurity levels near one part per billion. Demand concentrates in residual P-type multicrystalline ingot production in Southeast Asian manufacturing corridors facing cost pressure from newer architectures.
- G6:Intermediate purity grade bridging solar and semiconductor specifications with dopant control below 0.5 parts per billion. Procurement pools in East Asian N-type cell fabs are absorbing volumes as TOPCon diffusion accelerates furnace qualification timelines.
- G7:Ultra-high-purity feedstock for advanced cell architectures.
- G8:Semiconductor-grade material exceeding solar purity thresholds.
Volume placements concentrate in G6; the faster expansion belongs to G7.
Application:
Cost tier stratification separates premium cell-grade procurement from standard module assembly and economy industrial feedstock sourcing.
- Photovoltaic Cells:Direct feedstock consumption in p-n junction formation for monocrystalline architectures. China's N-type transition and TOPCon diffusion are concentrating G7 procurement in Tongwei and LONGi manufacturing corridors.
- Solar Modules:Encapsulated cell assemblies requiring lower-purity silicon in junction box and frame components. Module assemblers in India and Vietnam are absorbing G5 residual volumes as BIS certification tightens import specifications.
- Solar Panels:Field-deployed arrays integrating modules with mounting and inverter systems.
- Industrial Use:Non-solar applications in electronics and specialty chemicals.
Photovoltaic cells claim the dominant procurement share; solar modules are expanding most quickly as distributed generation accelerates.
Production Method:
Customer type differentiation separates utility-scale developers seeking Siemens-process purity from commercial installers accepting FBR economics.
- Siemens Process:Chemical vapor deposition of trichlorosilane in rod-form reactors yielding semiconductor-grade purity. Wacker Chemie AG anchors European supply with German and Norwegian corridor specialization under EU F-Gas Regulation emission constraints.
- Fluidized Bed Reactor:Granular polysilicon production via silane decomposition in fluidized particle beds. REC Silicon and Hanwha Solutions are scaling FBR capacity in Washington state and South Korea for utility-scale solar cost advantages.
- Orange Process:Emerging metallurgical purification route reducing energy intensity.
- Other Methods:Experimental and hybrid reactor configurations.
Siemens Process retains margin concentration; FBR-Siemens hybrids are climbing the fastest as blended feedstock recipes gain traction.
End User:
Supply concentration patterns align with project scale: gigawatt-scale pools command dedicated G7 contracts while fragmented residential demand absorbs spot-market G6 availability.
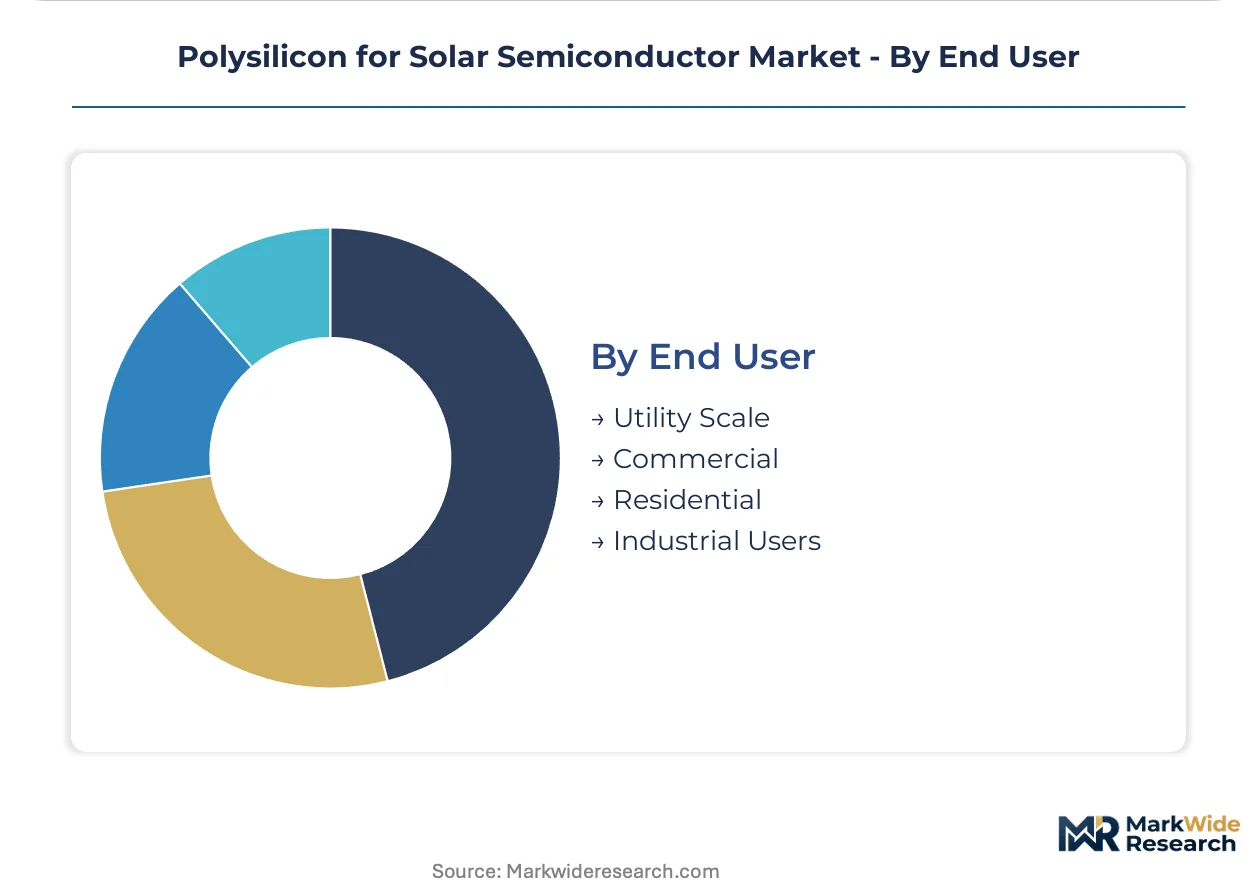
- Utility Scale:Centralized solar farms above 50 megawatts with long-term offtake contracting. Procurement pools in Saudi Arabia, Morocco, and Chile are consolidating G7 supply agreements with fixed-price escalators for multi-gigawatt pipelines.
- Commercial:Distributed generation systems for industrial and retail facilities. Rooftop installers in Germany and Australia are absorbing G6 volumes as net metering policies shift toward self-consumption optimization.
- Residential:Single-family and small multi-family building installations.
- Industrial Users:Captive consumption in vertically integrated manufacturing.
Utility scale dominates absolute volume; commercial deployment is gaining share fastest as behind-the-meter economics improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of polysilicon feedstock while consuming even larger volumes through its domestic cell and module assembly base. This production-consumption asymmetry shapes trade flows and carbon border vulnerabilities across integrated supply chains.
China
Xinjiang and Inner Mongolia host the dominant share of metallurgical-grade silicon smelting and polysilicon purification capacity. MIIT enforces GB standards for energy consumption per kilogram, accelerating furnace upgrades across domestic corridors. Manufacturing clusters in Sichuan leverage hydropower access to produce lower-carbon polysilicon for export qualification.
Germany
Specialized Siemens-process capacity in Burghausen and Nünchritz anchors European semiconductor-grade supply. The EU F-Gas Regulation constrains fluorinated compound emissions from cleaning cycles, elevating operating expenditure for incumbent producers. Wacker Chemie AG maintains rod-form reactor operations under these emission constraints while supplying advanced cell architectures.
United States
Washington state hosts fluidized bed reactor capacity serving cost-sensitive utility-scale solar procurement. The Inflation Reduction Act domestic content bonus structures are reshaping competitive access for polysilicon sourced across integrated manufacturing zones. REC Silicon ASA represents the granular production archetype in this corridor.
India
Gujarat and Tamil Nadu are emerging as module assembly hubs with tightening BIS certification requirements for solar component imports. The country's national renewable energy regulator enforces quality standards that create first-mover advantages for ASEAN corridor qualification pathways. Polysilicon demand concentrates in Mundra and Sri City manufacturing zones.
South Korea
Busan-Ulsan and Seoul Capital Area house integrated electronics conglomerates with captive polysilicon consumption. The national industrial regulator enforces chemical handling standards for high-purity trichlorosilane operations. Hanwha Solutions scales FBR capacity for blended feedstock recipes targeting cost-sensitive applications.
Polysilicon for Solar Semiconductor Market Competitive Landscape
The competitive structure tilts toward scale-driven integrated producers with captive wafer manufacturing capabilities. Market concentration is pronounced at the feedstock tier, where purification energy intensity and capital requirements create barriers to entry. Three archetypes dominate: integrated polysilicon-to-cell pipelines, Siemens-process specialists serving semiconductor-grade demand, and fluidized bed reactor operators competing on granular production economics. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with producers securing long-term offtake agreements through developer consortiums.
Within the integrated pipeline tier, Tongwei Co., Ltd and Daqo New Energy Corp. exemplify scale-driven positioning through backward control over crystallization stages. Wacker Chemie AG occupies a specialized position among European Siemens-process operators, representing the purity-premium archetype under EU emission constraints. These three companies anchor the competitive map without exhaustive enumeration of strategic actions or financial positions.
| Leading Market Players |
|---|
| Tongwei Co., Ltd |
| Daqo New Energy Corp. |
| GCL Technology Holdings Co., Ltd. |
| Wacker Chemie AG |
| Xinte Energy Co., Ltd |
| OCI Company Ltd |
| Hemlock Semiconductor Corporation |
| REC Silicon ASA |
| Tokuyama Corporation |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal carbon border adjustment mechanisms gate both qualified supply and premium-tier pricing access for polysilicon producers seeking European utility-scale procurement pools. Manufacturers with verified low-carbon production footprints in Sichuan hydropower corridors command pricing premiums, while Xinjiang-origin material faces tariff exposure that compresses margin structures for unqualified suppliers.
Pricing Analysis
Margin tightening in G7 ultra-high-purity tiers reflects TOPCon furnace qualification bottlenecks and concentrated buyer power among Saudi and Moroccan gigawatt-scale developers. Three-tier pricing structure across premium, standard, and economy levels separates semiconductor-grade G8 from solar G7 and residual G5 feedstock, with quality grade and volume scale as primary differentiation drivers. Cost-down pressure on G6 intermediates accelerates because N-type cell fabs are consolidating procurement around long-term fixed-price escalators. Utility-scale independent power producers exhibit highest price sensitivity; semiconductor-grade buyers show lowest sensitivity due to purity certification requirements.
Supply Chain Analysis
Regional distribution centers in Busan-Ulsan, Burghausen, and Washington state anchor hub-and-spoke patterns for differentiated feedstock grades. Supply concentrates in China, Germany, and the United States, with metallurgical-grade silicon smelting drawing from quartzite mining corridors in Australia, Norway, and Brazil. Raw material dependencies rest on trichlorosilane synthesis, high-purity hydrogen, and corrosion-resistant reactor components. Single-source vulnerability in Xinjiang purification capacity exposes logistics bottlenecks during carbon border enforcement phases. Distribution runs through captive wafer manufacturing pipelines for integrated producers and merchant spot markets for independent developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polysilicon market sits in a technology-transition phase as TOPCon and heterojunction architectures displace legacy PERC cell manufacturing. This displacement concentrates procurement around G6 and G7 grade specifications that legacy P-type supply chains cannot serve.
For Market Incumbents: Hedge against fluidized bed reactor yield limitations by securing Siemens-process purity certification for semiconductor-grade qualification pathways. Daqo New Energy Corp and Tongwei Co., Ltd exemplify scale-driven positioning through backward integration into crystallization furnace deployment. Incumbents should anchor European supply corridors under EU F-Gas Regulation emission constraints while expanding ASEAN qualification pathways for India's BIS certification expansion. Capacity addition in Sichuan hydropower zones offers carbon intensity advantages for premium-tier pricing access. For New Entrants and Emerging Players: India's BIS certification expansion opens a window for ASEAN corridor qualification pathways targeting Mundra and Sri City module assembly zones. New entrants should prioritize G6 intermediate purity grades where TOPCon diffusion has created supply gaps between legacy G5 residual volumes and concentrated G7 procurement pools. The most penetrable segment lies in commercial rooftop installations across Germany and Australia absorbing spot-market G6 availability. A go-to-market angle anchored in blended feedstock recipes for cost-sensitive utility-scale solar developers offers differentiation against established Siemens-process specialists. For Investors and Strategic Acquirers: Long-term offtake contracting with fixed-volume escalators displacing spot-market purchasing is the leading indicator that utility-scale developer consortiums are consolidating buyer power and compressing supplier margins. Investment viability over the five-to-ten-year horizon hinges on carbon border adjustment alignment and purification energy intensity profiles. Acquisition targets should display integrated polysilicon-to-wafer manufacturing capabilities with captive crystallization furnace deployment. The signal to monitor is MIIT GB standard enforcement accelerating furnace upgrade investments across domestic Chinese corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Xinjiang and Inner Mongolia corridors add purification reactors to serve N-type cell demand. |
| Backward Integration | Tongwei Co., Ltd controls cost structures across polysilicon-to-cell pipeline stages. |
| Green Manufacturing Transition | Sichuan hydropower-based production qualifies for EU Green Deal carbon border premium positioning. |
| Long-term Supply Agreement | Saudi and Moroccan gigawatt-scale developers consolidate G7 procurement through fixed-price escalators. |
| Joint Venture | FBR-Siemens hybrid reactor configurations combine granular cost advantages with rod-based purity control. |
Research Methodology
Multi-period observation of polysilicon grade-specific procurement volumes, furnace qualification timelines, and carbon intensity benchmarking anchored the trend analysis, supplemented by interviews with plant managers at purification facilities, procurement leads at wafer manufacturers, EPC contractors in utility-scale solar development, and technical R&D directors at cell fabrication facilities. Secondary validation drew from MIIT GB standard filings, EU F-Gas Regulation compliance disclosures, customs and trade data across ASEAN corridors, and SEC 10-K filings from listed polysilicon producers. Bottom-up grade-volume modeling and top-down energy transition demand projections were triangulated against capacity expansion announcements.
Segment-weighting across grade purity tiers, production method economics, application-specific certification requirements, and end-user scale categories structured the analytical framework throughout the forecast period. CAGRs were derived from installed capacity pipelines for N-type cell architectures and displacement curves for legacy P-type demand. Industry-specific forecast inputs included TOPCon diffusion rates and carbon border adjustment implementation timelines.
Caveats apply where MIIT energy consumption standard enforcement, EU F-Gas Regulation retrofit requirements, or quartzite mining supply constraints could materially shift the outlook. Forecasts reflect documented assumptions regarding technology transition pacing and regulatory implementation schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Semiconductor Glass Wafer Market
Semiconductor Material
Electroceramics Market
Semiconductor Material
Chalcocite-Digenite Group Market
Semiconductor Material
Methyl Phenyl Silicone Resin Market
Semiconductor Material
Zinc Oxide Nanoparticles Market
Semiconductor Material
Gallium Trichloride Market
Semiconductor Material
Thermoelectric Materials Market
Semiconductor Material
India Liquid Silicon Rubber Market
Semiconductor Material
Europe Semiconductor Materials Market
Semiconductor Material
North America Semiconductor Materials Market
Semiconductor Material
Sapphire Substrate Market
Semiconductor Material
Semiconductor Grade PTFE Market
Semiconductor Material
Global Silicon Carbide (SIC) Market
Semiconductor Material
Tellurium Market
Semiconductor Material
Semiconductor Fabrication Material Market
Semiconductor Material
Europe Silicone Market