
 Lithium Niobate Modulator Market | 2026-2036
Lithium Niobate Modulator Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Niobate Modulator Market Analysis
Data service providers is rotating toward lithium niobate modulators as hyperscale cloud architectures displace legacy telecom procurement models. iXblue Group leverages in-house crystal growth and waveguide fabrication to sustain pricing power across European defense and research accounts. Fujitsu Optical Components Ltd anchors volume production for coherent optical transceivers serving Pacific Rim carrier networks. Lumentum Operations LLC differentiates through vertical control of indium phosphide and lithium niobate platforms for datacenter interconnects.
Lithium niobate modulators are electro-optic devices fabricated from LiNbO₃ crystals, typically operating at wavelengths near 1550 nm with half-wave voltages below 5 V for high-speed signal encoding in fiber-optic systems. Mach-Zehnder modulators dominate commercial volume due to established foundry processes and compatibility with 100 Gbps+ coherent formats. Electro-optic technology leads in bandwidth performance while photonic integration segments are gaining fastest as silicon nitride and thin-film lithium niobate hybrid platforms mature. Bulk modulators occupy a shrinking niche in laboratory and legacy test environments where packaging simplicity outweighs density requirements.
FCC equipment authorization rules in the United States and EU RoHS substance restrictions constrain material choices and qualification timelines for modulator vendors seeking transatlantic market access. Japan's METI funds domestic thin-film lithium niobate process development through national photonics initiatives, tightening supply alternatives for non-Japanese competitors. China's GB standards and MIIT certification requirements create parallel compliance tracks that favor local entities such as Beijing Panwoo Integrated Optoelectronic Inc. Stakeholders must monitor which regulatory bloc first mandates energy efficiency thresholds for optical transceivers, as this will cascade into modulator specification requirements across all supply tiers.
Market Dynamics
Thin-film lithium niobate fabrication is compressing half-wave voltages below 3 V while silicon photonics integration threatens discrete modulator architectures. This process convergence is redrawing competitive boundaries between bulk crystal suppliers and semiconductor foundries.
Growth Catalysts
- Hyperscale datacenter buildouts:Cloud operators in Virginia, Frankfurt, and Singapore are specifying lithium niobate modulators for 400 Gbps coherent links. Procurement volumes from Microsoft Azure and Amazon Web Services facilities are accelerating foundry utilization rates.
- Japan's METI photonics roadmap:National funding for thin-film process development is creating captive supply chains for domestic transceiver manufacturers. This policy mechanism is tightening technology access for non-Japanese competitors.
- Coherent DSP architecture evolution:Advanced modulation formats from 16-QAM to 64-QAM are demanding electro-optic bandwidth beyond indium phosphide capabilities. Lithium niobate's electro-optic coefficient is enabling these spectral efficiency gains.
Market Restraints
- Optical-grade lithium niobate crystal supply:Congoleum growth furnaces concentrate in Chinese and Japanese facilities. Non-Asian modulator vendors face 18-24 month qualification timelines for alternative substrate sources.
- EU RoHS substance restrictions:Lead-free soldering requirements and restricted substance lists are complicating hermetic packaging designs. Compliance testing adds 6-9 months to product certification cycles.
- Silicon photonics substitution:CMOS-compatible modulators from Intel and Cisco are capturing sub-100 Gbps applications. This platform threat is compressing addressable market scope for discrete lithium niobate devices.
Strategic Opportunities
- Quantum key distribution networks:China's national quantum communication backbone is procuring low-Vπ modulators for entanglement-based cryptography. This application is creating premium pricing tiers for ultra-low noise devices.
- Photonic integrated circuit foundry services:Tower Semiconductor and GlobalFoundries are adding thin-film lithium niobate process modules. Fabless modulator designers can now access captive fabrication without capital-intensive crystal growth investments.
- India's National Optical Fibre Network:BharatNet Phase III specifications are emphasizing domestic component sourcing. Local assembly partnerships with Cochin Special Economic Zone operators are creating market entry pathways.
Industry Challenges
- Thin-film process engineering talent:Wafer bonding, ion slicing, and sub-micron waveguide etching expertise concentrates in Japanese and French research institutes. Commercial-scale production teams command 40% salary premiums over bulk optics specialists.
- Multi-standard certification matrices:Simultaneous FCC Part 15, CE marking, and MIIT type approval requirements are fragmenting test budgets. Vendors serving transatlantic and Chinese markets face parallel qualification tracks.
- Legacy transceiver integration:Field-deployed 100 Gbps coherent modules use fixed-bias modulator architectures. Retrofit compatibility is forcing dual-product-line maintenance for modulator suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Niobate Modulator Market |
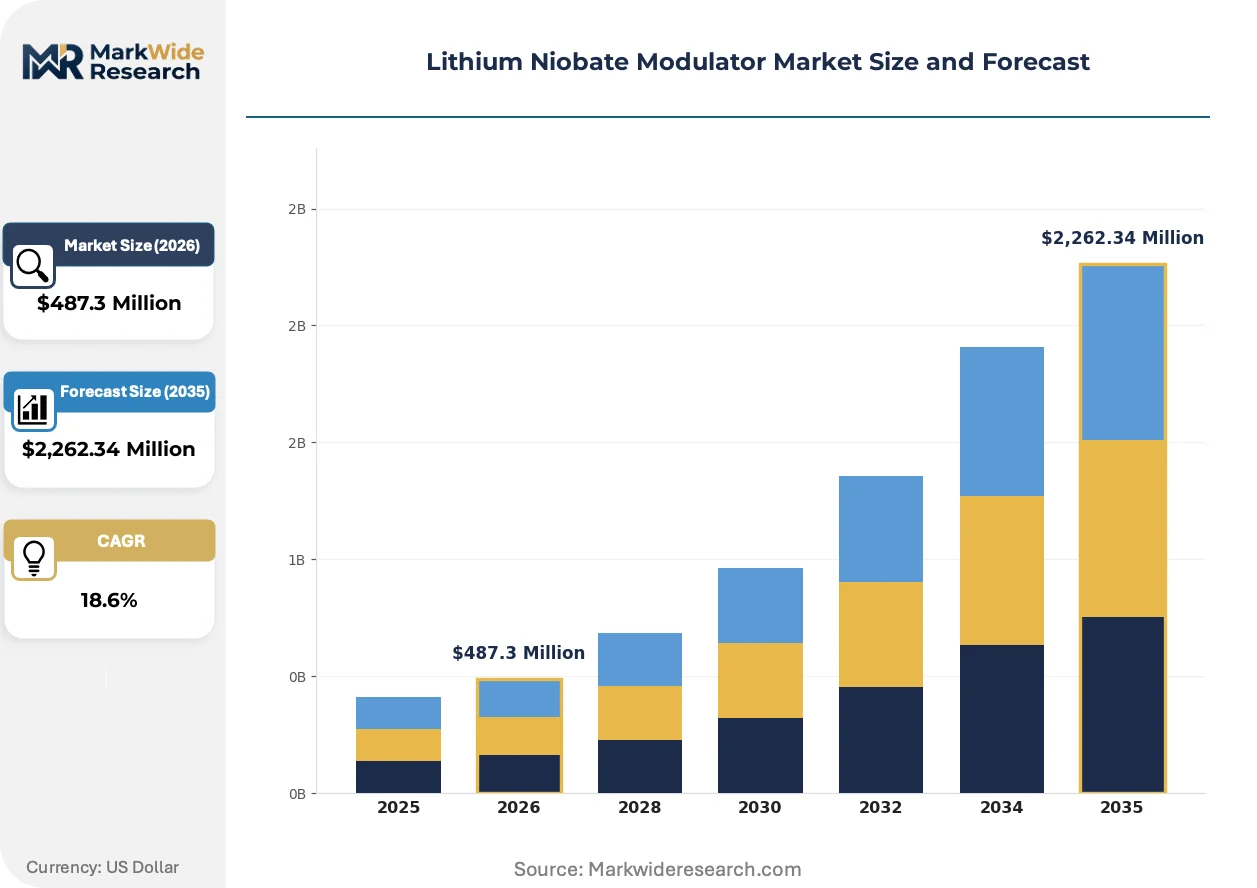
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $2,262.34 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Integrated Modulator, Bulk Modulator, Q-Switch Modulator, Mach-Zehnder Modulator Application: Telecommunications, Data Centers, Optical Networks, Test and Measurement End User: Telecom Operators, Data Service Providers, Research Institutions, Aerospace Technology: Electro-Optic, Acousto-Optic, Hybrid, Photonic Integration |
| Companies Covered | iXblue Group, Gooch & Housego plc, Fujitsu Optical Components Ltd, THORLABS, Lumentum Operations LLC, EOSPACE, Inc., Beijing Panwoo Integrated Optoelectronic Inc., Sumitomo Osaka Cement Co., Ltd., Photline, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Niobate Modulator Market Emerging Trajectories
Process migration from bulk to thin-film platforms is collapsing modulator footprints while multiplying bandwidth-density metrics. This transformation is enabling new packaging paradigms and threatening established supply relationships.
Thin-film lithium niobate on insulator is supplanting titanium-diffused waveguide structures in 800 Gbps transceiver designs. Coherent optical engine designers at Ciena and Infinera are adopting this platform for 96 GBaud applications. The technology is compressing modulator lengths from centimeters to millimeters while preserving electro-optic efficiency.
China's MIIT certification requirements for optical transceivers are mandating domestic component traceability. This regulatory friction is redirecting supply chain investment toward joint ventures with Beijing and Shanghai-based crystal growth facilities. Non-Chinese modulator vendors are establishing local assembly partnerships to maintain market access.
Hyperscale operators are consolidating optical component procurement through direct foundry relationships rather than transceiver vendor intermediation. Microsoft and Google are issuing their own modulator specifications to wafer fabs. This disintermediation is visible in Oregon and Iowa datacenter clusters where cloud architects specify electro-optic performance parameters directly.
Lithium Niobate Modulator Market Segmentation
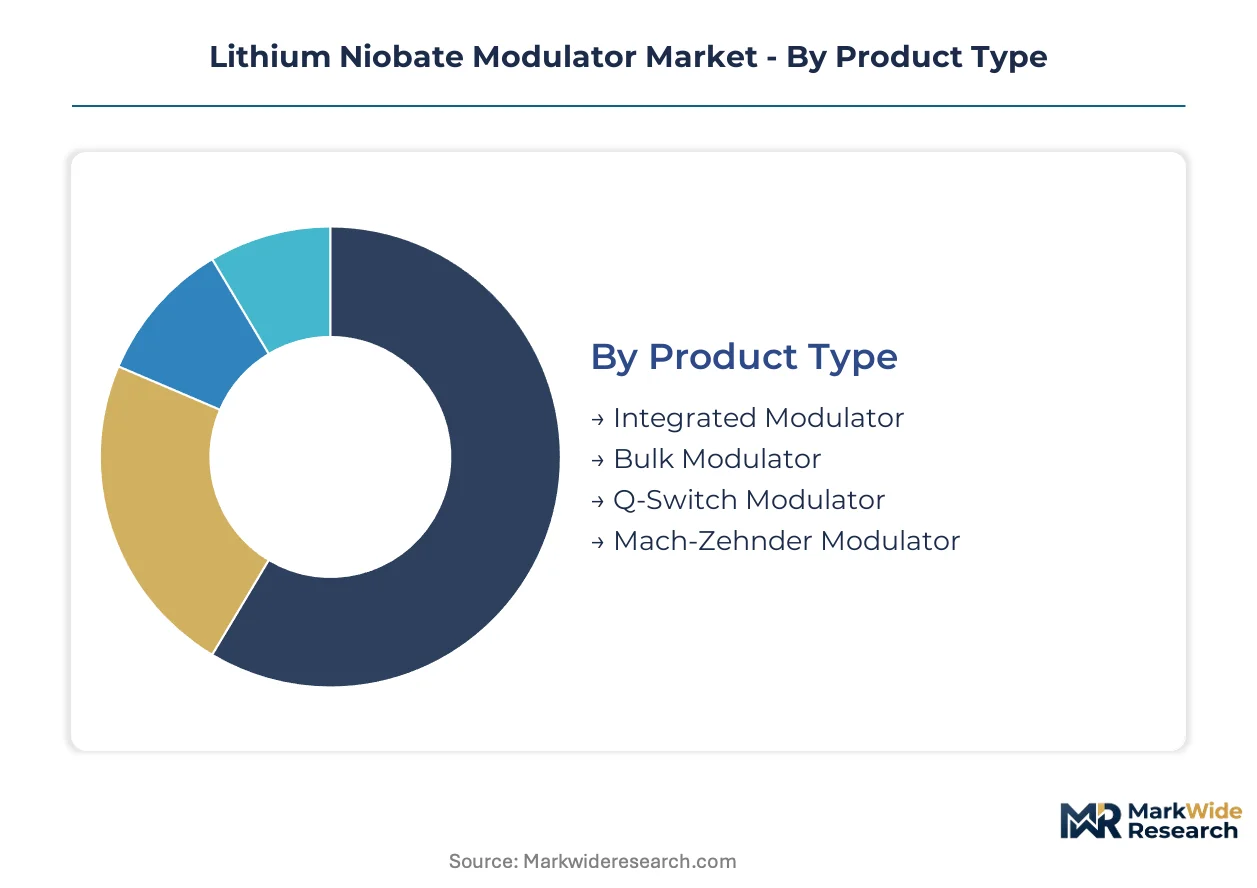
Lithium niobate modulators fragment across four structural dimensions that determine procurement channels and margin profiles. Product type and technology choices dictate whether volumes flow through transceiver OEMs or direct foundry relationships. Application and end-user segmentation reveals where pricing power concentrates versus where standardization erodes differentiation.
Product Type:
Channel strategy diverges sharply between integrated platforms serving hyperscale direct procurement and discrete devices moving through traditional optical component distribution.
- Mach-Zehnder Modulator:Titanium-diffused or thin-film waveguide structures dominate coherent optical transceiver designs at 400 Gbps and above. Demand concentrates in East Asian manufacturing clusters serving Pacific Rim carrier network upgrades, driven by 64-QAM modulation format requirements that exceed indium phosphide bandwidth limits.
- Integrated Modulator:Silicon nitride and thin-film lithium niobate hybrid platforms enable photonic integrated circuit architectures. Procurement is shifting toward direct foundry relationships with Tower Semiconductor and GlobalFoundries as cloud operators specify electro-optic parameters independently of transceiver vendors.
- Bulk Modulator:Congoleum-grown crystal substrates with simple packaging serve laboratory environments and legacy test equipment where density requirements remain minimal.
- Q-Switch Modulator:Pulsed operation designs address solid-state laser cavity control in industrial and research settings with limited volume scale.
By volume, Mach-Zehnder designs lead. By growth pace, Integrated platforms are expanding most quickly.
Application:
Cost tier stratification separates premium coherent engine specifications from commoditized connectivity modules.
- Data Centers:Hyperscale facilities in Virginia, Frankfurt, and Singapore specify lithium niobate modulators for 400 Gbps intra-campus links. Microsoft Azure and Amazon Web Services procurement volumes are accelerating thin-film foundry utilization rates.
- Telecommunications:Long-haul and metro carrier networks deploy coherent transceivers with electro-optic bandwidth requirements that silicon photonics cannot satisfy. Japan's NTT and South Korea's KT are anchoring regional demand concentration.
- Optical Networks:Enterprise and government backbone infrastructure favors established titanium-diffused platforms with proven field reliability.
- Test and Measurement:Instrument manufacturers require broadband linearity for optical spectrum analyzer and communications analyzer calibration sources.
Telecommunications generates the largest revenue pool. Data center applications show the steepest expansion trajectory.
End User:
Customer type determines whether procurement flows through consolidated transceiver vendors or fragmented direct channels.
- Data Service Providers:Cloud operators are consolidating component procurement through direct foundry specifications rather than intermediary transceiver vendors. This disintermediation is visible in Oregon and Iowa datacenter clusters.
- Telecom Operators:Tier-1 carriers in Japan and South Korea maintain captive optical component qualification programs that favor established Mach-Zehnder suppliers with multi-year field histories.
- Research Institutions:National laboratories and university photonics groups prioritize low-Vπ performance over volume cost, sustaining niche demand for specialty bulk and Q-switch designs.
- Aerospace:Satellite and defense communication systems require hermetic packaging and radiation-hard specifications that extend qualification timelines.
Data service providers are gaining share fastest in procurement volume. Telecom operators remain the largest installed base.
Technology:
Supply concentration in thin-film process expertise is redrawing competitive boundaries between crystal growers and semiconductor foundries.
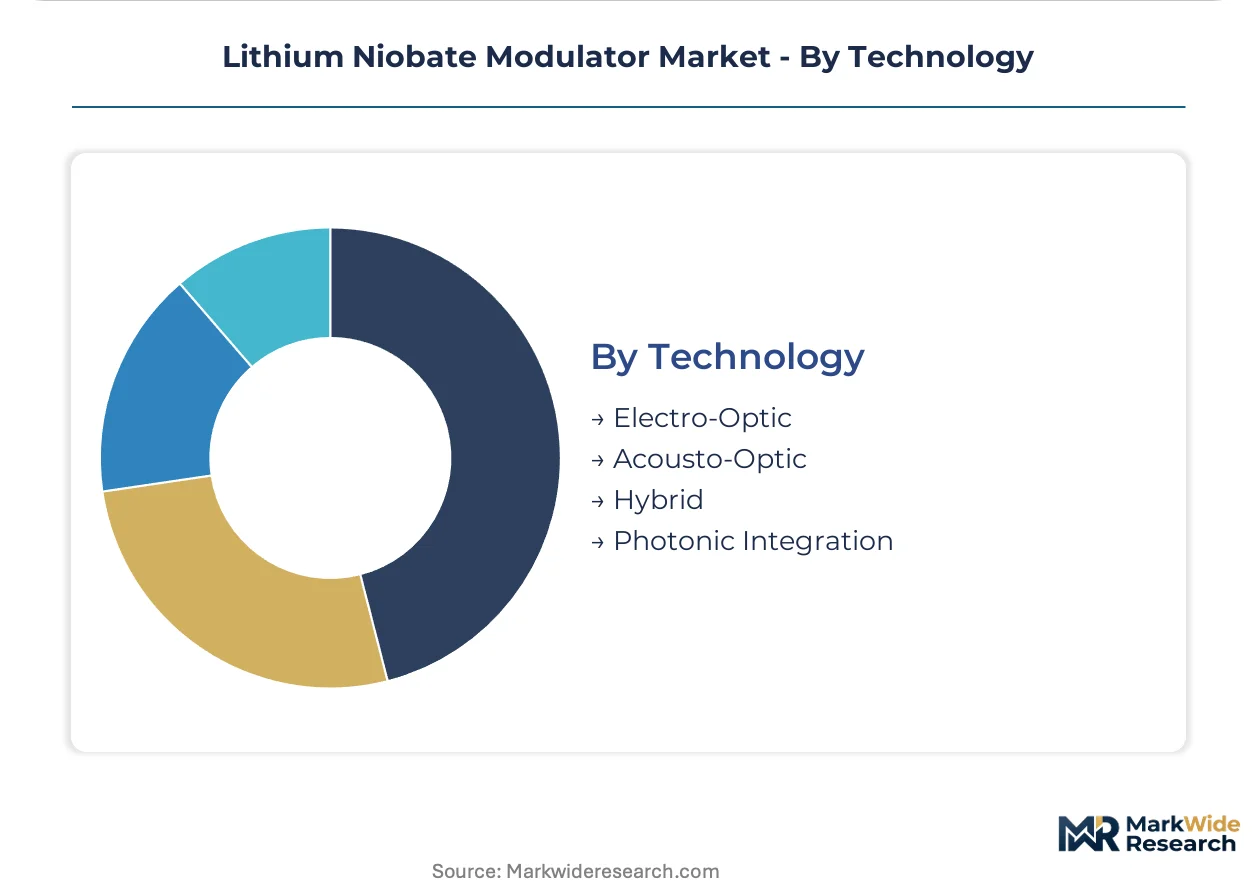
- Electro-Optic:Lithium niobate's Pockels effect enables voltage-controlled refractive index modulation with bandwidth exceeding competing material platforms. METI-funded Japanese process development is tightening technology access for non-domestic competitors.
- Photonic Integration:Thin-film lithium niobate on insulator platforms from ion slicing and wafer bonding processes enable millimeter-scale modulators with preserved electro-optic efficiency. Ciena and Infinera coherent engine designs are adopting this technology for 96 GBaud applications.
- Acousto-Optic:Surface acoustic wave interactions provide tunable filtering functions in specialized signal processing applications with limited addressable market scope.
- Hybrid:Multi-material platforms combining lithium niobate with silicon or indium phosphide address packaging and thermal management constraints in compact transceiver form factors.
Electro-Optic platforms dominate current revenue. Photonic Integration is climbing the fastest as thin-film processes mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pacific Light Cable Network landing stations in Japan and South Korea anchor East Asian demand concentration for high-bandwidth optical interconnects. Submarine cable termini in Singapore and Hong Kong funnel trans-Pacific data traffic through lithium niobate-equipped coherent transceivers. These infrastructure nodes determine where modulator procurement volumes aggregate.
China
MIIT certification requirements for optical transceivers are mandating domestic component traceability for national backbone upgrades. The national photonics initiative funds thin-film lithium niobate process development through Beijing and Shanghai research institutes. Yangtze River Delta manufacturing clusters are absorbing joint venture assembly partnerships from non-Chinese modulator vendors seeking market access.
Japan
METI's national photonics roadmap channels public funding toward captive thin-film process development for domestic transceiver manufacturers. NTT and other tier-1 carriers maintain multi-year qualification programs favoring established Mach-Zehnder suppliers. Kanto region optical component foundries concentrate wafer bonding and ion slicing expertise that commands salary premiums over bulk optics specialists.
South Korea
KT Corporation and SK Broadband are anchoring regional demand through metro and long-haul network modernization programs. The national regulator enforces electromagnetic compatibility standards that extend qualification timelines for imported modulator platforms. Seoul-Incheon manufacturing corridors host assembly operations serving Pacific Rim carrier procurement.
United States
Hyperscale datacenter buildouts in Virginia's Loudoun County and Oregon's Hillsboro cluster are specifying lithium niobate modulators for 400 Gbps intra-campus links. FCC equipment authorization rules constrain material choices and qualification timelines for transatlantic market access. Direct foundry relationships from Microsoft Azure and Amazon Web Services procurement teams are disintermediating traditional transceiver vendors.
Germany
Frankfurt's DE-CIX internet exchange and surrounding hyperscale facilities are driving coherent interconnect demand for lithium niobate platforms. EU RoHS substance restrictions complicate hermetic packaging designs with lead-free soldering requirements. Bavarian precision optics clusters host test and measurement instrument manufacturers requiring broadband linearity for calibration sources.
Lithium Niobate Modulator Market Vendor Landscape
Concentration sits with integrated photonics specialists and defense-aerospace contractors rather than discrete component distributors. The vendor base separates into three strategic tiers: European research-defense integrators with captive crystal growth, East Asian volume producers serving carrier network procurement, and North American datacenter-focused foundry partners. Dominant competitive moves include backward integration into thin-film process modules and strategic partnerships with semiconductor fabrication facilities.
Among European defense-research specialists, iXblue Group exemplifies the integrated crystal-to-module archetype. Japanese volume producers Fujitsu Optical Components Ltd and Sumitomo Osaka Cement Co., Ltd. occupy positions within the carrier network supply tier. Beijing Panwoo Integrated Optoelectronic Inc. represents the domestic Chinese compliance-focused segment. Lumentum Operations LLC anchors the North American datacenter interconnect vector with multi-material platform control.
| Leading Market Players |
|---|
| iXblue Group |
| Gooch & Housego plc |
| Fujitsu Optical Components Ltd |
| THORLABS |
| Lumentum Operations LLC |
| EOSPACE, Inc. |
| Beijing Panwoo Integrated Optoelectronic Inc. |
| Sumitomo Osaka Cement Co., Ltd. |
| Photline |
| Others |
Supply Flow & Price Mechanics
Thin-film lithium niobate wafer bonding is displacing bulk crystal growth as the dominant substrate preparation method, simultaneously shifting supply geography toward Japanese and French research institutes and compressing pricing premiums for electro-optic bandwidth performance. This process substitution redraws cost structures across modulator tiers as foundry utilization rates climb.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates hermetic-packaged aerospace specifications from datacenter interconnect volumes and laboratory-grade bulk devices. Certification grade under MIIT or FCC authorization schemes and volume scale from hyperscale direct procurement constitute the primary differentiation drivers. Pricing pressure stems from silicon photonics substitution in sub-100 Gbps applications, forcing lithium niobate vendors toward higher-format coherent links. Data service providers exhibit acute price sensitivity through consolidated foundry negotiations, while aerospace contractors absorb premiums for radiation-hard qualification.
Supply Chain Analysis
Port congestion along Shanghai-to-Long Beach trade lanes elevates inbound logistics costs for optical-grade lithium niobate ingots sourced from Chinese and Japanese crystal growth facilities. Supply concentrates in China, Japan, and France, drawing from Congoleum growth furnaces, ion slicing equipment, and sub-micron waveguide etching tools. Single-source vulnerability pervades thin-film process engineering talent pools. Distribution runs through transceiver OEM qualification programs for carrier networks and direct foundry relationships for hyperscale cloud operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as 800 Gbps coherent formats penetrate datacenter interconnects and national quantum communication backbones. Thin-film process maturation accelerates adoption beyond traditional telecom procurement boundaries.
For Market Incumbents: Fortify captive thin-film lithium niobate process modules through backward integration into ion slicing and wafer bonding capabilities. Secure multi-year supply agreements with Yangtze River Delta crystal growth facilities before MIIT domestic content mandates tighten further. METI-funded Japanese competitors threaten technology access for non-domestic vendors. For New Entrants and Emerging Players: Anchor in India's BharatNet Phase III domestic sourcing requirements through Cochin Special Economic Zone assembly partnerships. Quantum key distribution networks for China's national quantum communication backbone offer premium pricing tiers with limited incumbent saturation. Photonic integrated circuit foundry services at Tower Semiconductor and GlobalFoundries enable fabless entry without capital-intensive crystal growth investments. For Investors and Strategic Acquirers: Secondary-cycle assets sit with European defense-research specialists possessing integrated crystal-to-module capabilities and established foundry relationships. Five-to-ten year viability hinges on thin-film lithium niobate displacement of indium phosphide in coherent DSP architectures. Monitor which regulatory bloc first mandates energy efficiency thresholds for optical transceivers as the inflection signal for specification cascade across supply tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Thin-Film Process Module Addition | Semiconductor foundries at Tower Semiconductor and GlobalFoundries enable fabless modulator designers without crystal growth capital. |
| Domestic Content Joint Venture | Non-Chinese vendors partner with Beijing and Shanghai crystal growth facilities to satisfy MIIT certification traceability mandates. |
| Direct Foundry Relationship | Microsoft Azure and Amazon Web Services procurement teams disintermediate traditional transceiver vendors for 400 Gbps specifications. |
| Hermetic Packaging Redesign | EU RoHS lead-free soldering compliance adds certification cycles but preserves transatlantic market access for European vendors. |
| Quantum Communication Supply Agreement | China's national quantum backbone procures ultra-low noise modulators for entanglement-based cryptography at premium pricing tiers. |
Methodological Framework
Desk research of SEC filings from optical component vendors, MIIT certification databases, and METI photonics initiative disclosures preceded structured interviews with coherent transceiver design engineers, datacenter procurement officers, thin-film process specialists, and carrier network qualification managers. Primary fieldwork with iXblue Group, Fujitsu Optical Components, and Lumentum Operations supplemented secondary validation from patent filings and foundry utilization reports. Bottom-up volume modeling across product type and application segments triangulated against top-down market sizing from regional infrastructure deployment data.
Variance decomposition across electro-optic bandwidth requirements, thin-film yield rates, and hyperscale capex cycles drove analytical framework construction throughout the projection horizon. Segmentation dimensions encompassed product architecture, technology platform, end-user procurement channel, and geographic regulatory cluster. CAGRs derived from fitted adoption curves for 400 Gbps and 800 Gbps coherent formats, with cross-reference to cloud operator datacenter buildout announcements and submarine cable deployment schedules.
Material uncertainties — regulatory acceleration of energy efficiency mandates, breakthrough silicon photonics bandwidth extensions, and geopolitical restriction of thin-film process equipment exports — sit outside the modeled envelope. Forecasts reflect assumptions regarding continued electro-optic performance advantages over competing material platforms. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Laser Module Market
Optical Components
CVD Sic Ring Market
Optical Components
Optical Dome Market
Optical Components
Global Optical Measurement Market
Optical Components
Objective Lens Market
Optical Components
Italy Lithium Niobate Modulator Market
Optical Components
Silicon Photonics Market
Optical Components
Optical Cross Connect Market
Optical Components
Infrared Filter Market
Optical Components
Faraday Rotator Market
Optical Components
Polarizer Film Market
Optical Components
Low-E Glass Magnetron Sputtering Coating Line Market
Optical Components
Optical Instruments and Lenses Market
Optical Components
Optical Fiber Array Market
Optical Components
Fluorophore Market
Optical Components
North America Tunable Laser Market