
 Global Erectile Dysfunction Drugs Market | 2026-2036
Global Erectile Dysfunction Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Erectile Dysfunction Drugs Market Intelligence
The development of novel administration routes beyond standard oral tablets is rotating the market toward higher-value formulations with improved onset of action. Pfizer Inc. leverages its legacy brand strength from originator products. Eli Lilly and Company competes through extensive R&D in urology and related therapeutic areas, maintaining a strong pipeline. Viatris Inc. specializes in the high-volume generic segment, expanding access after key patent expirations.
Erectile dysfunction drugs are pharmaceutical agents designed to treat male impotence by enhancing physiological responses to sexual stimulation. The primary mechanism for most involves inhibiting the phosphodiesterase type 5 (PDE5) enzyme, which promotes vasodilation. Oral tablets remain the dominant administration route by volume, but injectable and topical options provide alternatives for specific patient needs. The PDE5 inhibitors drug type holds the largest share, while alprostadil formulations address a smaller segment of the patient population.
Market access is governed by stringent regulatory bodies such as the US FDA, the European Medicines Agency (EMA), and Japan's PMDA. These agencies mandate rigorous, multi-phase clinical trials to prove safety and efficacy before granting marketing authorization. The strategic decision for pharmaceutical companies now centers on navigating the complex pathway for over-the-counter status for established drugs versus investing in novel, first-in-class therapies.
Market Dynamics
The central structural force shaping the erectile dysfunction drugs market is the erosion of patent protection for blockbuster PDE5 inhibitors. This shift is bifurcating the market into a high-volume, price-sensitive generic segment and a high-value, innovation-focused branded segment.
Growth Catalysts
- Regulatory Reclassification:Deliberations by agencies like the UK's MHRA to switch certain PDE5 inhibitors to over-the-counter status are expanding patient access and normalizing treatment, removing the prescription barrier for consumers.
- Telehealth Expansion:The proliferation of digital health platforms and online pharmacies provides a discreet and convenient channel for patient consultations and drug dispensing, particularly appealing to younger demographics and those in remote areas.
- Demographic Aging:Increasing life expectancy and a growing elderly population in developed nations such as Japan and Germany are expanding the addressable patient base, as the prevalence of erectile dysfunction correlates strongly with age.
Market Restraints
- Cultural and Social Stigma:Persistent societal taboos and personal embarrassment surrounding erectile dysfunction in many cultures prevent men from seeking medical advice and treatment, limiting market penetration despite high prevalence.
- Counterfeit Drug Market:A vast and unregulated online market for counterfeit erectile dysfunction drugs poses significant health risks to consumers and diverts revenue from the legitimate pharmaceutical supply chain.
- Stringent Regulatory Hurdles:The high cost and long timelines associated with multi-phase clinical trials mandated by the US FDA and EMA for novel therapies create substantial barriers to entry for new molecular entities.
Strategic Opportunities
- Novel Administration Routes:Development of non-oral formulations such as topical gels, intraurethral suppositories, or fast-dissolving oral films offers differentiation and caters to patients with specific needs or aversions to pills.
- Emerging Market Penetration:A significant untapped patient population exists in large, developing economies like Brazil and India, where rising incomes and improving healthcare infrastructure create new growth frontiers.
- Digital Health Integration:Opportunities exist to bundle pharmaceutical treatments with digital coaching, diagnostics, and lifestyle management platforms to provide a more holistic and personalized approach to men's health.
Industry Challenges
- Brand Loyalty Erosion:Originator brands face the immense challenge of maintaining market share and pricing power against a flood of low-cost generic alternatives following patent expirations for foundational drugs like sildenafil.
- Navigating Advertising Regulations:Pharmaceutical companies must manage starkly different direct-to-consumer advertising rules, which are permissive in the United States but highly restrictive across most of Europe.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Erectile Dysfunction Drugs Market |
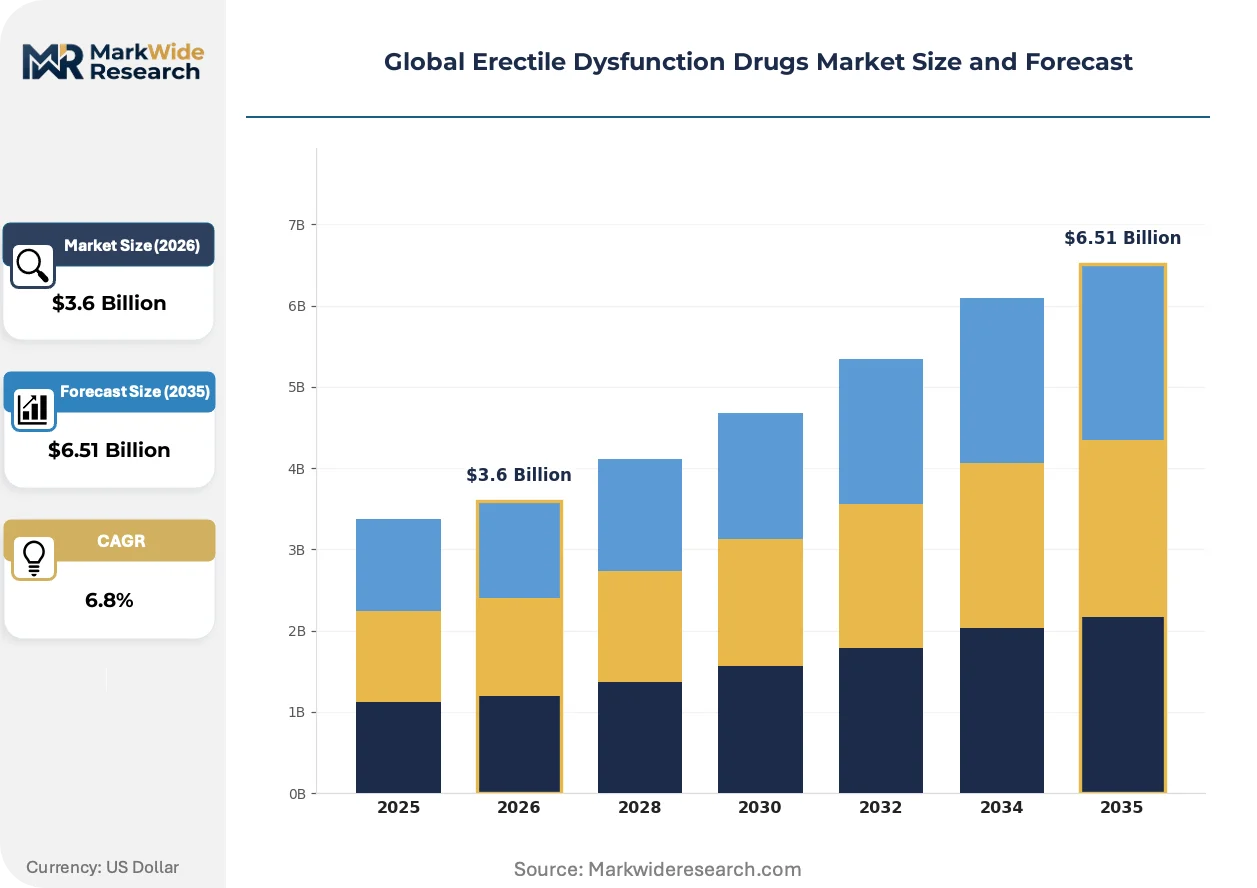
| Market Size in 2026 | $3.6 Billion |
| Market Size in 2035 | $6.51 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: PDE5 Inhibitors, Alprostadil, Testosterone Replacement, Herbal Supplements Administration Route: Oral, Injectable, Topical, Transurethral End User: Pharmacies, Hospitals, Clinics, Diagnostic Centers Product Form: Tablets, Capsules, Creams, Injections |
| Companies Covered | Viatris Inc., Sun Pharmaceutical Industries Ltd., Pfizer Inc., GSK plc, Sanofi, Eli Lilly and Company, Teva Pharmaceutical Industries Ltd., Lupin Limited, Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Erectile Dysfunction Drugs Market Strategic Shifts & Innovations
The market's evolution is defined by a push beyond traditional oral tablets toward more convenient formulations and a regulatory pivot toward broader consumer access. This movement reflects a deeper understanding of patient preferences for discretion, speed of action, and ease of use.
Novel drug delivery technologies provide alternatives for patients seeking improved pharmacokinetic profiles. These systems include fast-dissolving oral films, topical creams, and low-dose daily options designed for greater spontaneity. Patients who experience side effects from standard oral tablets or desire a faster onset of action are the primary adopters. This development is displacing the one-size-fits-all model of high-dose, on-demand oral pills, creating distinct value tiers based on formulation technology.
Regulatory bodies are increasingly considering the reclassification of established PDE5 inhibitors from prescription to over-the-counter (OTC) status. The United Kingdom's MHRA has already approved such a switch, setting a precedent for other national health authorities. This policy shift democratizes access but imposes new responsibilities on manufacturers for consumer education and safety monitoring. The oral tablet segment is most impacted, as companies retool their marketing from physician-detailing to direct-to-consumer branding.
Patient purchasing behavior is decisively moving toward digital channels for both consultation and fulfillment. The preference for telehealth platforms and online pharmacies bypasses the traditional, often cumbersome, process of in-person physician visits and trips to a physical pharmacy. This trend is most pronounced in markets with advanced digital infrastructure, such as the United States and South Korea, where convenience and privacy are highly valued by consumers.
Global Erectile Dysfunction Drugs Market Segmentation
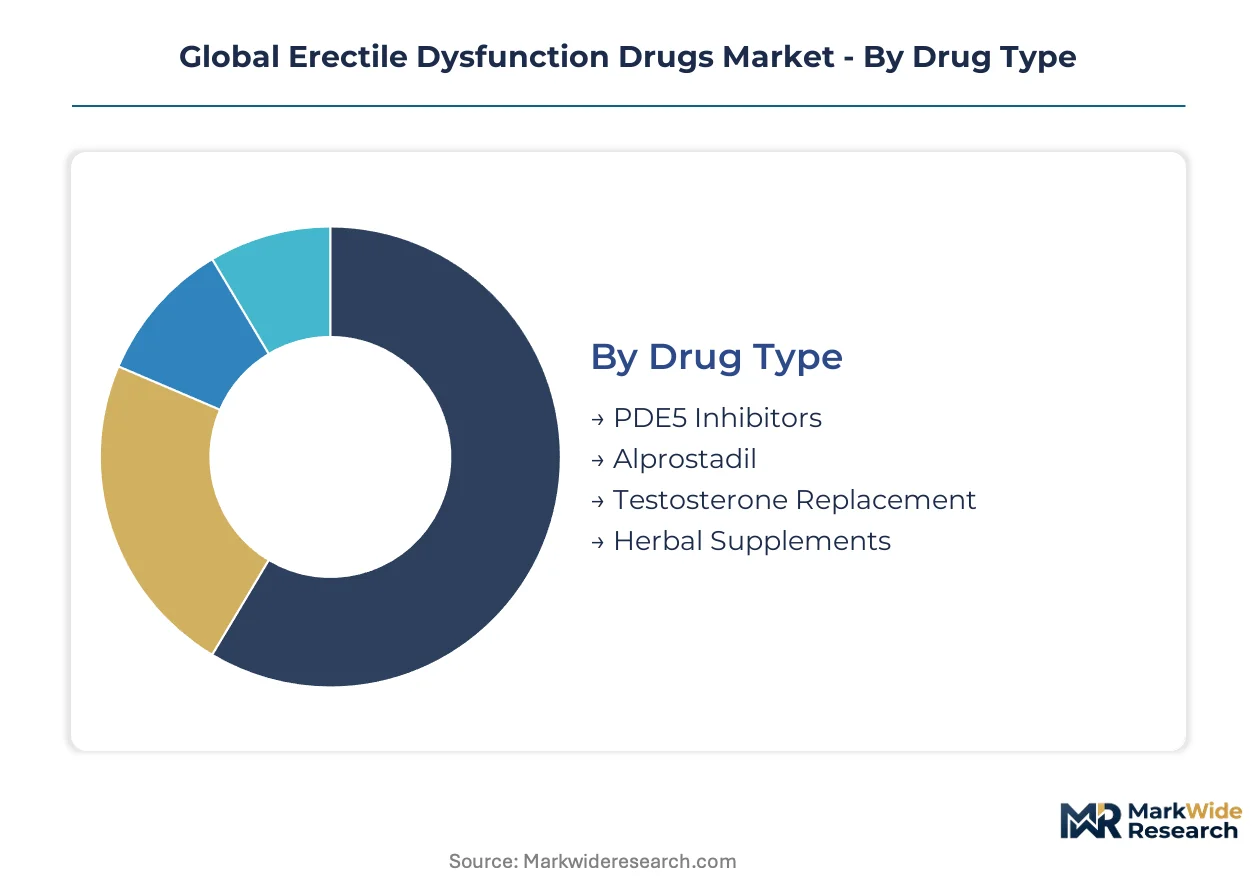
Market segmentation provides a granular view of the Global Erectile Dysfunction Drugs Market, highlighting distinct product offerings and distribution channels. This detailed breakdown helps pharmaceutical companies tailor their strategies to specific patient needs and regulatory environments. Understanding these segments is crucial for identifying areas of growth and competitive differentiation.
Drug Type:
Substitution pressure significantly influences the drug type segment, particularly with the rise of generic alternatives. Originator brands face intense competition from these lower-cost options, forcing innovation in new formulations. The market continues to evolve with pharmaceutical advancements.
- PDE5 Inhibitors:These drugs, including sildenafil and tadalafil, work by increasing blood flow to the penis during sexual stimulation. Demand concentrates heavily in the United States and key European markets, driven by established healthcare infrastructure and direct-to-consumer advertising.
- Alprostadil:This prostaglandin E1 analog induces vasodilation through a different mechanism, offering an alternative for patients unresponsive to PDE5 inhibitors. This formulation addresses a smaller segment of the patient population, often those with specific medical contraindications for oral therapies.
- Testosterone Replacement:This category addresses erectile dysfunction linked to low testosterone levels, available in various forms like gels or injections.
- Herbal Supplements:These non-prescription remedies often contain plant extracts and are sought by consumers preferring natural alternatives.
PDE5 Inhibitors anchors the volume base while Alprostadil gains share at the steepest rate.
Administration Route:
Volume concentration dictates the strategic focus within the administration route segment, with oral options dominating the market. However, patient preference for discretion and speed of action drives innovation in non-oral forms. Each route addresses distinct patient profiles.
- Oral:Standard oral tablets remain the dominant administration route by volume, favored for their convenience and widespread acceptance. This route is prevalent in markets like Japan and Germany due to established prescription patterns.
- Injectable:These formulations, typically self-administered into the penis, offer a rapid onset of action for patients seeking immediate effects. This option provides an alternative for individuals who cannot use or do not respond to oral medications.
- Topical:Creams or gels applied directly to the penis offer a non-invasive option, appealing to patients averse to pills or injections.
- Transurethral:This method involves inserting a small pellet into the urethra, delivering medication locally for targeted action.
Oral administration commands the largest market share, while injectable options demonstrate consistent growth.
End User:
The segmentation by customer type reveals varied purchasing behaviors and access points for erectile dysfunction drugs. Different end-user settings cater to distinct patient needs, from initial diagnosis to long-term treatment. Digital health platforms are reshaping patient engagement.
- Pharmacies:Retail and online pharmacies serve as primary dispensing points for prescribed and, increasingly, over-the-counter erectile dysfunction medications. Online pharmacies provide a discreet and convenient channel for patient consultations and drug dispensing in markets like the United States.
- Hospitals:These institutions are crucial for initial diagnosis, managing complex cases, and prescribing treatments, particularly for patients with underlying health conditions. Hospitals also play a role in educating patients on treatment options.
- Clinics:Specialized clinics, including urology and men's health centers, offer targeted consultations and treatment plans.
- Diagnostic Centers:These facilities primarily focus on identifying the underlying causes of erectile dysfunction, supporting treatment decisions.
Pharmacies represent the largest channel for drug distribution, with hospitals serving critical diagnostic and initial treatment roles.
Product Form:
Application diversity within the product form segment reflects ongoing efforts to improve patient adherence and treatment efficacy. Novel drug delivery technologies provide alternatives for patients seeking improved pharmacokinetic profiles. This diversification addresses specific patient preferences.
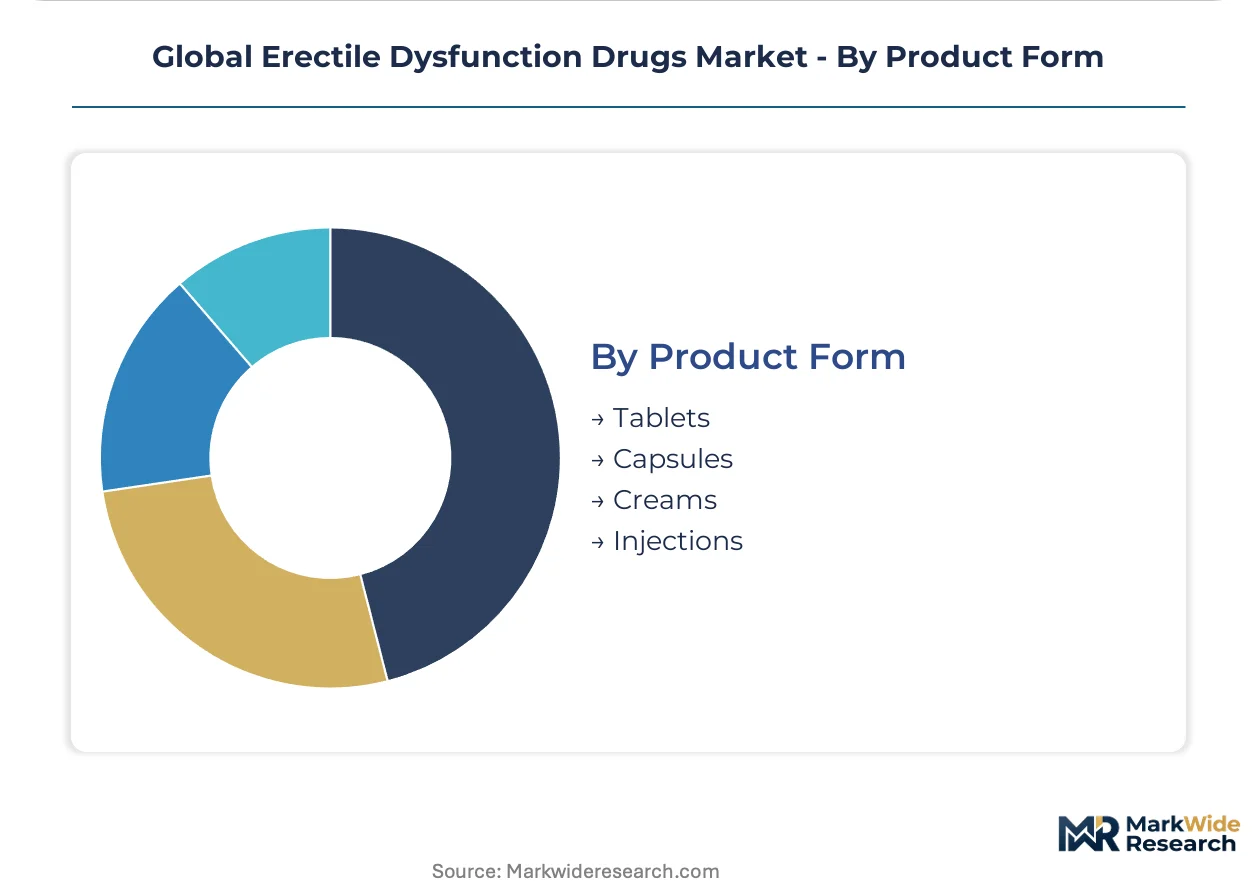
- Tablets:Oral tablets constitute the most common and widely used product form due to their ease of use and established efficacy. This form is central to regulatory reclassification efforts by agencies like the UK's MHRA.
- Injections:These forms offer direct and localized drug delivery, ensuring a quicker onset of action for patients requiring immediate results. Injections are often preferred by patients with specific medical conditions that limit oral absorption.
- Capsules:Similar to tablets, capsules provide an oral administration option, often used for specific drug formulations or extended-release variants.
- Creams:Topical creams offer a non-invasive, localized treatment option, appealing to patients seeking discretion and minimal systemic side effects.
Tablets dominate the product form landscape, while injections offer a compelling alternative for rapid action.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical products from established manufacturing hubs flow into diverse global markets, driven by specific regional demands and regulatory landscapes. The market for erectile dysfunction drugs shows distinct patterns of consumption and growth across key countries. These variations reflect differences in healthcare infrastructure, demographic trends, and cultural acceptance of treatment.
United States
Established healthcare infrastructure and widespread direct-to-consumer advertising drive significant demand for erectile dysfunction drugs. The US FDA mandates rigorous multi-phase clinical trials to prove safety and efficacy for new molecular entities. Pharmaceutical innovation clusters in Boston and the San Francisco Bay Area continue to develop novel drug delivery systems and therapies.
Germany
An aging population and a well-developed healthcare system contribute to consistent demand for erectile dysfunction treatments. The European Medicines Agency (EMA) oversees the stringent authorization process for drugs across the European Union. Major pharmaceutical companies in cities like Berlin and Frankfurt focus on both R&D and efficient distribution networks.
Japan
A rapidly aging demographic and increasing awareness of treatment options support market expansion, with a preference for discreet solutions. Japan's PMDA ensures the safety and quality of pharmaceutical products available to consumers. Tokyo and Osaka serve as crucial centers for pharmaceutical research, manufacturing, and strategic market access initiatives.
Brazil
Rising disposable incomes and improving healthcare infrastructure are opening new growth frontiers for erectile dysfunction drugs. ANVISA, the national health surveillance agency, regulates drug approvals and market entry within the country. São Paulo and Rio de Janeiro are primary hubs for pharmaceutical distribution and patient outreach campaigns.
India
A growing middle class and increasing health expenditure contribute to a significant untapped patient population. The CDSCO oversees drug manufacturing, clinical trials, and market authorization processes within the country. Pharmaceutical manufacturing clusters in Hyderabad and Ahmedabad support the robust supply of generic formulations.
Global Erectile Dysfunction Drugs Market Key Industry Players
Listed leaders compete with private specialists across therapeutic innovation and market access strategies. The market exhibits a bifurcated structure, with established branded products alongside a high-volume generic segment. This creates archetypes of innovation-driven pharmaceutical giants, generic powerhouses, and niche specialists. Companies pursue strategic partnerships for R&D and geographic expansion into emerging markets.
Within the innovation-driven segment, Pfizer Inc. and Eli Lilly and Company exemplify global pharmaceutical companies with strong R&D pipelines and legacy brand strength. Viatris Inc. occupies a significant position within the high-volume generic segment, expanding access after key patent expirations. These firms navigate patent expirations and regulatory shifts to maintain their market presence.
| Leading Market Players |
|---|
| Viatris Inc. |
| Sun Pharmaceutical Industries Ltd. |
| Pfizer Inc. |
| GSK plc |
| Sanofi |
| Eli Lilly and Company |
| Teva Pharmaceutical Industries Ltd. |
| Lupin Limited |
| Bayer AG |
| Others |
Cost & Logistics Intelligence
Long-term supply agreements for active pharmaceutical ingredients lock in both supply access and price visibility for manufacturers of erectile dysfunction drugs. This structural arrangement helps stabilize production costs amidst volatile raw material markets.
Pricing Analysis
The technology-generation pricing gap is stark between branded PDE5 inhibitors and their generic counterparts. Per-unit transactional pricing dominates the oral tablet segment, while novel formulations may command value-based premiums. Brand premium and the specific formulation technology drive price differentiation. Pricing softness stems from the proliferation of low-cost generic alternatives following patent expirations. Buyers of generic medications are highly price-sensitive, whereas patients seeking specific non-oral formulations show lower sensitivity.
Supply Chain Analysis
Inbound logistics costs, particularly for specialized active pharmaceutical ingredients (APIs), influence the final pricing of erectile dysfunction drugs. Geographic supply concentration for key APIs primarily centers in India and China, with some specialized production in the United States. The supply chain draws from critical inputs such as sildenafil citrate, tadalafil, and various excipients. Single-source vulnerability for specific APIs presents a structural supply chain risk. Distribution runs through a multi-channel model encompassing retail pharmacies, online pharmacies, and hospital procurement systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a fragmentation opportunity, driven by the demand-side shift toward discreet, convenient, and personalized treatment options. Niche segments are emerging around novel administration routes and digital health integration.
For Market Incumbents: Shield existing market share by investing in next-generation therapies and non-oral formulations. Counter the threat of generic erosion through strategic R&D in urology and related therapeutic areas, leveraging established brand strength. Expand direct-to-consumer advertising where regulatory frameworks permit, particularly for any potential OTC switches. For New Entrants and Emerging Players: Lead with innovative delivery mechanisms that address specific patient pain points, such as faster onset or reduced side effects. Target underpenetrated emerging markets like Brazil and India, where rising incomes create new growth frontiers. A go-to-market angle integrating telehealth platforms and discreet online dispensing can capture a significant patient base. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap specialists with strong pipelines in novel administration routes or those successfully navigating over-the-counter reclassification. Long-term viability within the next five to ten years hinges on differentiation beyond generic oral tablets. The signal to watch is the successful clinical trial completion and regulatory approval for first-in-class non-oral therapies.| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Novel Drug Delivery Systems | Develops high-value formulations with improved patient adherence and differentiated market positioning. |
| Expand Telehealth and Online Pharmacy Partnerships | Captures patient preference for discreet access and broadens market reach in digitally advanced regions. |
| Pursue Over-the-Counter Reclassification | Democratizes access for established drugs, expanding the addressable patient population significantly. |
| Penetrate Emerging Markets with Generic Portfolios | Leverages patent expirations to capture demand in regions with rising healthcare expenditure. |
| Integrate Digital Health Coaching Platforms | Offers holistic patient support, enhancing treatment efficacy and fostering brand loyalty beyond medication. |
Research Approach
Desk research of regulatory filings, clinical trial databases, and medical journals preceded structured interviews with drug development executives, regulatory affairs leads, and hospital procurement managers. This primary and secondary data combination enabled a comprehensive understanding of market dynamics. Bottom-up and top-down triangulation validated initial findings, ensuring robust data integrity.
Variance decomposition analysis informed the forecast framework across the analysis window. Segmentation dimensions modeled included drug type, administration route, end user, product form, and regional regulatory cluster. Compound Annual Growth Rates were derived from historical data trends and projected market shifts. Key industry-specific forecast inputs included patent expiration schedules and anticipated over-the-counter reclassification rates.
Forecasts assume regulatory continuity in regimes like the US FDA, EMA, and Japan's PMDA; material policy shifts would require re-modeling. The analysis reflects assumptions regarding clinical trial success rates and evolving healthcare reimbursement policies. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Liraglutide Market
Pharmaceuticals
Global Loperamide Hcl Market
Pharmaceuticals
Levothyroxine Sodium Market
Pharmaceuticals
Motilium Market
Pharmaceuticals
Atypical Antipsychotic Market
Pharmaceuticals
Global Pharmaceutical Traceability Market
Pharmaceuticals
Adrenocorticotropic Hormone [ACTH] Market
Pharmaceuticals
Global Novel Drug Delivery Systems (NDDS) Market
Pharmaceuticals
Adamantane Antiviral Drugs Market
Pharmaceuticals
Tenecteplase Drugs Market
Pharmaceuticals
Global Urothelial Cancer Drugs Market
Pharmaceuticals
Australia Pharmaceuticals Market
Pharmaceuticals
Hydroxypropyl Methylcellulose (HPMC) Capsules Market
Pharmaceuticals
US External Analgesics Market
Pharmaceuticals
Budesonide Market
Pharmaceuticals
Germany Pharmaceuticals Market