
 Global Novel Drug Delivery Systems (NDDS) Market | 2026-2036
Global Novel Drug Delivery Systems (NDDS) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Novel Drug Delivery Systems (NDDS) Market Foresight
Project finance partnerships between device developers and contract manufacturers is reshaping capital requirements for entrants in the NDDS space. Pfizer Inc. leverages its manufacturing scale to control supply of lipid nanoparticle formulations across multiple therapeutic areas. Novartis AG anchors its position through sustained R&D intensity in radioligand delivery systems. Becton Dickinson and Company specializes in injectable device engineering, occupying a narrow but defensible segment of the value chain.
Novel Drug Delivery Systems encompass engineered platforms that modulate pharmacokinetic profiles through controlled release, targeted tissue deposition, or enhanced bioavailability mechanisms, utilizing formulations with particle sizes typically below 200 nanometers for intracellular uptake. These systems serve the primary commercial purpose of extending product lifecycles, improving therapeutic indices, and enabling the delivery of biologics that would otherwise degrade in physiological environments. Liposomes and nanoparticles command the deepest margin pools due to formulation complexity and patent thickets, while microneedle patches represent the fastest-growing product type as patients and payers seek reduced clinic dependency. Oncology applications dominate current revenue, though autoimmune disorders are gaining share as subcutaneous biologic delivery expands.
The FDA enforces stringent chemistry, manufacturing, and controls standards for complex NDDS products, effectively filtering out undercapitalized entrants lacking bioequivalence demonstration capabilities. EMA's evolving guidelines on nanomedicine characterization and the EU MDR's enhanced clinical evidence requirements for combination products are simultaneously raising compliance costs and consolidating advantage among firms with established regulatory affairs infrastructure. Stakeholders must monitor how health technology assessment bodies in Germany and Japan calibrate reimbursement for delivery-mediated efficacy gains versus conventional administration routes.
Market Dynamics
Project finance partnerships between device developers and contract manufacturers is reshaping capital requirements for entrants in the NDDS space. Lipid nanoparticle formulation complexity and the FDA's chemistry, manufacturing, and controls standards are concentrating manufacturing capability among firms with validated bioequivalence infrastructure.
Growth Catalysts
- Subcutaneous biologic delivery:Autoimmune disorder patients in Germany and Japan are driving demand for self-administration platforms that reduce clinic dependency. This pull is expanding addressable populations beyond oncology.
- FDA accelerated approval pathways:Complex generic entrants leveraging 505(b)(2) submissions are compressing development timelines for delivery-mediated efficacy improvements. The pathway rewards firms with established regulatory affairs infrastructure.
- Nanoparticle engineering advances:Intracellular uptake mechanisms below 200 nanometers are enabling previously undeliverable biologics. Academic medical centers in the United States are expanding Phase III trial footprints for these platforms.
Market Restraints
- Specialized raw material concentration:High-purity lipids and synthetic polymers for lipid nanoparticle production concentrate among a handful of European and North American chemical suppliers. Input cost volatility constrains margin predictability for formulation developers.
- EMA nanomedicine characterization requirements:Evolving guidelines demand extensive physicochemical documentation that smaller entrants cannot generate. The compliance burden filters out undercapitalized competitors.
- Conventional intravenous administration:Established infusion infrastructure and clinician familiarity create inertia against novel delivery adoption in hospital settings. Switching costs include retraining and protocol rewriting.
Strategic Opportunities
- Microneedle patch platforms:Vaccine and hormone therapy applications in India present white space as domestic manufacturers seek reduced cold-chain dependency. Local production incentives align with patch stability advantages.
- Radioligand delivery systems:Theranostic convergence in Switzerland and the Netherlands is creating demand for precision-targeted radioisotope carriers. Regulatory frameworks for combination products are stabilizing in these jurisdictions.
- Home healthcare channel expansion:Direct-to-patient distribution models bypass traditional hospital pharmacy gatekeepers. Payers in Japan are piloting reimbursement for delivery systems that demonstrably reduce institutional costs.
Industry Challenges
- Formulation scientist scarcity:Lipid nanoparticle and liposome engineering requires hybrid expertise in colloid chemistry and pharmaceutical manufacturing. Talent pipelines from academic programs lag commercial demand in the United States and Germany.
- EU MDR clinical evidence requirements:Combination product reclassification demands additional trials that extend certification timelines by 18-36 months. Firms must front-load investment before revenue recognition.
- Patent thicket navigation:Dense intellectual property around PEGylation and surface modification technologies complicates freedom-to-operate analyses. Licensing negotiations consume executive bandwidth and delay program initiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Novel Drug Delivery Systems (NDDS) Market |
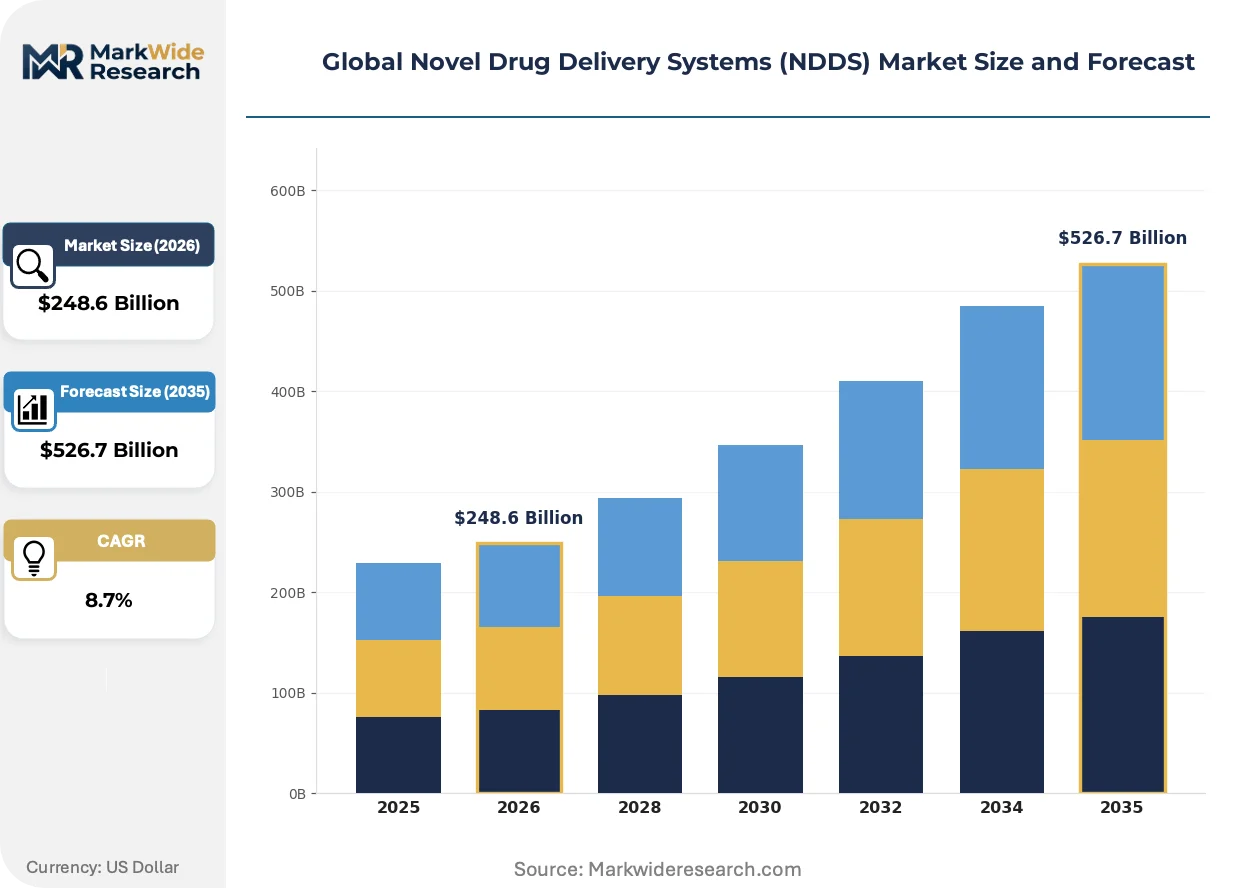
| Market Size in 2026 | $248.6 Billion |
| Market Size in 2035 | $526.7 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microneedle Patches, Liposomes, Nanoparticles, Implantable Pumps, Dendrimers Application: Oncology, Neurology, Infectious Diseases, Autoimmune Disorders, Cardiovascular Conditions End User: Pharmaceutical Manufacturers, Biotechnology Companies, Contract Research Organizations, Academic Institutes Delivery Technology: Transdermal, Inhalation, Oral, Injectable, Buccal |
| Companies Covered | Merck & Co., Inc., AstraZeneca PLC, Pfizer Inc., Sanofi S.A., Novartis AG, Johnson & Johnson, AbbVie Inc., Becton Dickinson and Company, F. Hoffmann-La Roche Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Novel Drug Delivery Systems (NDDS) Market Shifts & Advancements
In silico modeling and digital twin platforms are compressing formulation development cycles. These tools enable virtual screening of nanoparticle designs before bench-scale synthesis, reducing material waste and accelerating optimization loops.
Digital twin technology for nanoparticle formulation design is virtualizing traditional empiric development workflows. Large pharmaceutical manufacturers in the United States and Germany are deploying these platforms across multiple therapeutic programs simultaneously. The approach compresses lead optimization timelines and reduces physical prototype iterations by simulating biodistribution and release kinetics computationally.
EMA's evolving nanomedicine characterization guidelines and the EU MDR's enhanced clinical evidence requirements are elevating documentation burdens for combination products. Manufacturers must now submit extensive physicochemical stability data and real-world performance evidence. Smaller device developers are responding by partnering with established regulatory consultancies in Belgium and the Netherlands to navigate submission complexity.
Hospital procurement committees are unbundling delivery devices from drug contracts and evaluating them on standalone total-cost-of-ownership metrics. This shift disrupts traditional bundling strategies that masked device margins within pharmaceutical pricing. The pattern is most visible in German and Japanese academic medical centers, where pharmacy and therapeutics committees now mandate separate value demonstrations for administration technologies.
Global Novel Drug Delivery Systems (NDDS) Market Segmentation
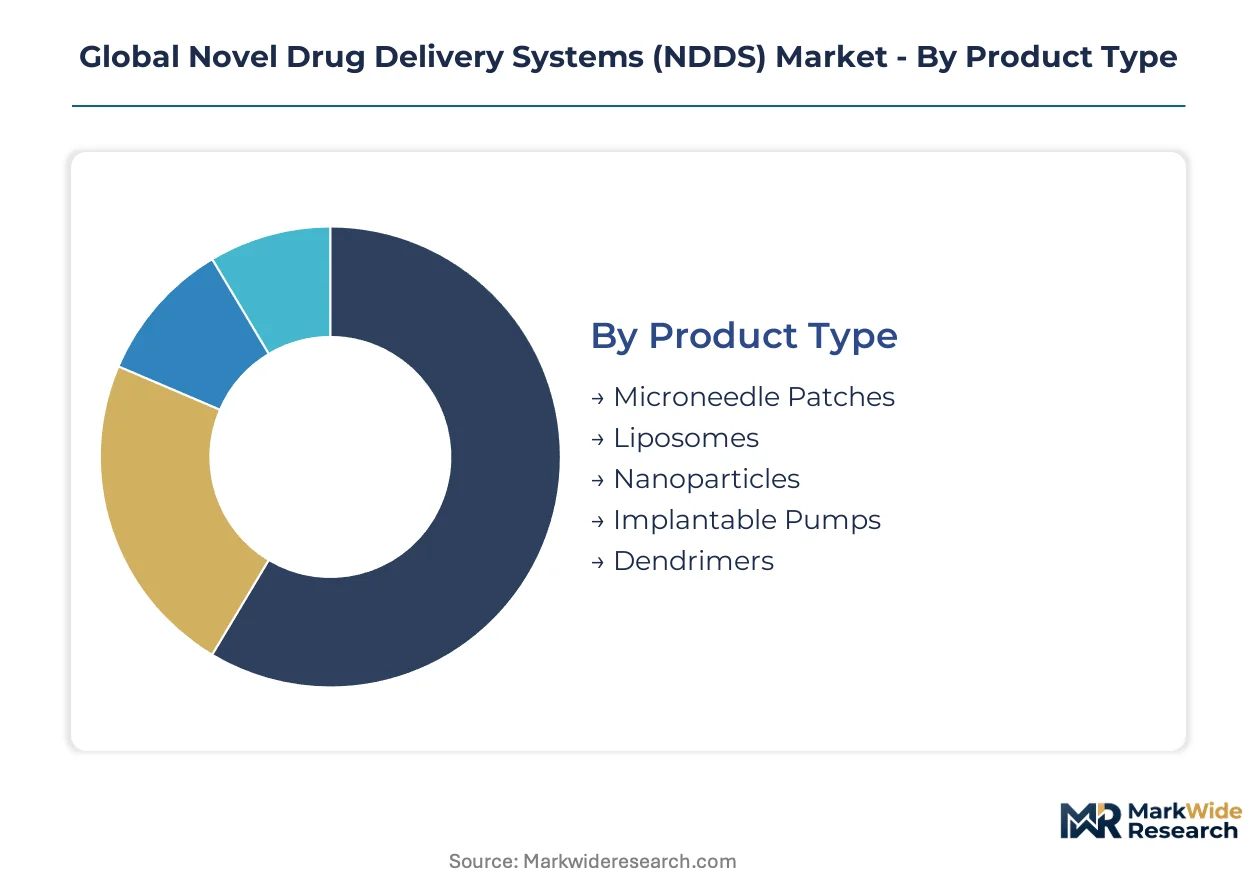
Novel Drug Delivery Systems fragment across multiple technical and commercial dimensions. Each segmentation axis reveals distinct margin structures, regulatory pathways, and competitive intensity patterns that shape strategic positioning.
Product Type:
Use-case spectrum spans chronic disease management to acute intervention, with formulation complexity determining barrier height and profit pool depth.
- Liposomes:Phospholipid bilayer vesicles encapsulate hydrophilic and hydrophobic payloads simultaneously. Demand concentrates in United States oncology centers seeking reduced systemic toxicity for chemotherapeutics, though EMA stability documentation requirements extend development timelines.
- Nanoparticles:Solid lipid or polymeric matrices below 200 nanometers enable intracellular uptake through endosomal pathways. Academic medical centers in Germany and Japan are expanding Phase III footprints for these platforms in autoimmune applications.
- Microneedle Patches:Dissolving or hydrogel-forming arrays penetrate stratum corneum without dermal nerve activation. Vaccine programs in India leverage patch stability to reduce cold-chain dependency.
- Implantable Pumps:Programmable reservoirs deliver continuous subcutaneous or intrathecal infusions. Long-acting hormonal and pain management protocols in Japanese home healthcare settings drive adoption.
- Dendrimers:Hyperbranched synthetic macromolecules with defined surface functionality for targeted ligand attachment. Early-stage CNS delivery programs in Swiss and Dutch research clusters explore blood-brain barrier penetration.
The dominant share belongs to liposomes, while microneedle patches are gaining share fastest.
Application:
Volume distribution tracks disease prevalence, reimbursement generosity, and the technical feasibility of delivery-mediated efficacy gains.
- Oncology:Cytotoxic payloads require tumor-selective deposition to widen therapeutic indices. United States academic medical centers anchor demand through participation in radioligand and nanoparticle trials.
- Autoimmune Disorders:Subcutaneous biologic delivery reduces clinic dependency for rheumatoid arthritis and multiple sclerosis patients. German and Japanese payers pilot reimbursement for self-administration platforms demonstrating institutional cost avoidance.
- Infectious Diseases:Vaccine adjuvant and antimicrobial delivery applications concentrate in outbreak-response funding cycles. Microneedle patch stability advantages attract Indian domestic manufacturing investment.
- Neurology:Blood-brain barrier penetration challenges limit current commercial penetration. Dendrimer and nanoparticle research programs in Netherlands and Switzerland target this white space.
- Cardiovascular Conditions:Sustained-release anticoagulant and antiarrhythmic formulations serve post-acute care transitions. Hospital pharmacy committees in Germany evaluate standalone device value separately from drug contracts.
Oncology commands the deepest revenue pool, though autoimmune disorders are climbing the fastest as subcutaneous biologics expand addressable populations.
End User:
Customer type determines procurement sophistication, regulatory burden allocation, and partnership structure preferences.
- Pharmaceutical Manufacturers:Integrated drug-device combination product developers internalize formulation and regulatory capabilities. Pfizer and Novartis maintain captive lipid nanoparticle supply chains across multiple therapeutic areas.
- Biotechnology Companies:Asset-focused developers outsource delivery platform engineering to access specialized colloid chemistry expertise. Project finance partnerships with contract manufacturers reshape capital requirements for this segment.
- Contract Research Organizations:Full-service providers integrate device development, bioequivalence studies, and regulatory submission preparation. Belgian and Netherlands-based consultancies navigate EMA nanomedicine characterization complexity for smaller clients.
- Academic Institutes:Research hospitals in United States, Germany, and Japan host the largest Phase III trial footprints for novel delivery mechanisms. Technology transfer offices negotiate licensing terms through dense PEGylation and surface modification patent thickets.
Pharmaceutical manufacturers retain the dominant procurement volume, while biotechnology companies are expanding most quickly through outsourced platform partnerships.
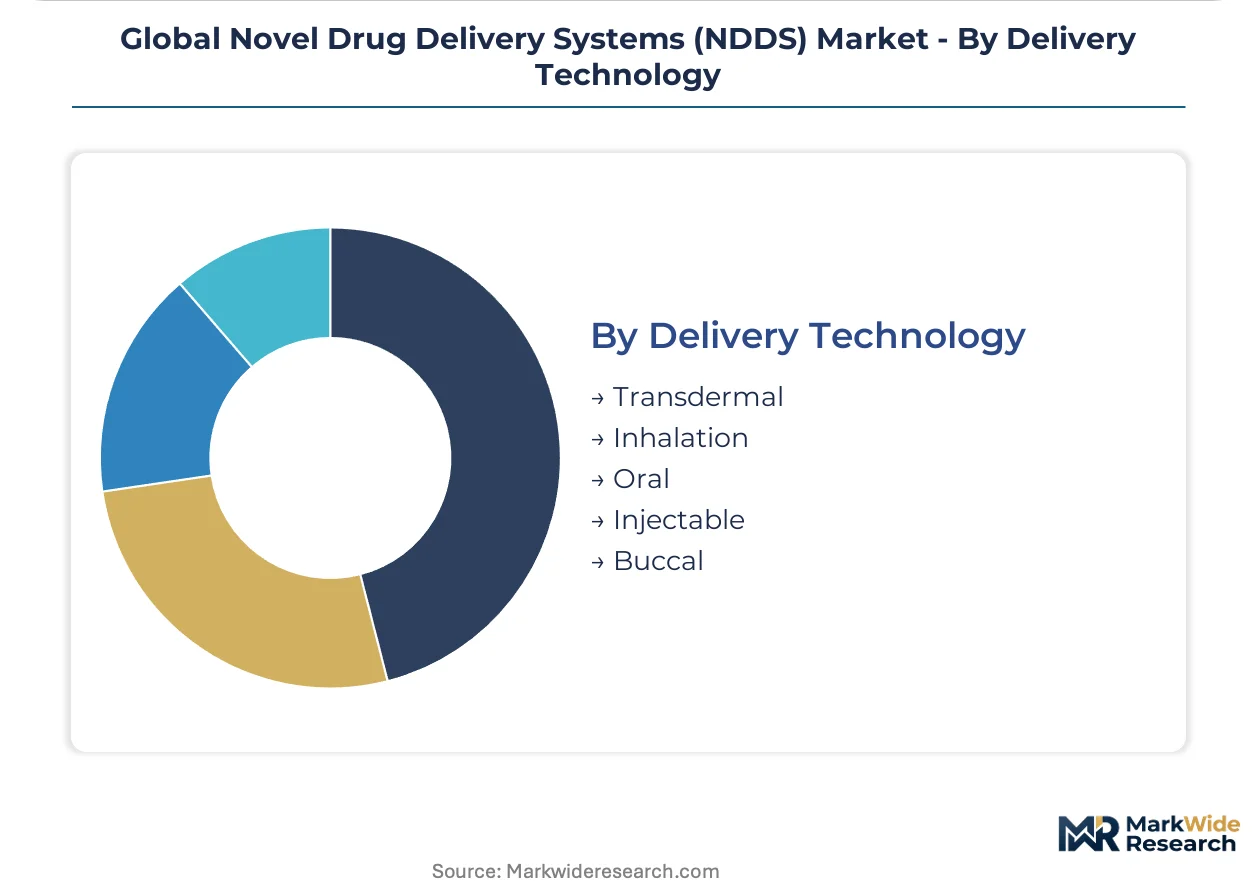
Delivery Technology:
Route selection balances patient convenience, payload protection requirements, and anatomical targeting precision.
- Injectable:Intravenous, subcutaneous, and intramuscular routes dominate biologic delivery. Lipid nanoparticle formulation complexity concentrates manufacturing capability among firms with validated FDA bioequivalence infrastructure.
- Transdermal:Passive diffusion and active microneedle systems serve hormone, vaccine, and pain management applications. Indian manufacturers seek reduced cold-chain dependency through patch-based distribution.
- Inhalation:Pulmonary deposition targets local respiratory disease and systemic absorption through alveolar capillary beds. Device engineering requirements occupy narrow but defensible value chain positions.
- Oral:Enteric coatings and permeation enhancers protect biologics from gastric degradation. Bioavailability improvements remain technically challenging for large molecules.
- Buccal:Mucosal absorption bypasses first-pass hepatic metabolism for rapid systemic uptake. Niche applications in emergency medicine and pediatric populations sustain limited commercial presence.
Injectable platforms command the dominant technology share, while transdermal systems are expanding most quickly through microneedle patch commercialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees and academic medical centers concentrate purchasing power in jurisdictions with established Phase III trial infrastructure. Payer sophistication and regulatory clarity determine where delivery-mediated efficacy gains command premium reimbursement. Manufacturing scale and formulation expertise cluster where FDA, EMA, and PMDA frameworks reward bioequivalence demonstration capabilities.
United States
FDA accelerated approval pathways attract complex generic entrants leveraging 505(b)(2) submissions for delivery-mediated improvements. The agency's chemistry, manufacturing, and controls standards filter out undercapitalized competitors lacking validated infrastructure. Academic medical centers in Boston and the San Francisco Bay Area host the largest Phase III trial footprints for nanoparticle-based oncology platforms.
Germany
Autoimmune disorder patients drive demand for subcutaneous biologic self-administration that reduces clinic dependency. EMA nanomedicine characterization guidelines and EU MDR clinical evidence requirements elevate compliance costs for combination products. The Rhine-Ruhr and Munich clusters concentrate lipid nanoparticle formulation expertise and regulatory consultancy capacity.
Japan
PMDA frameworks and METI industrial policy support home healthcare channel expansion with pilot reimbursement for institutional cost-avoiding delivery systems. Subcutaneous biologic delivery for rheumatoid arthritis and multiple sclerosis patients anchors demand growth. The Kanto region around Tokyo concentrates implantable pump engineering and direct-to-patient distribution infrastructure.
India
Vaccine and hormone therapy applications pull microneedle patch adoption as domestic manufacturers seek reduced cold-chain dependency. CDSCO regulatory pathways for novel delivery mechanisms remain less prescriptive than FDA or EMA equivalents. Manufacturing investment concentrates in Maharashtra and Gujarat, where local production incentives align with patch stability advantages for tropical distribution.
Switzerland
Theranostic convergence creates demand for precision-targeted radioisotope carriers in radioligand delivery systems. Swissmedic frameworks for combination products have stabilized, attracting R&D investment from firms navigating EMA complexity elsewhere. The Basel and Zurich research clusters anchor early-stage dendrimer programs targeting blood-brain barrier penetration for CNS delivery.
Global Novel Drug Delivery Systems (NDDS) Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where manufacturing scale and regulatory infrastructure determine tier membership. Large integrated pharmaceutical manufacturers maintain captive lipid nanoparticle supply chains and internalized bioequivalence capabilities. Strategic archetypes include platform technology licensors, contract manufacturing organizations with validated facilities, and device engineering specialists occupying narrow value chain positions. Competitive moves concentrate on strategic partnerships for project finance and technology licensing to navigate patent thickets around PEGylation and surface modification.
Among scale-driven integrated manufacturers, Pfizer Inc. and Novartis AG exemplify archetypes combining manufacturing breadth with therapeutic-area diversification. Becton Dickinson and Company occupies a specialist position in injectable device engineering. These three entities represent distinct competitive approaches: captive supply chain control, sustained R&D intensity in targeted delivery modalities, and narrow but defensible segment focus respectively.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| AstraZeneca PLC |
| Pfizer Inc. |
| Sanofi S.A. |
| Novartis AG |
| Johnson & Johnson |
| AbbVie Inc. |
| Becton Dickinson and Company |
| F. Hoffmann-La Roche Ltd. |
| Others |
Supply & Pricing Matrix
High-purity lipid suppliers in Germany and Switzerland anchor upstream concentration for lipid nanoparticle formulations, directing margin pools toward formulation developers with validated FDA bioequivalence infrastructure and captive manufacturing scale.
Pricing Analysis
Certification level creates the primary spread, with FDA-validated lipid nanoparticle formulations commanding premium positioning over standard-grade liposomal products. Pricing stratifies across premium validated-manufacturing, standard contract-manufactured, and economy research-grade tiers. Cost compression in standard-grade segments is intensifying because CDSCO-aligned Indian manufacturers are expanding microneedle patch capacity with local production incentives. Hospital procurement committees show lowest price sensitivity for oncology applications requiring intracellular uptake mechanisms, while vaccine adjuvant developers exhibit highest sensitivity due to outbreak-response funding cycles.
Supply Chain Analysis
High-purity phospholipids and synthetic polymers feed from specialized chemical manufacturers in Germany, Switzerland, and the United States. Formulation development draws from European lipid suppliers, North American polymer specialists, and Indian excipient producers. Single-source vulnerability concentrates in validated lipid nanoparticle manufacturing capacity, where FDA chemistry, manufacturing, and controls standards filter out secondary suppliers. Distribution runs through pharmaceutical manufacturers with captive supply chains, biotechnology companies outsourcing to contract manufacturers, and academic medical centers procuring through GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA accelerated approval pathways for complex generics represent a regulatory inflection compressing development timelines, positioning the NDDS market for high-growth disruption as delivery-mediated efficacy gains command expanded reimbursement.
For Market Incumbents: Build regulatory affairs infrastructure moats by internalizing bioequivalence demonstration capabilities and expanding validated lipid nanoparticle manufacturing footprints in Germany and the United States. Consolidation moves should target contract manufacturing organizations with FDA-approved facilities to preempt 505(b)(2) entrants from securing capacity. Channel control through direct-to-patient distribution partnerships in Japan reinforces institutional cost-avoidance narratives that secure payer reimbursement. For New Entrants and Emerging Players: Build out microneedle patch platforms for vaccine and hormone therapy applications in India, where CDSCO pathways remain less prescriptive and local production incentives align with reduced cold-chain dependency. Radioligand delivery systems for theranostic convergence in Switzerland and the Netherlands present additional white space. A go-to-market angle targeting domestic Indian manufacturers seeking tropical distribution stability bypasses established European and North American formulation incumbents. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed contract manufacturing organizations possessing validated lipid nanoparticle facilities but lacking therapeutic-area diversification. Long-term viability hinges on regulatory infrastructure durability rather than single-product pipelines. The signal to watch is EMA nanomedicine characterization guideline finalization, which will either consolidate advantage among established players or create acquisition opportunities from compliance-driven distress.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA 505(b)(2) submissions compress timelines for delivery-mediated efficacy improvements. |
| Manufacturing Scale-Up | Validated lipid nanoparticle capacity expansion in Germany secures supply chain control. |
| Strategic Partnership | Project finance partnerships with contract manufacturers reshape capital requirements for biotechnology entrants. |
| Geographic Expansion | Direct-to-patient distribution in Japan bypasses hospital pharmacy gatekeepers for home healthcare. |
| Reimbursement Strategy | Payer pilot programs for institutional cost-avoiding delivery systems anchor premium pricing. |
Research Methodology
Operator-level perspectives from regulatory affairs leads, formulation scientists, hospital procurement managers, and payer access specialists anchored the qualitative base for this study. Primary interviews combined with secondary validation from FDA filings, EMA submission databases, ClinicalTrials.gov records, and hospital procurement contracts. Bottom-up patient population modeling and top-down pharmaceutical manufacturer revenue triangulation converged on segment-level estimates.
Scenario-bracketing around regulatory pathway acceleration and raw material cost volatility shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include delivery technology, application area, end-user type, and regional regulatory cluster. CAGRs were derived from therapeutic-area expansion curves and reimbursement elasticity assumptions, with nanoparticle engineering advances and subcutaneous biologic delivery penetration serving as key forecast inputs.
Stress conditions across EMA guideline stringency, lipid input cost volatility, and FDA approval pathway access were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory infrastructure durability and payer reimbursement evolution. Cross-checking against CMS Medicare reimbursement data and Japanese METI industrial policy filings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Estonia Pharmaceutical Market
Pharmaceuticals
Opium Tincture Market
Pharmaceuticals
Indobufen API Market
Pharmaceuticals
Alirocumab Market
Pharmaceuticals
Asia-Pacific Contraceptives Market
Pharmaceuticals
Global Liraglutide Market
Pharmaceuticals
Global Pediatric Drugs Market
Pharmaceuticals
Global Oxytocic Pharmaceuticals Market
Pharmaceuticals
Intranasal Corticosteroids Market
Pharmaceuticals
Nasal Antihistamines Market
Pharmaceuticals
Cough and Cold Preparations Market
Pharmaceuticals
Asia-Pacific Fatty Bases for Suppositories Market
Pharmaceuticals
Global Loperamide Hcl Market
Pharmaceuticals
Endocarditis Drugs Market
Pharmaceuticals
Celiac Disease Drugs Market
Pharmaceuticals
Leuprolide Acetate Market