
 Germany Pharmaceuticals Market | 2026-2036
Germany Pharmaceuticals Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Pharmaceuticals Market Intelligence
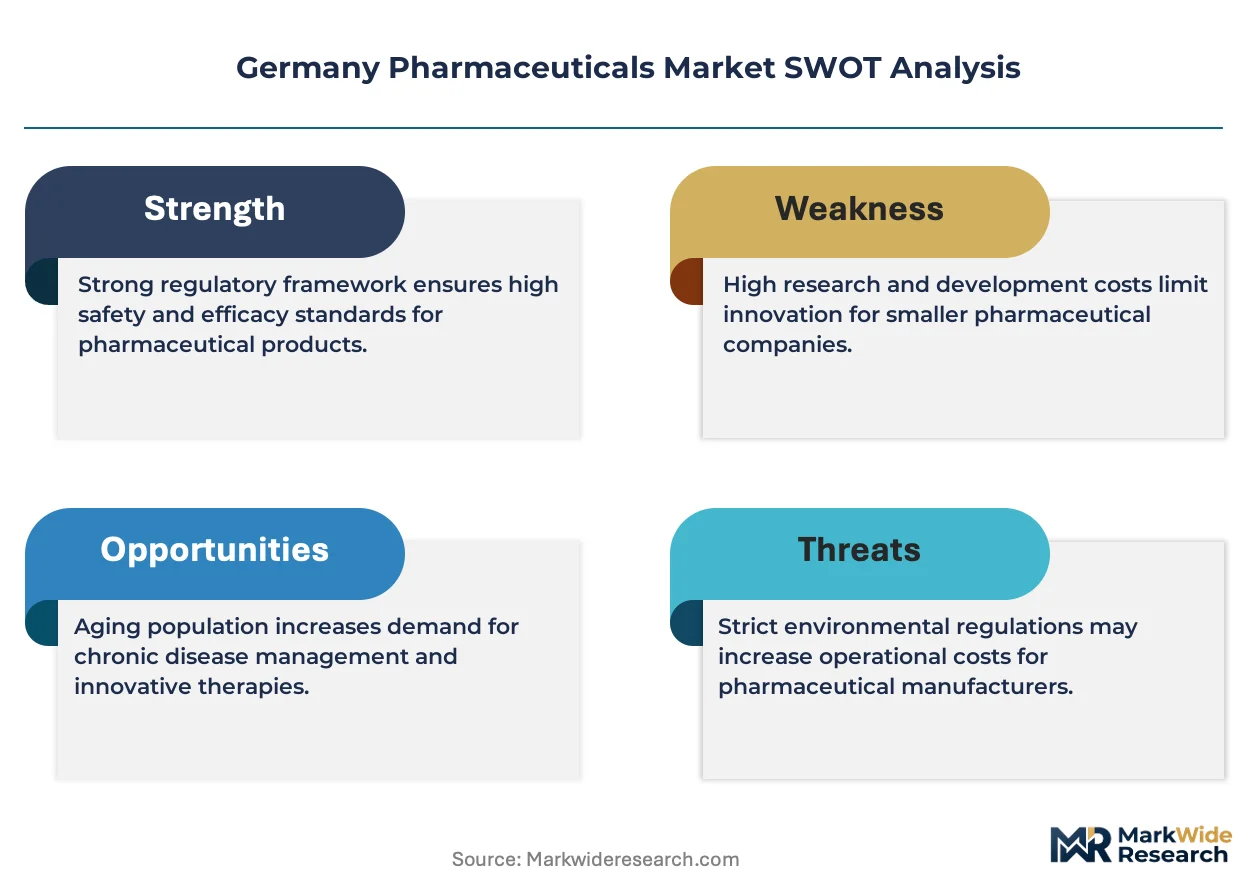
EU Good Manufacturing Practice certification is collapsing the supplier base for sterile injectable production, forcing mid-scale API manufacturers toward costly facility upgrades or contract exit. Bayer AG sustains vertical integration across small-molecule and radiopharmaceutical supply chains, while BioNTech SE dominates mRNA manufacturing capacity in the Rhine-Main biotech corridor. Boehringer Ingelheim anchors respiratory and metabolic therapy production through its Ingelheim headquarters complex, competing with Merck KGaA for specialized biologics fermentation scale.
Germany pharmaceuticals encompass chemically synthesized and biologically produced medicinal products formulated for disease prevention, diagnosis, or treatment, with active pharmaceutical ingredients typically requiring purity thresholds above 99.5% and stability validation across defined temperature bands. The sector serves acute hospital care, chronic disease management, and preventive vaccination programs through dosage forms ranging from lyophilized powders to lipid nanoparticle suspensions. Prescription drugs command the dominant value share as AMNOG price negotiations compress first-year margins, while biologics represent the fastest-expanding category driven by biosimilar substitution policies and oncology pipeline concentration. Injectable delivery modes capture disproportionate investment as homecare infusion protocols expand, though oral formulations retain volume leadership in cardiovascular and neurology maintenance therapies.
Germany's Federal Joint Committee (G-BA) and the Paul-Ehrlich-Institut govern market access through benefit assessment protocols and batch-release certification for biologics, creating dual regulatory gates that extend commercialization timelines. The EU Medical Device Regulation and German Medicines Act impose traceability mandates that reshape packaging investment and serialization infrastructure across domestic distribution networks. Stakeholders must monitor AMNOG reform negotiations and the EU pharmaceutical strategy's impact on Germany's reference pricing dominance to anticipate margin structure shifts.
Market Dynamics
AMNOG's early benefit assessment is restructuring Germany's pharmaceutical reimbursement landscape, forcing manufacturers to front-load clinical evidence generation and compressing first-year pricing power across innovative drug categories.
Growth Catalysts
- AMNOG pathway acceleration:The Federal Joint Committee's expedited assessment protocols for breakthrough therapies are shortening time-to-reimbursement for oncology biologics, incentivizing pipeline prioritization toward hematology and immuno-oncology assets.
- Biosimilar substitution mandates:Germany's automatic pharmacy substitution rules for approved biosimilars are expanding volume capture for domestic fermentation capacity, redirecting procurement toward Baden-Württemberg manufacturing clusters.
- Radiopharmaceutical infrastructure:Cyclotron network expansion across university hospital hubs is enabling same-day isotope production for diagnostic imaging, anchoring investment in Bavaria and North Rhine-Westphalia.
Market Restraints
- API supply concentration:Sterile injectable active pharmaceutical ingredient production is consolidating among EU Good Manufacturing Practice-certified facilities in Ireland and Italy, exposing German formulators to single-source risk for cytotoxic compounds.
- Reference pricing compression:The German reference pricing system for off-patent small molecules caps reimbursement at the third-lowest EU comparator price, eroding margin buffers for mature cardiovascular and neurology portfolios.
- Heating and cooling energy costs:Biologics fermentation and lyophilization processes face input cost volatility from natural gas price exposure, disproportionately impacting mid-scale contract manufacturing organizations without captive renewable generation.
Strategic Opportunities
- Homecare infusion protocols:Hospital-at-home reimbursement expansions by German statutory health insurers are creating demand for prefilled syringe and wearable injector formats, opening channel access beyond acute care purchasing.
- mRNA platform diversification:Lipid nanoparticle formulation expertise accumulated during COVID-19 vaccine production is transferable to personalized neoantigen therapies and rare disease protein replacement programs.
- Green chemistry incentives:The EU Green Deal's pharmaceutical sector sustainability mandates are rewarding solvent recycling investments and continuous flow manufacturing adoption with accelerated regulatory review pathways.
Industry Challenges
- Qualified personnel scarcity:Bioprocess engineering and regulatory affairs functions face recruitment bottlenecks as Rhine-Main and Munich biotech clusters compete for finite German university pipeline output.
- Serialization infrastructure retrofit:EU Medical Device Regulation traceability mandates require packaging line overhauls for combination products, straining capital allocation at mid-tier generic manufacturers.
- AMNOG evidence generation costs:Head-to-head comparator trials demanded by the Federal Joint Committee for novel therapeutic classes are extending development timelines and inflating Phase III program expenditures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Pharmaceuticals Market |
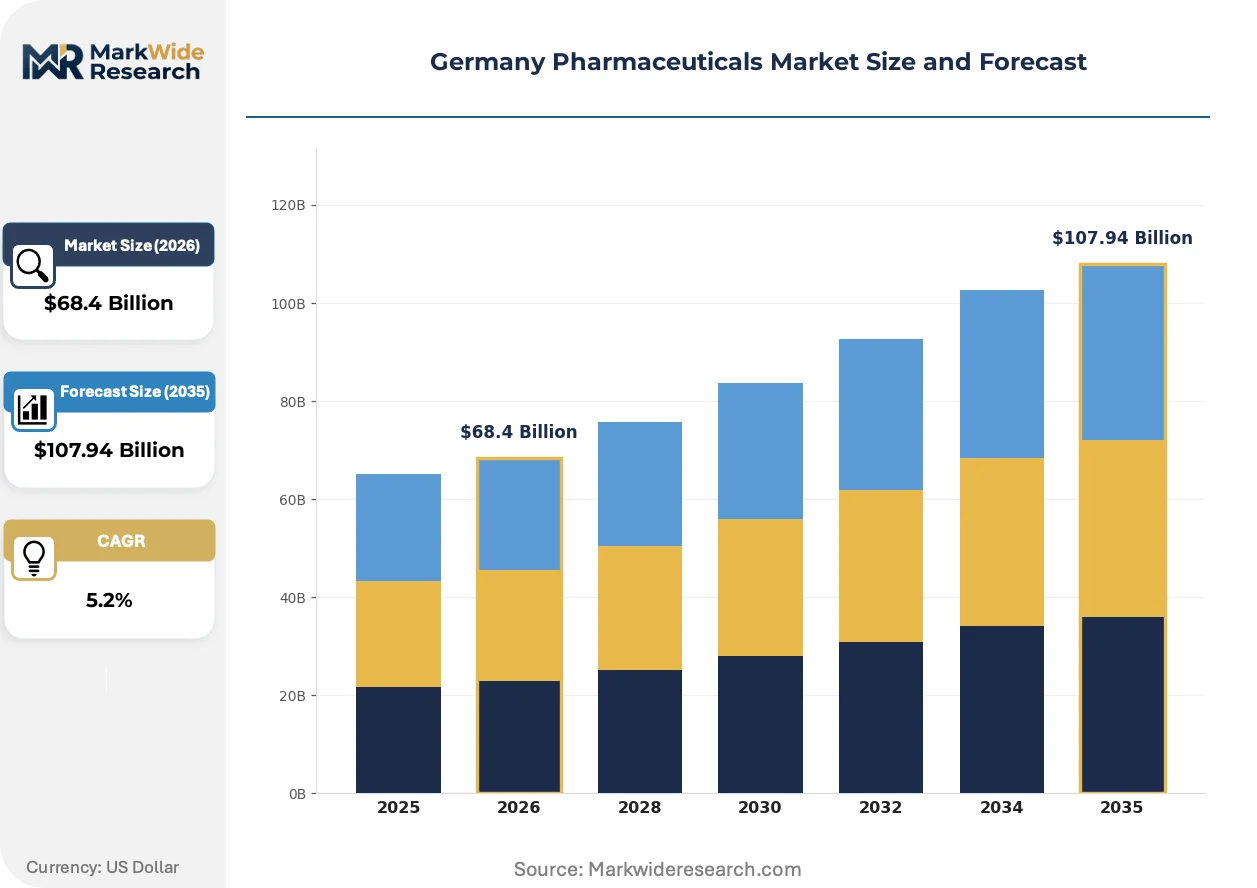
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $107.94 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Drugs, Over-the-Counter Medications, Biologics, Injectables Therapy Area: Oncology, Cardiovascular, Neurology, Infectious Diseases End User: Hospitals, Pharmacies, Clinics, Homecare Delivery Mode: Oral, Injectable, Transdermal, Inhalation |
| Companies Covered | Bayer AG, Boehringer Ingelheim, Merck KGaA, Fresenius Kabi AG, STADA Arzneimittel AG, B. Braun, Sanofi, AbbVie Inc., BioNTech SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Pharmaceuticals Market Strategic Shifts & Innovations
Continuous manufacturing technologies and modular facility designs are displacing batch processing paradigms, while regulatory convergence around real-world evidence is reshaping post-market commitment structures across German pharmaceutical development.
Continuous flow reactor technology is decomposing traditional batch API synthesis by enabling real-time quality monitoring and reduced solvent volumes. Bayer AG and Boehringer Ingelheim are retrofitting small-molecule facilities in Leverkusen and Ingelheim with skid-mounted reaction modules. This technology is decomposing capital intensity barriers for niche generic production, allowing mid-scale entrants to compete on cost with legacy volume players.
The EU Medical Device Regulation's 2021 implementation is forcing reclassification of drug-device combination products, triggering supplemental clinical data requirements for pre-filled pen injectors and inhalation systems. German notified bodies are experiencing backlog congestion, delaying market access for respiratory and diabetes portfolios. Manufacturers are responding by segregating device development timelines from drug approval pathways to reduce portfolio risk.
Hospital procurement consortia are consolidating purchasing power through regional tendering alliances, compressing supplier bases for standard infusion therapies and parenteral nutrition. The Rhineland and Berlin-Brandenburg hospital networks have established multi-year framework agreements that lock in volume commitments in exchange for price step-downs. This concentration is most visible in oncology supportive care, where three buying groups now control majority access for granulocyte colony-stimulating factors.
Germany Pharmaceuticals Market Segmentation
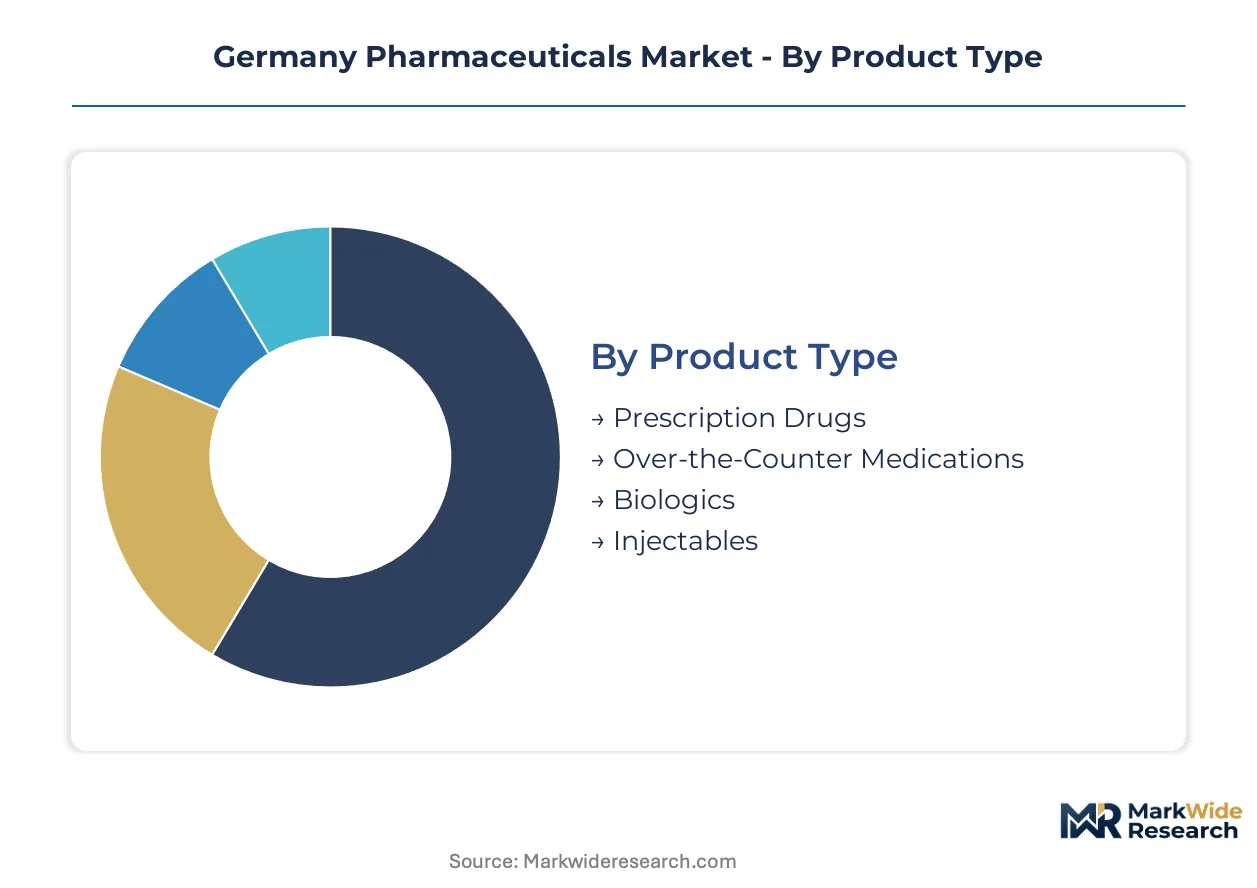
Germany's AMNOG reimbursement architecture creates divergent margin profiles across product categories, with early benefit assessment outcomes determining which segments warrant continued pipeline investment. Therapy area concentration in university hospital clusters further fragments demand patterns, requiring manufacturers to align formulation strategies with regional procurement consortia.
Product Type:
The Paul-Ehrlich-Institut's batch-release certification requirements impose steepest compliance burdens on biologics and sterile injectables, creating regulatory moats that reshape competitive entry economics.
- Prescription Drugs:Small-molecule formulations dominate statutory health insurance reimbursement volumes, with AMNOG price negotiations compressing first-year margins to reference-price benchmarks. Hospital procurement consortia in North Rhine-Westphalia and Bavaria concentrate demand for oncology and cardiovascular maintenance therapies, locking suppliers into multi-year framework agreements with annual step-down clauses.
- Biologics:Recombinant proteins and monoclonal antibodies require cold-chain distribution validated across 2-8°C bands, with Baden-Württemberg's specialized fermentation capacity capturing biosimilar substitution volumes. The Federal Joint Committee's expedited assessment pathways for breakthrough hematology therapies are redirecting pipeline prioritization toward mRNA and cell-based platforms.
- Over-the-Counter Medications:Pharmacy channel distribution bypasses AMNOG assessment entirely, with pricing freedom concentrated in analgesic and respiratory self-care categories.
- Injectables:Sterile fill-finish capacity constraints favor lyophilized and prefilled syringe formats, with homecare infusion protocols expanding reimbursement beyond acute care settings.
Prescription drugs handle the majority of throughput; biologics is the fastest mover on share.
Therapy Area:
Clinical trial density concentrates in southern German university hospital clusters, with Bavaria and Baden-Württemberg anchoring investigator-initiated studies that shape G-BA benefit assessments.
- Oncology:Immuno-oncology and targeted kinase inhibitors command premium reimbursement through AMNOG's early benefit assessment, with hematology indications receiving expedited Federal Joint Committee review. The Rhine-Main biotech corridor concentrates CAR-T manufacturing investment, while radiopharmaceutical cyclotron networks in Munich and Cologne enable same-day isotope production for diagnostic imaging.
- Cardiovascular:Anticoagulant and heart failure portfolios face reference pricing compression as generics penetrate the third-lowest EU comparator threshold, eroding margin buffers for mature small-molecule assets.
- Neurology:Multiple sclerosis and migraine prevention therapies drive biologics adoption, with subcutaneous formulations capturing homecare reimbursement expansions.
- Infectious Diseases:Antimicrobial stewardship programs in Berlin-Brandenburg hospital networks restrict broad-spectrum prescribing, favoring narrow-spectrum and combination therapies with demonstrated resistance profiles.
Oncology captures the steepest pricing premiums; neurology is expanding most quickly on volume.
End User:
Procurement concentration varies sharply across the care continuum, with hospital consortia wielding tender-based volume commitments against pharmacy substitution mandates.
- Hospitals:University hospital clusters in Heidelberg, Munich, and Berlin anchor specialized biologics consumption, with regional tendering alliances in the Rhineland consolidating purchasing power for standard infusion therapies. G-BA benefit assessments determine formulary inclusion before AMNOG price negotiations lock in reimbursement levels.
- Pharmacies:Automatic biosimilar substitution rules redirect dispensing toward domestic fermentation capacity, with Baden-Württemberg manufacturing clusters capturing volume shifts from originator biologics.
- Clinics:Outpatient oncology and dialysis centers concentrate injectable demand, with same-day administration protocols favoring prefilled formats over compounding.
- Homecare:Statutory health insurer reimbursement expansions for hospital-at-home protocols are creating channel access for wearable injectors and ambulatory infusion pumps, bypassing acute care purchasing committees.
Hospitals dominate biologics throughput; homecare is gaining share fastest on reimbursement expansion.
Delivery Mode:
Patient administration setting determines formulation investment priorities, with self-injection protocols requiring device combination product pathways under EU Medical Device Regulation.
- Injectable:Prefilled syringes and autoinjector systems capture homecare reimbursement growth, with lipid nanoparticle formulations requiring specialized fill-finish capacity in the Rhine-Main corridor. Lyophilization processes face energy cost volatility from natural gas exposure, disadvantaging mid-scale contract manufacturers without captive renewable generation.
- Oral:Modified-release and fixed-dose combination formats retain volume leadership in cardiovascular and neurology maintenance, with continuous manufacturing retrofits reducing solvent volumes and batch release timelines.
- Transdermal:Patch formulations for pain and hormone replacement bypass first-pass metabolism, with adhesion and residue standards governed by German Medicines Act quality specifications.
- Inhalation:Dry powder and metered-dose devices face reclassification under EU Medical Device Regulation, triggering supplemental clinical data requirements that delay market access for respiratory portfolios.
Oral formulations handle the largest prescription volumes; injectable formats are climbing the fastest on biologics expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's AMNOG early benefit assessment framework creates divergent regional investment patterns, with federal states competing to anchor biopharma manufacturing through specialized infrastructure incentives and university hospital density.
Bavaria
Munich and Erlangen concentrate CAR-T manufacturing investment alongside radiopharmaceutical cyclotron networks enabling same-day isotope production. The Bavarian Ministry of Economic Affairs funds bioprocess engineering centers through its Hightech Agenda. Roche Diagnostics anchors companion diagnostic development in Penzberg, feeding precision oncology pipelines across southern Germany.
North Rhine-Westphalia
Cologne and Düsseldorf host radiopharmaceutical production hubs serving diagnostic imaging demand from the Rhineland hospital consortium. The state biotechnology cluster initiative supports continuous manufacturing retrofits for small-molecule API synthesis. Bayer AG maintains its Leverkusen headquarters complex as a vertical integration anchor for pharmaceutical and consumer health portfolios.
Baden-Württemberg
Heidelberg and Tübingen university hospital clusters anchor investigator-initiated trials shaping G-BA benefit assessments for hematology therapies. The state's BioRegio STERN initiative funds fermentation capacity expansion for biosimilar production. Specialized manufacturing in the Rhine-Neckar triangle captures pharmacy substitution volumes from originator biologics.
Hesse
The Rhine-Main biotech corridor concentrates mRNA lipid nanoparticle formulation expertise accumulated during COVID-19 vaccine production. BioNTech SE anchors manufacturing scale in Mainz, with transferable platform technology extending into personalized neoantigen therapies. Frankfurt airport's cold-chain logistics infrastructure supports biologics distribution across European markets.
Berlin-Brandenburg
Charité hospital network procurement shapes antimicrobial stewardship program requirements restricting broad-spectrum prescribing. The region's hospital-at-home reimbursement pilots create demand for prefilled syringe and wearable injector formats. Brandenburg's pharmaceutical park outside Berlin hosts contract manufacturing organizations serving mid-scale biologics production.
Germany Pharmaceuticals Market Key Industry Players
Player mix skews toward vertically integrated diversified conglomerates with captive API production, creating tiered competitive dynamics where fermentation scale and radiopharmaceutical infrastructure determine regional procurement access. Three archetypes dominate: diversified chemical-pharma hybrids with backward integration into small-molecule synthesis, specialized biologics fermenters with GMP-certified sterile fill-finish capacity, and radiopharmaceutical operators with cyclotron network density. Competitive moves concentrate on M&A to secure AMNOG-ready clinical pipelines and capacity expansion in lipid nanoparticle formulation.
Among Germany-based diversified conglomerates, Bayer AG and Boehringer Ingelheim occupy positions spanning small-molecule and biologics production, with captive supply chains insulating margin structures from API concentration risk. Merck KGaA and Fresenius Kabi AG sit within the specialized biologics tier, where fermentation scale and hospital procurement relationships determine volume capture. BioNTech SE exemplifies the platform-technology archetype, with mRNA manufacturing expertise transferable across therapeutic categories. STADA Arzneimittel AG represents the mid-scale generic and biosimilar segment competing on cost through Baden-Württemberg production clusters.
| Leading Market Players |
|---|
| Bayer AG |
| Boehringer Ingelheim |
| Merck KGaA |
| Fresenius Kabi AG |
| STADA Arzneimittel AG |
| B. Braun |
| Sanofi |
| AbbVie Inc. |
| BioNTech SE |
| Others |
Cost & Logistics Intelligence
Multi-year framework agreements with annual step-down clauses lock in biologics procurement volumes for German hospital consortia while compressing supplier margins through predetermined price erosion schedules. These contract structures tether AMNOG-negotiated reimbursement rates to manufacturing scale commitments, forcing formulators to absorb API cost volatility within fixed-price obligations.
Pricing Analysis
Certification level creates the primary spread across German pharmaceutical supply tiers, with EU Good Manufacturing Practice-certified sterile injectables commanding premium positioning over standard small-molecule generics. Three-tier pricing structure across premium biologics, standard prescription drugs, and economy OTC categories stratifies margin profiles, with AMNOG price negotiations driving cost compression in the premium tier through reference-price benchmarking. Price differentiation intensifies between originator biologics and biosimilars as automatic pharmacy substitution rules redirect dispensing toward lower-cost alternatives. Hospital procurement committees exhibit highest price sensitivity for standard infusion therapies, while specialized oncology biologics retain pricing power through limited therapeutic alternatives.
Supply Chain Analysis
Inventory buffers for sterile API inputs stretch to 90-120 days as German formulators hedge against single-source concentration in Ireland and Italy. Active pharmaceutical ingredient production for cytotoxic compounds draws from EU-certified facilities, with fermentation capacity for biologics anchored in Baden-Württemberg and Hesse manufacturing clusters. Supply chain risk concentrates in natural gas-dependent lyophilization processes, exposing mid-scale contract manufacturers to energy cost volatility without captive renewable generation. Distribution runs through Frankfurt airport's cold-chain logistics infrastructure for biologics export, while domestic hospital networks receive direct shipments from regional manufacturing hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German pharmaceuticals sit in early-cycle expansion as hospital-at-home reimbursement protocols unlock channel access beyond acute care settings, extending addressable volume for prefilled syringe and wearable injector formats.
For Market Incumbents: Secure captive fermentation capacity in the Rhine-Main corridor to insulate margin structures from API supply concentration risk in Ireland and Italy. Anchor backward integration into lipid nanoparticle formulation expertise accumulated during pandemic-scale production, creating transferable platform technology for personalized neoantigen therapies. Defend hospital procurement relationships through multi-year framework agreements that lock in volume commitments against biosimilar substitution pressure. For New Entrants and Emerging Players: Anchor in Baden-Württemberg's BioRegio STERN initiative to access subsidized bioprocess engineering infrastructure and qualified personnel pipelines from Heidelberg and Tübingen university networks. Target homecare infusion protocols as the most penetrable channel, where statutory health insurer reimbursement expansions bypass entrenched hospital purchasing committees. Pursue green chemistry certification to qualify for accelerated regulatory review pathways under EU Green Deal pharmaceutical sector mandates. For Investors and Strategic Acquirers: Capital is best deployed toward specialized biologics fermenters with GMP-certified sterile fill-finish capacity and established relationships with German hospital procurement consortia. Long-term viability over the next decade hinges on AMNOG reform outcomes and the EU pharmaceutical strategy's impact on reference pricing dominance. Watch Federal Joint Committee expedited assessment pathway expansions for breakthrough therapies as the primary inflection signal for pipeline prioritization returns.| Strategic Initiative | Industry Significance |
|---|---|
| AMNOG-Ready Clinical Pipeline Acquisition | Secures early benefit assessment pathways through Federal Joint Committee submission readiness. |
| Lipid Nanoparticle Manufacturing Scale-Up | Captures transferable mRNA platform technology extending into personalized neoantigen therapies. |
| Green Chemistry Certification Program | Qualifies for EU Green Deal accelerated regulatory review pathways and sustainability incentives. |
| Homecare Infusion Protocol Partnership | Bypasses acute care purchasing committees through statutory health insurer reimbursement expansion. |
| Biosimilar Fermentation Capacity Expansion | Captures automatic pharmacy substitution volumes redirecting from originator biologics in Baden-Württemberg. |
Research Approach
Operator-level perspectives from drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists anchored the qualitative base for this analysis. Primary interview insights combined with secondary validation from EMA submission databases, ClinicalTrials.gov records, German statutory health insurance formulary listings, and Paul-Ehrlich-Institut batch-release documentation. Bottom-up volume modeling across therapy areas and dosage forms triangulated against top-down market sizing from customs trade data and pharmaceutical production statistics.
Sensitivity analysis tested forecast robustness across AMNOG reform scenarios, EU pharmaceutical strategy implementation timelines, and energy cost volatility assumptions over the projection horizon. Segmentation dimensions modeled include therapy area, product type, delivery mode, end-user channel, and regional regulatory cluster. CAGRs derived from historical volume trends, pipeline maturity assessments, and reimbursement pathway velocity indicators specific to hematology and immuno-oncology assets.
Material uncertainties — AMNOG negotiation outcomes, biosimilar substitution rule amendments, and natural gas price trajectories — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding Federal Joint Committee assessment protocols and EU Medical Device Regulation implementation timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Genitourinary Drugs Market
Pharmaceuticals
Metaxalone Market
Pharmaceuticals
Antimetabolite Drugs Market
Pharmaceuticals
Cyclosporine Drugs Market
Pharmaceuticals
Advanced Therapy Medicinal Products (Atmps) Market
Pharmaceuticals
Anti-Obesity Drugs Market
Pharmaceuticals
Steroid Injections Market
Pharmaceuticals
Posaconazole Market
Pharmaceuticals
Europe Sodium-Dependent Glucose Cotransporter 2 Market
Pharmaceuticals
Pharmacy Dark Store Market
Pharmaceuticals
Oral Anticoagulant Market
Pharmaceuticals
Dermatological Drugs Market
Pharmaceuticals
Lipid-Lowering Drugs Market
Pharmaceuticals
Global Electronic Aspirin Market
Pharmaceuticals
Global Testosterone Replacement Therapy Market
Pharmaceuticals
Global Fluorouracil (5FU) Market