
 Levothyroxine Sodium Market | 2026-2036
Levothyroxine Sodium Market Size, Share, and Industry Trends Forecast 2026-2036
Levothyroxine Sodium Market Foresight
Asset-light contract manufacturing and third-party API sourcing is rewriting competitive economics for mid-scale entrants. Merck leverages its integrated synthesis capabilities to control raw material quality from thyroid extract to finished dose. Teva Pharmaceutical Industries Ltd. anchors its position through high-volume generic tablet production serving retail pharmacy chains. Fresenius Kabi differentiates via hospital-focused injectable formats that command premium positioning in acute care settings.
Levothyroxine sodium is a synthetic thyroxine hormone (T4) administered as the sodium salt of L-3,3',5,5'-tetraiodothyronine, typically dosed in microgram increments to restore euthyroid function in hypothyroid patients. The compound requires precise crystalline form control and stability protection from light and moisture to maintain potency throughout shelf life. Tablet formulations dominate volume due to decades of clinical familiarity and patient self-administration protocols, though injectable formats capture concentrated value in perioperative and intensive care environments. Hospital pharmacy channels sustain the highest throughput for acute presentations, while retail pharmacy and emerging online platforms serve chronic maintenance populations with recurring refill patterns.
The FDA enforces stringent bioequivalence protocols for levothyroxine sodium through its narrow therapeutic index classification, compelling manufacturers to demonstrate tight pharmacokinetic equivalence margins. The EMA's MDR framework and REACH chemical registration requirements in Europe impose additional purity and documentation burdens on API suppliers seeking cross-border market access. Stakeholders must monitor evolving pharmacovigilance reporting obligations and bioequivalence study designs that regulators periodically revise to tighten therapeutic consistency standards.
Market Dynamics
FDA bioequivalence standards for narrow therapeutic index drugs are compressing manufacturing tolerances across the entire supply base. This regulatory pressure forces API producers and finished dose manufacturers to synchronize crystalline form control with tightened pharmacokinetic margins.
Growth Catalysts
- Hospital Injectable Demand:Acute care facilities in the United States are expanding perioperative thyroid hormone replacement protocols. Injectable levothyroxine sodium captures concentrated value in intensive care and surgical recovery settings.
- EMA MDR Framework:The European Medical Device Regulation imposes documentation burdens that favor established suppliers with quality management infrastructure. Compliance-ready manufacturers gain preferential access to hospital procurement channels.
- Aging Population Diagnoses:Thyroid disorder detection rates among patients over 65 are rising in Germany, Japan, and the United States. Chronic maintenance populations generate recurring refill patterns through retail and online pharmacy platforms.
Market Restraints
- Porcine Thyroid Extract Volatility:Natural desiccated thyroid alternatives compete for limited animal-derived raw material supplies. Price instability in porcine sourcing disrupts synthetic levothyroxine sodium cost benchmarking.
- API Concentration in China and India:Active pharmaceutical ingredient production clusters in Tianjin and Hyderabad create geographic supply risk. Regulatory inspections and export licensing delays propagate through finished dose supply chains.
- Narrow Therapeutic Index Limitations:The FDA's 90% confidence interval requirements for bioequivalence studies constrain formulation innovation. Generic entrants face extended development timelines and elevated clinical trial costs.
Strategic Opportunities
- Brazil ANVISA Pathway:Underpenetrated chronic disease management in São Paulo and Rio de Janeiro offers volume expansion potential. Local partnership structures accelerate hospital formulary inclusion.
- Continuous Manufacturing Technology:Real-time release testing and process analytical technology converge to compress batch cycle times. Early adopters reduce working capital requirements and improve yield consistency.
- Medicare Reimbursement Stability:United States federal payment policies favor established oral tablet therapies with decades of claims history. Reimbursement predictability supports long-term contract negotiations with pharmacy benefit managers.
Industry Challenges
- Analytical Method Transfer Complexity:Migrating bioequivalence protocols between contract research organizations creates validation bottlenecks. FDA acceptance of alternative study designs remains inconsistent across review divisions.
- Light and Moisture Protection Engineering:Packaging innovation for stability maintenance requires capital investment in barrier film technologies. Shelf-life extension claims demand accelerated aging studies with tight statistical powering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Levothyroxine Sodium Market |
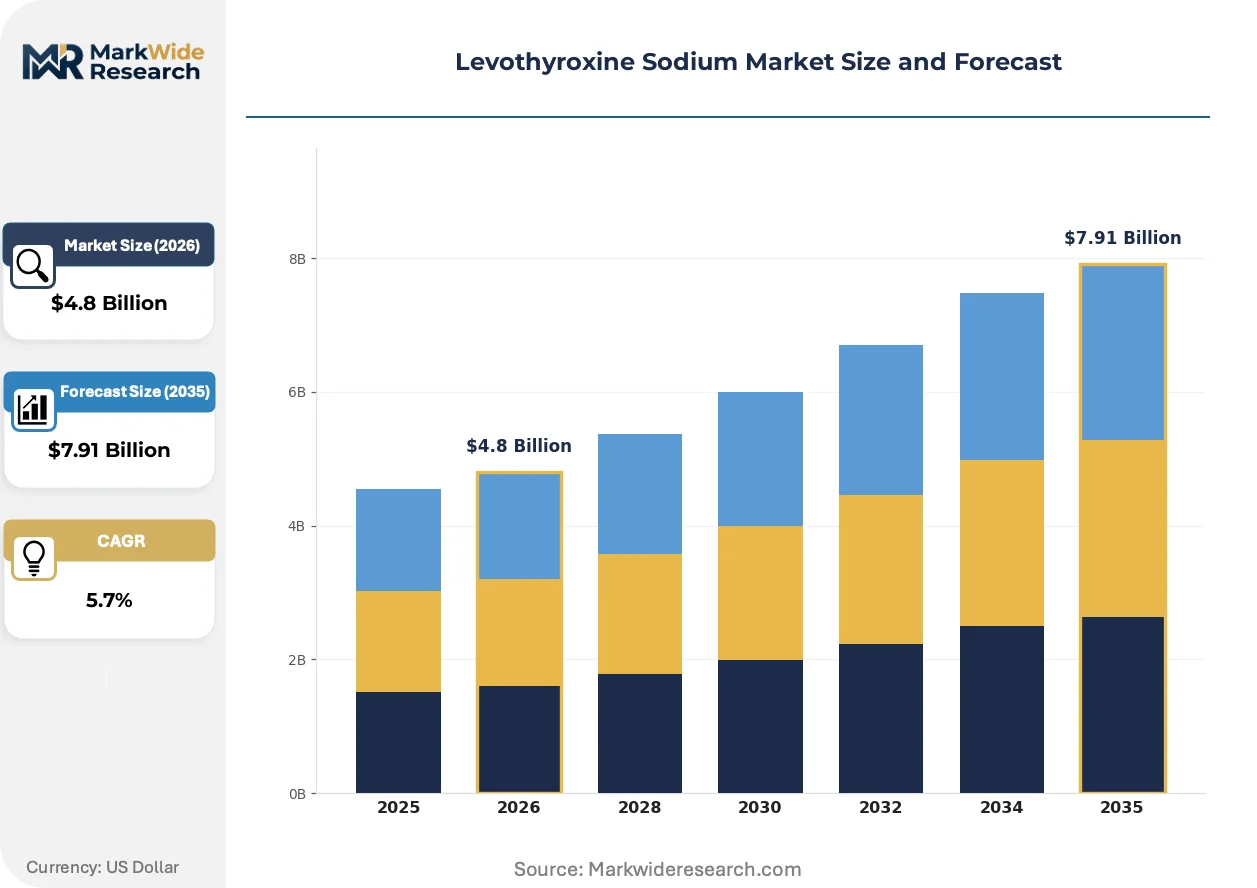
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Formulation Type: Tablet, Injectable, Capsule, Liquid End User: Hospitals, Clinics, Pharmacies, Homecare Distribution Channel: Online, Retail Pharmacy, Hospital Pharmacy, Wholesalers Packaging Type: Bottles, Blister Packs, Vials, Sachets |
| Companies Covered | Merck, Teva Pharmaceutical Industries Ltd., Pfizer Inc., IBSA Institut Biochimique SA, Fresenius Kabi, AbbVie Inc., Novartis, Lannett Company, Sanofi S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Levothyroxine Sodium Market Shifts & Advancements
Digital therapeutics integration and advanced manufacturing controls are collapsing traditional boundaries between pharmaceutical production and patient monitoring. These convergences reshape how levothyroxine sodium maintains therapeutic consistency across diverse administration settings.
Process analytical technology is collapsing the separation between manufacturing and quality release decisions. Real-time spectroscopic monitoring of crystalline form and moisture content enables immediate batch disposition. Hospital pharmacies and acute care buyers are adopting suppliers with demonstrated continuous manufacturing capabilities. This compression eliminates traditional quarantine periods and reduces inventory carrying costs for high-throughput procurement operations.
REACH chemical registration requirements in Europe are tightening purity documentation burdens on API suppliers seeking cross-border market access. The ECHA framework mandates expanded impurity profiling and toxicological assessment for thyroid hormone derivatives. Swiss and German finished dose manufacturers are consolidating supplier qualification programs to preempt registration delays. This regulatory friction favors integrated producers with captive API synthesis over contract-dependent competitors.
Hospital pharmacy consolidation in the United States is compressing vendor lists and elongating contract terms. Large health systems in Texas, California, and Florida are centralizing formulary decisions across multi-facility networks. Injectable levothyroxine sodium procurement is migrating toward sole-source agreements with premium positioning. This concentration displaces fragmented purchasing patterns that previously sustained mid-tier generic suppliers through price competition.
Levothyroxine Sodium Market Segmentation
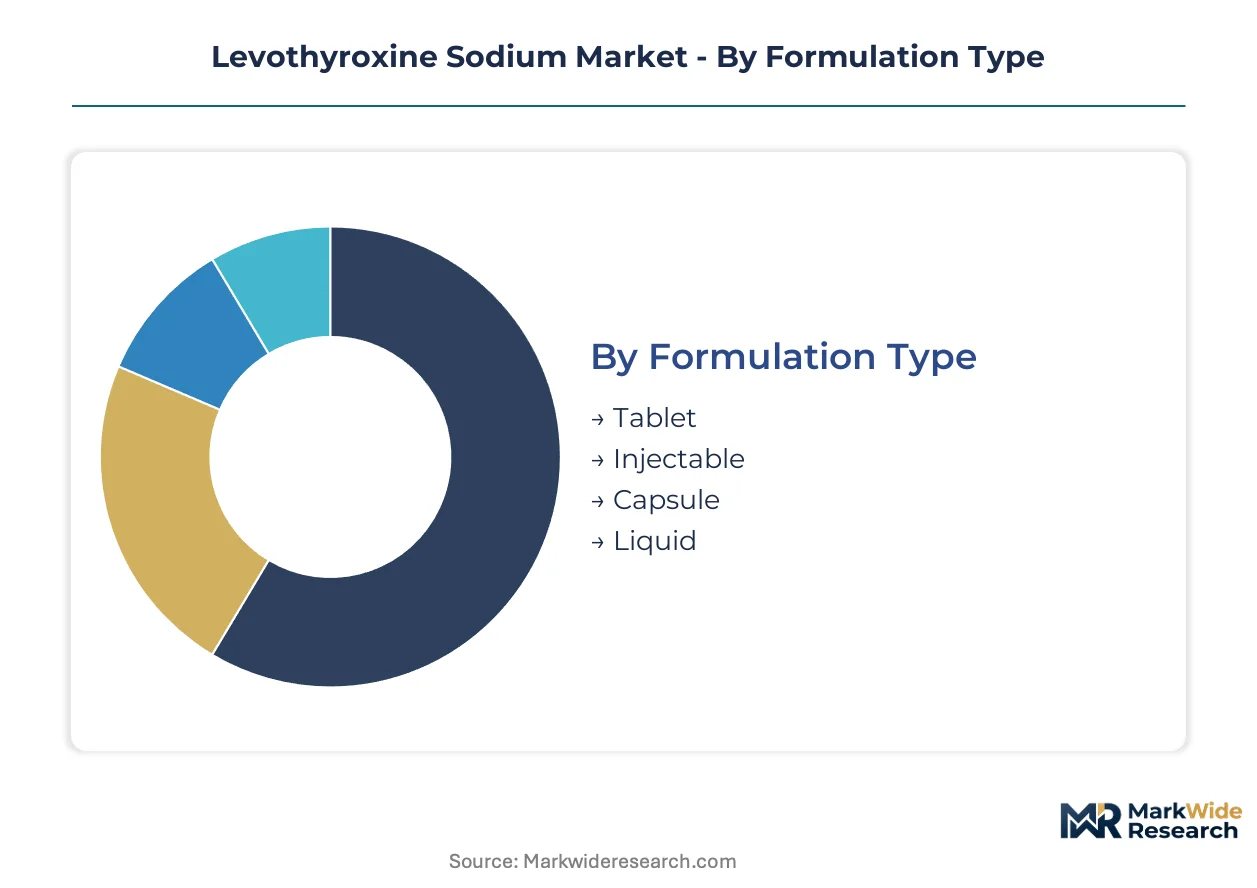
Levothyroxine sodium segmentation reflects divergent clinical requirements across acute intervention and chronic maintenance settings. Formulation stability demands, reimbursement pathways, and patient self-administration capabilities reshape how manufacturers allocate development resources across product architectures.
Formulation Type:
Tablet formulations anchor chronic hypothyroidism management through decades of clinical familiarity and precise microgram dosing flexibility.
- Tablet:Compressed crystalline levothyroxine sodium with excipient matrices enabling 12.5-300 microgram dose gradations. Medicare reimbursement stability in the United States sustains high-volume production for retail pharmacy chains, though FDA narrow therapeutic index requirements compress manufacturing tolerances.
- Injectable:Sterile sodium salt solution for intravenous or intramuscular administration in perioperative and intensive care environments. Hospital procurement in Texas, California, and Florida health systems concentrates demand for single-use vial formats with immediate bioavailability.
- Capsule:Gelatin-encapsulated powder formulations offering alternative excipient profiles for patients with tablet binder sensitivities. Compounding pharmacies in Germany and Japan maintain niche demand for customized dose combinations.
- Liquid:Oral solution formulations enabling precise dose titration for pediatric patients and swallowing-impaired populations. Homecare adoption in São Paulo and Rio de Janeiro supports volume expansion for Brazil ANVISA-registered suppliers.
Established volume favors Tablet; emerging adoption favors Injectable.
End User:
Patient acuity determines procurement authority, with institutional buyers commanding premium positioning for sterile formats.
- Hospitals:Acute care facilities manage perioperative thyroid replacement and myxedema coma interventions. Injectable procurement through centralized formularies in United States health systems generates concentrated demand with premium pricing.
- Clinics:Outpatient endocrinology practices coordinate dose titration and monitoring for newly diagnosed hypothyroid patients. Medicare reimbursement protocols in the United States favor established oral tablet therapies with documented claims history.
- Pharmacies:Retail and hospital pharmacy channels sustain recurring refill patterns for chronic maintenance populations. Online platform growth in Japan and Germany expands patient access beyond traditional brick-and-mortar networks.
- Homecare:Self-administered oral therapies for stable hypothyroid patients with established euthyroid function. Aging population diagnoses in Germany and Japan expand this segment's refill velocity.
Procurement concentration favors Hospitals; patient volume expansion favors Pharmacies.
Distribution Channel:
Channel selection reflects reimbursement mechanics, inventory carrying costs, and patient convenience requirements across acute and chronic settings.
- Online:Direct-to-patient platforms with automated refill scheduling and home delivery capabilities. Chronic maintenance populations in Japan and Germany adopt digital pharmacy services for levothyroxine sodium continuity.
- Retail Pharmacy:Community-based dispensing with established insurance adjudication infrastructure. United States Medicare Part D coverage sustains high-throughput tablet distribution through national chains.
- Hospital Pharmacy:Centralized procurement for inpatient formulary management and perioperative protocols. Injectable levothyroxine sodium sourcing migrates toward sole-source agreements with premium positioning in Texas and Florida health systems.
- Wholesalers:Inventory aggregation and logistics services connecting manufacturers to fragmented downstream buyers. Regulatory inspection delays at API facilities in Tianjin propagate supply disruptions through wholesale distribution networks.
Volume scale favors Retail Pharmacy; margin capture favors Hospital Pharmacy.
Packaging Type:
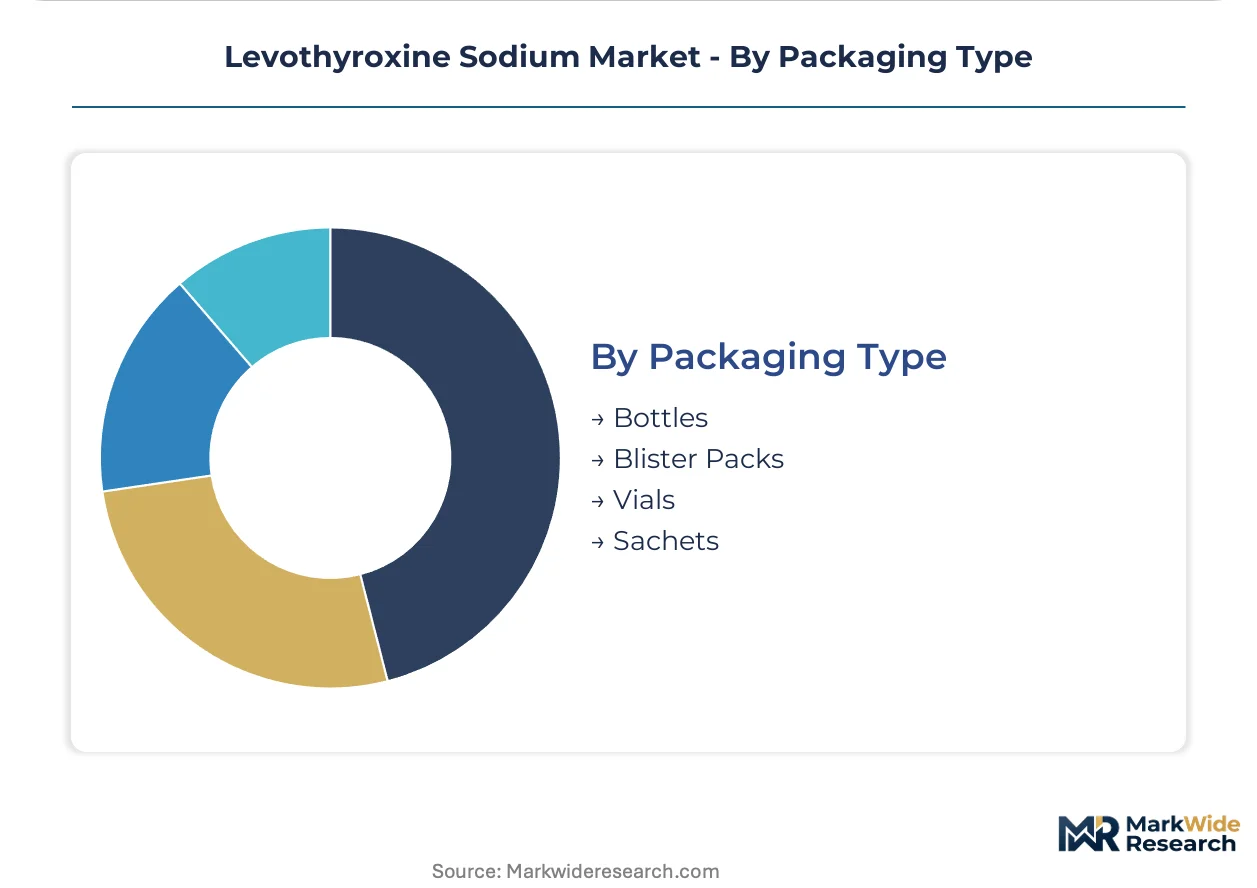
Barrier engineering requirements vary with stability sensitivity, dosing precision, and administration setting sterility demands.
- Bottles:HDPE containers with desiccant inserts for 90-100 count tablet supplies. Retail pharmacy chains in the United States favor this format for chronic maintenance dispensing economics.
- Blister Packs:Individual dose cavities with aluminum-foil barrier films protecting against moisture and light. Patient adherence programs in Japan and Germany utilize calendar-pack designs for dose tracking.
- Vials:Glass or polymer containers for sterile injectable solutions with single-dose or multi-dose configurations. Hospital pharmacy procurement in California and Texas concentrates on vial formats with extended beyond-use dating.
- Sachets:Unit-dose foil pouches for oral powder or liquid formulations. Pediatric and geriatric homecare applications in Brazil favor sachet portability for dose flexibility.
Unit economics favor Bottles; stability engineering favors Blister Packs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare reimbursement stability in the United States sustains high-volume tablet distribution, while EMA bioequivalence protocols reshape manufacturing requirements across European hospital networks.
United States
Hospital pharmacy consolidation in Texas, California, and Florida health systems concentrates injectable procurement through sole-source agreements. FDA narrow therapeutic index standards compress manufacturing tolerances for generic tablet suppliers. Medicare Part D coverage anchors chronic maintenance dispensing through national retail chains.
Germany
Aging population diagnoses among patients over 65 expand chronic maintenance populations in Berlin and Munich metropolitan areas. EMA MDR framework documentation burdens favor established suppliers with quality management infrastructure. Swiss and German finished dose manufacturers consolidate supplier qualification programs in Baden-Württemberg.
Japan
Thyroid disorder detection rates rise among elderly populations in Tokyo and Osaka prefectures. METI industrial standards coordinate with PMDA pharmacovigilance requirements for hormone replacement therapies. Kanto region hospitals adopt digital pharmacy platforms for automated refill scheduling.
Brazil
Underpenetrated chronic disease management in São Paulo and Rio de Janeiro offers volume expansion potential for oral solution formulations. ANVISA registration pathways accelerate hospital formulary inclusion for local partnership structures. Homecare adoption supports demand for pediatric and geriatric dose flexibility.
India
API production clusters in Hyderabad create geographic supply concentration for finished dose manufacturers. CDSCO bioequivalence study requirements align with tightened international pharmacokinetic standards. Contract manufacturing organizations in Telangana serve European and North American markets.
Levothyroxine Sodium Market Competitive Landscape
Channel-controlling players compete with product-specialist players across hospital, retail, and digital pharmacy segments. The vendor base organizes around three archetypes: integrated pharmaceutical conglomerates with captive API synthesis, high-volume generic manufacturers serving retail chains, and hospital-focused sterile format specialists. Consolidation pressures favor scale-driven players with quality management infrastructure. Strategic moves center on backward integration into raw material sourcing and continuous manufacturing technology adoption.
Among integrated pharmaceutical conglomerates, Merck and Novartis occupy positions exemplifying captive control from thyroid extract through finished dose. Teva Pharmaceutical Industries Ltd. and Lannett Company represent the high-volume generic tier supplying retail pharmacy chains with tablet formulations. Fresenius Kabi anchors the hospital-specialist archetype through sterile injectable positioning in acute care procurement channels.
| Leading Market Players |
|---|
| Merck |
| Teva Pharmaceutical Industries Ltd. |
| Pfizer Inc. |
| IBSA Institut Biochimique SA |
| Fresenius Kabi |
| AbbVie Inc. |
| Novartis |
| Lannett Company |
| Sanofi S.A. |
| Others |
Supply & Pricing Matrix
API production clusters in Tianjin and Hyderabad anchor cost structures for finished dose manufacturers, concentrating margin capture with integrated producers who control crystalline form synthesis from thyroid extract to sterile vial. Hospital procurement consolidation in Texas, California, and Florida health systems shifts pricing power toward sole-source injectable agreements, while retail tablet markets compress under Medicare reimbursement ceilings.
Pricing Analysis
FDA narrow therapeutic index certification creates the primary spread between premium sterile injectables and commodity oral tablets. Three-tier pricing structure across premium, standard, and economy levels stratifies by bioequivalence study documentation depth and barrier packaging engineering. Pricing pressure stems from Medicare Part D reimbursement compression on chronic maintenance formulations. Retail pharmacy chains exhibit highest price sensitivity; hospital pharmacy procurement committees prioritize supply assurance over unit cost.
Supply Chain Analysis
Thyroid extract feedstock sourcing draws from porcine and bovine processing facilities concentrated in China, India, and select European rendering operations. Synthetic levothyroxine sodium production rests on iodine derivatives, L-tyrosine precursors, and crystallization solvent systems. Single-source vulnerability propagates from CDSCO inspection delays at Hyderabad API facilities through finished dose supply chains. Distribution runs through wholesaler aggregation networks serving fragmented retail pharmacies alongside direct hospital pharmacy contracts for sterile formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across hospital injectable, retail tablet, and emerging liquid formulation channels creates niche entry points for specialists. Rising thyroid disorder diagnoses among aging populations in Germany, Japan, and the United States generate demand-side shifts that reward targeted positioning.
For Market Incumbents: Harden quality management infrastructure against EMA MDR documentation burdens and FDA bioequivalence protocol revisions. Consolidate supplier qualification programs to preempt REACH registration delays. Deepen backward integration into captive API synthesis to offset Tianjin and Hyderabad supply concentration risks. Channel control through sole-source hospital agreements protects margin pools from retail price erosion.
For New Entrants and Emerging Players: Mid-market oral liquid formulations for pediatric and geriatric populations in São Paulo and Rio de Janeiro represent the most penetrable entry point. Continuous manufacturing technology adoption in Baden-Württemberg and Telangana offers second-mover positioning with compressed batch cycle times. ANVISA partnership structures accelerate hospital formulary inclusion faster than FDA narrow therapeutic index pathways.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract manufacturing organizations in Telangana serving North American and European markets. Five-to-ten year viability hinges on continuous manufacturing technology deployment and EMA MDR compliance infrastructure. The signal to watch is hospital pharmacy consolidation velocity in Texas and Florida health systems migrating toward sole-source agreements.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Technology Adoption | Real-time release testing compresses quarantine periods for hospital pharmacy procurement. |
| EMA MDR Compliance Infrastructure | Quality management documentation unlocks preferential access to Berlin and Munich hospital networks. |
| Backward Integration into API Synthesis | Captive thyroid extract processing insulates against porcine raw material price volatility. |
| Hospital System Partnership Expansion | Sole-source agreements in California and Texas health systems command premium injectable positioning. |
| Brazil ANVISA Registration Pathway | Local partnership structures accelerate formulary inclusion for underpenetrated chronic disease management. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with regulatory affairs leads, hospital procurement managers, formulary directors, and contract manufacturing executives; and secondary validation against FDA bioequivalence study databases, EMA MDR submission records, CMS Medicare Part D claims data, and ANVISA registration filings. Bottom-up patient population modeling and top-down pharmaceutical market sizing were triangulated for convergence.
Forecast inputs across the analysis window incorporated formulation type segmentation, end-user procurement authority tiers, distribution channel economics, and regional regulatory cluster variations. CAGRs were derived from patient diagnosis velocity projections, reimbursement policy stability assessments, and manufacturing capacity expansion announcements. Thyroid disorder detection rates among populations over 65 and hospital pharmacy consolidation patterns served as industry-specific demand and supply-side anchors.
Practitioners should monitor FDA bioequivalence protocol revisions, EMA MDR enforcement intensity, and API facility inspection frequencies for early signals of forecast deviation. Cross-checking against CMS Medicare claims benchmarks and hospital procurement database trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Myocardial Infarction Drugs Market
Pharmaceuticals
Rosuvastatin Market
Pharmaceuticals
United States Pharmaceutical Logistics Market
Pharmaceuticals
Small Volume Parenteral Market
Pharmaceuticals
Smart Pills Market
Pharmaceuticals
Sulfonylureas Market
Pharmaceuticals
Cough Suppressant Drugs Market
Pharmaceuticals
Global Varicella Vaccine Market
Pharmaceuticals
Metaxalone Market
Pharmaceuticals
Vitiligo Drugs Market
Pharmaceuticals
Adapalene Products Market
Pharmaceuticals
Acne Drugs Market
Pharmaceuticals
Human Growth Hormone Treatment and Drugs Market
Pharmaceuticals
Photophobia Drug Market
Pharmaceuticals
Anthelmintic Drugs Market
Pharmaceuticals
Soft Capsules Drugs Market