
 Tenecteplase Drugs Market | 2026-2036
Tenecteplase Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Tenecteplase Drugs Market Analytics
The gap between premium branded tenecteplase formulations and commodity-oriented biosimilar alternatives is realigning procurement strategies across hospital systems. Genentech (Roche) leverages its originator heritage and established thrombolytic protocols to sustain premium positioning in acute care settings. CSPC Pharmaceutical anchors volume supply through cost-competitive manufacturing scale in Asia-Pacific markets. Boehringer Ingelheim differentiates via integrated anticoagulant-to-thrombolytic portfolios that capture extended patient pathways.
Tenecteplase is a recombinant tissue plasminogen activator (tPA) variant engineered with amino acid substitutions at three sites (T103N, N117Q, KHRR 296-299 AAAAA), yielding a longer half-life of approximately 20-24 minutes and enabling single-bolus intravenous administration for thrombolytic therapy. The intravenous segment dominates current revenue pools due to emergency department administration protocols, while the subcutaneous delivery investigation represents the fastest-growing development trajectory as manufacturers pursue post-hospitalization continuity models. Application concentration in acute coronary syndrome and stroke reflects established clinical guideline endorsements, though pulmonary embolism protocols are expanding as single-bolus convenience drives protocol adoption.
The FDA governs tenecteplase through biologics license pathways and pharmacovigilance requirements, while the EMA's biosimilar comparability guidelines shape European competitive entry, and China's NMPA accelerates domestic innovation through priority review channels for cardiovascular therapies. These regulatory frameworks elevate manufacturing quality standards and extend development timelines, simultaneously protecting innovators and constraining rapid generic penetration. Stakeholders must monitor evolving thrombolysis window extensions and real-world evidence requirements that could redefine reimbursement and clinical adoption thresholds.
Market Dynamics
Single-bolus administration protocols are compressing emergency department treatment windows and displacing multi-infusion thrombolytic regimens across acute care networks. This shift is electrifying manufacturing scale-up for high-concentration vial formats and rewiring hospital formulary procurement around convenience-driven clinical workflows.
Growth Catalysts
- FDA Accelerated Approval Pathways:Streamlined biologics review timelines compress development-to-commercialization cycles for novel thrombolytic formulations targeting acute coronary syndrome protocols.
- Aging Demographics in Germany:Expanding elderly populations with elevated stroke incidence drive emergency department tenecteplase utilization and protocol standardization across Bavarian and North Rhine-Westphalia hospital clusters.
- Subcutaneous Delivery Investigation:Post-hospitalization continuity models enable thrombolytic therapy extension beyond acute settings, opening ambulatory care and home infusion channels.
Market Restraints
- Plasma-Derived Raw Material Volatility:Recombinant protein production depends on stable cell culture media supply, with Chinese hamster ovary cell line availability constraining batch consistency.
- EMA Biosimilar Comparability Burden:Immunogenicity study requirements and extensive clinical equivalence trials extend European market entry timelines for cost-competitive alternatives.
- Alteplase Substitution in Resource-Limited Settings:Established tissue plasminogen activator alternatives with deeper generic penetration capture price-sensitive procurement in emerging acute care markets.
Strategic Opportunities
- Pulmonary Embolism Protocol Expansion:Single-bolus convenience drives adoption beyond stroke and ACS into massive and submassive PE management, opening interventional radiology and intensive care unit channels.
- China NMPA Priority Review Channels:Domestic cardiovascular therapy innovation incentives accelerate local manufacturing scale and reduce import dependency for thrombolytic supply security.
- Lyophilized Formulation Stability:Extended shelf-life and reduced cold-chain dependency enable distribution into rural and military medical infrastructure with limited refrigeration capacity.
Industry Challenges
- Pharmacovigilance Infrastructure Scaling:Post-market bleeding event monitoring requires specialized hemostasis expertise that acute care networks struggle to staff across rotating emergency department personnel.
- Legacy EHR Integration Friction:Thrombolytic decision-support algorithms and door-to-needle time tracking demand real-time data interoperability that fragments across hospital system acquisition histories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tenecteplase Drugs Market |
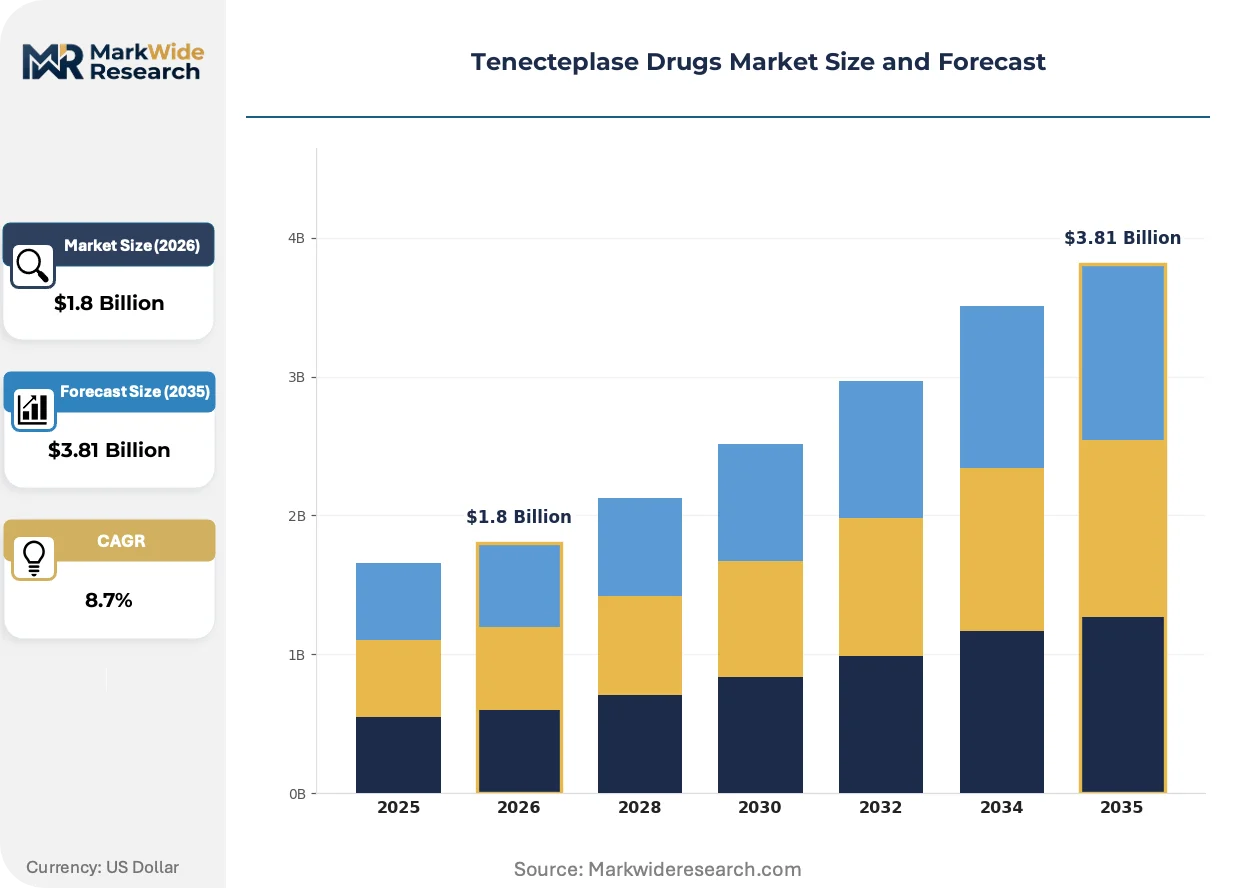
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intravenous, Oral, Subcutaneous, Combination Therapy Application: Acute Coronary Syndrome, Stroke, Pulmonary Embolism, Thrombosis Delivery Mode: Hospital, Clinic, Home Care, Long-term Care End User: Healthcare Providers, Physicians, Pharmacists, Patients |
| Companies Covered | Emcure Pharmaceuticals, CSPC Pharmaceutical, Genentech (Roche), Rewine Pharmaceuticals, Feng Hua Biotech, Boehringer Ingelheim, Gennova Bio, Shimao Tianjie Pharmaceutical, Pfizer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tenecteplase Drugs Market Evolving Landscape
Biomanufacturing platform convergence and regulatory science advances are compressing development timelines while expanding administration settings beyond traditional emergency department boundaries. These forces are rewiring competitive positioning around formulation stability and point-of-care preparation simplicity.
Site-specific PEGylation and albumin-binding domain fusion technologies are extending tenecteplase circulatory half-life toward 72-hour therapeutic windows. Academic medical centers in Massachusetts and California are piloting these variants in extended neuroprotection protocols. This capability is electrifying prehospital ambulance administration models and collapsing the geography between symptom onset and thrombolytic delivery.
EMA's 2023 refined biosimilar immunogenicity guidance and FDA's updated thrombolytic pharmacovigilance requirements are elevating post-approval study commitments. Manufacturers now face mandatory real-world bleeding outcome registries extending five years post-launch. European hospital systems are responding with centralized procurement consortia that demand transparent pharmacovigilance cost-sharing mechanisms.
Hospital pharmacy consolidation into regional purchasing organizations is unbundling traditional distributor relationships in favor of direct manufacturer contracting. Three-tier pricing stratification across premium originator, licensed biosimilar, and emerging market-sourced alternatives now governs formulary placement. This restructuring is most visible in United States integrated delivery networks where CVS Health and Cardinal Health channel control has compressed independent hospital purchasing autonomy.
Tenecteplase Drugs Market Segmentation
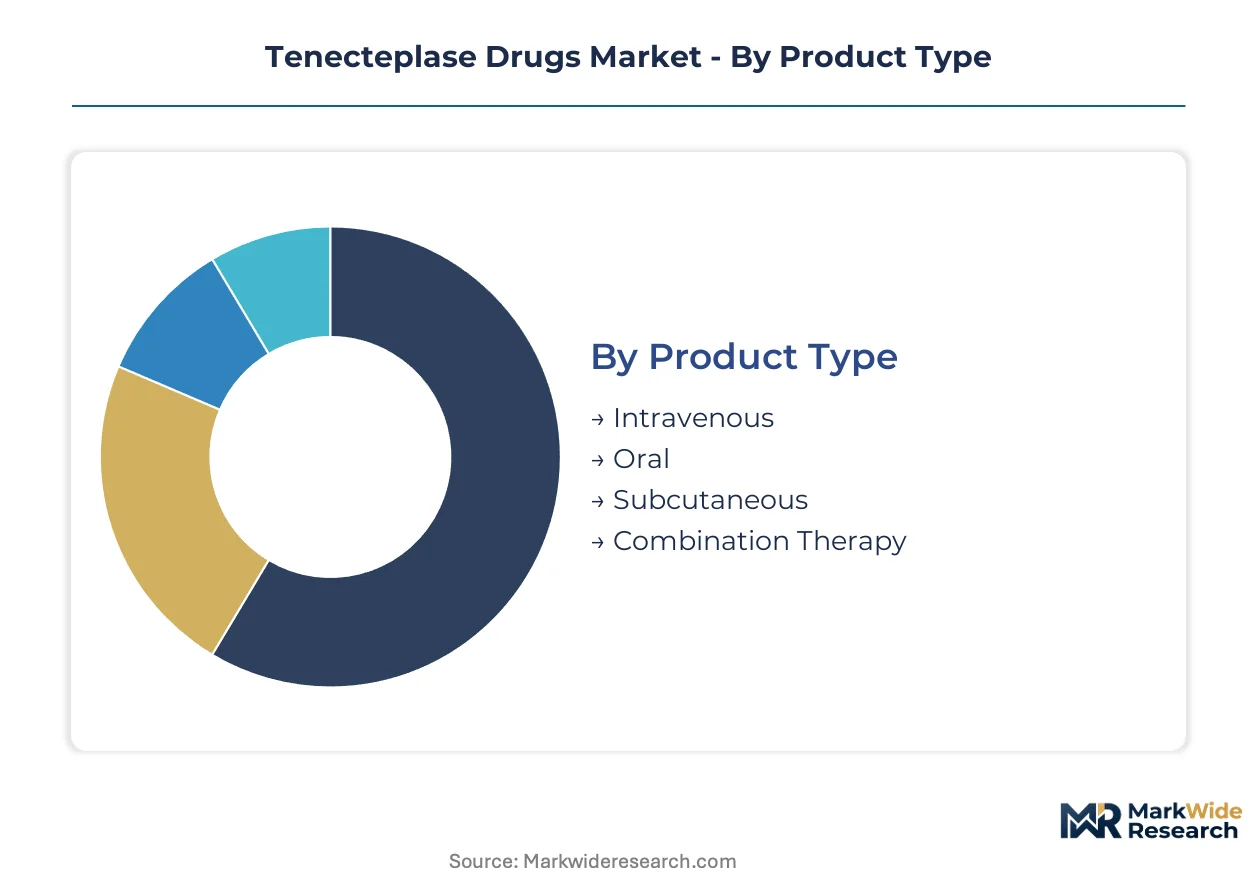
Tenecteplase market segmentation reveals how regulatory pathways, administration settings, and clinical workflows fragment commercial opportunity. Each dimension carries distinct certification burdens and reimbursement thresholds that shape manufacturer investment priorities.
Product Type:
FDA biologics license pathways govern intravenous and subcutaneous formats through distinct CMC review intensities, while oral and combination variants face compounded pharmacokinetic validation requirements.
- Intravenous:Recombinant protein formulation delivered via single-bolus injection dominates emergency department protocols. Demand concentrates in United States Level I trauma centers and German university hospitals where door-to-needle time metrics drive formulary standardization.
- Subcutaneous:Extended half-life variants enable post-acute administration outside hospital settings. Pilot programs at Massachusetts General Hospital and Stanford Health Care are testing home infusion models for stroke recovery continuity.
- Oral:Peptide-based delivery research targets gastric stability challenges through enteric coating technologies.
- Combination Therapy:Co-formulation with antiplatelet agents requires anticoagulant interaction studies under FDA guidance.
Leading the category by volume: Intravenous. Growing fastest: Subcutaneous.
Application:
Clinical guideline endorsements from the American Heart Association and European Society of Cardiology create tiered reimbursement access across thrombotic indications.
- Acute Coronary Syndrome:STEMI protocols with established mortality benefit data command premium pricing in catheterization laboratory settings. German cardiac centers in Munich and Hamburg anchor European utilization.
- Stroke:Extended therapeutic window approvals in China and the United States are expanding eligible patient populations beyond traditional 4.5-hour limits.
- Pulmonary Embolism:Massive PE indications gain traction in interventional radiology departments seeking alternatives to systemic heparin.
- Thrombosis:Deep vein thrombosis applications remain investigational with Phase III trials ongoing at Johns Hopkins and Peking Union Medical College Hospital.
Acute Coronary Syndrome generates the largest revenue pool. Stroke applications are climbing the fastest.
Delivery Mode:
Site-of-care economics and nursing intensity requirements stratify profitability across administration settings.
- Hospital:Emergency department and intensive care unit administration captures highest reimbursement rates under DRG-based payment systems. United States integrated delivery networks in Texas and Florida concentrate procurement volume.
- Clinic:Outpatient infusion centers in China's tier-1 cities are piloting same-day thrombolytic protocols for stable PE patients.
- Home Care:Subcutaneous delivery investigation enables skilled nursing administration with remote physician oversight.
- Long-term Care:Nursing facility protocols remain limited by bleeding risk monitoring capabilities and specialist availability.
Hospital settings dominate current value capture. Home Care delivery is expanding most quickly.
End User:
Prescription authority and formulary control determine purchasing influence across stakeholder types.
- Healthcare Providers:Hospital systems and integrated delivery networks wield consolidated purchasing power through regional GPO contracts. Kaiser Permanente and Intermountain Healthcare exemplify centralized tenecteplase procurement.
- Physicians:Interventional cardiologists and emergency medicine specialists drive protocol adoption through clinical pathway committees.
- Pharmacists:Clinical pharmacy specialists manage inventory and preparation workflows in thrombolytic-ready emergency departments.
- Patients:Direct access remains constrained by prescription requirements and administration safety protocols.
Healthcare Providers control the largest procurement volume. Physician-directed protocol expansion is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors North American tenecteplase clinical development through Massachusetts General Hospital's extended neuroprotection protocols. German university hospitals in Munich and Hamburg drive European protocol standardization. Chinese tier-1 cities pilot outpatient thrombolytic administration models.
United States
Level I trauma centers in Texas and Florida concentrate procurement volume through integrated delivery networks. FDA biologics license pathways and pharmacovigilance requirements govern market entry with mandatory real-world bleeding outcome registries. Stanford Health Care in California pilots home infusion models for stroke recovery continuity.
Germany
Bavarian and North Rhine-Westphalia hospital clusters standardize emergency department tenecteplase utilization for aging populations with elevated stroke incidence. EMA biosimilar comparability guidelines shape competitive entry through immunogenicity study requirements. Munich cardiac centers anchor European acute coronary syndrome protocol adoption.
China
Tier-1 cities expand eligible stroke populations through extended therapeutic window approvals. NMPA priority review channels accelerate domestic cardiovascular therapy innovation and reduce import dependency. Peking Union Medical College Hospital conducts Phase III trials for deep vein thrombosis applications.
India
Emerging acute care markets face price-sensitive procurement competition from established tissue plasminogen activator alternatives. CDSCO governs biologics licensing with evolving pharmacovigilance infrastructure requirements. Major metropolitan hospital systems consolidate purchasing through regional group procurement organizations.
Japan
PMDA review timelines align with global thrombolytic development cycles for acute coronary syndrome formulations. METI industrial policy supports domestic biomanufacturing platform convergence. Tokyo academic medical centers participate in site-specific PEGylation variant pilot programs for extended half-life applications.
Tenecteplase Drugs Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across recombinant protein manufacturing and clinical protocol development. The market structure concentrates around originator heritage players, cost-competitive Asian manufacturers, and integrated anticoagulant-to-thrombolytic portfolios. Three archetypes dominate: premium branded originators leveraging established emergency department relationships, volume-scale biosimilar suppliers capturing procurement consolidation, and diversified pharmaceutical conglomerates bundling thrombolytic offerings with anticoagulant franchises. Dominant competitive moves include direct manufacturer contracting with regional purchasing organizations and lyophilized formulation development for reduced cold-chain dependency.
Among originator heritage specialists, Genentech occupies a position exemplifying premium-tier clinical protocol anchoring through established thrombolytic relationships. CSPC Pharmaceutical represents the volume-scale manufacturing archetype with cost-competitive supply positioning across Asia-Pacific procurement networks. Boehringer Ingelheim sits within the integrated portfolio tier, bundling tenecteplase offerings with extended anticoagulant patient pathway capture.
| Leading Market Players |
|---|
| Emcure Pharmaceuticals |
| CSPC Pharmaceutical |
| Genentech (Roche) |
| Rewine Pharmaceuticals |
| Feng Hua Biotech |
| Boehringer Ingelheim |
| Gennova Bio |
| Shimao Tianjie Pharmaceutical |
| Pfizer |
| Others |
Value Network & Pricing Analysis
Captive biomanufacturing of Chinese hamster ovary cell lines anchors supply security for originator tenecteplase producers while simultaneously underwriting premium pricing power through batch-to-batch consistency guarantees. This integration choice separates Genentech's emergency department formulary lock-in from commodity biosimilar entrants competing on spot-market cell culture media costs.
Pricing Analysis
Door-to-needle time metrics anchor value-based pricing for intravenous tenecteplase in Level I trauma centers, where reimbursement ties to stroke protocol throughput rather than vial cost. Pricing stratifies across premium originator, licensed biosimilar, and emerging market-sourced tiers, with FDA biologics license tier commanding highest formulary placement. Cost compression in the biosimilar tier is intensifying because EMA immunogenicity study requirements extend development timelines and amortization burdens. Hospital procurement managers at integrated delivery networks exhibit highest price sensitivity, while interventional cardiologists in catheterization laboratories remain least sensitive due to mortality outcome anchoring.
Supply Chain Analysis
EMA biosimilar comparability guidelines and FDA pharmacovigilance requirements gate upstream supplier qualification, forcing dual-source validation for cell culture media and single-use bioreactor components. Manufacturing concentrates in the United States, Germany, and China, with recombinant protein production drawing from stable CHO cell line availability, pharmaceutical-grade media supply, and lyophilization capacity. Single-source vulnerability runs through Chinese hamster ovary cell line repositories controlled by limited academic licensors. Distribution runs through regional purchasing organizations and direct manufacturer contracting with integrated delivery networks, bypassing traditional wholesale distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Site-specific PEGylation variants are displacing legacy single-bolus intravenous formats, collapsing the geography between symptom onset and thrombolytic delivery while opening prehospital administration channels.
For Market Incumbents: Deploy lyophilized formulation stability as the anchor lever to defend emergency department formulary position against subcutaneous delivery entrants. Backward integration into cell line development secures batch consistency against raw material volatility. Capacity addition in Bavarian hospital clusters captures aging demographic stroke volume expansion before biosimilar EMA comparability timelines mature. For New Entrants and Emerging Players: Launch via home infusion pilot programs targeting post-hospitalization continuity gaps in Massachusetts and California academic medical centers. Pulmonary embolism protocols in interventional radiology departments represent the most penetrable application white-space, with massive PE indications lacking established tenecteplase guideline anchoring. Go-to-market through remote physician oversight platforms enables skilled nursing administration without catheterization laboratory infrastructure. For Investors and Strategic Acquirers: Exit pathways concentrate in platform biomanufacturing acquisitions by diversified pharmaceutical conglomerates seeking thrombolytic-to-anticoagulant patient pathway bundling. Long-term viability frames around 72-hour therapeutic window extension technologies and real-world bleeding outcome registry infrastructure. Watch NMPA priority review channel acceleration for domestic Chinese manufacturers as inflection signal for import dependency reduction.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Extended neuroprotection protocols at Massachusetts General Hospital validate 72-hour therapeutic windows. |
| Regulatory Approval Pathway | FDA accelerated biologics review compresses development-to-commercialization cycles for novel thrombolytic formulations. |
| Manufacturing Scale-Up | High-concentration vial formats electrify production to match single-bolus emergency department demand surges. |
| Pipeline Diversification | Subcutaneous delivery investigation opens ambulatory care and home infusion revenue channels beyond acute settings. |
| Strategic Partnership | Regional purchasing organization contracts at Kaiser Permanente consolidate procurement volume and compress distributor margins. |
Research Methodology
Multi-period observation of door-to-needle time metrics, biosimilar EMA submission timelines, and NMPA priority review approvals anchored the trend analysis, supplemented by interviews with drug development executives at originator heritage firms, regulatory affairs leads navigating FDA pharmacovigilance requirements, formulary directors at integrated delivery networks, hospital procurement managers consolidating through regional GPOs, and payer access specialists managing DRG-based reimbursement. Secondary validation drew from FDA biologics license filings, EMA biosimilar comparability guidance documents, ClinicalTrials.gov tenecteplase protocol registrations, and hospital formulary database audits. Bottom-up patient volume modeling and top-down pharmaceutical market sizing triangulated demand estimates.
Input-output matrices mapped recombinant protein manufacturing capacity, cell culture media supply constraints, and emergency department protocol adoption rates across the projection horizon. Segmentation dimensions modeled administration route, clinical indication, site-of-care setting, patient population severity, and regional regulatory cluster complexity. CAGRs derived from slope analysis of historical biologics pricing erosion patterns and thrombolytic therapeutic window extension adoption curves. Forecast inputs incorporated CHO cell line availability indices and real-world bleeding outcome registry participation rates.
Plasma-derived raw material volatility, EMA biosimilar immunogenicity study requirement changes, and alteplase substitution acceleration in price-sensitive procurement are the dominant revision risks to demand assumptions. Forecasts reflect documented assumptions about protocol standardization velocity and regulatory pathway stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Decongestants Market
Pharmaceuticals
Depression Drugs Market
Pharmaceuticals
Pharmaceutical Wholesale & Distribution Market
Pharmaceuticals
Marburg Virus Disease Therapeutics Market
Pharmaceuticals
Gemcitabine HCL Market
Pharmaceuticals
Monkeypox Vaccine and Treatment Market
Pharmaceuticals
Global Central Nervous System (CNS) Stimulant Drugs Market
Pharmaceuticals
Emergency Contraceptive Pills Market
Pharmaceuticals
Global Benzodiazepines Market
Pharmaceuticals
Global Transdermal Drug Delivery Systems Market
Pharmaceuticals
Alopecia Drugs Market
Pharmaceuticals
Obsessive Compulsive Disorder (OCD) Drug Market
Pharmaceuticals
Global Electronic Aspirin Market
Pharmaceuticals
Global Female Contraceptive Market
Pharmaceuticals
Metaxalone Market
Pharmaceuticals
Germany Pharmaceutical Warehousing Market