
 Budesonide Market | 2026-2036
Budesonide Market Size, Share, and Industry Trends Forecast 2026-2036
Budesonide Market Analysis
The divergence between premium branded nebulization systems and commodity oral capsule supplies is realigning procurement strategies across hospital formularies. AstraZeneca leverages its respiratory portfolio depth to sustain channel control in metered-dose inhaler segments. Teva Pharmaceutical Industries anchors its position through vertical integration into active pharmaceutical ingredient sourcing for inhalation suspensions.
Budesonide is a non-halogenated glucocorticoid with a 16α, 17α-acetal ketal structure, formulated at potencies ranging from 0.25 mg/2 mL to 1 mg/2 mL for nebulization, primarily indicated for maintenance therapy in eosinophilic airway inflammation. The inhalation suspension segment dominates hospital procurement volumes due to its pediatric and acute-care applicability, while the nasal spray category competes on seasonal allergy cycle timing against newer antihistamine combinations. Metered-dose inhaler formulations occupy a mature margin pool where device patent cliffs determine generic substitution timing.
FDA bioequivalence requirements for orally inhaled products, EMA's MDR device classification rules, and India's CDSCO stability testing mandates collectively shape product development timelines and market access pathways. The EPA's residual solvent guidelines further constrain manufacturing process design for inhalation-grade batches. Stakeholders must monitor regulatory divergence between US particle size distribution standards and European cascade impactor protocols when planning multi-territory filing strategies.
Market Dynamics
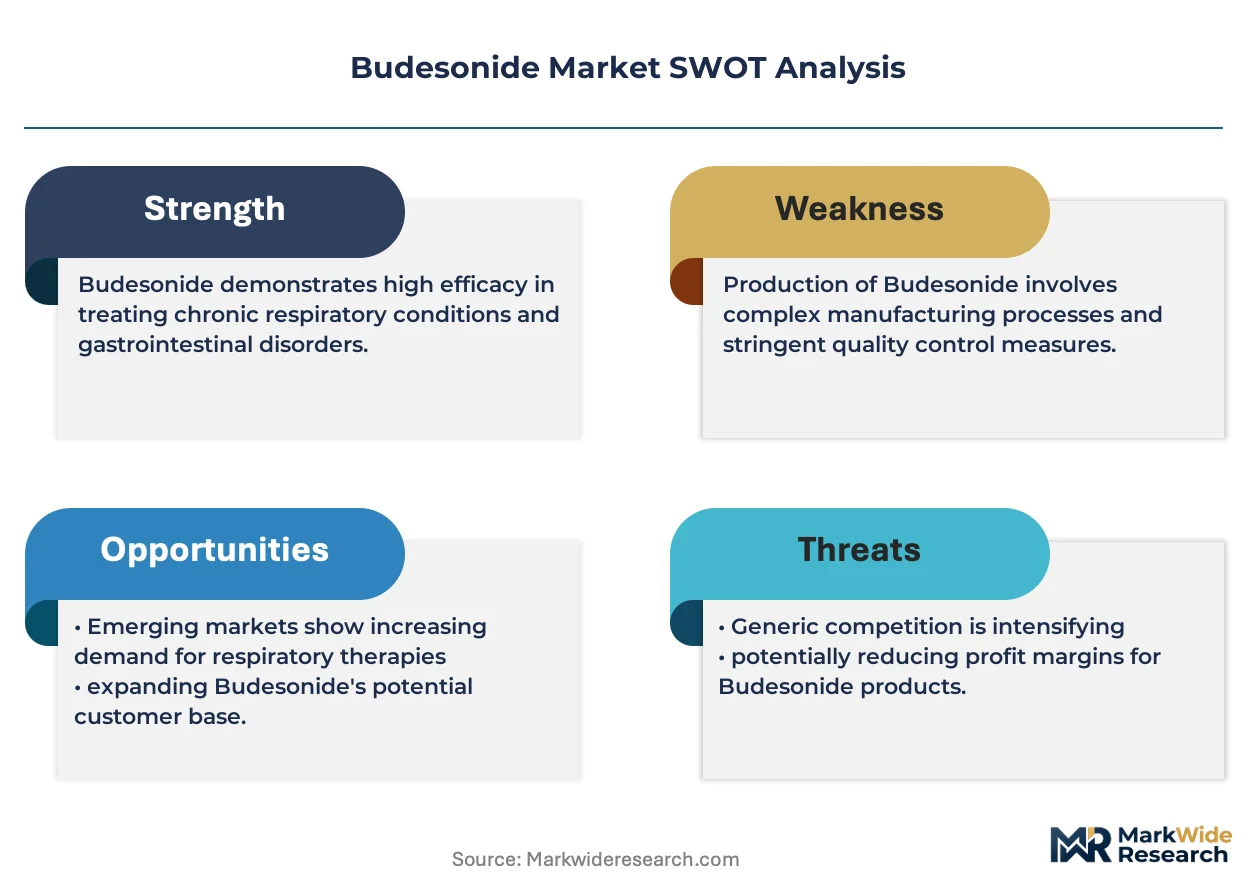
FDA bioequivalence standards for orally inhaled products are tightening particle size distribution requirements, forcing reformulation investments and delaying generic entry timelines across nebulized suspension portfolios.
Growth Catalysts
- Eosinophilic airway disease protocols:Pulmonology departments in United States hospital systems are expanding maintenance corticosteroid regimens for chronic asthma and COPD populations.
- REACH solvent guidelines:ECHA restrictions on residual manufacturing solvents are accelerating adoption of closed-loop processing systems for inhalation-grade API production.
- Pediatric nebulization demand:Acute-care facilities are prioritizing suspension formulations for children under five years unable to coordinate dry-powder inhaler use.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient production for inhalation-grade budesonide concentrates among three specialized manufacturers in India and China.
- Device-patent cliff timing:Metered-dose inhaler formulation margins compress when proprietary valve-actuator combinations lose exclusivity protection.
- Fluticasone substitution:Primary care prescribers in seasonal allergy segments increasingly favor combination antihistamine-steroid nasal sprays over budesonide monotherapy.
Strategic Opportunities
- Japan's geriatric COPD expansion:METI reimbursement incentives for home nebulization systems target the country's aging respiratory patient base.
- Smart inhaler convergence:Bluetooth-enabled dose-counters paired with nebulization devices enable remote monitoring integration into telehealth platforms.
- Brazil's ANVISA fast-track:Simplified bioequivalence pathways for essential medicines accelerate generic suspension entry into Latin America's largest hospital market.
Industry Challenges
- Cascade impactor technician scarcity:Specialized analytical chemists capable of performing aerodynamic particle size distribution testing remain concentrated in Western European and North American contract laboratories.
- Legacy nebulizer incompatibility:Hospital systems face capital replacement cycles when upgrading to breath-actuated devices requiring different viscosity formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Budesonide Market |
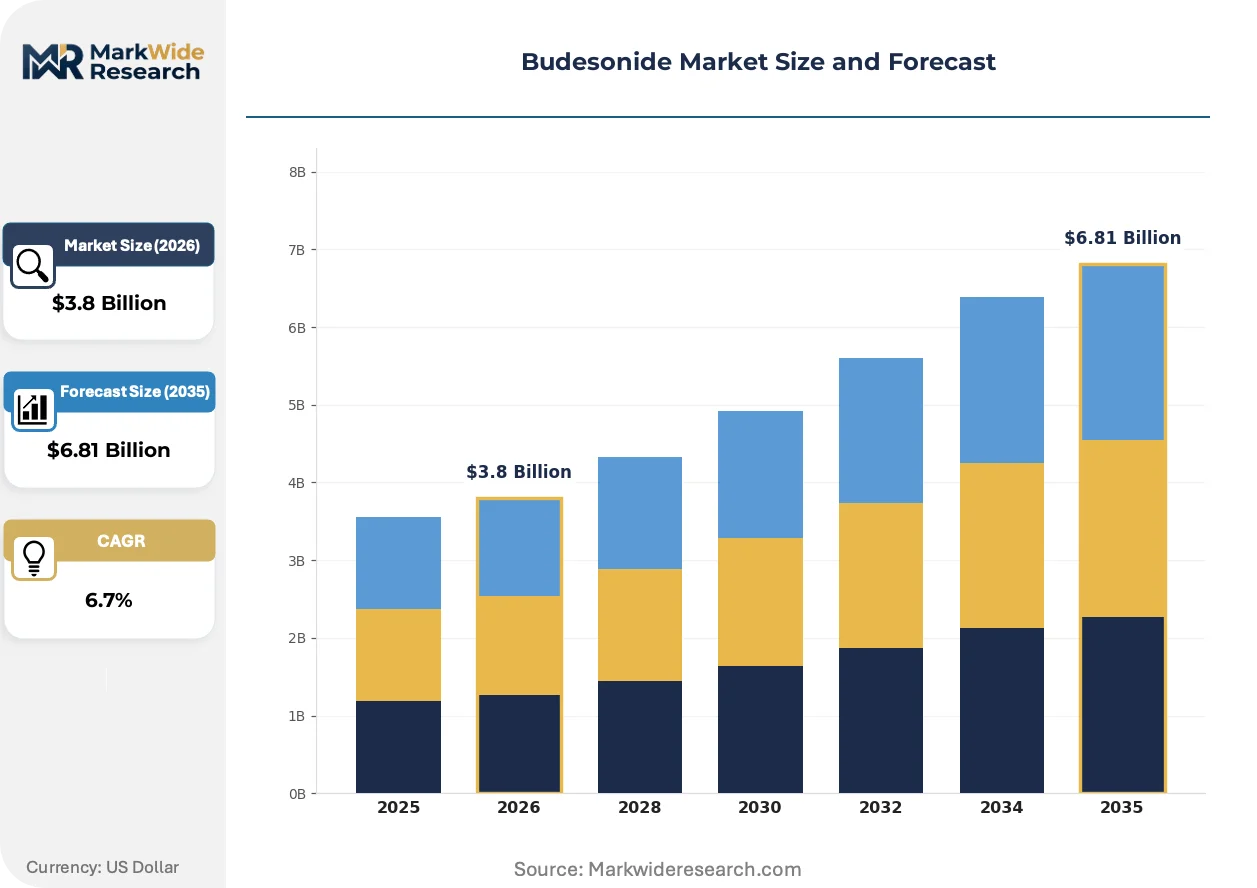
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inhalation Suspension, Nasal Spray, Oral Capsule, Metered-Dose Inhaler Application: Asthma, Allergic Rhinitis, Chronic Obstructive Pulmonary Disease, Ulcerative Colitis Delivery Mode: Nebulization, Intranasal, Oral, Inhalation End User: Hospitals, Clinics, Homecare, Pharmacies |
| Companies Covered | AstraZeneca, Teva Pharmaceutical Industries, Novartis AG, Cosmo Pharmaceuticals, Sandoz, Chiesi Farmaceutici, Cipla, Orion Corporation, Lupin Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Budesonide Market Emerging Trajectories
Formulation science and connected-device architectures are converging to reshape how maintenance corticosteroids deliver therapeutic value beyond mere drug deposition.
Lipid-based nanoparticle carriers are integrating hydrophobic budesonide into aqueous suspensions with enhanced pulmonary deposition profiles. Pediatric respiratory clinics in Germany and the Netherlands are piloting these formulations for severe asthma populations. The technology is integrating sustained-release kinetics that compress dosing frequency from twice-daily to once-daily regimens.
EMA's Medical Device Regulation reclassification of nebulizer systems as Class IIa or IIb devices imposes clinical evidence requirements previously absent for drug-device combinations. Manufacturers must now submit usability studies and human-factors validation for each new inhalation suspension pairing. Hospital procurement committees in France and Italy are responding by consolidating supplier relationships with firms holding dual drug-and-device regulatory competencies.
Direct-to-hospital consignment models are displacing traditional wholesale distribution for nebulized formulations. United States integrated delivery networks negotiate formulary placement through guaranteed minimum volume commitments rather than per-unit pricing. This restructuring concentrates purchasing power among three national GPOs while squeezing regional distributors from the inhalation suspension supply chain.
Budesonide Market Segmentation
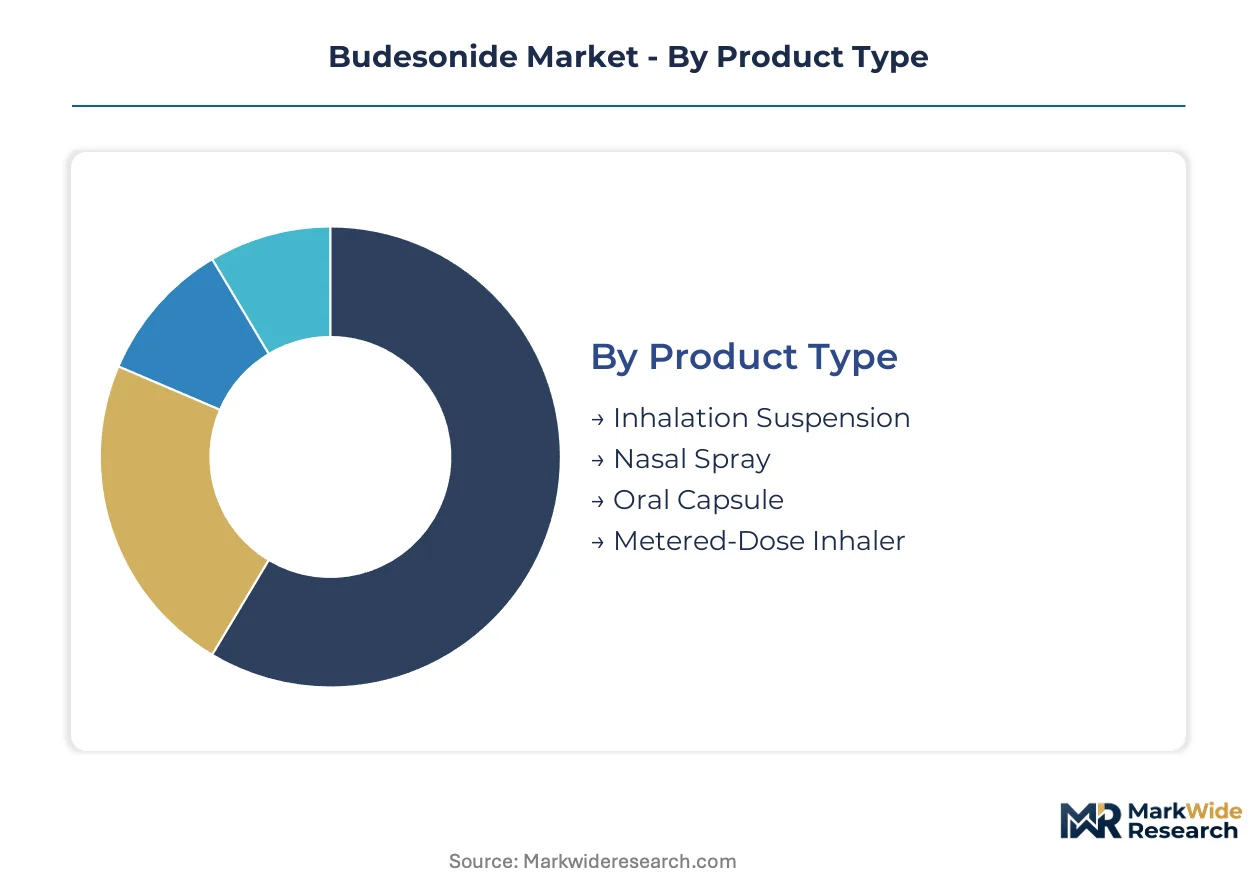
Budesonide formulation heterogeneity demands precise segmentation mapping. Each delivery architecture serves distinct patient populations with non-interchangeable clinical protocols and reimbursement pathways.
Product Type:
Standardization dominates inhalation suspensions for acute-care protocols, while customization pressures intensify around device-actuator combinations in portable formats.
- Inhalation Suspension:Aqueous formulations at 0.25 mg/2 mL to 1 mg/2 mL potencies deliver corticosteroid via jet or ultrasonic nebulizers. Hospital systems in the United States prioritize this format for pediatric and acute exacerbation cases where coordination-dependent devices fail. FDA bioequivalence tightening on particle size distribution sustains branded formulation premiums.
- Metered-Dose Inhaler:Pressurized canister systems suspend budesonide in hydrofluoroalkane propellant with proprietary valve-actuator engineering. Generic substitution accelerates when device patents expire, compressing margins in maintenance asthma segments.
- Nasal Spray:Aqueous suspensions for seasonal allergic rhinitis compete against fluticasone-antihistamine combinations in primary care prescribing.
- Oral Capsule:Enteric-coated formulations target distal ileum and colon for inflammatory bowel disease maintenance.
Most installed capacity flows through Inhalation Suspension. Expansion is steepest in Metered-Dose Inhaler as breath-actuated device innovation extends patent protection windows.
Application:
Volume concentration aligns with chronic disease prevalence and maintenance therapy duration rather than acute intervention frequency.
- Asthma:Maintenance corticosteroid protocols in eosinophilic airway inflammation represent the foundational demand pool. United States pulmonology departments expand nebulized suspension formularies for severe persistent cases.
- Chronic Obstructive Pulmonary Disease:Long-acting bronchodilator-corticosteroid combinations dominate maintenance, but budesonide monotherapy persists in acute exacerbation protocols.
- Allergic Rhinitis:Nasal spray formulations compete on seasonal timing against combination therapies.
- Ulcerative Colitis:Oral capsule demand concentrates in gastroenterology practices seeking steroid-sparing maintenance options.
Patient-month volumes concentrate in Asthma. Steepest prescription growth is occurring in Chronic Obstructive Pulmonary Disease as home nebulization expands.
Delivery Mode:
Device capital requirements and patient coordination capability create sharp segmentation boundaries between institutional and ambulatory settings.
- Nebulization:Jet and mesh nebulizer systems convert liquid suspension into respirable aerosol for patients lacking inhaler coordination. Pediatric and geriatric populations in acute-care facilities drive procurement volumes.
- Inhalation:Dry-powder and soft-mist devices serve maintenance populations with adequate manual dexterity and inspiratory flow rates.
- Intranasal:Pump-actuated spray mechanisms deliver topical corticosteroid for upper airway inflammation.
- Oral:Enteric-coated capsules bypass proximal absorption for distal gastrointestinal targeting.
Hospital procurement concentrates in Nebulization. Home-based expansion is climbing the fastest in Inhalation as breath-actuated devices simplify patient compliance.
End User:
Purchasing authority and reimbursement mechanism differentiate procurement behavior across institutional and retail channels.
- Hospitals:Integrated delivery networks negotiate nebulized suspension formularies through guaranteed volume commitments with national GPOs. EMA MDR device classification imposes new clinical evidence requirements on nebulizer system suppliers.
- Homecare:Durable medical equipment suppliers distribute compressor nebulizer systems with maintenance drug consignment. Japan METI reimbursement incentives target this channel for geriatric COPD populations.
- Clinics:Pulmonology and allergy practices prescribe portable inhaler formats with sample-driven initiation protocols.
- Pharmacies:Retail dispensing concentrates in nasal spray and oral capsule categories with direct patient cost-sharing exposure.
Procurement volume concentrates in Hospitals. Revenue expansion is gaining share fastest in Homecare as remote monitoring integration creates sticky device-drug ecosystems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized analytical chemists performing cascade impactor testing cluster in Western Europe and North America, creating regional bottlenecks for aerodynamic particle size validation. This workforce concentration shapes where multi-territory filing strategies originate and where manufacturing partnerships form.
United States
Pulmonology departments in hospital systems expand maintenance corticosteroid protocols for eosinophilic airway inflammation. FDA tightened bioequivalence standards for inhaled generics reshape competitive entry timelines. The Research Triangle Park cluster in North Carolina anchors contract analytical services for particle size distribution testing.
Germany
Pediatric respiratory clinics pilot lipid-based nanoparticle carriers for severe asthma populations. EMA Medical Device Regulation reclassification of nebulizer systems imposes clinical evidence requirements on drug-device combinations. The Rhine-Ruhr industrial corridor concentrates closed-loop processing system manufacturing for inhalation-grade API production.
India
Active pharmaceutical ingredient production for inhalation-grade budesonide concentrates among specialized manufacturers in Hyderabad and Ahmedabad. CDSCO stability testing mandates shape product development timelines for export-oriented facilities. The Mumbai-Pune pharmaceutical belt anchors backward integration into corticosteroid intermediate synthesis.
Japan
Home nebulization systems target the country's aging respiratory patient base through METI reimbursement incentives. PMDA alignment with FDA particle size distribution standards simplifies parallel filing strategies. The Kansai region around Osaka hosts device manufacturers developing Bluetooth-enabled dose-counters for telehealth integration.
Brazil
Simplified bioequivalence pathways for essential medicines accelerate generic suspension entry into Latin America's largest hospital market. ANVISA fast-track procedures concentrate regulatory expertise in São Paulo. The São Paulo state pharmaceutical corridor anchors regional distribution networks serving Mercosur hospital systems.
Budesonide Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the inhalation suspension value chain. The structure fragments between API manufacturers owning fermentation and chemical synthesis assets, formulation specialists controlling particle engineering capabilities, and device engineers holding nebulizer system patents. Three archetypes dominate: vertically integrated respiratory portfolio holders, generic suspension specialists with GPO contract depth, and dual drug-device competency firms navigating EMA MDR requirements. Competitive moves concentrate on strategic partnerships for cascade impactor testing access and capacity expansion into lipid-based nanoparticle formulation.
Among European-origin respiratory portfolio holders, AstraZeneca exemplifies the integrated archetype spanning metered-dose inhaler segments through device patent management. Teva Pharmaceutical Industries anchors the generic-specialist tier with captive supply chain structures for inhalation suspensions. Chiesi Farmaceutici occupies a position within the dual-competency cluster, navigating combined pharmaceutical and medical device regulatory pathways for nebulization systems.
| Leading Market Players |
|---|
| AstraZeneca |
| Teva Pharmaceutical Industries |
| Novartis AG |
| Cosmo Pharmaceuticals |
| Sandoz |
| Chiesi Farmaceutici |
| Cipla |
| Orion Corporation |
| Lupin Limited |
| Others |
Supply Flow & Price Mechanics
EPA residual solvent guidelines gate qualified supply for inhalation-grade batches and premium-tier pricing access. Manufacturers investing in closed-loop processing systems command formulation premiums while commodity oral capsule suppliers compete on volume scale.
Pricing Analysis
Bundled device-drug consignment models separate from unbundled API commodity transactions. Three-tier pricing structure across premium, standard, and economy levels reflects FDA bioequivalence certification status and particle size distribution validation. Pricing pressure stems from metered-dose inhaler patent cliffs accelerating generic substitution. Hospital GPOs exhibit lowest price sensitivity due to guaranteed volume commitments, while retail pharmacies face direct patient cost-sharing exposure.
Supply Chain Analysis
Cold-chain logistics and temperature-controlled freight costs constrain distribution radius for aqueous suspension formulations. Active pharmaceutical ingredient production concentrates in India and China, with specialized manufacturers in Hyderabad and Ahmedabad anchoring inhalation-grade supply. Formulation science inputs draw from corticosteroid intermediate synthesis and lipid-based nanoparticle carrier technologies. Single-source vulnerability persists for cascade impactor testing services concentrated in Western European and North American contract laboratories. Distribution runs through direct-to-hospital consignment models displacing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Budesonide Market functions as a stable compounder anchored by chronic airway disease maintenance protocols that generate recurring prescription volumes regardless of economic cycles.
For Market Incumbents: Deploy device patent lifecycle management to extend exclusivity windows for metered-dose inhaler formulations. Deepen backward integration into inhalation-grade API production to offset supply concentration risk from Indian and Chinese manufacturers. Secure dual drug-and-device regulatory competencies to navigate EMA MDR reclassification requirements for nebulizer systems. For New Entrants and Emerging Players: Enter via Brazil's ANVISA fast-track pathway for essential medicines generic suspensions. Target Japan's home nebulization segment where METI reimbursement incentives create accessible entry points. Pursue Bluetooth-enabled dose-counter integration as a differentiated go-to-market angle for telehealth platform partnerships. For Investors and Strategic Acquirers: Roll-up economics work for generic suspension specialists with GPO contract depth because hospital procurement consolidation concentrates purchasing power among three national networks. The five-to-ten year viability window favors manufacturers with captive particle engineering capabilities. Watch FDA bioequivalence guidance revisions as the inflection signal for generic entry timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Lipid-Based Nanoparticle Formulation Development | Pediatric respiratory clinics in Germany pilot enhanced pulmonary deposition profiles for severe asthma populations. |
| Bluetooth-Enabled Dose-Counter Integration | Telehealth platform partnerships in Japan's Kansi region enable remote monitoring for geriatric COPD patients. |
| EMA MDR Dual Competency Certification | Hospital procurement committees in France and Italy consolidate supplier relationships with combined drug-device regulatory expertise. |
| Direct-to-Hospital Consignment Model Expansion | United States integrated delivery networks negotiate formulary placement through guaranteed minimum volume commitments. |
| Cascade Impactor Testing Capacity Investment | Research Triangle Park cluster in North Carolina anchors contract analytical services for FDA particle size distribution validation. |
Methodological Framework
Bottom-up hospital formulary modeling reconciled against top-down API production tracking forms the analytical core of this study. Primary interviews with pulmonology department heads, hospital procurement managers, GPO contracts specialists, and regulatory affairs directors combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Triangulation between demand-side prescription volume analysis and supply-side manufacturing capacity assessments ensures cross-verified outputs.
Input-output matrix framing connects patient population prevalence to formulation production volumes across the projection horizon. Segmentation dimensions include delivery mode, application, end-user channel, and regional regulatory cluster. CAGRs derive from patient-month volume trajectories, dosing frequency assumptions, and price index movements. Forecast inputs incorporate EMA MDR implementation timelines and FDA bioequivalence guidance evolution.
Inputs from FDA and EMA regulatory databases were available through the study window; gaps in real-time hospital procurement transaction data introduce uncertainty bands around volume estimates. Forecasts reflect assumptions about chronic disease prevalence stability and reimbursement policy continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Ampicillin Drugs Market
Pharmaceuticals
Spain OTC Drugs Market
Pharmaceuticals
Global Self-Administered Drugs Market
Pharmaceuticals
Europe Dipeptide Peptidase 4 (DPP-4) Inhibitors Market
Pharmaceuticals
Middle East and Africa Gastrointestinal Drugs Market
Pharmaceuticals
Adapalene Market
Pharmaceuticals
Acetaminophen Injection Market
Pharmaceuticals
Global Interleukin Inhibitors Market
Pharmaceuticals
Global Atosiban Market
Pharmaceuticals
Vutrisiran Market
Pharmaceuticals
Dyslipidemia Therapeutics Market
Pharmaceuticals
Anti-Arrhythmic Drugs Market
Pharmaceuticals
Musculoskeletal Disorders Drugs Market
Pharmaceuticals
Global Vero Cell Rabies Vaccine Market
Pharmaceuticals
Anthelmintic Drugs Market
Pharmaceuticals
Global Pharmaceutical Warehousing Market