
 Hydroxypropyl Methylcellulose (HPMC) Capsules Market | 2026-2036
Hydroxypropyl Methylcellulose (HPMC) Capsules Market Size, Share, and Industry Trends Forecast 2026-2036
Hydroxypropyl Methylcellulose (HPMC) Capsules Market Foresight
Pharmaceutical formulation chemists is rotating toward HPMC capsule expertise as vegan and halal certification requirements expand across prescription and over-the-counter portfolios. Lonza leverages its integrated excipient-to-capsule platform to secure long-term supply agreements with multinational drug makers. ACG Worldwide anchors South Asian production capacity through vertically controlled cellulose ether sourcing. Suheung competes in East Asian markets with specialized enteric-coating capabilities for acid-sensitive APIs.
Hydroxypropyl methylcellulose capsules consist of a semi-synthetic polymer derived from alkali-treated cellulose etherified with propylene oxide and methyl chloride, yielding film-forming shells with dissolution profiles tunable between pH 1.2 and 6.8 buffers. Hard capsules dominate current volume as oral solid dosage forms retain preference for immediate-release formulations across chronic disease therapies. Nutraceutical applications represent the fastest-expanding segment, driven by probiotic and enzyme formulations requiring moisture-barrier properties superior to gelatin. Contract manufacturers occupy the most concentrated margin pool within end-user channels, converting bulk capsule purchases into finished blister-packaged products for brand owners.
FDA dissolution testing protocols and EMA guidelines on excipient qualification shape material selection criteria for new drug applications, while India's CDSCO mandates BIS certification for imported capsule shells used in domestic formulations. The EU Green Deal chemical sustainability targets are pressuring manufacturers to document renewable feedstock ratios in HPMC supply chains. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and IP standards to anticipate qualification cost shifts.
Market Dynamics
Pharmaceutical formulators are migrating en masse from gelatin to HPMC shells as vegan certification and religious dietary compliance harden from preference to procurement mandate, compressing qualification timelines and rewiring excipient supply relationships.
Growth Catalysts
- EMA excipient qualification guidelines:European regulators now require documented allergen-free supply chains for capsule components, accelerating HPMC substitution in pediatric and geriatric formulations.
- India's CDSCO BIS certification mandate:Domestic manufacturers must source certified HPMC shells for export-bound products, creating captive demand from Mumbai and Hyderabad formulation clusters.
- Moisture-barrier performance:Probiotic and enzyme nutraceuticals require sub-5% moisture vapor transmission rates that gelatin cannot achieve, pulling HPMC into functional food applications.
Market Restraints
- Cellulose ether supply concentration:Alkali-treated cellulose feedstock for HPMC production clusters in Chinese and Indian chemical parks, exposing formulators to regional environmental shutdown risks.
- Propylene oxide price volatility:This etherification reagent fluctuates with petrochemical feedstock costs, compressing margin predictability for capsule shell converters.
- Gelatin cost advantage in mature markets:Bovine and porcine gelatin retains 30-40% price discount in non-regulated nutraceutical segments, delaying HPMC penetration in price-sensitive channels.
Strategic Opportunities
- East Asian enteric coating demand:Japan's PMDA and South Korea's MFDS are tightening acid-resistance standards for proton pump inhibitor formulations, opening specialized HPMC-P capsule grades.
- EU Green Deal chemical sustainability targets:Renewable feedstock documentation requirements favor HPMC producers with certified cellulose sourcing against petroleum-derived alternatives.
- Direct-to-consumer nutraceutical channels:Subscription vitamin services require vegetarian-certified packaging claims that HPMC enables, bypassing traditional pharmacy distribution.
Industry Challenges
- Pharmacopeial harmonization gaps:USP, EP, and IP dissolution testing protocols diverge on HPMC shell qualification criteria, forcing redundant validation studies for multi-territory filings.
- Specialized polymer chemistry expertise:Formulation chemists with HPMC shell rheology and film-forming knowledge remain scarce relative to gelatin-trained talent pools.
- Legacy blister-line retrofit costs:Gelatin-optimized packaging equipment requires humidity-control modifications to handle HPMC's different moisture sensitivity profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydroxypropyl Methylcellulose (HPMC) Capsules Market |
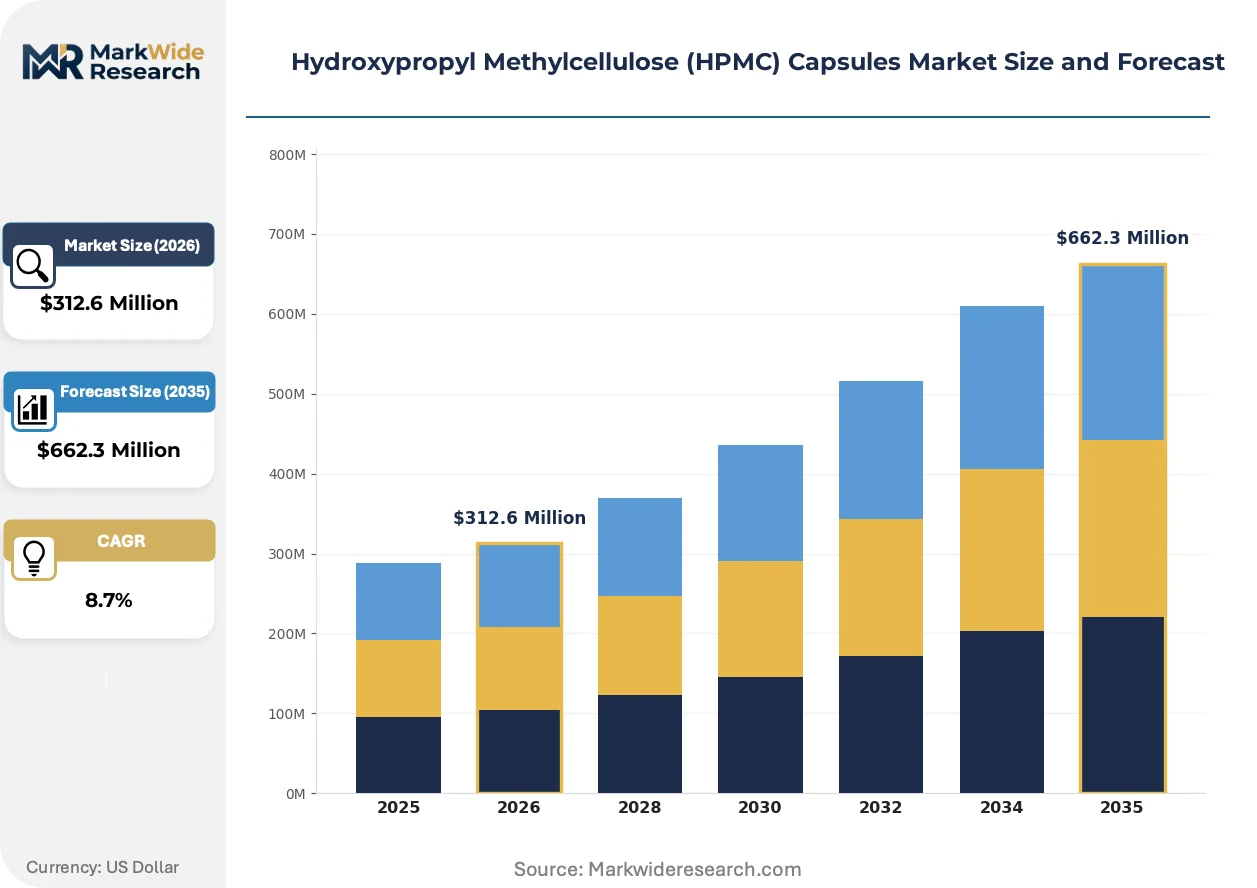
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $662.3 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Capsules, Soft Capsules, Liquid Capsules, Sprinkle Capsules Application: Nutraceuticals, Pharmaceuticals, Dietary Supplements, Cosmetics End User: Pharmacies, Online Retailers, Hospitals, Contract Manufacturers Distribution Channel: Direct Sales, Distributors, E-commerce, Wholesale |
| Companies Covered | ACG Worldwide, CapsCanada Corporation, Lonza, Qualicaps, Suheung, Sunil Healthcare, Natural Capsules, Healthcaps India, Bright Pharma Caps, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydroxypropyl Methylcellulose (HPMC) Capsules Market Shifts & Advancements
Manufacturing technology and regulatory documentation standards are converging to redefine competitive advantage in capsule supply, with material science differentiation displacing pure scale economics.
Pre-gelatinized HPMC grades with built-in gelling agents are supplanting traditional two-piece shell constructions in high-speed encapsulation lines. Contract manufacturers serving Big Pharma are adopting these grades to eliminate separate gelling-step equipment. This technology is supplanting conventional HPMC-AS variants in pH-dependent release formulations.
REACH chemical safety dossier requirements are compelling European capsule suppliers to submit full toxicological profiles for propylene oxide residuals. The industrial consequence is a qualification bottleneck for smaller Asian exporters. Multinational drug makers are responding by consolidating supplier panels to three qualified vendors with complete ECHA registration packages.
Long-term supply agreements now dominate procurement for HPMC capsules, with pharmaceutical procurement teams locking five-year contracts to secure vegetarian-certified capacity. This behavior is displacing spot-market purchasing that characterized gelatin shell buying. The shift is most visible in German and Swiss generic drug houses securing supply from Indian vertically integrated producers.
Hydroxypropyl Methylcellulose (HPMC) Capsules Market Segmentation
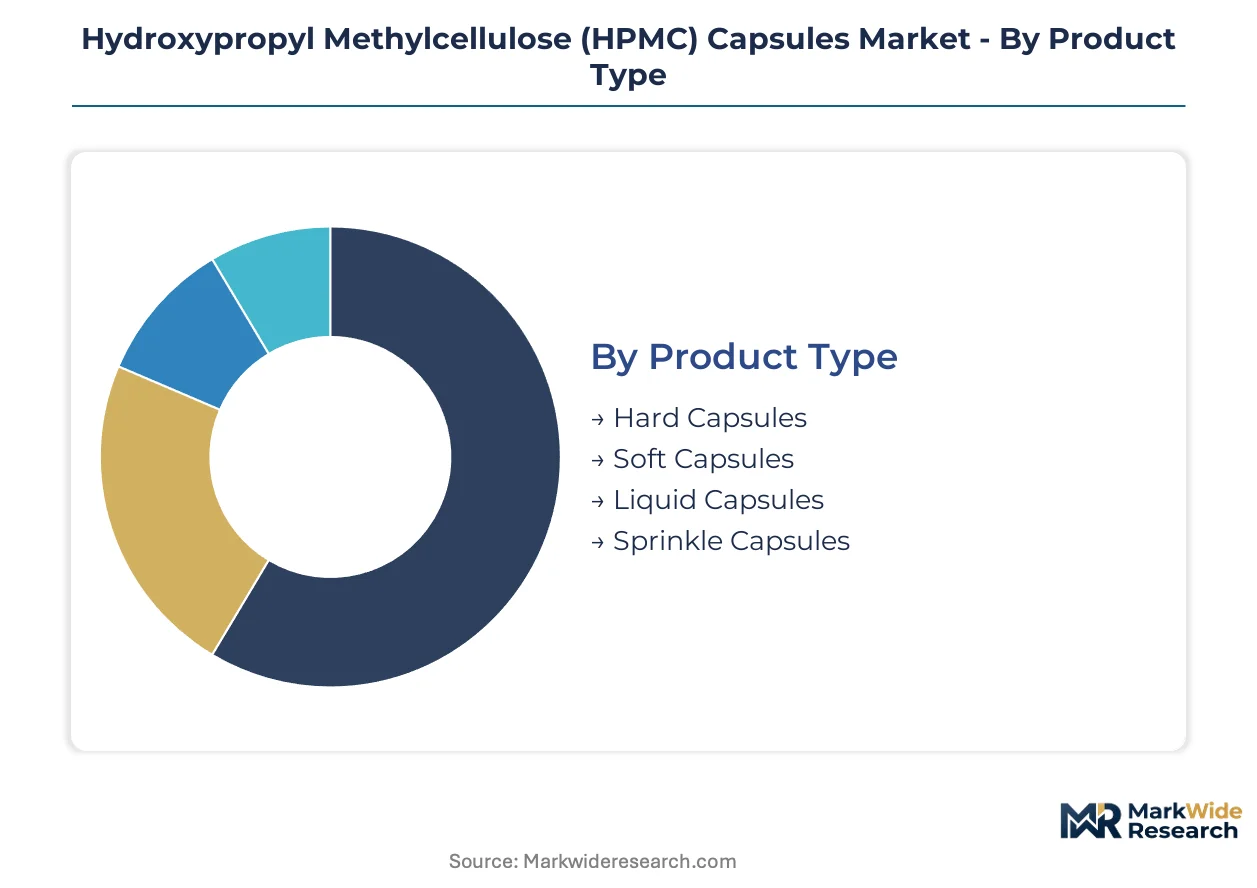
Segmentation in the HPMC capsules market reveals how substitution pressures from gelatin alternatives reshape competitive dynamics across product formats and customer channels. Each dimension carries distinct margin profiles and qualification barriers that determine supplier positioning.
Product Type:
Hard capsules face the most intense substitution threat as gelatin-optimized filling equipment requires costly humidity retrofits, while soft capsule converters exploit HPMC's film-forming advantages for oil-based formulations.
- Hard Capsules:Two-piece shells constructed from HPMC polymer blends with gelling agents enable high-speed encapsulation on legacy gelatin lines with modified environmental controls. Pharmaceutical manufacturers in Germany and Switzerland concentrate procurement here for immediate-release oral solid dosages, driven by EMA allergen-free mandates tightening qualification timelines.
- Soft Capsules:Seamless rotary-die shells exploit HPMC's superior oxygen barrier properties for lipid-soluble APIs and omega-3 nutraceuticals. Demand clusters with Japanese and South Korean contract manufacturers serving proton pump inhibitor formulations, constrained by PMDA and MFDS acid-resistance standards that HPMC-P grades satisfy.
- Liquid Capsules:Single-unit reservoirs for hydrophilic drug solutions requiring precise fill-volume accuracy.
- Sprinkle Capsules:Pull-apart shells designed for pediatric and geriatric populations needing dose titration flexibility.
Hard capsules anchor the volume base while soft capsules gain share at the steepest rate.
Application:
Cost-tier stratification separates premium-certified pharmaceutical grades from economy nutraceutical variants, with certification documentation driving price spreads.
- Pharmaceuticals:Prescription drug applications demand USP-NF, EP, and IP pharmacopeial compliance with full supply chain traceability for IND and NDA filings. Multinational drug makers in Basel and Frankfurt lock five-year supply agreements for vegetarian-certified capacity, constrained by FDA dissolution protocol validation requirements.
- Nutraceuticals:Probiotic, enzyme, and botanical formulations leverage HPMC's sub-5% moisture vapor transmission rates that gelatin cannot achieve. Subscription vitamin services in direct-to-consumer channels require packaging claims bypassing traditional pharmacy distribution, climbing the fastest as functional food applications expand.
- Dietary Supplements:Over-the-counter wellness products with halal and kosher certification requirements.
- Cosmetics:Topical and ingestible beauty formulations requiring shell stability in humid climates.
Pharmaceuticals dominate revenue concentration while nutraceuticals expand most quickly.
End User:
Customer-type concentration determines margin capture, with contract manufacturers converting bulk purchases into finished packaged products commanding the most concentrated profit pools.
- Contract Manufacturers:CDMOs and CMOs serving Big Pharma consolidate procurement through long-term supply agreements, integrating HPMC capsule filling into turnkey formulation services. Mumbai and Hyderabad clusters anchor South Asian production capacity for export-bound products, shaped by CDSCO BIS certification mandates.
- Pharmacies:Retail and hospital dispensaries sourcing finished blister-packaged medications.
- Hospitals:Institutional procurement of unit-dose formulations for inpatient administration.
- Online Retailers:Direct-to-consumer platforms for nutraceutical subscription services.
Contract manufacturers capture the deepest margins while online retailers expand fastest.
Distribution Channel:
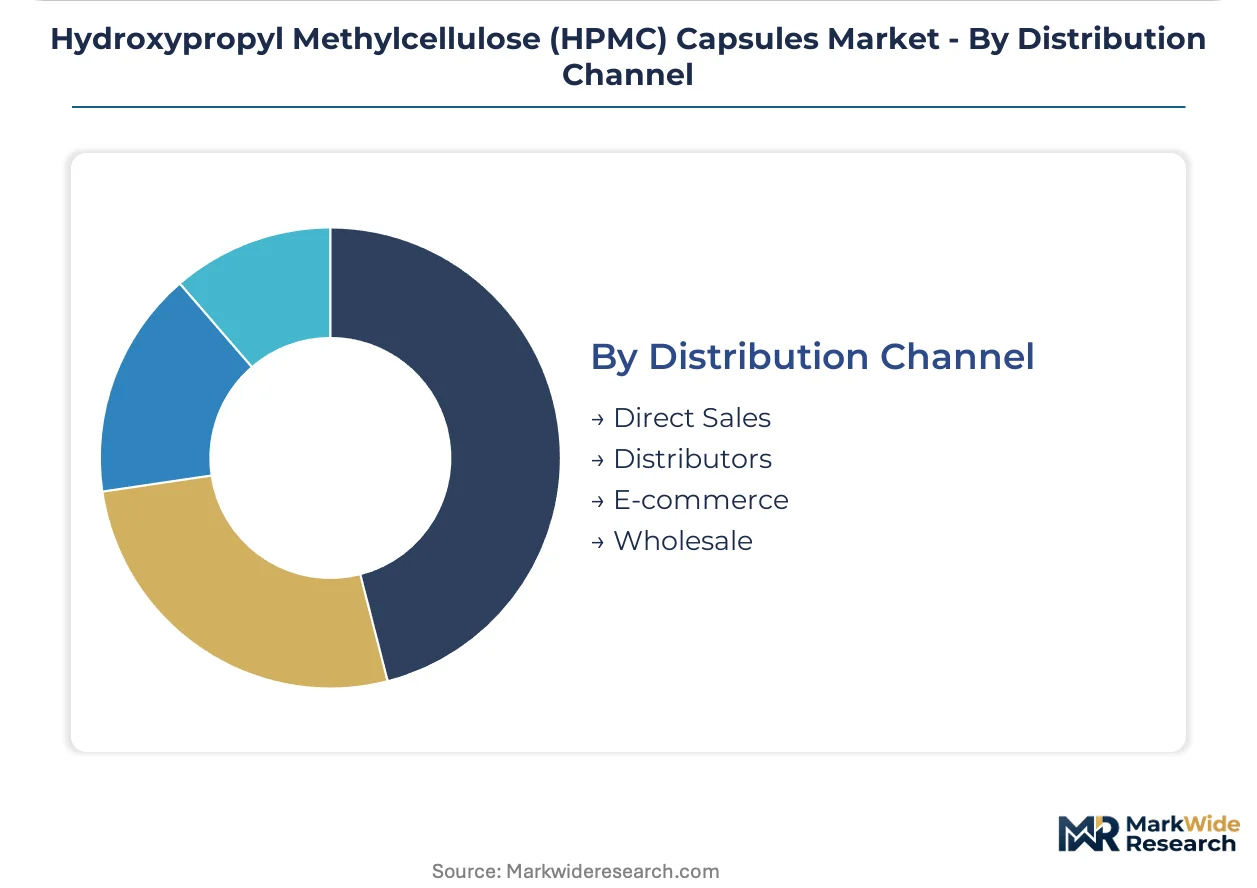
Supply concentration in direct sales relationships reflects the technical qualification burden that disqualifies arm's-length transactions.
- Direct Sales:Pharmaceutical procurement teams negotiate directly with vertically integrated HPMC shell producers for certified capacity allocation. Lonza and ACG Worldwide anchor this channel through integrated excipient-to-capsule platforms, with technical service agreements spanning dissolution profile customization.
- Distributors:Regional intermediaries serving mid-tier nutraceutical formulators.
- E-commerce:Digital procurement platforms for small-batch nutraceutical startups.
- Wholesale:Volume aggregation for generic drug houses with standardized specifications.
Direct sales commands the qualification-intensive premium segment while e-commerce grows fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA dissolution protocols and EMA allergen-free mandates anchor demand concentration in the United States and Germany, while India's CDSCO certification requirements reshape supply chain geography for export-oriented capsule production.
United States
Multinational drug makers in New Jersey and Massachusetts accelerate HPMC substitution for pediatric and geriatric portfolios as FDA tightens cross-contamination documentation. USP-NF pharmacopeial compliance requirements compress qualification timelines for new drug applications. The Greater Boston biotech cluster drives specialized demand for moisture-barrier capsules in probiotic formulations.
Germany
REACH chemical safety dossiers compel capsule suppliers to submit full toxicological profiles for propylene oxide residuals, filtering smaller exporters from procurement panels. Generic drug houses in Frankfurt and Basel lock five-year supply agreements to secure vegetarian-certified capacity. The Rhine-Main region concentrates technical service agreements spanning dissolution profile customization.
India
CDSCO mandates BIS certification for imported capsule shells used in domestic formulations, creating captive demand from Mumbai and Hyderabad manufacturing clusters. Vertically integrated producers control alkali-treated cellulose feedstock through captive chemical park operations. The Telangana formulation corridor serves export-bound contract manufacturing for European and North American brand owners.
Japan
PMDA acid-resistance standards for proton pump inhibitor formulations pull specialized HPMC-P capsule grades into commercial production. Pharmaceutical procurement teams in Tokyo and Osaka prioritize suppliers with complete ECHA-equivalent registration packages. The Kansai region hosts technical partnerships between shell converters and enteric-coating technology specialists.
Switzerland
Swissmedic guidelines on excipient traceability align with EMA allergen-free mandates, favoring HPMC over gelatin in prescription portfolios. Basel-based multinational headquarters consolidate supplier panels to three qualified vendors with documented renewable feedstock ratios. The Swiss-German border region anchors logistics hubs for just-in-time capsule delivery to Alpine formulation facilities.
Hydroxypropyl Methylcellulose (HPMC) Capsules Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated excipient-to-capsule platforms commanding premium positioning and regional chemical converters capturing volume tiers. The vendor base separates into three strategic clusters: multinational platform operators with pharmacopeial harmonization capabilities, Asian vertically integrated producers with captive cellulose ether supply, and specialized coating technology houses serving acid-sensitive formulations. Competitive dynamics center on long-term supply agreement duration and ECHA registration package completeness rather than spot-price competition.
Among platform-integrated multinationals, Lonza and ACG Worldwide exemplify archetypes that combine excipient manufacturing with finished shell production. Suheung occupies a position within the specialized coating tier. These three anchors illustrate how competitive positioning fragments across technology depth, geographic production density, and regulatory documentation breadth rather than converging on single-axis scale advantages.
| Leading Market Players |
|---|
| ACG Worldwide |
| CapsCanada Corporation |
| Lonza |
| Qualicaps |
| Suheung |
| Sunil Healthcare |
| Natural Capsules |
| Healthcaps India |
| Bright Pharma Caps |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts lock in both HPMC capsule supply access and price visibility for multinational drug makers navigating EMA allergen-free mandates and FDA dissolution protocol requirements. These agreements displace spot-market purchasing that characterized gelatin shell procurement, compressing margin predictability for converters while securing vegetarian-certified capacity allocation.
Pricing Analysis
Indian and Chinese HPMC capsule exports trade at 15-25% discounts to European-manufactured equivalents, though BIS certification and REACH dossier completeness erode this spread. Pricing stratifies across pharmaceutical-grade certified, nutraceutical-standard, and economy unbranded tiers, with certification documentation driving the widest spreads. Cost compression in economy nutraceutical channels intensifies as gelatin retains 30-40% price advantages, while pharmaceutical buyers show limited price sensitivity due to regulatory qualification lock-in. Contract manufacturers serving Big Pharma face the least price pressure; direct-to-consumer nutraceutical startups exhibit the highest.
Supply Chain Analysis
Alkali-treated cellulose feedstock concentration in Chinese and Indian chemical parks creates single-source vulnerability for HPMC polymer production. Propylene oxide etherification reagents and methyl chloride catalysts draw from petrochemical complexes in Shandong and Gujarat, exposing converters to regional environmental shutdown directives. Tariff exposure on cellulose ether imports into the EU compounds cost unpredictability. Distribution runs through direct technical service agreements between vertically integrated shell producers and pharmaceutical procurement teams, bypassing arm's-length wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
HPMC capsule demand is recovering from cyclical compression as pharmaceutical formulators restock vegetarian-certified inventory following EMA guideline implementation. The cyclical driver is regulatory mandate conversion from preference to procurement requirement.
For Market Incumbents: Consolidate supplier panels to three qualified vendors with complete ECHA registration packages, mirroring Lonza's integrated excipient-to-capsule platform strategy. Backward integration into alkali-treated cellulose feedstock secures margin control against Chinese environmental shutdown risks. Lock five-year supply agreements with Mumbai and Hyderabad contract manufacturers before CDSCO certification mandates tighten further. For New Entrants and Emerging Players: Differentiate on enteric-coating technology for acid-sensitive APIs, exploiting PMDA and MFDS standards that HPMC-P grades satisfy. The most penetrable white-space sits in East Asian proton pump inhibitor formulations where specialized coating capabilities remain scarce. Target direct-to-consumer nutraceutical subscription services requiring vegetarian-certified packaging claims that bypass traditional pharmacy distribution. For Investors and Strategic Acquirers: Specialized coating technology houses with ECHA-equivalent registration packages present the strongest acquisition profile for exposure to HPMC-P demand inflection. Long-term viability hinges on pharmacopeial harmonization progress between USP, EP, and IP standards. The signal to watch is FDA dissolution testing protocol revisions that could accelerate multi-territory qualification cost shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Locks vegetarian-certified capacity for Basel and Frankfurt generic drug houses. |
| Backward Integration | Captures alkali-treated cellulose supply through Indian chemical park operations. |
| REACH Dossier Completion | Filters smaller Asian exporters from European procurement panels. |
| Enteric Coating Technology | Addresses PMDA acid-resistance standards for proton pump inhibitor formulations. |
| Direct-to-Consumer Channel | Bypasses traditional pharmacy distribution for nutraceutical subscription services. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with formulation chemists, regulatory affairs leads at CDMOs, procurement managers at multinational drug makers, and excipient technical directors; and secondary validation through FDA filings, EMA submission databases, USP-NF monographs, and CDSCO BIS certification records. Bottom-up capsule volume estimates from Indian and Chinese production clusters were triangulated against top-down pharmaceutical dosage form forecasts.
Across the projection horizon, the analytical framework modeled segmentation across product type, application, end-user channel, and regional regulatory cluster. CAGRs were derived from growth rate convergence analysis applied to HPMC substitution trajectories in gelatin-displacing formulations. Forecast inputs incorporated EMA excipient qualification timeline compression and India's CDSCO certification mandate enforcement patterns.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of allergen-free mandates would require recalibration. Forecasts reflect assumptions about pharmacopeial harmonization progress and cellulose ether supply stability. Practitioners should keep alternative scenarios live as REACH chemical safety dossier requirements and EU Green Deal feedstock documentation standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Dementia Drugs Market
Pharmaceuticals
Global Peptide Cancer Vaccine Market
Pharmaceuticals
Anti-Inflammatory Analgesic and Antipyretic Drugs Market
Pharmaceuticals
Global Anti-Suicide Drugs Market
Pharmaceuticals
Vascular Endothelial Growth Factor (VEGF) Antibodies Market
Pharmaceuticals
Anti-Inflammatory Biologics Market
Pharmaceuticals
US Intravenous Immunoglobulin Market
Pharmaceuticals
Cryptococcosis Therapeutics Market
Pharmaceuticals
Asia-Pacific Sodium-Dependent Glucose Cotransporter 2 (SGLT-2) Market
Pharmaceuticals
Global Thyroid Cancer Drugs Market
Pharmaceuticals
Vascular Endothelial Growth Factor (VEGF) Inhibitors Market
Pharmaceuticals
North America Glucagon-Like Peptide-1 Agonists Market
Pharmaceuticals
Liver Fibrosis Drugs Market
Pharmaceuticals
Europe Diabetes Drugs Market
Pharmaceuticals
Middle East and Africa Adenomyosis Drugs Market
Pharmaceuticals
Cough Suppressant Drugs Market