
 Eisenmenger Syndrome Treatment Market | 2026-2036
Eisenmenger Syndrome Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Eisenmenger Syndrome Treatment Market Foresight
Targeted prostacyclin analog formulations are redrawing competitive boundaries in Eisenmenger syndrome care. Actelion Pharmaceuticals leverages vertical integration across its pulmonary arterial hypertension portfolio to sustain supply chain reliability for complex infused therapies. Pfizer competes through manufacturing scale in oral endothelin receptor antagonists, while United Therapeutics anchors its position with in-house production of treprostinil-based delivery systems.
Eisenmenger syndrome constitutes an advanced form of pulmonary arterial hypertension arising from uncorrected congenital cardiac shunts, characterized by reversed intracardiac or great vessel shunting with systemic-level pulmonary vascular resistance exceeding 10 Wood units and fixed cyanosis. Its primary clinical purpose centers on preventing right heart failure, paradoxical embolism, and progressive hypoxemia in adult congenital heart disease populations. Medications dominate current value generation across oral, injectable, and inhalation delivery modes, with prostacyclin pathways capturing concentrated margin pools; catheter interventions represent the fastest-growing structural segment as interventional cardiologists expand transcatheter closure feasibility in carefully selected patients with preserved pulmonary vascular reactivity.
The FDA's orphan drug program and EMA's incentives for rare disease therapeutics shape development economics and exclusivity timelines for Eisenmenger syndrome innovators. Reimbursement pathways under Medicare in the United States and national health technology assessment processes in Germany and France determine patient access to high-cost chronic therapies. Stakeholders must monitor evolving pulmonary hypertension guideline revisions and their impact on treatment escalation protocols across referral networks.
Market Dynamics
Specialty clinic consolidation around adult congenital heart disease referral centers is concentrating treatment decisions into fewer high-volume institutions, amplifying purchasing power and accelerating protocol standardization for prostacyclin-based therapies.
Growth Catalysts
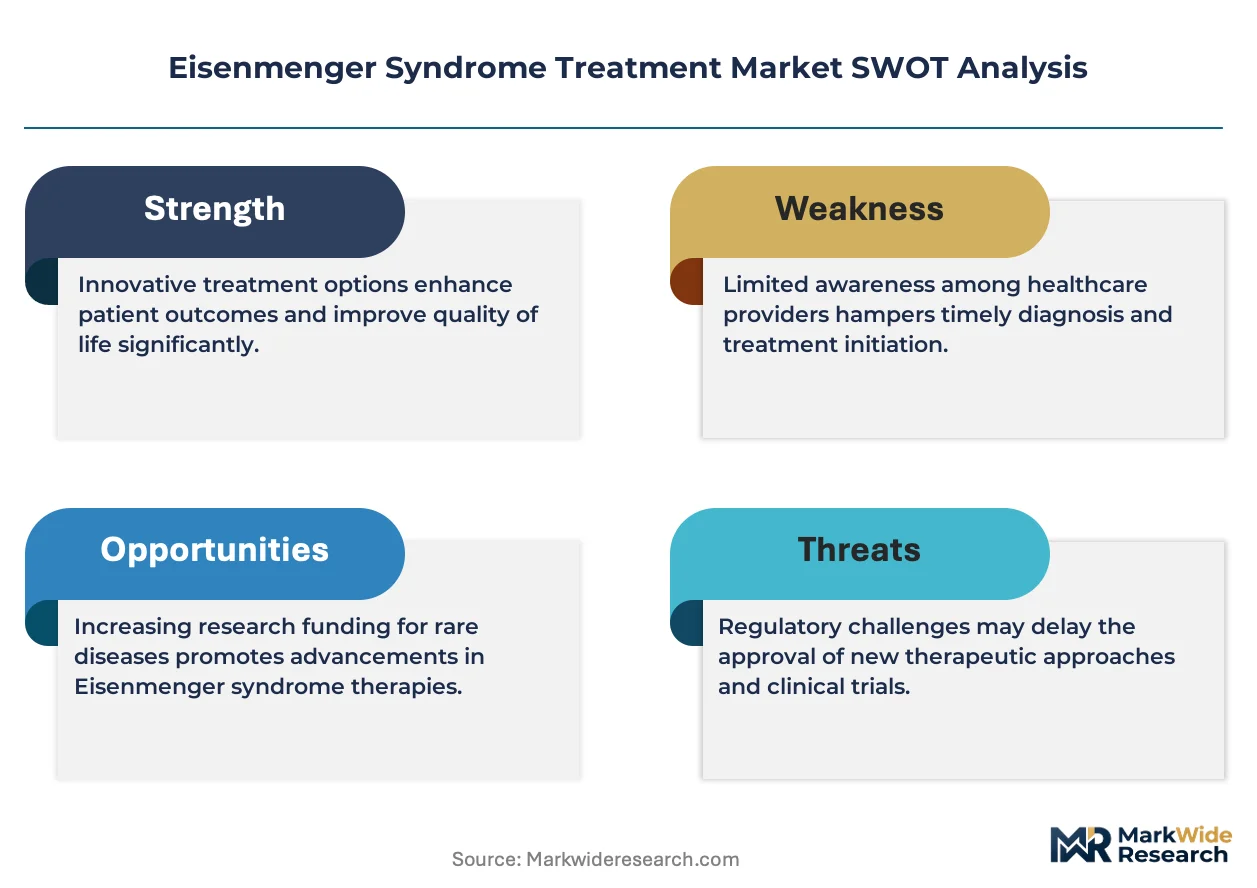
- FDA Orphan Drug Designation:The framework grants seven-year market exclusivity and tax credits for clinical trials, incentivizing developers to prioritize Eisenmenger syndrome within broader pulmonary arterial hypertension pipelines.
- Catheter intervention advances:Transcatheter closure feasibility assessments using vasoreactivity testing are expanding the addressable patient pool beyond pure medical management in tertiary care centers.
- Germany's national health technology assessment:IQWiG evaluation pathways for rare disease therapies are streamlining reimbursement for high-cost chronic treatments in Europe's largest pharmaceutical market.
Market Restraints
- Prostacyclin analog production concentration:Complex synthesis requirements for treprostinil and epoprostenol limit active pharmaceutical ingredient suppliers to a handful of specialized contract manufacturers.
- Medicare bundled payment constraints:Prospective payment systems for outpatient infusion services compress margins on high-touch parenteral therapy administration.
- Fixed pulmonary vascular resistance:Irreversible vascular remodeling in long-standing shunts eliminates surgical correction options for the majority of diagnosed patients.
Strategic Opportunities
- Japan's SAKIGAKE designation:Priority review and early reimbursement consultation for rare disease innovations accelerates market entry timelines for novel oral formulations.
- Telemedicine-enabled remote monitoring:Wearable oxygen saturation and hemodynamic tracking platforms are extending specialist reach into underserved rural congenital heart disease populations.
- Combination therapy protocols:Sequential addition of endothelin receptor antagonists to prostacyclin backgrounds is creating new positioning opportunities for oral agents.
Industry Challenges
- Adult congenital cardiology workforce scarcity:Fellowship training programs produce fewer than fifty specialists annually in the United States, constraining referral network expansion.
- Multicenter trial enrollment complexity:Geographic dispersion of eligible patients across low-prevalence centers prolongs study timelines and inflates per-patient recruitment costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eisenmenger Syndrome Treatment Market |
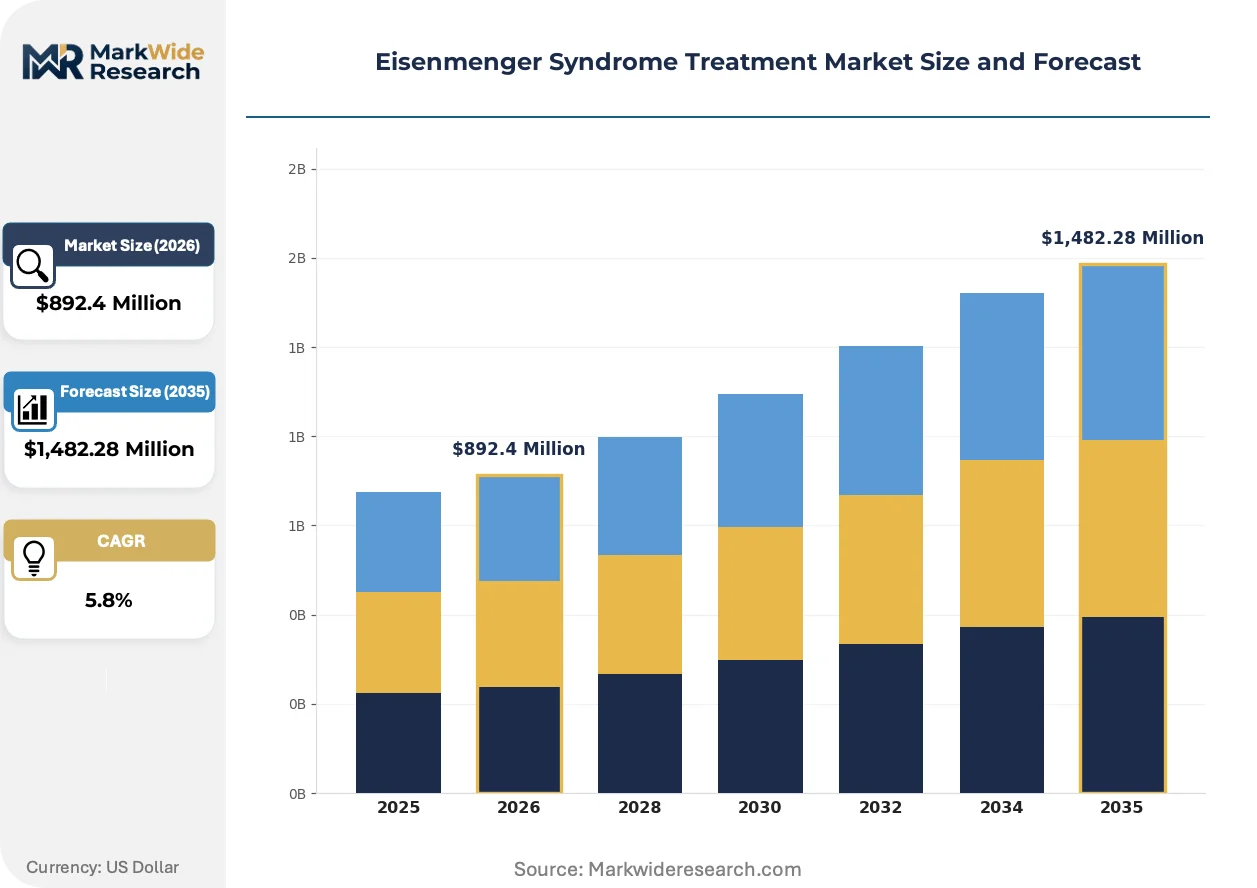
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,482.28 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Surgical Procedures, Catheter Interventions, Support Devices End User: Hospitals, Specialty Clinics, Home Care Settings, Rehabilitation Centers Therapy Area: Pulmonary Hypertension, Heart Conditions, Congenital Defects, Vascular Disorders Delivery Mode: Oral, Injectable, Inhalation, Intravenous |
| Companies Covered | Actelion Pharmaceuticals Ltd., Gilead Sciences, Inc., Pfizer, Inc., Teva Pharmaceutical Industries Ltd., Bayer AG, Novartis AG, Merck & Co., Inc., GlaxoSmithKline plc, United Therapeutics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eisenmenger Syndrome Treatment Market Shifts & Advancements
Device-drug convergence and regulatory pathway optimization are redrawing competitive boundaries, with delivery system innovation becoming as critical as molecular mechanism in securing prescriber preference and payer coverage.
Subcutaneous infusion pump miniaturization is supplanting bulky ambulatory systems previously required for continuous prostacyclin delivery. Adult congenital heart disease centers in the United States are transitioning patients to palm-sized devices within eighteen months of commercial availability. This shift is compressing the competitive relevance of legacy intravenous infrastructure and favoring manufacturers with integrated device-pharmaceutical capabilities.
The European Medicines Agency's PRIME eligibility criteria for rare disease therapies are compressing regulatory review timelines from validation to opinion. Developers gain enhanced scientific advice and accelerated assessment pathways that reduce development risk capital requirements. Oral endothelin receptor antagonist sponsors are leveraging this framework to pursue simultaneous EMA-FDA filings.
Consolidated purchasing by integrated delivery networks is displacing fragmented hospital-level procurement for infused therapies. Large academic medical centers in Germany and France are negotiating multi-year supply agreements that bundle drug, device, and nursing support. This concentration is most visible in the Rhineland and Ile-de-France regions where referral catchments exceed five million lives.
Eisenmenger Syndrome Treatment Market Segmentation
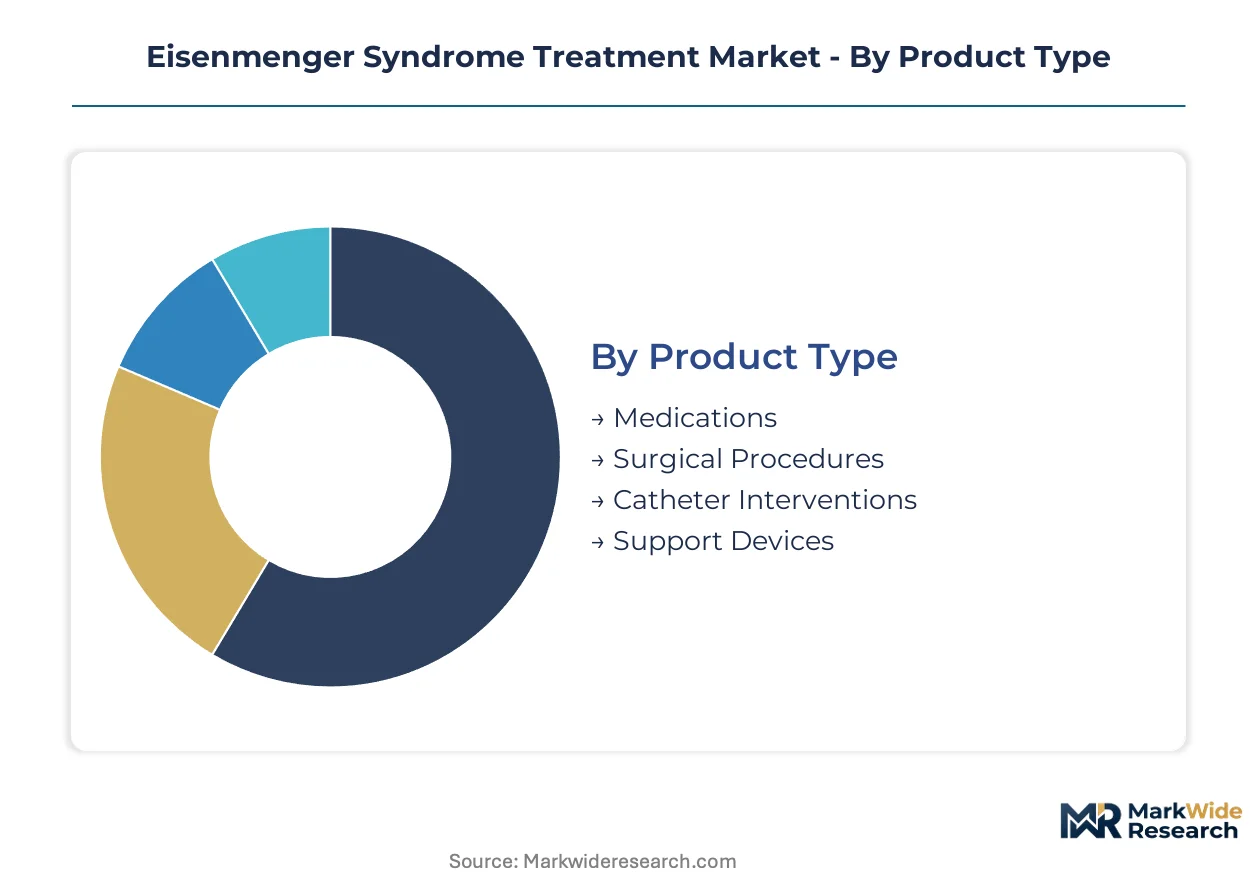
Eisenmenger syndrome treatment segmentation reveals concentrated value pools in prostacyclin-based medications and catheter interventions, with delivery mode and care setting fragmentation creating distinct competitive arenas. Understanding these divides exposes where margin capture concentrates versus where volume expansion opportunities emerge.
Product Type:
Domestic markets in the United States and Germany absorb the majority of high-complexity surgical and catheter volumes, while export-oriented manufacturing concentrates treprostinil analogs for distribution across European and Asian referral networks.
- Medications:Prostacyclin analogs, endothelin receptor antagonists, and phosphodiesterase-5 inhibitors form the pharmacologic backbone. Demand clusters at adult congenital heart disease centers in Philadelphia, Boston, and Munich where protocol standardization drives consistent prescribing. Medicare bundled payments and Germany's IQWiG assessments shape reimbursement thresholds for chronic oral versus infused therapy escalation.
- Catheter Interventions:Transcatheter closure procedures for vasoreactive patients represent the structural segment with steepest expansion trajectory. Feasibility testing using acute vasodilator challenge protocols at centers like the Mayo Clinic and Heidelberg University Hospital is expanding eligible candidate pools beyond pure medical management.
- Surgical Procedures:Heart-lung transplantation and combined cardiac repair remain restricted to supraregional centers with extracorporeal membrane oxygenation backup.
- Support Devices:Oxygen concentrators and portable hemodynamic monitors serve home-based chronic hypoxemia management.
Medications hold the largest share; momentum sits with catheter interventions.
End User:
Cost tier stratification separates high-acuity hospital episodes from lower-touch chronic management, with reimbursement differentials driving site-of-care migration for stable patients.
- Specialty Clinics:Consolidated adult congenital heart disease referral centers in the United States—Cleveland Clinic, Johns Hopkins, and Stanford—concentrate complex diagnostic workup and therapy initiation. These centers capture disproportionate prostacyclin infusion starts due to nursing infrastructure and pharmacy compounding capabilities that community hospitals lack.
- Hospitals:Acute decompensation episodes, diagnostic right heart catheterization, and interventional procedures anchor hospital-based revenue. German university hospitals in Berlin and Hamburg maintain dedicated pulmonary hypertension units with 24-hour prostacyclin infusion capability.
- Home Care Settings:Subcutaneous and ambulatory intravenous delivery shifts stable patients toward home nursing.
- Rehabilitation Centers:Cardiopulmonary conditioning programs serve post-interventional recovery.
Specialty clinics dominate complex therapy initiation; home care settings are climbing fastest as pump miniaturization enables discharge.
Therapy Area:
Application focus varies by developmental pipeline, with pulmonary hypertension attracting orphan drug investment while congenital defect repair remains procedurally driven.
- Pulmonary Hypertension:Targeted vascular remodeling therapies address elevated pulmonary vascular resistance exceeding 10 Wood units. FDA orphan drug designations and EMA PRIME eligibility compress development timelines for novel prostacyclin pathway modulators, with sponsors prioritizing this indication within broader pulmonary arterial hypertension portfolios.
- Congenital Defects:Anatomic shunt closure feasibility assessments determine candidacy for transcatheter or surgical intervention. French and Italian centers lead volume in atrial septal defect and ventricular septal defect closure in Eisenmenger physiology.
- Heart Conditions:Right ventricular failure prevention and arrhythmia management support chronic stability.
- Vascular Disorders:Paradoxical embolism prophylaxis and cyanosis management address systemic complications.
Pulmonary hypertension commands development investment; congenital defect interventions are expanding most quickly through catheter advances.
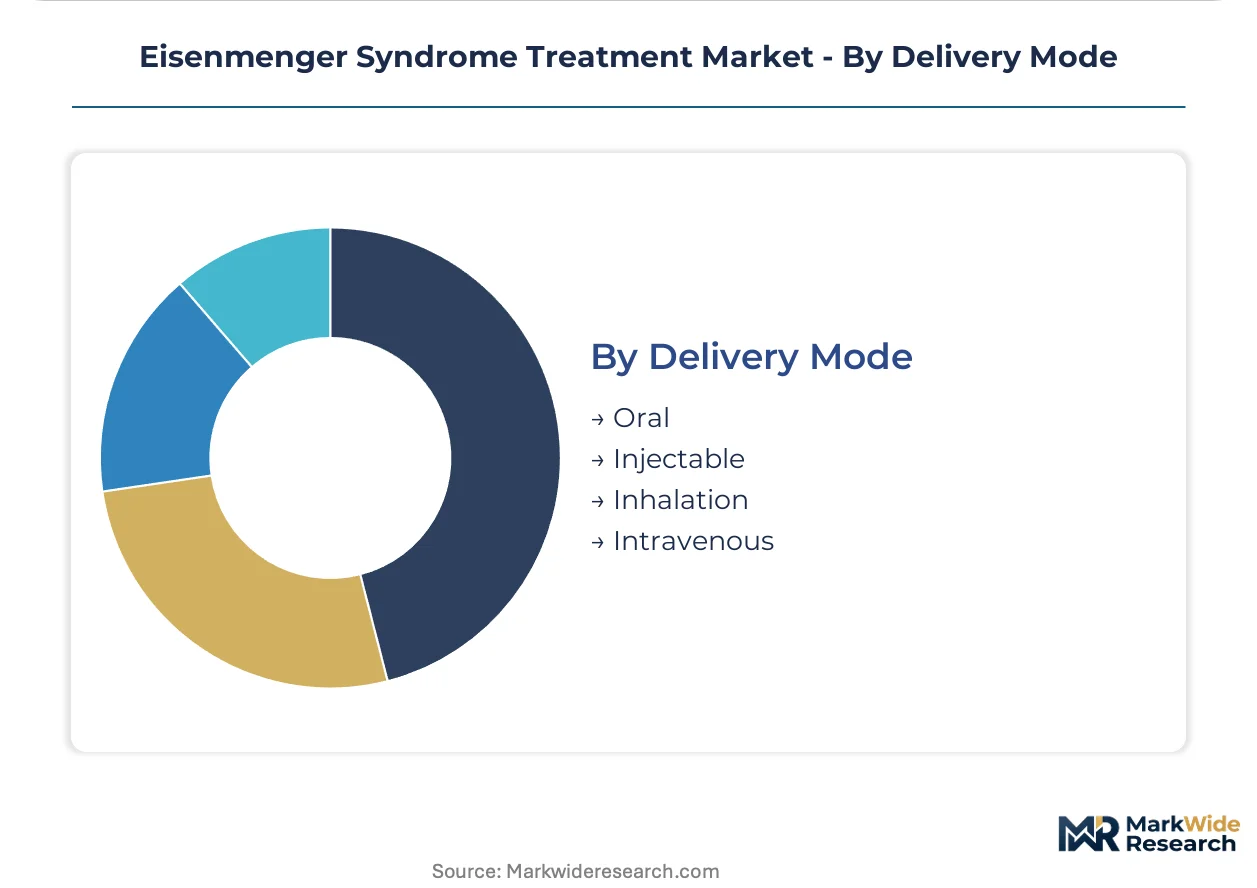
Delivery Mode:
Customer type fragmentation separates chronic outpatient self-administration from acute inpatient-controlled delivery, with patient capability and disease severity determining modality selection.
- Intravenous:Continuous epoprostenol infusion through permanent indwelling catheters serves the most hemodynamically compromised patients. United States tertiary centers maintain dedicated infusion suites; infection risk and thrombosis surveillance requirements limit expansion beyond high-volume institutions.
- Injectable:Subcutaneous treprostinil delivered via miniaturized ambulatory pumps is displacing intravenous routes in stable patients. Palm-sized devices introduced in the United States are compressing legacy pump market relevance within eighteen months of availability.
- Oral:Endothelin receptor antagonists and phosphodiesterase-5 inhibitors enable background therapy without infusion infrastructure.
- Inhalation:Iloprost and treprostinil nebulization provides acute vasodilator testing and intermittent symptom relief.
Intravenous delivery retains the highest acuity share; injectable routes are gaining share fastest through device innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Complex synthesis requirements for prostacyclin analogs concentrate active pharmaceutical ingredient production among specialized contract manufacturers in the United States, Germany, and Switzerland. Referral networks for adult congenital heart disease cluster at tertiary institutions with dedicated pulmonary hypertension infrastructure.
United States
Adult congenital heart disease centers in Philadelphia, Boston, and Cleveland concentrate prostacyclin infusion starts due to nursing infrastructure and pharmacy compounding capabilities. The FDA's orphan drug designation framework grants seven-year market exclusivity and tax credits for clinical trials. Medicare bundled payment systems for outpatient infusion services shape site-of-care economics across large academic medical centers.
Germany
University hospitals in Berlin, Hamburg, and Heidelberg maintain dedicated pulmonary hypertension units with 24-hour prostacyclin infusion capability and transcatheter closure programs. IQWiG evaluation pathways streamline reimbursement for high-cost chronic treatments in Europe's largest pharmaceutical market. The Rhineland region hosts consolidated purchasing agreements that bundle drug, device, and nursing support across referral catchments exceeding five million lives.
France
Centers in Paris and Marseille lead European volume in atrial septal defect and ventricular septal defect closure in Eisenmenger physiology. ANSM oversight of rare disease therapeutics aligns with EMA PRIME eligibility criteria that compress regulatory review timelines. The Ile-de-France region anchors interventional cardiology training programs that feed specialist workforce pipelines across Western Europe.
Japan
The SAKIGAKE designation accelerates market entry timelines for novel oral formulations through priority review and early reimbursement consultation. PMDA scientific advice programs reduce development risk capital requirements for sponsors pursuing simultaneous EMA-FDA filings. Tokyo-based referral centers pioneer wearable oxygen saturation and hemodynamic tracking platforms for rural congenital heart disease populations.
United Kingdom
Specialist commissioning frameworks concentrate Eisenmenger syndrome care at supraregional centers in London, Birmingham, and Manchester with extracorporeal membrane oxygenation backup. NHS England technology appraisal processes determine patient access to high-cost chronic therapies alongside NICE guidance. The Southeast region hosts the majority of fellowship training programs that produce adult congenital cardiology specialists.
Eisenmenger Syndrome Treatment Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Eisenmenger syndrome treatment landscape. The market structure consolidates around vertically integrated pulmonary arterial hypertension portfolios and specialized prostacyclin delivery system manufacturers. Three archetypes dominate: integrated pharmaceutical-device developers with in-house production capabilities, large-scale oral therapy manufacturers leveraging manufacturing scale, and rare disease specialists exploiting regulatory exclusivity pathways. Competitive moves center on pump miniaturization R&D and multi-year supply agreements bundling drug, device, and nursing support.
Among integrated pharmaceutical-device developers, Actelion Pharmaceuticals Ltd. and United Therapeutics Corporation exemplify the archetype combining molecular development with captive delivery system production. Pfizer, Inc. occupies a position representing large-scale manufacturing leverage in oral endothelin receptor antagonist supply. These three anchors illustrate how competitive positioning in Eisenmenger syndrome care increasingly depends on controlling both the therapeutic molecule and its administration infrastructure rather than either alone.
| Leading Market Players |
|---|
| Actelion Pharmaceuticals Ltd. |
| Gilead Sciences, Inc. |
| Pfizer, Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Bayer AG |
| Novartis AG |
| Merck & Co., Inc. |
| GlaxoSmithKline plc |
| United Therapeutics Corporation |
| Others |
Supply & Pricing Matrix
Ninety-day inventory buffers for treprostinil active pharmaceutical ingredients concentrate pricing power among United States and German contract manufacturers, with Medicare bundled payment compression feeding directly into procurement consolidation at adult congenital heart disease centers.
Pricing Analysis
The FDA's orphan drug designation dictates the pricing tier structure across Eisenmenger syndrome therapies, separating premium prostacyclin analogs from standard oral endothelin receptor antagonists and economy-tier phosphodiesterase-5 inhibitors. Price differentiation hinges on infusion infrastructure requirements and FDA exclusivity status, with seven-year market exclusivity protecting premium tiers. Cost compression in infused therapies intensifies as Medicare prospective payment systems squeeze outpatient administration margins. Community hospitals exhibit highest price sensitivity due to nursing infrastructure gaps, while tertiary referral centers absorb premium pricing through bundled device-drug-service contracts.
Supply Chain Analysis
Ninety-day inventory buffers for treprostinil APIs reflect synthesis complexity that anchors supply in the United States, Germany, and Switzerland. Raw material dependencies include specialized epoprostenol precursors, medical-grade silicones for pump manufacturing, and high-purity solvents for sterile formulation. Single-source vulnerability concentrates in treprostinil API production, where complex organic synthesis limits qualified suppliers. Distribution runs through integrated delivery networks that bundle drug, device, and nursing support across consolidated adult congenital heart disease referral catchments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through specialty clinic consolidation, with adult congenital heart disease referral centers in Philadelphia, Boston, and Cleveland capturing disproportionate prostacyclin infusion starts and squeezing manufacturer margins through multi-year supply agreements.
For Market Incumbents: Fortify device-pharmaceutical integration by deepening in-house pump manufacturing capabilities and securing captive treprostinil API supply through backward integration into specialized contract manufacturers. The threat of subcutaneous pump miniaturization displacing intravenous infrastructure demands accelerated R&D in palm-sized delivery systems. Channel control through exclusive nursing support contracts anchors retention at high-volume centers. For New Entrants and Emerging Players: Remote monitoring service gaps in rural congenital heart disease populations offer white-space entry points where incumbent telemedicine platforms under-serve. The most penetrable segment lies in wearable hemodynamic tracking for home-based prostacyclin management, with Japan's SAKIGAKE designation providing the fastest regulatory pathway. A direct-to-specialist go-to-market model bypasses consolidated purchasing resistance. For Investors and Strategic Acquirers: Carve-out targets emerge from large-cap pharmaceutical parents with under-monetized pulmonary arterial hypertension assets lacking device integration. Long-term viability hinges on controlling both molecule and delivery infrastructure rather than either alone. The signal to watch is FDA breakthrough therapy designation velocity for novel prostacyclin pathway modulators, indicating inflection in competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Pump Miniaturization R&D | Palm-sized subcutaneous devices displace legacy intravenous infrastructure within eighteen months of FDA clearance. |
| Orphan Drug Designation Pursuit | Seven-year exclusivity and tax credits compress development risk capital for novel prostacyclin analogs. |
| Integrated Delivery Network Partnership | Multi-year supply agreements bundling drug, device, and nursing support lock out fragmented competitors. |
| Telemedicine Platform Development | Wearable oxygen saturation tracking extends specialist reach into underserved rural congenital heart disease populations. |
| Transcatheter Closure Program Investment | Vasoreactivity testing capabilities expand addressable patient pools beyond pure medical management. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with interventional cardiologists, adult congenital heart disease program directors, hospital pharmacy compounding specialists, and prostacyclin infusion nursing coordinators. Secondary validation drew from FDA orphan drug designation filings, EMA PRIME eligibility submissions, Medicare bundled payment rulemaking, and IQWiG health technology assessment reports. Bottom-up prescription volume modeling and top-down pulmonary arterial hypertension market allocation triangulated segment-level estimates.
Across the analysis window, analytical frameworks modeled treatment escalation pathways by delivery mode, care setting acuity, and regional regulatory cluster. CAGRs derived from patient population incidence-stable prevalence conversion, therapy penetration curves, and price-volume interaction effects. Forecast inputs incorporated prostacyclin analog synthesis capacity expansion timelines and catheter intervention volume trajectories at tertiary centers.
Underlying assumptions cover stable orphan drug incentive frameworks and continued specialty clinic consolidation, with deviation risk concentrated in Medicare reimbursement rate adjustments and adult congenital cardiology workforce expansion shortfalls. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Ventricular Tachycardia Market
Cardiovascular
Heart Block Therapeutics Market
Cardiovascular
Atherosclerosis Market
Cardiovascular
US Statin Market
Cardiovascular
United States Cardiometabolic Fixed-Dose Combinations Market
Cardiovascular
Europe Acute Coronary Syndrome Market
Cardiovascular
Global Statin Market
Cardiovascular
Pericarditis Treatment Market
Cardiovascular
Cardiac Troponin Market
Cardiovascular
Heart Blocks Treatment Market
Cardiovascular
Ticagrelor Market
Cardiovascular
Angina Pectoris Market
Cardiovascular
Antihypertensive Market
Cardiovascular
Cardiac Arrhythmia Therapeutics Market
Cardiovascular
Global Hyperlipidemia Drugs Market
Cardiovascular
Pulmonary Valve Replacement Market