
 Adrenocorticotropic Hormone [ACTH] Market | 2026-2036
Adrenocorticotropic Hormone [ACTH] Market Size, Share, and Industry Trends Forecast 2026-2036
Adrenocorticotropic Hormone [ACTH] Market Outlook
Peptide synthesis expertise is redrawing competitive boundaries in the ACTH landscape. Mallinckrodt plc leverages its vertically integrated plasma-derived hormone portfolio to sustain supply chain control over corticotropin formulations. Pfizer, Inc. anchors its position through manufacturing scale in sterile injectable capacity, while Novartis AG competes via R&D intensity in synthetic peptide analog programs.
Adrenocorticotropic hormone is a 39-amino acid polypeptide secreted by the anterior pituitary gland, synthesized from pro-opiomelanocortin through post-translational cleavage, and functions principally to stimulate glucocorticoid release from the adrenal cortex for diagnostic and therapeutic applications. Injection formulations dominate current revenue due to their established use in adrenal insufficiency testing and acute therapeutic intervention, while diagnostic testing applications are expanding fastest as hospitals adopt standardized cosyntropin stimulation protocols. Tablet and capsule segments remain marginal, constrained by gastrointestinal degradation of peptide structures that limits oral bioavailability.
FDA oversight of peptide drug manufacturing through current Good Manufacturing Practice requirements and the EMA's centralised marketing authorisation procedure for synthetic hormones shape product standards and market access timelines for manufacturers. The EU MDR's tightened clinical evidence requirements for Class III devices and diagnostics are extending certification cycles for ACTH companion testing platforms. Stakeholders must monitor evolving pharmacovigilance obligations and peptide sourcing transparency mandates that will determine which suppliers retain hospital formulary positions.
Market Dynamics
Peptide manufacturing complexity and FDA orphan drug incentives are compressing supplier margins while concentrating procurement among vertically integrated plasma processors and synthetic peptide specialists.
Growth Catalysts
- Diagnostic protocol standardization:Tertiary hospitals in the United States are adopting cosyntropin stimulation testing as the reference standard for adrenal insufficiency screening, expanding routine endocrinology workflows.
- FDA orphan drug designation:The pathway delivers seven years of market exclusivity and tax credits for clinical trials, accelerating investment in rare disease ACTH analog development.
- Synthetic peptide chemistry advances:Solid-phase synthesis and recombinant expression technologies are reducing production batch variability and enabling scalable corticotropin analog manufacturing.
Market Restraints
- Plasma supply concentration:Corticotropin derived from porcine pituitary tissue depends on abattoir sourcing networks concentrated in Midwestern United States processing facilities.
- EMA centralized marketing authorization:The procedure requires extensive stability data and multi-site manufacturing inspections, extending European market entry timelines by 18-24 months.
- Peptide gastrointestinal degradation:Oral ACTH formulations face fundamental bioavailability barriers that limit patient convenience and expandable addressable populations.
Strategic Opportunities
- Pediatric endocrinology expansion:Underpenetrated congenital adrenal hyperplasia screening programs in India present volume growth potential for synthetic ACTH diagnostic kits.
- Companion diagnostic integration:The FDA's in vitro diagnostic guidance creates alignment incentives between ACTH stimulation protocols and automated cortisol immunoassay platforms.
- Long-acting depot formulations:PEGylation and microsphere encapsulation technologies are converging to enable monthly administration intervals for chronic therapeutic indications.
Industry Challenges
- Peptide analytical chemistry expertise:Mass spectrometry and high-performance liquid chromatography method development for 39-amino acid polypeptide characterization requires scarce specialized talent.
- Cold chain infrastructure investment:Temperature-controlled distribution from manufacturing sites through hospital pharmacies demands sustained capital deployment in validated storage systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adrenocorticotropic Hormone [ACTH] Market |
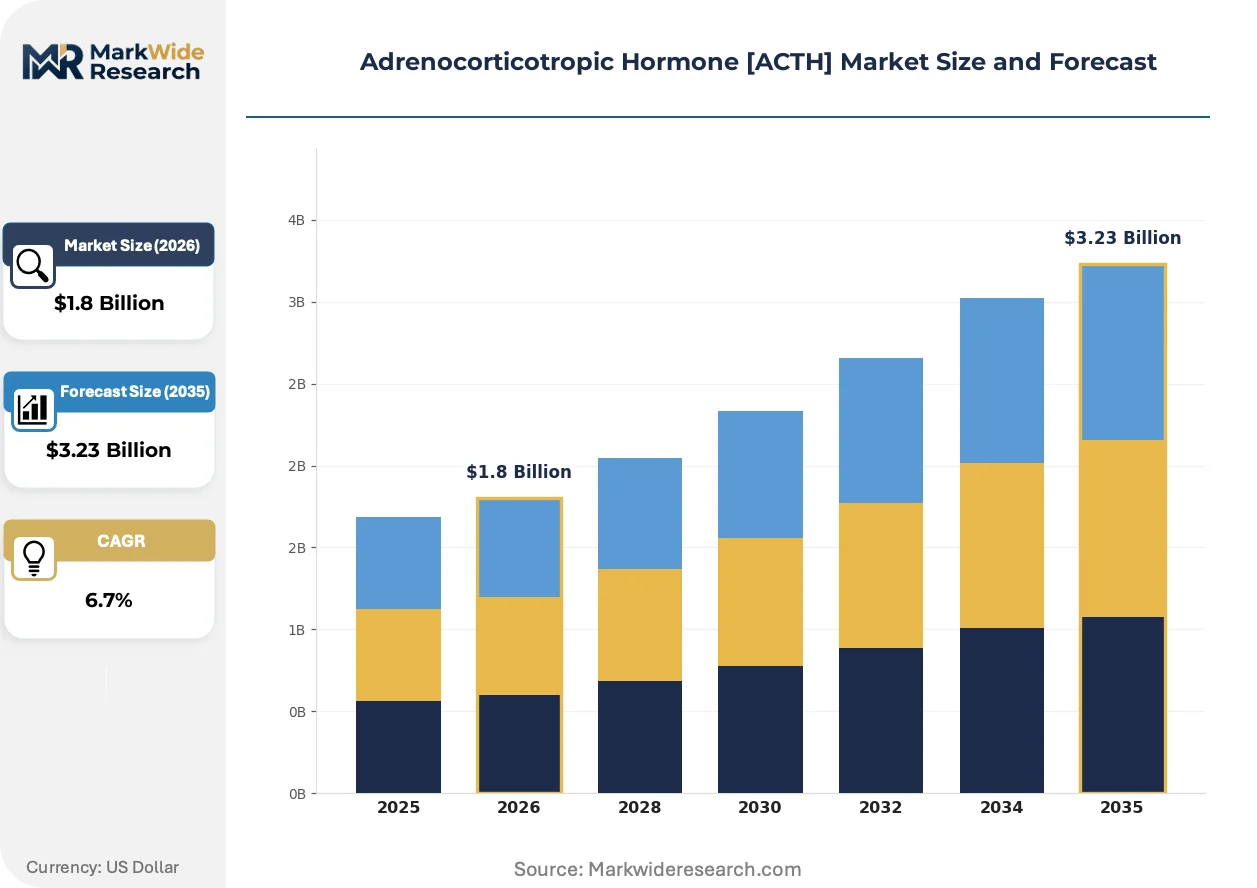
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection, Tablet, Nasal Spray, Capsule Indication: Addison's Disease, Cushing's Syndrome, Congenital Adrenal Hyperplasia, Diagnostic Testing Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Oral End User: Hospitals, Clinics, Homecare, Diagnostic Laboratories |
| Companies Covered | Mallinckrodt plc, Pfizer, Inc., Novartis AG, Merck KGaA, Ferring B.V., Viatris, Inc., Hikma Pharmaceuticals plc, Avantor, Inc., ANI Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adrenocorticotropic Hormone [ACTH] Market Strategic Shifts
Biosensor integration and regulatory harmonization efforts are compressing diagnostic turnaround times while reshaping how endocrinology departments validate adrenal function.
Microfluidic immunoassay platforms are miniaturizing cortisol quantification workflows for point-of-care deployment. Reference laboratories in Germany and academic medical centers in Massachusetts are piloting cartridge-based systems that reduce sample-to-result intervals from hours to minutes. This technology is miniaturizing the footprint of ACTH stimulation testing and enabling same-day clinical decision-making in outpatient settings.
The EU MDR's tightened clinical evidence requirements for Class III in vitro diagnostics are extending certification cycles for ACTH companion testing platforms. Manufacturers must now submit prospective clinical performance studies rather than retrospective analytical validations, increasing documentation burdens. Synthetic ACTH diagnostic kit suppliers targeting European hospital networks are responding by front-loading clinical trial investments and restructuring quality management systems.
Hospital procurement departments are consolidating peptide hormone purchasing through sole-source agreements with integrated health systems. Group purchasing organizations are displacing individual hospital formulary negotiations, compressing supplier margins while guaranteeing volume commitments. This concentration is most visible in United States multi-hospital networks where standardized cosyntropin protocols reduce variation in adrenal insufficiency diagnostic pathways.
Adrenocorticotropic Hormone [ACTH] Market Segmentation
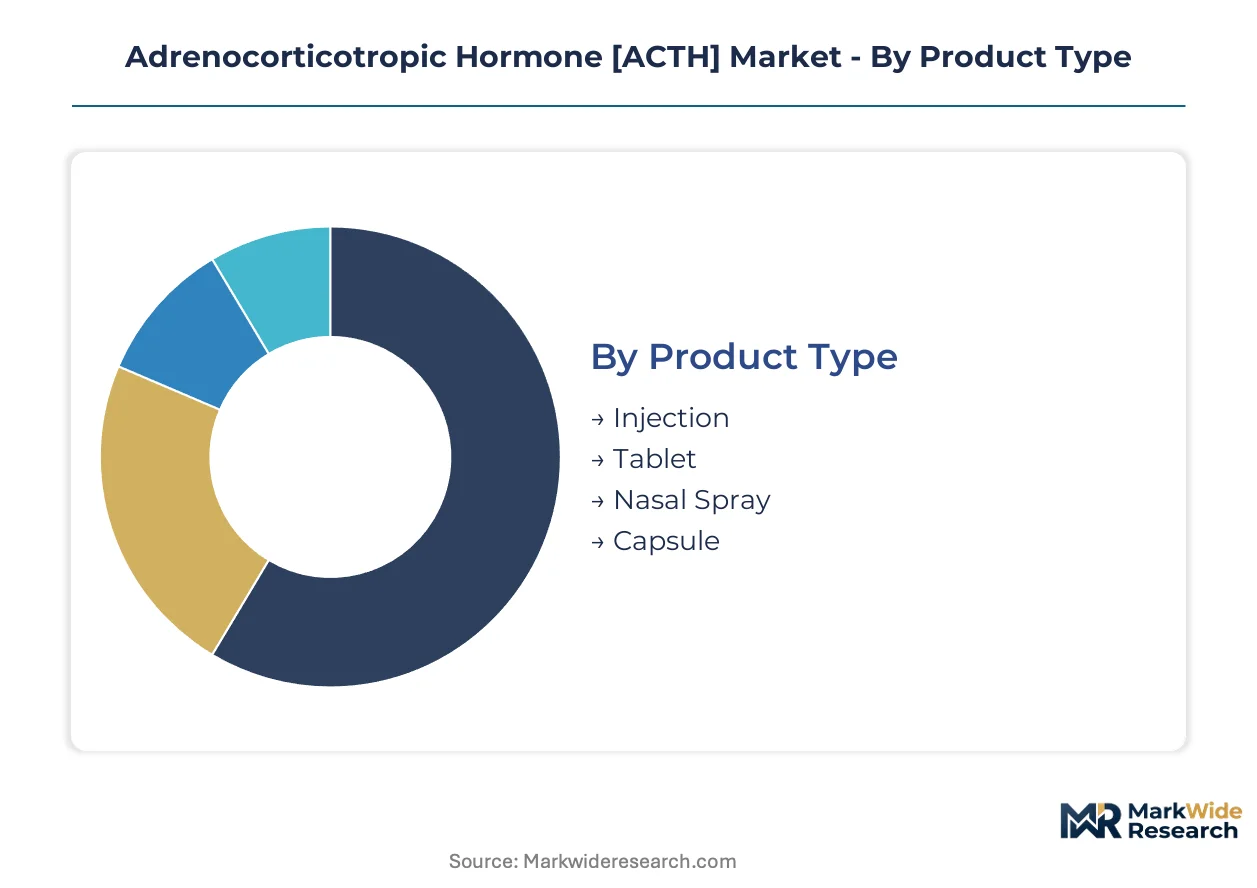
ACTH market segmentation reveals divergent margin profiles across formulation technologies and care settings. Injection formats command premium pricing due to manufacturing complexity, while diagnostic applications are reshaping volume distribution through hospital protocol standardization.
Product Type:
Margin pools concentrate in sterile injectable formats where peptide stability requirements and aseptic processing create supply scarcity.
- Injection:Sterile parenteral formulations of synthetic cosyntropin or purified corticotropin require cold-chain distribution and validated aseptic manufacturing. Demand concentrates in United States tertiary hospitals and reference laboratories performing adrenal insufficiency stimulation protocols, with supply constrained by FDA current Good Manufacturing Practice inspections and peptide synthesis batch variability.
- Tablet:Oral solid dosage forms face fundamental bioavailability limitations as 39-amino acid polypeptides degrade in gastric environments. Development programs in Massachusetts biotech clusters target enteric coating technologies, though no approved tablet products currently capture meaningful revenue.
- Nasal Spray:Mucosal delivery systems exploit nasal epithelium permeability for systemic peptide absorption. Early-stage programs in German pharmaceutical R&D centers investigate absorption enhancers to overcome molecular weight barriers.
- Capsule:Encapsulation technologies for oral delivery remain preclinical, with gastrointestinal degradation limiting commercial viability despite patient convenience advantages.
The dominant share belongs to Injection, while Diagnostic Testing applications are expanding most quickly through hospital protocol adoption.
Indication:
Application-driven segmentation shows diagnostic protocols generating volume concentration while rare disease therapeutics sustain premium pricing tiers.
- Addison's Disease:Primary adrenal insufficiency requires lifelong glucocorticoid replacement with ACTH reserved for diagnostic confirmation and acute crisis management. Patient populations in United States endocrinology practices drive therapeutic demand alongside European hospital networks managing autoimmune etiologies.
- Cushing's Syndrome:ACTH-dependent forms require suppression testing and occasionally therapeutic intervention for ectopic secretion. Diagnostic complexity in academic medical centers creates specialized demand for high-dose dexamethasone suppression protocols combined with corticotropin measurement.
- Congenital Adrenal Hyperplasia:Inherited enzyme deficiencies in steroidogenesis require newborn screening and lifelong management. Underpenetrated screening programs in Indian pediatric endocrinology present volume expansion potential for synthetic ACTH diagnostic kits.
- Diagnostic Testing:Cosyntropin stimulation protocols for adrenal insufficiency screening represent the fastest-expanding application segment. Standardization across United States tertiary hospitals and reference laboratories is displacing variable cortisol measurement methods.
Addison's Disease holds the largest therapeutic share, though Diagnostic Testing is climbing the fastest as hospitals consolidate around cosyntropin reference standards.
Delivery Mode:
Route of administration segmentation reflects pharmacokinetic requirements and care setting infrastructure constraints.
- Intravenous:Direct vascular delivery enables rapid ACTH plasma concentration for acute diagnostic and therapeutic scenarios. United States emergency departments and intensive care units require IV accessibility for adrenal crisis management.
- Subcutaneous:Depot formulations and patient-administered therapies exploit subcutaneous absorption kinetics. Homecare settings in European markets favor this route for chronic therapeutic indications where hospital visits burden patient compliance.
- Intramuscular:Traditional depot injection sites provide sustained corticotropin release for diagnostic stimulation testing. Clinical laboratories in German hospital networks standardize on IM administration for cosyntropin protocols.
- Oral:Gastrointestinal peptide degradation renders oral delivery clinically ineffective despite patient preference. No approved oral ACTH products exist, with development programs stalled at preclinical stages.
Intravenous administration dominates acute care settings, while Subcutaneous delivery is gaining share fastest through homecare expansion and long-acting formulation development.
End User:
Customer segmentation reveals procurement concentration through integrated health systems and diagnostic laboratory networks.
- Hospitals:Tertiary care centers with dedicated endocrinology departments perform the majority of ACTH stimulation testing. United States multi-hospital networks are consolidating peptide hormone purchasing through sole-source agreements that standardize cosyntropin protocols.
- Clinics:Outpatient endocrinology practices manage chronic ACTH therapeutic indications and follow-up diagnostic monitoring. Patient volume in United States specialty clinic chains drives recurring demand for injectable formulations.
- Homecare:Self-administered ACTH therapies for chronic conditions require patient training and cold-chain logistics support. European homecare nursing services are expanding to accommodate subcutaneous depot formulations.
- Diagnostic Laboratories:Reference laboratories process cosyntropin stimulation samples for cortisol quantification. Automated immunoassay platforms in Massachusetts and German laboratory networks are integrating with standardized ACTH protocols.
Hospitals retain the dominant procurement volume, while Diagnostic Laboratories are expanding their share fastest through outsourced testing consolidation and automated platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic protocol preferences diverge sharply across geographies, with United States hospitals driving cosyntropin stimulation volume while European networks emphasize standardized cortisol immunoassay integration and emerging markets expand newborn screening infrastructure.
United States
Tertiary hospital networks and reference laboratories dominate ACTH consumption through standardized adrenal insufficiency protocols. FDA orphan drug designation incentives accelerate synthetic peptide analog development programs. Specialized pituitary centers in Massachusetts and California anchor diagnostic demand concentration.
Germany
Academic medical centers pilot microfluidic immunoassay platforms for point-of-care cortisol quantification. EMA centralized marketing authorisation procedures extend certification timelines for companion diagnostic kits. Industrial clusters in Bavaria and Baden-Württemberg house sterile injectable manufacturing capacity serving hospital networks.
India
Pediatric endocrinology departments expand congenital adrenal hyperplasia screening programs in Maharashtra and Karnataka. CDSCO regulatory pathways for peptide hormone imports shape market access for diagnostic kit suppliers. Mumbai and Delhi medical institutions drive volume for synthetic ACTH stimulation protocols.
Japan
Homecare nursing services accommodate subcutaneous depot formulations for chronic therapeutic indications. PMDA oversight of peptide drug manufacturing enforces stability data requirements for market authorization. Tokyo and Osaka metropolitan hospital networks concentrate diagnostic testing demand.
Switzerland
Specialized endocrinology practices manage rare disease therapeutic applications with premium pricing tiers. Swissmedic marketing authorization procedures emphasize pharmacovigilance systems for hormone therapies. Basel and Zurich pharmaceutical R&D clusters support synthetic peptide chemistry programs.
Adrenocorticotropic Hormone [ACTH] Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the ACTH competitive structure. Plasma-derived hormone processors and synthetic peptide manufacturers occupy distinct vertical positions with divergent supply chain control mechanisms. Three archetypes define the field: vertically integrated plasma processors, large-scale sterile injectable manufacturers, and synthetic peptide R&D specialists. Competitive dynamics center on manufacturing capacity expansion and regulatory pathway navigation for rare disease designations.
Among integrated plasma-derived hormone suppliers, Mallinckrodt plc exemplifies supply chain control over corticotropin formulations. Pfizer, Inc. occupies a position representing manufacturing scale in sterile injectable capacity. Novartis AG sits within the synthetic peptide analog development tier, anchoring R&D-intensive competitive positioning.
| Leading Market Players |
|---|
| Mallinckrodt plc |
| Pfizer, Inc. |
| Novartis AG |
| Merck KGaA |
| Ferring B.V. |
| Viatris, Inc. |
| Hikma Pharmaceuticals plc |
| Avantor, Inc. |
| ANI Pharmaceuticals |
| Others |
Value Chain & Pricing Dynamics
FDA current Good Manufacturing Practice requirements gate both supplier qualification and price differentiation in the ACTH market, separating plasma-derived corticotropin processors from synthetic peptide manufacturers through inspection intensity and batch release protocols that compress margins for non-integrated players.
Pricing Analysis
Long-term offtake agreements between United States multi-hospital networks and integrated plasma processors dominate procurement, with three-tier pricing structure across premium, standard, and economy levels reflecting FDA inspection history and cold-chain certification status. Price differentiation hinges on peptide synthesis batch consistency and aseptic manufacturing scale. Pricing pressure stems from group purchasing organization consolidation that squeezes supplier margins. Reference laboratories exhibit lowest price sensitivity due to diagnostic protocol standardization, while outpatient clinics face highest sensitivity from reimbursement compression.
Supply Chain Analysis
Inventory buffers and extended lead times characterize peptide hormone procurement, with validated cold-chain storage creating working capital intensity from manufacturing sites through hospital pharmacies. Supply concentrates in United States Midwestern abattoir networks for porcine pituitary tissue and German industrial clusters for synthetic peptide chemistry. Raw material dependencies include porcine pituitary glands, solid-phase synthesis resins, and sterile vial components. Single-source vulnerability from plasma supply concentration threatens continuity. Distribution runs through specialized pharmaceutical wholesalers with temperature-controlled logistics certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated United States multi-hospital networks and group purchasing organizations that displace individual formulary negotiations, fragmenting supplier pricing autonomy.
For Market Incumbents: Consolidate manufacturing capacity in FDA-inspected sterile injectable facilities to defend against synthetic peptide specialists encroaching on diagnostic kit volumes. Lock in backward integration into porcine pituitary sourcing networks before plasma supply concentration tightens further. Prioritize companion diagnostic platform partnerships to anchor hospital protocol standardization. For New Entrants and Emerging Players: FDA orphan drug designation fast-track creates regulatory leverage for rare disease ACTH analog developers seeking premium pricing tiers. Target underpenetrated congenital adrenal hyperplasia screening programs in Indian pediatric endocrinology as the most penetrable geography. Deploy automated cortisol immunoassay platform integration as the go-to-market angle to bypass incumbent hospital formulary lock-in. For Investors and Strategic Acquirers: EMA centralized marketing authorisation reshapes the acquisition landscape by extending European market entry timelines and raising clinical evidence burdens for synthetic ACTH diagnostic kit suppliers. Five-to-ten year viability favors vertically integrated plasma processors with captive abattoir sourcing over standalone peptide chemistry specialists. Monitor FDA orphan drug designation grants as the inflection signal for rare disease therapeutic portfolio prioritization.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA pathway delivers seven-year exclusivity for rare disease ACTH analog programs. |
| Companion Diagnostic Integration | Alignment with automated cortisol immunoassay platforms anchors hospital protocol adoption. |
| Synthetic Peptide Chemistry Scale-Up | Solid-phase synthesis capacity reduces batch variability for diagnostic kit manufacturing. |
| Cold-Chain Infrastructure Expansion | Temperature-controlled distribution networks secure hospital formulary positions. |
| Pediatric Endocrinology Partnership | Congenital adrenal hyperplasia screening programs in India unlock volume expansion. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with endocrinology department heads, hospital procurement managers, reference laboratory directors, and peptide manufacturing quality officers; and secondary validation through FDA 483 inspection databases, EMA centralized marketing authorisation records, ClinicalTrials.gov entries, and hospital GPO contract disclosures. Bottom-up patient volume modeling and top-down manufacturer capacity estimates were triangulated.
Across the analysis window, forecasts reflect segment-level modeling across formulation type, indication, delivery mode, and end-user channel. CAGRs were derived from patient population epidemiology, protocol adoption curves, and pricing trajectory assumptions. Industry-specific inputs include cosyntropin stimulation test volume per tertiary hospital and synthetic peptide batch yield rates.
Decision-makers should treat outputs as directional under stable regulatory inspection intensity and plasma supply continuity assumptions; material deviation in FDA enforcement patterns or abattoir network consolidation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Beta Blockers Market
Pharmaceuticals
Korea Pharmaceutical Market
Pharmaceuticals
Vaginitis Therapeutics Market
Pharmaceuticals
Germany Pharmaceutical Warehousing Market
Pharmaceuticals
Global Human Vaccines Market
Pharmaceuticals
Compound Diclofenac Sodium and Chlorphenamine Maleate Tablets Market
Pharmaceuticals
Europe Parenteral Lipid Emulsion Market
Pharmaceuticals
Optic Nerve Disorders Drugs Market
Pharmaceuticals
Global Antacids Market
Pharmaceuticals
Peptide and Anticoagulant Drugs Market
Pharmaceuticals
Antihelminthics Market
Pharmaceuticals
United States Insulin Drugs and Delivery Devices Market
Pharmaceuticals
Europe FMD Vaccine Market
Pharmaceuticals
Ocular Excipients Market
Pharmaceuticals
Dyslipidemia Drugs Market
Pharmaceuticals
Global Nasal Drug Delivery Technology Market