
 Erectile Dysfunction Market | 2026-2036
Erectile Dysfunction Market Size, Share, and Industry Trends Forecast 2026-2036
Erectile Dysfunction Market Intelligence
The price-performance gap between branded originator drugs and their generic equivalents is collapsing. Eli Lilly and Company leverages its legacy brand strength in oral pills to maintain market presence. Teva Pharmaceutical Industries, in contrast, competes on volume and distribution scale across multiple geographies. Pfizer sustains its position through extensive channel partnerships and established brand recognition.
Erectile dysfunction treatments encompass pharmaceutical and medical device interventions designed to restore male sexual function. Many oral therapies, such as PDE5 inhibitors, function by increasing blood flow to the penis through vasodilation. Oral pills represent the dominant product type due to ease of use and high efficacy. The distribution channel is rapidly shifting, with online pharmacies and telemedicine platforms gaining share from traditional brick-and-mortar pharmacies.
Market access and drug approval timelines are governed by national bodies like the US FDA, the European Medicines Agency (EMA), and China's NMPA. These agencies set stringent requirements for clinical trial data and manufacturing quality, influencing which products reach patients. Stakeholder success will depend on navigating the transition from prescription-only models to over-the-counter availability in select jurisdictions.
Market Dynamics
The central structural force shaping the market is the rapid digitalization of the patient journey. Telemedicine platforms and online pharmacies are fundamentally altering how patients access consultation, prescriptions, and treatments, shifting the point of care from clinical settings to the home.
Growth Catalysts
- Aging Demographics:Countries with rapidly aging populations, particularly Japan and Germany, are experiencing a natural expansion of the addressable patient base for erectile dysfunction therapies.
- Telehealth Expansion:The proliferation of digital health platforms provides discreet and convenient access to medical advice and prescriptions, overcoming barriers of stigma and improving patient initiation rates.
- Regulatory Evolution:A move by agencies like the UK's MHRA to reclassify certain PDE5 inhibitors for over-the-counter sale creates a new access framework that could be adopted by other jurisdictions.
Market Restraints
- Social Stigma:Cultural and social taboos surrounding sexual health continue to inhibit open discussion and diagnosis in many regions, suppressing the total addressable market.
- Counterfeit Products:The prevalence of unregulated and counterfeit medications sold through illicit online channels poses significant patient safety risks and erodes trust in legitimate treatments.
- Regulatory Hurdles:Stringent and lengthy clinical trial requirements imposed by bodies like China's NMPA and the US FDA can delay the introduction of novel therapies and increase development costs.
Strategic Opportunities
- OTC Reclassification:Pursuing over-the-counter status for established oral therapies in markets like the United States and Australia presents a significant opportunity to expand patient access and volume.
- Subscription Models:Developing direct-to-consumer subscription services that bundle medication with telehealth consultations can build patient loyalty and create recurring revenue streams.
- Emerging Economies:Focusing on market education and building distribution infrastructure in large, underpenetrated markets in Southeast Asia and Latin America offers long-term growth potential.
Industry Challenges
- Supply Chain Integrity:Ensuring the security of the pharmaceutical supply chain against counterfeit infiltration requires constant investment in authentication technologies and tracking systems.
- Data Privacy Compliance:Telemedicine providers must navigate a complex web of patient data regulations, including HIPAA in the US and GDPR in Europe, which adds operational overhead.
- Reimbursement Ambiguity:Securing favorable reimbursement policies for newer, more expensive treatments like medical devices can be challenging with both public and private payers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Erectile Dysfunction Market |
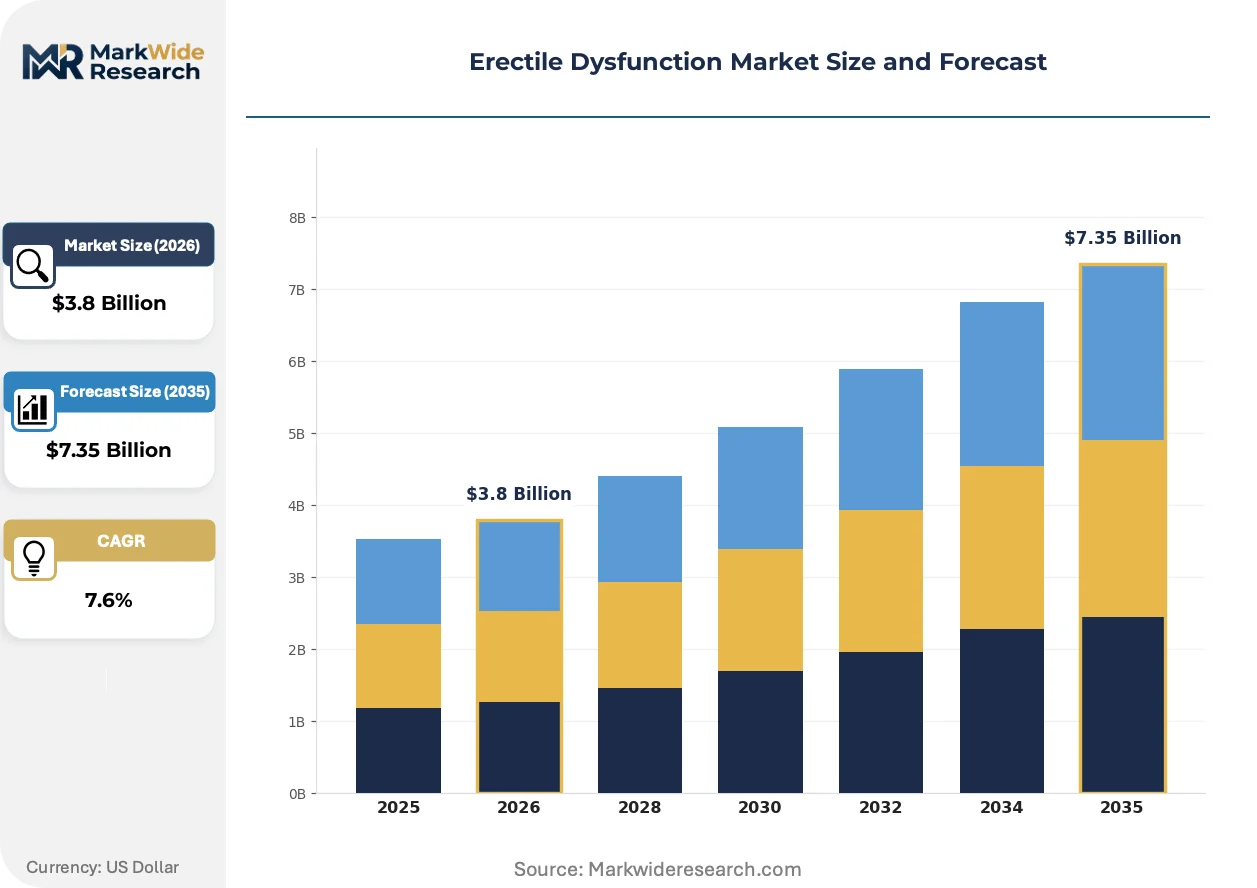
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral Pills, Penile Injections, Vacuum Erection Devices, Urethral Suppositories, Testosterone Replacement, Topical Gels Therapy Area: Psychogenic ED, Vasculogenic ED, Neurogenic ED, Hormonal ED, Anatomical ED, Drug-Induced ED End User: Urology Clinics, Sexual Health Centers, General Hospitals, Diagnostic Labs, Rehabilitation Centers, Home Care Patients Distribution Channel: Pharmacies, Online Pharmacies, Hospitals, Specialty Clinics, Medical Distributors, Telemedicine Platforms |
| Companies Covered | Teva Pharmaceutical Industries, Coloplast Group, Pfizer, Sun Pharmaceutical Industries, Sanofi, Eli Lilly and Company, Boston Scientific, Petros Pharmaceuticals, Bayer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Erectile Dysfunction Market Strategic Shifts & Innovations
The market is being redefined by the convergence of digital health services and a broadening portfolio of treatment modalities. This shift moves the focus from a singular reliance on oral pills toward a more personalized and accessible patient care model.
Low-intensity shockwave therapy (LI-SWT) is a non-invasive treatment that uses acoustic waves to promote blood vessel growth in penile tissue. Urologists and specialized men's health clinics are increasingly adopting it for patients who do not respond well to oral PDE5 inhibitors. This restorative, device-based approach is displacing the sole reliance on pharmacotherapy for managing more complex cases of vasculogenic ED.
Regulatory frameworks are adapting to improve patient access while mitigating risks. The UK's Medicines and Healthcare products Regulatory Agency (MHRA) reclassified sildenafil for sale by pharmacists without a prescription, a model known as 'Pharmacy' medicine. This policy aims to steer patients away from dangerous unregulated online sources. The oral pills category is most affected, requiring manufacturers to develop new pharmacist-facing educational materials.
Patient procurement patterns are evolving toward subscription-based, direct-to-consumer services. This model offers discreet home delivery and integrated telehealth support, bypassing the need for in-person pharmacy visits. The behavioral change is most visible in the United States, where a competitive landscape of digital health startups has accelerated adoption among consumers comfortable with online healthcare services.
Erectile Dysfunction Market Segmentation
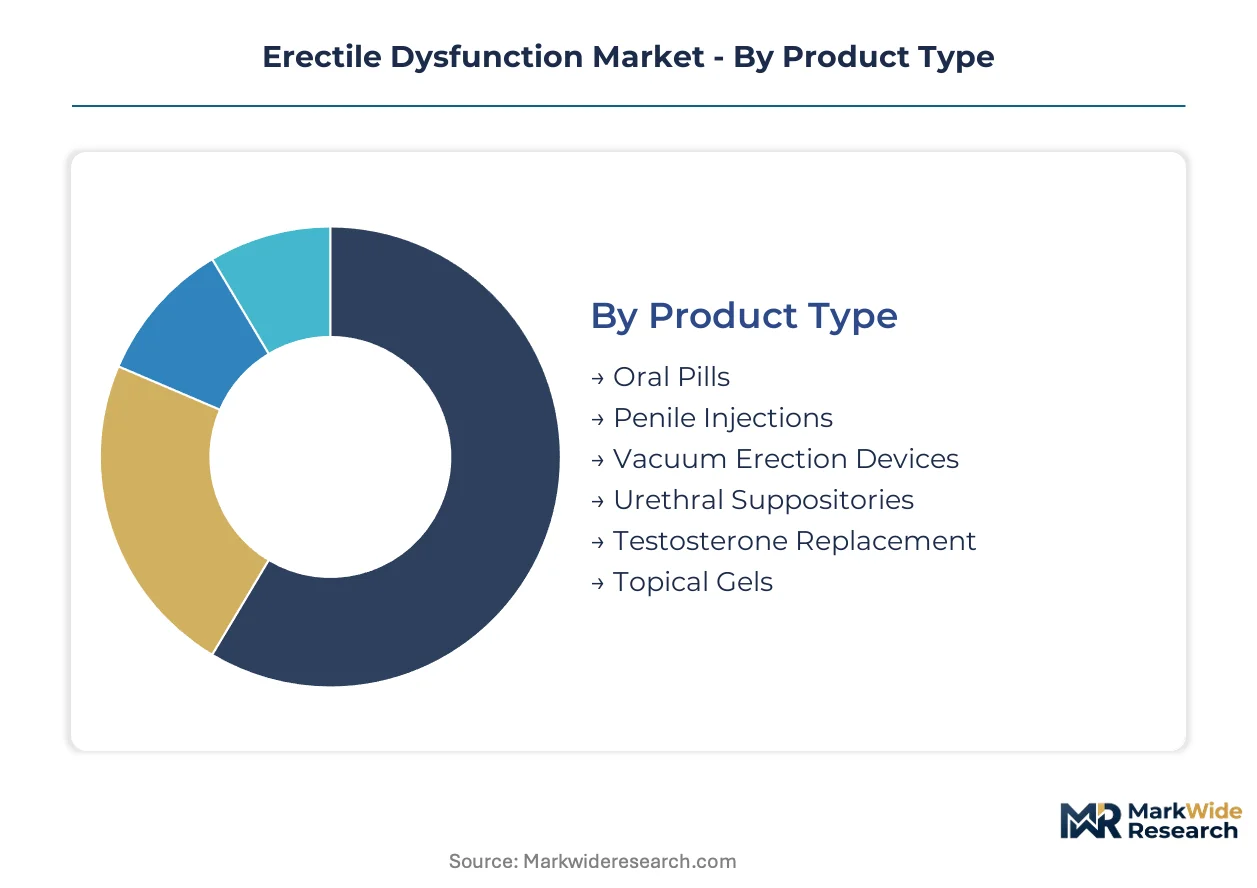
The Erectile Dysfunction Market segmentation provides a granular view of treatment modalities and patient access points. Understanding these distinct segments helps stakeholders identify specific growth vectors and address evolving patient needs. This analysis informs strategic product development and market penetration.
Product Type:
Margin pools within product types often concentrate in novel therapies and established, high-efficacy oral medications, reflecting patient preference and clinical outcomes.
- Oral Pills:These pharmaceutical agents, primarily PDE5 inhibitors, enhance penile blood flow through vasodilation, offering a non-invasive treatment. Demand is strongest in the United States due to convenience and high efficacy, supported by telemedicine.
- Penile Injections:Injections involve vasodilators directly into the penis, providing rapid, localized effects for patients unresponsive to oral therapies. Demand concentrates in specialized urology clinics in Germany, serving complex cases.
- Vacuum Erection Devices:Mechanical devices create negative pressure to draw blood into the penis, offering a non-pharmacological solution.
- Urethral Suppositories:Alprostadil-based suppositories deliver medication into the urethra, an alternative for men unable to use oral pills.
- Testosterone Replacement:This therapy addresses ED linked to low testosterone, improving libido and erectile function.
- Topical Gels:Experimental formulations deliver vasodilators transdermally, aiming for localized effects with fewer systemic side effects.
The dominant share belongs to Oral Pills, while Penile Injections are closing the gap fastest.
Therapy Area:
Volume of patients in each therapy area dictates resource allocation, with prevalent conditions requiring broad access solutions.
- Vasculogenic ED:This type stems from impaired penile blood flow, often linked to cardiovascular disease or diabetes. Treatment demand is high for PDE5 inhibitors and shockwave therapy in aging populations across Japan.
- Psychogenic ED:Originating from psychological factors like stress or anxiety, this form often responds to counseling and oral medications. Patients in the United States increasingly seek discreet telehealth consultations.
- Neurogenic ED:Nerve damage from conditions like spinal cord injury causes this ED, necessitating specialized treatment.
- Hormonal ED:Imbalances in hormones, particularly low testosterone, drive this ED, managed with hormone replacement.
- Anatomical ED:Structural abnormalities of the penis, such as Peyronie's disease, lead to this ED, sometimes requiring surgery.
- Drug-Induced ED:Certain medications can cause this ED, requiring medication review and adjustment.
Vasculogenic ED treatments hold the largest segment, with Psychogenic ED therapies demonstrating the steepest expansion trajectory.
End User:
The maturity of patient care models varies across end-user segments, from established clinical settings to rapidly evolving home-based services.
- Home Care Patients:Individuals managing ED discreetly from home represent a rapidly expanding user base, driven by telemedicine and direct-to-consumer services. This segment accelerates in the United States where digital health platforms are prevalent.
- Urology Clinics:These specialized medical centers provide comprehensive diagnosis and advanced treatment options, including surgical interventions. Patients with refractory ED in countries like Germany frequently seek care here.
- Sexual Health Centers:These clinics offer holistic care, combining medical treatments with psychological support for sexual dysfunction.
- General Hospitals:Hospitals provide acute care for severe ED cases or those requiring inpatient procedures.
- Diagnostic Labs:These facilities perform essential tests, including hormone panels and vascular assessments, crucial for diagnosis.
- Rehabilitation Centers:Patients recovering from conditions affecting sexual function receive specialized physical and occupational therapy.
Urology Clinics retain significant patient volume, while the Home Care Patients segment is gaining share most quickly.
Distribution Channel:
Supply concentration heavily favors digital channels, as manufacturers adapt to shifting patient procurement patterns and regulatory changes.
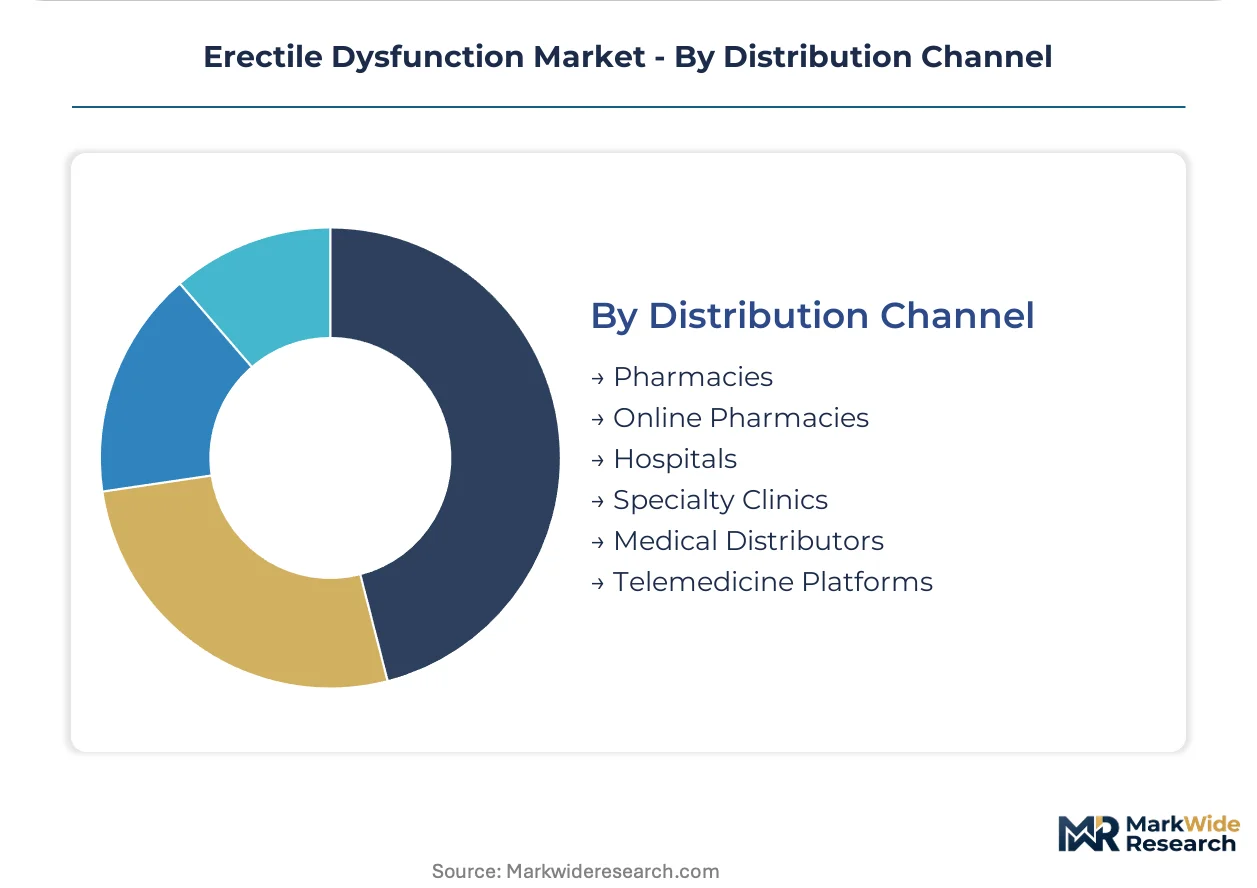
- Online Pharmacies:These platforms provide discreet access to prescription medications, delivering treatments directly to patients after online verification. This channel dominates in the UK and the United States, driven by regulatory evolution.
- Telemedicine Platforms:These digital services connect patients with healthcare providers for remote consultations, diagnosis, and e-prescriptions, removing barriers. Adoption accelerates among younger demographics in Australia seeking confidential care.
- Pharmacies:Traditional brick-and-mortar pharmacies remain important for immediate access and in-person consultation.
- Hospitals:Hospital pharmacies primarily serve inpatients or those receiving complex treatments.
- Specialty Clinics:These clinics stock specialized medications and devices not readily available elsewhere.
- Medical Distributors:These entities manage the bulk supply chain, ensuring products reach healthcare providers.
Pharmacies continue to hold substantial market presence, yet Online Pharmacies exhibit the most rapid expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply-side concentration in the Erectile Dysfunction Market is shifting towards regions with advanced healthcare infrastructure and evolving regulatory landscapes. This dynamic influences patient access and treatment availability across diverse geographies. Digitalization of patient journeys further amplifies these regional shifts.
United States
Demand for oral pills and telehealth services is substantial, driven by patient preference for discreet access. The US FDA's stringent approval processes influence novel therapy introduction and market entry. Digital health startups in major tech hubs like San Francisco and New York are accelerating direct-to-consumer models.
Germany
Specialized urology clinics drive demand for penile injections and advanced medical devices, particularly for complex cases. The European Medicines Agency (EMA) guidelines shape market access for new pharmaceutical treatments. Munich and Berlin are centers for medical technology innovation and clinical research.
Japan
An aging demographic fuels demand for vasculogenic ED treatments, including PDE5 inhibitors and shockwave therapy. The country's national pharmaceutical regulator (PMDA) oversees product approvals and market entry. Tokyo and Osaka remain key for clinical research and specialized men's health clinics.
United Kingdom
Regulatory evolution by the MHRA, reclassifying certain PDE5 inhibitors for over-the-counter sale, is expanding patient access. Online pharmacies dominate distribution, offering discreet procurement options. London's digital health sector is a hub for telemedicine platforms and subscription-based services.
Australia
Younger demographics increasingly adopt telemedicine platforms for confidential consultations and prescriptions, boosting psychogenic ED therapy. The Therapeutic Goods Administration (TGA) regulates product safety and efficacy, potentially influencing future OTC reclassification. Major cities like Sydney and Melbourne see strong growth in digital health services.
Erectile Dysfunction Market Key Industry Players
Concentration sits with established pharmaceutical companies leveraging strong brand recognition and extensive distribution networks for oral therapies. The market exhibits a tiered structure, with originator brands at the premium end and generic manufacturers competing on volume. Strategic archetypes include global pharmaceutical giants, specialized medical device manufacturers, and emerging digital health platforms focusing on patient access. Portfolio diversification, geographic expansion into underpenetrated markets, and strategic partnerships remain dominant competitive moves across the industry.
Within the established pharmaceutical tier, Eli Lilly and Company exemplifies leveraging legacy brand strength in oral pills to maintain market presence. Pfizer sustains its position through extensive channel partnerships and established brand recognition across various treatment modalities. Teva Pharmaceutical Industries, a global pharmaceutical firm, represents the volume-driven generic archetype, competing on distribution scale across multiple geographies and offering more accessible options. These diverse players anchor the market by balancing innovation with broad patient access.
| Leading Market Players |
|---|
| Teva Pharmaceutical Industries |
| Coloplast Group |
| Pfizer |
| Sun Pharmaceutical Industries |
| Sanofi |
| Eli Lilly and Company |
| Boston Scientific |
| Petros Pharmaceuticals |
| Bayer |
| Others |
Cost & Logistics Intelligence
Generic drug manufacturing scale significantly shapes supply concentration and influences price floors across the erectile dysfunction market. High-volume production capabilities, particularly for oral pills, enable cost efficiencies that generic manufacturers leverage to gain market share, intensifying competition in established product categories.
Pricing Analysis
The US FDA and EMA dictate the pricing tier structure for pharmaceutical interventions, emphasizing clinical efficacy and safety. Pricing models often combine per-unit transactional sales for traditional pharmacy channels with subscription-based services for online platforms. Price differentiation stems from brand premium for originator drugs and the efficacy of novel device-based therapies. Pricing softness runs through the generic oral pill segment due to volume-driven competition. Home Care Patients exhibit higher price sensitivity compared to those seeking specialized care at Urology Clinics.
Supply Chain Analysis
Inventory management for oral therapies and medical devices reflects varied lead times, influencing supply chain resilience. Geographic supply concentration for active pharmaceutical ingredients (APIs) primarily sits with India and China, while specialized medical devices often source components from Germany and the United States. The supply chain for oral pills depends on bulk APIs and excipients. A structural supply chain risk involves the infiltration of counterfeit products through illicit online channels. Distribution runs through a hybrid model, combining traditional pharmacy networks with rapidly expanding online pharmacies and telemedicine platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
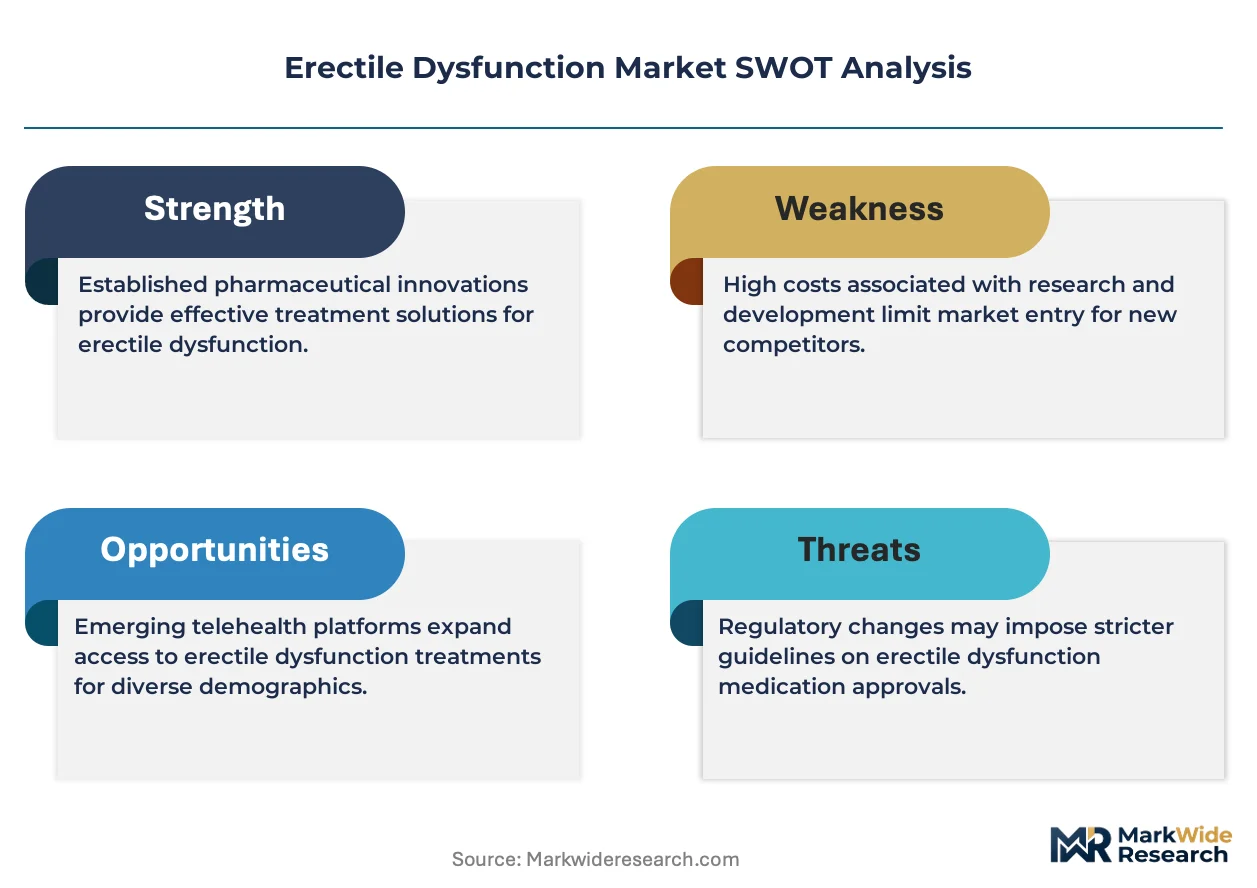
The Erectile Dysfunction Market exhibits a defensive moat, primarily due to regulatory entrenchment that creates high barriers to entry for novel treatments and ensures demand for approved therapies.
For Market Incumbents: Secure market share by actively pursuing over-the-counter reclassification for established oral therapies in key jurisdictions like the United States. Invest in R&D for non-pharmacological treatments, such as low-intensity shockwave therapy, to counter the threat of generic erosion. Extend channel control by acquiring or partnering with prominent digital health platforms. Leverage existing brand recognition to cross-sell into new patient access points.
For New Entrants and Emerging Players: Lead with innovative direct-to-consumer models that prioritize discretion and convenience, particularly for psychogenic ED therapies. Target underpenetrated markets in Southeast Asia and Latin America by focusing on market education and building localized distribution. Develop niche solutions, such as experimental topical gels or personalized treatment plans, to address specific patient segments. Emphasize telehealth integration as a primary go-to-market angle.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among digital health platforms offering subscription-based services that bundle consultations and medication. The long-term viability of this market is strong, supported by aging demographics and increasing patient willingness to seek treatment. Target acquisition profiles include specialized medical device manufacturers and digital health startups with strong patient engagement. The signal to watch is the broader regulatory acceptance of over-the-counter status for PDE5 inhibitors beyond current markets.
| Strategic Initiative | Industry Significance |
|---|---|
| OTC Reclassification Advocacy | Expands patient access and volume for oral pills, shifting procurement away from traditional prescription models. |
| Telemedicine Platform Integration | Enhances patient convenience and discretion, driving adoption rates among younger demographics. |
| R&D in Non-Oral Therapies | Diversifies treatment portfolios, addressing patients unresponsive to traditional pharmaceutical agents. |
| Expansion into Emerging Economies | Unlocks significant long-term growth potential in large, underpenetrated markets with rising healthcare access. |
| Supply Chain Integrity Investment | Mitigates risks from counterfeit products, safeguarding patient safety and brand reputation. |
Research Approach
Operator-level perspectives from urologists, pharmaceutical R&D leads, telemedicine platform executives, and regulatory affairs specialists anchored the qualitative base for this analysis. Primary interviews were triangulated with extensive secondary validation from sources including US FDA filings, EMA submissions, industry association reports, and academic journals. This approach facilitated a robust bottom-up and top-down understanding of market dynamics.
Sensitivity analysis framed the quantitative assessment, exploring various scenarios for market evolution across the analysis window. The analytical framework modeled segmentation dimensions including product type, therapy area, end user, distribution channel, and patient age cohort. Compound annual growth rates were derived from historical trends and projected future demand, informed by key industry-specific inputs like aging population data and telemedicine adoption rates.
Forecasts assume regulatory continuity in regimes such as the US FDA, EMA, and UK MHRA; material policy shifts would require re-modeling. This study acknowledges risk factors such as unforeseen regulatory changes, new waves of counterfeit products, or major economic downturns. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Nasal Drug Delivery Technology Market
Pharmaceuticals
Japan Diabetes Drugs Market
Pharmaceuticals
Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Anti-Parasitic Drugs Market
Pharmaceuticals
Global Autoimmune Drugs Market
Pharmaceuticals
Radiopharmaceutical (Oral Route) Market
Pharmaceuticals
Nimodipine Market
Pharmaceuticals
Global Finasteride Market
Pharmaceuticals
Injectable Potassium Phosphate Market
Pharmaceuticals
Anticholinergic Drugs Market
Pharmaceuticals
Valganciclovir Market
Pharmaceuticals
Pentoxyverine Market
Pharmaceuticals
Global Onychomycosis Treatment Market
Pharmaceuticals
Asia Pacific SGLT2 Inhibitors Market
Pharmaceuticals
Seropositive Rheumatoid Arthritis Drug Market
Pharmaceuticals
Asia-Pacific Obsessive-Compulsive Disorder (OCD) Drugs Market