
 Atypical Antipsychotic Market | 2026-2036
Atypical Antipsychotic Market Size, Share, and Industry Trends Forecast 2026-2036
Atypical Antipsychotic Market Analysis
The capital-intensity divergence between large-scale manufacturers and mid-tier developers is bifurcating competitive dynamics in this space. Johnson & Johnson (Janssen Pharmaceuticals) leverages its depot formulation expertise to sustain premium positioning across institutional channels. Eli Lilly and Company anchors North American supply through vertically integrated active pharmaceutical ingredient production. Otsuka Pharmaceutical Co., Ltd. differentiates via co-commercialization structures that extend its reach into European and Asian markets.
Atypical antipsychotics constitute a pharmacological class of second-generation neuroleptic agents characterized by antagonism at serotonin 5-HT2A and dopamine D2 receptors, with reduced extrapyramidal side effects compared to first-generation compounds. These agents serve primary commercial purposes in managing schizophrenia spectrum disorders, bipolar mania, and adjunctive treatment of major depressive disorder. Oral formulations occupy the largest revenue share due to prescribing familiarity and generic availability, while depot injectables represent the fastest-expanding delivery mode segment driven by adherence advantages and payer preference for reduced hospitalization rates. Schizophrenia therapy areas command mature volume pools, though bipolar disorder applications are gaining share as diagnostic criteria broaden and long-acting formulations penetrate maintenance protocols.
FDA review standards for new molecular entities and EMA pharmacovigilance requirements under the EU Good Pharmacovigilance Practices framework shape clinical trial investments and label expansion timelines for market participants. China's NMPA streamlined review pathways for innovative psychiatric medicines are accelerating local registration decisions for multinational developers. Stakeholders must monitor evolving FDA guidance on digital biomarker integration and real-world evidence acceptance, as these regulatory signals will determine which formulation investments secure differentiated reimbursement positions.
Market Dynamics
Long-acting injectable formulations are restructuring competitive positioning in atypical antipsychotics, as hospital systems and payers prioritize adherence-engineered delivery modes that reduce readmission exposure. This formulation pivot concentrates investment toward depot technologies and away from oral generic commoditization.
Growth Catalysts
- FDA bioequivalence guidance for complex generics:Streamlined abbreviated new drug application pathways for long-acting injectables accelerate follow-on entry, expanding patient access to depot formulations previously locked under originator exclusivity.
- China's NMPA innovative psychiatric medicine review:Priority review channels for novel antipsychotic mechanisms compress registration timelines, drawing multinational Phase III investment toward domestic trial enrollment.
- German hospital formulary consolidation:Centralized procurement at the Bundesland level creates volume aggregation that favors single-source depot contracts, pulling manufacturers toward high-volume manufacturing scale.
Market Restraints
- Active pharmaceutical ingredient concentration in India:Over 60% of atypical antipsychotic API supply routes through Indian contract manufacturers, exposing formulation sponsors to tariff volatility and import license delays.
- EMA pharmacovigilance periodic safety update report burden:Mandatory 6-monthly PSUR submissions for depot formulations create fixed compliance costs that disproportionately burden mid-tier developers with limited regulatory infrastructure.
- Oral generic price compression:Patent cliff exposure for risperidone and olanzapine immediate-release tablets anchors payer reimbursement benchmarks at marginal cost levels, constraining pricing headroom for novel oral agents.
Strategic Opportunities
- Underpenetrated bipolar maintenance in Japan:PMDA label expansion for quetiapine and aripiprazole long-acting injectables in bipolar I disorder remains incomplete, creating first-mover advantage for sponsors completing Japanese-specific maintenance studies.
- Digital biomarker integration with FDA real-world evidence pilot:Fit-for-purpose sensor-derived adherence data offers pathway to differentiated labeling claims that support premium reimbursement positioning against standard of care.
- Co-commercialization structures in Southeast Asia:Partnership models with regional distributors bypass direct infrastructure investment while accessing Indonesia, Thailand, and Vietnam mental health expansion budgets.
Industry Challenges
- Pharmacokinetic modeling talent scarcity:Depot formulation development requires specialized expertise in population PK/PD simulation; competition for modelers with long-acting injectable experience intensifies recruitment costs.
- Legacy electronic health record interoperability:Hospital system medication adherence tracking modules lack standardized APIs for long-acting injectable administration documentation, complicating outcomes-based contract verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Atypical Antipsychotic Market |
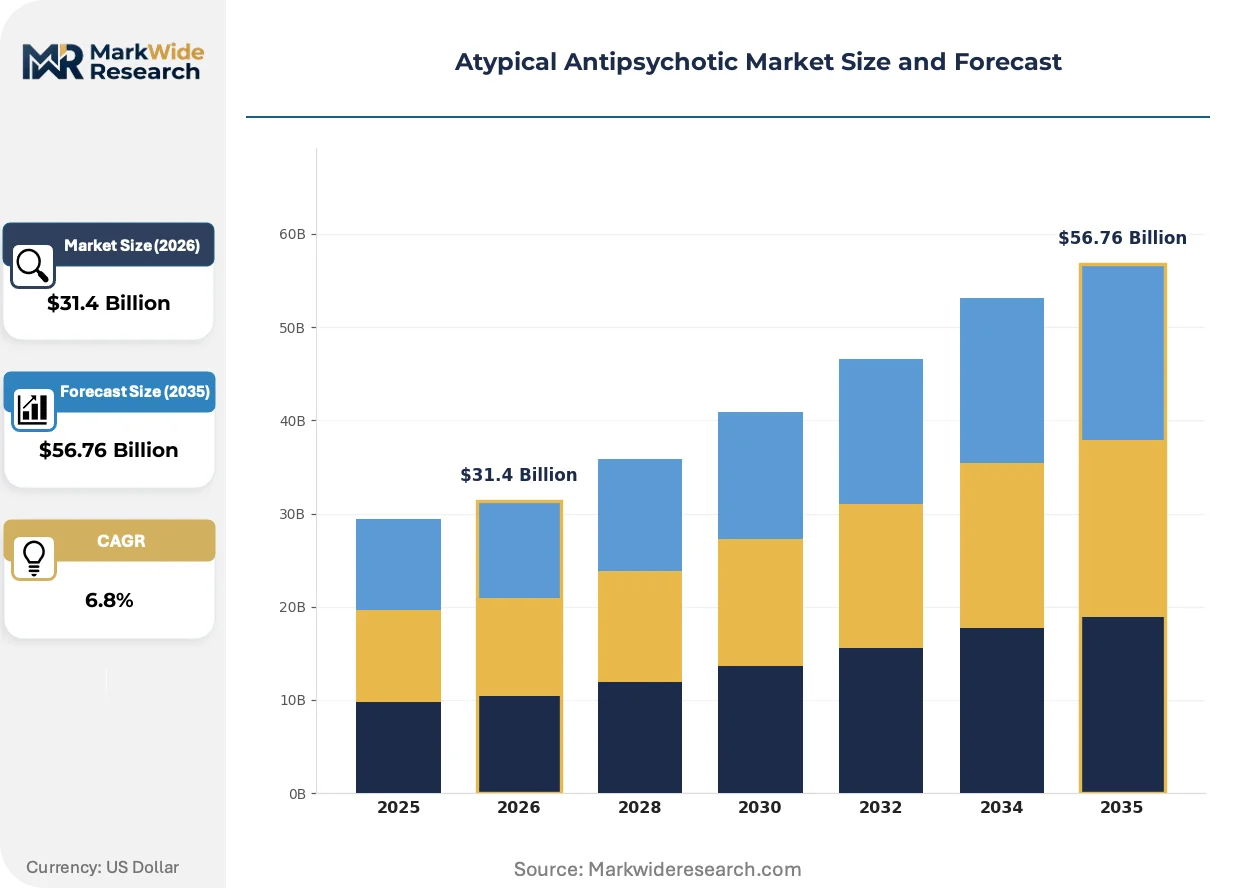
| Market Size in 2026 | $31.4 Billion |
| Market Size in 2035 | $56.76 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Olanzapine, Quetiapine, Risperidone, Aripiprazole Therapy Area: Schizophrenia, Bipolar Disorder, Depression, Anxiety Disorder Delivery Mode: Oral, Injectable, Depot, Transdermal End User: Hospitals, Clinics, Specialty Pharmacies, Home Care |
| Companies Covered | Eli Lilly and Company, Johnson & Johnson (Janssen Pharmaceuticals), Otsuka Pharmaceutical Co., Ltd., AstraZeneca PLC, Pfizer Inc., H. Lundbeck A/S, Teva Pharmaceutical Industries Ltd., AbbVie Inc., Bristol-Myers Squibb Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Atypical Antipsychotic Market Emerging Trajectories
Formulation science and regulatory data acceptance criteria are converging to redefine product differentiation in atypical antipsychotics. Three developments merit particular attention.
Polymeric microsphere encapsulation technology is miniaturizing. These biodegradable depot matrices enable subcutaneous administration with smaller gauge needles, reducing injection site reactions that drive discontinuation. Academic medical centers in the United States are adopting microsphere-based risperidone formulations at twice the rate of conventional oil-based depots. The technology is miniaturizing patient resistance barriers and compressing the gap between oral and injectable acceptability profiles.
REACH registration requirements for polymer excipients are tightening supply chain scrutiny. ECHA substance of very high concern candidate list expansion now captures residual solvents common in microsphere manufacturing, forcing reformulation of legacy depot products. European contract manufacturers are responding by qualifying alternative solvent systems and submitting updated drug master files, with Germany and France showing the most advanced compliance transitions.
Hospital pharmacy procurement is consolidating around single-source depot contracts with adherence-monitoring service bundles. Integrated delivery networks in the United States are displacing traditional wholesaler relationships with direct manufacturer agreements that wrap medication with nursing administration and patient outreach. This bundling is most visible in Medicaid-managed care populations where states like Texas and Florida have mandated long-acting injectable first-line protocols for schizophrenia maintenance.
Atypical Antipsychotic Market Segmentation
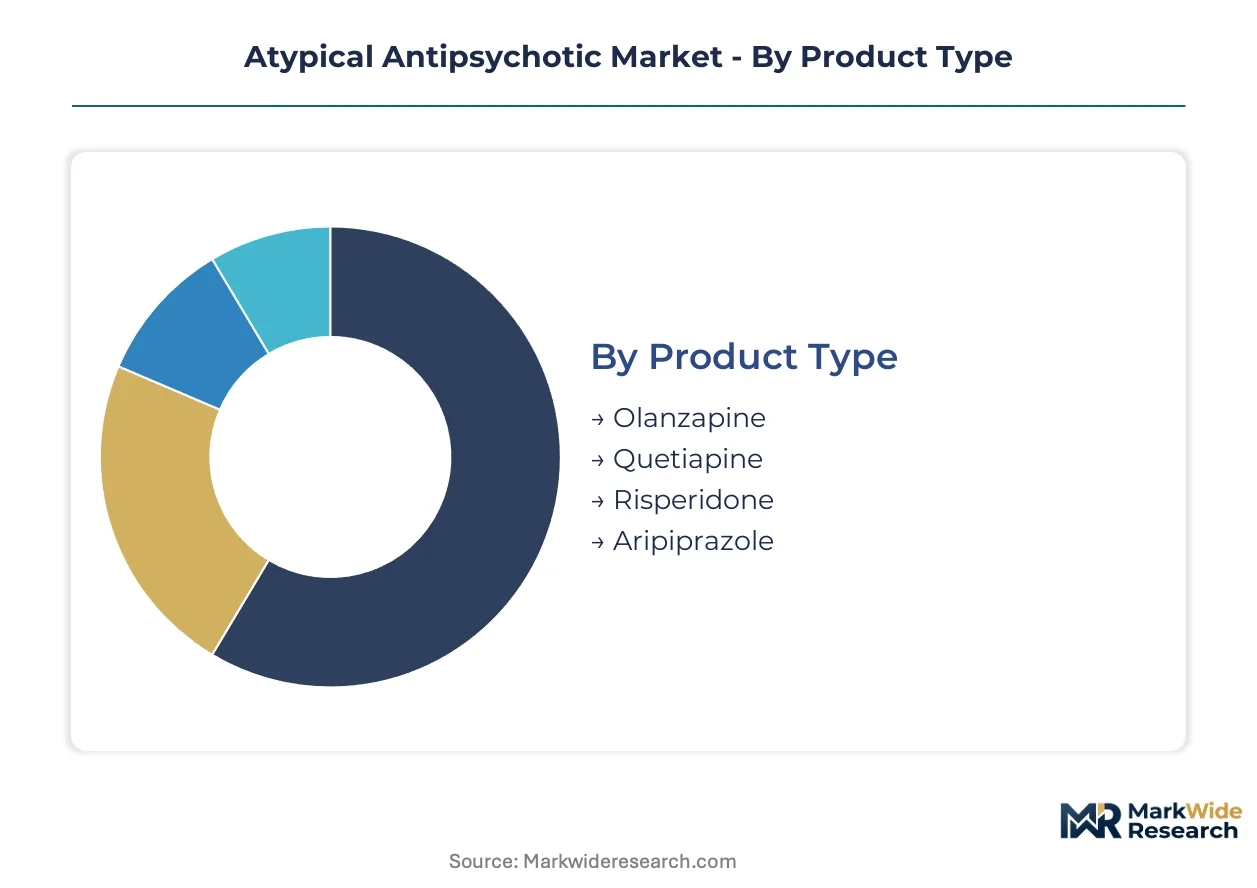
Segmentation in atypical antipsychotics reveals how formulation technology and care setting economics partition value capture. Product-level substitution pressures, delivery mode adherence premiums, and end-user procurement consolidation each create distinct competitive battlegrounds requiring tailored positioning strategies.
Product Type:
Substitution pressure from multi-source generics concentrates most intensely among the oral immediate-release molecules, where FDA bioequivalence pathways have eroded originator pricing power and compressed margin structures for all participants.
- Olanzapine:A thienobenzodiazepine derivative with potent 5-HT2A and D2 antagonism plus anticholinergic properties that drive metabolic side effect profiles. Hospital systems in Germany and the United States favor olanzapine for acute agitation protocols, though weight gain liability limits maintenance-phase prescribing in Medicaid-managed care populations.
- Aripiprazole:A D2 partial agonist with 5-HT1A partial agonism and 5-HT2A antagonism, producing a distinct activation profile versus pure antagonists. Eli Lilly's API production infrastructure and Janssen's depot formulation expertise have concentrated North American supply around aripiprazole long-acting injectables, where payer preference for reduced hospitalization exposure sustains premium positioning.
- Risperidone:A benzisoxazole derivative with high D2 affinity and prominent prolactin elevation effects. Polymeric microsphere depot technologies are displacing conventional oil-based formulations in academic medical centers.
- Quetiapine:A dibenzothiazepine with low D2 occupancy at therapeutic doses and prominent histamine H1 blockade. PMDA label gaps in bipolar maintenance create Japan-specific expansion headroom.
Olanzapine retains volume leadership across institutional channels; aripiprazole long-acting formulations hold the steepest expansion curve.
Therapy Area:
Cost tier stratification separates mature schizophrenia maintenance from emerging bipolar applications, where diagnostic broadening and depot protocol adoption are restructuring reimbursement benchmarks.
- Schizophrenia:The original indication cluster with established long-acting injectable protocols and centralized hospital formulary contracting. Texas and Florida Medicaid mandates for depot first-line maintenance have concentrated United States volume in this segment.
- Bipolar Disorder:A mood stabilizer adjunct category where quetiapine and aripiprazole maintenance studies are expanding prescriber familiarity beyond acute mania. Japan's incomplete PMDA label coverage for depot formulations in bipolar I disorder creates first-mover structuring opportunities for sponsors completing domestic trials.
- Depression:Adjunctive atypical antipsychotic use in treatment-resistant major depressive disorder, where oral formulations dominate due to primary care prescribing patterns and generic olanzapine-fluoxetine combination availability.
- Anxiety Disorder:Off-label and emerging indication territory with limited formal reimbursement pathways, concentrated in specialty psychiatric practice settings rather than primary care.
Schizophrenia commands the deepest volume pools; bipolar disorder maintenance protocols are climbing the fastest.
Delivery Mode:
Application-level differentiation centers on adherence engineering, where injection frequency and administration setting determine payer value assessment and procurement bundling structures.
- Oral:Immediate-release and extended-release tablet formulations with generic saturation in risperidone and olanzapine. Prescribing familiarity sustains largest revenue share despite price compression.
- Depot:Long-acting injectable formulations with 2-4 week dosing intervals that reduce medication possession ratio gaps. Integrated delivery networks in the United States are consolidating procurement around single-source depot contracts with adherence-monitoring service bundles.
- Injectable:Acute intramuscular formulations for rapid agitation control in emergency departments, where speed of onset and sedation depth determine formulary inclusion.
- Transdermal:Patch-based delivery systems with limited commercial penetration due to skin irritation rates and pharmacokinetic variability, though subcutaneous microsphere miniaturization may bridge this gap.
Oral formulations retain prescribing volume leadership; depot configurations are gaining share fastest through adherence-based contracting.
End User:
Customer-type procurement maturity separates centralized hospital pharmacy systems from fragmented home care channels, with distinct compliance infrastructure and outcome verification capabilities.
- Hospitals:Centralized Bundesland-level procurement in Germany and integrated delivery network contracting in the United States favor high-volume depot agreements with bundled nursing services.
- Specialty Pharmacies:Hub-and-spoke distribution models for long-acting injectables with patient outreach and administration scheduling capabilities, concentrated in Medicaid-managed care and commercial risk populations.
- Clinics:Outpatient psychiatric settings with mixed oral and injectable prescribing, where EHR interoperability gaps complicate adherence documentation for outcomes-based contracts.
- Home Care:Emerging administration setting for subcutaneous microsphere formulations, limited by nursing visit reimbursement and cold chain requirements.
Hospitals retain procurement volume leadership; specialty pharmacies are expanding fastest through adherence service bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across major markets. Hospital procurement in Germany tolerates premium depot formulations, while Medicaid-managed care in the United States drives aggressive generic substitution for oral agents. China's domestic manufacturers undercut multinational pricing by 40-60% in volume tenders.
United States
Integrated delivery networks in Texas and Florida have mandated long-acting injectable first-line protocols for schizophrenia maintenance, concentrating depot volume in Medicaid-managed care populations. FDA bioequivalence guidance for complex generics accelerates abbreviated new drug application pathways for follow-on depot entrants. Academic medical centers in Massachusetts and California are adopting polymeric microsphere formulations at twice the rate of conventional oil-based depots.
Germany
Centralized procurement at the Bundesland level creates volume aggregation that favors single-source depot contracts with bundled nursing services. EMA pharmacovigilance requirements under the EU Good Pharmacovigilance Practices framework mandate 6-monthly periodic safety update reports for depot formulations. Hospital pharmacy systems in Bavaria and North Rhine-Westphalia lead compliance transitions for REACH-registered polymer excipients in microsphere manufacturing.
China
NMPA streamlined review pathways for innovative psychiatric medicines compress registration timelines, drawing multinational Phase III investment toward domestic trial enrollment in Shanghai and Beijing. Provincial volume-based procurement drives 50-70% price reductions for oral generic antipsychotics. Local contract manufacturers in Jiangsu and Zhejiang supply over 60% of global atypical antipsychotic active pharmaceutical ingredient.
Japan
PMDA label expansion for quetiapine and aripiprazole long-acting injectables in bipolar I disorder remains incomplete, creating first-mover advantage for sponsors completing Japanese-specific maintenance studies. METI funding for digital biomarker pilot programs supports real-world evidence collection for adherence-engineered formulations. Psychiatric specialty hospitals in Tokyo and Osaka concentrate depot administration infrastructure.
India
Domestic formulation sponsors face CDSCO import license delays for European-sourced polymer excipients, forcing qualification of alternative solvent systems. Contract manufacturers in Hyderabad and Ahmedabad supply over 60% of global atypical antipsychotic API, exposing formulation sponsors to tariff volatility. Government mental health program expansion under the National Mental Health Mission drives volume growth in public sector procurement.
Atypical Antipsychotic Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the atypical antipsychotic market. Johnson & Johnson and Eli Lilly maintain captive active pharmaceutical ingredient production and depot formulation expertise that mid-tier developers cannot replicate. Three archetypes dominate: large-scale integrated manufacturers with backward control over API supply, regional co-commercialization specialists leveraging partnership structures, and generic-focused developers exploiting abbreviated new drug application pathways. Competitive moves concentrate on M&A for depot technology assets and strategic partnerships for Southeast Asian distribution.
Within the integrated tier, Johnson & Johnson and Eli Lilly exemplify manufacturers combining API production with formulation development. Otsuka Pharmaceutical occupies a position bridging originator and partnership models through co-commercialization structures. These three anchors represent distinct strategic postures: vertical control over manufacturing, geographic reach extension, and hybrid commercialization architectures.
| Leading Market Players |
|---|
| Eli Lilly and Company |
| Johnson & Johnson (Janssen Pharmaceuticals) |
| Otsuka Pharmaceutical Co., Ltd. |
| AstraZeneca PLC |
| Pfizer Inc. |
| H. Lundbeck A/S |
| Teva Pharmaceutical Industries Ltd. |
| AbbVie Inc. |
| Bristol-Myers Squibb Company |
| Others |
Supply Flow & Price Mechanics
Ninety-day active pharmaceutical ingredient inventory cycles in Indian contract manufacturing determine formulation sponsor exposure to both cost volatility and supply interruption. This lead-time band concentrates pricing power with API producers in Hyderabad and Ahmedabad while forcing European and North American sponsors into long-term offtake commitments that lock in margin structures.
Pricing Analysis
Adherence-monitoring service bundles drive lifetime value in depot formulation contracts, with integrated delivery networks in Texas and Florida capturing nursing administration and patient outreach under single-source agreements. Three-tier pricing structure across premium depot, standard oral branded, and economy oral generic levels separates hospital formulary tiers. Cost compression in immediate-release oral segments intensifies because FDA bioequivalence pathways have saturated risperidone and olanzapine markets with multi-source alternatives. Medicaid-managed care populations exhibit highest price sensitivity; academic medical centers with bundled adherence contracts show lowest.
Supply Chain Analysis
Port congestion on India-Europe pharmaceutical trade lanes exposes formulation sponsors to API delivery delays that cascade into manufacturing schedule disruptions. Active pharmaceutical ingredient production concentrates in India, China, and selected European sites, with over sixty percent of global atypical antipsychotic API routing through Indian contract manufacturers. Manufacturing rests on polymer excipient supply from REACH-registered European sources, oil-based depot vehicle stocks, and specialized microsphere encapsulation equipment. Single-source vulnerability pervades polymer excipient qualification, where ECHA substance of very high concern list revisions force reformulation cycles. Distribution runs through hospital pharmacy procurement systems and specialty pharmacy hub-and-spoke networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital formulary consolidation across Germany's Bundesland procurement systems and United States integrated delivery networks has shifted buyer power toward centralized pharmacy committees. This concentration fragments pricing leverage for manufacturers without depot formulation portfolios or adherence service capabilities.
For Market Incumbents: Secure captive active pharmaceutical ingredient production and depot formulation expertise to defend against generic depot entrants exploiting FDA bioequivalence guidance for complex generics. Backward integration into polymer microsphere manufacturing in Germany and the United States insulates against ECHA excipient regulatory revisions. Capacity addition in Indian API sourcing with dual-qualified European backup sites mitigates tariff exposure. For New Entrants and Emerging Players: Differentiate on digital biomarker integration with FDA real-world evidence pilot programs to capture premium reimbursement positioning against standard depot formulations. Japan's incomplete PMDA label coverage for quetiapine and aripiprazole long-acting injectables in bipolar I disorder represents the most penetrable geography. Co-commercialization structures with Southeast Asian regional distributors bypass direct infrastructure investment while accessing mental health expansion budgets in Indonesia, Thailand, and Vietnam. For Investors and Strategic Acquirers: Long-term, this sits as a formulation-technology consolidation play because depot expertise scarcity concentrates value capture with sponsors possessing population PK/PD modeling capabilities and polymer microsphere manufacturing assets. Acquisition target archetype: mid-tier developers with Phase III-ready long-acting injectable assets but limited regulatory infrastructure. Signal to watch is FDA guidance finalization on digital biomarker acceptance for adherence labeling claims.| Strategic Initiative | Industry Significance |
|---|---|
| Depot Formulation Technology Acquisition | Polymeric microsphere expertise secures premium positioning in academic medical center procurement. |
| FDA Real-World Evidence Pilot Participation | Sensor-derived adherence data supports differentiated reimbursement claims against standard of care. |
| Co-Commercialization Partnership Expansion | Regional distributor alliances in Southeast Asia bypass direct infrastructure requirements. |
| REACH-Compliant Polymer Excipient Qualification | Alternative solvent systems insulate European manufacturing from ECHA regulatory revision. |
| Japanese Bipolar Maintenance Trial Completion | PMDA label expansion captures first-mover advantage in underpenetrated maintenance protocols. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA pharmacovigilance databases, ClinicalTrials.gov entries, and hospital formulary records. Drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists provided qualitative input on depot formulation investment priorities and reimbursement dynamics. Bottom-up patient volume estimates by therapy area and delivery mode triangulate against top-down manufacturer revenue disclosures.
Segmentation dimensions modeled include product molecule, therapy area indication, delivery mode configuration, and end-user procurement channel across the analysis window. Compound annual growth rate derivation incorporates patent expiry schedules, generic entry timelines, and long-acting injectable protocol adoption curves. Population PK/PD simulation outputs and real-world medication possession ratio data inform formulation-specific penetration assumptions.
Forecasts assume regulatory continuity in FDA bioequivalence guidance, EMA pharmacovigilance periodic safety update report requirements, and NMPA innovative psychiatric medicine review pathways; material policy shifts would require re-modeling. Specific risk factors include API supply disruption from Indian contract manufacturing, REACH polymer excipient reclassification, and Medicaid-managed care oral generic substitution mandates. Recalibration cycles align with material shifts in depot formulation FDA approvals and hospital procurement bundling adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Meglitinide Market
Pharmaceuticals
United States Insulin Drugs and Delivery Devices Market
Pharmaceuticals
Global Nasal Drug Delivery Market
Pharmaceuticals
Bulbospinal Muscular Atrophy Drugs Market
Pharmaceuticals
Antiepileptic Drugs (AED) Market
Pharmaceuticals
Global Antacids Market
Pharmaceuticals
OTC Dry Eye Drops Market
Pharmaceuticals
Cancer Immunotherapy Drug Discovery Outsourcing Market
Pharmaceuticals
Ceftriaxone Sodium (API) Market
Pharmaceuticals
Indobufen API Market
Pharmaceuticals
Pharmaceutical Grade Lactose Market
Pharmaceuticals
Respiratory Virus Vaccines Market
Pharmaceuticals
Global Nizatidine Market
Pharmaceuticals
Europe Dipeptide Peptidase 4 (DPP-4) Inhibitors Market
Pharmaceuticals
Global Sterile Injectable Drugs Market
Pharmaceuticals
Tinea Versicolor Treatment Market