
 Liquid Filled Hard Capsules Market | 2026-2036
Liquid Filled Hard Capsules Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Filled Hard Capsules Market Outlook
Continuous manufacturing integration is tilting liquid-filled capsule production away from batch-oriented setups toward streamlined, quality-by-design workflows. Lonza Group Ltd. leverages its integrated CDMO platform to anchor high-value pharmaceutical contracts across North America and Europe. Catalent Inc. sustains competitive differentiation through specialized softgel and liquid-fill expertise at scale. ACG dominates the vegetarian capsule substrate segment with dedicated HPMC supply chains that serve formulation-sensitive clients.
Liquid filled hard capsules are dosage forms wherein active pharmaceutical ingredients, oils, or suspensions are sealed within rigid gelatin or hypromellose shells, typically accommodating fill volumes of 0.25–1.0 mL with shell wall thicknesses calibrated for gastric release profiles. Their primary purpose centers on improving bioavailability of lipophilic or poorly water-soluble compounds while enabling taste-masking and precise unit-dose delivery. Vegetarian capsules now lead product-type growth as EMA and FDA guidelines tighten around bovine-sourced gelatin traceability, with enteric-coated variants capturing premium margin pools in proton pump inhibitor and enzyme formulations. Pharmaceutical companies remain the dominant end-user channel, though contract manufacturers are expanding fastest as Big Pharma outsources liquid-fill capacity to avoid capital-intensive shell-forming investments.
FDA dissolution standards and EMA GMP Annex 1 revisions on containment and cross-contamination directly shape facility investment requirements and product approval timelines for liquid-filled formats. ISO 15378 primary packaging standards and USP <905> uniformity of dosage units further constrain which manufacturers can supply regulated markets. Stakeholders must monitor how evolving pharmacopeial standards for extractables and leachables from capsule shells reshape supplier qualification protocols and raw material sourcing decisions.
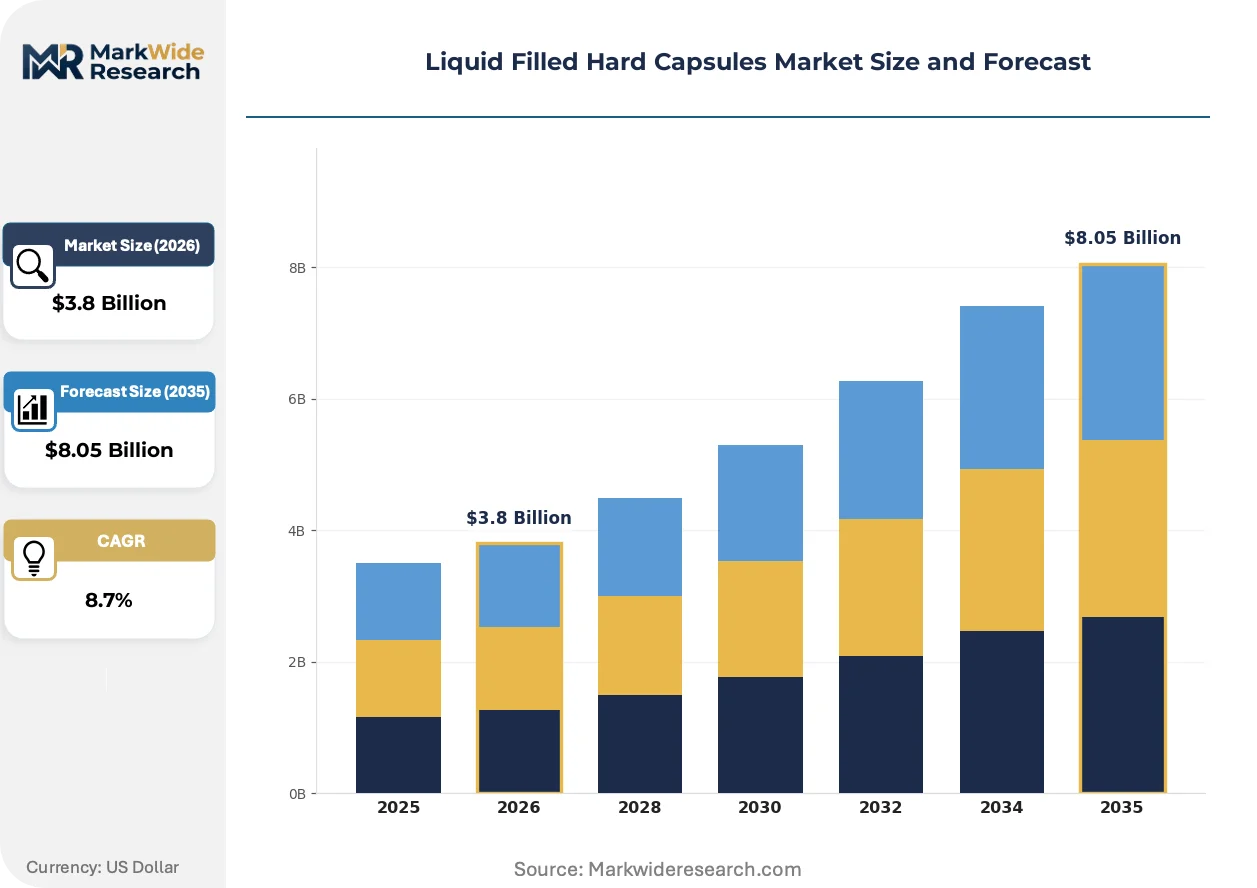
Market Dynamics
Continuous manufacturing integration is displacing batch-oriented liquid-fill operations as pharmaceutical manufacturers pursue quality-by-design workflows and real-time release testing to meet tightening FDA bioequivalence standards.
Growth Catalysts
- Poorly Soluble API Formulation Demand:Lipophilic compound pipelines at major pharmaceutical firms are expanding, creating pull for lipid-based delivery systems that hard capsules accommodate.
- EMA GMP Annex 1 Revisions:Containment and cross-contamination mandates are accelerating facility upgrades that favor sealed liquid-fill processes over open powder handling.
- Vegetarian Capsule Substrate Momentum:HPMC shell adoption is concentrating in Germany and Switzerland as bovine gelatin traceability requirements tighten across European supply chains.
Market Restraints
- Gelatin Price Volatility:Bovine and porcine raw material costs fluctuate with livestock supply cycles, compressing margins for gelatin-dependent capsule manufacturers.
- Specialized Equipment Concentration:Liquid-fill encapsulation machinery production centers on German and Italian engineering clusters, creating supply bottleneck risks.
- Enteric Coating Technical Limits:pH-dependent release consistency remains challenging for proton pump inhibitor formulations, limiting application expansion.
Strategic Opportunities
- India CDMO Capacity Expansion:Domestic pharmaceutical outsourcing demand is outpacing local liquid-fill infrastructure, creating white space for dedicated facility investment.
- Orphan Drug Designation Tailwinds:FDA and EMA incentives for rare disease therapies favor unit-dose formats that liquid-filled capsules provide.
- Biosimilar Convergence:Peptide and protein formulation needs are intersecting with lipid nanoparticle expertise, opening hybrid delivery development paths.
Industry Challenges
- Extractables and Leachables Validation:USP and EP protocols for shell polymer characterization are extending supplier qualification timelines by 12-18 months.
- Continuous Manufacturing Talent Scarcity:Process analytical technology and real-time release testing expertise remains concentrated among a narrow specialist workforce.
- Legacy Batch System Integration:Retrofitting existing hard capsule lines for liquid-fill capability requires substantial capital outlay and facility downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Filled Hard Capsules Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Capsules, Gelatin Capsules, Vegetarian Capsules, Enteric-Coated Capsules End User: Pharmaceutical Companies, Nutraceutical Manufacturers, Contract Manufacturers, Research Laboratories Application: Vitamins, Dietary Supplements, Pharmaceuticals, Herbal Products Packaging Type: Bottles, Blisters, Pouches, Jars |
| Companies Covered | Lonza Group Ltd., Catalent Inc., ACG, Thermo Fisher Scientific Inc., Sirio Pharma Co. Ltd., Healthcaps India Ltd., Lefancaps LTD., Altasciences, Qualicaps, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Filled Hard Capsules Market Strategic Shifts
Formulation science, regulatory science, and manufacturing technology are converging to reshape how liquid-filled capsules are developed, validated, and supplied to regulated markets.
Hot-melt extrusion paired with lipid-based formulation science is hybridizing traditional liquid-fill processes, enabling thermosensitive APIs to enter capsule formats previously restricted to room-temperature fills. Specialty pharmaceutical developers in Switzerland and Massachusetts are piloting these integrated workflows. The technology is compressing development timelines for poorly soluble compounds while demanding new equipment qualification standards.
REACH restrictions on pharmaceutical excipients are forcing European manufacturers to requalify shell plasticizers and colorants, triggering raw material sourcing shifts toward bio-based alternatives. The industrial consequence is a supplier consolidation wave as smaller chemical houses exit the certified excipient market. Oral solid dosage producers in Germany and the Netherlands are responding by locking in multi-year supply agreements with compliant vendors.
Big Pharma procurement departments are unbundling liquid-fill manufacturing from traditional oral dose contracting, creating dedicated vendor panels for specialized capsule formats. CDMOs with integrated shell-forming and fill-seal capabilities are capturing these disaggregated contracts. This pattern is most visible in New Jersey and Basel, where pharmaceutical headquarters proximity drives supplier selection criteria.
Liquid Filled Hard Capsules Market Segmentation
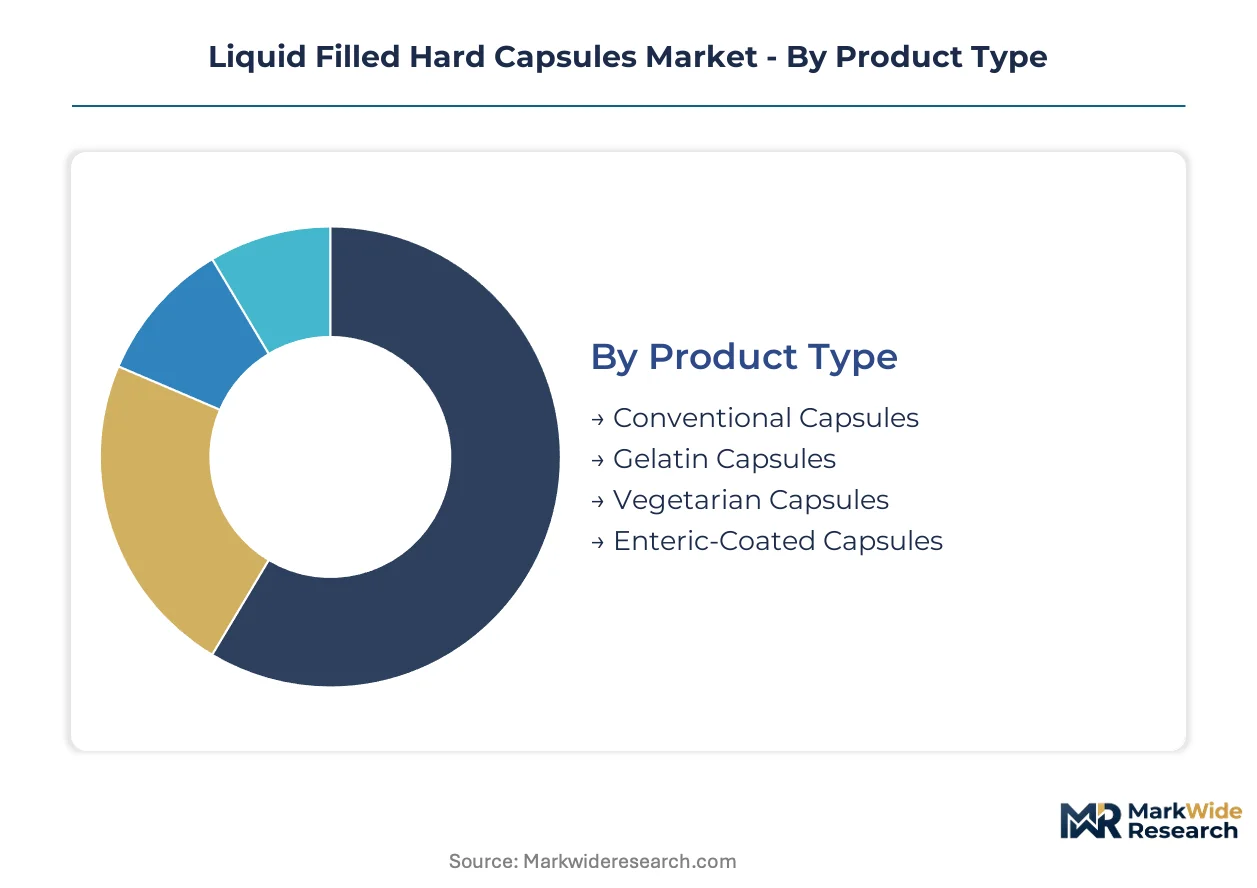
Liquid filled hard capsules serve distinct formulation requirements across pharmaceutical, nutraceutical, and consumer health sectors. Segmentation reveals how shell chemistry, end-user capabilities, and packaging formats align with regulatory pathways and commercial scale.
Product Type:
Mature gelatin formats dominate current volumes while vegetarian alternatives accelerate on EMA and FDA traceability mandates.
- Conventional Capsules:Standard gelatin or HPMC shells without specialized coatings, offering baseline protection for non-reactive fills. Demand concentrates among generic pharmaceutical manufacturers in India seeking cost-optimized oral dose solutions.
- Gelatin Capsules:Bovine and porcine-derived shells provide proven barrier properties and established dissolution profiles. Switzerland's specialized CDMOs anchor procurement for high-value lipid-based formulations requiring validated release kinetics.
- Vegetarian Capsules:HPMC and pullulan alternatives address religious dietary restrictions and bovine spongiform encephalopathy concerns.
- Enteric-Coated Capsules:pH-resistant polymers enable intestinal release for acid-labile APIs.
Gelatin capsules handle the majority of throughput; vegetarian capsules are the fastest mover on share.
End User:
Customer capabilities range from fully integrated pharmaceutical operations to outsourced development specialists.
- Pharmaceutical Companies:Internal liquid-fill capacity supports proprietary pipeline assets and lifecycle management strategies. Big Pharma headquarters in New Jersey and Basel drive vendor qualification standards for specialized capsule formats.
- Nutraceutical Manufacturers:Omega-3, vitamin D, and coenzyme Q10 formulations favor liquid-filled hard capsules for oxidation protection and precise dosing. Demand clusters among direct-to-consumer brands seeking differentiated delivery formats.
- Contract Manufacturers:CDMOs with integrated shell-forming and fill-seal capabilities capture disaggregated procurement contracts.
- Research Laboratories:Early-phase formulation development requires flexible batch sizes and rapid shell customization.
Pharmaceutical companies retain the largest procurement volumes; contract manufacturers are expanding most quickly as outsourcing deepens.
Application:
Formulation requirements vary sharply between regulated drug products and consumer health categories.
- Vitamins:Lipid-soluble vitamins A, D, E, and K require oil-based carriers that hard capsules accommodate without emulsification challenges. German and Swiss manufacturers lead formulation science for stability-optimized fills.
- Dietary Supplements:Botanical extracts and marine oils demand oxygen and light barrier properties.
- Pharmaceuticals:Poorly soluble APIs drive adoption of lipid-based drug delivery systems with demonstrated bioavailability enhancement.
- Herbal Products:Standardized plant extracts with bitter or volatile compounds benefit from taste-masking and sealed unit-dose presentation.
Pharmaceutical applications command premium pricing tiers; dietary supplements show the steepest expansion trajectory on volume.
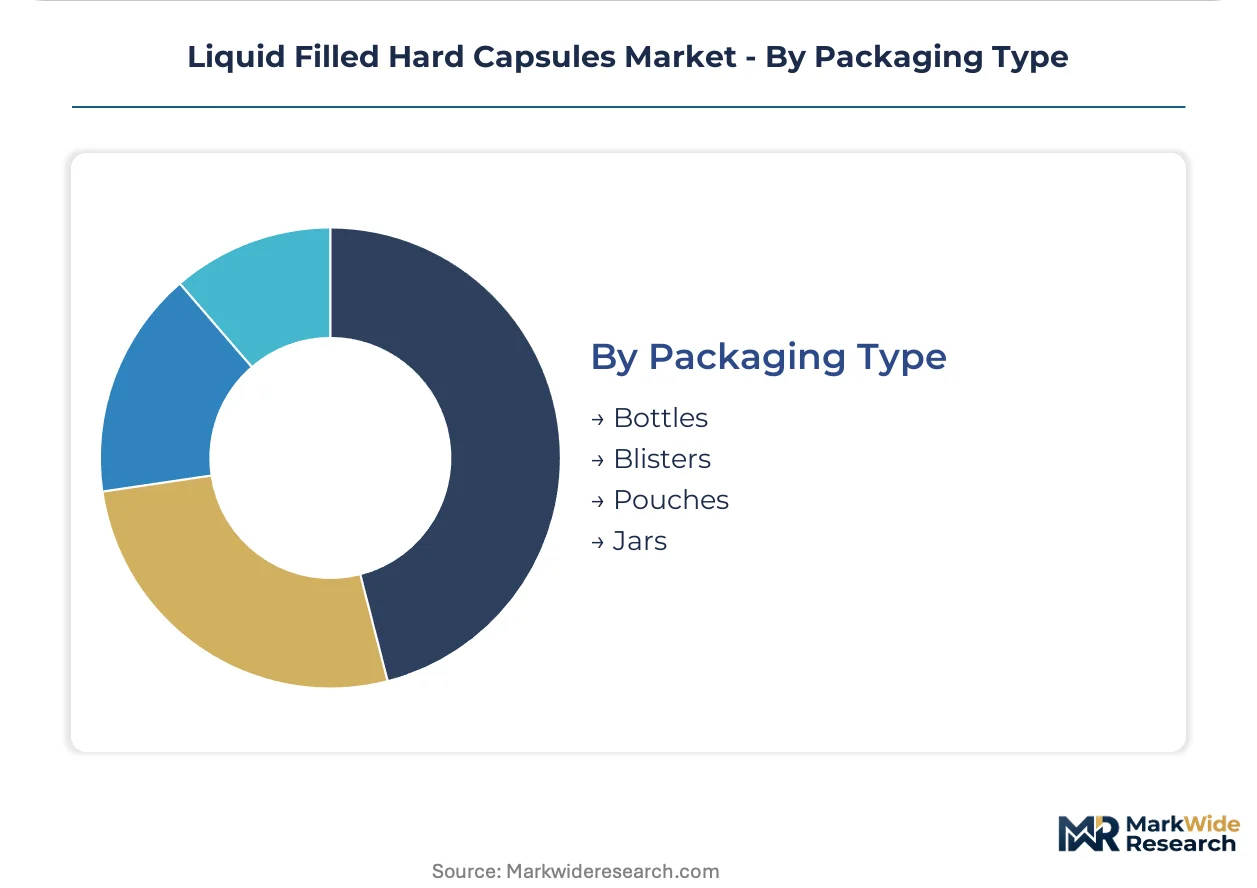
Packaging Type:
Primary packaging selection balances moisture protection, patient compliance, and distribution economics.
- Bottles:High-density polyethylene and glass containers support count-based dispensing for chronic therapies. US retail pharmacy distribution favors bottles for cost efficiency at scale.
- Blisters:Cold-form aluminum and thermoformed films provide unit-dose integrity with tamper evidence. European markets prefer blisters for adherence packaging and hospital unit-dose requirements.
- Pouches:Flexible laminates enable sample quantities and travel-size formats.
- Jars:Wide-mouth containers accommodate bulk nutraceutical formats and institutional dispensing.
Bottles handle the majority of throughput; blisters are gaining share fastest on unit-dose compliance trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swiss CDMOs export liquid-fill capacity to German and US pharmaceutical headquarters, anchoring the trade corridor that supplies lipid-based formulation expertise to multinational drug developers.
United States
FDA bioequivalence standards for poorly soluble APIs drive demand for advanced capsule technologies. The agency's dissolution testing protocols constrain which manufacturers qualify for ANDA submissions. New Jersey's pharmaceutical corridor hosts vendor qualification panels that disaggregate liquid-fill procurement from traditional oral dose contracting.
Germany
EMA GMP Annex 1 containment mandates accelerate facility upgrades favoring sealed liquid-fill processes. REACH restrictions on pharmaceutical excipients force requalification of shell plasticizers and colorants. The Rhine-Main cluster concentrates specialized CDMOs with dedicated HPMC supply chains for vegetarian capsule production.
Switzerland
Swissmedic quality guidelines reinforce stringent traceability requirements for bovine-sourced materials. Basel's pharmaceutical headquarters proximity drives supplier selection criteria for high-value lipid-based formulations. The country's specialized CDMOs anchor procurement contracts requiring validated release kinetics.
India
Domestic pharmaceutical outsourcing demand outpaces local liquid-fill infrastructure, creating white space for facility investment. CDSCO regulations on primary packaging standards constrain supplier qualification for regulated export markets. Maharashtra and Gujarat host emerging contract manufacturers expanding shell-forming and fill-seal capabilities.
China
NMPA pharmacopeial standards for extractables and leachables extend supplier qualification timelines. The Yangtze River Delta concentrates engineering clusters producing liquid-fill encapsulation machinery. Zhejiang and Jiangsu provinces see CDMO capacity expansion serving both domestic and export pharmaceutical demand.
Liquid Filled Hard Capsules Market Competitive Environment
Channel-controlling players compete with product-specialist players across a tiered structure where scale advantages concentrate among integrated CDMOs and substrate technology holders. The vendor base organizes around three archetypes: integrated pharmaceutical service platforms, specialized capsule substrate manufacturers, and regional contract manufacturers with fill-seal capabilities. Dominant competitive moves include capacity expansion in vegetarian shell production and strategic partnerships linking formulation science with manufacturing scale.
Among integrated service platforms, Lonza Group Ltd. and Catalent Inc. occupy positions anchoring high-value pharmaceutical contracts across North America and Europe. ACG represents the specialized substrate tier with dedicated HPMC supply chains serving formulation-sensitive clients. These three companies exemplify how competitive positioning stratifies between full-service integration and focused component specialization.
| Leading Market Players |
|---|
| Lonza Group Ltd. |
| Catalent Inc. |
| ACG |
| Thermo Fisher Scientific Inc. |
| Sirio Pharma Co. Ltd. |
| Healthcaps India Ltd. |
| Lefancaps LTD. |
| Altasciences |
| Qualicaps |
| Others |
Value Chain & Pricing Dynamics
The Rhine-Alpine freight corridor connects German shell-forming equipment manufacturers to Swiss CDMOs and US pharmaceutical headquarters, with container rates on this lane directly feeding into the cost structures that separate premium lipid-based formulations from commoditized gelatin fills. This logistics backbone reinforces how geographic concentration of HPMC supply chains in Germany and Switzerland enables price differentiation between vegetarian and bovine-sourced capsule tiers.
Pricing Analysis
Technology-generation pricing gaps separate legacy batch-processed gelatin capsules from continuous-manufacturing-ready vegetarian formats and next-generation enteric-coated variants with validated release kinetics. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with FDA-validated release profiles commanding substantial premiums over generic dissolution specifications. Pricing pressure stems from gelatin raw material volatility as livestock supply cycles compress margins for bovine-dependent manufacturers. Generic pharmaceutical manufacturers in India exhibit the highest price sensitivity, while Swiss CDMOs serving Big Pharma headquarters in Basel demonstrate minimal elasticity for validated lipid-based formulations.
Supply Chain Analysis
Upstream feedstock for HPMC vegetarian shells draws from cellulose ether production concentrated in Germany, the United States, and Japan, while gelatin supply rests on bovine and porcine processing clusters in Brazil, Argentina, and select European markets. Key inputs include pharmaceutical-grade hypromellose, plasticizers for shell flexibility, and enteric coating polymers for pH-dependent release applications. Single-source vulnerability characterizes liquid-fill encapsulation machinery, with German and Italian engineering houses controlling specialized equipment production. Distribution runs through CDMO platforms with integrated shell-forming and fill-seal capabilities, which pharmaceutical procurement panels increasingly favor over fragmented component suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated pharmaceutical procurement panels that disaggregate liquid-fill contracting from traditional oral dose suppliers, fragmenting vendor relationships as Big Pharma headquarters in New Jersey and Basel centralize vendor qualification standards.
For Market Incumbents: Pre-empt emerging vegetarian capsule specialists by locking multi-year HPMC supply agreements with German cellulose ether producers before REACH restrictions tighten further. Anchor capacity expansion in Switzerland to capture proximity premiums from Basel pharmaceutical headquarters, while investing in continuous manufacturing qualification to defend against batch-processed substitutes from Indian contract manufacturers. For New Entrants and Emerging Players: Build out dedicated liquid-fill infrastructure in Maharashtra and Gujarat to capture domestic Indian pharmaceutical outsourcing demand that currently outpaces local supply. Target orphan drug developers seeking unit-dose formats for rare disease therapies, leveraging FDA and EMA incentive pathways as the most penetrable regulatory entry point. Position through specialized lipid-based formulation expertise rather than commoditized shell production. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underutilized pharmaceutical excipient divisions that hold REACH-compliant HPMC supply chains but lack liquid-fill manufacturing integration. Long-term viability hinges on continuous manufacturing adoption and vegetarian substrate conversion trends across the analysis window. Monitor CDSCO regulatory alignment with FDA and EMA standards as the critical signal for Indian contract manufacturer export competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Vegetarian Shell Capacity Expansion | HPMC supply chain investments in Germany and Switzerland capture EMA traceability mandate premiums. |
| Continuous Manufacturing Integration | Quality-by-design workflows at Lonza and Catalent facilities meet tightening FDA bioequivalence standards. |
| REACH-Compliant Excipient Requalification | Bio-based plasticizer sourcing agreements lock in European market access ahead of regulatory deadlines. |
| India CDMO Facility Investment | Maharashtra and Gujarat liquid-fill capacity addresses domestic outsourcing demand outpacing local infrastructure. |
| Orphan Drug Format Development | Unit-dose liquid-filled capsules align with FDA and EMA incentives for rare disease therapy delivery. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pharmaceutical formulation scientists, CDMO operations directors, regulatory affairs specialists, and procurement managers at Big Pharma headquarters. Secondary validation drew from FDA ANDA filings, EMA GMP inspection reports, USP pharmacopeial updates, and customs trade data for encapsulation machinery imports. Bottom-up capacity assessments at German, Swiss, and Indian manufacturing facilities were triangulated against top-down pharmaceutical pipeline analysis for poorly soluble API candidates.
Calibration against historical capacity utilization rates and announced facility expansions anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include shell chemistry, end-user capability tier, application regulatory pathway, packaging format, and regional regulatory cluster. CAGRs were derived from growth driver elasticity analysis applied to baseline penetration rates, with specific inputs including lipid-based formulation pipeline counts at major pharmaceutical firms and EMA GMP Annex 1 compliance investment schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Indian contract manufacturers or Chinese equipment producers would shift outcomes beyond modeled ranges. Cross-checking against CDSCO regulatory alignment progress and FDA dissolution standard update timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Trisenox Market
Pharmaceuticals
Global Orphan Drugs Market
Pharmaceuticals
Antibiotic-Associated Diarrhea Treatment Market
Pharmaceuticals
Italy OTC Drugs Market
Pharmaceuticals
Cardiometabolic Drugs Market
Pharmaceuticals
Epigenetics Drugs and Diagnostic Technologies Market
Pharmaceuticals
Human Growth Hormone Treatment and Drugs Market
Pharmaceuticals
Sulfonylureas Market
Pharmaceuticals
MRSA Antibiotic Preparations Market
Pharmaceuticals
Herbal Drugs Market
Pharmaceuticals
Latin America Dipeptide Peptidase 4 (DPP-4) Inhibitors Market
Pharmaceuticals
Second Generation Cephalosporins Market
Pharmaceuticals
Enbrel Market
Pharmaceuticals
Tunisia Pharmaceutical Market
Pharmaceuticals
Global Anti-Infective Agents Market
Pharmaceuticals
Nasal Vaccines Market