
 Motilium Market | 2026-2036
Motilium Market Size, Share, and Industry Trends Forecast 2026-2036
Motilium Market Insights
Single-source API procurement for domperidone is restructuring into multi-source qualification programs across generic supply chains. Novartis AG sustains brand recognition in regulated European markets through legacy positioning. Dr. Reddy's Laboratories Ltd. leverages vertically integrated API-to-finished-dose capabilities to compete on cost in emerging markets. Lupin Limited anchors its presence in India through deep pharmacy distribution networks.
Motilium (domperidone) is a dopamine D2-receptor antagonist with a piperidinyl-benzimidazolone core, formulated as 10 mg tablets or 1 mg/mL oral suspension, primarily indicated for gastrokinetic and antiemetic therapy. The compound enhances gastric motility through increased lower esophageal sphincter pressure and accelerated gastric emptying. Tablet formulations dominate volume due to manufacturing simplicity and patient compliance, while oral suspension captures pediatric gastroenterology segments where dose flexibility matters. Hospital procurement of injectable domperidone commands premium positioning in acute postoperative nausea protocols.
The FDA maintains domperidone's unapproved status, restricting importation to investigational-use pathways, while Health Canada permits prescription access under PMRA-monitored risk management. EMA's pharmacovigilance requirements mandate cardiac safety screening before domperidone initiation across EU member states. Stakeholders must monitor evolving cardiac QT-prolongation risk assessments that could trigger further label restrictions or formulation withdrawals.
Market Dynamics
EMA's restricted-label guidance for domperidone is fragmenting prescription patterns across European hospital networks while Indian pharmacy chains absorb displaced volume through cost-competitive oral formulations.
Growth Catalysts
- Postoperative nausea protocols:Tertiary hospital gastroenterology departments in India and Brazil are standardizing domperidone as first-line antiemetic therapy in surgical recovery wards.
- CDSCO streamlined approval pathways:India's national pharmaceutical regulator has accelerated generic bioequivalence reviews for domestic manufacturers supplying pharmacy networks.
- Pediatric formulation demand:Oral suspension formats are capturing volume in pediatric gastroenterology segments where dose flexibility outweighs tablet convenience.
Market Restraints
- Cardiac QT-prolongation screening:EMA pharmacovigilance mandates require electrocardiogram baseline testing before domperidone initiation, adding procedural friction in EU member states.
- Single-source API concentration:Active pharmaceutical ingredient production for domperidone concentrates in select Indian and Chinese chemical manufacturing clusters, creating supply vulnerability.
- 5-HT3 antagonist substitution:Ondansetron and granisetron formulations are displacing domperidone in oncology-associated nausea protocols across North American and European markets.
Strategic Opportunities
- Sub-Saharan Africa pharmacy networks:Underpenetrated distribution infrastructure in Nigeria and Kenya presents whitespace for cost-effective oral tablet formulations.
- Hospital-at-home expansion:Post-acute care models in Germany and the Netherlands are creating demand for patient-administered antiemetic therapies outside institutional settings.
- Modified-release formulation development:Extended-release domperidone technologies are converging with cardiac safety monitoring to address EMA dosing-duration restrictions.
Industry Challenges
- Cardiac safety data requirements:Thorough QT study protocols and periodic safety update reports demand specialized clinical pharmacology expertise that mid-scale generic manufacturers struggle to retain.
- Multi-source API qualification timelines:Reconfiguring supply chains away from concentrated chemical manufacturers requires 18-24 month validation cycles for alternative raw material suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motilium Market |
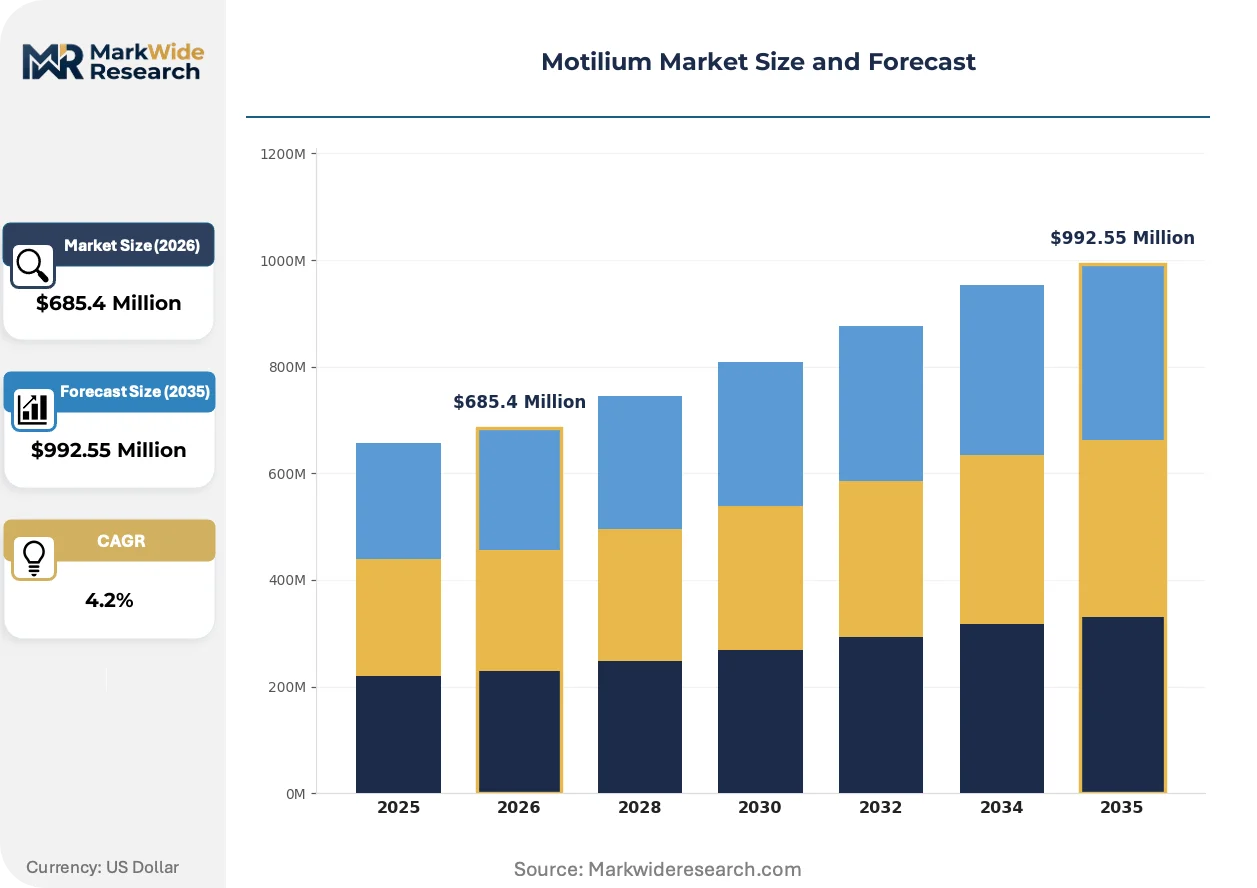
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $992.55 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Oral Suspension, Injection End User: Hospitals, Pharmacies, Clinics, Homecare Administration Route: Oral, Injectable, Topical, Transdermal Therapy Area: Gastroenterology, Neurology, Pediatrics, Others |
| Companies Covered | Novartis AG, Lupin Limited, Abbott Laboratories, GlaxoSmithKline PLC, Pfizer Inc, AstraZeneca Plc, Merck Co., Ltd., Dr. Reddy's Laboratories Ltd., Schwitz Biotech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motilium Market Trends and Innovations
Formulation science and cardiac risk stratification are converging to reshape how domperidone products reach prescribing physicians. Manufacturers are racing to differentiate through delivery mechanisms and safety profiling rather than commodity pricing alone.
Modified-release domperidone technologies are converging with biomarker-guided patient selection to reduce peak plasma concentrations while preserving gastrokinetic efficacy. Early adopters in German and Dutch hospital pharmacy committees are piloting these formulations in high-risk geriatric populations. The structural consequence is compressing market share for conventional immediate-release tablets in regulated European markets.
EMA's 2023 updated product information requirements for domperidone are forcing manufacturers to integrate cardiac safety databases into routine pharmacovigilance workflows. The industrial consequence is elevated regulatory affairs staffing costs and extended launch timelines for new market entrants. Generic suppliers in Poland and Romania are responding by consolidating dossier preparation through specialized contract research organizations.
Hospital procurement committees are consolidating antiemetic purchasing through therapeutic class tenders rather than molecule-specific contracts. This behavior is disrupting traditional pharmaceutical sales representative access and replacing it with centralized pharmacy and therapeutics committee decision-making. The shift is most visible in France and Italy where regional hospital group purchasing organizations now dominate volume allocation.
Motilium Market Segmentation
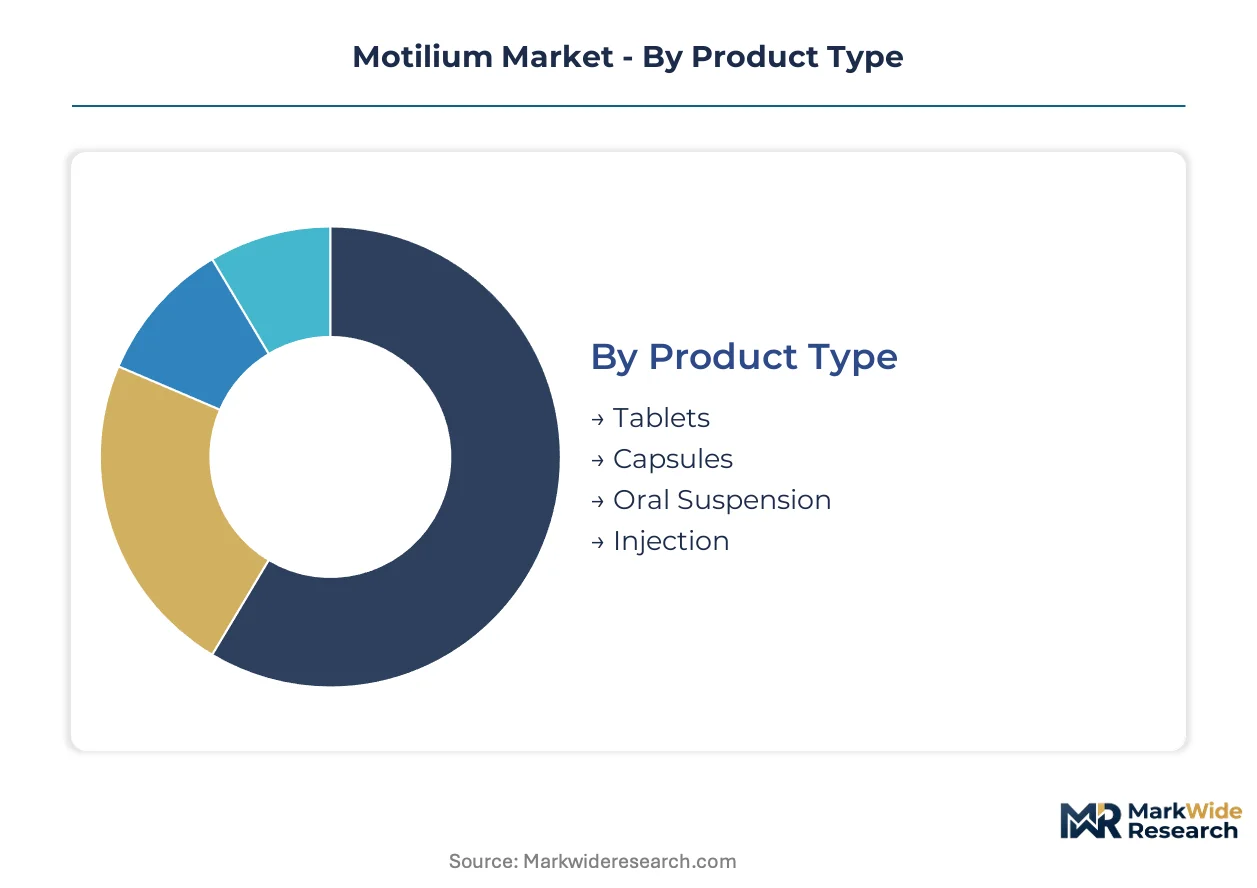
Domperidone's formulation diversity and administration flexibility create distinct procurement channels and prescribing behaviors across healthcare settings. Understanding how product formats, delivery sites, and therapeutic applications partition demand reveals where manufacturers must align supply capabilities with clinical workflow requirements.
Product Type:
Cost tier separates chronic therapy maintenance from acute intervention formats.
- Tablets:Compressed 10 mg domperidone base formulations dominate manufacturing scale due to process simplicity and ambient stability. Tertiary hospital formularies in India and Brazil standardize tablet procurement for outpatient gastroenterology protocols where compliance monitoring is feasible.
- Oral Suspension:Aqueous 1 mg/mL formulations enable weight-based dosing precision in pediatric populations. German and Dutch hospital-at-home programs are piloting suspension formats for geriatric patients with dysphagia, though cold chain requirements constrain pharmacy distribution reach.
- Capsules:Gelatin-encapsulated variants offer taste masking for patients with medication aversion. Limited differentiation from tablets restricts volume to niche compliance-focused segments.
- Injection:Intravenous domperidone commands premium positioning in acute postoperative nausea protocols where oral intake is contraindicated. Restricted to institutional settings due to cardiac monitoring requirements.
Tablets lead volumes today; oral suspension is gaining share fastest.
End User:
Procurement sophistication and reimbursement pathways fragment buyer power across the care continuum.
- Hospitals:Centralized pharmacy and therapeutics committees govern therapeutic class tenders in France and Italy, consolidating antiemetic purchasing through regional group purchasing organizations. EMA cardiac safety mandates require electrocardiogram baseline screening infrastructure that only institutional settings maintain.
- Pharmacies:Indian retail pharmacy chains absorb displaced European volume through cost-competitive oral formulations supplied by domestic manufacturers with vertically integrated API capabilities. CDSCO streamlined approval pathways accelerate generic substitution.
- Clinics:Ambulatory gastroenterology practices in Brazil prescribe domperidone for functional dyspepsia management. Limited diagnostic capacity restricts use to empiric therapy rather than protocol-driven selection.
- Homecare:Post-acute care models in Germany and the Netherlands create demand for patient-administered antiemetic therapies outside institutional settings. Reimbursement fragmentation limits consistent access.
Hospitals anchor procurement value; pharmacies are expanding volume most rapidly.
Administration Route:
Patient condition severity and absorption reliability determine route selection.
- Oral:Gastrointestinal absorption variability influences time-to-onset in fasting versus fed states. Standard for maintenance therapy across all geographies where domperidone is approved.
- Injectable:Bioavailability certainty justifies premium pricing in perioperative settings. Restricted distribution due to QT-prolongation risk monitoring requirements.
- Topical:Transdermal absorption of domperidone remains investigational with no approved formulations. Preclinical programs explore bypassing first-pass metabolism.
- Transdermal:Patch-based delivery systems are not commercially available. Academic research continues on sustained-release skin permeation technologies.
Oral administration dominates prescription volumes; injectable formats command highest per-dose revenue.
Therapy Area:
Clinical evidence depth and guideline endorsement shape prescribing authority.
- Gastroenterology:Dopamine D2-receptor antagonism enhances lower esophageal sphincter pressure and accelerates gastric emptying. Tertiary hospital departments in India and Brazil standardize domperidone as first-line antiemetic therapy in surgical recovery wards.
- Pediatrics:Oral suspension formats capture volume where dose flexibility outweighs tablet convenience. Weight-based prescribing requires pharmacy compounding capabilities or manufactured suspension availability.
- Neurology:Domperidone addresses dopaminergic medication-induced nausea in Parkinson's disease patients. Limited label indications restrict formal promotion despite clinical utility.
- Others:Off-protocol use in oncology-associated nausea faces displacement by 5-HT3 antagonists. Ondansetron and granisetron formulations dominate this segment in North American and European markets.
Gastroenterology generates the steepest prescription trajectory; pediatrics is climbing fastest among approved indications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian pharmaceutical manufacturing clusters in Hyderabad and Mumbai anchor domperidone API production, while European hospital networks absorb reformulated volumes under tightened cardiac monitoring protocols. Regulatory divergence between EMA restrictions and CDSCO facilitation is redrawing prescription geography.
India
Domestic manufacturers in Hyderabad and Mumbai supply cost-effective oral tablets through deep pharmacy distribution networks. CDSCO streamlined approval pathways accelerate generic bioequivalence reviews for local producers. Vertically integrated API-to-finished-dose capabilities concentrate in Gujarat and Maharashtra chemical manufacturing zones.
Germany
Hospital-at-home programs in Bavaria and North Rhine-Westphalia pilot patient-administered antiemetic therapies outside institutional settings. EMA pharmacovigilance mandates require electrocardiogram baseline screening before domperidone initiation. Modified-release formulation development clusters around Frankfurt and Berlin clinical pharmacology units.
Brazil
Tertiary hospital gastroenterology departments in São Paulo and Rio de Janeiro standardize domperidone as first-line antiemetic therapy in surgical recovery wards. ANVISA maintains prescription-only classification with periodic safety reviews. Domestic distribution networks in Minas Gerais absorb regional pharmacy volume.
Netherlands
Post-acute care models in Amsterdam and Rotterdam create demand for oral suspension formats in geriatric populations with dysphagia. EMA cardiac safety databases integrate into routine pharmacovigilance workflows. Regional hospital group purchasing organizations consolidate antiemetic purchasing through therapeutic class tenders.
France
Regional hospital group purchasing organizations in Île-de-France and Auvergne-Rhône-Alpes dominate volume allocation through centralized pharmacy committees. ANSM enforces EMA-mandated QT-prolongation risk assessments in prescribing protocols. Generic suppliers consolidate dossier preparation through specialized contract research organizations in Lyon.
Motilium Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue modified-release and cardiac-safety-differentiated formulations. The vendor base stratifies between legacy brand holders with European hospital recognition and cost-competitive generic manufacturers serving pharmacy networks. Three archetypes dominate: vertically integrated API producers, regional hospital formulary incumbents, and emerging market volume suppliers. Competitive moves center on multi-source API qualification programs and therapeutic class tender positioning.
Among Swiss and Indian pharmaceutical conglomerates, Novartis AG and Dr. Reddy's Laboratories Ltd. exemplify divergent strategic positioning. Novartis occupies the legacy brand tier in regulated European markets where EMA restrictions preserve premium positioning. Dr. Reddy's represents the vertically integrated archetype, anchoring cost-competitive supply through captive API production. Lupin Limited sits within the domestic distribution specialist tier, leveraging deep Indian pharmacy networks to absorb displaced European volume.
| Leading Market Players |
|---|
| Novartis AG |
| Lupin Limited |
| Abbott Laboratories |
| GlaxoSmithKline PLC |
| Pfizer Inc |
| AstraZeneca Plc |
| Merck Co., Ltd. |
| Dr. Reddy's Laboratories Ltd. |
| Schwitz Biotech |
| Others |
Pricing and Supply Chain Analysis
Modified-release formulation development is compressing cost economics for immediate-release tablets while concentrating manufacturing scale among German and Dutch clinical pharmacology units capable of cardiac safety integration. API production consolidation in Hyderabad and Mumbai chemical zones simultaneously anchors input cost structures and creates procurement leverage for vertically integrated finished-dose suppliers.
Pricing Analysis
Input-cost pass-through from domperidone API manufacturing in Gujarat and Maharashtra chemical zones feeds directly into finished-dose pricing for Indian pharmacy networks. Three-tier pricing structure across premium, standard, and economy levels separates EMA-compliant modified-release formulations from immediate-release tablets and unbranded generic substitutes. Cost compression in standard-tier oral tablets is intensifying because CDSCO accelerated bioequivalence reviews multiply competing suppliers. Hospital procurement committees in France and Italy exhibit lowest price sensitivity due to therapeutic class tender consolidation, while Brazilian ambulatory clinics face highest sensitivity from limited reimbursement coverage.
Supply Chain Analysis
India's PLI scheme for active pharmaceutical ingredients is reshaping sourcing patterns for domperidone base production away from concentrated chemical clusters. API manufacturing draws from piperidine intermediates, benzimidazolone precursors, and specialized catalysts sourced through Mumbai and Hyderabad trading houses. Single-source vulnerability concentrates in select Indian and Chinese chemical manufacturing zones where 18-24 month validation cycles delay alternative supplier qualification. Distribution runs through regional hospital group purchasing organizations in European markets and deep pharmacy distribution networks in Indian metropolitan centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Motilium market reads as a late-cycle quality story where EMA cardiac safety mandates are filtering demand toward premium formulations with integrated pharmacovigilance capabilities.
For Market Incumbents: Lock in modified-release formulation positioning through Frankfurt and Berlin clinical pharmacology partnerships before generic substitution erodes premium tiers. Consolidate multi-source API qualification programs to deflect supply disruption threats from concentrated Indian and Chinese chemical manufacturing zones. Prioritize therapeutic class tender positioning with French and Italian regional hospital group purchasing organizations. For New Entrants and Emerging Players: Begin with underpenetrated Sub-Saharan Africa pharmacy networks in Nigeria and Kenya where cost-effective oral tablet formats face limited competition from 5-HT3 antagonist substitutes. Target Brazilian tertiary hospital gastroenterology departments standardizing domperidone as first-line antiemetic therapy in surgical recovery wards. Pursue CDSCO streamlined approval pathways for generic bioequivalence to accelerate market entry through vertically integrated API capabilities. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale generic manufacturers lacking cardiac safety database infrastructure yet possessing captive API production. Long-term viability hinges on regulatory compliance capabilities across EMA pharmacovigilance mandates and emerging modified-release formulation development. Watch for EMA QT-prolongation risk assessment updates as the inflection signal triggering further label restrictions or formulation withdrawals.| Strategic Initiative | Industry Significance |
|---|---|
| Modified-Release Formulation Development | EMA cardiac safety mandates compress immediate-release tablet market share in regulated European hospital networks. |
| Multi-Source API Qualification | CDSCO streamlined reviews enable Indian manufacturers to diversify raw material suppliers beyond concentrated chemical clusters. |
| Therapeutic Class Tender Positioning | French and Italian regional hospital group purchasing organizations consolidate antiemetic purchasing through centralized pharmacy committees. |
| Pediatric Oral Suspension Expansion | German and Dutch hospital-at-home programs pilot suspension formats for geriatric dysphagia populations. |
| Sub-Saharan Africa Distribution Buildout | Nigerian and Kenyan pharmacy networks present whitespace for cost-competitive oral tablet formulations. |
Research Methodology
Direct dialogue with hospital pharmacy directors, regulatory affairs specialists at generic manufacturers, CDSCO filing consultants, and EMA pharmacovigilance officers grounded qualitative findings in operational reality. Secondary validation drew from EMA product information updates, CDSCO bioequivalence approval databases, ClinicalTrials.gov cardiac safety study registrations, and French ANSM prescribing protocol amendments. Bottom-up prescription volume modeling across formulation types and top-down market sizing through API production capacity analysis were triangulated for convergence.
Segmented outputs across product type, end user, administration route, and therapy area were generated through the projection horizon. CAGRs were derived from regression analysis against historical prescription trends and regulatory event impacts. Forecast inputs incorporated EMA label restriction scenarios, CDSCO approval velocity assumptions, and 5-HT3 antagonist substitution rates in oncology-associated nausea protocols.
Several conditions sit outside the modeled scope, including FDA approval pathway changes for domperidone, novel transdermal delivery system commercialization, and breakthrough 5-HT3 antagonist formulations displacing dopamine antagonists. Forecasts reflect documented assumptions about regulatory stability and cardiac safety database integration costs. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
US Emergency Contraceptive Pills Market
Pharmaceuticals
US Plasma Fractionation Market
Pharmaceuticals
Antispasmodics Drugs Market
Pharmaceuticals
Europe Novel Drug Delivery System (NDDS) Market
Pharmaceuticals
Bladder Cancer Treatment Drugs Market
Pharmaceuticals
Josamycin Market
Pharmaceuticals
Viral Conjunctivitis Pipeline Drugs Market
Pharmaceuticals
Stanozolol Market
Pharmaceuticals
Carbetocin Acetate Market
Pharmaceuticals
Carbetocin Injection Market
Pharmaceuticals
Alectinib Drugs Market
Pharmaceuticals
AI Drug Development Market
Pharmaceuticals
Influenza Antiviral Market
Pharmaceuticals
Gastrointestinal Diseases Drug Development Market
Pharmaceuticals
Asia-Pacific Contraceptive Drugs and Devices Market
Pharmaceuticals
North America Pharmaceutical Warehousing Market