
 US External Analgesics Market | 2026-2036
US External Analgesics Market Size, Share, and Industry Trends Forecast 2026-2036
US External Analgesics Market Insights
Pharmaceutical-grade topical formulations is reorganizing competitive dynamics across the US external analgesics landscape. Baxter leverages its hospital channel dominance to sustain institutional procurement relationships. Medtronic anchors its position through specialized pain management device-adjacent portfolios. Stryker differentiates via integrated orthopedic-to-home-care continuity.
External analgesics comprise dermatologically applied formulations containing active pharmaceutical ingredients that penetrate epidermal layers to modulate peripheral nociceptor signaling, with menthol-based cryotherapy preparations and lidocaine-infused transdermal patches representing distinct pharmacokinetic profiles. The primary commercial purpose centers on non-systemic pain mitigation for musculoskeletal conditions, post-procedural recovery, and chronic inflammatory states. Topical creams and patches command the largest volume positions, while lidocaine segments capture disproportionate margin pools due to prescription-adjacent positioning. Chronic pain applications anchor value generation, though sports injury use cases demonstrate the fastest volume trajectory through direct-to-consumer channel expansion.
FDA OTC monograph reform, EPA manufacturing facility standards, and USP dissolution testing protocols collectively elevate compliance costs while compressing marginal formulation suppliers. The Drug Enforcement Administration's scheduling oversight for certain lidocaine concentrations further segments market access between pharmacy-only and mass retail channels. Stakeholders must monitor evolving monograph finalization timelines and premarket notification requirements to calibrate portfolio registration investments against channel eligibility.
Market Dynamics
FDA OTC monograph reform is compressing marginal formulation suppliers while concentrating procurement authority among hospital systems and retail pharmacy chains with compliance infrastructure. This regulatory tightening is reshaping competitive dynamics across the US external analgesics landscape.
Growth Catalysts
- Sports medicine clinic expansion:Institutional procurement of topical lidocaine patches and menthol cryotherapy preparations is accelerating as outpatient orthopedic procedures shift toward ambulatory settings.
- Sun Belt demographic concentration:Aging populations in Florida, Arizona, and Texas overlap with outdoor recreation demand, creating concentrated regional consumption clusters for musculoskeletal pain management.
- DEA scheduling oversight refinement:Clearer concentration thresholds for pharmacy-only versus mass retail channel eligibility are reducing regulatory uncertainty for portfolio registration investments.
Market Restraints
- API supply concentration:Lidocaine and menthol active pharmaceutical ingredient production concentrates among a limited set of contract manufacturers, exposing formulators to input cost volatility and qualification delays.
- USP dissolution testing compliance:Updated dissolution protocols for transdermal patches require capital-intensive analytical equipment upgrades that marginal suppliers cannot absorb.
- Systemic oral analgesic substitution:NSAID and acetaminophen oral formulations retain physician prescribing preference for moderate-to-severe pain, limiting topical penetration in institutional settings.
Strategic Opportunities
- Direct-to-consumer channel expansion:E-commerce platforms and telehealth-integrated prescription services are opening pharmacy-adjacent access for lidocaine concentrations previously restricted to brick-and-mortar distribution.
- Device-adjacent portfolio bundling:Integration with continuous passive motion machines and TENS units creates reimbursement-advantaged positioning within orthopedic post-procedural protocols.
- EPA manufacturing facility standards:Early compliance with volatile organic compound emission controls generates competitive moats against laggard competitors facing facility retrofit requirements.
Industry Challenges
- Formulation scientist scarcity:Specialized expertise in transdermal penetration enhancement and patch adhesion engineering is concentrating among a limited talent pool, inflating R&D compensation costs.
- Monograph finalization timeline uncertainty: FDA OTC reform implementation delays are freezing portfolio registration investments as stakeholders await premarket notification requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US External Analgesics Market |
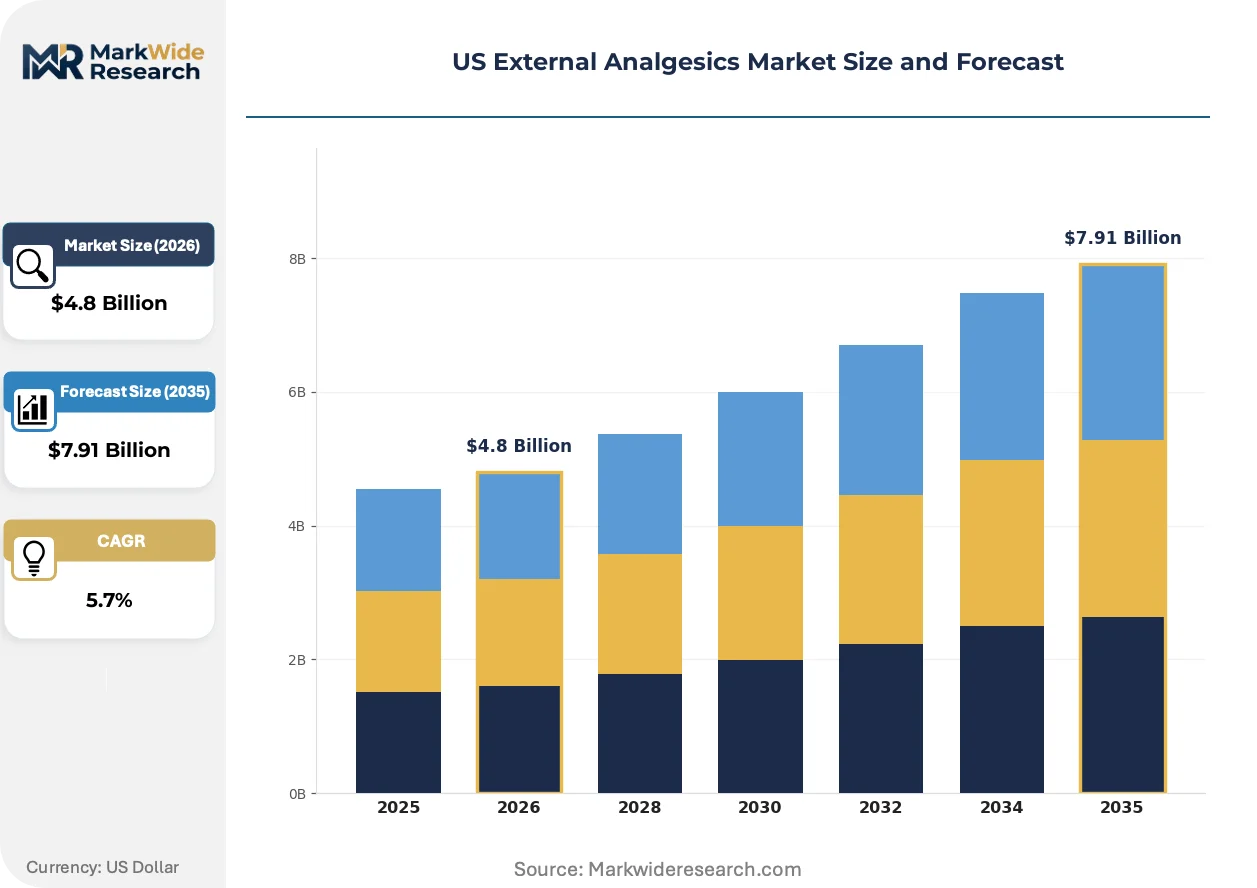
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Creams, Gels, Patches, Oils Use Case: Chronic Pain, Acute Pain, Sports Injuries, Arthritis Active Ingredient: Menthol, Capsaicin, Salicylates, Lidocaine Distribution Channel: Pharmacies, Online Retailers, Supermarkets, Health Stores |
| Companies Covered | Baxter, Boston Scientific Corporation, Medtronic, Stryker, Enovis, Abbott, OMRON Healthcare, Inc., ICU Medical Inc., Nevro Corp., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US External Analgesics Market Trends and Innovations
Pharmaceutical-grade topical delivery systems are displacing conventional over-the-counter formulations through enhanced bioavailability and institutional procurement preference. Three interconnected developments are reshaping product architecture and channel economics.
Iontophoretic and microneedle-assisted transdermal platforms are displacing passive diffusion patches in post-surgical and chronic pain applications. Academic medical centers and orthopedic surgery departments are piloting these systems for opioid-sparing protocols. The structural consequence is margin compression for conventional lidocaine patch manufacturers unable to demonstrate enhanced pharmacokinetic profiles.
FDA OTC monograph reform is elevating documentation requirements for active ingredient safety and efficacy substantiation. The industrial consequence is accelerated exit of private-label assemblers lacking clinical trial infrastructure. Mass retail channel participants are consolidating supplier relationships toward vertically integrated pharmaceutical manufacturers with established FDA correspondence histories.
Institutional procurement through integrated delivery networks is consolidating purchasing authority away from individual clinic discretion. Hospital system formularies are narrowing approved topical analgesic SKUs toward contract-manufactured house brands and established pharmaceutical labels with proven reimbursement codes. This concentration is most visible in the Southeast and Midwest regions where health system consolidation has advanced furthest.
US External Analgesics Market Segmentation
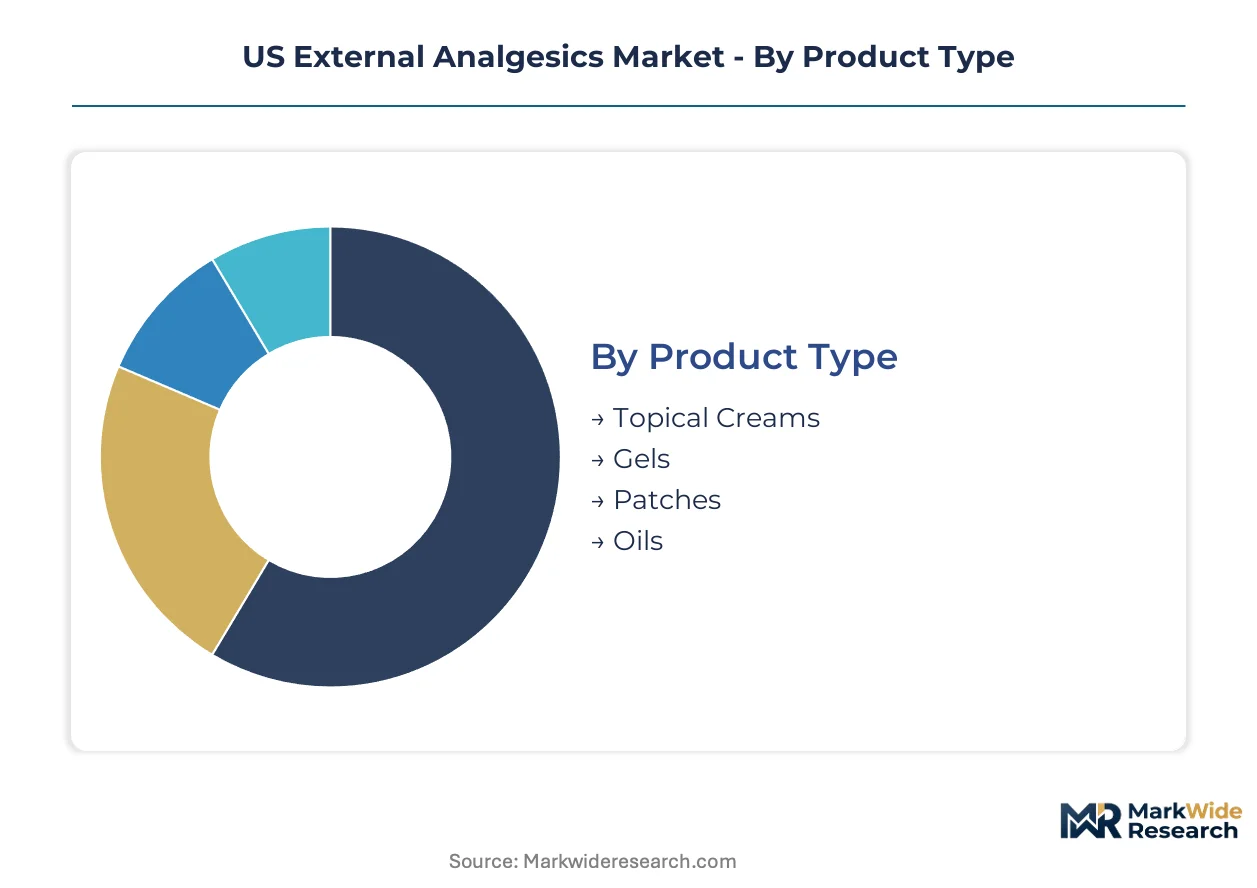
Segmentation in US external analgesics reveals how formulation chemistry, procurement channel, and clinical application intersect to determine pricing power and reimbursement access. Manufacturers calibrate portfolio investments across these dimensions to capture margin concentration in prescription-adjacent segments while defending volume positions in mass retail.
Product Type:
Margin pools concentrate in patch formats where extended-release transdermal technology commands pharmacy-tier pricing and institutional formulary placement.
- Topical Creams:Semisolid emulsions with rapid epidermal penetration dominate household penetration and primary care dispensing. Demand clusters in Sun Belt metropolitan areas where Medicare Part D coverage drives generic substitution toward pharmacy-distributed house brands.
- Patchess:Multi-layer laminates with rate-controlling membranes achieve the highest realized prices through workers' compensation and post-surgical reimbursement codes. Hospital system formularies in Texas and Florida are narrowing approved SKUs toward contract-manufactured labels with proven adhesive performance in humid climates.
- Gels:Hydrophilic matrices with evaporative cooling action target sports medicine clinics and athletic training facilities seeking non-greasy application.
- Oils:Lipid-based carriers with essential oil adjuncts occupy natural products channel positioning with limited institutional access.
Topical creams hold installed capacity across mass manufacturing lines. Patches are rotating up the share rankings through integrated delivery network procurement consolidation.
Use Case:
Volume distribution skews toward chronic applications, yet acute and sports segments demonstrate the steepest expansion trajectory through direct-to-consumer channel development.
- Chronic Pain:Long-duration neuropathic and musculoskeletal conditions generate recurring prescription-adjacent purchases with the strongest insurance adjudication rates. Medicare populations in Arizona and Florida sustain baseline demand for lidocaine-based patch regimens.
- Sports Injuries:Acute soft-tissue trauma and overuse syndromes drive fastest-growing consumer segment through athletic retail and telehealth-integrated dispensing. NCAA training facilities and outpatient orthopedic centers in Texas are piloting menthol cryotherapy protocols as opioid-sparing alternatives.
- Acute Pain:Post-procedural and injury-related episodes concentrate procurement authority in hospital discharge planning and urgent care protocols.
- Arthritis:Degenerative joint disease applications overlap with chronic pain segment but carry distinct OTC self-selection behavior and seasonal demand patterns.
Chronic pain anchors manufacturing scale commitments. Sports injuries are climbing the fastest through ambulatory surgery center expansion and athletic participation rates.
Active Ingredient:
Regulatory scheduling and compendial standards fragment competitive access, with concentration-dependent classifications determining channel eligibility and pricing architecture.
- Lidocaine:Amide-type local anesthetic with dose-dependent DEA oversight above specified thresholds creates pharmacy-only positioning with prescription-adjacent margins. FDA monograph reform is tightening concentration documentation requirements, advantaging manufacturers with established clinical trial infrastructure.
- Menthol:Terpene-based counterirritant with evaporative cooling mechanism achieves broadest retail distribution and lowest regulatory burden. Cryotherapy preparations are displacing conventional rubefacients in institutional procurement through enhanced bioavailability claims.
- Capsaicin:Vanilloid receptor agonist with neurogenic desensitization profile occupies niche positioning for neuropathic pain with compliance challenges from initial burning sensation.
- Salicylates:Ester derivatives with anti-inflammatory mechanism face substitution pressure from oral NSAID preference in moderate-to-severe pain protocols.
Menthol formulations hold installed capacity across legacy manufacturing assets. Lidocaine segments are gaining share fastest through reimbursement code development and health system formulary consolidation.
Distribution Channel:
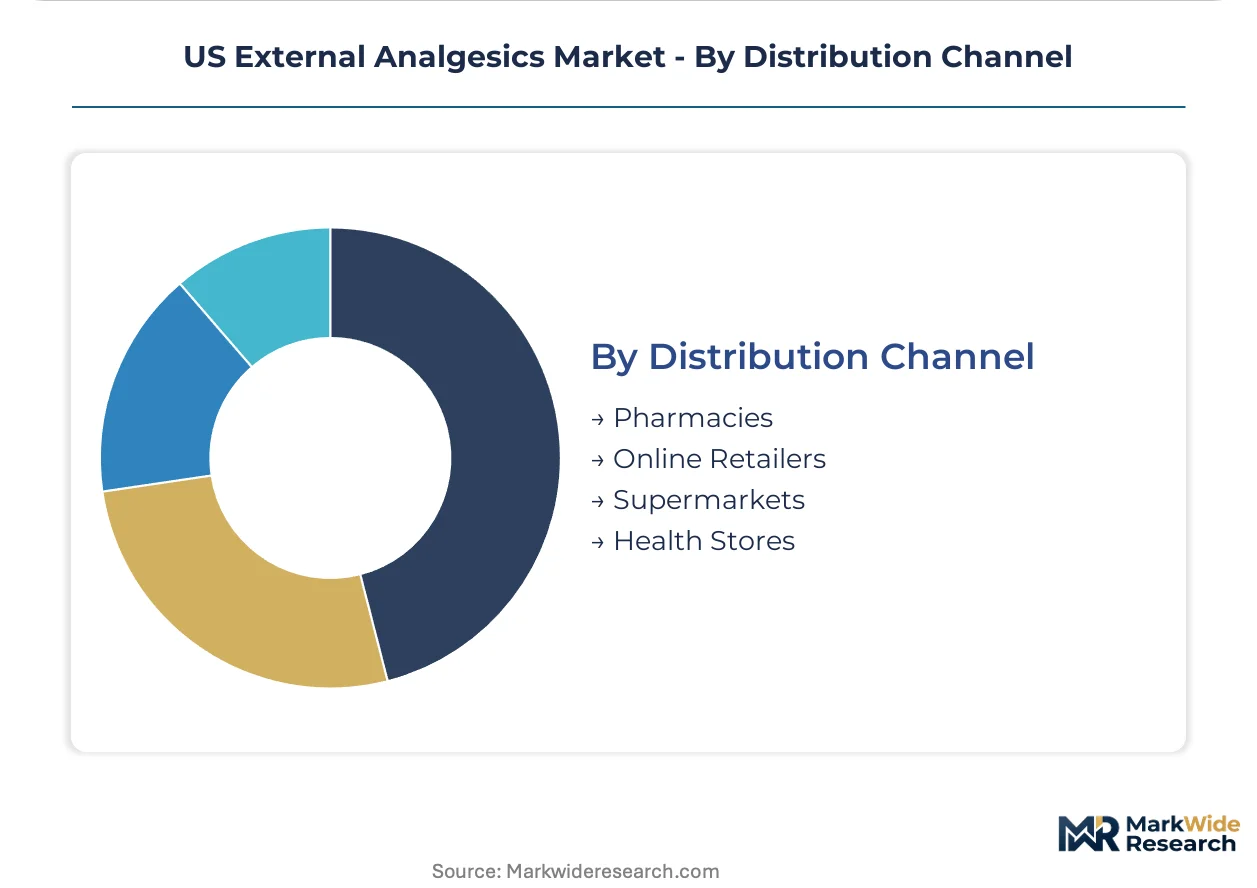
Channel economics diverge sharply between pharmacy-tier professional dispensing and mass retail self-selection, with online platforms eroding traditional geography-based access constraints.
- Pharmacies:Brick-and-mortar and mail-order dispensaries control prescription-adjacent lidocaine access and insurance adjudication infrastructure. CVS Health and Walgreens Boots Alliance procurement consolidation in the Southeast is narrowing supplier relationships toward vertically integrated manufacturers.
- Online Retailers:E-commerce platforms and telehealth-integrated services are opening pharmacy-adjacent access for concentrations previously restricted to physical distribution. Amazon and specialized orthopedic supply sites are capturing sports injury segment growth through subscription replenishment models.
- Supermarkets:Mass merchandisers with pharmacy counters bridge OTC and professional dispensing through co-located clinical services.
- Health Stores:Natural products specialists with limited formulary scope serve capsaicin and botanical-adjunct segments outside institutional reimbursement networks.
Pharmacies maintain installed capacity through insurance network contracts. Online retailers are rotating up the share rankings through direct-to-consumer platform investments and telehealth integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US external analgesics distribution concentrates in Sun Belt corridors where Florida, Texas, and Arizona absorb disproportionate volumes through Medicare Part D channels and sports medicine clinic procurement. Interstate commerce flows through Memphis and Dallas-Fort Worth distribution nodes serving institutional pharmacy networks.
Florida
Medicare Advantage enrollment density and orthopedic surgery volume drive lidocaine patch consumption in Tampa and Miami metropolitan clusters. FDA OTC monograph reform implementation timelines affect formulary registration investments by distributors serving the state's hospital systems. Jacksonville anchors wholesale distribution for Southeast institutional procurement networks.
Texas
Workers' compensation claim volume and ambulatory surgery center expansion accelerate menthol cryotherapy adoption in Houston and Dallas medical corridors. DEA scheduling oversight for lidocaine concentration thresholds shapes pharmacy-only versus retail channel eligibility decisions. Austin's telehealth infrastructure supports direct-to-consumer platform penetration for sports injury segments.
Arizona
Retiree population concentration and outdoor recreation injury rates sustain baseline demand for chronic pain formulations in Phoenix and Tucson markets. EPA manufacturing facility standards for volatile organic compound emissions affect contract manufacturer qualification timelines. Flagstaff and Prescott clusters demonstrate seasonal demand spikes tied to hiking and skiing injury patterns.
California
Integrated delivery network consolidation in Los Angeles and San Francisco Bay Area compresses formulary SKU counts toward vertically integrated house brands. USP dissolution testing protocol upgrades require analytical equipment investments that marginal suppliers cannot absorb. San Diego's military medical facilities pilot device-adjacent portfolio bundling with TENS unit protocols.
North Carolina
Research Triangle pharmaceutical manufacturing infrastructure supports contract formulation capacity for transdermal patch production. FDA premarket notification requirements for enhanced bioavailability claims influence R&D investment allocation by regional developers. Charlotte and Raleigh health system procurement consolidation narrows supplier relationships toward established FDA correspondence histories.
US External Analgesics Market Competitive Landscape
Listed leaders compete with private specialists across channel access and regulatory compliance infrastructure. The vendor base separates into hospital-system suppliers with formulary placement, retail pharmacy distributors with insurance adjudication networks, and direct-to-consumer platforms with telehealth integration. Three archetypes dominate: vertically integrated pharmaceutical manufacturers, device-adjacent portfolio bundlers, and specialized topical formulation houses. Competitive moves concentrate on M&A for FDA correspondence histories and capacity expansion for USP dissolution testing compliance.
Within the device-adjacent tier, Baxter, Medtronic, and Stryker occupy positions exemplifying hospital channel dominance, specialized pain management portfolios, and orthopedic-to-home-care continuity respectively. Boston Scientific Corporation represents the listed multinational archetype with institutional procurement relationships. These anchors illustrate how regulatory compliance infrastructure and reimbursement code development separate sustainable participants from marginal suppliers facing monograph reform exit pressure.
| Leading Market Players |
|---|
| Baxter |
| Boston Scientific Corporation |
| Medtronic |
| Stryker |
| Enovis |
| Abbott |
| OMRON Healthcare, Inc. |
| ICU Medical Inc. |
| Nevro Corp. |
| Others |
Pricing and Supply Chain Analysis
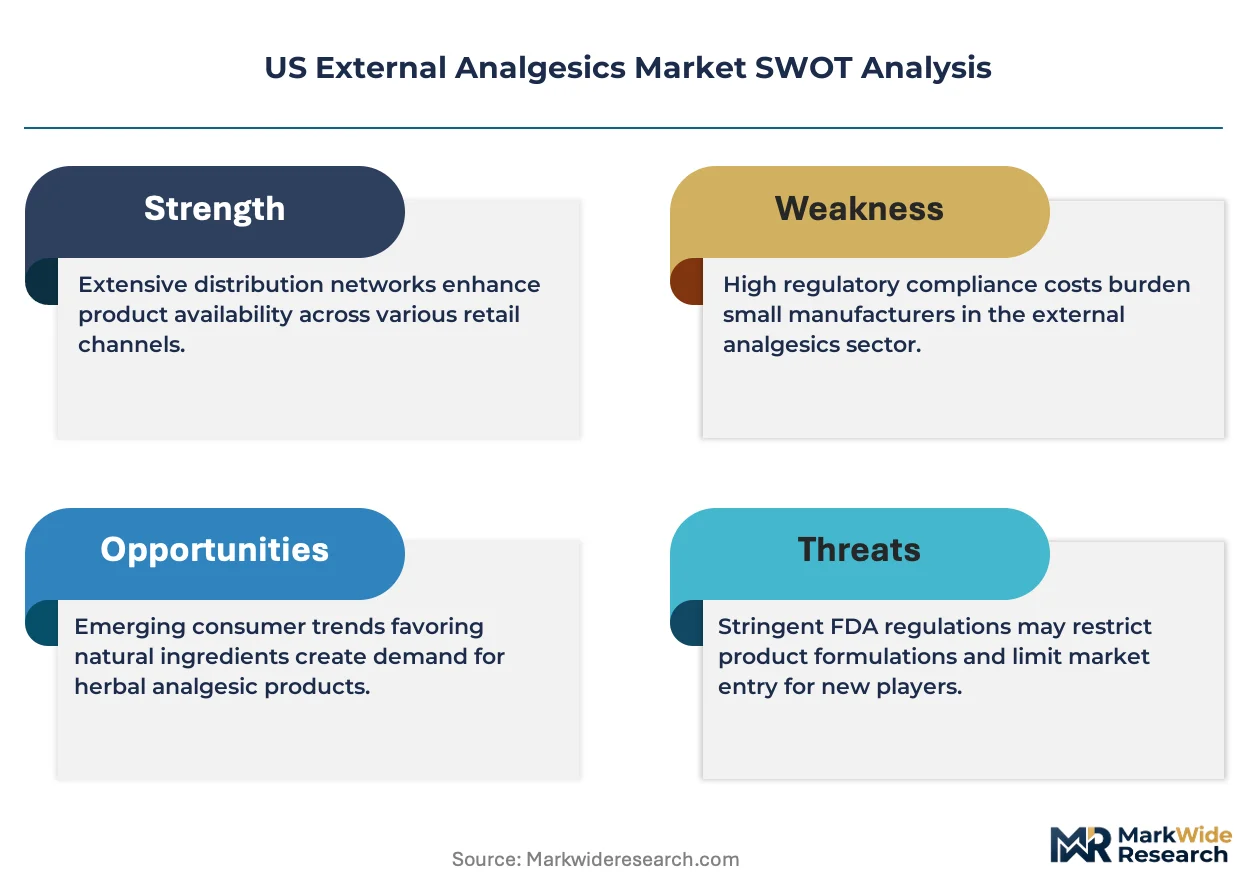
Contract manufacturing scale economies in transdermal patch production anchor price floors across the US external analgesics landscape, concentrating supply authority among FDA-registered facilities with USP dissolution testing infrastructure while marginal formulators face cost compression from compliance investments.
Pricing Analysis
Next-generation iontophoretic delivery systems command pharmacy-tier premiums over conventional lidocaine patches and menthol-based cryotherapy preparations. Three-tier pricing structure across premium, standard, and economy levels separates device-adjacent bundles with reimbursement codes from mass retail OTC formulations and private-label house brands. Price differentiation rests on FDA monograph compliance tier and health system formulary placement. Cost compression in standard-tier patches is intensifying because hospital procurement consolidation narrows supplier pools. Mass retail consumers demonstrate highest price sensitivity, while orthopedic clinics and workers' compensation payers exhibit lowest sensitivity due to reimbursement insulation.
Supply Chain Analysis
API qualification bottlenecks at Indian and Chinese contract manufacturers concentrate supply risk for lidocaine and menthol inputs. Active pharmaceutical ingredient production draws from facilities in India, China, and the United States, with formulation finishing concentrated in North Carolina and Puerto Rico manufacturing corridors. Raw material dependencies include petroleum-derived menthol feedstocks, lidocaine base compounds, and multi-layer patch laminates. Single-source vulnerability in specialized transdermal adhesive supply creates exposure for patch manufacturers. Distribution runs through Memphis and Dallas-Fort Worth nodes serving institutional pharmacy networks and retail chain distribution centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists in the US external analgesics market as direct-to-consumer channel expansion and telehealth integration create niche access points outside consolidated hospital procurement networks.
For Market Incumbents: Consolidate formulary placement through backward integration into contract manufacturing capacity and preemptive EPA volatile organic compound compliance investments. Defensive positioning requires securing FDA correspondence histories ahead of monograph finalization timelines. Threat substitution from oral NSAID prescribing preference in institutional settings demands reimbursement code development for device-adjacent bundles. Capacity addition in Research Triangle pharmaceutical corridors anchors supply security. For New Entrants and Emerging Players: Differentiate on sports injury segment specialization through menthol cryotherapy formulations with enhanced bioavailability claims. White-space targets include telehealth-integrated prescription services for lidocaine concentrations and athletic training facility direct procurement. The most penetrable segment is online retail sports injury applications with subscription replenishment models. Go-to-market angle centers on NCAA training facility pilot programs as opioid-sparing protocol validators. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated pharmaceutical manufacturers with established FDA regulatory infrastructure over pure-play topical formulation houses. Long-term viability over the projection horizon hinges on monograph reform compliance moats and health system consolidation capture. Acquisition target archetype includes specialized topical formulation houses with clinical trial infrastructure. Signal to watch is FDA OTC monograph finalization timeline acceleration as inflection indicator for portfolio registration investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Notification Investment | Early compliance with evolving monograph requirements secures channel eligibility ahead of marginal supplier exits. |
| Hospital System Partnership Development | Integrated delivery network formulary placement anchors volume commitments through orthopedic post-procedural protocols. |
| Telehealth Platform Integration | Direct-to-consumer channel access opens pharmacy-adjacent positioning for prescription-strength lidocaine concentrations. |
| USP Dissolution Testing Infrastructure | Analytical equipment upgrades satisfy updated patch performance standards while excluding undercapitalized competitors. |
| Device-Adjacent Portfolio Bundling | TENS unit and continuous passive motion machine integration creates reimbursement-advantaged positioning in workers' compensation channels. |
Research Methodology
The analysis maps topical creams, transdermal patches, cryotherapy gels, and device-adjacent delivery systems, each validated through hospital procurement managers, formulary directors, regulatory affairs leads, and contract manufacturing executives. Primary interviews with industry stakeholders combine with secondary validation through FDA OTC monograph filings, USP dissolution protocol documentation, hospital procurement databases, and CMS Medicare Part D claims data. Bottom-up demand modeling and top-down market sizing triangulate volume estimates across the analysis window.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models segmentation dimensions including formulation chemistry, procurement channel, clinical application, and active ingredient regulatory tier. CAGRs derive from patient population growth trajectories, ambulatory surgery center expansion rates, and sports medicine clinic procurement patterns. Industry-specific forecast inputs include DEA scheduling oversight refinement timelines and EPA manufacturing facility compliance trajectories.
Material uncertainties — FDA monograph finalization delays, API supply concentration disruptions, and health system consolidation pace — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory implementation timelines and reimbursement code development without guaranteeing specific outcomes. Practitioners should keep alternative scenarios live as DEA concentration threshold determinations and EPA emission control enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Cytomegalovirus Treatment Market
Pharmaceuticals
Clozapine Market
Pharmaceuticals
Topical Drugs CDMO Market
Pharmaceuticals
Live Vaccines Market
Pharmaceuticals
Global Nasal Drug Delivery Market
Pharmaceuticals
Cancer Immunotherapy Drug Discovery Outsourcing Market
Pharmaceuticals
Europe Adenomyosis Drugs Market
Pharmaceuticals
Pharmaceutical Contract Development and Manufacturing Organization (CDMO) Market
Pharmaceuticals
Steroid Injections Market
Pharmaceuticals
Short-Acting Insulin Market
Pharmaceuticals
BRAF-MEK Inhibitors Market
Pharmaceuticals
Antiandrogens Market
Pharmaceuticals
Finland Pharmaceutical Market
Pharmaceuticals
Global Immunomodulators Market
Pharmaceuticals
Acetaminophen Market
Pharmaceuticals
Nesiritide Market