
 Adamantane Antiviral Drugs Market | 2026-2036
Adamantane Antiviral Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Adamantane Antiviral Drugs Market Outlook
Specialized medicinal chemist talent is bifurcating between traditional small-molecule synthesis and emerging biologics platforms, constraining R&D bandwidth for adamantane derivatives. Sigma-Aldrich Corporation leverages its global reagent distribution network to sustain raw material access for contract manufacturers. Shandong Duoju Chemical anchors East Asian supply through captive production of adamantane intermediates. FUJIFILM Wako Pure Chemical Corporation differentiates via pharmaceutical-grade purity standards that exceed compendial requirements.
Adamantane antiviral drugs comprise tricyclic amine compounds that block the M2 ion channel of influenza A viruses, disrupting viral uncoating through pH-mediated conformational interference; rimantadine and amantadine share this mechanism but differ in pharmacokinetic profiles, with rimantadine exhibiting reduced central nervous system penetration. Tablet and capsule formulations dominate commercial volumes due to outpatient prescribing convenience, while injectable formats command premium positioning in hospital settings. Amantadine retains the largest installed base among drug types, though memantine applications in neurodegenerative indications are expanding the addressable therapeutic scope beyond antiviral use.
FDA pharmacovigilance requirements and EMA post-authorization safety studies shape clinical trial investment thresholds for new adamantane entrants, while China's NMPA accelerates generic equivalence reviews that compress pricing power for established molecules. The WHO Essential Medicines List inclusion criteria influence national procurement priorities across low- and middle-income health systems. Stakeholders must monitor antiviral resistance surveillance data and regulatory science advances to calibrate pipeline prioritization against evolving clinical utility assessments.
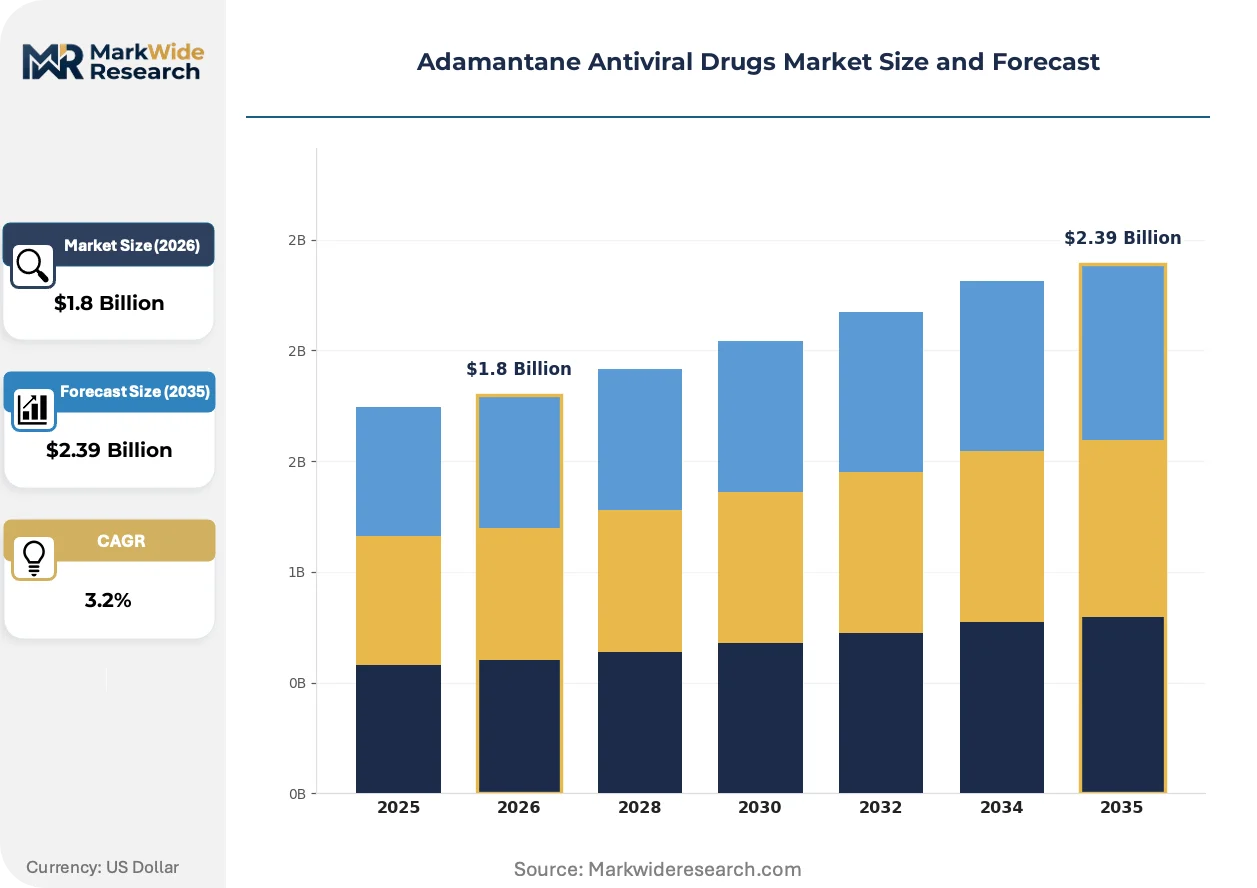
Market Dynamics
Antiviral resistance surveillance data from the WHO is compressing clinical utility assessments for adamantane derivatives, forcing manufacturers to recalibrate pipeline investments against diminishing influenza A susceptibility patterns while hospital procurement protocols tighten efficacy thresholds.
Growth Catalysts
- EMA Post-Authorization Safety Studies:These frameworks maintain market access for approved rimantadine formulations by generating real-world evidence that supports continued reimbursement across European hospital networks.
- Tablet Formulation Demand:Outpatient prescribing convenience drives volume expansion in retail pharmacy channels, particularly where seasonal influenza vaccination co-administration protocols exist.
- Shandong Province Production Clusters:Captive adamantane intermediate manufacturing in this Chinese hub insulates contract manufacturers from raw material volatility, stabilizing input costs for generic finished-dose producers.
Market Restraints
- Amantadine Input Cost Volatility:Adamantane hydrocarbon feedstock prices fluctuate with petroleum derivative markets, squeezing margin structures for API manufacturers without backward integration into petrochemical supply.
- Widespread M2 Channel Resistance:Circulating influenza A H3N2 and H1N1 strains now carry S31N mutations that render adamantane-class drugs clinically ineffective in most geographic regions.
- FDA Pharmacovigilance Requirements:Elevated clinical trial investment thresholds for neuropsychiatric adverse event monitoring deter new market entrants from pursuing novel adamantane derivatives.
Strategic Opportunities
- Memantine Neurodegenerative Expansion:NMDA receptor antagonist applications in Alzheimer's disease management extend the therapeutic addressable scope beyond antiviral indications, opening neurology-focused prescribing channels.
- India's Essential Medicines List Procurement:National health mission tenders for influenza prophylaxis stockpiles create volume opportunities for cost-optimized generic amantadine suppliers meeting BIS quality standards.
- Continuous Manufacturing Technology:Adoption of flow chemistry platforms for adamantane API synthesis reduces batch failure rates and accelerates regulatory filing timelines for process-optimized generic entrants.
Industry Challenges
- Medicinal Chemist Talent Scarcity:Specialized synthetic expertise for tricyclic amine chemistry is migrating toward biologics platforms, constraining R&D bandwidth for legacy small-molecule antiviral optimization.
- Injectables Certification Complexity:Pharmaceutical-grade purity requirements for hospital-administered rimantadine solutions exceed compendial standards, extending validation timelines for sterile manufacturing line approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adamantane Antiviral Drugs Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.39 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Amantadine, Rimantadine, Tromantadine, Memantine Formulation: Tablet, Capsule, Syrup, Injectable Target Virus: Influenza A, Respiratory Syncytial Virus, Hepatitis B Virus, Herpes Simplex Virus End User: Pharmacies, Ambulatory Care Centers, Specialty Clinics, Research Laboratories |
| Companies Covered | TCI Chemicals (India) Pvt. Ltd., Shandong Duoju Chemical, FUJIFILM Wako Pure Chemical Corporation, Hubei Dechao Chemical Co., Ltd., Shandong Yihuiyang New Material Technology Co., Ltd, Sigma-Aldrich Corporation, Shandong Kunbao Chemical Co., Ltd., Hunan Huateng Pharmaceutical Co., Ltd, Sichuan Zhongbang New Materials Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adamantane Antiviral Drugs Market Strategic Shifts
Resistance-driven therapeutic obsolescence is forcing adamantane drug developers toward mechanistic diversification and manufacturing efficiency gains rather than indication expansion within influenza virology.
Amantadine synthesis routes are bifurcating between traditional acid-catalyzed isomerization of dicyclopentadiene and emerging biocatalytic approaches using engineered enzymes. Contract manufacturers in China and India are adopting the latter to reduce hazardous waste disposal burdens. This technology transition is bifurcating the supplier base into petrochemical-integrated incumbents and biotech-enabled challengers with divergent cost structures.
REACH registration requirements for adamantane intermediates are tightening substance volume tracking and exposure scenario documentation across European manufacturing operations. Chemical suppliers must now submit extended safety data sheets covering downstream pharmaceutical applications. API producers serving EMA-regulated markets are absorbing compliance costs through dedicated regulatory affairs staffing and third-party toxicology testing contracts.
Hospital procurement committees are consolidating antiviral formulary decisions under centralized pharmacy and therapeutics oversight, displacing individual prescriber discretion for influenza prophylaxis. This concentration demands outcome documentation and resistance surveillance data from manufacturers seeking contract renewals. The United States exhibits the most pronounced shift, with integrated delivery networks standardizing amantadine access protocols across affiliated acute care facilities.
Adamantane Antiviral Drugs Market Segmentation
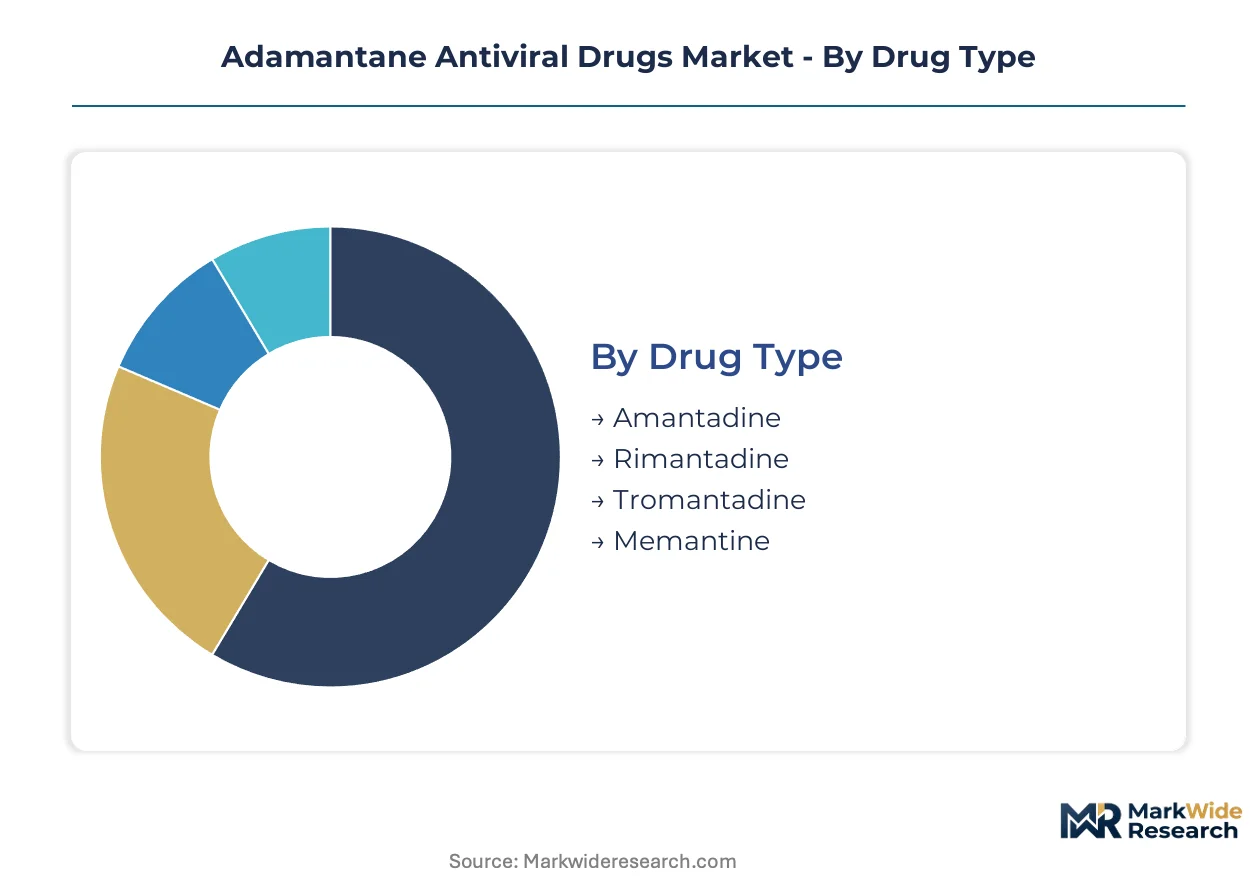
Segmentation in the adamantane antiviral drugs market reveals how resistance patterns and formulation economics reshape competitive priorities across therapeutic applications. Manufacturers must align production assets with the segments where clinical utility persists despite viral evolution pressures.
Drug Type:
Substitution pressure from neuraminidase inhibitors and polymerase inhibitors weighs most heavily on segments with narrow influenza-only indications, while neurodegenerative applications insulate certain derivatives from antiviral obsolescence.
- Amantadine:The original tricyclic amine compound retains the largest installed prescribing base for influenza A prophylaxis despite widespread M2 channel resistance mutations. Hospital procurement in the United States continues for seasonal stockpiling protocols where formulary inertia sustains volume.
- Memantine:NMDA receptor antagonist mechanism extends therapeutic utility into Alzheimer's disease management, creating neurology-focused demand channels that escape antiviral resistance constraints entirely. Prescribing concentrates in geriatric care networks across Germany and Japan where dementia prevalence drives consistent utilization.
- Rimantadine:Modified pharmacokinetic profile reduces CNS penetration versus amantadine, positioning this derivative for outpatient influenza prophylaxis where neuropsychiatric adverse event risk deters first-generation use.
- Tromantadine:Topical formulation heritage in herpes simplex applications constrains addressable market scope compared to systemic antiviral alternatives with broader indication profiles.
Amantadine anchors the volume base while memantine gains share at the steepest rate as neurology applications expand faster than declining antiviral prescriptions.
Formulation:
Cost tier stratification separates premium hospital-administered formats from mass-market oral solids, with manufacturing complexity determining margin structures across the dosage form spectrum.
- Tablet:Compressed solid dosage dominates outpatient prescribing convenience for seasonal influenza prophylaxis, with immediate-release formulations commanding standard reimbursement tiers across retail pharmacy networks.
- Injectable:Sterile solution manufacturing requires pharmaceutical-grade purity exceeding compendial standards, extending validation timelines and creating premium positioning in acute care settings where bioavailability assurance justifies higher procurement expenditure.
- Capsule:Gelatin shell encapsulation offers taste-masking advantages for pediatric and geriatric patient populations where tablet swallowing compliance presents challenges.
- Syrup:Liquid oral formulation serves pediatric prescribing protocols and patients with dysphagia, though stability concerns and shipping weight constrain distribution economics versus solid alternatives.
Tablet formulations generate the highest absolute volumes while injectable formats capture the most favorable unit economics per dose administered.
Target Virus:
Application-specific efficacy validation determines segment viability as resistance surveillance data forces continuous reassessment of clinical utility across virology indications.
- Influenza A:Original antiviral indication now compromised by S31N M2 channel mutations in circulating H3N2 and H1N1 strains, compressing effective prescribing to prophylaxis stockpiles and resistance-naive subpopulations.
- Herpes Simplex Virus:Tromantadine topical applications retain niche utility against HSV-1 and HSV-2 lesions where mechanistic differentiation from nucleoside analogs supports continued formulary inclusion.
- Respiratory Syncytial Virus:Limited clinical evidence base constrains regulatory approval pathways and restricts prescribing to investigational protocols.
- Hepatitis B Virus:Adamantane derivatives lack established efficacy against HBV replication mechanisms, relegating this segment to preclinical research interest without commercialized therapeutic applications.
Influenza A indications retain the largest historical revenue base while herpes simplex applications demonstrate the most durable clinical utility against resistance pressures.
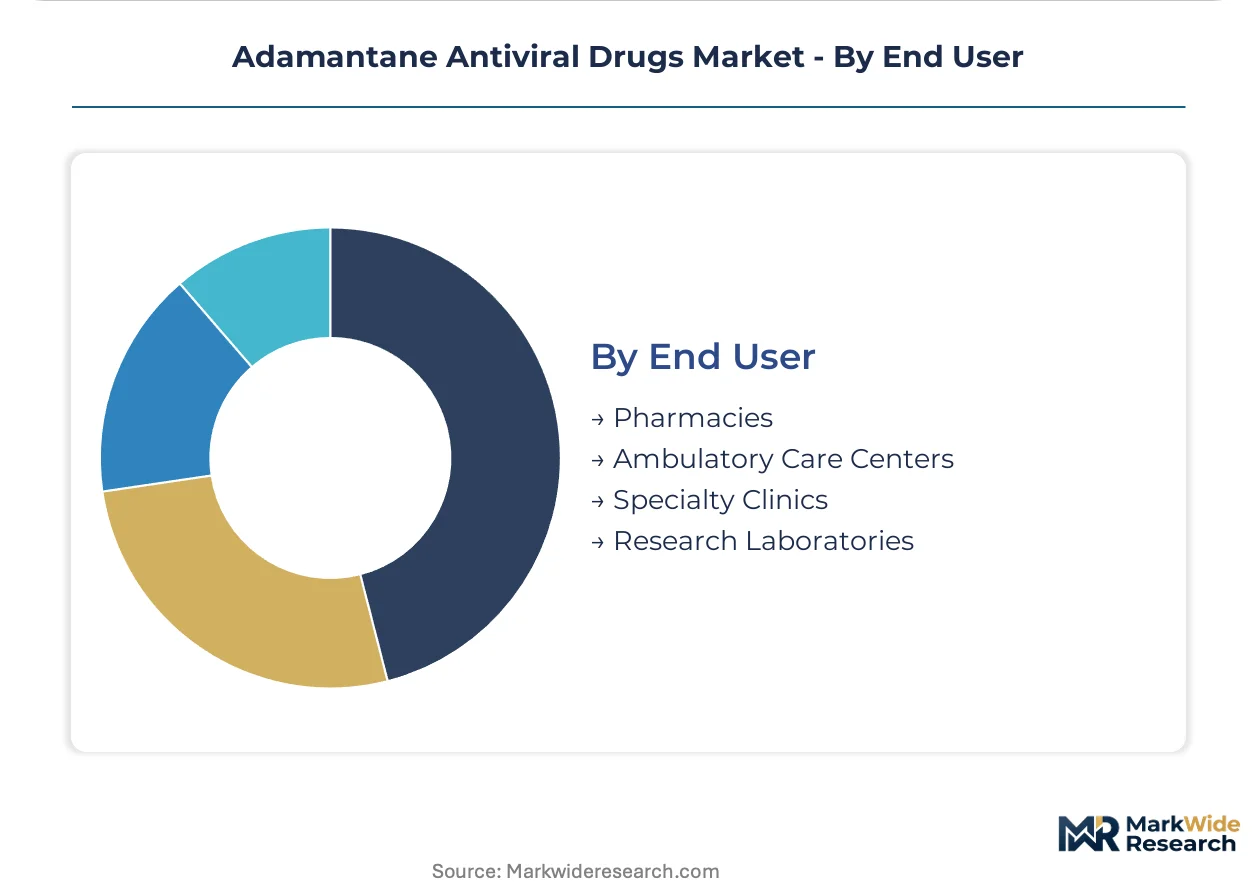
End User:
Customer type concentration shapes distribution infrastructure requirements, with centralized procurement in institutional channels diverging from fragmented retail pharmacy fulfillment patterns.
- Pharmacies:Community and hospital pharmacy networks handle the preponderance of dispensed volume, with seasonal demand surges requiring inventory staging ahead of influenza vaccination campaigns.
- Specialty Clinics:Neurology-focused centers drive memantine prescribing for Alzheimer's disease management, with cognitive assessment protocols determining treatment initiation and continuation decisions.
- Ambulatory Care Centers:Outpatient infusion and urgent care facilities administer injectable formulations for acute influenza exposure prophylaxis in high-risk patient cohorts.
- Research Laboratories:Academic and contract research organizations procure reference standards and investigational compounds for resistance surveillance and mechanistic studies.
Pharmacies anchor the volume base while specialty clinics gain share at the steepest rate as neurodegenerative indications expand the prescriber base beyond infectious disease specialists.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA pharmacovigilance requirements anchor the United States as the dominant geography, where seasonal influenza vaccination protocols drive consistent hospital procurement of amantadine formulations. National regulators across Germany, Japan, India, and China shape distinct compliance pathways for adamantane derivative manufacturers.
United States
Hospital pharmacies in the United States expand procurement of amantadine for influenza A prophylaxis as integrated delivery networks standardize access protocols. FDA continued evaluation of antiviral efficacy standards shapes product development pathways for domestic manufacturers. The Southeast region concentrates seasonal demand surges requiring inventory staging ahead of vaccination campaigns.
Germany
Geriatric care networks across Germany drive consistent memantine utilization for Alzheimer's disease management where dementia prevalence supports neurology-focused prescribing. EMA post-authorization safety studies maintain market access for rimantadine formulations by generating real-world evidence. The Rhine-Ruhr metropolitan cluster hosts pharmaceutical distribution infrastructure serving European hospital networks.
Japan
PMDA regulatory frameworks govern approval pathways for novel adamantane derivatives entering Japanese markets. Pharmaceutical-grade purity requirements from domestic manufacturers exceed compendial standards for hospital-administered formulations. The Kanto region around Tokyo anchors demand concentration for neurodegenerative applications as aging demographics expand the prescriber base.
India
National health mission tenders for influenza prophylaxis stockpiles create volume opportunities for cost-optimized generic amantadine suppliers meeting BIS quality standards. CDSCO accelerates generic equivalence reviews that compress pricing power for established molecules. Gujarat and Maharashtra production clusters supply contract manufacturers with backward-integrated intermediate sourcing.
China
NMPA regulatory science advances calibrate pipeline prioritization for domestic adamantane entrants against evolving clinical utility assessments. Captive production of adamantane intermediates in Shandong Province insulates contract manufacturers from raw material volatility. The Yangtze River Delta concentration of chemical synthesis capacity supports flow chemistry platform adoption for API manufacturing.
Adamantane Antiviral Drugs Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the adamantane antiviral drugs market. Petrochemical-integrated incumbents compete with biotech-enabled challengers using divergent cost structures for intermediate production. Strategic archetypes include global reagent distributors, East Asian captive manufacturers, and pharmaceutical-grade purity specialists. Competitive moves concentrate on manufacturing technology transitions and regulatory compliance capacity expansion.
Among East Asian chemical manufacturers, Shandong Duoju Chemical and Hubei Dechao Chemical Co., Ltd. exemplify the captive production archetype for adamantane intermediates. Sigma-Aldrich Corporation occupies a position within the global reagent distribution tier that sustains raw material access for contract manufacturers. FUJIFILM Wako Pure Chemical Corporation represents the pharmaceutical-grade purity specialist archetype with standards exceeding compendial requirements.
| Leading Market Players |
|---|
| TCI Chemicals (India) Pvt. Ltd. |
| Shandong Duoju Chemical |
| FUJIFILM Wako Pure Chemical Corporation |
| Hubei Dechao Chemical Co., Ltd. |
| Shandong Yihuiyang New Material Technology Co., Ltd |
| Sigma-Aldrich Corporation |
| Shandong Kunbao Chemical Co., Ltd. |
| Hunan Huateng Pharmaceutical Co., Ltd |
| Sichuan Zhongbang New Materials Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Petrochemical-integrated capacity utilization in Shandong Province anchors global adamantane intermediate production, concentrating supply-side scale economies that simultaneously depress generic API price floors and erect barriers against biotech-enabled challengers lacking backward integration into dicyclopentadiene feedstock. This dual effect compresses margin structures for finished-dose manufacturers while rewarding incumbents with captive hydrocarbon sourcing.
Pricing Analysis
Geographic price spreads separate Indian contract manufacturers supplying national health mission tenders from Japanese pharmaceutical-grade purity specialists serving hospital networks. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by certification grade and sterile manufacturing validation status. Cost compression in standard-tier tablet formulations is intensifying because NMPA-accelerated generic equivalence reviews compress pricing power for established molecules. Government procurement channels exhibit highest price sensitivity, while neurology-focused memantine prescribers in German geriatric networks demonstrate lowest sensitivity due to reimbursement insulation.
Supply Chain Analysis
Strategic stockpile preferences dominate hospital pharmacy procurement for influenza A prophylaxis, displacing just-in-time inventory models as integrated delivery networks standardize access protocols ahead of seasonal vaccination campaigns. Raw material dependencies draw from petroleum-derived dicyclopentadiene, catalytic hydrogenation reagents, and pharmaceutical-grade solvents sourced primarily from China, India, and the United States. Single-source vulnerability concentrates in Shandong Province adamantane intermediate clusters, where environmental compliance actions or feedstock disruptions cascade downstream. Distribution runs through regional chemical distributors and specialized pharmaceutical wholesalers serving hospital formularies and retail pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics inflection is emerging as flow chemistry manufacturing platforms and biocatalytic synthesis routes create interoperability between petrochemical-integrated incumbents and biotech-enabled challengers, reshaping competitive boundaries beyond traditional scale advantages.
For Market Incumbents: Compound defensive positioning by deepening backward integration into adamantane hydrocarbon feedstock to insulate against petroleum derivative volatility, while accelerating EMA post-authorization safety study investments to maintain reimbursement access against neuraminidase inhibitor substitution threats. Prioritize certification capacity for pharmaceutical-grade purity standards exceeding compendial requirements to defend premium positioning in hospital-administered injectable segments. For New Entrants and Emerging Players: Continuous manufacturing technology adoption represents a service-layer gap where incumbents under-serve cost-optimized generic demand, enabling challengers to reduce batch failure rates and accelerate regulatory filing timelines. Target India's Essential Medicines List procurement tenders for influenza prophylaxis stockpiles as the most penetrable geography, leveraging BIS quality standard compliance as the primary go-to-market credential against established suppliers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biotech-enabled API manufacturers with engineered enzyme capabilities and flow chemistry platforms over petrochemical-integrated incumbents facing stranded asset risk from resistance-driven therapeutic obsolescence. Long-term viability across the analysis window hinges on neurology indication diversification beyond antiviral applications. Monitor antiviral resistance surveillance data from WHO as the critical inflection indicator for pipeline prioritization recalibration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adamantane Intermediates | Captive production in Shandong Province insulates contract manufacturers from petroleum feedstock volatility. |
| Flow Chemistry Platform Adoption | Biocatalytic synthesis routes reduce hazardous waste burdens and accelerate regulatory filings for generic entrants. |
| EMA Post-Authorization Safety Studies | Real-world evidence generation maintains rimantadine reimbursement across European hospital networks. |
| Memantine Neurology Channel Expansion | Alzheimer's disease applications escape antiviral resistance constraints entirely through NMDA receptor antagonist mechanism. |
| REACH Registration Compliance Investment | Extended safety data sheets for adamantane intermediates secure European manufacturing access against regulatory exclusion. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital formulary directors, pharmaceutical procurement managers, regulatory affairs specialists at CDSCO and NMPA, and contract manufacturing executives at Shandong-based intermediate producers. Secondary validation drew from FDA pharmacovigilance databases, EMA post-authorization study registries, WHO antiviral resistance surveillance reports, and BIS quality standard documentation. Bottom-up volume modeling triangulated against top-down expenditure analysis across retail pharmacy, hospital, and government tender channels.
Across the analysis window, the forecasting framework segmented by drug type, formulation, target virus indication, and end-user channel to capture resistance-driven therapeutic obsolescence effects and neurology indication expansion dynamics. CAGRs were derived from epidemiological modeling of influenza seasonality, dementia prevalence trajectories, and procurement protocol standardization trends. Industry-specific inputs included M2 channel mutation surveillance frequencies, geriatric care network expansion rates, and continuous manufacturing technology adoption curves.
Underlying assumptions cover sustained regulatory science alignment between FDA, EMA, and NMPA on antiviral efficacy standards, with deviation risk concentrated in accelerated resistance mutation emergence or abrupt reimbursement policy shifts in national health systems. Forecasts reflect these documented conditions with explicit acknowledgment that viral evolution trajectories and regulatory harmonization pace remain exogenous variables. Revision becomes warranted when WHO resistance surveillance data crosses thresholds indicating clinical utility collapse for adamantane-class prophylaxis protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Ramipril Market
Pharmaceuticals
Contract Pharmaceutical Fermentation Services Market
Pharmaceuticals
Cannabinoid Drugs Market
Pharmaceuticals
Large Molecule Contract Development and Manufacturing Organization Market
Pharmaceuticals
Repurposed Human Immunosuppressants Market
Pharmaceuticals
Injectable Potassium Phosphate Market
Pharmaceuticals
Respiratory Virus Vaccines Market
Pharmaceuticals
Live Vaccines Market
Pharmaceuticals
Global Anticoccidial Drugs Market
Pharmaceuticals
Global BHK Rabies Vaccine Market
Pharmaceuticals
Risedronate Sodium Market
Pharmaceuticals
Vaginal Antifungals Market
Pharmaceuticals
Chemotherapy-Induced Nausea and Vomiting (CINV) Treatment Market
Pharmaceuticals
Antidiarrhoeal Market
Pharmaceuticals
Global Lidocaine Market
Pharmaceuticals
Global PD-1 and PD-L1 Inhibitors Market