
 Australia Pharmaceuticals Market | 2026-2036
Australia Pharmaceuticals Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Pharmaceuticals Market Outlook
Modular packaging of combination therapies is pivoting how Australian prescribers and hospital formularies evaluate cost-effectiveness per treatment episode. CSL Limited anchors domestic plasma-derived biologics manufacturing through vertically integrated fractionation facilities in Melbourne. Mayne Pharma Group specializes in oral and injectable dose formulations, leveraging modified-release technology to differentiate its hospital supply contracts.
Australia pharmaceuticals encompass chemically synthesized and biologically derived medicinal products formulated for disease prevention, diagnosis, or treatment, typically manufactured under GMP conditions with defined purity specifications, stability profiles, and bioavailability parameters. Prescription drugs dominate total value as chronic disease prevalence sustains specialist prescribing volumes, while biologics represent the fastest-expanding margin pool driven by oncology and immunology indications. Generic substitution under the Pharmaceutical Benefits Scheme compresses pricing for small-molecule commoditized segments, concentrating manufacturer competition on bioequivalence certification speed.
TGA's Australian Register of Therapeutic Goods mandates pre-market efficacy and safety validation, while the Pharmaceutical Benefits Advisory Committee determines subsidy eligibility that directly shapes patient access and commercial volume potential. The Therapeutic Goods Act and complementary state pharmacy regulations govern distribution channel licensing, restricting direct-to-consumer sales for prescription categories. Stakeholders must monitor PBAC reimbursement list updates and TGA priority review pathway expansions to anticipate which therapy areas will unlock subsidized volume growth.
Market Dynamics
PBAC reimbursement decisions and TGA priority review pathways are compressing commercial timelines for novel therapies, forcing manufacturers to front-load health economics evidence generation before regulatory submission.
Growth Catalysts
- Biologics expansion in oncology:Australia's ageing population sustains demand for monoclonal antibodies and immune checkpoint inhibitors in solid tumor management, with hospital formularies expanding dedicated infusion capacity.
- TGA streamlined approval pathways:Priority review and provisional determination mechanisms accelerate market access for breakthrough therapies, reducing time-to-reimbursement for sponsors with robust clinical packages.
- New South Wales specialist infrastructure:Concentration of tertiary referral centers in Sydney and Melbourne anchors high-value prescribing volumes for complex chronic conditions.
Market Restraints
- Plasma supply concentration:Domestic fractionation depends on CSL Limited's Melbourne facilities, creating single-source vulnerability for immunoglobulin and albumin products.
- Generic substitution under PBS:Mandatory price disclosure and reference pricing compress margins for small-molecule commoditized segments, limiting manufacturer reinvestment capacity.
- Biologics manufacturing complexity:Cell culture and purification requirements demand specialized cleanroom infrastructure that few Australian contract manufacturers possess.
Strategic Opportunities
- Regional hospital networks:Queensland and Western Australia specialist centers remain underpenetrated relative to New South Wales and Victoria, offering volume expansion potential for established therapy classes.
- Modular combination packaging:Fixed-dose combinations for cardiovascular and metabolic disease management reduce adherence friction and differentiate hospital tender submissions.
- Digital therapeutics integration:TGA's evolving software-as-a-medical-device framework creates regulatory clarity for prescription digital therapies alongside traditional pharmacotherapy.
Industry Challenges
- Health economics talent scarcity:PBAC submission requirements demand specialized pharmacoeconomic modeling expertise that competes for limited domestic analytical talent.
- Cold chain integrity:Biologics distribution requires validated temperature-controlled logistics across Australia's vast geography, with last-mile rural delivery presenting particular complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Pharmaceuticals Market |
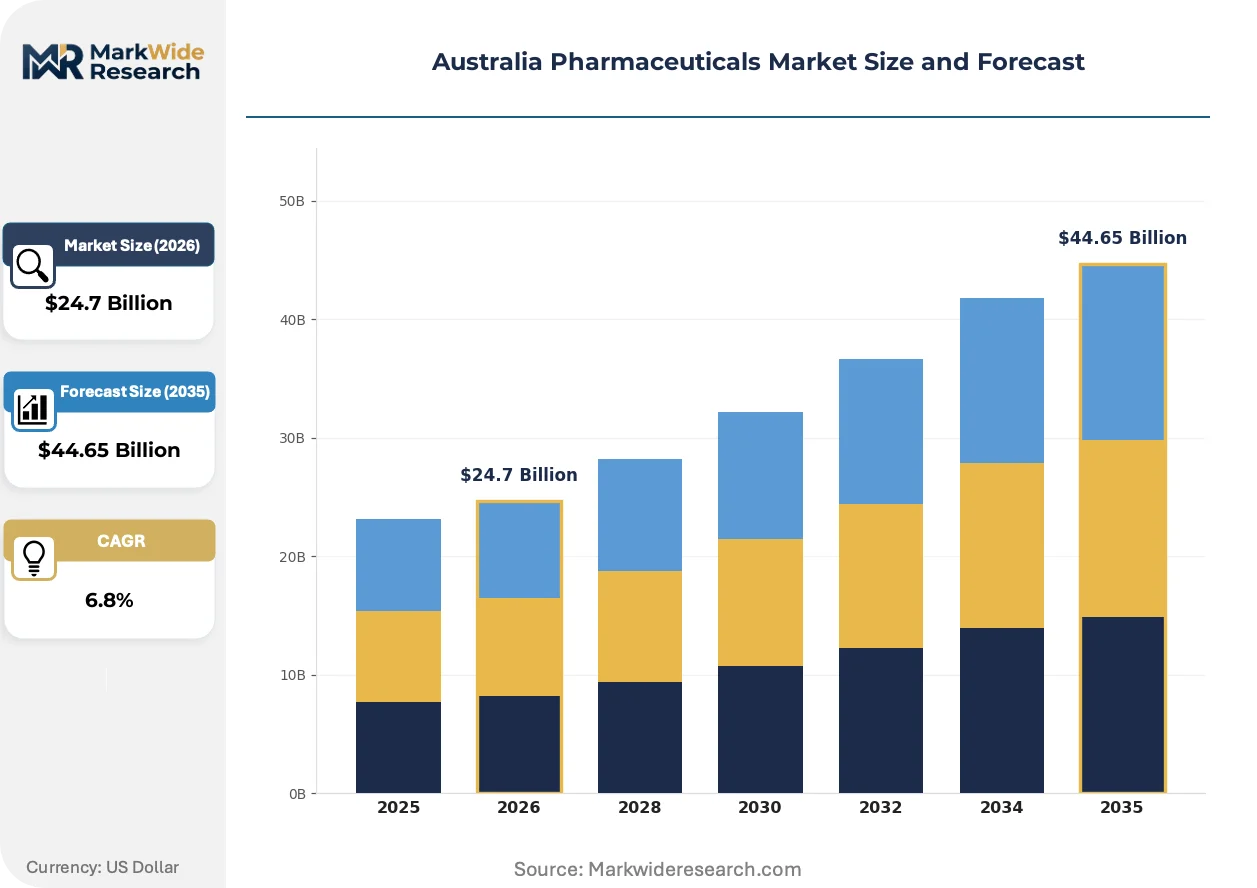
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $44.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Drugs, Over-the-Counter Medicines, Biologics, Generics Therapy Area: Oncology, Cardiovascular, Neurology, Endocrinology Formulation: Tablets, Injectables, Topicals, Powders Distribution Channel: Pharmacies, Hospitals, Online Retail, Wholesale |
| Companies Covered | AstraZeneca PLC, Mayne Pharma Group, CSL Limited, Incannex Healthcare, Telix Pharmaceuticals, Pfizer Australia Holdings, Johnson & Johnson Services, Inc., Starpharma Holdings, Merck & Co., Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Pharmaceuticals Market Strategic Shifts
Digital health infrastructure and precision medicine capabilities are reshaping how Australian prescribers integrate pharmacotherapy with diagnostic stratification, compressing the traditional trial-and-error treatment paradigm.
Continuous manufacturing platforms for oral solid dose formulations are consolidating production economics for generic sponsors. Mayne Pharma Group and local contract manufacturers are adopting direct compression and hot-melt extrusion to reduce batch cycle times. This technology compression is consolidating competitive advantage around speed-to-market for bioequivalent submissions.
TGA's software-as-a-medical-device regulatory guidance is clarifying oversight boundaries for prescription digital therapeutics. The framework distinguishes between wellness applications and clinically validated interventions requiring prescription status. Mental health and substance use disorder applications are most affected, with sponsors restructuring clinical evidence packages to meet TGA's risk-based classification thresholds.
Hospital pharmacy procurement is consolidating around episode-based value assessment rather than per-unit cost metrics. New South Wales and Victoria health networks are piloting bundled payment models for oncology and immunology biologics, with formulary decisions weighting total cost of care against clinical outcomes. This behavioral shift is most visible in metropolitan tertiary centers where specialist pharmacy committees control access protocols.
Australia Pharmaceuticals Market Segmentation
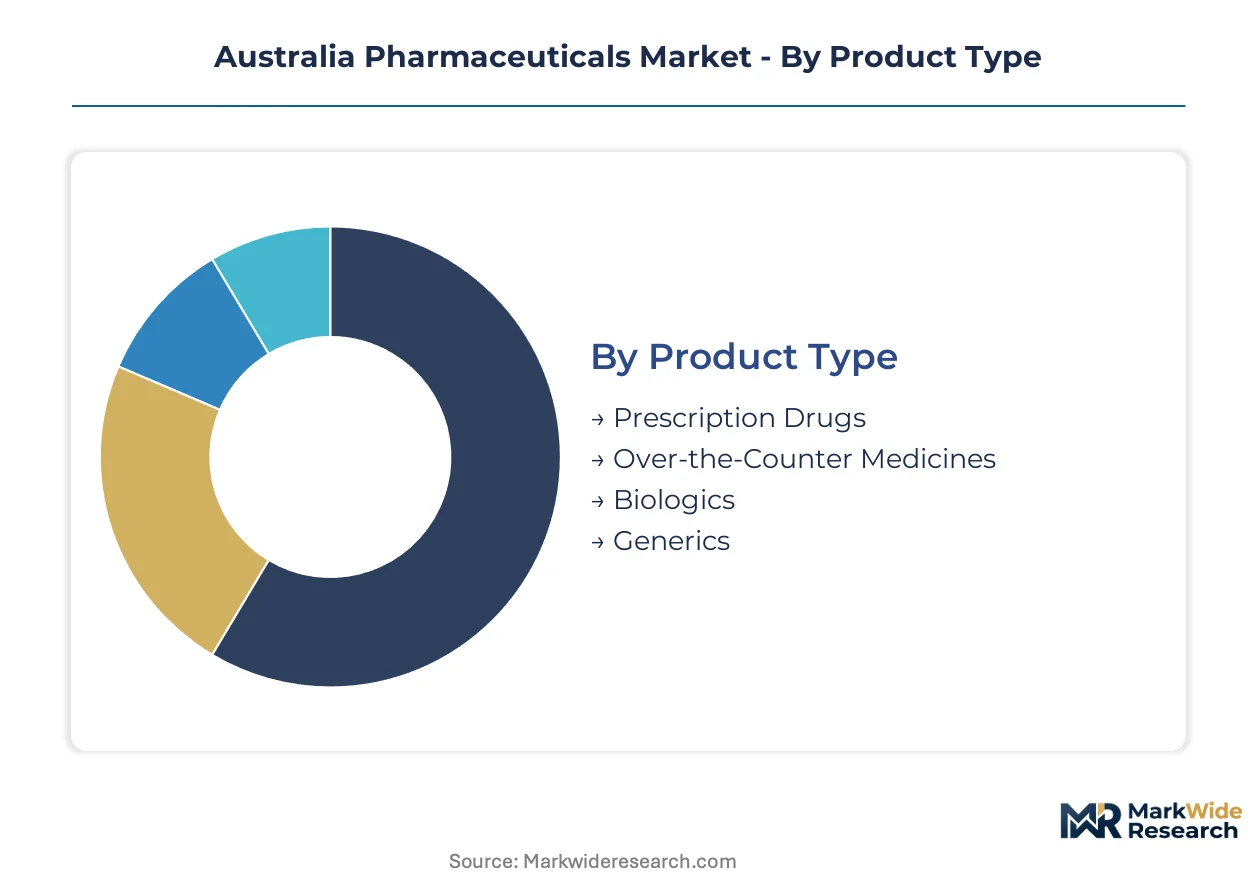
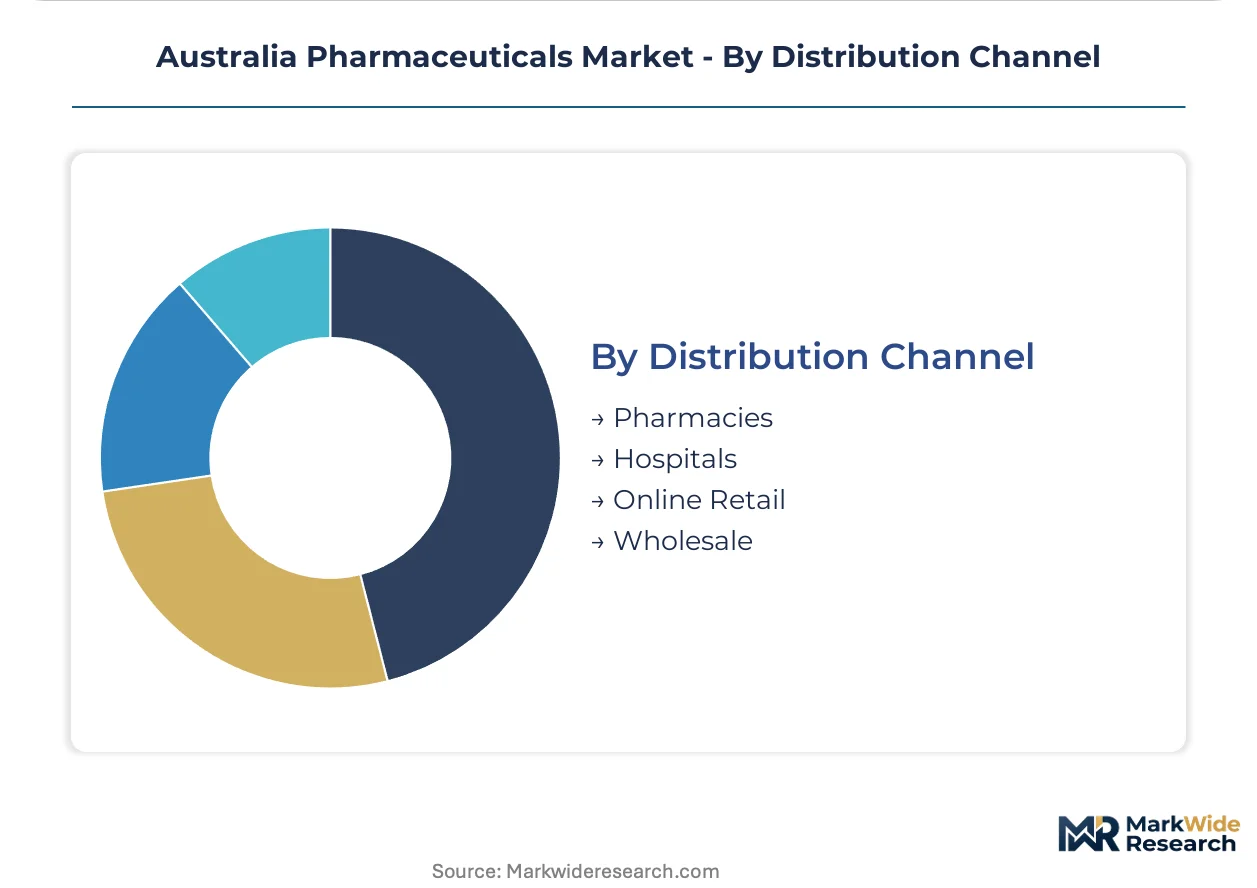
Pharmaceutical segmentation in Australia reflects the interplay between regulatory pathways, clinical infrastructure, and reimbursement mechanics. Distinct demand profiles emerge across product categories, with hospital procurement and PBS subsidy status determining commercial viability for each segment.
Product Type:
Technology intensity and manufacturing complexity separate these categories, with biologics commanding specialized production infrastructure and prescription drugs dominating volume throughput.
- Prescription Drugs:Small-molecule formulations requiring specialist authorization under PBS protocols. Chronic disease prevalence in New South Wales and Victoria sustains high prescribing volumes through hospital outpatient clinics and community specialists.
- Biologics:Cell-derived therapeutic proteins and monoclonal antibodies manufactured through recombinant DNA technology. Hospital infusion centers in Sydney and Melbourne anchor demand as oncology and immunology indications expand.
- Over-the-Counter Medicines:Self-selected remedies for minor ailments distributed through community pharmacies and retail channels.
- Generics:Bioequivalent substitutes subject to mandatory PBS price disclosure, compressing margins while expanding volume access.
Prescription drugs lead on scale; biologics lead on momentum.
Therapy Area:
Clinical unmet need and reimbursement generosity concentrate manufacturer investment, with Australia's ageing demographic shifting the disease burden toward chronic and degenerative conditions.
- Oncology:Systemic cytotoxic agents, targeted small molecules, and immune-modulating biologics for solid and hematological malignancies. TGA priority review pathways accelerate access for breakthrough therapies, while PBAC reimbursement decisions determine commercial uptake in tertiary centers.
- Cardiovascular:Antihypertensives, anticoagulants, and lipid-modifying agents addressing Australia's high ischemic heart disease burden. Fixed-dose combination packaging is gaining traction in hospital formularies seeking adherence improvements.
- Neurology:Therapeutics for epilepsy, multiple sclerosis, and neurodegenerative disorders requiring specialist diagnosis and long-term management protocols.
- Endocrinology:Insulin analogues, GLP-1 receptor agonists, and thyroid hormones responding to diabetes and metabolic syndrome prevalence.
Oncology commands the steepest expansion trajectory; cardiovascular maintains the largest installed patient base.
Formulation:
Manufacturing platform economics and administration setting requirements shape competitive dynamics, with sterile injectables demanding capital-intensive cleanroom infrastructure unavailable to most domestic sponsors.
- Injectables:Parenteral formulations including vials, pre-filled syringes, and infusion bags for hospital administration. Cold chain requirements and aseptic processing constraints limit domestic manufacturing options, concentrating supply around CSL Limited's Melbourne fractionation complex and imported finished doses.
- Tablets:Oral solid dosage forms dominating outpatient prescribing and PBS dispensing volumes. Continuous manufacturing adoption by Mayne Pharma Group and contract manufacturers is compressing production cycle times for generic sponsors.
- Topicals:Transdermal and dermal preparations for localized dermatological and pain management applications.
- Powders:Reconstitutable formulations and inhalation products requiring specialized stability testing and device compatibility validation.
Tablets lead on scale; injectables lead on momentum.
Distribution Channel:
Channel control and margin capture vary sharply, with hospital procurement consolidating around episode-based value assessment while community pharmacy retains PBS dispensing gatekeeper status.
- Hospitals:Tertiary and secondary health networks procuring through tender processes weighted toward total cost of care. New South Wales and Victoria health clusters pilot bundled payment models for high-cost biologics, shifting formulary decisions toward outcome metrics.
- Pharmacies:Community dispensaries processing PBS prescriptions and providing patient counseling on chronic medication management. State pharmacy regulations restrict ownership structures and location requirements, preserving incumbent competitive positions.
- Online Retail:Emerging channel for non-prescription categories and pharmacy-fulfilled repeat prescriptions, subject to TGA advertising restrictions and state licensing requirements.
- Wholesale:National distribution networks maintaining inventory buffers and cold chain integrity across Australia's vast geography, with last-mile rural delivery presenting particular operational complexity.
Hospitals lead on scale; online retail leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's pharmaceutical industry traces its modern scale to post-war manufacturing investments in Melbourne and Sydney, where domestic fractionation and formulation capabilities consolidated during the 1950s-1960s. TGA's establishment in 1990 formalized regulatory harmonization with international standards, accelerating foreign sponsor entry. Today state-level health procurement and specialist infrastructure distribution determine regional demand intensity.
New South Wales
Sydney's tertiary hospital networks anchor the nation's highest biologics prescribing volumes, driven by oncology and immunology patient concentration. The state's Local Health Districts pilot bundled payment models for high-cost therapies, shifting formulary decisions toward episode-based value metrics. Westmead and Royal North Shore hospitals host dedicated infusion centers that attract interstate referrals for complex chronic conditions.
Victoria
Melbourne's CSL Limited fractionation complex supplies domestic immunoglobulin and albumin demand while anchoring plasma-derived biologics manufacturing. The state's Therapeutic Innovation Precinct clusters clinical trial operations with university research hospitals, accelerating sponsor site activation timelines. Parkville's specialist pharmacy committees influence national reimbursement precedent through early formulary adoption of novel therapies.
Queensland
Brisbane's Metro North and Metro South hospital networks expand specialist capacity to capture northern New South Wales patient flows, driving biologics volume growth. The state's Hospital and Health Services consolidate procurement through shared services entities, compressing tender negotiation cycles for established therapy classes. Gold Coast private hospital infrastructure attracts medical tourism for oncology protocols.
Western Australia
Perth's isolation from eastern seaboard supply chains necessitates validated cold chain logistics across the Nullarbor, raising distribution costs for temperature-sensitive biologics. The state's Department of Health operates centralized pharmacy services that buffer inventory for remote regional hospitals. Fiona Stanley Hospital's specialist cancer center anchors demand for immune checkpoint inhibitors in solid tumor management.
South Australia
Adelaide's manufacturing heritage in oral solid dose formulations supports generic sponsor operations, with Mayne Pharma Group maintaining modified-release technology capabilities. The state's health network procurement concentrates through SA Health's centralized tender processes, favoring suppliers with demonstrated supply continuity. The Adelaide BioMed City precinct clusters clinical research organizations with hospital pharmacy trial units.
Australia Pharmaceuticals Market Competitive Environment
Premium-margin players sit above commodity-margin players across the biologics-generics spectrum, with hospital formulary access determining tier placement. CSL Limited's plasma fractionation monopoly and multinational patent-protected biologics sponsors occupy the upper tier, while PBS-exposed generic manufacturers compete on bioequivalence certification velocity. Three archetypes dominate: domestic plasma-derived specialists, multinational innovative sponsors, and regional generic scale players. Consolidation through M&A and strategic licensing partnerships represent the primary competitive vectors as PBAC reimbursement timelines compress.
Within the domestic manufacturing tier, CSL Limited and Mayne Pharma Group anchor distinctly different capability positions. CSL Limited exemplifies vertically integrated plasma biologics production through its Melbourne fractionation infrastructure. Mayne Pharma Group occupies the oral and injectable dose formulation specialist archetype, with modified-release technology differentiation supporting hospital supply contracts. Among multinational innovators, AstraZeneca PLC and Pfizer Australia Holdings represent the innovative sponsor archetype, leveraging global clinical portfolios to secure TGA priority review and PBAC reimbursement.
| Leading Market Players |
|---|
| AstraZeneca PLC |
| Mayne Pharma Group |
| CSL Limited |
| Incannex Healthcare |
| Telix Pharmaceuticals |
| Pfizer Australia Holdings |
| Johnson & Johnson Services, Inc. |
| Starpharma Holdings |
| Merck & Co., Inc. |
| Others |
Value Chain & Pricing Dynamics
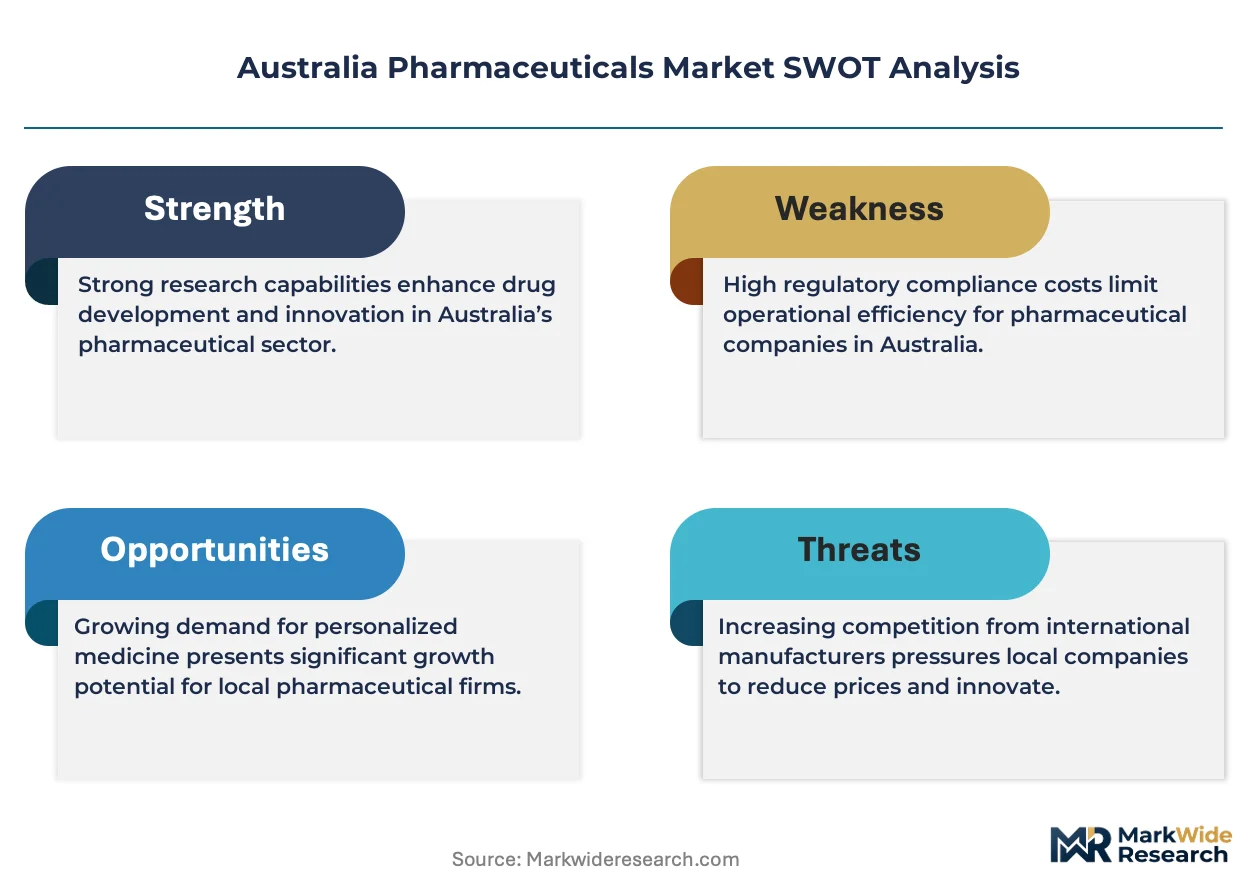
Hospital pharmacy committees in New South Wales and Victoria concentrate procurement authority for high-cost biologics, anchoring a value-based pricing model that weights total cost of care against clinical outcomes. PBAC reimbursement thresholds and tender-based hospital procurement compress margins for manufacturers while rewarding sponsors with robust health economics evidence packages.
Pricing Analysis
Three-tier pricing structure across premium biologics, standard small-molecules, and economy generics dominates the Australian market. Price differentiation hinges on PBAC subsidy status and TGA priority review pathway access, with patented oncology biologics commanding the widest spreads. Cost compression in the generic tier intensifies because mandatory PBS price disclosure triggers automatic price reductions at statutory intervals. Hospital formularies exhibit the sharpest price sensitivity, while specialist outpatient clinics demonstrate greater willingness to absorb premium pricing for breakthrough therapies with demonstrated outcome advantages.
Supply Chain Analysis
Domestic-content rules under Australia's Therapeutic Goods Act reshape sourcing patterns for plasma-derived products, mandating local fractionation where CSL Limited's Melbourne facilities anchor supply. Active pharmaceutical ingredients draw predominantly from India and China, with finished dose formulations supplemented by imports from the United States and European Union. Single-source vulnerability concentrates in immunoglobulin and albumin products where CSL's fractionation monopoly creates supply continuity risk. Distribution runs through national wholesale networks maintaining validated cold chain integrity across vast distances, with last-mile rural delivery presenting particular operational complexity for temperature-sensitive biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australia Pharmaceuticals Market represents a late-cycle quality story where chronic disease prevalence and ageing demographics shift demand toward premium biologics with demonstrated outcome differentiation. Formulary committees increasingly weight total cost of care over per-unit acquisition cost, rewarding sponsors with integrated evidence packages.
For Market Incumbents: Lock in formulary position through backward integration into plasma collection infrastructure and expanded Melbourne fractionation capacity. Generic substitution under PBS price disclosure threatens small-molecule margins, demanding accelerated bioequivalence certification velocity and continuous manufacturing adoption to defend cost position. Priority review pathway investment remains the critical lever for novel therapy sponsors seeking compressed time-to-reimbursement. For New Entrants and Emerging Players: Capture volume in Queensland and Western Australia specialist centers where tertiary infrastructure expansion lags New South Wales and Victoria penetration. Regional hospital networks in Brisbane and Perth present the most penetrable geography for established oncology and immunology therapy classes. Digital therapeutics integration alongside traditional pharmacotherapy offers a differentiated go-to-market angle under TGA's evolving software-as-a-medical-device framework. For Investors and Strategic Acquirers: Mid-cap biotech sponsors with late-stage clinical pipelines are the most active acquirer targets in this space, as multinational innovators seek to replenish portfolios ahead of patent cliffs. Long-term viability favors vertically integrated plasma specialists and formulation technology platforms with demonstrated hospital supply contract durability. PBAC reimbursement list additions for novel oncology indications serve as the primary inflection signal warranting ongoing watch.| Strategic Initiative | Industry Significance |
|---|---|
| PBAC Reimbursement Strategy | Determines commercial volume potential for novel therapies seeking subsidized patient access. |
| TGA Priority Review Pathway | Accelerates market entry timelines for breakthrough therapies with robust clinical evidence packages. |
| Plasma Collection Infrastructure | Secures captive supply of raw material for fractionation-dependent immunoglobulin and albumin products. |
| Continuous Manufacturing Adoption | Compresses production cycle times for generic sponsors competing on bioequivalence certification speed. |
| Digital Therapeutics Integration | Creates regulatory clarity for prescription software interventions under TGA's risk-based classification framework. |
Study Parameters
Multiple input streams — regulatory filings, hospital procurement databases, and sponsor clinical trial disclosures — were reconciled through structured primary interviews with formulary directors, TGA regulatory affairs leads, hospital pharmacy procurement managers, and PBAC reimbursement specialists. Secondary validation drew from TGA Australian Register of Therapeutic Goods entries, PBAC public summary documents, Pharmaceutical Benefits Scheme pricing data, and hospital tender announcement records. Bottom-up patient-volume modeling and top-down market sizing approaches were triangulated to establish segment boundaries.
Data-stream reconciliation across product type, therapy area, formulation, and distribution channel dimensions supported the analytical framework throughout the projection horizon. CAGRs were derived from trend extrapolation of historic PBS dispensing volumes, hospital biologics procurement records, and specialist prescribing pattern analysis. Treatment line positioning and regional regulatory cluster differentiation informed forecast segmentation for oncology and immunology indications.
PBAC reimbursement delays, TGA regulatory pathway revisions, and plasma supply disruptions are the dominant revision risks that could alter trajectory assumptions across the modeling period. A small set of named triggers — formulary adoption rates for novel biologics, generic substitution velocity under PBS, and digital therapeutics regulatory clarity — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Antidotes Market
Pharmaceuticals
Global Pediatric Drugs Market
Pharmaceuticals
Pharma PLM Market
Pharmaceuticals
Europe FMD Vaccine Market
Pharmaceuticals
Extended Oral Antibiotics Market
Pharmaceuticals
Oral Anticoagulant Market
Pharmaceuticals
Urticaria Drugs Market
Pharmaceuticals
Sporanox Market
Pharmaceuticals
Anti Obesity Prescription Drugs Market
Pharmaceuticals
Antispasmodics Drugs Market
Pharmaceuticals
Global Preventive Vaccines Market
Pharmaceuticals
Global Cyclosporine Market
Pharmaceuticals
Global Doxorubicin Market
Pharmaceuticals
Global Lidocaine Transdermal Patch Market
Pharmaceuticals
Germany Pharmaceutical 3PL Market
Pharmaceuticals
Latin America FMD Vaccine Market