
 Global Clinical Decision Support System Market | 2026-2036
Global Clinical Decision Support System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Clinical Decision Support System Market Foresight
The shift from fragmented, single-source clinical data architectures toward unified, multi-source platforms is consolidating procurement strategies across large health systems. Wolters Kluwer N.V. leverages its medical publishing heritage to anchor knowledge-based content layers within enterprise CDSS contracts. Siemens Healthineers competes through deep integration with imaging workflows, while Epic Systems Corporation controls the ambulatory segment through its dominant EHR footprint in U.S. hospital networks.
A clinical decision support system comprises software applications that analyze patient data against structured medical knowledge bases to generate real-time alerts, diagnostic suggestions, or therapy recommendations at the point of care. These systems typically incorporate rule-based inference engines, natural language processing modules, and probabilistic clinical algorithms to filter signal from noise in electronic health records. Knowledge-based systems retain the largest installed base due to their explainable reasoning chains and regulatory auditability, though cloud-based deployment is gaining share as health systems seek to reduce on-premise infrastructure burdens. Among end users, hospitals command the deepest CDSS penetration, while ambulatory care centers represent the fastest expansion vector as outpatient complexity rises.
The FDA regulates CDSS software as medical devices under evolving guidance that distinguishes decision-support tools from autonomous diagnostic systems, while HIPAA mandates govern patient data flows that underpin these platforms. In Europe, the EU AI Act and MDR create layered compliance obligations for algorithmic transparency and clinical validation. Stakeholders must monitor how divergent regulatory timelines across the U.S., European, and Japanese frameworks reshape product roadmaps and market access requirements.
Market Dynamics
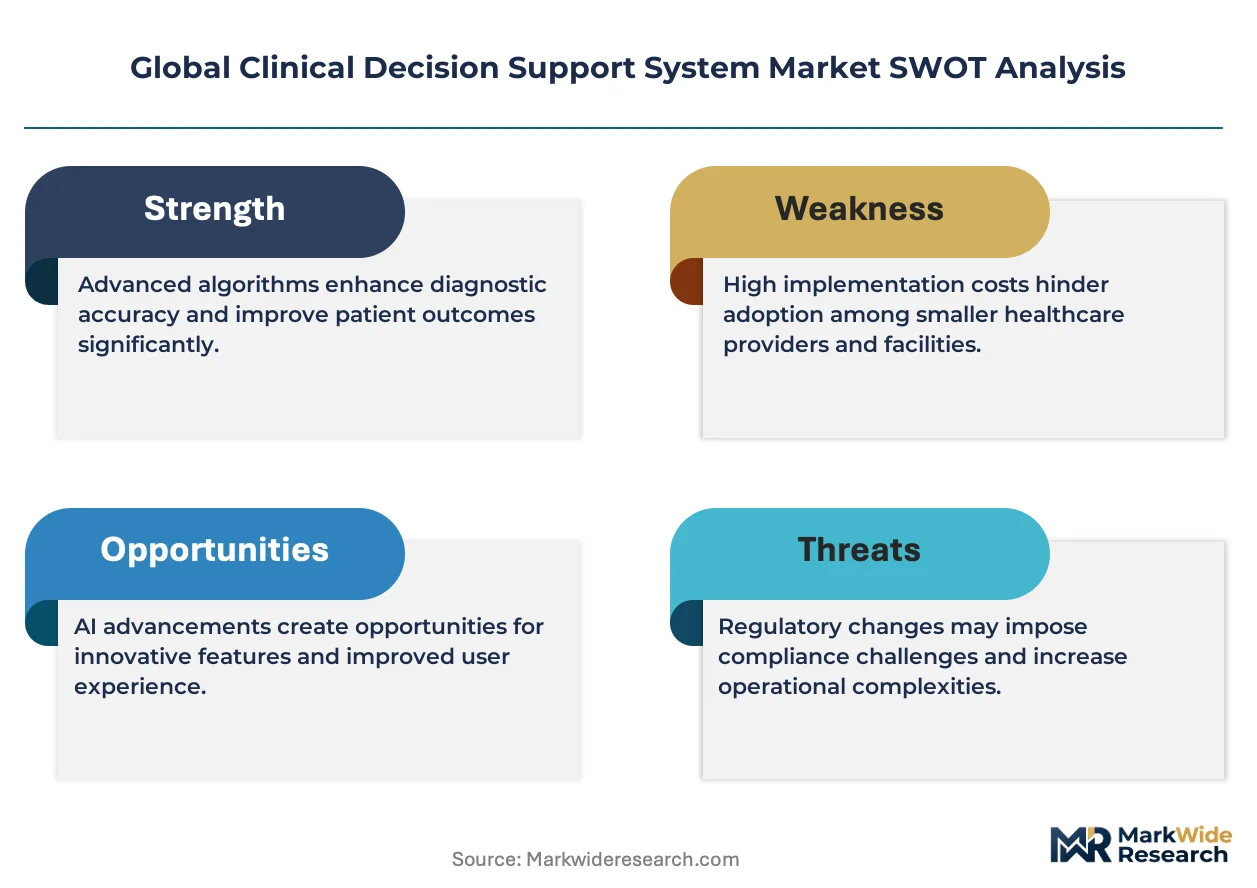
Regulatory mandates for algorithmic transparency are compressing vendor roadmaps as the FDA, EU AI Act, and PMDA impose divergent validation requirements on clinical decision support modules.
Growth Catalysts
- Interoperability mandates:The 21st Century Cures Act in the United States compels EHR vendors to open APIs for third-party CDSS integration. Hospital networks accelerate procurement of certified decision-support modules to meet compliance deadlines.
- Diagnostic error reduction targets:Ambulatory surgery centers deploy real-time alert systems to address rising outpatient complexity. These facilities prioritize CDSS platforms that integrate with existing workflow engines.
- Cloud migration incentives:Health systems in Germany and Japan reduce on-premise infrastructure burdens by adopting SaaS-based clinical knowledge bases. Procurement teams favor subscription models over perpetual licenses.
Market Restraints
- Algorithmic audit costs:The EU AI Act's high-risk system classification imposes extensive documentation burdens on CDSS vendors. Compliance expenditures consume disproportionate resources relative to revenue scale.
- Specialist talent scarcity:Clinical informaticists with dual expertise in medicine and machine learning command premium compensation. Health systems struggle to staff implementation teams for complex deployments.
- Legacy system entrenchment:Proprietary data formats in incumbent EHR platforms create technical friction for modular CDSS integration. Interoperability gaps persist despite regulatory pressure.
Strategic Opportunities
- Rural health network expansion:Federally qualified health centers in the United States represent underpenetrated deployment targets for telemedicine-integrated CDSS. These facilities lack specialist coverage and prioritize diagnostic support tools.
- Japan's super-aging society:The PMDA's streamlined approval pathway for geriatric-focused algorithms creates regulatory tailwinds. Vendors targeting polypharmacy alert systems gain accelerated market access.
- Natural language processing convergence:Integration of large language models with structured knowledge bases enables ambient clinical documentation. Early adopters in academic medical centers pilot voice-activated decision support at the point of care.
Industry Challenges
- Alert fatigue mitigation:Clinicians override excessive low-value notifications, eroding trust in CDSS platforms. Vendors must redesign prioritization algorithms to preserve clinical engagement.
- Validation timeline compression:Prospective clinical studies for FDA 510(k) clearance require multi-site coordination. Startups exhaust runway before completing evidentiary requirements.
- Data governance fragmentation:HIPAA, GDPR, and Japan's Act on Protection of Personal Information impose conflicting consent and retention rules. Multi-national deployments demand jurisdiction-specific architectural modifications.
Report Scope
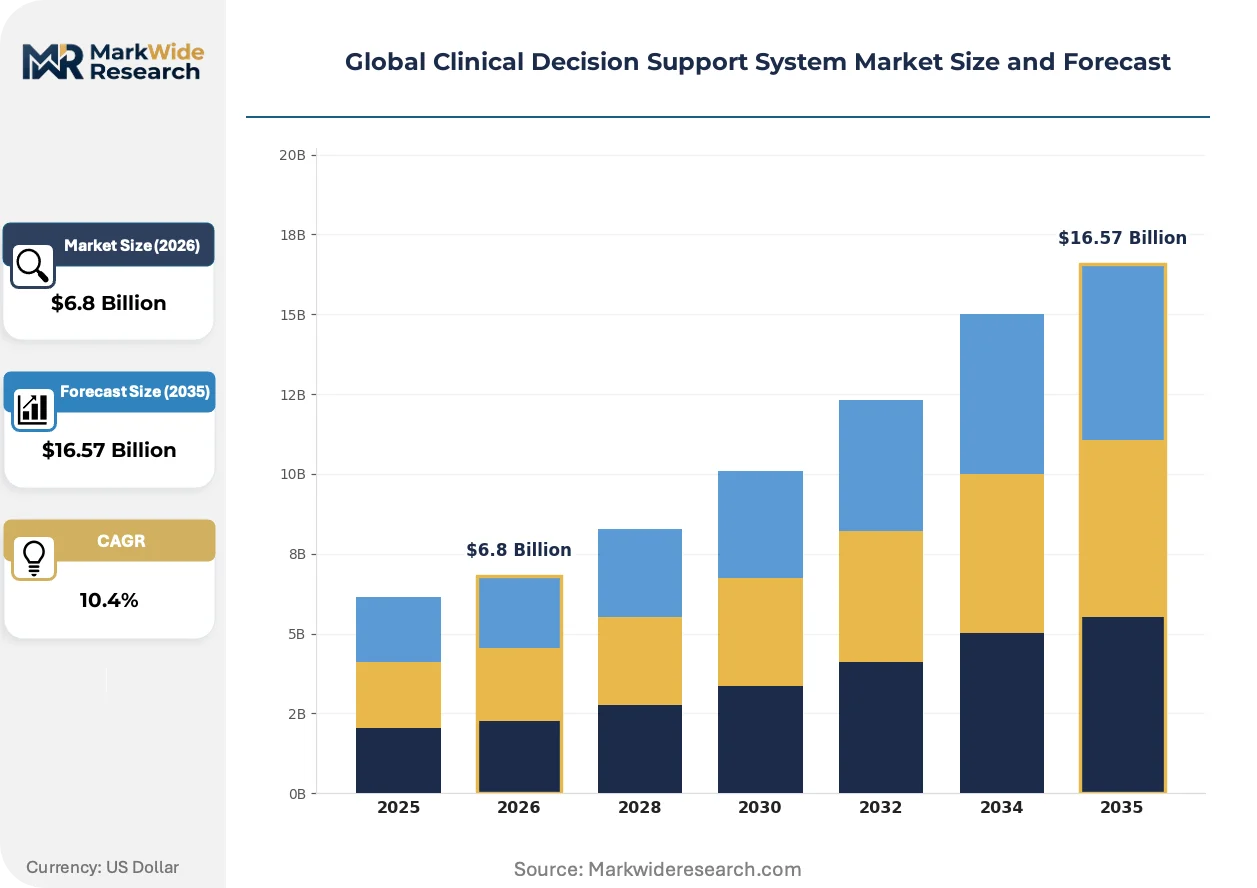
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Clinical Decision Support System Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $16.57 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Knowledge-Based Systems, Non-Knowledge-Based Systems, Hybrid Systems, Guidelines-Based Systems Deployment: On-Premise, Cloud-Based, Hybrid, Web-Based Application: Drug Interaction Checking, Disease Diagnosis, Therapy Management, Clinical Workflow Optimization End User: Hospitals, Ambulatory Care Centers, Diagnostic Laboratories, Specialty Clinics |
| Companies Covered | Wolters Kluwer N.V., Change Healthcare, Oracle, Siemens Healthineers, Koninklijke Philips N.V., Merative, Veradigm Inc., Elsevier B.V., Epic Systems Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Clinical Decision Support System Market Shifts & Advancements
Generative AI architectures are restructuring how clinical knowledge bases are constructed, queried, and maintained. Three distinct vectors are reshaping competitive positioning and procurement criteria.
Probabilistic clinical algorithms are overtaking deterministic rule-based engines in enterprise procurement evaluations. These systems process unstructured clinical notes to generate differential diagnoses. Academic medical centers in the United States pilot these tools for complex case review. The technology is overtaking legacy inference engines by reducing manual knowledge base curation burdens.
The EU AI Act's high-risk system classification is mandating algorithmic impact assessments for diagnostic support modules. Vendors must document training data provenance and performance metrics across demographic subgroups. European hospital procurement committees now require transparency documentation as a mandatory evaluation criterion. German university hospitals have established dedicated AI ethics review boards to evaluate vendor submissions.
Subscription-based knowledge base licensing is displacing perpetual content agreements in health system procurement. Chief information officers prioritize vendors offering continuous updates over static annual releases. This shift concentrates purchasing power with platforms demonstrating sustained editorial investment. The transformation is most visible in United States integrated delivery networks consolidating vendor relationships.
Global Clinical Decision Support System Market Segmentation
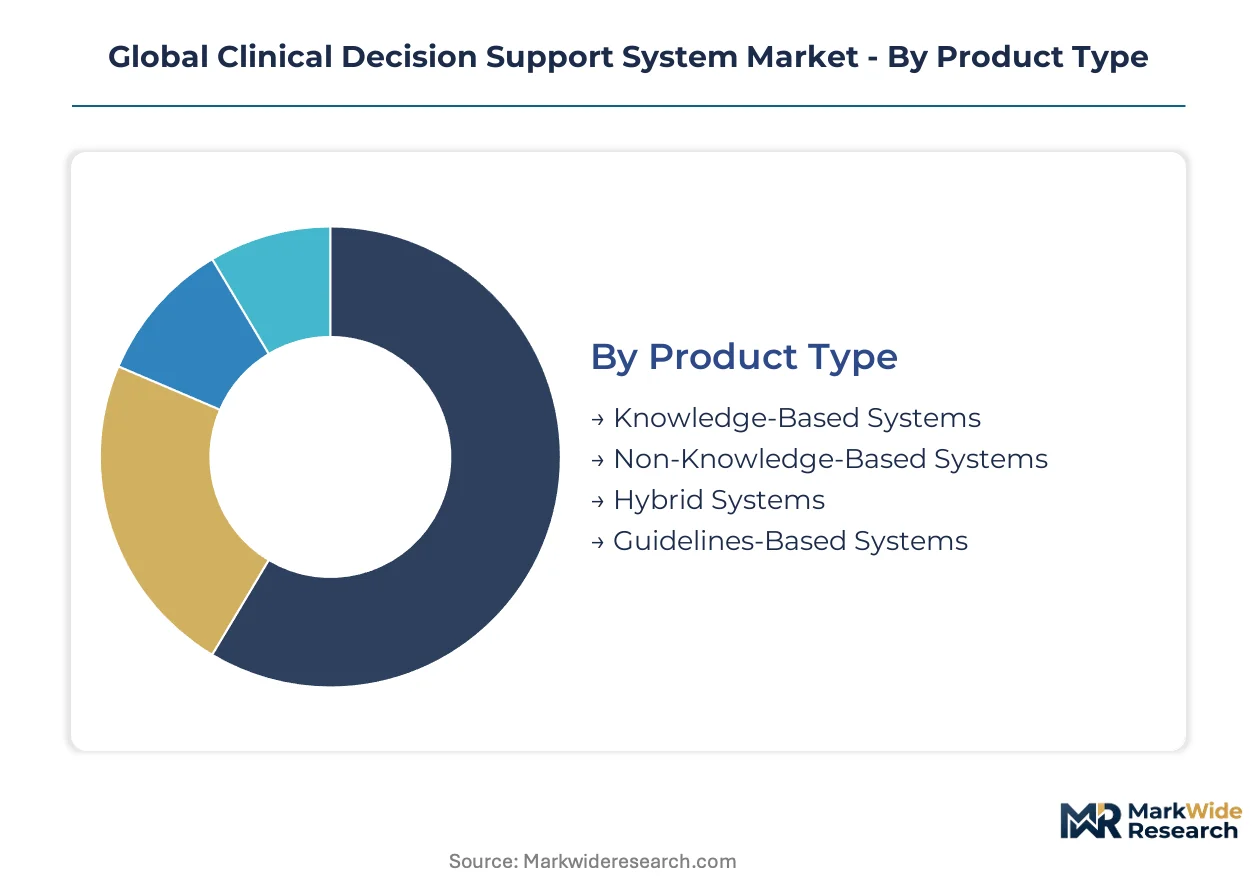
CDSS procurement strategies diverge sharply across product architectures, deployment models, and care settings. Hospital networks prioritize segments offering regulatory auditability and EHR interoperability, while ambulatory operators chase workflow efficiency gains.
Product Type:
Knowledge-based systems dominate installed base volume, yet hybrid architectures command premium pricing through combined explainability and adaptive learning.
- Knowledge-Based Systems:These platforms embed structured medical ontologies and explicit inference rules that generate traceable clinical recommendations. German university hospitals and Japanese academic medical centers specify these systems for regulatory submissions requiring documented reasoning chains. FDA 510(k) pathways favor their transparent decision logic.
- Hybrid Systems:Architectures fuse symbolic reasoning with machine learning pattern recognition to balance interpretability and predictive accuracy. United States integrated delivery networks pilot these for complex diagnostic cases where neither pure rules nor black-box models suffice. Procurement committees cite their dual-validation capability as decisive.
- Non-Knowledge-Based Systems:Pure statistical models trained on large clinical datasets without explicit medical knowledge encoding.
- Guidelines-Based Systems:Platforms implementing standardized care protocols from medical specialty societies.
Today's leader: Knowledge-Based Systems. Tomorrow's challenger: Hybrid Systems.
Deployment:
Cloud migration accelerates fastest in markets with mature data protection frameworks, while on-premise retention persists where sovereignty concerns dominate.
- Cloud-Based:SaaS delivery eliminates capital expenditure for server infrastructure and enables continuous knowledge base updates. Health systems in Germany leverage these deployments to satisfy GDPR Article 32 security requirements through EU-sovereign data centers. Subscription economics align vendor incentives with ongoing clinical relevance.
- On-Premise:Local installation maintains physical control over patient data flows and customization depth. Japanese hospital networks favor these deployments where PMDA audit trails demand direct system access. Air-gapped configurations serve military and intelligence community healthcare facilities.
- Hybrid:Split architectures processing sensitive data locally while leveraging cloud analytics for non-identifiable population insights.
- Web-Based:Browser-accessible platforms requiring minimal local IT footprint for rapid departmental deployment.
Cloud-Based deployment is climbing the fastest as HIPAA Business Associate Agreements and GDPR processor contracts standardize.
Application:
Error-prone clinical tasks drive procurement priority, with medication safety commanding the largest absolute spend and diagnostic support posting the steepest expansion trajectory.
- Drug Interaction Checking:Real-time screening of prescribed medications against patient-specific allergy profiles and pharmacokinetic interaction databases. United States hospital networks deploy these modules to meet Joint Commission medication management standards. Alert fatigue mitigation features determine vendor selection.
- Disease Diagnosis:Differential diagnosis generation from presenting symptoms, laboratory values, and imaging findings. Academic medical centers in Japan pilot probabilistic diagnostic engines for rare disease identification. PMDA's streamlined pathway for geriatric-focused algorithms accelerates vendor entry.
- Therapy Management:Treatment protocol selection and dosing optimization across oncology, antimicrobial stewardship, and chronic disease management.
- Clinical Workflow Optimization:Scheduling, resource allocation, and care pathway orchestration tools.
Drug Interaction Checking anchors current procurement budgets. Disease Diagnosis is gaining share fastest as large language models mature.
End User:
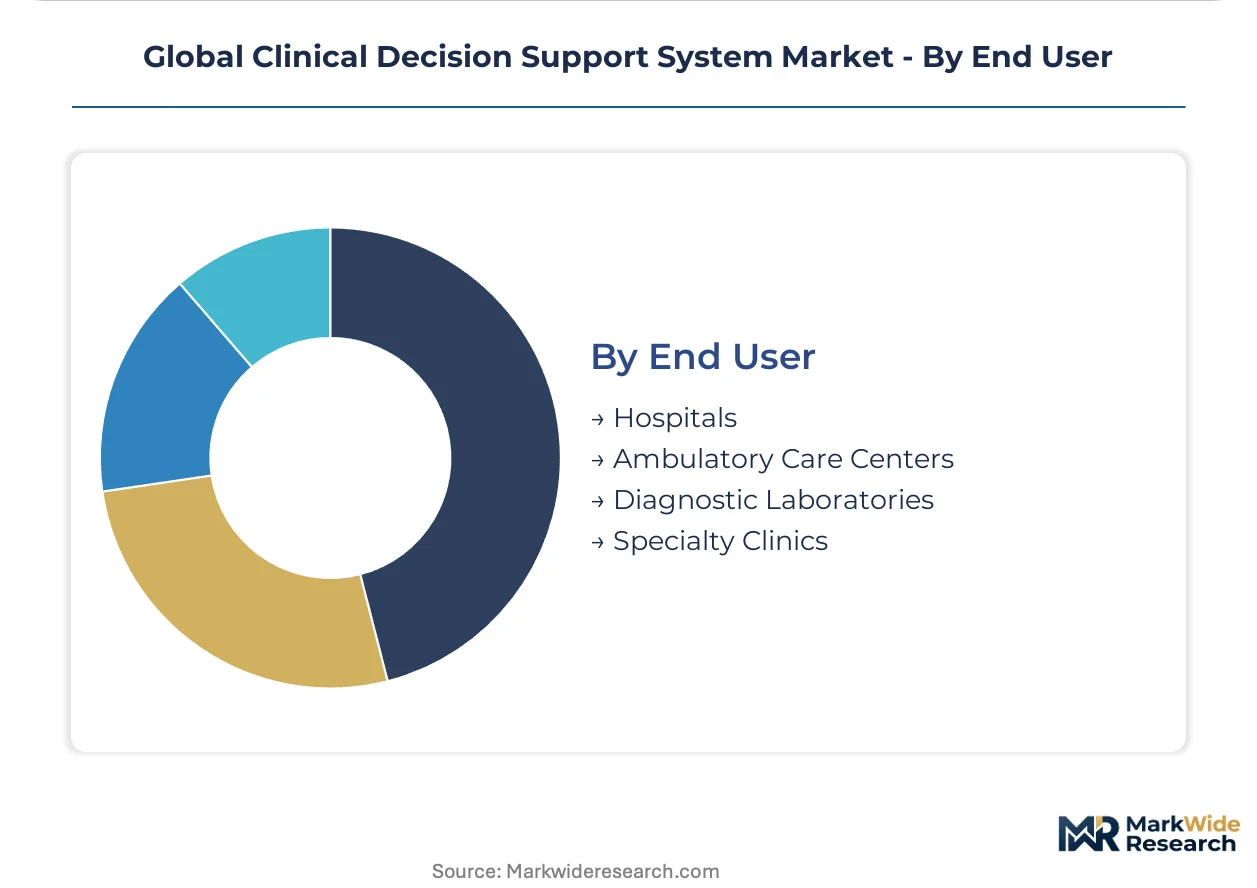
Hospital scale enables integrated CDSS suites, while outpatient settings demand modular point solutions with lighter implementation burdens.
- Hospitals:Multi-department deployments spanning emergency medicine, intensive care, and perioperative services. Epic Systems Corporation's dominant EHR footprint in United States hospital networks creates captive demand for integrated decision-support modules. Chief medical information officers prioritize enterprise-wide alert governance.
- Ambulatory Care Centers:Outpatient surgery and chronic disease management facilities with limited specialist coverage. Federally qualified health centers in rural United States regions deploy telemedicine-integrated CDSS to address diagnostic support gaps. These facilities represent the most underpenetrated addressable market.
- Diagnostic Laboratories:Pathology and radiology operations requiring interpretation support for complex specimen analysis.
- Specialty Clinics:Cardiology, oncology, and mental health practices with disease-specific decision-support requirements.
Hospitals retain the deepest penetration. Ambulatory Care Centers represent the steepest expansion trajectory as outpatient complexity rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping vendor investment patterns as the FDA's evolving guidance on clinical decision support software creates compliance cost gaps against Europe's layered EU AI Act and MDR obligations. Vendors are calibrating market entry sequences based on divergence in validation timelines across Washington, Brussels, and Tokyo.
United States
Hospital networks dominate procurement volume as integrated delivery networks consolidate vendor relationships under value-based care contracts. The 21st Century Cures Act compels EHR vendors to open APIs for third-party CDSS integration, accelerating certified module adoption. Epic Systems Corporation's dominant footprint across academic medical centers in Boston and the Research Triangle creates captive demand for embedded decision-support workflows.
Germany
University hospitals specify knowledge-based systems for regulatory submissions requiring documented reasoning chains under MDR compliance frameworks. GDPR Article 32 security requirements drive health systems toward EU-sovereign cloud data centers for SaaS knowledge base deployments. The Berlin-Brandenburg health technology cluster hosts specialized AI ethics review boards evaluating vendor transparency documentation.
Japan
Super-aging demographics concentrate demand for geriatric-focused polypharmacy alert systems as outpatient complexity rises. PMDA's streamlined approval pathway for algorithms targeting elderly populations accelerates vendor market access timelines. The Kanto region's academic medical centers pilot probabilistic diagnostic engines for rare disease identification.
United Kingdom
NHS England's procurement frameworks prioritize interoperability standards that reduce technical friction for modular CDSS integration with incumbent EHR platforms. The Medicines and Healthcare products Regulatory Agency aligns post-Brexit device guidance with FDA convergence initiatives. London's digital health cluster concentrates health informatics talent for implementation team staffing.
India
CDSCO's medical device classification rules create uncertainty for software-as-medical-device determinations, slowing enterprise procurement decisions. Telemedicine-integrated CDSS deployments expand across federally qualified health centers addressing specialist coverage gaps in rural states. The Hyderabad-Bengaluru corridor attracts clinical informatics talent for health system implementation teams.
Global Clinical Decision Support System Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cloud-native architectures and large language model integration. The vendor base stratifies across three tiers: dominant EHR-integrated platforms, specialized medical content publishers, and imaging workflow specialists. Two strategic archetypes define competitive positioning: knowledge-base custodians leveraging editorial heritage, and workflow-integrated platforms controlling point-of-care access. Consolidation pressure intensifies as health systems demand unified procurement relationships, while technology licensing agreements proliferate between AI specialists and incumbent infrastructure vendors.
Among medical content specialists, Wolters Kluwer N.V. and Elsevier B.V. exemplify the knowledge-custodian archetype, anchoring enterprise contracts through structured clinical ontologies. Siemens Healthineers occupies a position within the imaging-integrated tier, representing workflow-centric competitive logic. Epic Systems Corporation exemplifies the EHR-captive model, leveraging ambulatory footprint density to control decision-support module distribution. These three anchors illustrate divergent paths to procurement influence without converging on common technology strategies.
| Leading Market Players |
|---|
| Wolters Kluwer N.V. |
| Change Healthcare |
| Oracle |
| Siemens Healthineers |
| Koninklijke Philips N.V. |
| Merative |
| Veradigm Inc. |
| Elsevier B.V. |
| Epic Systems Corporation |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up medical content specialists anchor supply concentration in clinical decision support, consolidating fragmented knowledge bases into subscription platforms that enforce pricing discipline through exclusive editorial control. This ownership pattern compresses vendor margins while concentrating procurement leverage with health systems demanding continuous knowledge base updates.
Pricing Analysis
Distributor margins in enterprise CDSS contracts typically run 15-25 percent for channel partners reselling into mid-tier hospital networks. Three-tier pricing structure across premium, standard, and economy levels separates academic medical centers with full-suite deployments from rural clinics purchasing modular point solutions. Price differentiation centers on certification grade—FDA 510(k)-cleared modules command 40-60 percent premiums over non-device-classified decision support—and customization depth for EHR integration. Pricing pressure stems from cloud migration incentives as SaaS economics displace perpetual license revenue. Ambulatory care centers exhibit highest price sensitivity, while integrated delivery networks in the United States negotiate enterprise discounts through volume consolidation.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Epic Systems Corporation's dominant EHR footprint, bypassing traditional distribution for embedded decision-support modules. Knowledge base development concentrates in the Netherlands, Germany, and the United States where medical publishers maintain structured clinical ontologies. Raw material inputs draw from clinical informaticist labor pools in India and Eastern Europe, GPU compute clusters for machine learning training, and proprietary EHR data licensing agreements. Single-source vulnerability persists where Wolters Kluwer N.V. and Elsevier B.V. control exclusive content licensing for specialist medical societies. Distribution runs through health system GPO contracts and direct vendor relationships with hospital procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The clinical decision support market reads as a late-cycle quality story as procurement committees prioritize algorithmic transparency documentation and regulatory auditability over cost minimization.
For Market Incumbents: To counter generative AI entrants disrupting knowledge base economics, Wolters Kluwer N.V. and Elsevier B.V. must deepen vertical integration into natural language processing talent pools through targeted clinical informaticist hiring. Siemens Healthineers should reinforce imaging workflow integration as the priority defensive moat against modular CDSS vendors. Certification investment in EU AI Act high-risk system compliance creates switching costs that preserve incumbent pricing power. For New Entrants and Emerging Players: Capture federally qualified health centers in rural United States regions as the most penetrable deployment target, where specialist coverage gaps create urgent demand for telemedicine-integrated diagnostic support. Japan's super-aging society offers accelerated PMDA approval pathways for geriatric-focused polypharmacy alert systems. A cloud-native SaaS go-to-market angle with subscription economics aligns vendor incentives with undercapitalized rural health network procurement constraints. For Investors and Strategic Acquirers: Valuations sit cheapest among hybrid system specialists bridging knowledge-based explainability with machine learning predictive accuracy. Long-term viability over the next decade hinges on regulatory convergence between FDA, EU AI Act, and PMDA validation timelines. Acquisition targets should demonstrate sustained editorial investment in knowledge base currency. The signal to watch is health system procurement committee mandates for algorithmic impact assessment documentation as a mandatory evaluation criterion.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | High-risk system classification mandates transparency documentation for European hospital procurement committees. |
| Large Language Model Integration | Probabilistic diagnostic engines from academic medical centers in Japan and the United States reduce manual knowledge curation burdens. |
| Rural Health Network Partnership | Federally qualified health centers address specialist coverage gaps through telemedicine-integrated CDSS deployment. |
| Cloud-Native SaaS Migration | Subscription economics align vendor incentives with continuous knowledge base updates demanded by CIOs. |
| Imaging Workflow Deep Integration | Siemens Healthineers leverages radiology and pathology interpretation support for competitive positioning. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with chief medical information officers, hospital procurement committee chairs, clinical informaticists, biomedical engineers, and GPO contracts managers with secondary validation against FDA 510(k) filings, EU MDR submissions, hospital procurement databases, CMS Medicare reimbursement data, and GPO contract repositories. Bottom-up deployment tracking across health systems triangulated with top-down vendor revenue analysis.
Segment-weighting approaches distributed value across knowledge-based, hybrid, and non-knowledge-based product architectures; cloud-based, on-premise, and hybrid deployment models; and hospital, ambulatory care center, diagnostic laboratory, and specialty clinic end users. Modeled dimensions included EHR integration complexity, regulatory certification tier, and regional adoption pattern. CAGRs derived from fitted growth curves incorporating interoperability mandate compliance deadlines, diagnostic error reduction target adoption, and cloud migration incentive penetration. Industry-specific inputs captured PMDA streamlined pathway utilization rates and EU AI Act implementation timeline phasing.
Regulatory divergence between FDA, EU AI Act, and PMDA frameworks, alert fatigue mitigation failure eroding clinical engagement, and specialist talent scarcity constraining implementation velocity are the dominant revision risks across the projection horizon. Forecasts reflect documented assumptions regarding health system consolidation trajectories and EHR vendor API openness. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Healthcare Mobile Application Market
Digital Health Solutions
Digital Therapeutics Market
Digital Health Solutions
Healthcare Chatbots Market
Digital Health Solutions
Global Digital Medicines Market
Digital Health Solutions
Pregnancy Management Software Market
Digital Health Solutions
Artificial Intelligence in Medicine Market
Digital Health Solutions
Smart Healthcare Market
Digital Health Solutions
Women Health Applications Market
Digital Health Solutions
Global Emergency Medical Services Billing Software Market
Digital Health Solutions
Middle East and Africa Virtual Reality (VR) Health Market
Digital Health Solutions
Healthcare Digital Signage Market
Digital Health Solutions
Global Patient Centric Healthcare App Market
Digital Health Solutions
Eclinical Solutions Market
Digital Health Solutions
Patient Engagement Platforms Market
Digital Health Solutions
Advanced Clinical Decision Support Platforms Market
Digital Health Solutions
Global Microservices in Healthcare Market