
 Global Loperamide Hcl Market | 2026-2036
Global Loperamide Hcl Market Size, Share, and Industry Trends Forecast 2026-2036
Global Loperamide Hcl Market Foresight
The over-the-counter self-medication segment is pivoting toward convenience-oriented formats as consumers favor accessible diarrhea relief without clinical visits. Johnson & Johnson leverages its consumer health infrastructure to dominate shelf presence across retail pharmacies. Teva Pharmaceutical Industries Ltd. anchors its position through generic manufacturing scale and broad regulatory dossiers. Perrigo Company plc specializes in private-label store brands that compete aggressively on price at major pharmacy chains.
Loperamide hydrochloride is a synthetic piperidine derivative that functions as a peripherally acting mu-opioid receptor agonist, typically formulated at 2 mg per tablet or capsule for acute and chronic diarrhea management. The compound slows intestinal motility by inhibiting acetylcholine and prostaglandin release in the myenteric plexus, making it a first-line symptomatic treatment. Tablet formulations occupy the largest volume share due to manufacturing simplicity and patient familiarity, while oral suspension formats capture pediatric and geriatric demand where swallowing difficulties limit solid dosage uptake. Online pharmacies represent the fastest-growing distribution channel as digital prescription workflows and direct-to-patient shipping reshape procurement patterns.
The FDA maintains strict bioequivalence requirements for abbreviated new drug applications referencing innovator loperamide products, while the EMA enforces comparable standards through its centralized marketing authorization procedures. India's CDSCO and China's NMPA impose additional local stability and impurity profiling mandates that shape export-oriented manufacturing decisions. Stakeholders must monitor evolving opioid-scheduling discussions in multiple jurisdictions, as regulatory reclassification of loperamide could fundamentally alter access pathways and formulation strategies.
Market Dynamics
The pivot toward direct-to-patient distribution channels is restructuring competitive positioning in loperamide hydrochloride, as online pharmacies erode the traditional retail pharmacy gatekeeper role and force reformulation priorities toward convenience-oriented dosage forms.
Growth Catalysts
- EMA bioequivalence harmonization:Centralized marketing authorization procedures reduce redundant dossier submissions across EU member states, accelerating generic market entry timelines for loperamide products.
- Pediatric formulation demand:Oral suspension formats address swallowing difficulties in geriatric and pediatric populations, expanding addressable patient demographics beyond standard tablet users.
- India's CDSCO export pathway:Streamlined stability and impurity profiling mandates for active pharmaceutical ingredients position Indian manufacturers as preferred suppliers to regulated markets.
Market Restraints
- API concentration risk:Bulk loperamide hydrochloride production concentrates among a limited cohort of Chinese and Indian chemical manufacturers, creating single-source vulnerability.
- Opioid-scheduling friction:Regulatory reclassification discussions in multiple jurisdictions threaten to impose prescription-only restrictions that would eliminate over-the-counter revenue streams.
- Excipient cost volatility:Microcrystalline cellulose and croscarmellose sodium prices fluctuate with pulp and cotton linter markets, compressing formulation margins.
Strategic Opportunities
- Southeast Asia pharmacy digitization:Indonesia and Vietnam exhibit low online pharmacy penetration relative to digital payment adoption, creating first-mover expansion potential.
- Combination therapy formats:Loperamide-simethicone fixed-dose combinations address multi-symptom traveler diarrhea, opening travel medicine and military procurement channels.
- Continuous manufacturing adoption:FDA's emerging guidance on real-time release testing enables batch-size flexibility and reduced quality control hold times.
Industry Challenges
- Process analytical technology integration:Transitioning from end-point testing to in-line spectroscopic monitoring demands capital investment and specialized pharmaceutical engineering talent.
- Reference product variability:Sourcing consistent innovator batches for bioequivalence studies grows complicated as originator manufacturers reformulate or discontinue legacy presentations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Loperamide Hcl Market |
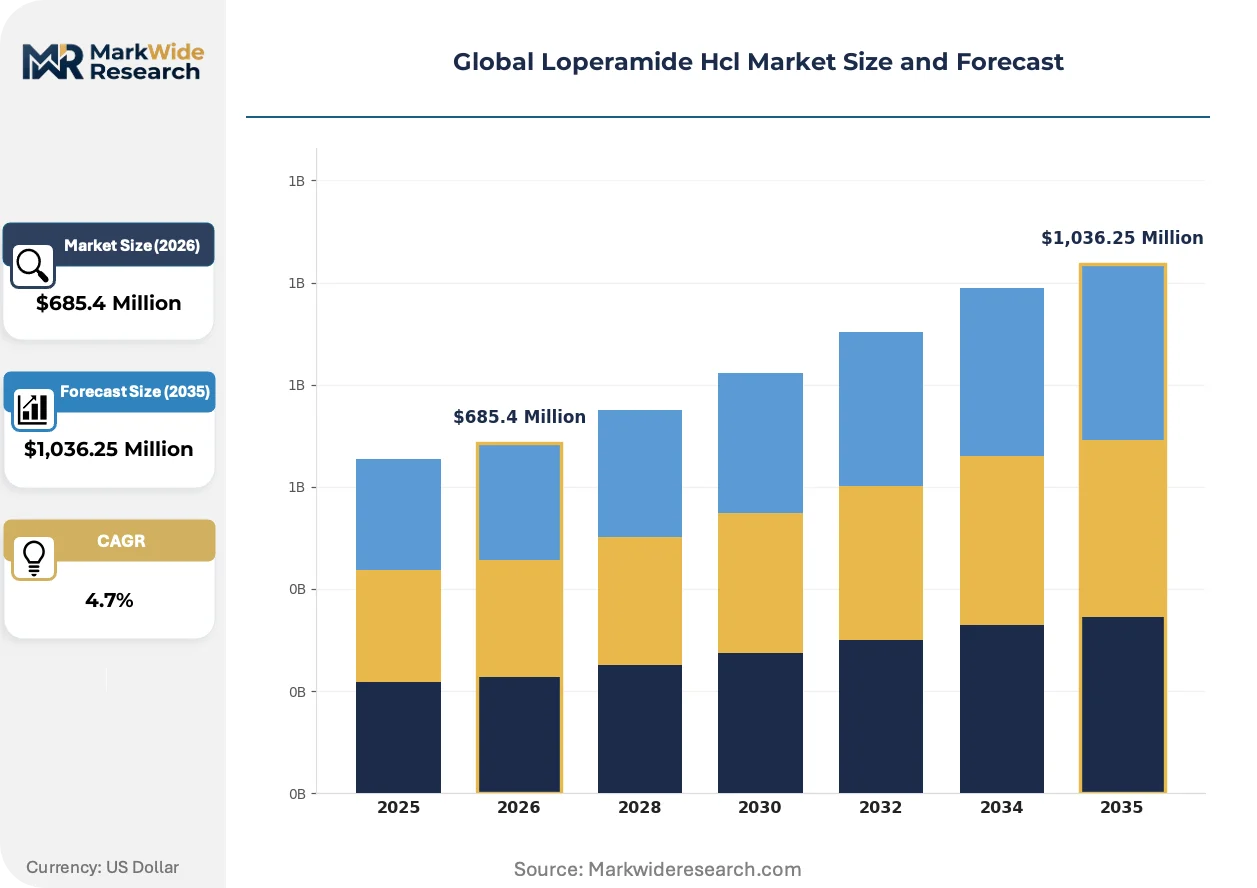
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,036.25 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablet, Capsule, Oral Suspension, Chewable Tablet, Gel Therapy Area: Diarrhea Relief, Irritable Bowel Syndrome, Traveler’s Diarrhea, Acute Enteritis, Chronic Diarrhea End User: Pharmacies, Hospitals, Clinics, Specialty Treatment Centers Distribution Channel: Retail Pharmacies, Online Pharmacies, Hospital Pharmacies, Drug Wholesalers |
| Companies Covered | Johnson & Johnson, Teva Pharmaceutical Industries Ltd., Perrigo Company plc, Sun Pharmaceutical Industries Ltd., GlaxoSmithKline plc, Pfizer Inc., Sanofi S.A., Aurobindo Pharma Ltd., Cipla Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Loperamide Hcl Market Shifts & Advancements
Digital health infrastructure and regulatory science advances are compressing development timelines while reshaping how loperamide products reach patients. Three interconnected developments define this transition.
Orally disintegrating tablet technology is converging with consumer demand for discreet, no-water dosing. Travelers and shift workers adopt these formats at accelerating rates. The convergence is compressing differentiation timelines for standard immediate-release tablets and forcing line-extension investments.
FDA's evolving stance on real-world evidence for post-market surveillance is tightening pharmacovigilance obligations for antidiarrheal products. Manufacturers must now integrate spontaneous reporting databases with electronic health record mining. Self-medication segments face the steepest compliance cost escalation as they lack prescriber intermediaries to filter adverse event signals.
Subscription-based replenishment models are displacing episodic pharmacy purchases among chronic diarrhea patients. Direct-to-consumer platforms capture recurring revenue while bypassing wholesale and retail margin stacking. Germany and the United States exhibit the highest subscription penetration, driven by insurance-integrated digital pharmacy networks and high-deductible health plan cost consciousness respectively.
Global Loperamide Hcl Market Segmentation
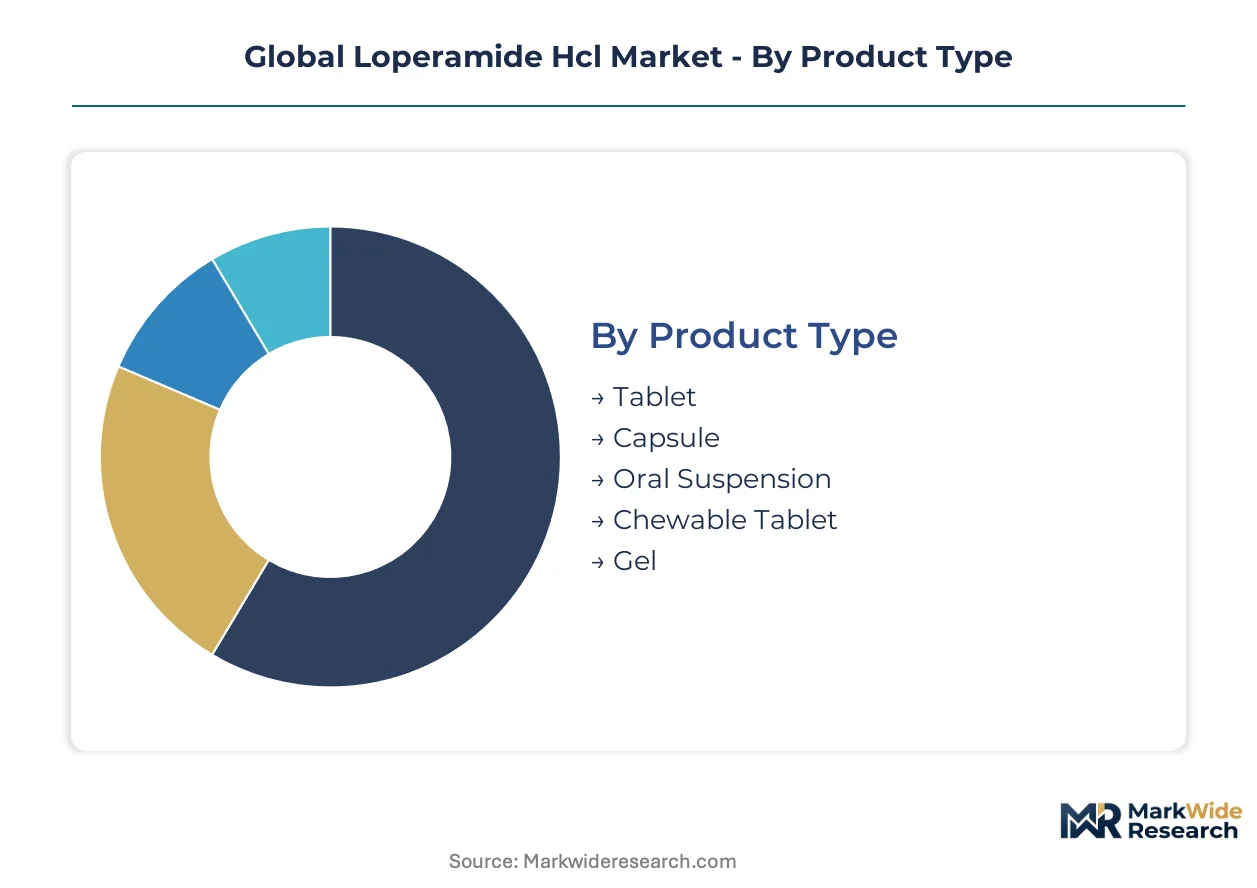
Segmentation in loperamide hydrochloride reveals how formulation choices, clinical settings, and procurement pathways fragment addressable demand. Manufacturers must align production capacity across dosage forms while navigating divergent regulatory requirements for prescription and over-the-counter positioning.
Product Type:
Volume concentration favors established solid oral formats, while premium positioning attaches to patient-convenience innovations that command shelf price premiums.
- Tablet:Standard 2 mg immediate-release tablets dominate manufacturing throughput due to established compression equipment and universal bioequivalence reference standards. Demand concentrates in the United States and Germany where retail pharmacy networks maintain extensive over-the-counter shelf space. FDA bioequivalence requirements for abbreviated new drug applications perpetuate tablet dominance among generic entrants.
- Oral Suspension:Liquid formulations address pediatric and geriatric populations with documented swallowing difficulties, expanding addressable demographics beyond standard tablet users. India's CDSCO export pathway positions Indian manufacturers as preferred suppliers of suspension APIs to regulated markets requiring pediatric dossiers. The format captures premium pricing in hospital discharge settings where caregiver compliance is prioritized.
- Capsule:Gelatin shell encapsulation offers taste masking and moisture protection for loperamide's hygroscopic properties.
- Chewable Tablet:Orally disintegrating formats target traveler and shift-worker convenience segments demanding no-water dosing.
- Gel:Semi-solid presentations remain niche, limited to compounding pharmacy channels and specialized pediatric formulations.
Mature deployment sits with Tablet formats. Newer deployment is concentrated in Oral Suspension and Chewable Tablet segments.
Therapy Area:
Application differentiation separates acute symptomatic relief from chronic condition management, with reimbursement pathways and prescription requirements determining commercial viability.
- Diarrhea Relief:Acute symptomatic treatment represents the foundational indication driving over-the-counter volume, with self-medication protocols established across major pharmacy markets. The United States maintains the highest per-capita consumption through retail pharmacy networks and insurance-integrated digital pharmacy platforms. EMA bioequivalence harmonization enables rapid generic substitution across EU member states.
- Irritable Bowel Syndrome:Chronic condition management requires physician diagnosis and often prescription-only status, attaching higher margins but lower volume throughput. Germany's statutory health insurance system reimburses loperamide for IBS-D subtype under specific diagnostic codes, creating a stable reimbursed demand pool distinct from episodic over-the-counter purchases.
- Traveler's Diarrhea:Prophylactic and treatment use in travel medicine channels commands premium pricing through airport pharmacies and travel clinic networks.
- Acute Enteritis:Infectious diarrhea management in hospital settings requires combination therapy protocols with antimicrobial agents.
- Chronic Diarrhea:Long-term management in oncology and HIV populations attaches to specialty pharmacy distribution with prior authorization requirements.
Volume leadership rests with Diarrhea Relief. Value expansion is climbing the fastest in Irritable Bowel Syndrome and Chronic Diarrhea segments.
End User:
Customer type stratification reflects the split between self-directed procurement and clinically supervised administration, with inventory management requirements diverging sharply.
- Pharmacies:Community and retail pharmacy networks handle the majority of over-the-counter transactions, with inventory turnover rates determining generic substitution patterns. The United States exhibits the highest pharmacy channel concentration through national chains and independent operators. Germany's pharmacy ownership restrictions create regional density variations that shape wholesale distribution logistics.
- Hospitals:Inpatient and emergency department utilization concentrates in acute enteritis and post-operative ileus protocols, with formulary committees determining preferred presentations. India's hospital sector expansion drives demand for unit-dose packaging and cold chain-compliant suspensions.
- Clinics:Outpatient medical offices handle prescription transitions from acute to chronic management.
- Specialty Treatment Centers:Gastroenterology and infectious disease centers manage complex chronic diarrhea cases with compounded or off-label protocols.
Established procurement sits with Pharmacies. Emerging procurement is concentrating in Specialty Treatment Centers.
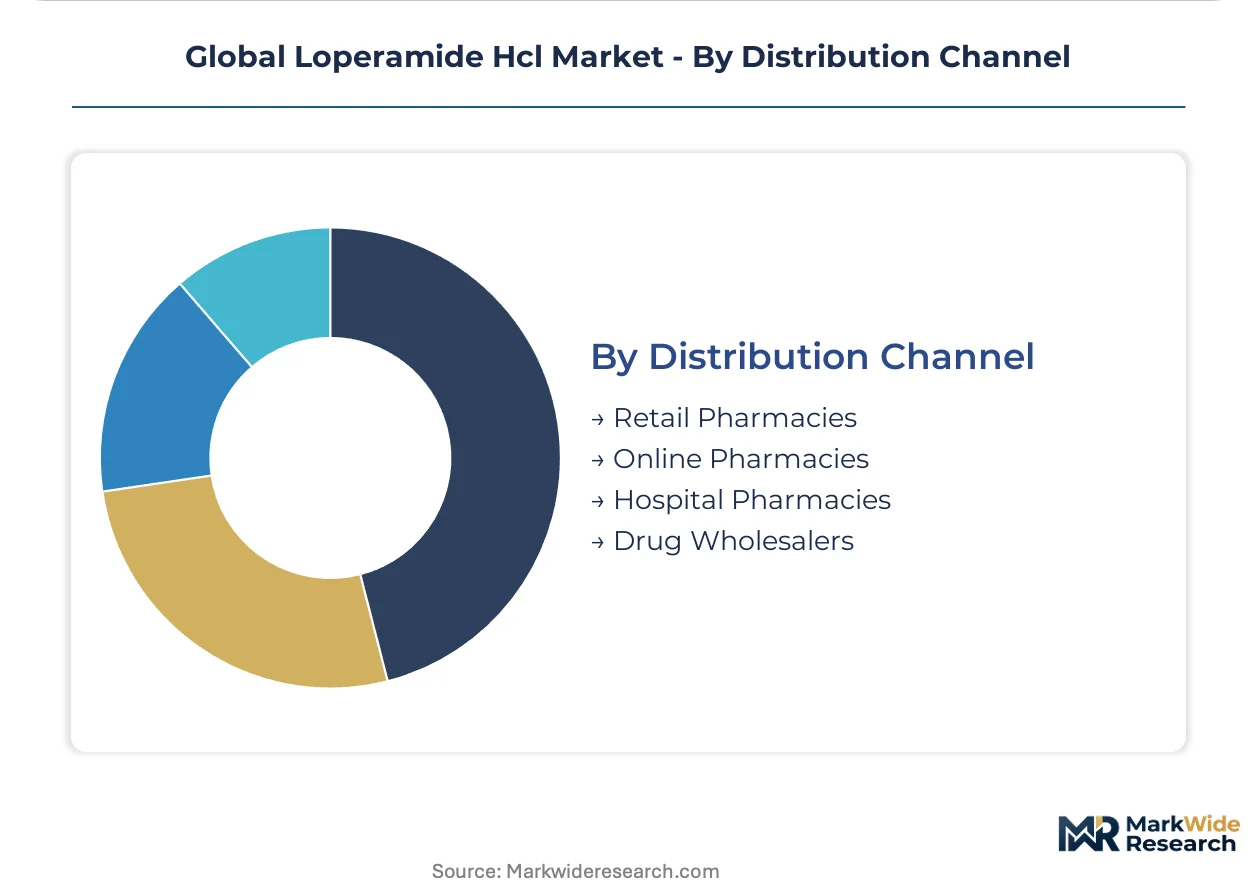
Distribution Channel:
Channel evolution tracks the displacement of physical intermediation by direct-to-patient digital platforms, with margin stacking and inventory risk redistribution as primary consequences.
- Online Pharmacies:Digital prescription workflows and direct-to-patient shipping are gaining share fastest, compressing traditional wholesale and retail margin structures. Germany's insurance-integrated digital pharmacy networks and United States high-deductible health plan cost consciousness drive subscription-based replenishment models. FDA enforcement discretion on telehealth prescribing has expanded eligible patient populations.
- Retail Pharmacies:Brick-and-mortar networks retain impulse purchase and immediate-need segments where same-day access outweighs price sensitivity. Shelf presence negotiations with national chains determine generic manufacturer market access in the United States.
- Hospital Pharmacies:Centralized purchasing through group purchasing organizations concentrates volume and standardizes presentations.
- Drug Wholesalers:Three-tier distribution remains essential for inventory financing and geographic reach in fragmented markets.
Traditional volume flows through Drug Wholesalers to Retail Pharmacies. Digital migration is accelerating most quickly in Online Pharmacies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's pharmaceutical special economic zones in Hyderabad and Ahmedabad concentrate bulk active pharmaceutical ingredient manufacturing for export-oriented loperamide production. FDA and EMA bioequivalence standards shape facility investment decisions across these zones.
United States
Retail pharmacy networks drive over-the-counter volume through national chains and insurance-integrated digital platforms. FDA bioequivalence requirements for abbreviated new drug applications perpetuate tablet dominance among generic entrants. New Jersey and Pennsylvania host formulation facilities serving domestic distribution.
Germany
Statutory health insurance reimbursement for irritable bowel syndrome-D subtype creates stable prescribed demand distinct from episodic purchases. EMA centralized marketing authorization procedures enable rapid generic substitution across EU member states. The Rhine-Ruhr corridor anchors wholesale distribution logistics.
India
CDSCO streamlined stability and impurity profiling mandates position Indian manufacturers as preferred API suppliers to regulated markets. Export-oriented production concentrates in Hyderabad's pharmaceutical special economic zone and Ahmedabad's chemical manufacturing belt. These clusters supply formulation facilities in North America and Europe.
China
NMPA local stability requirements and dual carbon goals reshape manufacturing investment priorities for domestic and export markets. The Yangtze River Delta hosts chemical intermediates production feeding global loperamide supply chains. Environmental compliance upgrades are accelerating facility consolidation.
United Kingdom
Post-Brexit MHRA regulatory autonomy has diverged from EMA procedures, creating separate dossier submission requirements for market access. London and Southeast England concentrate digital pharmacy platform headquarters serving subscription-based replenishment models. These platforms bypass traditional wholesale margin structures.
Global Loperamide Hcl Market Competitive Landscape
Top-tier vendors anchor branded over-the-counter positioning, while mid-tier generic manufacturers compete on bioequivalence dossier breadth and manufacturing scale. The vendor base stratifies across three functional tiers: multinational consumer health conglomerates with retail shelf dominance, generic specialists with regulatory dossier depth, and private-label contractors serving pharmacy chain store brands. Dominant competitive moves include portfolio diversification into convenience-oriented dosage forms and backward integration into active pharmaceutical ingredient supply.
Within the multinational consumer health tier, Johnson & Johnson and GlaxoSmithKline occupy positions defined by retail pharmacy network access and brand recognition. Teva Pharmaceutical Industries Ltd. exemplifies the generic specialist archetype through manufacturing scale and broad regulatory filings. Perrigo Company plc represents the private-label contractor model, competing on price positioning at major pharmacy chains.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Teva Pharmaceutical Industries Ltd. |
| Perrigo Company plc |
| Sun Pharmaceutical Industries Ltd. |
| GlaxoSmithKline plc |
| Pfizer Inc. |
| Sanofi S.A. |
| Aurobindo Pharma Ltd. |
| Cipla Inc. |
| Others |
Supply & Pricing Matrix
China's dual carbon goals and NMPA environmental compliance mandates gate qualified active pharmaceutical ingredient supply for loperamide hydrochloride, restricting premium-tier pricing access to manufacturers with upgraded facilities. Buyers in regulated markets now demand carbon-footprint documentation alongside traditional quality certifications, bifurcating supply into sustainability-verified and legacy tiers with corresponding price premiums.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent procurement from scheduled orders across loperamide hydrochloride supply contracts. Three-tier pricing structure across premium, standard, and economy levels reflects FDA bioequivalence certification status, batch-specific impurity profiles, and geographic delivery requirements. Cost compression in economy-tier tablet formulations is intensifying because Indian and Chinese API suppliers compete on volume scale. Hospital group purchasing organizations exhibit the sharpest price sensitivity, while specialty treatment centers prioritize supply security over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from FDA and EMA-regulated buyers mandate multi-supplier qualification for loperamide API, forcing formulation facilities to validate parallel Indian and Chinese chemical manufacturers. Bulk production concentrates in Hyderabad's pharmaceutical special economic zone, Ahmedabad's chemical belt, and the Yangtze River Delta intermediates corridor. Feedstock dependencies include 4-piperidone hydrochloride, N,N-dimethylaniline, and chloroacetyl chloride. Single-source vulnerability persists for high-purity grades meeting pediatric suspension standards. Distribution runs through three-tier wholesale networks to retail pharmacies, with direct-to-patient digital channels eroding traditional margin stacking.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where EMA-FDA regulatory harmonization pressures subscale generic manufacturers lacking bioequivalence dossier breadth to exit. Surviving players will capture volume from displaced competitors.
For Market Incumbents: Anticipate opioid-scheduling reclassification discussions by diversifying formulation portfolios toward combination therapies with simethicone. Backward integration into API supply through captive production in Hyderabad's special economic zones reduces single-source exposure. Prioritize continuous manufacturing investments that compress quality control hold times below batch-process competitors.
For New Entrants and Emerging Players: Begin with Indonesia and Vietnam's underpenetrated online pharmacy segments where digital payment infrastructure outpaces pharmaceutical platform development. Target chewable tablet and orally disintegrating formats for traveler convenience segments underserved by incumbent tablet dominance. Establish direct-to-patient subscription models bypassing wholesale margin extraction.
For Investors and Strategic Acquirers: EMA centralized marketing authorization withdrawals for subscale sponsors is the leading indicator that mid-tier generic manufacturers face forced divestiture. The five-to-ten year viability window favors acquisition targets with validated pediatric suspension dossiers and established CDSCO export pathways. Monitor FDA enforcement discretion shifts on telehealth prescribing as the signal for direct-to-consumer channel expansion viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Dossier Expansion | Broad EMA centralized marketing authorization coverage accelerates EU member state substitution. |
| Pediatric Formulation Development | Oral suspension dossiers unlock hospital discharge and geriatric caregiver compliance premiums. |
| Continuous Manufacturing Adoption | FDA real-time release testing guidance enables batch-size flexibility and reduced inventory holding. |
| Direct-to-Patient Channel Buildout | Subscription replenishment models capture recurring revenue from chronic diarrhea patient populations. |
| API Supply Integration | Captive production in Indian pharmaceutical special economic zones mitigates concentration risk. |
Research Methodology
Document review covered FDA abbreviated new drug application filings, EMA centralized marketing authorization procedures, and CDSCO export pathway guidelines, complemented by interviews with generic manufacturing executives, regulatory affairs directors at formulation facilities, hospital formulary committee members, and online pharmacy platform operators. Secondary validation drew from pharmaceutical trade customs data, SEC 10-K disclosures of listed manufacturers, and WHO prequalification program records. Bottom-up volume modeling triangulated against top-down market sizing from national pharmacy sales audits.
Cross-referencing historical volume trends against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include dosage form, therapy area indication, end-user facility type, and distribution channel regulatory cluster. Compound annual growth rate derivation incorporated pricing elasticity assumptions for over-the-counter versus prescription-only status scenarios, alongside pediatric formulation penetration curves.
Underlying measurement precision varies by segment; tablet and oral suspension volume estimates carry tighter precision than gel and compounding pharmacy niche formats. Forecasts reflect assumptions around opioid-scheduling status maintenance, API supply continuity from Indian and Chinese manufacturing zones, and digital pharmacy regulatory enforcement postures. A model refresh is warranted upon material change in EMA bioequivalence guidance or FDA telehealth prescribing discretion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Local Anesthesia Drugs Market
Pharmaceuticals
Novel Drug Delivery Systems in Cancer Therapy Market
Pharmaceuticals
Anti-Obesity Drugs Market
Pharmaceuticals
Next-Generation Immunology Drugs Market
Pharmaceuticals
Sterile Dosage Form Market
Pharmaceuticals
Collagenase Clostridium Histolyticum Market
Pharmaceuticals
Global Controlled Release Drug Delivery Market
Pharmaceuticals
Europe Pharmaceutical Warehousing Market
Pharmaceuticals
Anticholinergic Drugs Market
Pharmaceuticals
Thin Film Drug Manufacturing Market
Pharmaceuticals
Asia-Pacific Contraceptives Market
Pharmaceuticals
Cancer Therapeutics and Biotherapeutics Market
Pharmaceuticals
2-Valent HPV Vaccine (2vHPV) Market
Pharmaceuticals
Europe Pharmaceutical Market
Pharmaceuticals
Antiretroviral (ARV) Agents Market
Pharmaceuticals
GLP-1 Receptor Agonist Market