
 Smart Motors Market | 2026-2036
Smart Motors Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Motors Market Intelligence
Predictive maintenance software licensing is fragmenting away from bundled hardware sales into standalone subscription models. Siemens AG leverages its extensive industrial software portfolio to capture this emerging value stream. Rockwell Automation competes by integrating advanced analytics directly into its motor control platforms for factory automation. In contrast, Nidec Corporation specializes in high-efficiency motor components designed for original equipment manufacturers in the smart appliance sector.
A smart motor integrates a motor, drive, and control electronics, often including an embedded microcontroller, into a single cohesive unit. Its primary function is to provide precise, programmable motion control while offering real-time diagnostics and network connectivity for automated systems. Brushless DC Motors lead in adoption due to their superior efficiency and longevity in continuous operation scenarios. Demand from Manufacturing Units for solutions featuring Predictive Maintenance technology is accelerating, driven by the critical need to minimize operational downtime.
Energy efficiency mandates, such as the EU's Ecodesign Directive and China's GB standards for motor performance, are shaping product development cycles. In the United States, standards promoted by the EPA influence procurement choices, particularly in large-scale HVAC systems and industrial applications. Vendor selection will increasingly depend on the sophistication of their integrated software platforms and ability to support open communication protocols for seamless system integration.
Market Dynamics
The convergence of operational technology and information technology is the central force defining the smart motors market. This integration, driven by demand for AI-powered predictive maintenance, transforms motors from simple hardware components into data-generating nodes within automated industrial ecosystems.
Growth Catalysts
- Industrial Automation Clusters:Demand for precision and reliability in advanced manufacturing clusters in Germany and specialized robotics sectors in Japan accelerates the adoption of integrated smart motor systems for complex motion control tasks.
- Energy Efficiency Mandates:Regulations including the EU's Ecodesign Directive and China's GB standards for motor performance are compelling industrial users to replace legacy systems with higher-efficiency smart motors to meet compliance targets.
- Predictive Maintenance Technology:The critical need to reduce operational downtime in continuous-process industries, such as automotive assembly and packaging, drives investment in smart motors featuring embedded diagnostic and predictive capabilities.
Market Restraints
- Higher Initial Investment:The upfront capital cost of a smart motor, which combines the motor, drive, and controller, is significantly greater than purchasing these components separately, posing a barrier for cost-sensitive end-users.
- Integration with Legacy Systems:A lack of standardized communication protocols across all vendors creates complexity and cost when integrating new smart motors into existing factory automation infrastructure running on proprietary networks.
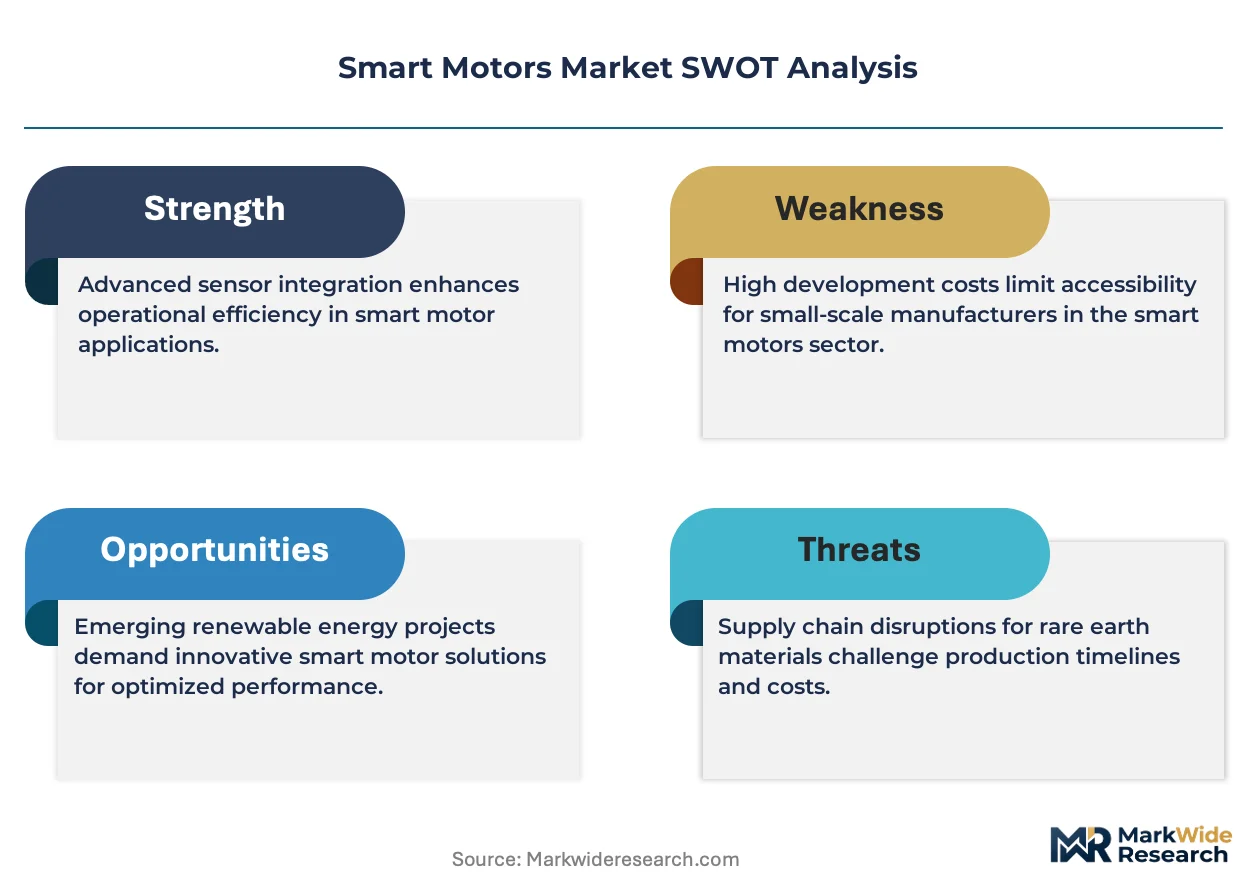
- Specialized Component Dependency:The supply chain relies on a concentrated base of suppliers for critical power electronics and microcontrollers, creating vulnerability to geopolitical trade friction and component shortages that can delay production.
Strategic Opportunities
- Standalone Software Licensing:The unbundling of predictive maintenance software from hardware into subscription-based models creates a new, recurring value stream for vendors with strong analytics and cloud platform capabilities.
- Open Communication Standards:Developing products that support open, interoperable protocols like OPC UA or MQTT allows vendors to penetrate accounts with multi-vendor automation environments, reducing a key barrier to adoption for customers.
- HVAC System Modernization:Energy standards promoted by the EPA in the United States create an opportunity to replace inefficient motors in large-scale commercial HVAC systems with smart motors offering superior control and efficiency.
Industry Challenges
- Technical Skill Gaps:A shortage of technicians and control engineers with the hybrid expertise needed to program, integrate, and maintain networked electromechanical systems constrains the pace of deployment in many industrial facilities.
- Cybersecurity Vulnerabilities:As smart motors become connected nodes on industrial networks, they introduce new attack surfaces, requiring vendors and operators to implement robust security measures to protect against operational disruptions and data breaches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Motors Market |
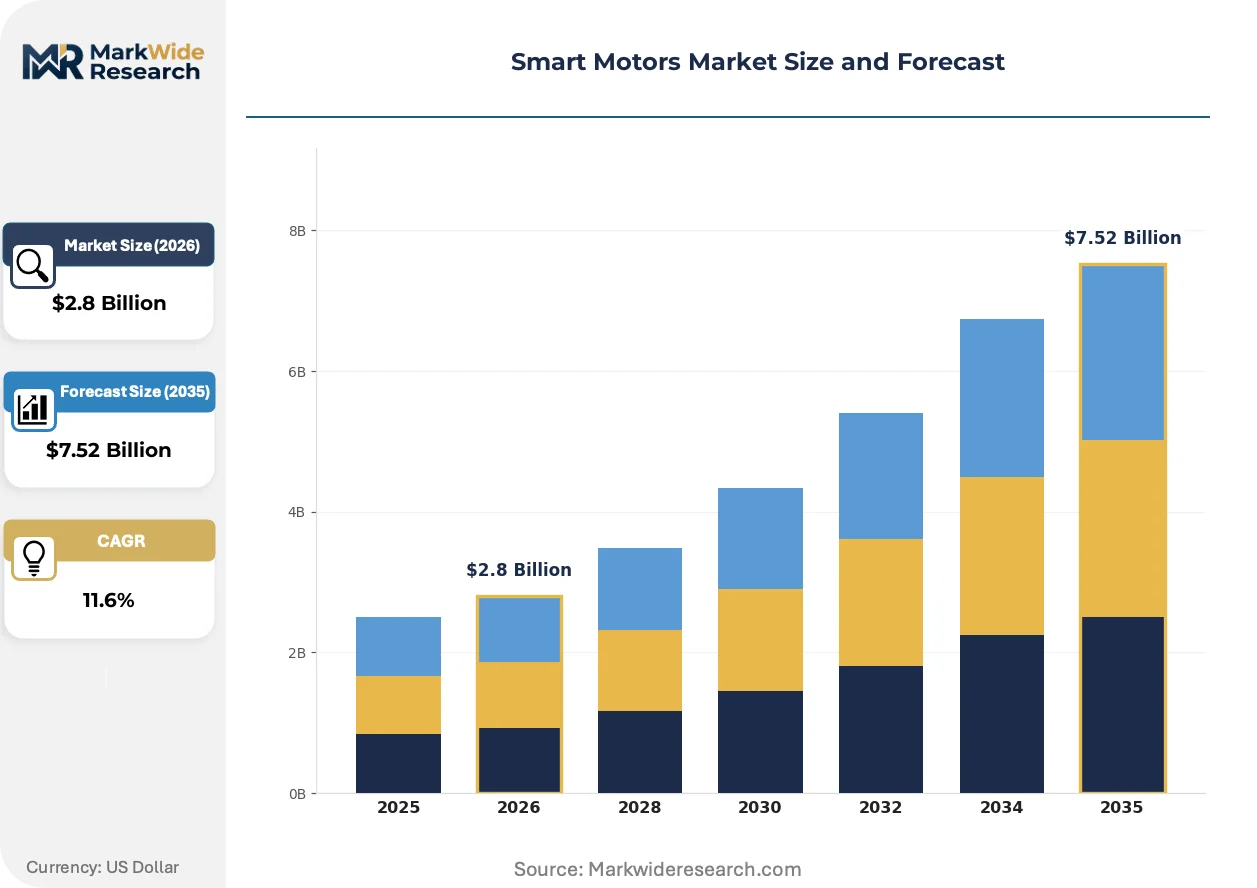
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.52 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brushless DC Motors, Synchronous Motors, Stepper Motors, Servo Motors, AC Induction Motors Technology: IoT Enabled, Sensor Integrated, AI-Based Control, Remote Monitoring, Predictive Maintenance Application: Robotics, HVAC Systems, Automated Manufacturing, Smart Appliances, Renewable Energy Systems End User: Manufacturing Units, Building Automation Companies, Energy Producers, Consumer Electronics Firms, Aerospace Agencies |
| Companies Covered | ABB Ltd, Nidec Corporation, Rockwell Automation, Schneider Electric, General Electric, Fuji Electric Co., Ltd., Siemens AG, Moog, Inc., Dunkermotoren GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Motors Market Strategic Shifts & Innovations
Value creation is shifting from electromechanical hardware performance to software-defined capabilities and data analytics. This transition transforms the competitive landscape, favoring vendors who can deliver not just motion control but also actionable operational intelligence through integrated platforms and services.
Digital twin technology creates a virtual, real-time replica of a physical smart motor and its operating environment. Industrial operators in aerospace and automotive manufacturing are adopting this for system simulation and failure prediction. This technology is virtualizing significant parts of the commissioning and maintenance lifecycle, enabling remote diagnostics and offline programming which reduces on-site engineering requirements.
The EU's Ecodesign Directive for electric motors establishes progressively stricter minimum energy performance standards. This regulation forces the phase-out of less efficient motor classes across the industrial base. The industrial pump, fan, and compressor segments are most affected, which quickens the replacement cycle and favors the adoption of integrated smart motor solutions that inherently exceed these new efficiency thresholds.
A clear behavioral change is the move from one-time capital purchases to subscription-based access for advanced software features. This unbundling of analytics software from the core motor hardware disrupts the traditional sales model, creating recurring revenue opportunities for suppliers. This pattern is most visible within sophisticated manufacturing operations in Germany and Japan, where operators prioritize opex-based models for specialized software.
Smart Motors Market Segmentation
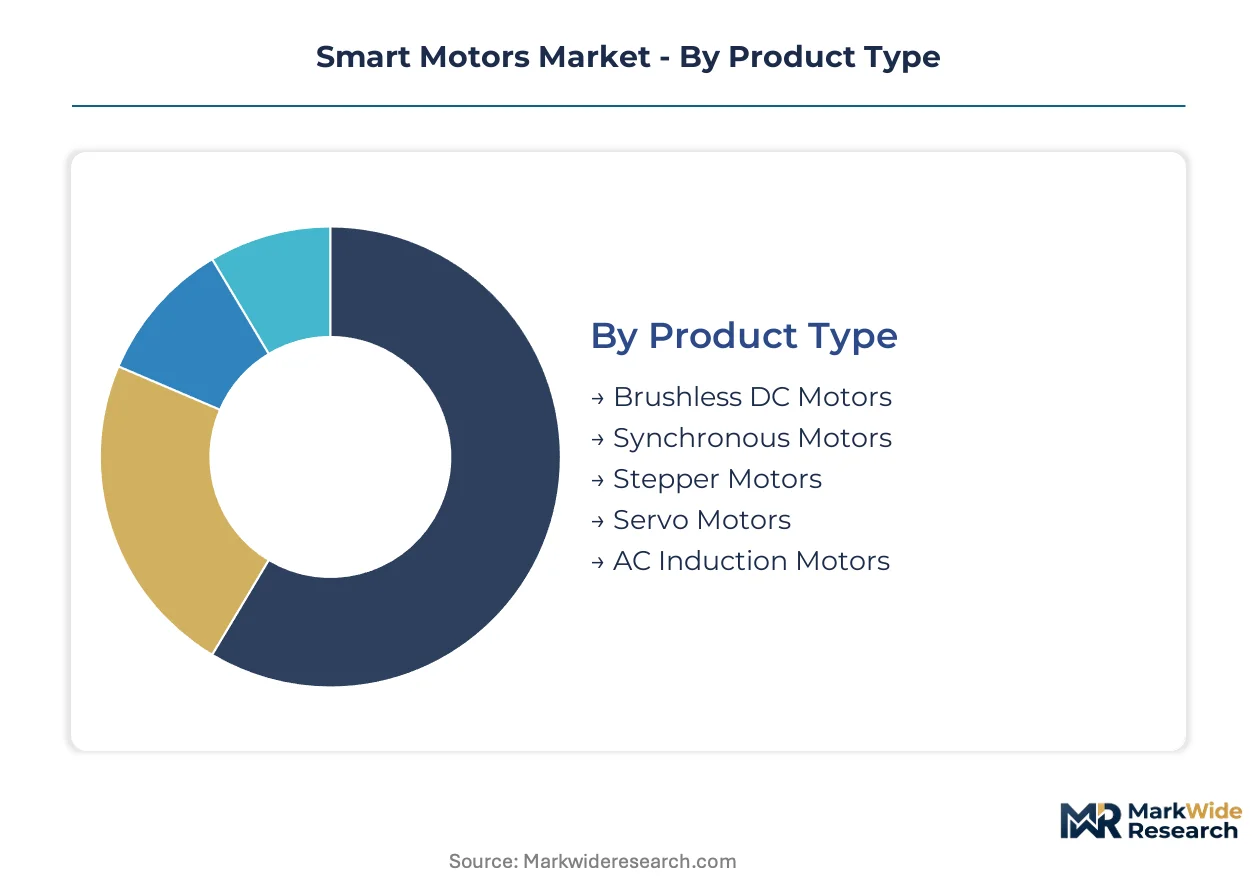
The Smart Motors Market segmentation reveals distinct value propositions and operational advantages across various product types, embedded technologies, applications, and end-user industries. Understanding these segments is crucial for identifying areas of concentrated demand and emerging growth trajectories.
Product Type:
Product type delineation focuses on the inherent operational characteristics and drive mechanisms of smart motors.
- Brushless DC Motors:These motors offer superior efficiency, compact size, and long operational life due to the absence of brushes, making them ideal for continuous operation. Demand concentrates in robotics and precision automation in Germany, driven by stringent performance requirements.
- Servo Motors:Known for their precise control over angular position, velocity, and acceleration, servo motors are essential for dynamic motion control. Specialized robotics sectors in Japan utilize these motors extensively for complex, high-accuracy assembly tasks.
- Synchronous Motors:These motors operate at a constant speed, synchronized with the frequency of the supply current, offering high efficiency in steady-state applications.
- Stepper Motors:Stepper motors provide precise, incremental motion control without feedback, suitable for applications requiring exact positioning.
- AC Induction Motors:Widely used for their robustness and lower cost, these motors are being upgraded with smart features for enhanced control and energy management.
AC Induction Motors command the established base. The steepest expansion runs through Brushless DC Motors.
Technology:
The technological backbone of smart motor systems differentiates offerings based on embedded functionalities and connectivity.
- Predictive Maintenance:This technology integrates sensors and analytics to forecast equipment failures, enabling proactive maintenance and minimizing unscheduled downtime. Manufacturing units in the automotive sector prioritize these capabilities to ensure continuous production lines.
- AI-Based Control:Leveraging artificial intelligence algorithms, these systems optimize motor performance, adapt to varying load conditions, and enhance energy efficiency. Advanced manufacturing clusters in Germany implement AI-based control for complex process optimization.
- IoT Enabled:Smart motors with IoT capabilities connect to broader industrial networks, facilitating data exchange and remote management.
- Sensor Integrated:Embedded sensors provide real-time data on temperature, vibration, and current, crucial for diagnostics and performance monitoring.
- Remote Monitoring:This feature allows operators to supervise motor status and performance from distant locations, improving operational flexibility.
Predictive Maintenance technology drives new value streams. IoT Enabled solutions broaden connectivity across industrial ecosystems.
Application:
Application segments highlight where smart motor capabilities deliver specific operational advantages and efficiency gains.
- Automated Manufacturing:Smart motors provide the precise motion control and diagnostic feedback necessary for high-speed, high-volume production lines. This segment in China leverages smart motors for increased throughput and reduced operational errors.
- HVAC Systems:Integrated smart motors optimize fan and pump operation in large commercial buildings, significantly reducing energy consumption and operational costs. EPA standards in the United States influence procurement choices for these efficiency-driven upgrades.
- Robotics:Smart motors are fundamental components in robotic arms and mobile platforms, enabling fluid and accurate movements.
- Smart Appliances:These motors enhance the efficiency and functionality of household appliances, contributing to energy savings and user convenience.
- Renewable Energy Systems:Smart motors are used in tracking systems for solar panels and pitch control for wind turbines, optimizing energy capture.
Automated Manufacturing represents the largest end-use. HVAC Systems show significant efficiency-driven replacement demand.
End User:
End-user categories reflect distinct procurement behaviors and operational priorities for smart motor adoption.
- Manufacturing Units:These facilities adopt smart motors to enhance production efficiency, reduce downtime, and integrate seamlessly into existing automation infrastructure. Demand from automotive assembly plants in Europe is particularly strong.
- Building Automation Companies:These firms integrate smart motors into intelligent building management systems to optimize energy usage and improve occupant comfort. Commercial infrastructure projects in the United States increasingly specify smart motor solutions.
- Energy Producers:Companies in power generation and distribution utilize smart motors for auxiliary equipment and control systems.
- Consumer Electronics Firms:These companies incorporate smart motors into various electronic devices for improved functionality and energy performance.
- Aerospace Agencies:Smart motors are used in specialized applications within aerospace for precision control and reliability in critical systems.
Manufacturing Units remain the primary customer base. Building Automation Companies are rapidly integrating smart motor solutions for energy management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for smart motors exhibits varied price elasticity across regions. Cost-sensitive markets prioritize initial investment over long-term operational savings. Conversely, advanced manufacturing hubs in Germany and Japan readily adopt premium solutions for their precision and reliability benefits.
Germany
German manufacturing units drive demand for integrated smart motor systems, particularly for complex motion control tasks. The EU's Ecodesign Directive compels industrial users to replace legacy systems with higher-efficiency smart motors. Advanced manufacturing clusters in Bavaria integrate AI-based control for complex process optimization, minimizing operational downtime.
Japan
Japanese specialized robotics sectors utilize servo motors extensively for complex, high-accuracy assembly tasks. JIS standards for industrial machinery influence product development cycles, emphasizing efficiency and performance. Robotics innovation centers in Tokyo and Osaka accelerate the adoption of integrated smart motor solutions for advanced automation.
United States
United States procurement choices are influenced by EPA standards, particularly in large-scale HVAC systems. Demand for efficiency-driven upgrades in commercial infrastructure projects is significant. Building automation companies in the Northeast are rapidly integrating smart motor solutions for energy management and improved occupant comfort.
China
Chinese automated manufacturing leverages smart motors for increased throughput and reduced operational errors in high-speed production lines. GB standards for motor performance are shaping product development cycles, driving the adoption of higher-efficiency solutions. Manufacturing units in the Yangtze River Delta prioritize predictive maintenance technology to ensure continuous production.
Smart Motors Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another within the smart motors market. The market structure exhibits a tiered consolidation, with large industrial conglomerates competing alongside specialized component manufacturers. Key strategic archetypes include integrated solution providers, high-efficiency component specialists, and software-centric analytics firms. Dominant competitive moves involve strategic partnerships for software integration and portfolio diversification into recurring revenue streams.
Global industrial technology providers anchor the premium segment. Siemens AG, a German industrial conglomerate, exemplifies the integrated software and hardware approach, leveraging its extensive portfolio for predictive maintenance. United States-based Rockwell Automation occupies a position by integrating advanced analytics into its motor control platforms for factory automation. Japan's Nidec Corporation represents a specialized component manufacturer, focusing on high-efficiency motor components for original equipment manufacturers.
| Leading Market Players |
|---|
| ABB Ltd |
| Nidec Corporation |
| Rockwell Automation |
| Schneider Electric |
| General Electric |
| Fuji Electric Co., Ltd. |
| Siemens AG |
| Moog, Inc. |
| Dunkermotoren GmbH |
| Others |
Cost & Logistics Intelligence
Specialized component dependency on power electronics and microcontrollers creates vulnerability to geopolitical trade friction, influencing both pricing tier spreads and the concentrated supply chain shape for smart motors.
Pricing Analysis
Predictive maintenance software subscriptions drive significant lifetime value for smart motor vendors. This subscription-based model for analytics unbundles from traditional transactional hardware sales. Price differentiation stems from the sophistication of integrated software platforms and support for open communication protocols. Pricing softness affects basic AC Induction Motors, while advanced manufacturing hubs prioritize long-term operational savings, accepting higher initial costs.
Supply Chain Analysis
Upstream sourcing for smart motors heavily relies on specialized components like power electronics and microcontrollers. These critical inputs primarily originate from concentrated supplier bases in East Asia and Europe. Geopolitical trade friction poses a significant structural risk, leading to potential component shortages. Distribution runs through direct sales to manufacturing units and building automation companies, alongside OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart motors market offers a significant service-attach opportunity for vendors. Predictive maintenance software licensing, unbundled into subscription models, represents a recurring-revenue layer expanding faster than core hardware sales.
For Market Incumbents:
Build deep software ecosystem moats to counteract hardware commoditization and new entrant software plays. Integrated solution providers like Siemens AG must expand their industrial software portfolios and cloud capabilities. Invest in R&D for AI-based control and support open communication protocols like OPC UA to reduce customer integration barriers. This strategy defends against specialized software-centric analytics firms and addresses technical skill gaps in the market.
For New Entrants and Emerging Players:
US commercial infrastructure projects represent a significant underpenetration for energy-efficient smart motor solutions. Target specific industrial segments with legacy HVAC systems seeking efficiency upgrades driven by EPA standards. Offer specialized sensor-integrated motors with simplified integration for smaller manufacturing units. A go-to-market angle involves partnering with building automation companies to access large-scale commercial retrofit opportunities.
For Investors and Strategic Acquirers:
The market sits at an early growth phase that favors specialized software and analytics firms with strong cloud platforms. Acquisition targets should include companies offering advanced predictive maintenance algorithms or open communication protocol expertise. Focus on firms with proven integration capabilities for multi-vendor industrial environments. The signal to watch is the accelerating adoption rate of standalone software subscriptions across diverse manufacturing sectors.
| Strategic Initiative | Industry Significance |
|---|---|
| Software Platform Integration | Enhances recurring revenue streams for Siemens AG. |
| Open Protocol Development | Reduces integration complexity for Rockwell Automation customers. |
| Component Specialization | Secures Nidec Corporation's position in OEM supply. |
| Geographic Expansion | Captures demand in China's automated manufacturing sector. |
| Digital Twin Investment | Virtualizes commissioning for aerospace and automotive operators. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory documents, company annual reports, and industry association publications. The analysis involved in-depth interviews with plant managers, control engineers, procurement leads, and R&D directors across key manufacturing regions. This approach ensured comprehensive data collection and validation from both demand and supply sides. Bottom-up and top-down triangulation further refined market size and growth projections.
Forecast inputs considered include energy efficiency mandates, industrial automation investment, and technological advancements in AI-based control. The analytical framework modeled market dynamics across product type, embedded technology, application, and end-user industry segments. Compound annual growth rates were derived from historical adoption patterns and projected market penetration over the projection horizon. Regulatory compliance trends served as a critical input for segment-specific growth.
Practitioners should monitor geopolitical trade friction and component supply disruptions for early signals of market shifts. Forecasts reflect assumptions documented regarding technological adoption rates and regulatory enforcement. Cross-checking against industrial production indices and capital expenditure reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Latin America Electric Drives Market
Industrial Motors
North America Refrigeration Oil Market
Industrial Motors
HVAC Motors Market
Industrial Motors
United Kingdom AC Motors Market
Industrial Motors
United Kingdom DC Motor Market
Industrial Motors
Oil Mist Collector Market
Industrial Motors
Global Direct Current (DC) Motor Market
Industrial Motors
Global Explosion-Proof Motor Casting Market
Industrial Motors
North America Induction Motor Market
Industrial Motors
Middle East and Africa Variable Frequency Drive (VFD) Market
Industrial Motors
Global Low Voltage Motors Market
Industrial Motors
Europe Tank Insulation Market
Industrial Motors
Liquid Nitrogen Purge Systems Market
Industrial Motors
Cryogenic Air Separation Units (Asus) Market
Industrial Motors
Explosion Proof Electric Motors and Actuators Sales Market
Industrial Motors
High Voltage Motor Sleeve Bearing Market