
 Explosion Proof Electric Motors and Actuators Sales Market | 2026-2036
Explosion Proof Electric Motors and Actuators Sales Market Size, Share, and Industry Trends Forecast 2026-2036
Explosion Proof Electric Motors and Actuators Sales Market Insights
A widening capability gap between capital-heavy integrated manufacturers and component-assemblers is bifurcating competitive tiers in the explosion proof equipment sector. ABB leverages captive foundry and winding operations to control lead times for large-frame hazardous duty motors. Siemens sustains R&D intensity across synchronous and brushless platforms for chemical processing clients. WEG anchors its position through vertical manufacturing scale in South American and North American facilities.
Explosion proof electric motors and actuators are electromechanical devices engineered with encapsulated windings, flameproof enclosures rated for T1-T6 temperature classes, and sealing systems that contain internal ignition of flammable atmospheres; they serve to drive pumps, compressors, and valve actuation in zones classified by gas group and auto-ignition temperature. AC motors dominate volume in oil and gas upstream applications where induction technology meets IEC 60079-1 construction standards, while brushless actuators represent the fastest-expanding technology segment as digital position control replaces pneumatic systems in pharmaceutical batch processing. Margin pools concentrate in synchronous gear motor configurations for chemical processing, where precision speed control commands specification premiums.
ATEX directives in Europe, IECEx international certification schemes, and OSHA 29 CFR 1910.307 hazardous location standards in the United States collectively dictate enclosure design, testing protocols, and market access for explosion proof equipment manufacturers. Compliance with these overlapping frameworks requires dual-certified product architectures that extend development cycles but create defensible barriers for qualified suppliers. Stakeholders must monitor divergence between regional certification timelines when allocating engineering resources across product platforms.
Market Dynamics
Upstream oil and gas operators in the United States Gulf Coast are extending replacement cycles for flameproof motor systems, compressing demand volatility into concentrated procurement windows while IECEx and ATEX compliance thresholds tighten.
Growth Catalysts
- IECEx Certification Harmonization:International alignment of hazardous area equipment standards reduces duplicate testing costs for manufacturers serving multiple jurisdictions. Chemical processing facilities in Singapore and Rotterdam accelerate certified equipment deployment.
- Digital Valve Actuation:Brushless electric actuators replace pneumatic systems in pharmaceutical batch processing, eliminating compressed air infrastructure and enabling precise position feedback. FDA-regulated facilities drive specification intensity.
- United States Gulf Coast Petrochemical Corridor:Ethylene cracker expansions and LNG export terminal construction create sustained demand for large-frame hazardous duty motors. Project bundling favors suppliers with captive foundry capacity.
Market Restraints
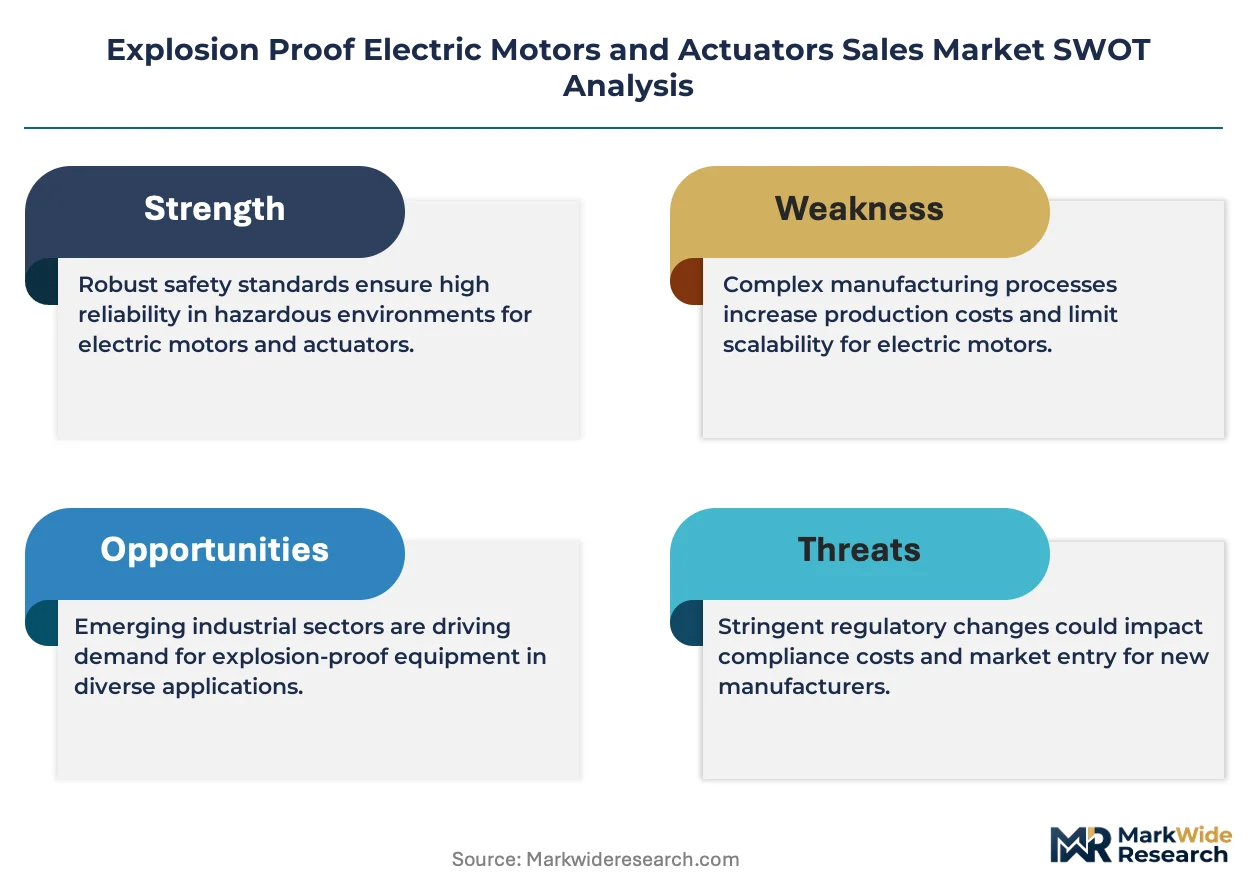
- Copper and Laminated Steel Price Volatility:Winding materials and magnetic core inputs constitute 35-40% of motor manufacturing cost structures. Foundry energy costs in Germany and China amplify margin pressure.
- Dual-Certification Development Cycles:ATEX Directive 2014/34/EU and IECEx 02 scheme divergence extends product validation timelines. Engineering resource allocation fragments across regional compliance tracks.
- Pneumatic Actuator Residual Base:Established compressed air infrastructure in legacy chemical plants creates switching friction. Retrofit economics favor partial electrification over full replacement.
Strategic Opportunities
- Indian Pharmaceutical Manufacturing:CDSCO-regulated active pharmaceutical ingredient facilities under PLI scheme incentives require explosion-proof automation. Domestic motor assembly partnerships reduce import duty exposure.
- Synchronous Gear Motor Precision Control:Integration of permanent magnet synchronous motors with intelligent drives enables variable speed operation in polymer extrusion. Specification premiums concentrate in specialty chemical segments.
- Direct Distribution to EPC Contractors:Engineering-procurement-construction firms in Middle Eastern petrochemical projects consolidate vendor lists. Bypassing traditional distribution captures margin and reduces lead time uncertainty.
Industry Challenges
- IEC 60079-1 Flameproof Enclosure Testing Bottlenecks:Certified test laboratory capacity constraints in Europe and North America extend time-to-market for new product introductions. Queue management becomes a competitive differentiator.
- Hazardous Area Installation Skill Scarcity:Competent person certification for Ex equipment installation and maintenance lags demand growth in emerging manufacturing clusters. Training infrastructure requires capital commitment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Explosion Proof Electric Motors and Actuators Sales Market |
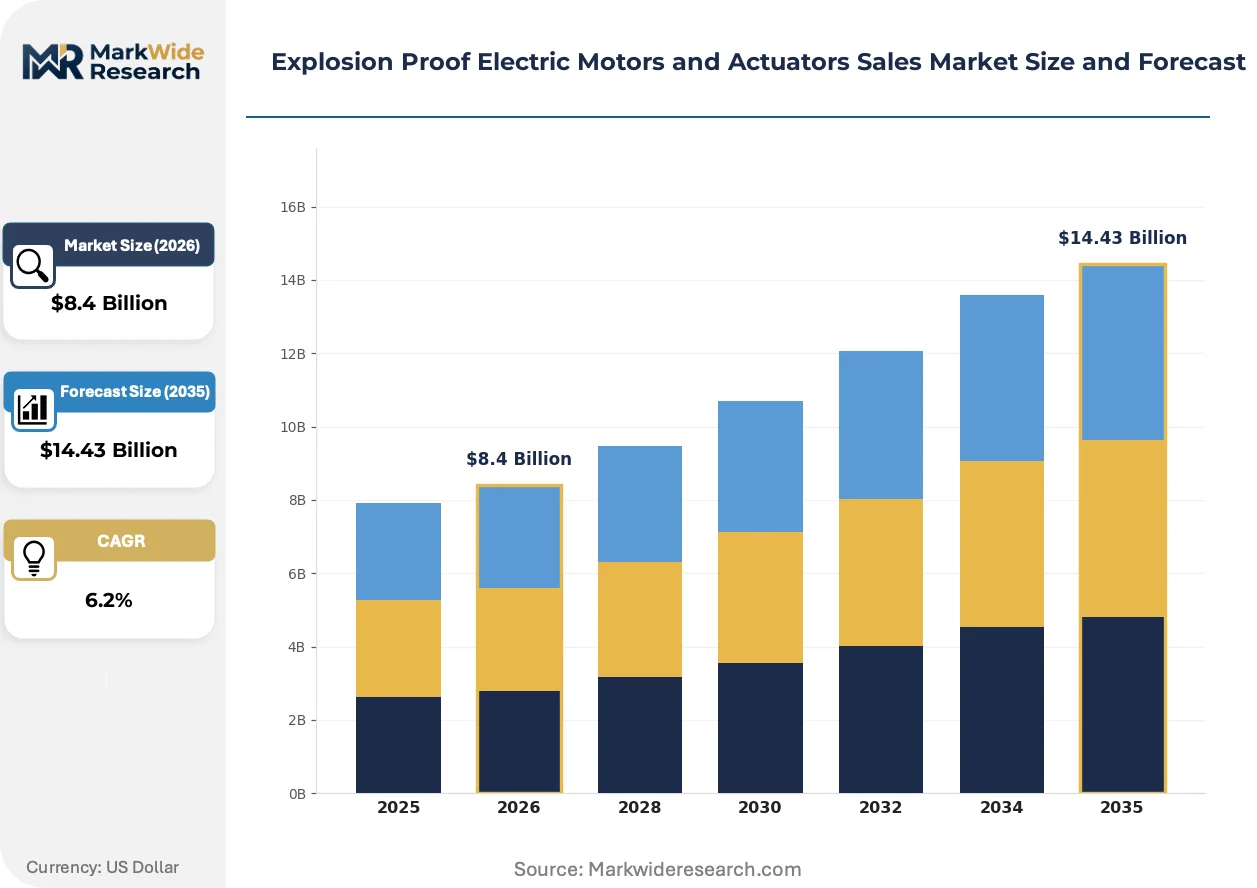
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Motors, DC Motors, Actuators, Gear Motors Application: Oil & Gas, Chemical Processing, Mining, Pharmaceuticals Technology: Brushless, Synchronous, Induction, Stepper End User: Manufacturers, Distributors, End Users, OEMs |
| Companies Covered | ABB, Siemens, Schneider Electric, Emerson Electric, WEG, Regal Beloit, Nidec Corporation, Rockwell Automation, Rotork PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Explosion Proof Electric Motors and Actuators Sales Market Trends and Innovations
Electrification of mechanical drive systems and embedded intelligence in hazardous area equipment are compressing traditional technology generations while reshaping supplier-customer relationships.
Integrated motor-drive systems with encapsulated power electronics are miniaturizing control architecture previously housed in separate junction boxes. Offshore platform operators in the North Sea adopt these compact configurations to reduce footprint and cabling complexity. The technology is miniaturizing equipment footprints by 30-40% while consolidating vendor accountability.
OSHA 29 CFR 1910.307 enforcement intensity is elevating documentation requirements for hazardous location electrical installations. United States refineries face heightened inspection scrutiny and penalty exposure. Insurers now mandate third-party equipment certification verification, shifting specification authority from procurement to risk management functions.
Lifecycle service contracting is displacing transactional spare parts purchasing among integrated chemical producers. Bayer and BASF-type operators unbundle maintenance from capital budgets, creating recurring revenue pools for motor OEMs with diagnostic capabilities. Germany's chemical corridor exhibits the most advanced contracting sophistication, with performance guarantees penetrating mid-tier processor accounts.
Explosion Proof Electric Motors and Actuators Sales Market Segmentation
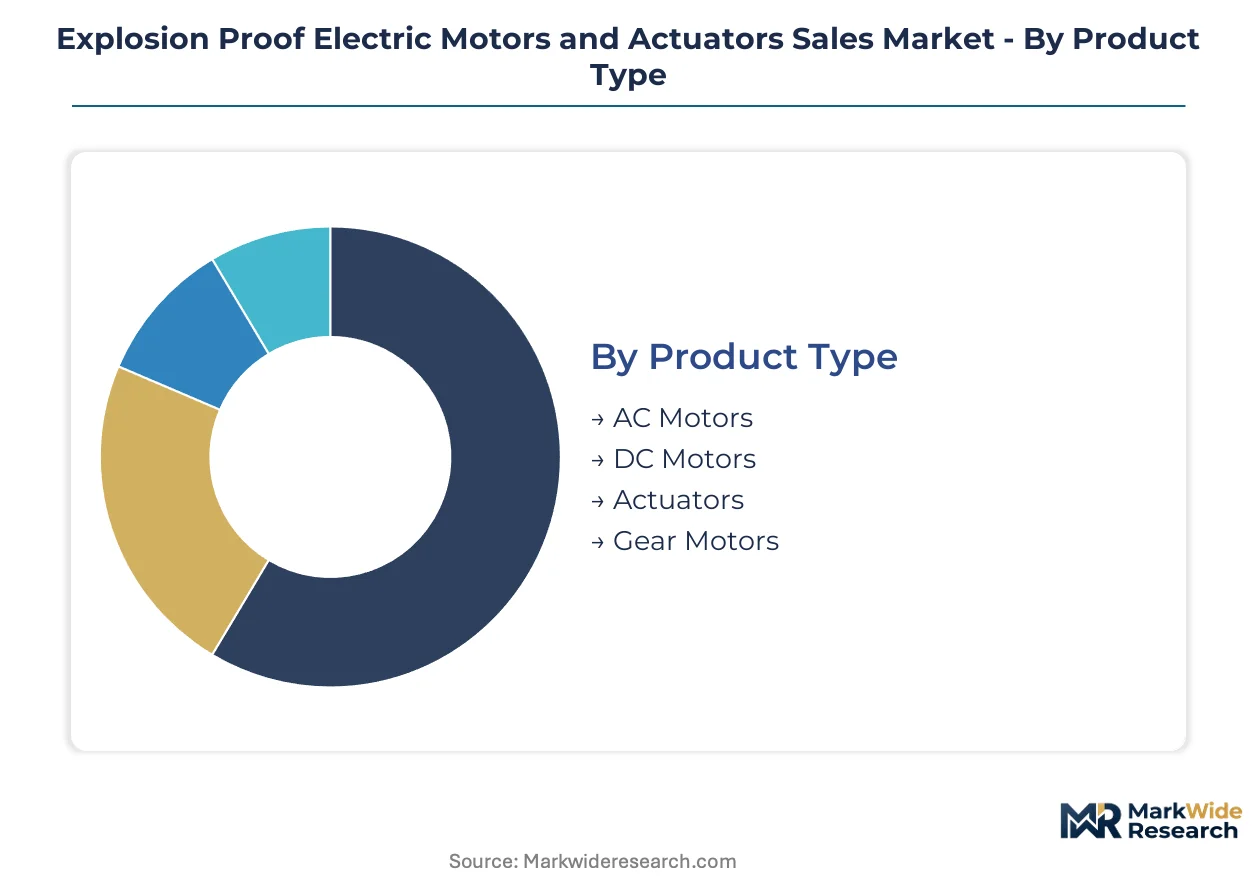
Explosion proof equipment procurement channels diverge sharply by technical complexity and certification burden. Channel economics dictate which segments flow through integrated OEMs versus specialized distributors.
Product Type:
AC motors and gear motors concentrate through direct OEM relationships with petrochemical EPCs, while actuators and DC motors fragment across distributor networks serving smaller batch processors.
- AC Motors:Induction-based designs with flameproof enclosures rated T1-T6 dominate upstream oil and gas applications. Demand concentrates along the United States Gulf Coast ethylene corridor where IEC 60079-1 compliance is non-negotiable for compressor drives.
- Actuators:Brushless electric positioners with encapsulated electronics are displacing pneumatic systems in pharmaceutical batch operations. Singapore and Rotterdam chemical clusters drive specification intensity for FDA-validated facilities requiring precise valve control.
- DC Motors:Commutated designs with explosion-proof housings serve specialized mining ventilation and portable equipment. Underground coal operations in Australia and South Africa sustain residual demand despite AC conversion trends.
- Gear Motors:Integrated synchronous configurations with precision speed control command premium positioning in polymer extrusion. German chemical processors under REACH compliance timelines favor lifecycle service contracting for these systems.
By volume, AC motors leads. By growth pace, actuators is ahead.
Application:
Cost tier stratification separates capital-intensive upstream installations from maintenance-driven replacement cycles in mature processing corridors.
- Oil & Gas:Upstream exploration and midstream compression operations require large-frame hazardous duty motors with captive foundry sourcing. United States Gulf Coast LNG export terminals bundle procurement into concentrated project windows.
- Chemical Processing:Specialty and commodity chemical plants demand synchronous gear motors for extrusion and mixing. Margin pools concentrate here due to precision control requirements and ATEX Directive 2014/34/EU compliance complexity.
- Mining:Underground coal and hard rock extraction operations utilize flameproof ventilation and haulage motors. South African and Australian regulatory frameworks mandate rigorous inspection regimes that extend replacement cycles.
- Pharmaceuticals:Active pharmaceutical ingredient facilities under CDSCO PLI scheme incentives in India require explosion-proof automation. Brushless actuators eliminate compressed air infrastructure while enabling batch validation documentation.
Chemical processing captures the highest margin concentration. Pharmaceuticals is climbing the fastest.
Technology:
Volume distribution skews toward mature induction platforms, while application expansion concentrates in digitally integrated alternatives.
- Induction:Squirrel-cage designs with encapsulated windings constitute the installed base majority. IECEx certification harmonization reduces duplicate testing costs for these standardized configurations across Singapore, Rotterdam, and Houston markets.
- Brushless:Permanent magnet motors with integrated position feedback enable precise actuation without sparking commutators. FDA-regulated pharmaceutical facilities drive specification intensity for validated batch control.
- Synchronous:Permanent magnet and reluctance variants deliver variable speed operation for polymer extrusion. German specialty chemical processors pay specification premiums for energy recovery capabilities.
- Stepper:Discrete-position motors serve specialized valve sequencing and metering applications. Limited penetration reflects control complexity and torque constraints in hazardous atmospheres.
Induction dominates unit shipments. Brushless is gaining share fastest.
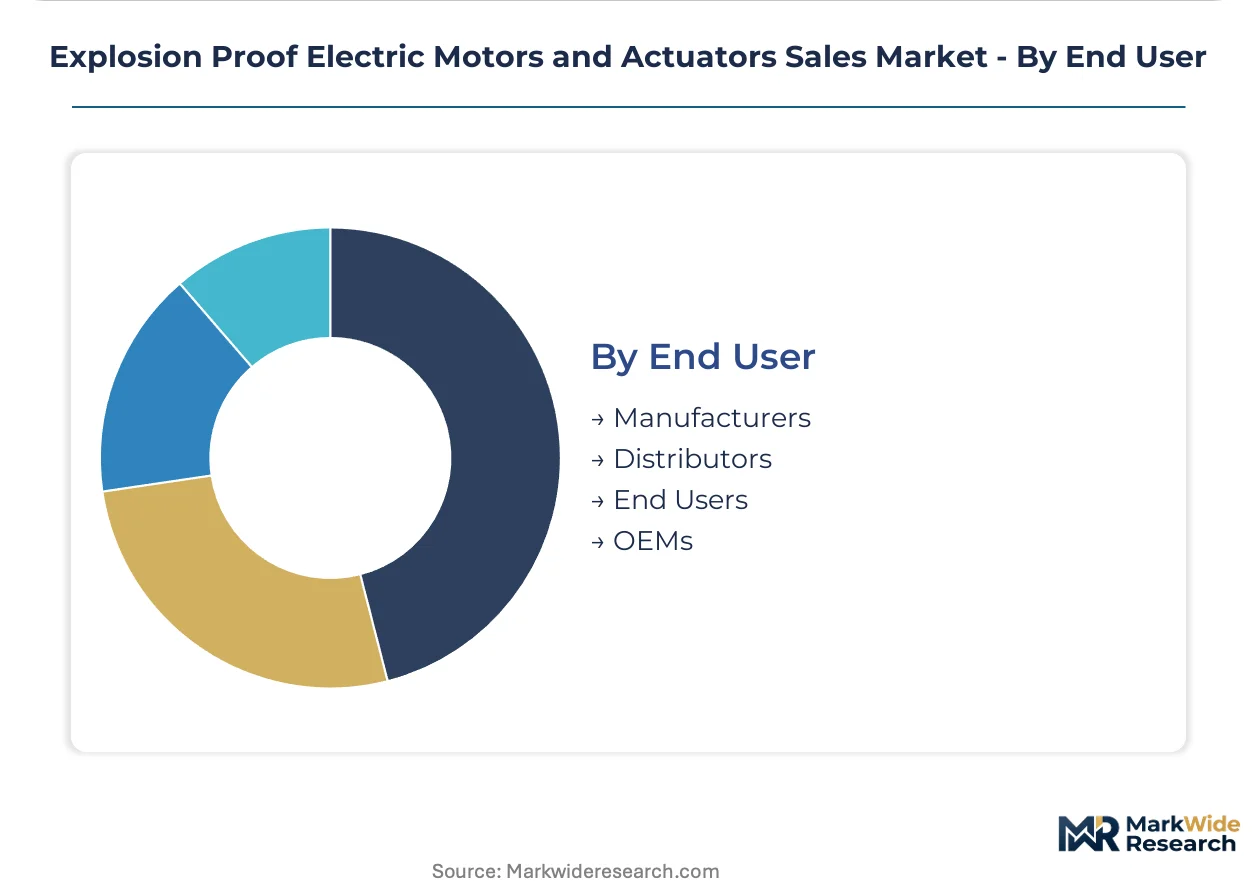
End User:
Customer type determines contract structure, with integrated manufacturers consolidating vendor lists while distributors fragment service relationships.
- Manufacturers:Integrated chemical producers like Bayer and BASF-type operators unbundle maintenance from capital budgets. Lifecycle service contracting with diagnostic capabilities displaces transactional spare parts purchasing in Germany's chemical corridor.
- OEMs:Original equipment manufacturers for pumps, compressors, and valves bundle explosion proof motors as integrated subsystems. Direct distribution relationships with Middle Eastern EPC contractors bypass traditional channels.
- Distributors:Specialized hazardous area equipment distributors serve mid-tier processors with fragmented procurement. Indian domestic assembly partnerships reduce import duty exposure for CDSCO-regulated facilities.
- End Users:Direct procurement by plant operators concentrates in large upstream oil and gas installations. OSHA 29 CFR 1910.307 enforcement intensity shifts specification authority from procurement to risk management functions.
Manufacturers command the largest contract value. OEMs is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: United States Gulf Coast operators prioritize large-frame replacement cycles, European chemical processors demand synchronous precision control, while Asian pharmaceutical clusters drive brushless actuator specification intensity.
United States
OSHA 29 CFR 1910.307 enforcement intensity elevates documentation requirements for hazardous location electrical installations. Insurers mandate third-party equipment certification verification, shifting specification authority from procurement to risk management functions. Texas and Louisiana ethylene corridor projects bundle procurement into concentrated windows favoring suppliers with captive foundry capacity.
Germany
Bayer and BASF-type operators unbundle maintenance from capital budgets, creating recurring revenue pools for motor OEMs with diagnostic capabilities. REACH compliance timelines accelerate lifecycle service contracting sophistication. The chemical corridor spanning North Rhine-Westphalia and Bavaria exhibits the most advanced performance guarantee penetration into mid-tier processor accounts.
India
CDSCO-regulated active pharmaceutical ingredient facilities under PLI scheme incentives require explosion-proof automation. Domestic motor assembly partnerships reduce import duty exposure for hazardous area equipment. Gujarat and Maharashtra pharmaceutical clusters drive brushless actuator demand for batch validation documentation.
China
GB standards alignment with IECEx schemes reduces duplicate testing costs for manufacturers serving export markets. MIIT industrial upgrading programs accelerate synchronous motor adoption in specialty chemical segments. Yangtze River Delta petrochemical complexes concentrate demand for flameproof compressor drives.
Singapore
IECEx certification harmonization enables rapid deployment of certified equipment across Rotterdam-connected chemical trading networks. FDA-regulated pharmaceutical facilities drive specification intensity for validated batch control systems. Jurong Island petrochemical hub concentrates brushless electric actuator procurement for precision valve operations.
Explosion Proof Electric Motors and Actuators Sales Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive foundry operations and dual-certification capabilities separating competitive strata. The market structure concentrates premium positioning around synchronous gear motor configurations and intelligent drive integration. Two strategic archetypes dominate: vertically integrated manufacturers controlling winding and enclosure production, and technology specialists focusing on digital actuation platforms. Competitive moves center on direct EPC contractor relationships and lifecycle service contracting displacement of transactional spare parts purchasing.
Among Swiss-Swedish and German industrial conglomerates, ABB and Siemens exemplify the integrated leader archetype through captive manufacturing scale and multi-platform R&D intensity. WEG anchors the emerging market specialist tier with South American and North American production footprint. These three occupy positions reflecting divergent geographic anchoring and vertical integration depth rather than convergent strategic postures.
| Leading Market Players |
|---|
| ABB |
| Siemens |
| Schneider Electric |
| Emerson Electric |
| WEG |
| Regal Beloit |
| Nidec Corporation |
| Rockwell Automation |
| Rotork PLC |
| Others |
Pricing and Supply Chain Analysis
Captive foundry utilization rates above 85 percent in Germany and China simultaneously concentrate supply-side leverage and establish price floors for flameproof enclosures. This scale dynamic forces component-assemblers into margin compression while integrated manufacturers defend premium positioning through in-house winding operations.
Pricing Analysis
Lifecycle service contracts now generate 40-50 percent of lifetime value for synchronous gear motor configurations, displacing transactional spare parts purchasing among Bayer-type chemical processors. Three-tier pricing structure across IECEx-certified premium, ATEX-standard, and economy induction platforms separates specification premiums by certification grade and after-sales bundling. Pricing pressure stems from copper and laminated steel volatility in winding materials, with mid-tier processors exhibiting highest price sensitivity while integrated oil and gas operators prioritize lead time certainty over unit cost.
Supply Chain Analysis
IECEx-certified test laboratory capacity in Europe and North America constitutes a critical chokepoint that extends time-to-market for new flameproof enclosure introductions. Manufacturing concentration centers on Germany, China, and Brazil for magnetic core laminations and cast enclosure production, with supply chains drawing from Chilean copper and Australian rare earth elements for permanent magnet actuators. Single-source vulnerability runs through foundry energy costs in Germany, while distribution runs through direct EPC contractor relationships in Middle Eastern petrochemical projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among engineering-procurement-construction firms that consolidate vendor lists for Gulf Coast ethylene corridor projects, fragmenting traditional distributor channels.
For Market Incumbents: Fortify captive foundry capacity in North American and South American facilities to compress lead times for large-frame hazardous duty motors. Deepen IECEx and ATEX dual-certification portfolios to create compliance barriers against emerging Asian component-assemblers. Prioritize diagnostic-enabled lifecycle service contracting to capture recurring revenue pools from Bayer and BASF-type operators unbundling maintenance from capital budgets. For New Entrants and Emerging Players: Differentiate on brushless electric actuator platforms for CDSCO-regulated pharmaceutical facilities in Gujarat and Maharashtra, where import duty exposure creates white-space for domestic assembly partnerships. Target precision valve control applications in Singapore's Jurong Island petrochemical hub, where FDA-validated batch documentation requirements favor specialized digital positioner suppliers. Pursue direct distribution to Middle Eastern EPC contractors bypassing traditional hazardous area equipment distributors. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among motor OEMs with integrated diagnostic capabilities serving Germany's chemical corridor under REACH compliance timelines. Long-term viability hinges on backward integration into winding and enclosure production rather than component-assembly models. Acquisition targets should demonstrate captive test laboratory access or queue management capabilities at IECEx-certified facilities. Watch for inflection when OSHA 29 CFR 1910.307 enforcement intensity shifts specification authority permanently from procurement to risk management functions.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Portfolio Expansion | ATEX Directive 2014/34/EU and IECEx 02 scheme alignment reduces duplicate testing costs for Singapore and Rotterdam chemical clusters. |
| Captive Foundry Capacity Addition | In-house enclosure casting in Texas and Louisiana compresses lead times for Gulf Coast LNG export terminal procurement windows. |
| Lifecycle Service Contracting | Performance guarantees with diagnostic capabilities penetrate mid-tier German chemical processors unbundling maintenance from capital budgets. |
| Domestic Assembly Partnerships | Indian pharmaceutical clusters under CDSCO PLI scheme reduce import duty exposure for brushless actuator suppliers. |
| Direct EPC Distribution Channels | Bypassing traditional distributors captures margin and reduces uncertainty for Middle Eastern petrochemical project bundling. |
Research Methodology
Operator-level perspectives from maintenance directors at integrated chemical producers, OEM procurement teams for pump and compressor manufacturers, EPC contractor engineering leads, and aftermarket service heads anchored the qualitative base for this analysis. Primary fieldwork combined with secondary validation from customs and trade data, SEC filings of listed motor manufacturers, IECEx certification registry databases, and OSHA enforcement records. Bottom-up unit shipment estimates triangulated against top-down value projections across product type, application, technology, and end user segmentation.
Sensitivity analysis on copper price trajectories and foundry energy cost scenarios shaped the forecast framework across the analysis window. Segmentation dimensions modeled include motor technology tier, hazardous zone classification, certification scheme jurisdiction, and regional petrochemical corridor concentration. CAGRs derived from regression analysis against historical replacement cycle data and project pipeline visibility. Industry-specific inputs incorporated ethylene cracker expansion timelines and pharmaceutical facility validation documentation requirements.
Decision-makers should treat outputs as directional under stable regulatory harmonization assumptions; material divergence between ATEX and IECEx timelines would warrant model refresh. Forecasts embed assumptions regarding OSHA enforcement intensity trajectory and CDSCO PLI scheme continuation. Practitioners should keep alternative scenarios live as GB standards alignment with IECEx schemes and MIIT industrial upgrading program priorities evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Asia Pacific Safety Drives and Motors Market
Industrial Motors
Global Explosion-Proof Motor Casting Market
Industrial Motors
Air Heater Tubes Market
Industrial Motors
Asia Pacific and Middle East and Africa Submerged Arc Furnace Market
Industrial Motors
Global Brushed DC Motor Market
Industrial Motors
Power Scraper Market
Industrial Motors
Hoist and Elevator Motors Market
Industrial Motors
AC Motor Market
Industrial Motors
Global Linear Motors Market
Industrial Motors
Global Switched Reluctance Motor Market
Industrial Motors
Cryogenic Air Separation Units (Asus) Market
Industrial Motors
Hydraulic Motors Market
Industrial Motors
Japan AC Motor Market
Industrial Motors
Brushless DC Motor Market
Industrial Motors
Variable Speed Drive Market
Industrial Motors
Europe Tank Insulation Market