
 China AC Motor Market | 2026-2036
China AC Motor Market Size, Share, and Industry Trends Forecast 2026-2036
China AC Motor Market Insights
Multi-source component procurement is shifting toward captive in-house motor production among major industrial groups. Wolong Electric leverages vertical integration across copper winding and lamination operations to secure supply chain control. Broad-Ocean Motor anchors its position through specialized HVAC motor manufacturing for domestic appliance OEMs. Inovance Technology competes by extending servo motor R&D intensity for precision robotics applications.
An AC motor converts alternating current into mechanical rotation through electromagnetic induction between stator windings and a rotor assembly, typically operating at speeds governed by supply frequency and pole count. Industrial machinery applications dominate volume consumption, while servo motor segments capture premium margins from robotics and CNC equipment demand. Variable frequency drive technology leads adoption curves as manufacturers retrofit existing installations for energy compliance.
China's MIIT enforces GB 18613 efficiency standards that mandate IE3 minimum ratings for general-purpose motors, while SAMR oversees market access certification through CCC marking requirements. NMPA coordinates with MEE on industrial equipment environmental compliance that shapes motor material specifications and recycling protocols. Stakeholders must monitor how dual carbon policy targets recalibrate efficiency tier thresholds and raw material sourcing requirements for rare-earth permanent magnet formulations.
Market Dynamics
China's AC motor market is being fundamentally restructured by the convergence of MIIT-mandated efficiency upgrades and the electrification of domestic automotive manufacturing, which together are compressing legacy motor architectures while expanding high-performance permanent magnet demand.
Growth Catalysts
- GB 18613 Efficiency Mandates:MIIT's IE3 minimum efficiency standards for general-purpose motors are forcing wholesale replacement of installed industrial bases, creating sustained procurement volume through 2035.
- Electric Vehicle Powertrain Demand:BYD and NIO's expanding production schedules are pulling high-torque density motors into automotive supply chains at unprecedented scale.
- Yangtze River Delta Manufacturing Cluster:Concentrated OEM and tier-one supplier presence across Shanghai, Jiangsu, and Zhejiang provinces generates localized demand aggregation and logistics efficiency.
Market Restraints
- Rare-Earth Magnet Supply Concentration:Neodymium and dysprosium processing capacity concentrates in Inner Mongolia and Jiangxi, creating single-source vulnerability for high-efficiency motor formulations.
- Copper Price Volatility:Stator winding material costs fluctuate with LME pricing, compressing margin predictability for mid-tier motor assemblers serving price-sensitive HVAC OEMs.
- Legacy Infrastructure Lock-In:Existing fixed-speed motor installations with decades of depreciation remaining resist VFD retrofit capital outlays despite operational savings.
Strategic Opportunities
- Robotics Servo Motor Expansion:Precision automation demand from electronics and semiconductor manufacturing in Shenzhen and Suzhou is opening premium-margin segments beyond commodity industrial motors.
- Dual Carbon Policy Tailwinds:National carbon neutrality targets are accelerating MEE-coordinated subsidies for IE4 and IE5 ultra-premium efficiency tier adoption in heavy industry.
- Aftermarket Service Unbundling:Predictive maintenance contracts and motor-as-a-service models are penetrating steel and cement sectors previously dominated by transactional equipment sales.
Industry Challenges
- Electromagnetic Design Talent Scarcity:Finite pool of engineers capable of thermal-fluid and electromagnetic co-simulation is bottlenecking next-generation motor development timelines.
- CCC Certification Backlogs:SAMR's expanded testing requirements for variable frequency drive integration are extending product launch cycles by four to six months.
- Legacy Control System Integration:Retrofitting smart motor monitoring into existing PLC architectures requires custom protocol gateways that fragment supplier value propositions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China AC Motor Market |
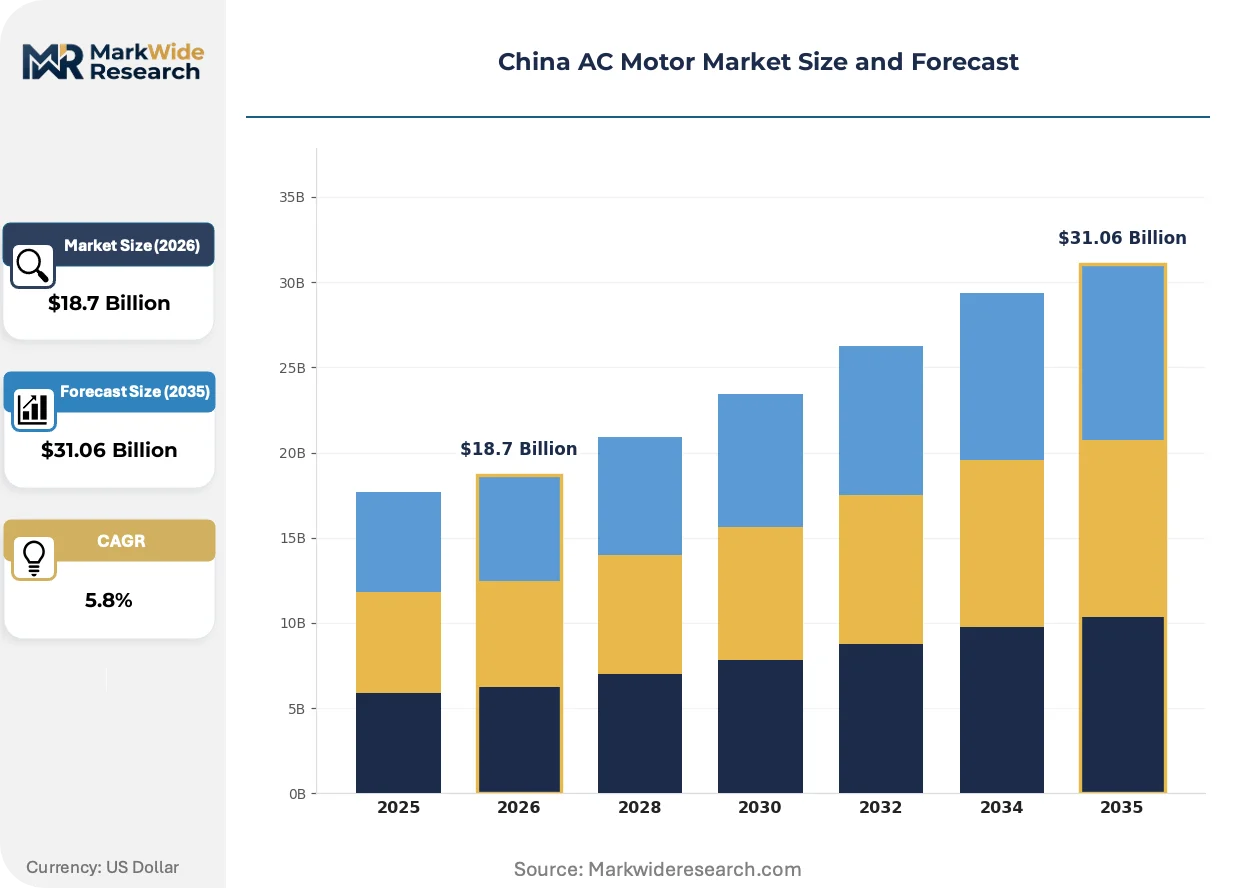
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Induction Motor, Synchronous Motor, Servo Motor, Permanent Magnet Motor Application: Industrial Machinery, HVAC Systems, Robotics, Automotive End User: Manufacturing, Energy, Transportation, Consumer Electronics Technology: Variable Frequency Drive, Direct-On-Line, Soft Starter, Control Systems |
| Companies Covered | Wolong Electric, Broad-Ocean Motor, Inovance Technology, Johnson Electric, ABB Limited, Siemens AG, Nidec Corporation, Rockwell Automation, Yaskawa Electric Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China AC Motor Market Trends and Innovations
Permanent magnet synchronous motor architectures are displacing induction designs across China's highest-volume applications, while digital twin integration and AI-assisted thermal management are redefining performance optimization workflows.
Silicon carbide (SiC) power electronics is electrifying motor-drive system efficiency by enabling higher switching frequencies with reduced thermal losses. Automotive OEMs in Guangdong and Zhejiang are adopting SiC-integrated inverters at accelerating pace for 800V platform vehicles. This electrification is compressing the performance gap between premium and standard motor tiers, forcing mid-market suppliers toward either capability upgrade or commodity retreat.
MIIT's evolving GB standards framework is tightening efficiency verification protocols through mandatory third-party testing and digital certificate registries. Manufacturers must now submit continuous load-cycle test data rather than single-point efficiency claims, raising compliance costs for smaller producers. The industrial machinery segment is responding through consolidated procurement specifications that pre-qualify only suppliers with in-house testing laboratories.
Buyers in the Yangtze River Delta are consolidating motor procurement through integrated equipment packages rather than component sourcing. System integrators and machinery OEMs are absorbing motor selection decisions previously made by end-user maintenance departments, compressing supplier count per account. This concentration is most visible in compressor and pump applications where packaged solutions now specify captive motor brands by default.
China AC Motor Market Segmentation
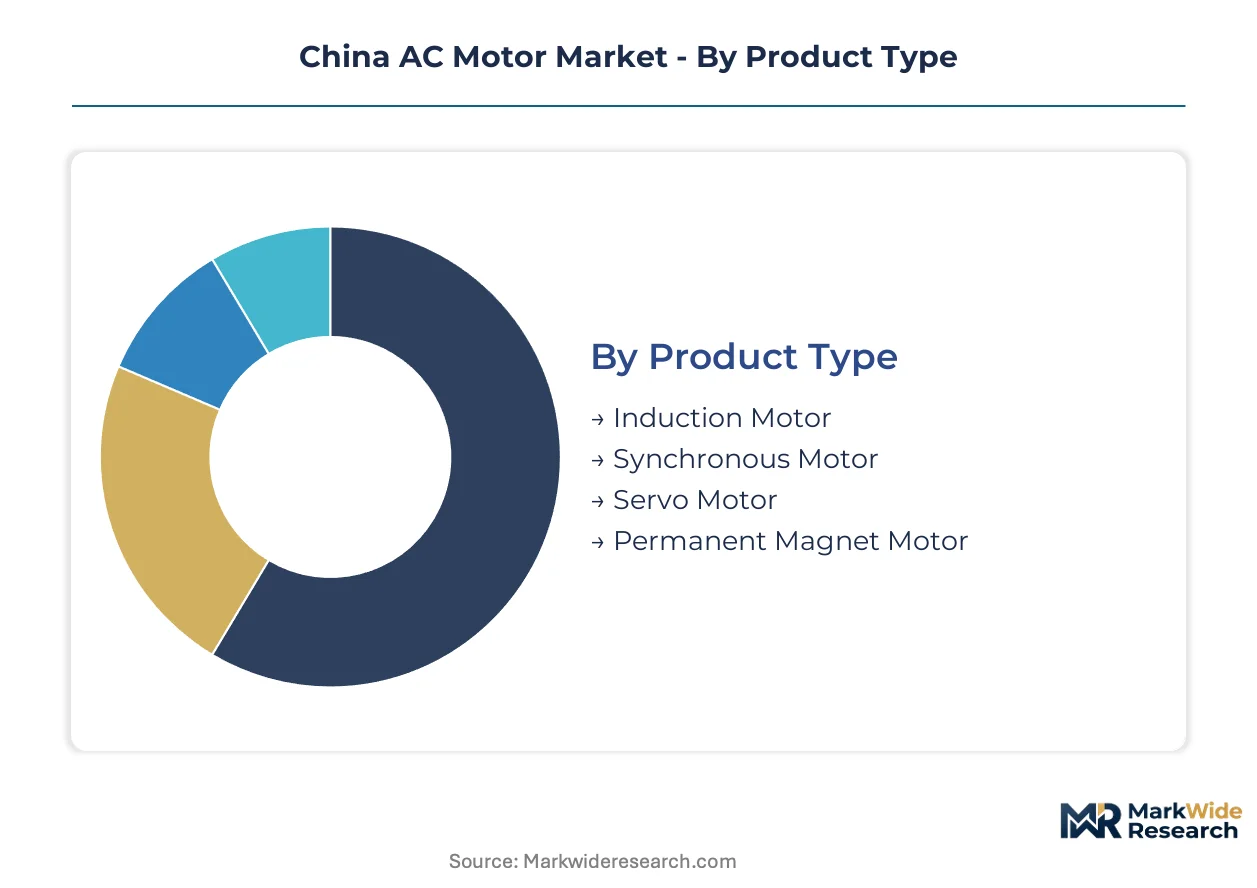
China's AC motor market segmentation reflects divergent buyer priorities across efficiency mandates, electrification timelines, and automation intensity. Procurement specifications now stratify sharply between commodity replacement cycles and premium technology integration.
Product Type:
Buyers select motor architectures based on efficiency tier requirements and torque density specifications rather than upfront cost alone.
- Induction Motor:Squirrel-cage rotor designs dominate legacy industrial infrastructure with proven reliability under harsh operating conditions. Demand concentrates in steel and cement retrofit programs across Hebei and Shandong provinces where GB 18613 IE3 compliance deadlines force equipment replacement.
- Synchronous Motor:Rotor field excitation enables precise speed control for compressor and pump applications in petrochemical facilities. Procurement volumes cluster in Ningbo and Dalian port-industrial complexes where process consistency outweighs capital expenditure sensitivity.
- Servo Motor:Closed-loop positioning systems with encoder feedback deliver sub-arcminute accuracy for multi-axis automation.
- Permanent Magnet Motor:Rare-earth rotor formulations achieve IE4/IE5 efficiency thresholds with compact form factors.
Induction motor shipments lead on scale; permanent magnet configurations lead on momentum.
Application:
Application selection tracks end-user capital allocation cycles and regulatory compliance deadlines rather than organic demand expansion.
- Industrial Machinery:Conveyor systems, compressors, and machine tool spindles consume the largest motor volumes by unit count. Procurement concentrates in Jiangsu province manufacturing clusters where MIIT efficiency audits accelerate equipment refresh schedules.
- HVAC Systems:Centrifugal fans and chiller compressors specify high-efficiency motors for commercial building energy codes. Demand aggregates in Shanghai and Hangzhou where municipal green building mandates tighten faster than national standards.
- Robotics:Six-axis articulated arms and SCARA systems require harmonic drive-compatible servo motors with dynamic response specifications.
- Automotive:Traction motors and electric power steering systems pull high-torque-density designs into vehicle assembly supply chains.
Industrial machinery anchors volume; automotive applications are climbing the fastest.
End User:
End-user segmentation reflects divergent procurement sophistication between state-directed infrastructure and private manufacturing investment.
- Manufacturing:Discrete and process industries specify motors through consolidated equipment procurement rather than component sourcing. Demand concentrates in Guangdong electronics assembly and Zhejiang textile machinery where automation upgrades outpace greenfield investment.
- Energy:Power generation and oil & gas operations prioritize reliability-centered maintenance specifications over efficiency premiums. Procurement aggregates in Sichuan hydropower maintenance and Xinjiang pipeline compressor stations.
- Transportation:Rail electrification and port cargo handling systems specify traction motors with extended duty cycles.
- Consumer Electronics:Appliance OEMs in Hefei and Qingdao source fractional horsepower motors through captive supplier relationships with strict cost targets.
Manufacturing dominates procurement value; transportation shows the steepest expansion trajectory.
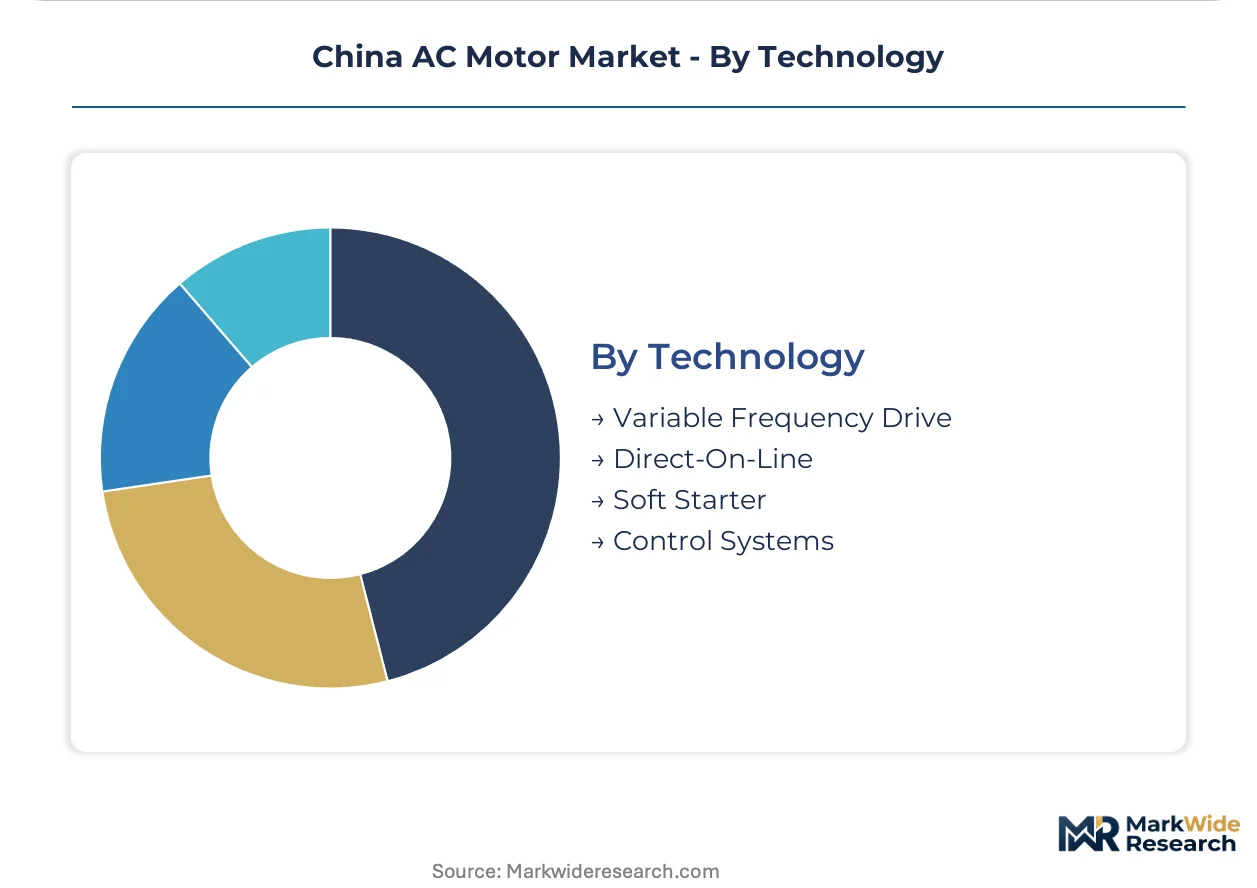
Technology:
Technology adoption correlates with facility electrical infrastructure age and maintenance department technical capacity.
- Variable Frequency Drive:VFD-motor packages enable precise speed control with 15-40% energy recovery versus fixed-speed operation. Retrofit demand concentrates in Shandong chemical processing where SAMR subsidies offset capital costs.
- Direct-On-Line:Across-the-line starting remains standard for low-horsepower applications with infrequent start cycles. Procurement persists in rural manufacturing where electrical infrastructure cannot support harmonic-rich VFD installations.
- Soft Starter:Reduced-voltage starting limits mechanical and electrical stress for high-inertia loads.
- Control Systems:Integrated motor-drive-controller packages with IoT connectivity enable predictive maintenance contracts.
VFD integration leads installed base; control systems gain share fastest among new installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration within China follows regulatory cost gradients, with manufacturers relocating motor assembly from coastal compliance zones to interior provinces where GB efficiency enforcement remains less stringent. This arbitrage pattern concentrates high-volume output in lower-tier cities while premium R&D and testing facilities cluster in enforcement-heavy metros.
Yangtze River Delta
Shanghai, Jiangsu, and Zhejiang provinces anchor China's highest-value motor procurement, driven by BYD and NIO powertrain demand plus MIIT-mandated industrial equipment upgrades. SAMR's intensified CCC certification audits in this zone force smaller assemblers toward consolidation or exit. Suzhou and Ningbo host the densest concentrations of servo motor specialists serving semiconductor and robotics OEMs.
Pearl River Delta
Guangdong province pulls high-torque-density motors into automotive supply chains as Guangzhou and Shenzhen OEMs expand EV platform production. MEE-coordinated dual carbon subsidies accelerate IE4 and IE5 tier adoption in Shenzhen's electronics manufacturing cluster. Dongguan's machinery OEMs are absorbing motor selection decisions previously made by end-user procurement departments.
Beijing-Tianjin-Hebei
Hebei province's steel and cement sectors drive induction motor replacement cycles under GB 18613 IE3 compliance deadlines. SAMR's expanded testing requirements for VFD integration extend product launch timelines for Tianjin-based suppliers. Tangshan and Shijiazhuang concentrate heavy-industry motor demand where reliability-centered maintenance specifications outweigh efficiency premiums.
Sichuan-Chongqing
Western China's hydropower maintenance and pipeline compressor stations prioritize extended-duty traction motors. NMPA industrial equipment directives shape material specifications for rare-earth permanent magnet formulations in Chengdu. Chongqing's automotive manufacturing base is pulling motor procurement volumes away from coastal suppliers through localized tier-one development.
Shandong Peninsula
Shandong's chemical processing sector generates VFD retrofit demand where SAMR subsidies offset capital costs for variable frequency drive packages. Qingdao's appliance OEMs source fractional horsepower motors through captive supplier relationships with strict cost targets. Jinan's industrial machinery cluster concentrates procurement through integrated equipment packages rather than component sourcing.
China AC Motor Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue servo motor specialization and SiC-integrated drive systems. The vendor base stratifies between scale-driven industrial motor fabricators and precision-focused automation specialists. Three archetypes dominate: vertically integrated conglomerates controlling copper winding and lamination operations, HVAC-dedicated manufacturers with captive appliance OEM relationships, and servo motor developers targeting robotics accuracy specifications. Competitive moves center on backward integration into rare-earth magnet supply chains and predictive maintenance service unbundling.
Among domestic integrated producers, Wolong Electric exemplifies the conglomerate archetype through upstream control over critical component operations. Broad-Ocean Motor anchors the HVAC-specialist position with established appliance OEM channel relationships. Inovance Technology occupies the precision-automation tier, representing the servo motor R&D intensity required for multi-axis robotics applications. These three Chinese entities collectively illustrate the strategic divergence between commodity scale and premium technology positioning.
| Leading Market Players |
|---|
| Wolong Electric |
| Broad-Ocean Motor |
| Inovance Technology |
| Johnson Electric |
| ABB Limited |
| Siemens AG |
| Nidec Corporation |
| Rockwell Automation |
| Yaskawa Electric Corporation |
| Others |
Pricing and Supply Chain Analysis
BYD and NIO procurement consolidation for EV powertrain motors is compressing supplier margins while forcing mid-tier assemblers toward backward integration or exit. This buyer-side concentration amplifies pricing power for vertically integrated producers controlling copper winding and lamination operations.
Pricing Analysis
Copper LME pricing volatility passes directly into stator winding costs, compressing margin predictability for mid-tier motor assemblers. Pricing stratifies across IE5 ultra-premium, IE4 high-efficiency, and IE3 compliance tiers, with certification grade and volume scale as primary differentiation drivers. Cost compression in standard induction motors intensifies because Hebei steel sector procurement favors lowest compliant bids. HVAC OEMs in Qingdao exhibit highest price sensitivity; robotics integrators in Suzhou accept premium positioning for servo accuracy specifications.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from automotive powertrain programs, while distributor networks serve fragmented industrial replacement markets. Neodymium and dysprosium processing concentrates in Inner Mongolia and Jiangxi, creating single-source vulnerability for permanent magnet formulations. Stator steel laminations draw from Baosteel and Shougang mills; copper rod feeds from Jiangxi and Anhui smelters. Distribution runs through machinery OEMs absorbing motor selection decisions previously made by end-user procurement departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's AC motor market functions as a regulatory compounder where MIIT's GB 18613 efficiency mandates generate sustained replacement demand through 2035.
For Market Incumbents: Deepen backward integration into rare-earth magnet supply chains to offset Jiangxi processing concentration risk. Expand in-house testing laboratory capacity to meet SAMR's expanded CCC certification requirements for VFD integration. Lock long-term copper supply agreements before LME volatility transmits into winding cost structures. For New Entrants and Emerging Players: Begin with servo motor specialization for Shenzhen and Suzhou robotics OEMs where electromagnetic design talent scarcity limits incumbent response speed. Target precision automation segments in semiconductor manufacturing equipment. Pursue predictive maintenance service contracts as entry wedge into steel and cement sectors. For Investors and Strategic Acquirers: Asymmetric upside sits with servo motor developers possessing thermal-fluid co-simulation capabilities and established encoder feedback partnerships. Five-to-ten year viability hinges on positioning ahead of IE5 tier proliferation under dual carbon policy acceleration. Monitor MEE subsidy disbursement velocity for IE4 and IE5 adoption as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Supply | Secures neodymium processing access against Jiangxi concentration vulnerability. |
| In-House Testing Laboratory Certification | Meets SAMR's expanded CCC requirements for VFD-integrated motor launches. |
| Servo Motor R&D Intensity Expansion | Captures precision robotics demand from Shenzhen semiconductor equipment OEMs. |
| Predictive Maintenance Service Unbundling | Penetrates steel and cement sectors through motor-as-a-service contracts. |
| SiC-Integrated Drive System Development | Aligns with Guangdong automotive OEM 800V platform electrification roadmaps. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with motor procurement directors at machinery OEMs, maintenance engineers at steel and cement facilities, HVAC system integrators, and automotive Tier 1 sourcing managers with secondary validation. Secondary sources included MIIT efficiency standard filings, SAMR CCC certification registries, China Customs trade data, and copper LME pricing archives. Bottom-up shipment estimates and top-down industrial output correlations were triangulated against each other.
Segment-weighting applied product type splits across induction, synchronous, servo, and permanent magnet architectures; application weighting across industrial machinery, HVAC, robotics, and automotive; and technology adoption curves for VFD, direct-on-line, soft starter, and integrated control systems. CAGRs were derived from installed base replacement modeling against MIIT compliance deadlines and EV production forecasts. Rare-earth magnet price indices and copper volatility bands fed sensitivity testing.
Several conditions sit outside the modeled scope, including geopolitical disruption to rare-earth export quotas and unannounced GB standard tier escalations beyond IE5. Forecasts reflect assumptions about dual carbon policy subsidy continuity and automotive electrification penetration trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Global Direct Current (DC) Motor Market
Industrial Motors
Explosion Proof Electric Motors and Actuators Sales Market
Industrial Motors
Global Explosion-Proof Motor Casting Market
Industrial Motors
Electric Motors for Drones and Electric Vehicle Market
Industrial Motors
Middle East and Africa Variable Frequency Drive (VFD) Market
Industrial Motors
AC Servo Motors and Drives Market
Industrial Motors
North America Industrial Motors Market
Industrial Motors
Food Grade Hydraulic Oil Market
Industrial Motors
Liquid Nitrogen Purge Systems Market
Industrial Motors
Gear Motor Market
Industrial Motors
Europe Tank Insulation Market
Industrial Motors
Global Energy Efficient Motor Market
Industrial Motors
Global Permanent Magnet Motor Market
Industrial Motors
Fractional Horsepower Motor Market
Industrial Motors
Submersible Pump Motor Market
Industrial Motors
Air Heater Tubes Market