
 High Speed Blowers Market | 2026-2036
High Speed Blowers Market Size, Share, and Industry Trends Forecast 2026-2036
High Speed Blowers Market Analysis
OEM-direct procurement channels for high-speed turbo blowers is reshaping how municipalities and industrial operators source aeration equipment. Atlas Copco AB leverages its magnetic bearing compressor heritage to dominate premium wastewater applications. Gardner Denver Inc. anchors North American distribution through integrated service networks. Kaeser Kompressoren SE competes on energy efficiency certification and regional manufacturing proximity.
High speed blowers are turbomachines operating above 20,000 RPM, typically employing air foil or magnetic bearings to eliminate mechanical contact and achieve efficiencies exceeding 75% at design point. Their primary purpose is to deliver oil-free compressed air or process gas for aeration, pneumatic conveying, and industrial vacuum applications. Centrifugal designs occupy the largest installed base due to scalability from 50 to 5,000+ horsepower, while regenerative configurations sustain niche positions in low-pressure, high-flow vacuum applications where pulsation tolerance matters. Electric drive technology leads technology segmentation as permanent magnet synchronous motors displace induction motor-pinion gearbox combinations across new installations.
The US Department of Energy's fan and blower efficiency standards, the EU Ecodesign Directive, and China's GB 19761 motor efficiency grades collectively mandate minimum performance thresholds that filter out conventional multistage centrifugal designs. REACH and RoHS compliance in Europe further restrict lubricant and magnet material sourcing, adding certification cost but protecting compliant manufacturers. Stakeholders must monitor magnetic bearing supply chain concentration and permanent magnet rare earth sourcing as dual constraints on capacity expansion and cost structure.
Market Dynamics
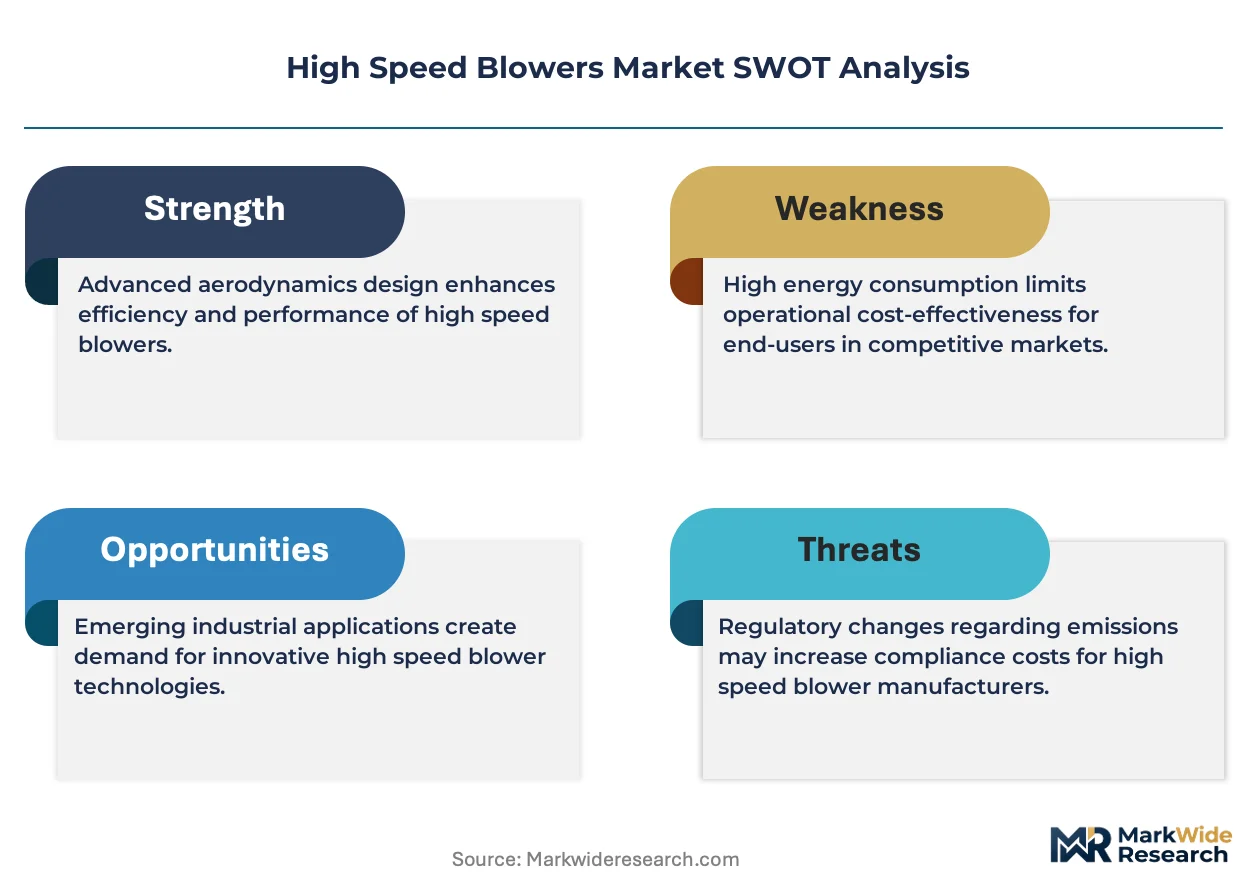
Magnetic bearing technology is compressing maintenance cycles and energy intensity across municipal and industrial aeration systems, forcing incumbent multistage centrifugal architectures into accelerated replacement schedules.
Growth Catalysts
- Wastewater effluent tightening:Germany, China, and the United States are expanding aeration capacity to meet nitrogen and phosphorus discharge limits, directly stimulating turbo blower procurement.
- EU Ecodesign Directive:Minimum efficiency thresholds for fans above 10 kW are filtering out conventional gearbox-driven designs from European public tenders.
- Permanent magnet motor maturation:Rare earth magnet cost stabilization and domestic sourcing initiatives in China are accelerating electric drive adoption over induction motor-pinion combinations.
Market Restraints
- Neodymium supply concentration:Permanent magnet rare earth processing concentrates in Chinese refining corridors, exposing motor manufacturers to export quota volatility and price spikes.
- Magnetic bearing vendor scarcity:Active magnetic bearing controller and sensor supply chains cluster among three European and Japanese specialist firms, constraining OEM scaling capacity.
- REACH compliance burden:ECHA registration requirements for lubricant alternatives and magnet coatings add certification timelines that delay product launches by 8-14 months.
Strategic Opportunities
- India municipal sanitation expansion:The country's AMRUT 2.0 scheme targets 100% sewage connectivity in 500 cities, creating first-mover positioning for energy-efficient aeration equipment.
- Biogas upgrading integration:Convergence of high-speed blowers with membrane-based biogas purification systems opens process gas compression applications in agricultural waste facilities.
- US Inflation Reduction Act:Clean energy manufacturing tax credits for efficient industrial equipment are redirecting municipal capital toward magnetic bearing turbo blowers in wastewater retrofits.
Industry Challenges
- Rotordynamics expertise scarcity:Magnetic bearing commissioning and active vibration control require specialized field engineers, with training pipelines lagging installation growth by 30-40%.
- Legacy control system integration:SCADA retrofit compatibility with 1990s-era distributed control systems in US municipal plants forces custom engineering on 60% of replacement projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Speed Blowers Market |
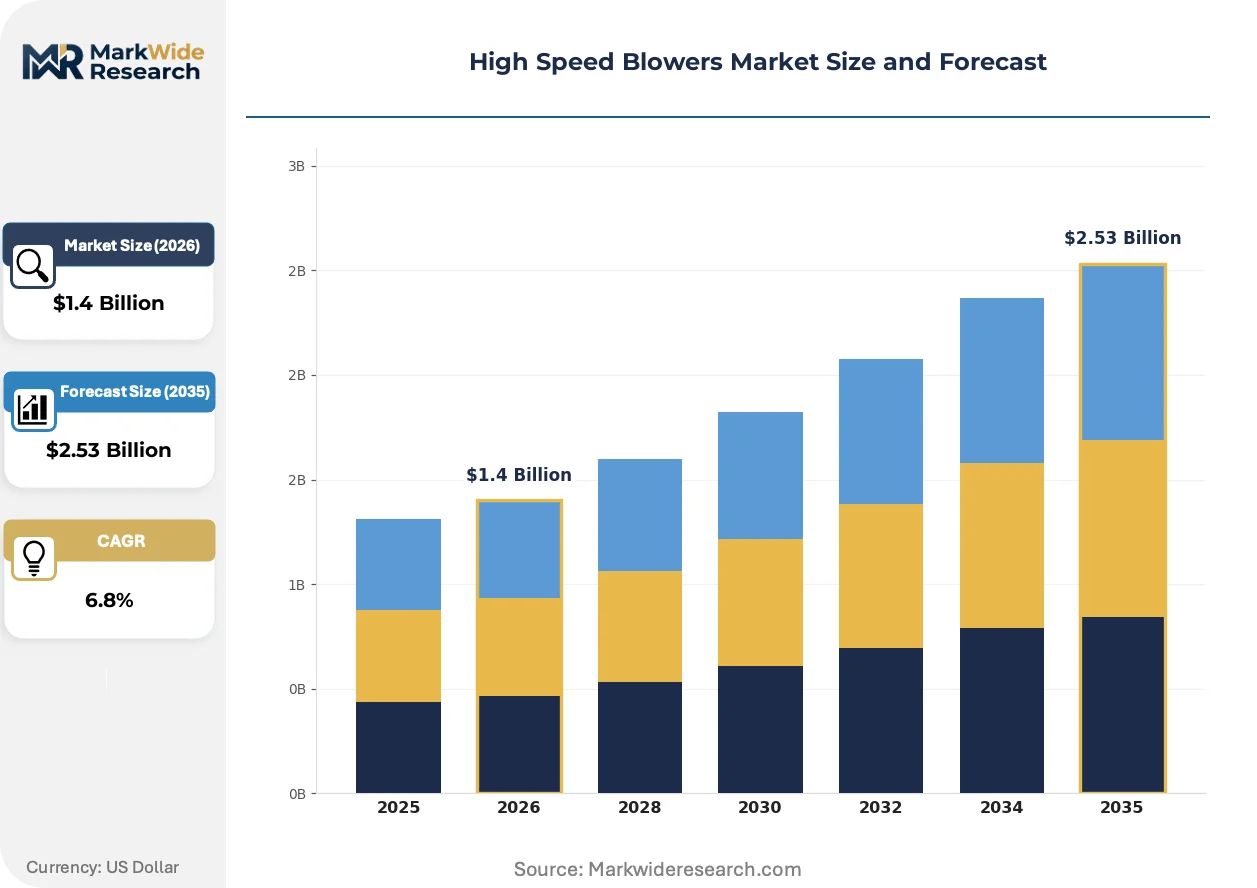
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
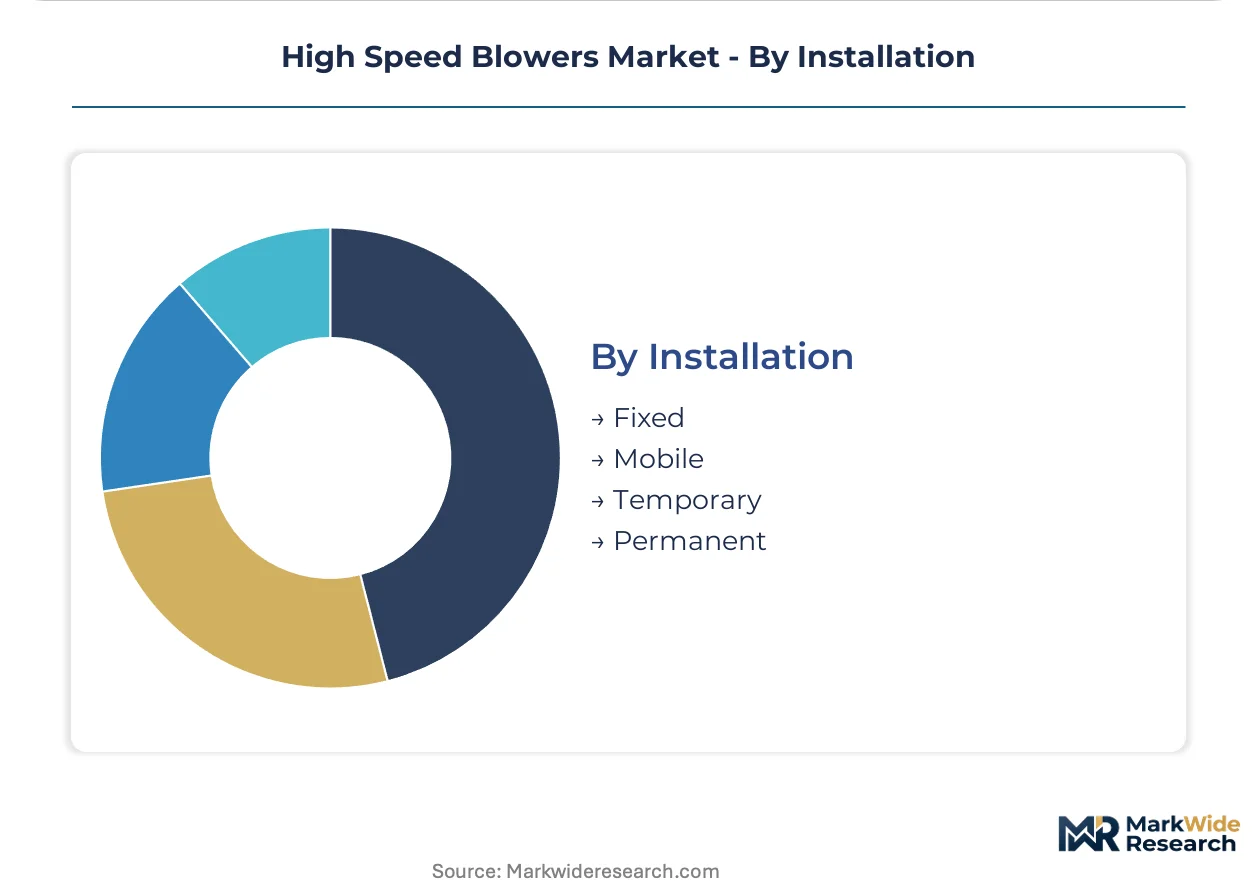
| Segmentation | Product Type: Centrifugal, Axial, Regenerative, Side Channel End User: Manufacturing, HVAC, Wastewater Treatment, Food Processing Technology: Electric, Pneumatic, Mechanical, Hybrid Installation: Fixed, Mobile, Temporary, Permanent |
| Companies Covered | Atlas Copco AB, Aerzen Turbo Co., Ltd, APG Neuros, Inc, Gardner Denver Inc., Kaeser Kompressoren SE, Continental Industries, Howden North America, Inc, Atlantic Blower, Eminent Blowers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Speed Blowers Market Emerging Trajectories
Active magnetic bearing architectures are displacing oil-lubricated and air-foil bearing systems across the 200-500 kW power band, compressing total cost of ownership calculations and reshaping competitive differentiation.
Air-foil bearing technology is migrating from niche food and pharmaceutical applications into mainstream wastewater treatment. Municipal operators in the US Southeast are adopting oil-free designs to eliminate EPA discharge liability from lubricant seal failures. This migration is compressing the addressable market for conventional rolling element bearings and forcing incumbents to develop magnetic bearing partnerships or exit the segment.
The EU F-Gas Regulation phase-down is accelerating refrigerant-based cooling system replacement in blower motor drives. Industrial operators face retrofit deadlines for equipment using hydrofluorocarbon coolants, with permanent magnet synchronous motors and liquid-cooled architectures gaining preference. German engineering procurement specifications now explicitly exclude refrigerant-cooled options above 315 kW.
Equipment-as-a-service contracting is fragmenting traditional capital purchase patterns. Dutch and Danish water utilities are unbundling blower assets from 20-year performance guarantees, transferring operational risk to OEM service arms. This restructuring concentrates procurement authority among integrated solution providers and marginalizes component-only vendors in Northern European markets.
High Speed Blowers Market Segmentation
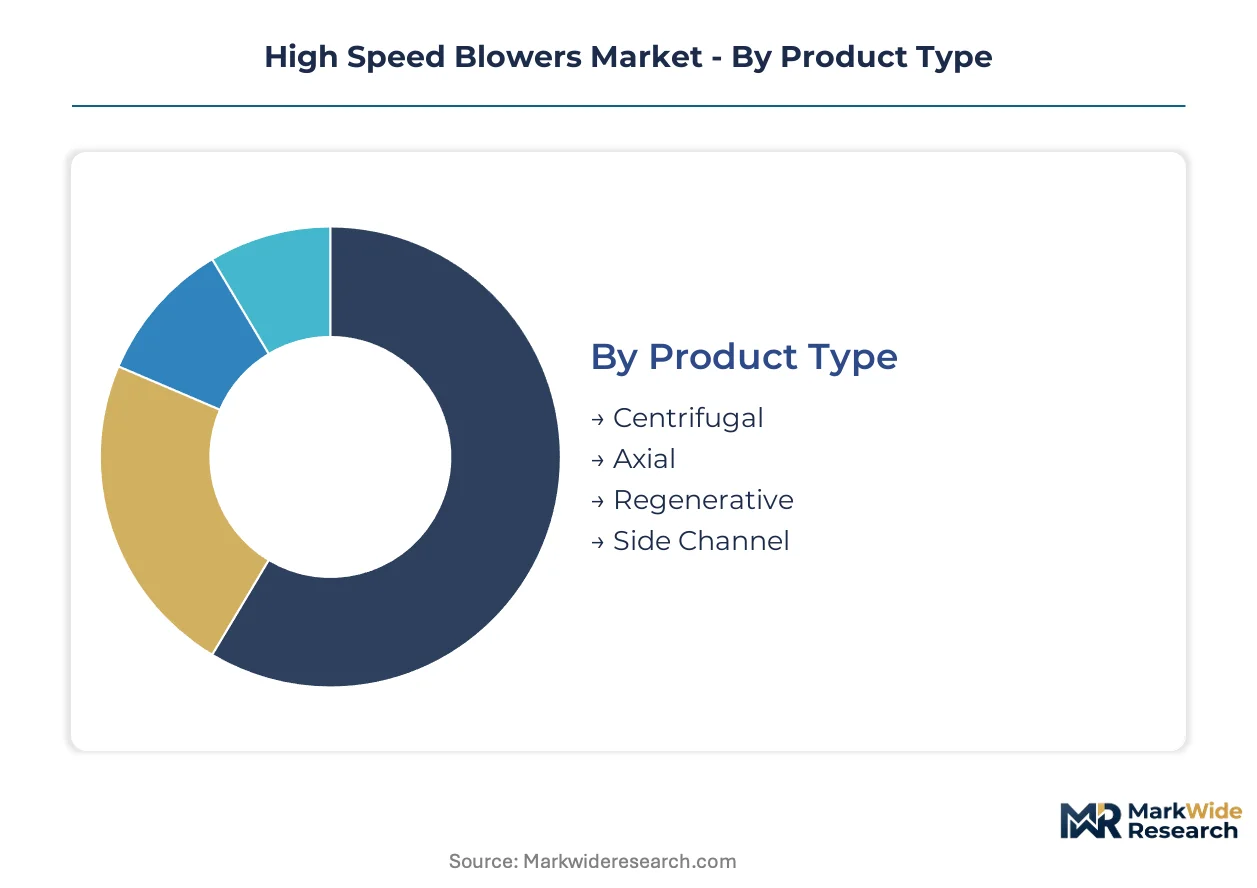
High-speed blower procurement patterns diverge sharply across technology architectures and operational contexts. Municipal operators prioritize energy efficiency certification and magnetic bearing reliability, while industrial buyers balance capital constraints against throughput requirements.
Product Type:
Mature centrifugal designs dominate installed base economics, while emerging bearing technologies are redrawing competitive boundaries in premium power bands.
- Centrifugal:Scalable impeller architectures span 50 to 5,000+ horsepower with oil-free magnetic bearing configurations now displacing multistage gearbox alternatives. German and Chinese wastewater treatment plants are consolidating procurement around these designs to meet tightened nitrogen discharge limits.
- Axial:Compact flow paths suit high-volume, low-pressure aeration where footprint constraints dominate. HVAC retrofit programs in the United States are specifying axial configurations for building automation integration.
- Regenerative:Pulsation-tolerant compression sustains vacuum conveying applications in pharmaceutical packaging lines.
- Side Channel:Single-stage designs serve intermittent pneumatic transport with minimal maintenance overhead.
Centrifugal retains volume leadership; regenerative holds the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive municipal infrastructure from margin-sensitive industrial process lines.
- Wastewater Treatment:Aeration basins consume 60-70% of plant electrical load, making magnetic bearing turbo blowers the default specification for EU Ecodesign Directive compliance. German operators are replacing 1990s-era multistage units under accelerated replacement schedules.
- Manufacturing:Compressed air systems in automotive and electronics assembly require pulsation-free supply with ISO 8573-1 Class 0 oil-free certification. Chinese industrial clusters are upgrading from piston to high-speed centrifugal architectures.
- HVAC:Building automation integration demands variable-speed drives with BACnet connectivity.
- Food Processing:USDA and FDA sanitary standards mandate stainless steel construction with CIP-compatible bearing housings.
Wastewater treatment commands the premium pricing tier; manufacturing delivers the broadest volume base.
Technology:
Application context determines whether electric drive efficiency or pneumatic mechanical simplicity takes precedence.
- Electric:Permanent magnet synchronous motors with active magnetic bearings now exceed 75% efficiency at design point. The US Department of Energy's fan efficiency standards and China's GB 19761 motor grades are filtering out induction motor-pinion combinations from new installations.
- Pneumatic:Explosion-proof operation in chemical processing environments where electrical spark risk is prohibitive.
- Mechanical:Gearbox-driven multistage centrifugal units sustain replacement part revenue in legacy installed bases.
- Hybrid:Combines electric prime movers with mechanical backup for critical aeration redundancy.
Electric dominates new specification authority; hybrid configurations are gaining share fastest in risk-averse municipal procurement.
Installation:
Customer type splits between permanent infrastructure investors and temporary capacity renters.
- Fixed:Permanent concrete pad installations with 20-year asset depreciation schedules anchor municipal wastewater capital planning. Dutch water utilities are unbundling fixed assets from performance guarantees through equipment-as-a-service contracting.
- Permanent:Factory-integrated skids with pre-commissioned controls reduce field installation risk for industrial buyers.
- Mobile:Trailer-mounted turbo blowers serve construction dewatering and emergency bypass aeration.
- Temporary:Rental fleets address seasonal peak loads and plant turnaround maintenance windows.
Fixed installations retain capital commitment dominance; mobile units are climbing the fastest in disaster response and infrastructure gap markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Department of Energy's fan efficiency standards anchor North American procurement patterns, while Germany's Ecodesign Directive implementation and China's GB 19761 motor grades filter conventional equipment from new tenders. Municipal and industrial operators across three continents face synchronized pressure to replace multistage centrifugal architectures.
United States
Wastewater treatment plants in the Great Lakes and Chesapeake Bay watersheds are accelerating aeration capacity upgrades to meet EPA nitrogen discharge limits. The US Department of Energy's fan efficiency standards are filtering induction motor-pinion combinations from municipal procurement specifications. Chicago and Milwaukee industrial clusters are consolidating compressed air system retrofits around magnetic bearing turbo blowers to capture IRA clean energy manufacturing tax credits.
Germany
Ruhr Valley wastewater utilities are replacing 1990s-era multistage units under tightened effluent standards for phosphorus removal. The EU Ecodesign Directive's minimum efficiency thresholds for fans above 10 kW are excluding gearbox-driven designs from public tenders. Bavarian engineering procurement specifications now explicitly exclude refrigerant-cooled motor options above 315 kW, redirecting demand toward liquid-cooled permanent magnet architectures.
China
Yangtze River Delta municipal authorities are expanding aeration basins to meet MEE surface water quality standards for total nitrogen. GB 19761 motor efficiency grades are accelerating displacement of induction motor-pinion combinations in new installations. Suzhou and Hangzhou industrial parks are upgrading process gas systems as domestic rare earth magnet sourcing initiatives stabilize permanent magnet supply chains.
India
The AMRUT 2.0 scheme's 100% sewage connectivity target for 500 cities is creating first-mover positioning for energy-efficient aeration equipment. Central Electricity Authority efficiency guidelines are filtering conventional multistage designs from state-level water utility tenders. Maharashtra and Gujarat municipal corporations are piloting equipment-as-a-service contracting models that transfer operational risk to OEM service arms.
Netherlands
Dutch water utilities are unbundling blower assets from 20-year performance guarantees through equipment-as-a-service restructuring. REACH compliance requirements for lubricant alternatives and magnet coatings are extending certification timelines for new product introductions. Randstad region treatment plants are specifying active magnetic bearing architectures to eliminate oil contamination risk from seal failures in sensitive delta ecosystems.
High Speed Blowers Market Vendor Landscape
Integrated solution providers and component-specialist vendors split the market along the fault line of service bundling versus equipment-only supply. The vendor base concentrates among European engineering conglomerates with magnetic bearing heritage, North American distribution networks with integrated service capabilities, and Asian fabricators competing on manufacturing proximity. Three archetypes dominate: premium-tier magnetic bearing OEMs, mid-market centrifugal specialists, and regional service-integrated distributors. Competitive moves center on strategic partnerships for bearing controller technology and geographic expansion through municipal utility privatization waves.
Among European engineering conglomerates, Atlas Copco AB and Kaeser Kompressoren SE exemplify the premium-tier magnetic bearing OEM archetype, leveraging compressor technology heritage to anchor municipal wastewater specifications. Gardner Denver Inc. occupies a position within the North American service-integrated distribution tier, anchoring regional procurement through aftermarket network density. Aerzen Turbo Co., Ltd represents the specialized turbo blower fabricant archetype, concentrating engineering resources on aeration-optimized impeller architectures.
| Leading Market Players |
|---|
| Atlas Copco AB |
| Aerzen Turbo Co., Ltd |
| APG Neuros, Inc |
| Gardner Denver Inc. |
| Kaeser Kompressoren SE |
| Continental Industries |
| Howden North America, Inc |
| Atlantic Blower |
| Eminent Blowers |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese rare earth magnet refining corridors is compressing permanent magnet motor pricing while simultaneously constraining OEM scaling capacity through export quota volatility. This utilization asymmetry forces blower manufacturers to absorb input cost swings while maintaining competitive positioning across municipal and industrial procurement channels.
Pricing Analysis
Geographic price spreads between German-engineered magnetic bearing systems and Chinese-fabricated alternatives span premium-mid-economy pricing differentiation driven by certification grade and after-sales service bundling. EU Ecodesign Directive compliance and REACH registration requirements add certification premiums to European-sourced equipment. Cost compression in mid-market centrifugal tiers is intensifying because domestic rare earth sourcing initiatives in China are stabilizing permanent magnet supply chains. Municipal wastewater operators demonstrate the least price sensitivity due to 20-year asset depreciation schedules, while industrial manufacturing buyers prioritize capital constraints over efficiency premiums.
Supply Chain Analysis
Upstream feedstock concentration in Chinese rare earth processing corridors and Japanese magnetic bearing controller fabrication anchors component availability for permanent magnet synchronous motors. Neodymium magnet supply draws from Chinese refining infrastructure while active magnetic bearing sensors source from European and Japanese specialist firms. Single-source vulnerability in magnetic bearing controller supply chains constrains OEM production scaling during demand surges. Distribution runs through OEM-direct procurement channels for municipal infrastructure and integrated service networks for industrial aftermarket support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The high speed blowers market is entering a cyclical recovery phase as municipal wastewater infrastructure replacement cycles converge with EU Ecodesign Directive compliance deadlines. Equipment-as-a-service contracting restructuring is compressing traditional capital purchase patterns and redirecting procurement authority toward integrated solution providers.
For Market Incumbents: Build regulatory certification moats through accelerated REACH compliance and EU Ecodesign Directive pre-certification to exclude emerging competitors from European public tenders. Secure captive supply of magnetic bearing controllers through strategic partnerships with Japanese and European specialist firms to mitigate single-source vulnerability. Expand aftermarket service network density in North American industrial clusters to defend against distributor-led competitive pressure. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia and municipal sanitation expansion under India's AMRUT 2.0 scheme represent the most penetrable entry points for energy-efficient aeration equipment. Biogas upgrading integration in agricultural waste facilities offers process gas compression applications with lower incumbent saturation. Pursue equipment-as-a-service contracting models to bypass capital procurement barriers and transfer operational risk acceptance to OEM service arms. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across magnetic bearing turbo blower manufacturing as rare earth magnet cost stabilization and domestic sourcing initiatives reduce input volatility. Acquisition targets should prioritize specialized turbo blower fabricants with aeration-optimized impeller architectures and established municipal utility relationships. Monitor magnetic bearing vendor scarcity as the critical inflection signal for OEM scaling constraints and pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Magnetic Bearing Technology Partnership | Secures controller supply from Japanese and European specialist firms against single-source risk. |
| Equipment-as-a-Service Contracting | Captures Dutch and Danish utility restructuring toward performance-guaranteed operational risk transfer. |
| Domestic Rare Earth Sourcing | Leverages Chinese permanent magnet supply chain stabilization for cost-competitive electric drive production. |
| REACH Compliance Pre-Certification | Accelerates European market entry ahead of ECHA registration timelines that delay competitors. |
| Biogas Upgrading System Integration | Opens process gas compression in agricultural waste facilities with membrane-based purification convergence. |
Methodological Framework
Cross-validation between primary interviews with municipal wastewater plant engineers, OEM procurement managers, aftermarket service heads, and magnetic bearing specialists and secondary validation through SEC 10-K filings, customs trade data, and EU Ecodesign Directive implementation reports anchors the qualitative findings. Bottom-up segmentation modeling triangulates against top-down macroeconomic indicators across the analysis window.
Calibration against historical replacement cycle data and regulatory compliance deadline clustering informs the projection framework. Segmentation dimensions span product architecture, end-use application, bearing technology type, and regional regulatory cluster. CAGRs derive from installed base turnover rates and efficiency standard phase-in schedules, incorporating permanent magnet motor adoption curves and magnetic bearing penetration assumptions.
Macroeconomic conditions sit as an overlay; deviation in rare earth commodity prices, export quota policies, or municipal capital expenditure cycles would shift the trajectory. Cross-checking against EPA and MEE effluent standard enforcement intensity is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Asia-Pacific Compressor Oil Market
Compressors
Oil-Free Air Compressor Market
Compressors
CNG Compressor Market
Compressors
Integrally Geared Centrifugal Compressor Market
Compressors
USA Scroll Compressor Market
Compressors
Centrifugal Compressors Market
Compressors
Europe Centrifugal Compressor Market
Compressors
Bus Compressor Market
Compressors
Oil Free Compressor Market
Compressors
Turbocompressor Market
Compressors
Rotary Air Compressor Market
Compressors
Compressed Air Filtration and Dryer System Market
Compressors
Europe Compressor Market
Compressors
Industrial Air Compressor Market
Compressors
Positive Displacement Gas Compressor Market
Compressors
Gas Compressors Market