
 Mud Mixers Market | 2026-2036
Mud Mixers Market Size, Share, and Industry Trends Forecast 2026-2036
Mud Mixers Market Analytics
Market Context
The gap between premium automated mud mixing systems and commodity portable units is realigning procurement patterns across energy and construction verticals. Schlumberger NV leverages its integrated drilling solutions portfolio to anchor premium positioning in offshore contracts. GN Solids Control Co. competes through specialized solids control integration that extends mixer lifecycle in high-abrasion environments. Xuzhou Construction Machinery Co. Ltd. dominates the stationary mixer segment for infrastructure projects across Asia.
Technical Definition and Segment Structure
A mud mixer is a mechanical device engineered to homogenize drilling fluids, cement slurries, or soil amendments through controlled shear forces typically operating at 50-1,500 RPM with power ratings from 5 to 200 horsepower. The equipment ensures consistent rheological properties critical to wellbore stability, zonal isolation, and cuttings transport in subsurface operations. Portable mixers lead volume in construction applications where site mobility governs equipment selection, while high-volume stationary systems command margin pools in oil and gas central processing facilities. Electromechanical technology occupies the fastest-expanding tier as variable-frequency drives improve energy efficiency against pneumatic alternatives in fixed installations.
Regulatory Environment
EPA offshore emissions standards and OSHA silica exposure limits shape equipment design requirements for US-manufactured and imported mud mixing systems. The EU F-Gas Regulation constrains hydraulic system refrigerant choices for European-deployed equipment, while China's MEE enforcement of GB standards elevates local environmental compliance costs. Stakeholders must monitor how divergent energy efficiency mandates across the US, Europe, and China fragment certification requirements and complicate platform standardization strategies.
Market Dynamics
Automated mud mixing systems are compressing the operational gap between offshore deepwater rigs and onshore pad drilling sites, forcing equipment manufacturers to reconcile divergent performance specifications within unified product architectures.
Growth Catalysts
- EPA offshore emissions standards:The regulatory push for closed-loop hydraulic designs is accelerating replacement cycles for legacy pneumatic systems in Gulf of Mexico operations.
- Pad drilling intensity:Permian Basin operators require continuous drilling fluid supply chains that sustain 24-hour mixing cycles across multi-well pads.
- Variable-frequency drive technology:Electromechanical systems with precision RPM control are capturing fixed-installation contracts previously held by pneumatic alternatives.
Market Restraints
- Specialized alloy supply concentration:High-abrasion mixer components depend on nickel-chromium steel sourcing concentrated in select metallurgical centers.
- EU F-Gas Regulation compliance costs:European-deployed hydraulic systems face constrained refrigerant choices that inflate engineering redesign expenses.
- Pneumatic system residual base:Existing installed capacity in mature oilfields creates substitution friction against electromechanical upgrades.
Strategic Opportunities
- Geothermal drilling expansion:Heat-resistant mixer designs developed for oil and gas applications transfer directly into geothermal well construction in Iceland and Kenya.
- China MEE enforcement trajectory:Stricter GB standards implementation creates first-mover advantage for manufacturers with pre-certified environmental compliance packages.
- Remote monitoring convergence:Integration of IoT sensors with legacy mixer fleets enables predictive maintenance contracts in unmanned offshore platforms.
Industry Challenges
- Cross-disciplinary engineering talent:Mud mixer design now requires simultaneous fluency in rheology, hydraulics, and automation controls.
- Legacy system integration complexity:Retrofitting variable-frequency drives into existing pneumatic infrastructure demands custom electrical engineering.
- Multi-jurisdiction certification timelines:Simultaneous EPA, CE marking, and GB standard approvals extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mud Mixers Market |
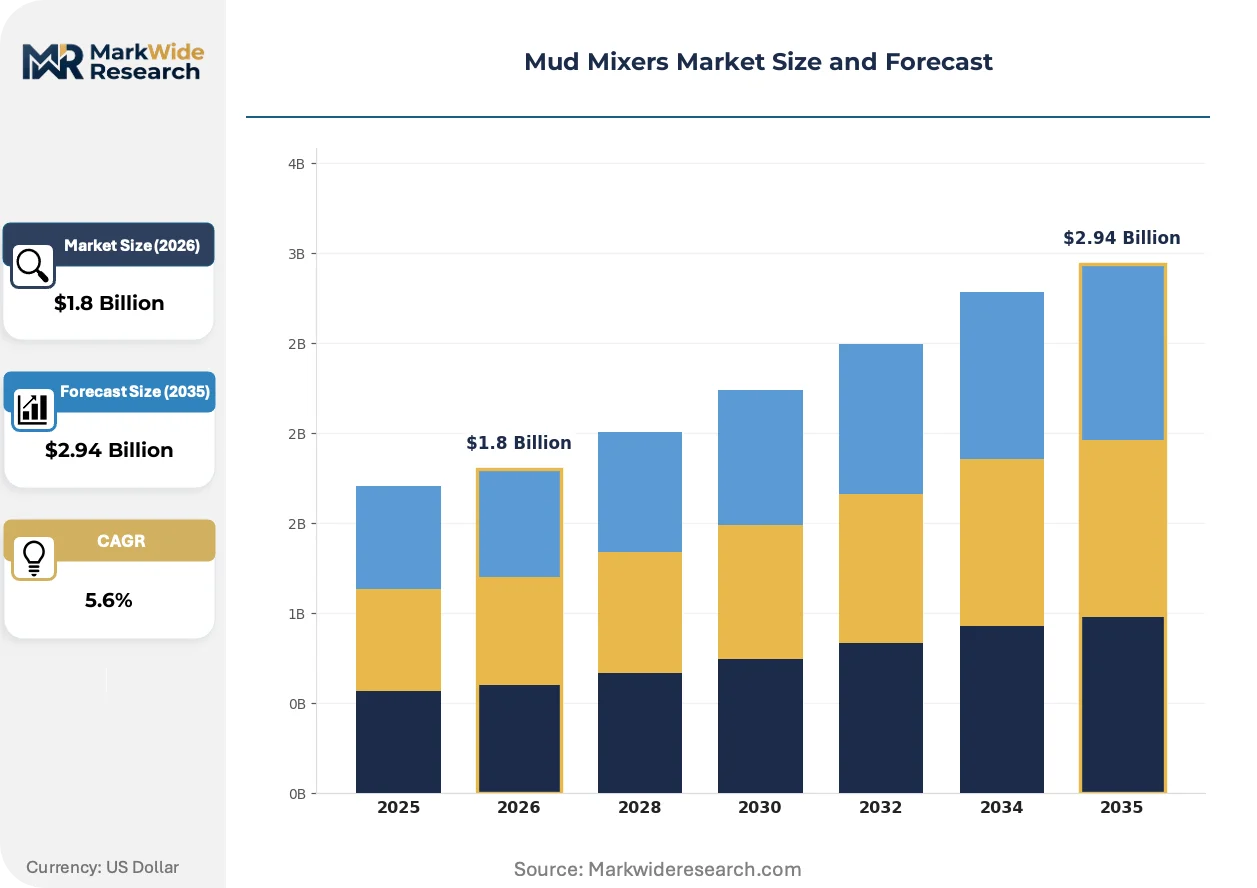
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Mixers, Stationary Mixers, Paddle Mixers, High-Volume Mixers End User: Construction, Oil & Gas, Agriculture, Mining Technology: Electromechanical, Hydraulic, Pneumatic, Manual Application: Cement Mixing, Drilling Mud Preparation, Soil Stabilization, Waste Treatment |
| Companies Covered | Schlumberger NV, GN Solids Control Co., Xuzhou Construction Machinery Co. Ltd., Xi'An TianRui Petroleum Machinery Equipment Co. Ltd., EBARA HG, RYOBI Limited, AMC Drilling Optimization Company, Kraft Tool Co., EZG Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mud Mixers Market Evolving Landscape
Digitalization of fluid property monitoring is redefining how operators specify mixer performance, shifting procurement criteria from mechanical durability to real-time data integration capabilities.
Shear-controlled mixing technology is consolidating discrete unit operations into single-vessel systems. Offshore contractors in the Gulf of Mexico are specifying these integrated platforms for newbuild deepwater rigs. The technology is consolidating vendor relationships by eliminating separate hydration unit suppliers from equipment packages.
OSHA silica exposure limits are forcing construction-grade mixer redesigns with sealed hopper systems and negative-pressure dust containment. Infrastructure contractors face capital allocation decisions between retrofitting existing portable units or accelerated replacement schedules. US-based rental fleet operators are most affected, with equipment pools requiring systematic upgrades to maintain site access.
Rental and service-based contracting is displacing outright equipment purchases in North American construction verticals. Equipment lessors are capturing margin through bundled maintenance and fluid testing services. The shift is most visible in Texas and Oklahoma infrastructure markets where project duration uncertainty favors operational expenditure models.
Mud Mixers Market Segmentation
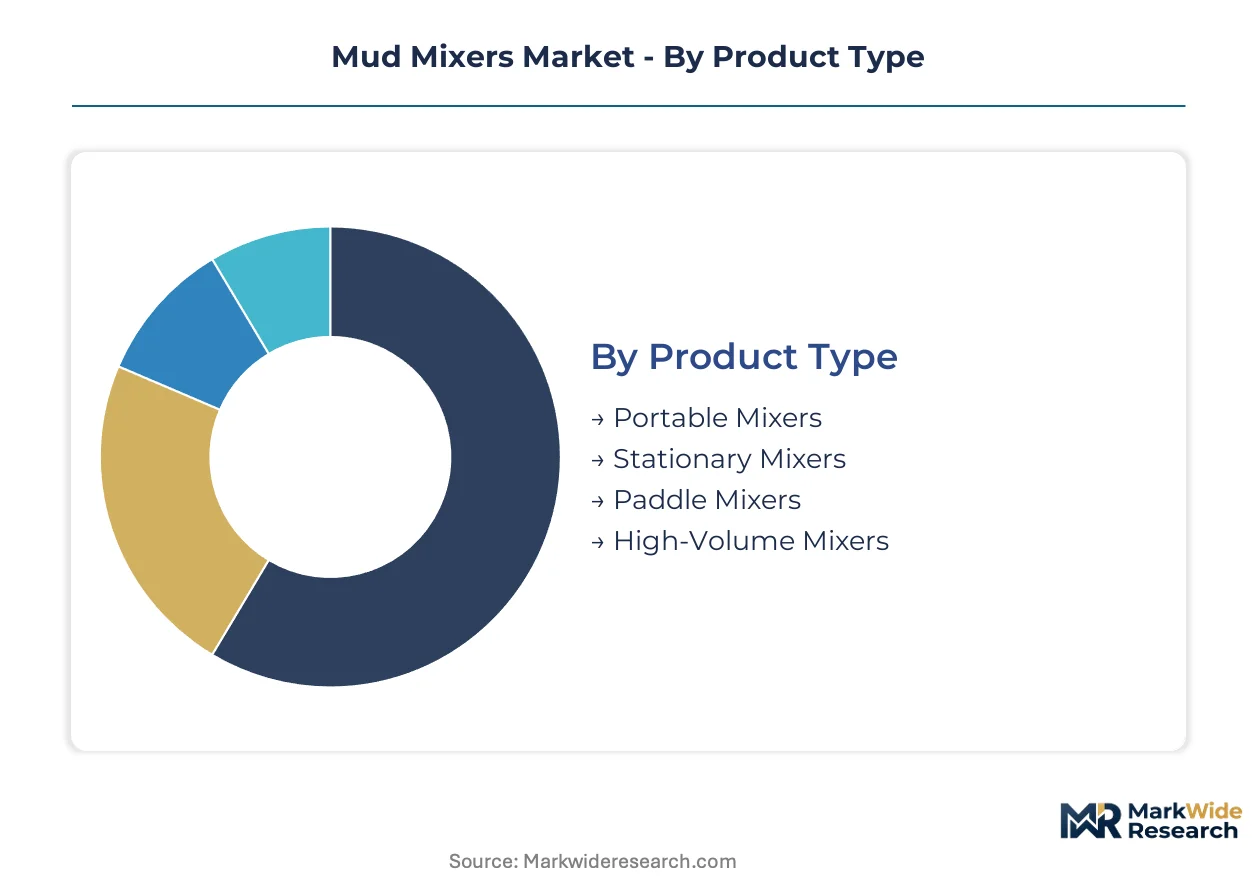
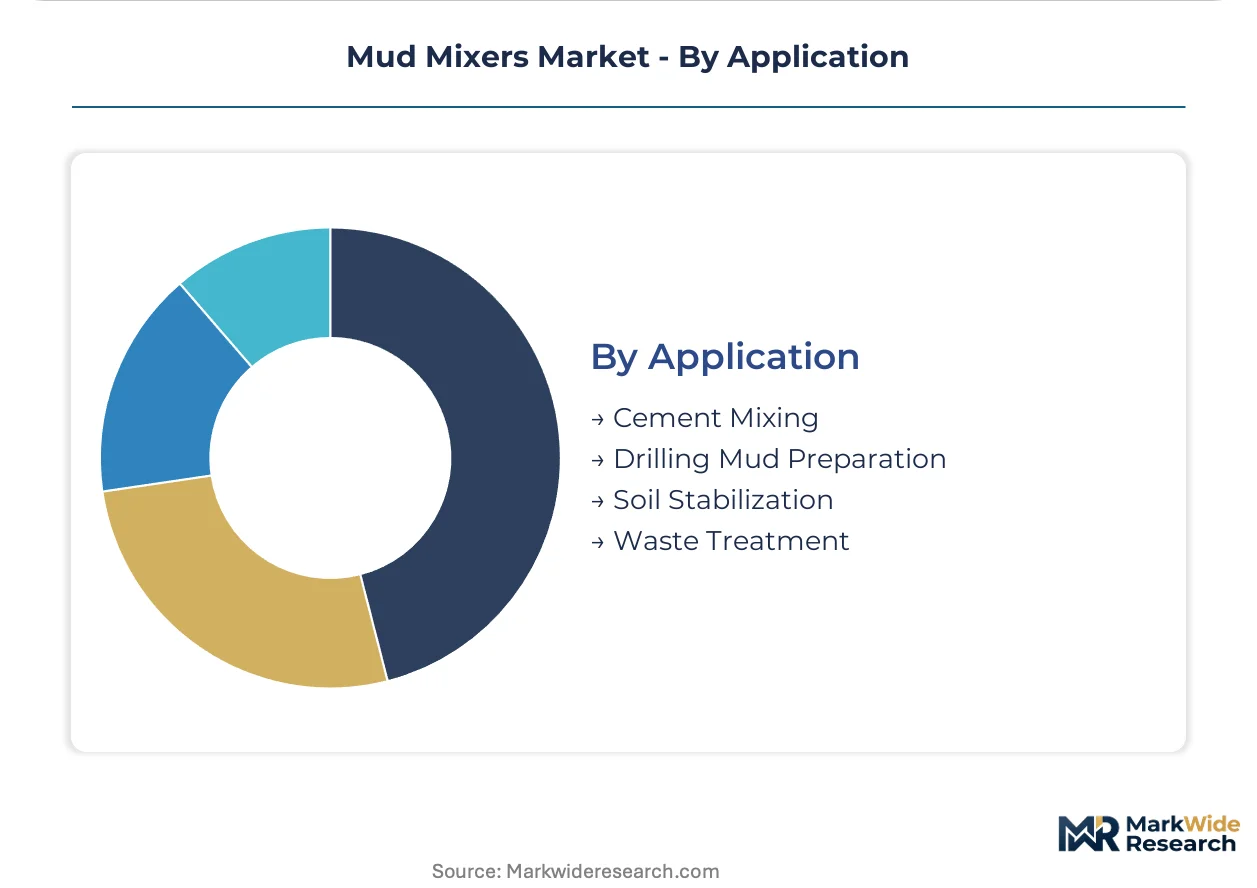
Mud mixer procurement patterns diverge sharply across application environments, with oil and gas operators prioritizing continuous-duty specifications while construction contractors optimize for site mobility. Understanding these segment boundaries clarifies why technology choices and pricing tiers fail to translate across end-use verticals.
Product Type:
Supply concentration in high-volume stationary systems has concentrated manufacturing capacity among integrated drilling solution providers, while portable mixer production fragments across regional fabrication shops.
- Portable Mixers:Self-contained units mounted on skids or trailers deliver 5-50 horsepower output for construction sites requiring rapid relocation. Infrastructure contractors in Texas and Oklahoma favor rental fleet procurement of these units to manage project duration uncertainty.
- Stationary Mixers:Fixed-installation systems operating at 50-200 horsepower anchor central processing facilities in oil and gas operations. Permian Basin pad drilling intensity sustains 24-hour mixing cycles that demand this equipment class.
- Paddle Mixers:Low-shear designs suit cement slurry preparation where gentle blending preserves additive integrity.
- High-Volume Mixers:Continuous-flow architectures handle throughput rates exceeding 500 gallons per minute for offshore deepwater rig supply.
Stationary mixers absorb the bulk of installed capacity; portable mixers are expanding most quickly through rental channel penetration in North American construction markets.
End User:
Cost tier differentiation separates premium automated systems serving capital-intensive extraction industries from commodity equipment purchased by price-sensitive agricultural operators.
- Construction:Project-based demand cycles drive preference for leased equipment with bundled maintenance services. OSHA silica exposure limits are forcing sealed hopper redesigns across US rental fleets.
- Oil & Gas:Offshore deepwater contracts specify integrated shear-controlled mixing platforms that consolidate vendor relationships. EPA emissions standards accelerate replacement of legacy pneumatic systems in Gulf of Mexico operations.
- Agriculture:Seasonal soil amendment applications favor lower-capital manual and small electromechanical units.
- Mining:High-abrasion tailings processing requires specialized alloy components with extended lifecycle ratings.
Oil and gas commands the premium pricing tier; construction is gaining share fastest through operational expenditure contracting models.
Technology:
Application environment dictates technology selection, with fixed installations favoring precision control while remote sites prioritize pneumatic reliability independent of electrical infrastructure.
- Electromechanical:Variable-frequency drive systems deliver 50-1,500 RPM precision control with superior energy efficiency metrics. These units are displacing pneumatic alternatives in fixed installations where grid power is assured.
- Hydraulic:Closed-loop designs satisfy EPA offshore emissions standards through contained fluid circuits. EU F-Gas Regulation compliance costs constrain refrigerant choices for European-deployed equipment in this category.
- Pneumatic:Compressed-air operation persists in mature oilfields where electrical retrofitting costs exceed replacement economics.
- Manual:Human-powered units serve small-scale agricultural and remote construction applications with minimal capital requirements.
Electromechanical systems absorb the bulk of new fixed-installation demand; hydraulic configurations are expanding most quickly in regulated offshore environments.
Application:
Volume concentration in drilling mud preparation reflects oil and gas capital expenditure dominance, while waste treatment applications emerge from environmental compliance spending.
- Cement Mixing:Construction-grade paddle and portable mixer deployment supports infrastructure project timelines where batch consistency governs structural integrity.
- Drilling Mud Preparation:Rheological property control ensures wellbore stability and cuttings transport in subsurface operations. Shear-controlled technology consolidates hydration and mixing into single-vessel systems for Gulf of Mexico newbuild rigs.
- Soil Stabilization:Agricultural and civil engineering applications blend amendments for erosion control and foundation preparation.
- Waste Treatment:Contaminated soil and drilling waste processing requires specialized mixing for chemical fixation and bioremediation.
Drilling mud preparation absorbs the bulk of equipment value; waste treatment is expanding most quickly through environmental remediation project growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midland-Odessa anchors the most intensive mud mixer deployment globally, where Permian Basin pad drilling sustains continuous 24-hour mixing cycles across multi-well sites. This Texas cluster concentrates demand for high-volume stationary systems and automated fluid supply chains. Regulatory pressure from EPA offshore emissions standards simultaneously reshapes equipment specifications in Gulf of Mexico deepwater operations.
United States
Pad drilling intensity in the Permian Basin and Bakken Formation drives replacement cycles for legacy pneumatic systems. EPA offshore emissions standards mandate closed-loop hydraulic designs for Gulf of Mexico newbuild rigs. The Houston-Galveston corridor hosts the densest concentration of drilling fluid service companies and integrated equipment lessors.
China
MEE enforcement of GB standards elevates environmental compliance costs for hydraulic system manufacturers serving domestic oilfields. Xuzhou Construction Machinery anchors stationary mixer production for infrastructure projects across the Yangtze River Delta. Sinopec and CNOOC procurement specifications increasingly favor electromechanical systems with variable-frequency drive technology.
Norway
Equinor's North Sea electrification program accelerates demand for grid-connected mud mixing systems on offshore platforms. The country's petroleum regulator enforces stricter emissions thresholds than EU baseline requirements. Stavanger-Bergen corridor engineering firms specialize in retrofitting legacy pneumatic infrastructure for closed-loop hydraulic operation.
Saudi Arabia
Aramco's gas expansion and unconventional drilling programs sustain import demand for high-abrasion mixer components. The national petroleum regulator mandates equipment certification aligned with API specifications for all new drilling contracts. Dammam-Khobar industrial zone hosts regional fabrication capacity serving Eastern Province oilfield operations.
Brazil
Pre-salt deepwater development drives specification of shear-controlled single-vessel mixing platforms for floating production units. ANP local content requirements pressure international suppliers to partner with domestic fabricators. Macaé-Rio de Janeiro corridor concentrates offshore equipment integration and maintenance service providers.
Mud Mixers Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the technology-automation spectrum, with integrated drilling solution providers commanding offshore contract premiums while regional fabricators compete on portable unit price. The vendor base stratifies into three tiers: full-service energy technology conglomerates, specialized solids control equipment manufacturers, and construction machinery generalists. Two dominant competitive moves define current positioning: strategic partnerships between mixer specialists and drilling fluid service companies, and geographic expansion through rental fleet acquisitions in North American shale plays.
Within the integrated energy technology tier, Schlumberger NV exemplifies full-service positioning through bundled drilling solutions. GN Solids Control Co. and Xuzhou Construction Machinery Co. Ltd. occupy distinct specialization vectors—one in solids control integration, the other in infrastructure-scale stationary systems. These three entities represent the archetype spread: conglomerate-integrated, application-specialized, and construction-focused respectively.
| Leading Market Players |
|---|
| Schlumberger NV |
| GN Solids Control Co. |
| Xuzhou Construction Machinery Co. Ltd. |
| Xi'An TianRui Petroleum Machinery Equipment Co. Ltd. |
| EBARA HG |
| RYOBI Limited |
| AMC Drilling Optimization Company |
| Kraft Tool Co. |
| EZG Manufacturing |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up rental fleet operators in North American shale plays exert pricing discipline through operational expenditure bundling, compressing margins for commodity portable mixer manufacturers while reinforcing premium positioning for automated system providers serving integrated drilling contracts.
Pricing Analysis
Throughput-based pricing anchors offshore deepwater contracts where operators tie payments to continuous drilling fluid availability rather than equipment ownership. Three-tier pricing structure across premium automated platforms, standard electromechanical units, and economy pneumatic systems separates oil and gas procurement from construction rental markets. Cost compression in the portable segment is intensifying because OSHA silica compliance upgrades force capital reinvestment without corresponding rate increases. Construction contractors exhibit highest price sensitivity through rental channel preference, while Aramco and Equinor specifications demonstrate lowest sensitivity to upfront capital outlays.
Supply Chain Analysis
Nickel-chromium steel supply rests on metallurgical centers in Germany, Japan, and China, with specialized alloy sourcing for high-abrasion mixer components concentrated among a limited supplier base. Variable-frequency drive assemblies draw from South Korean and German electrical component manufacturers, while hydraulic system refrigerants face constrained availability under EU F-Gas Regulation limits. Single-source vulnerability in specialty alloy procurement creates exposure to export restriction shocks. Distribution runs through integrated drilling solution providers for offshore contracts and regional equipment lessors for onshore construction markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mud mixer market is becoming a vertical-integration race as manufacturers pursue captive supply of nickel-chromium alloy components to secure margin control against metallurgical supply concentration.
For Market Incumbents: Deepen solids control integration capabilities to defend against shear-controlled single-vessel platforms that eliminate separate hydration unit suppliers from Gulf of Mexico newbuild specifications. Secure backward integration into specialty alloy sourcing to mitigate nickel-chromium supply concentration risk. Anchor premium positioning through predictive maintenance service contracts enabled by IoT sensor integration on legacy fleet retrofits. For New Entrants and Emerging Players: The gap between premium automated offshore systems and commodity portable construction units offers entry space for mid-tier electromechanical platforms targeting Permian Basin pad drilling operators. Target waste treatment applications where environmental remediation project growth outpaces established vendor coverage. Pursue rental fleet acquisition strategies in Texas and Oklahoma infrastructure markets to bypass direct OEM competition. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized solids control equipment manufacturers with pre-certified EPA compliance packages in Gulf Coast corridor geographies. Long-term viability hinges on automation convergence and regulatory pre-positioning across multiple jurisdiction standards. Monitor MEE enforcement trajectory in China as inflection indicator for first-mover advantage in environmental compliance bundling.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Supply | Captive nickel-chromium sourcing secures margin control against metallurgical concentration in Germany and Japan. |
| Closed-Loop Hydraulic System Development | EPA offshore emissions compliance enables Gulf of Mexico contract access for newbuild deepwater rig specifications. |
| IoT Sensor Platform Integration | Predictive maintenance contracts capture recurring revenue from unmanned offshore platform installations. |
| Rental Fleet Geographic Expansion | Texas and Oklahoma equipment lessor acquisitions bypass direct OEM price competition in construction verticals. |
| Shear-Controlled Single-Vessel Consolidation | Hydration-mixing integration eliminates separate unit suppliers from Equinor and Aramco procurement packages. |
Research Methodology
Multi-period observation of pad drilling intensity indicators, EPA compliance upgrade cycles, and rental fleet utilization rates anchored the trend analysis, supplemented by interviews with drilling fluid service company procurement directors, offshore platform maintenance engineers, construction equipment lessor operations managers, and metallurgical supply specialists. Secondary validation drew from SEC 10-K filings of integrated energy technology providers, EIA drilling activity databases, ACC equipment demand reports, and customs trade records for alloy component imports. Bottom-up field deployment tracking and top-down capital expenditure analysis were triangulated to reconcile volume estimates.
Input-output matrix modeling connected drilling rig count projections to mixer replacement demand across portable, stationary, and high-volume system categories. Segmentation dimensions included product mobility tier, end-use vertical, power source technology, and regional regulatory framework cluster. CAGRs were derived from fitted trend extrapolation validated against historical replacement cycle patterns. Forecast inputs incorporated Permian Basin well completion schedules, Norwegian North Sea electrification timelines, and China MEE enforcement phase-ins.
Underlying measurement precision varies by segment; offshore deepwater contract specifications carry tighter precision than fragmented construction rental markets. Forecasts reflect documented assumptions regarding regulatory implementation pacing and commodity alloy pricing stability. Abrupt shifts in EPA enforcement stringency or nickel export restrictions from key metallurgical centers warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil and Gas Hose Assemblies Market
Oil & Gas
Southeast Asia LNG Market
Oil & Gas
South-East Asia Oil and Gas Pipeline Market
Oil & Gas
Pipeline Integrity Market
Oil & Gas
Electric Fracking Market
Oil & Gas
Oil and Gas Field Services Market
Oil & Gas
Russia Oil and Gas EPC Market
Oil & Gas
Vietnam Oil and Gas Midstream Market
Oil & Gas
Flexible Pipes for Oil and Gas Market
Oil & Gas
Asia-Pacific Oilfield Auxiliary Rental Equipment Market
Oil & Gas
Colombia Oil and Gas Downstream Market
Oil & Gas
Asia-Pacific Oil Country Tubular Goods Market
Oil & Gas
Digital Oilfield Market
Oil & Gas
Brazil Oil and Gas Midstream Market
Oil & Gas
Central Asia Oil and Gas Market
Oil & Gas
Europe Oilfield Services Market