
 Power Stacker Market | 2026-2036
Power Stacker Market Size, Share, and Industry Trends Forecast 2026-2036
Power Stacker Market Analytics
Chinese OEM capacity expansion is rebalancing regional supply availability for material handling equipment. Jungheinrich AG leverages its European manufacturing footprint to sustain premium positioning in automated warehouse solutions. Crown Equipment Corporation differentiates through integrated battery and charger technology leadership. EP Equipment competes aggressively on cost-optimized electric stacker designs for emerging market distributors.
A power stacker is a motorized or manually operated vertical lifting device designed to transport and stack palletized loads, typically featuring mast heights exceeding three meters and load capacities ranging from 1000 kg to 2500 kg. The equipment serves as essential infrastructure in warehousing and manufacturing environments where vertical storage density and floor-space efficiency determine operational throughput. Electric power stackers now dominate procurement budgets across the application spectrum, while lithium-ion variants capture the fastest-growing share as facilities phase out lead-acid battery maintenance regimes. Warehousing applications anchor the largest volume segment, though e-commerce end users generate the highest margin pools due to fleet standardization requirements and 24-hour utilization cycles.
OSHA workplace safety standards in the United States and CE machinery directives in Europe mandate operator protection systems and electromagnetic compatibility certification, directly shaping R&D allocation for control system redesigns. China's GB standards and SAMR quality supervision protocols impose additional testing burdens for imported equipment, creating compliance-based segmentation between domestic and export-oriented manufacturers. Stakeholders must monitor battery chemistry regulations and regional carbon border adjustments to anticipate fleet procurement timing and supplier qualification requirements.
Market Dynamics
Electric power stackers are displacing internal combustion models as warehouse operators face carbon accounting mandates and total cost of ownership pressures from lithium-ion battery economics.
Growth Catalysts
- E-commerce fulfillment density:Third-party logistics providers in the United States are expanding vertical storage configurations to maximize cubic utilization, directly stimulating mast height and reach specifications.
- REACH chemical restrictions:European battery recycling directives are accelerating lead-acid phase-outs, forcing fleet managers toward sealed lithium-ion architectures with zero maintenance protocols.
- Lithium-ion chemistry maturation:Cell production scale-up in South Korea and Japan is compressing battery pack costs below lead-acid parity on a lifecycle basis.
Market Restraints
- Steel and copper input volatility:Mast fabrication and motor winding costs fluctuate with commodity exchanges, squeezing margin predictability for mid-tier manufacturers.
- Controller semiconductor concentration:Power electronics sourcing depends on Taiwanese foundry capacity, exposing lead times to geopolitical disruption.
- Lead-acid infrastructure lock-in:Existing charging bay investments and maintenance staffing create switching friction for facilities with depreciated battery fleets.
Strategic Opportunities
- India warehousing formalization:Organized retail expansion and GST compliance are creating first-time demand for motorized handling equipment in Tier-2 distribution hubs.
- Autonomous navigation convergence:LiDAR and vision systems are integrating with stacker chassis to enable goods-to-person automation without fixed infrastructure.
- California CARB mandates:Warehouse emissions rules are creating regulatory pull for zero-emission equipment ahead of federal requirements.
Industry Challenges
- High-voltage technician scarcity:Lithium-ion service and thermal event response require certified specialists that vocational programs have not yet scaled to produce.
- CE machinery directive certification timelines:Electromagnetic compatibility testing and notified body queue delays extend product launch windows by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Stacker Market |
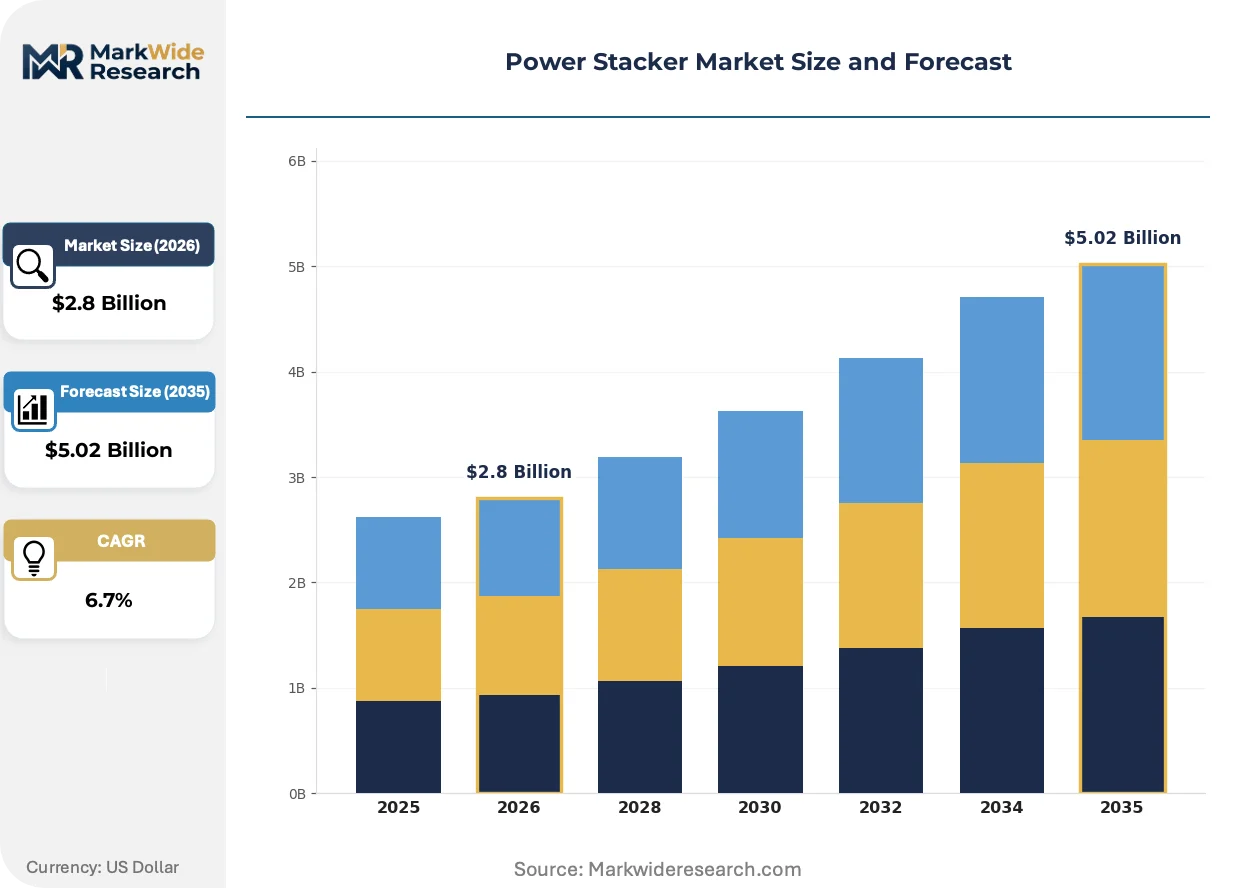
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Power Stacker, Manual Power Stacker, Semi-electric Power Stacker, Lithium-ion Power Stacker Application: Warehousing, Manufacturing, Retail, Logistics End User: Retailers, E-commerce, Freight Companies, Industrial Users Capacity: 1000 kg, 1500 kg, 2000 kg, 2500 kg |
| Companies Covered | Toyota Industries Corporation, Jungheinrich AG, Crown Equipment Corporation, Linde Material Handling, Hyster-Yale Materials Handling, EP Equipment, Godrej Material Handling, Doosan Industrial Vehicle, Kion Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Stacker Market Evolving Landscape
Equipment intelligence and energy architecture are converging to redefine operational economics, with automation readiness and battery chemistry emerging as primary purchase criteria.
Telematics platforms are integrating predictive maintenance algorithms that monitor hydraulic cycle counts and motor thermal profiles. E-commerce operators with 24-hour utilization schedules are adopting these systems fastest. This capability is integrating fleet management software directly into procurement specifications, displacing standalone equipment purchases.
The EU Green Deal's carbon border adjustment mechanism is reshaping equipment import economics. Manufacturers exporting to Europe must document embedded emissions across steel and battery supply chains. German automotive suppliers with existing sustainability audit infrastructure are qualifying suppliers most aggressively.
Equipment-as-a-service contracts are compressing capital expenditure barriers for mid-size warehousing operations. Third-party logistics providers near Chicago and Dallas are replacing ownership models with per-pallet-move pricing. This shift is most visible among facilities with seasonal volume volatility seeking balance sheet flexibility.
Power Stacker Market Segmentation
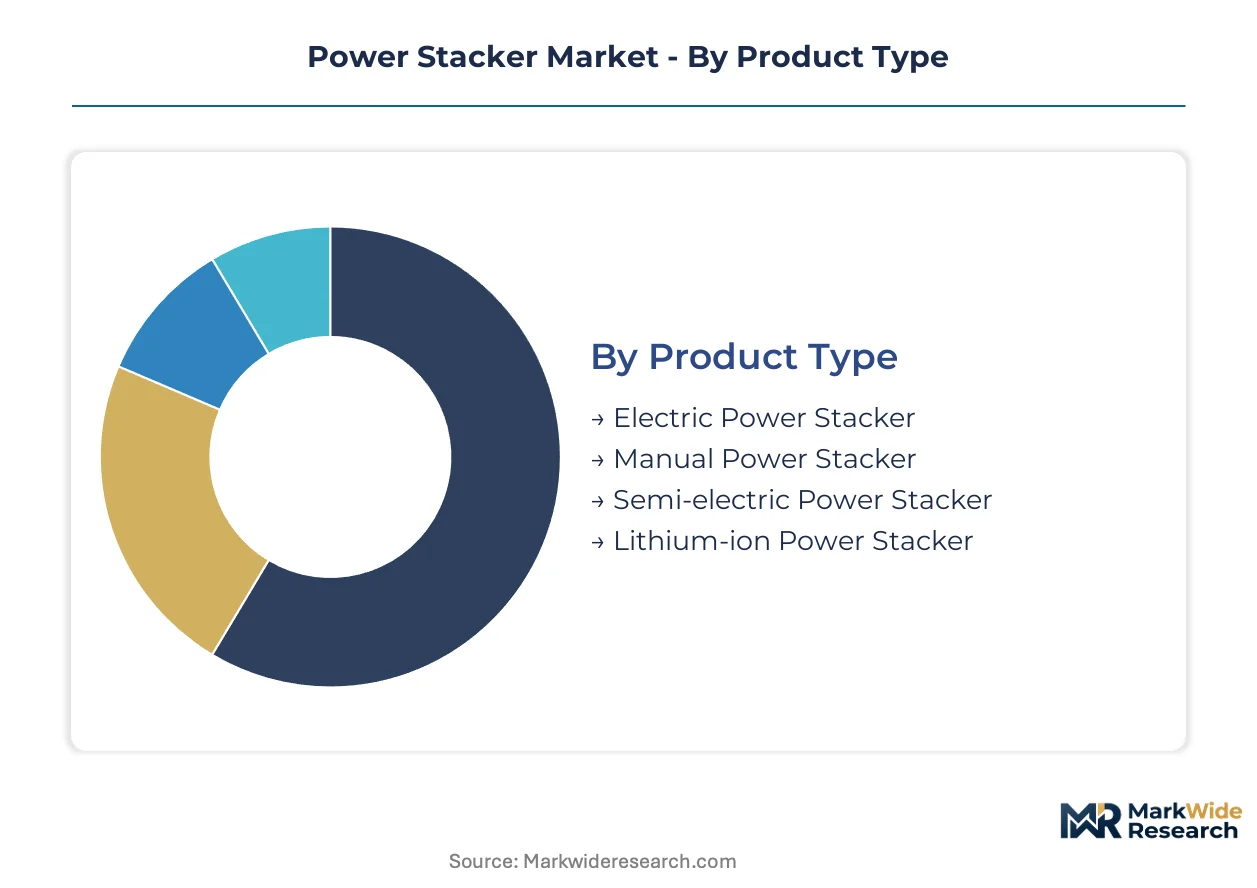
Power stacker procurement decisions hinge on duty cycles, vertical reach requirements, and total cost of ownership calculations across battery chemistries. Fleet managers segment purchases by operational intensity rather than nominal specifications alone.
Product Type:
Capital intensity varies sharply across powertrain architectures, with lithium-ion variants demanding premium upfront outlays against lifecycle savings.
- Electric Power Stacker:Lead-acid battery systems dominate current installed bases across North American and European warehousing operations. Third-party logistics providers near Chicago and Dallas prioritize these units for 24-hour utilization cycles where maintenance staffing already exists.
- Lithium-ion Power Stacker:Sealed cell architectures eliminate watering protocols and opportunity-charge during operator breaks. CARB warehouse emissions mandates in California are accelerating conversions as facilities face carbon accounting disclosures.
- Manual Power Stacker:Hydraulic pump mechanisms suit low-throughput operations with intermittent lifting needs.
- Semi-electric Power Stacker:Hybrid designs combine manual propulsion with electric lift for budget-constrained facilities.
Electric power stackers absorb the bulk of installed capacity; lithium-ion power stackers are expanding most quickly.
Application:
Margin profiles diverge by vertical storage density and throughput velocity, with e-commerce fulfillment commanding premium equipment specifications.
- Warehousing:High-bay racking configurations exceeding three meters drive mast height and reach specifications. E-commerce fulfillment centers generate the highest margin pools due to fleet standardization requirements.
- Logistics:Cross-dock operations prioritize maneuverability in confined trailer loading zones. Freight companies concentrate demand around Dallas-Fort Worth distribution corridors.
- Manufacturing:Just-in-line feeding of assembly stations requires precise load positioning.
- Retail:Backroom replenishment operations favor compact footprints for store-level inventory management.
Warehousing applications anchor volume procurement; logistics is climbing the fastest as parcel networks densify.
End User:
Customer sophistication determines specification stringency, with enterprise e-commerce operators driving standardization protocols.
- E-commerce:Automated warehouse integration demands telematics-ready chassis with predictive maintenance algorithms. These buyers specify fleet management software compatibility as a procurement gate.
- Freight Companies:Drayage and less-than-truckload terminals prioritize durability under continuous loading cycles.
- Retailers:Seasonal volume volatility creates demand for equipment-as-a-service contracts with per-pallet-move pricing.
- Industrial Users:Manufacturing facilities balance capital expenditure constraints against shift-based utilization requirements.
E-commerce operators absorb dominant procurement value; freight companies are gaining share fastest as intermodal volumes surge.
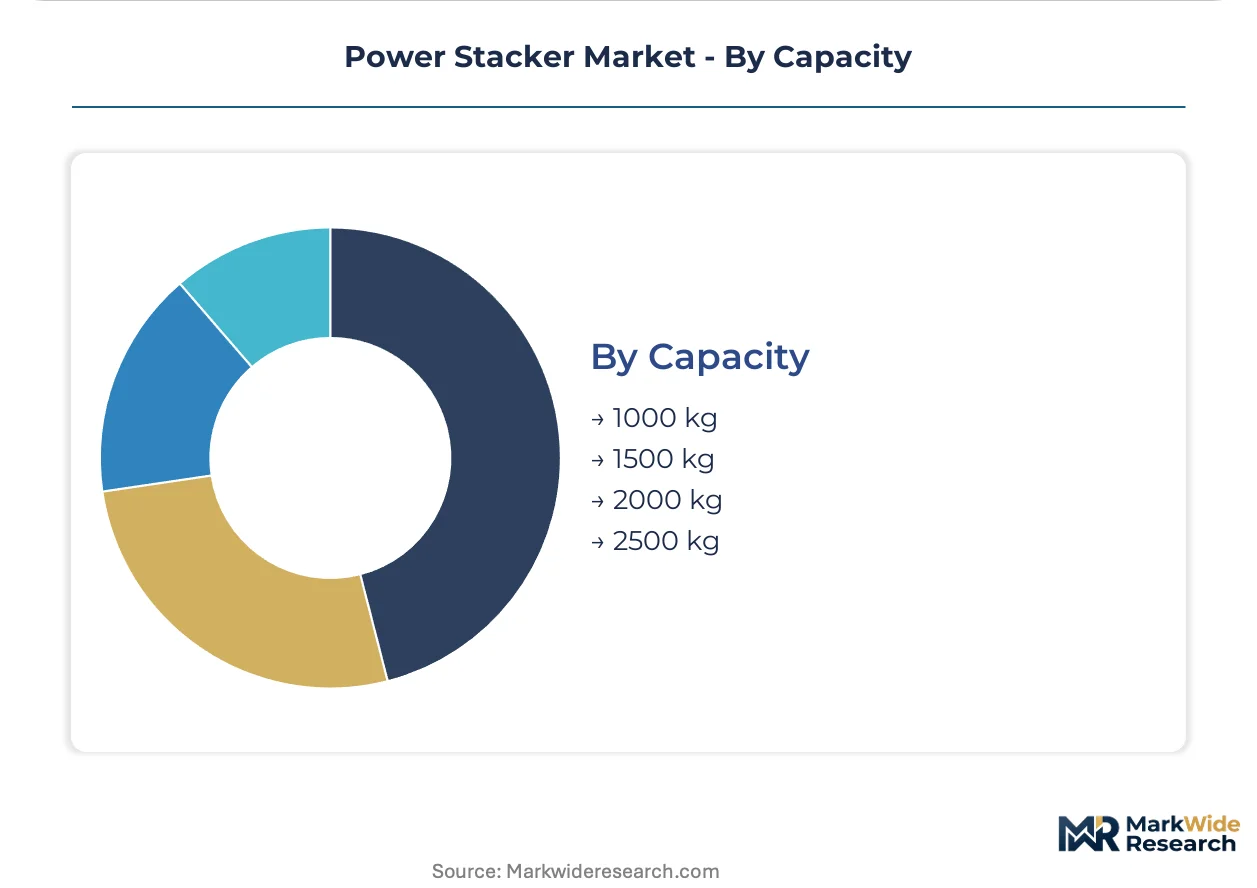
Capacity:
Load rating selection correlates directly with pallet composition and SKU density in vertical storage configurations.
- 1500 kg:Intermediate rating suits standard GMA pallet dimensions with moderate product density. European distribution hubs specify this capacity most frequently for Euro-pallet compatibility.
- 2000 kg:Heavy-duty rating addresses beverage and building materials handling where unit loads concentrate weight.
- 1000 kg:Light-duty specification serves retail backrooms and electronics fulfillment with low-density inventory.
- 2500 kg:Maximum rating supports industrial applications with steel coil and machinery component handling.
1500 kg configurations dominate unit shipments; 2000 kg ratings are expanding fastest as SKU density increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel mill capacity in Hebei Province supplies mast fabrication feedstock for Asian equipment assembly. Lithium-ion cell production clusters in South Korea and Japan compress battery pack economics below lead-acid parity. Warehouse construction in the United States, Germany, China, and India is concentrating demand near major logistics corridors.
United States
Third-party logistics providers near Chicago and Dallas are deploying electric fleets to meet 24-hour utilization cycles. OSHA workplace safety standards mandate operator protection systems and electromagnetic compatibility certification for all imported equipment. California's CARB warehouse emissions rules are accelerating zero-emission conversions ahead of federal requirements.
Germany
Automotive suppliers with existing sustainability audit infrastructure are qualifying power stacker vendors most aggressively under EU Green Deal carbon border adjustments. REACH chemical restrictions and battery recycling directives are forcing lead-acid phase-outs toward sealed lithium-ion architectures. The Ruhr industrial corridor and Bavarian logistics hubs are standardizing fleet specifications for automated warehouse integration.
China
Domestic OEM capacity expansion is rebalancing regional supply availability for material handling equipment exports. GB standards and SAMR quality supervision protocols impose additional testing burdens that create compliance-based segmentation between domestic and export-oriented manufacturers. Yangtze River Delta warehousing clusters are absorbing the bulk of lithium-ion power stacker deployments.
India
Organized retail expansion and GST compliance are creating first-time demand for motorized handling equipment in Tier-2 distribution hubs. BIS certification requirements and DGFT import regulations are shaping procurement timelines for foreign equipment vendors. Maharashtra and Gujarat logistics corridors are formalizing warehousing infrastructure with standardized material handling specifications.
Japan
Cell production scale-up by METI-supported battery manufacturers is compressing lithium-ion pack costs for regional equipment assemblers. JIS standards and PMDA-equivalent machinery safety protocols maintain high barriers for non-domestic suppliers. Kanto and Kansai industrial belts are integrating telematics-ready chassis into existing automated warehouse networks.
Power Stacker Market Competitive Landscape
Global majors compete with regional champions across manufacturing footprint and battery technology integration. The vendor base organizes around three strategic tiers: European premium-positioned specialists with automated warehouse solutions, Asian cost-optimized fabricators serving emerging market distributors, and North American integrated technology providers. Consolidation pressure is concentrating among mid-tier manufacturers facing semiconductor sourcing constraints and steel input volatility. Dominant competitive moves include capacity expansion in lithium-ion battery integration and strategic partnerships for autonomous navigation convergence.
Within the premium automation tier, Jungheinrich AG and Crown Equipment Corporation exemplify European and North American positioning respectively. EP Equipment occupies a cost-optimized archetype among Asian manufacturers competing on electric stacker designs for price-sensitive distributors. Toyota Industries Corporation anchors the diversified industrial conglomerate segment with integrated material handling portfolios spanning multiple powertrain architectures.
| Leading Market Players |
|---|
| Toyota Industries Corporation |
| Jungheinrich AG |
| Crown Equipment Corporation |
| Linde Material Handling |
| Hyster-Yale Materials Handling |
| EP Equipment |
| Godrej Material Handling |
| Doosan Industrial Vehicle |
| Kion Group |
| Others |
Value Network & Pricing Analysis
Steel price indices from Hebei Province mills cascade through mast fabrication costs into three distinct equipment pricing tiers, compressing margins for mid-tier assemblers while premium automation specialists absorb volatility through long-term supply contracts with Yangtze River Delta foundries.
Pricing Analysis
Warranty and service bundling separates premium European automation vendors from unbundled Asian cost competitors. Three-tier pricing structure across premium, standard, and economy levels reflects CE certification grade and lithium-ion battery integration depth. Pricing pressure stems from lead-acid infrastructure lock-in among budget-constrained third-party logistics providers near Chicago and Dallas. Retailers exhibit highest price sensitivity due to seasonal volume volatility, while e-commerce operators prioritize telematics compatibility over upfront cost.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese foundry capacity for power electronics controllers. Mast steel draws from Hebei Province mills, lithium-ion cells from South Korean and Japanese producers, and hydraulic systems from German component specialists. Semiconductor sourcing concentration exposes lead times to geopolitical disruption. Distribution runs through authorized dealer networks serving regional warehousing clusters, with equipment-as-a-service contracts compressing traditional sales cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The power stacker market sits in a technology-transition phase as lithium-ion architectures displace lead-acid battery systems, rewarding vendors with integrated charging infrastructure and predictive maintenance capabilities.
For Market Incumbents: Deepen backward integration into lithium-ion cell pack assembly to capture lifecycle service revenue and defend against Asian cost-optimized entrants. Crown Equipment Corporation's battery-charger technology leadership demonstrates how captive supply of energy architecture creates switching costs. Invest in CARB-compliant zero-emission certifications ahead of federal warehouse emissions mandates.
For New Entrants and Emerging Players: Begin with equipment-as-a-service contracts targeting Tier-2 Indian distribution hubs where GST compliance is formalizing first-time motorized handling demand. White-space exists in compact semi-electric designs for retail backroom replenishment. Partner with local aftermarket service networks to overcome high-voltage technician scarcity barriers.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier European manufacturers facing semiconductor sourcing constraints in Germany and the Netherlands. Long-term viability hinges on autonomous navigation convergence capabilities and lithium-ion integration depth. Watch California CARB enforcement timelines as the inflection signal for zero-emission fleet conversion acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Lithium-Ion Battery Integration | Captures lifecycle service revenue from e-commerce operators phasing out lead-acid maintenance regimes. |
| Autonomous Navigation Convergence | Enables goods-to-person automation for 24-hour utilization cycles without fixed warehouse infrastructure. |
| Equipment-as-a-Service Launch | Compresses capital barriers for seasonal-volume retailers seeking per-pallet-move pricing flexibility. |
| CE Certification Investment | Accelerates electromagnetic compatibility approval timelines for European automotive supplier qualification. |
| Indian Distribution Partnership | Positions for GST-driven warehousing formalization in Maharashtra and Gujarat logistics corridors. |
Research Methodology
Document review covered customs trade databases, OSHA and CE machinery directive filings, and equipment manufacturer SEC disclosures, complemented by interviews with warehouse operations directors, fleet procurement managers at third-party logistics providers, aftermarket service technicians, and lithium-ion battery supply specialists. Secondary validation drew from steel price indices, battery chemistry cost curves, and regional warehouse construction permits. Bottom-up demand modeling triangulated against top-down market sizing.
Unit shipment and value estimates emerged from segmentation across powertrain architecture, mast height specification, battery chemistry, and end-use intensity. The analytical framework incorporated duty cycle utilization rates, carbon accounting compliance timelines, and regional fleet replacement cycles. CAGRs derived from logistic growth curves fitted to lithium-ion adoption S-cycles and e-commerce fulfillment center expansion patterns.
Underlying measurement precision varies by segment; lithium-ion power stacker forecasts carry tighter precision than manual equipment projections given visible procurement pipeline visibility. Forecasts reflect assumptions about CARB enforcement intensity, semiconductor lead time normalization, and steel input cost trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Liquid Nitrogen Purge Systems Market
Industrial Motors
China AC Motor Market
Industrial Motors
Variable Speed Drive Market
Industrial Motors
Japan AC Motor Market
Industrial Motors
Gearless Elevator Traction Motor Market
Industrial Motors
Gear Motor Market
Industrial Motors
United Kingdom DC Motor Market
Industrial Motors
Germany AC Motor Market
Industrial Motors
Global Permanent Magnet Motor Market
Industrial Motors
Seamless Steel Gas Cylinders Market
Industrial Motors
Global Parallel Shaft Geared Motors Market
Industrial Motors
North America Hazardous Location Motors Market
Industrial Motors
Industrial Personnel and Burden Carriers [Electric] Market
Industrial Motors
Asia Pacific Safety Drives and Motors Market
Industrial Motors
Power Scraper Market
Industrial Motors
Asia Pacific and Middle East and Africa Submerged Arc Furnace Market