
 Inverter Duty Motors Market | 2026-2036
Inverter Duty Motors Market Size, Share, and Industry Trends Forecast 2026-2036
Inverter Duty Motors Market Intelligence
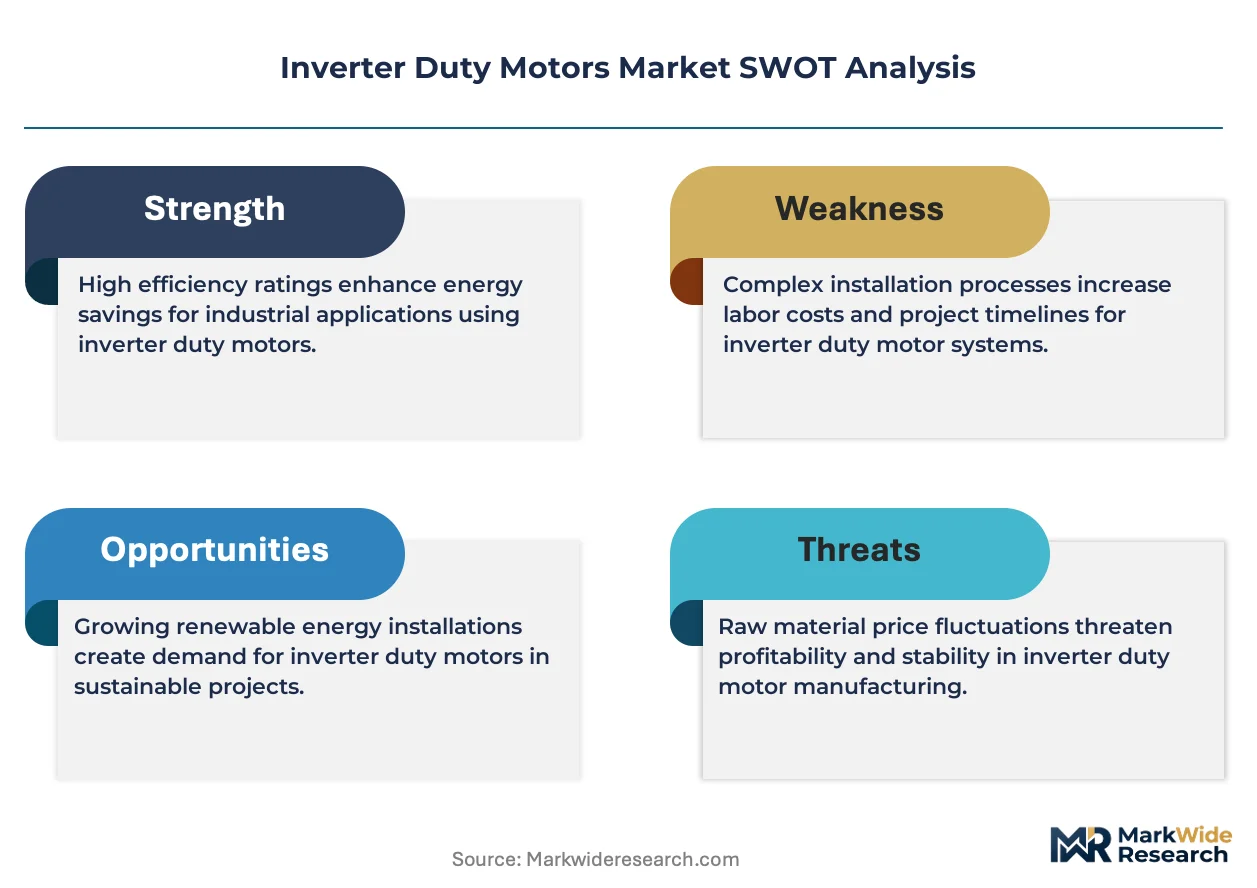
NEMA Premium efficiency tier adoption is collapsing the cost premium between conventional and inverter-rated designs across North American industrial channels. ABB leverages its integrated drive-motor portfolio to anchor specification decisions in European process industries. Siemens competes through digital twin integration that extends service revenue beyond hardware shipments. WEG dominates Latin American supply through captive foundry capacity and regional distribution density.
Inverter duty motors are purpose-built rotating machines with reinforced insulation systems rated for pulse-width modulated power, typically specified with Class H or Class F winding insulation and bearing protection against shaft currents to survive variable frequency drive output waveforms. Their primary industrial purpose is delivering adjustable-speed mechanical power without thermal degradation from harmonic voltage stress. Induction motors occupy the volume core of replacement demand while permanent magnet motor configurations capture margin in precision speed-control applications for compressors and conveyors. PID control architectures concentrate value in oil and gas processing where tight flow regulation justifies premium motor-drive system pricing.
NEMA MG1 Part 31 and IEC 60034-17 establish minimum insulation withstand thresholds that filter non-compliant suppliers from specification lists across US and European project channels. China's GB 18613 efficiency grades and India's BIS certification requirements are tightening import eligibility for motor vendors serving Asian industrial clusters. Water treatment end users in Germany and California face overlapping efficiency mandates from EU Ecodesign rules and FERC pump efficiency guidelines that accelerate inverter duty motor retrofits. Stakeholders must monitor how regional efficiency tier convergence reshapes manufacturing footprint decisions and component sourcing strategies.
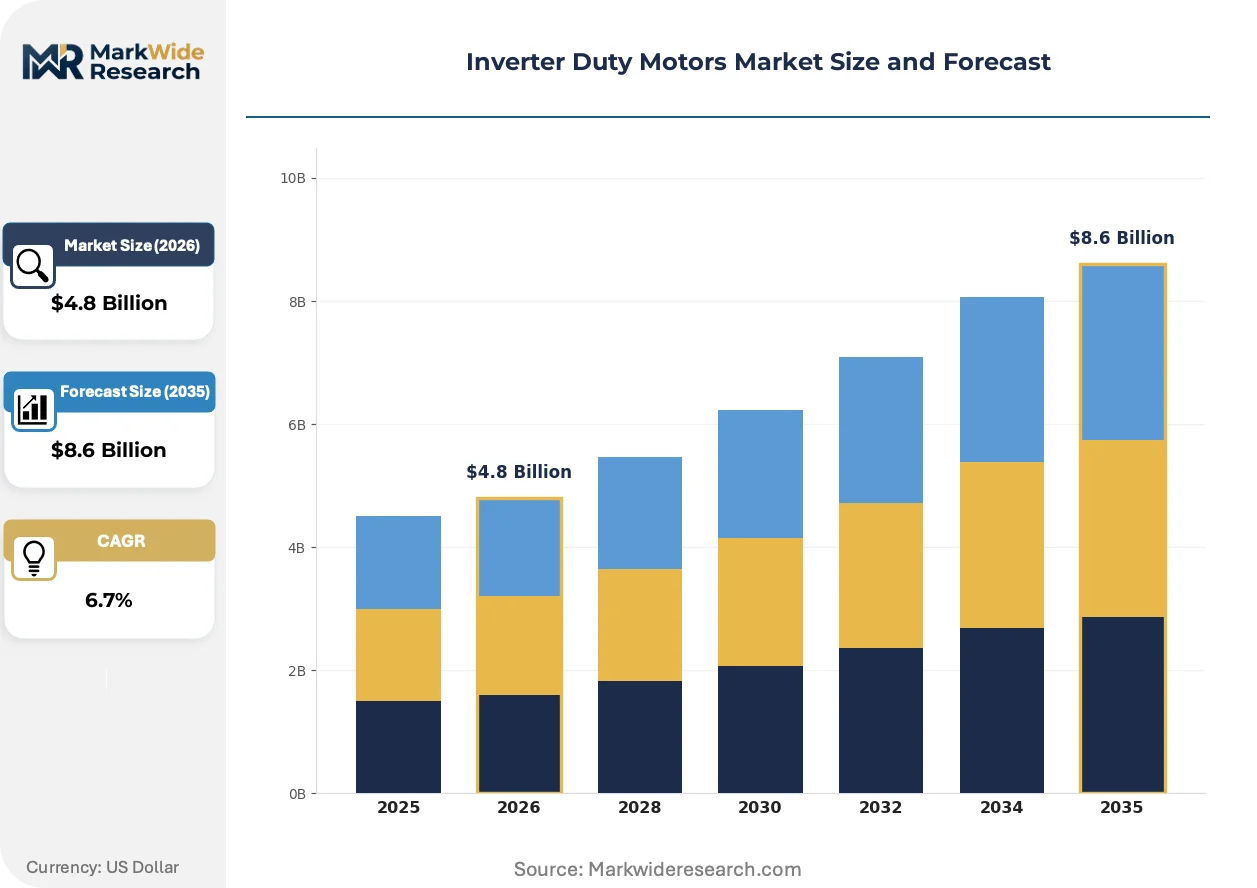
Market Dynamics
NEMA MG1 Part 31 and IEC 60034-17 insulation standards are compressing the performance delta between standard induction motors and purpose-built inverter-rated designs, forcing manufacturers to consolidate product architectures or exit specification channels entirely.
Growth Catalysts
- Water treatment infrastructure:Municipal and industrial wastewater facilities across Germany and California face overlapping efficiency mandates from EU Ecodesign rules and FERC pump efficiency guidelines that accelerate inverter duty motor retrofits.
- GB 18613 efficiency tiers:China's tightening national efficiency grades for electric motors are disqualifying import-dependent suppliers and redirecting procurement toward domestic manufacturers with captive testing facilities.
- Pulse-width modulation survivability:Class H insulation systems with bearing current protection are becoming baseline specifications in oil and gas processing where variable frequency drive penetration exceeds eighty percent.
Market Restraints
- Copper and rare earth magnet volatility:Permanent magnet rotor configurations depend on neodymium supply concentrated in Chinese processing facilities, creating input cost instability for precision speed-control motor variants.
- Foundry capacity concentration:Latin American supply chains rely on Brazilian captive casting operations with limited secondary sourcing, amplifying lead time risk during regional energy rationing events.
- Harmonic heating limitations:Standard Class F insulation systems without reinforced turn insulation suffer premature winding failure under inverter carrier frequencies above four kilohertz, restricting retrofit applications.
Strategic Opportunities
- India's BIS certification expansion:Mandatory efficiency labeling for three-phase induction motors is creating first-mover advantage for vendors establishing local testing partnerships ahead of full enforcement.
- Digital twin convergence:Integration of motor thermal modeling with drive parameter optimization enables predictive maintenance contracts that extend vendor revenue beyond hardware shipment.
- Desalination plant buildouts:Saudi Arabia and UAE municipal water authorities are specifying inverter duty pump systems for reverse osmosis facilities with twenty-year operational life requirements.
Industry Challenges
- Winding technician scarcity:Class H insulation system repair requires specialized vacuum pressure impregnation expertise that vocational programs in North America and Western Europe have not scaled to replacement demand levels.
- Legacy motor inventory incompatibility:Existing NEMA frame sizes and IEC mounting configurations create mechanical integration friction when retrofitting inverter duty replacements into pre-2010 machine bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inverter Duty Motors Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Motor Type: AC Motors, Synchronous Motors, Induction Motors, Permanent Magnet Motors Application: HVAC Systems, Pumps, Conveyors, Compressors End User: Manufacturing, Oil & Gas, Water Treatment, Mining Control System: Direct Control, PID Control, Speed Control, Torque Control |
| Companies Covered | Regal Rexnord Corporation, General Electric, ABB, Toshiba, TECO-Westinghouse, Nidec Motor Corporation, WEG, Rockwell Automation, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inverter Duty Motors Market Strategic Shifts & Innovations
Silicon carbide power semiconductors and advanced thermal modeling are decomposing the traditional separation between motor and drive engineering, enabling integrated mechatronic systems that collapse commissioning complexity and enclosure footprint.
Switched reluctance motor topologies are decomposing the permanent magnet cost structure in compressor and conveyor applications where precision speed control previously demanded rare earth rotor materials. Food and beverage processors in the Netherlands and Denmark are piloting these magnet-free configurations for washdown-duty environments. The technology is decomposing the premium pricing hierarchy between induction and servo-class motion systems in mid-precision positioning tasks.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant compressor motor upgrades across European cold chain infrastructure. Inverter duty specifications are becoming mandatory for variable-speed scroll and screw compressors using lower-global-warming-potential working fluids. German and Italian HVAC OEMs are consolidating supplier lists to vendors with dual refrigerant-motor testing capabilities.
Service contract unbundling is fragmenting the traditional motor-drive system procurement model in North American process industries. End users in Texas and Louisiana petrochemical corridors are separating hardware acquisition from commissioning and predictive maintenance obligations, forcing manufacturers to establish regional service subsidiaries or cede margin to third-party integrators. This pattern is most pronounced in sour gas processing where EPA emissions monitoring requirements demand continuous uptime guarantees.
Inverter Duty Motors Market Segmentation
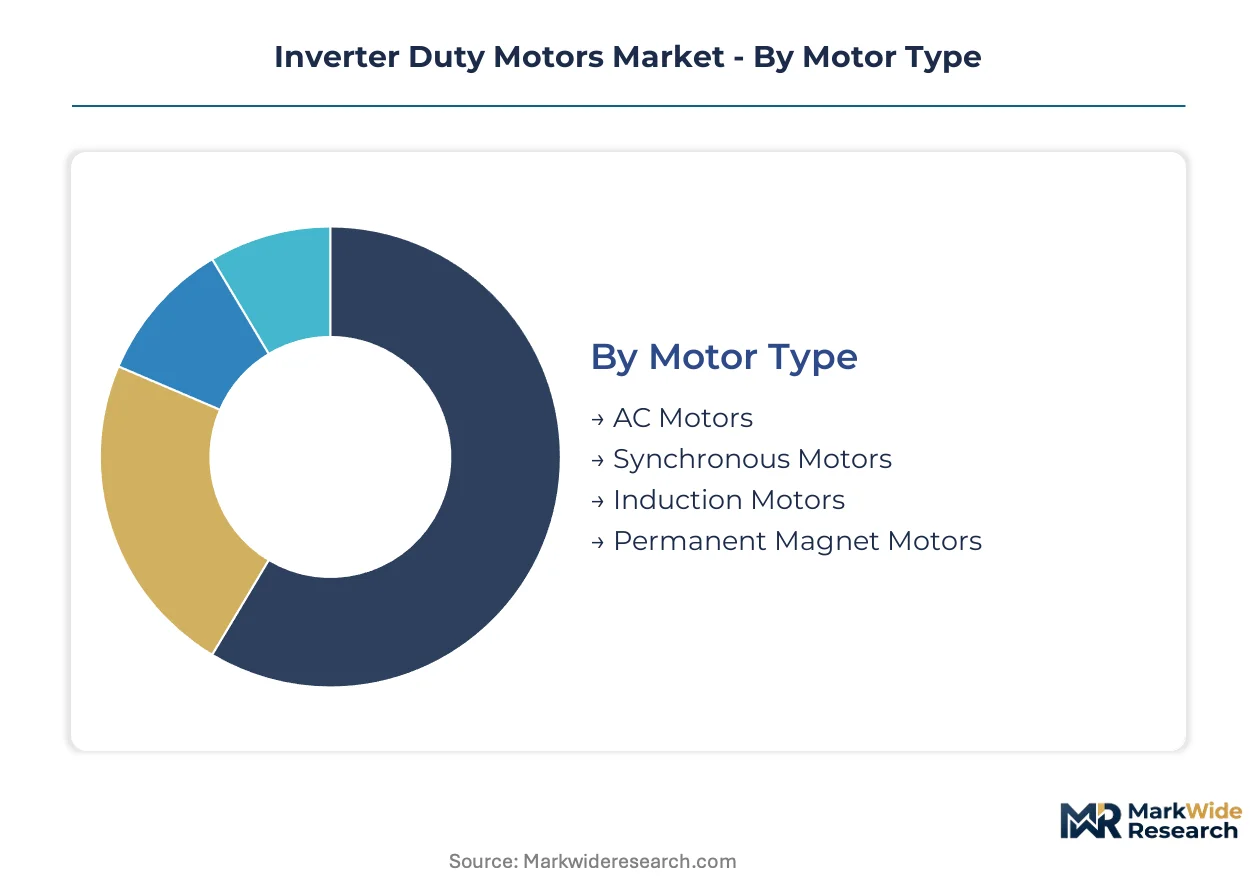
Inverter duty motor procurement patterns diverge sharply between domestic specification channels and export-led project engineering. Segmentation reveals how insulation class requirements, efficiency tier mandates, and control architecture complexity reshape vendor prioritization across end-use verticals.
Motor Type:
Domestic production concentrates on induction and AC motor platforms serving replacement demand in China and India, while permanent magnet and synchronous configurations dominate export flows to European precision-speed applications.
- AC Motors:Broad-spectrum variable frequency drive compatibility with Class F insulation baseline. Demand clusters in Chinese coastal manufacturing provinces where GB 18613 efficiency grades disqualify legacy imports and redirect procurement toward domestic suppliers with captive testing facilities.
- Induction Motors:Squirrel-cage rotor designs with reinforced turn insulation rated for pulse-width modulated power. Water treatment retrofits across Germany and California drive replacement volume as overlapping EU Ecodesign and FERC pump efficiency guidelines accelerate inverter duty specifications.
- Synchronous Motors:Field-excited or reluctance-based configurations for high-inertia loads.
- Permanent Magnet Motors:Neodymium rotor assemblies for precision speed-control in compressors and conveyors.
Induction motors hold the largest share; momentum sits with permanent magnet configurations as rare earth processing cost volatility forces magnet-free topology innovation.
Application:
Cost tier stratification separates premium-specified compressor systems from standard HVAC replacement cycles, with pump and conveyor applications occupying mid-tier pricing bands.
- Compressors:Scroll and screw compressor duty with refrigerant-specific thermal modeling. EU F-Gas Regulation phase-down schedules accelerate variable-speed motor upgrades across German and Italian cold chain infrastructure as lower-global-warming-potential working fluids demand tighter speed regulation.
- Pumps:Centrifugal and positive displacement configurations for flow control. Municipal wastewater facilities in Saudi Arabia and UAE specify inverter duty systems for reverse osmosis desalination with twenty-year operational life requirements.
- HVAC Systems:Fan and blower duty with washdown-rated enclosures.
- Conveyors:Belt and bulk material handling with dynamic braking requirements.
Pump applications command the highest specification density; conveyors are gaining share fastest in food and beverage washdown environments.
End User:
Customer type fragmentation separates project-engineered oil and gas procurement from municipal water treatment bidding, with manufacturing and mining occupying divergent aftermarket channels.
- Oil & Gas:Upstream and downstream process duty with explosion-proof enclosures. Variable frequency drive penetration exceeds eighty percent in sour gas processing corridors where EPA emissions monitoring demands continuous uptime guarantees and unbundled service contracts.
- Water Treatment:Municipal and industrial wastewater with redundant pump configurations. California and Germany face overlapping efficiency mandates that compress procurement timelines and disqualify standard motor alternatives from specification lists.
- Manufacturing:General industrial automation with standardized frame sizes.
- Mining:Harsh environment duty with sealed bearing systems.
Water treatment holds the largest share; oil and gas shows the steepest expansion trajectory as digital twin integration extends vendor revenue beyond hardware shipment.
Control System:
Technology maturity separates legacy direct control architectures from digitally integrated PID and torque control platforms, with speed control occupying the volume replacement core.
- PID Control:Closed-loop feedback architectures for tight flow and pressure regulation. Oil and gas processing justifies premium motor-drive system pricing where precise parameter optimization enables predictive maintenance contracts.
- Speed Control:Variable frequency drive scalar and vector control modes. Broad industrial replacement demand concentrates in North American channels where NEMA MG1 Part 31 insulation standards filter non-compliant suppliers from project specifications.
- Direct Control:Basic on-off and stepped speed operation.
- Torque Control:Direct torque and field-oriented control for high-dynamic response.
Speed control holds the largest share; PID control is climbing the fastest as process industries separate hardware acquisition from commissioning obligations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese motor manufacturers export inverter duty units to European process industries and Middle Eastern desalination projects, while German and Japanese suppliers anchor premium specification channels across North American oil and gas corridors.
United States
Petrochemical processors in Texas and Louisiana drive specification volume for explosion-proof inverter duty systems. EPA emissions monitoring mandates in sour gas processing corridors accelerate variable frequency drive penetration beyond eighty percent. Houston-area engineering firms unbundle hardware procurement from predictive maintenance contracts, fragmenting traditional vendor relationships.
Germany
Municipal wastewater facilities across Bavaria and North Rhine-Westphalia retrofit centrifugal pump systems with Class H insulation motors. EU Ecodesign rules overlap with national efficiency programs to compress procurement timelines for standard alternatives. Frankfurt-Rhine-Main industrial clusters concentrate specification authority for pan-European project engineering.
China
Coastal manufacturing provinces in Jiangsu and Zhejiang absorb domestic production capacity as GB 18613 efficiency grades disqualify import-dependent suppliers. MIIT industrial automation investments redirect procurement toward domestic manufacturers with captive testing facilities. Yangtze River Delta motor foundries supply Southeast Asian pump OEMs with IEC-standard induction platforms.
Saudi Arabia
Municipal water authorities specify inverter duty pump systems for reverse osmosis desalination facilities with twenty-year operational life requirements. SFDA-equivalent municipal regulators enforce redundant pump configurations for critical infrastructure resilience. Eastern Province industrial cities anchor procurement decisions for Gulf Cooperation Authority water treatment standardization.
India
Maharashtra and Gujarat manufacturing corridors drive replacement demand as BIS certification expansion tightens import eligibility for three-phase induction motors. CEA efficiency labeling mandates create first-mover advantage for vendors establishing local testing partnerships ahead of full enforcement. Delhi-NCR engineering consultants specify PID control architectures for compressed air systems in automotive component plants.
Inverter Duty Motors Market Key Industry Players
Listed leaders compete with private specialists across specification channel access and service contract bundling. The vendor base stratifies into three tiers: integrated drive-motor platforms, standalone motor fabricators with regional foundry control, and digital service aggregators. Consolidation pressure intensifies as NEMA MG1 Part 31 and IEC 60034-17 standards filter non-compliant suppliers from project channels. Dominant competitive moves include backward integration into captive foundry capacity and geographic expansion through regional service subsidiaries.
Among diversified industrial conglomerates, ABB, Siemens, and General Electric exemplify the integrated platform archetype. WEG and Nidec Motor Corporation represent regional specialists with density advantages in Latin American and Asian supply chains respectively. These named entities anchor competitive positioning without constraining the full scope of market participation.
| Leading Market Players |
|---|
| Regal Rexnord Corporation |
| General Electric |
| ABB |
| Toshiba |
| TECO-Westinghouse |
| Nidec Motor Corporation |
| WEG |
| Rockwell Automation |
| Siemens |
| Others |
Cost & Logistics Intelligence
NEMA MG1 Part 31 and IEC 60034-17 insulation standards gate both supplier qualification and price differentiation simultaneously, compressing margins for non-compliant fabricators while rewarding certified vendors with specification authority in project-engineered channels across Texas petrochemical corridors and German wastewater facilities.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on Class H insulation certification and captive foundry capacity. Cost compression in standard induction tiers is intensifying because Chinese domestic manufacturers with GB 18613 testing facilities are redirecting procurement away from import-dependent suppliers. Municipal water treatment authorities in California and Germany demonstrate the least price sensitivity due to overlapping EU Ecodesign and FERC pump efficiency mandates that disqualify lower-cost alternatives.
Supply Chain Analysis
Extended lead times for Class H vacuum pressure impregnation equipment are constraining winding capacity expansion. Supply concentrates in China, Germany, and Brazil, with raw material dependencies on copper magnet wire, silicon steel laminations, and neodymium for permanent magnet rotors. Single-source vulnerability in Chinese rare earth processing creates input cost instability for precision speed-control configurations. Distribution runs through regional service subsidiaries in oil and gas corridors and direct OEM relationships in water treatment infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The inverter duty motors market is entering a cyclical recovery phase as industrial automation investments across coastal Chinese manufacturing provinces and Middle Eastern desalination buildouts restock order pipelines depleted during prior capital expenditure contractions.
For Market Incumbents: Fortify specification authority by deepening backward integration into captive foundry capacity in Brazil and Mexico, insulating against Latin American energy rationing risks. Invest in dual refrigerant-motor testing capabilities to capture EU F-Gas Regulation-driven compressor upgrade cycles. Consolidate regional service subsidiaries in Texas and Louisiana petrochemical corridors where unbundled procurement fragments traditional vendor relationships. For New Entrants and Emerging Players: Differentiate on digital twin integration for predictive maintenance contracts, targeting mid-tier manufacturing automation in India's Maharashtra and Gujarat corridors where BIS certification expansion creates first-mover windows. Focus on magnet-free switched reluctance topologies for food and beverage washdown environments in the Netherlands and Denmark. Establish local testing partnerships ahead of full CEA enforcement to bypass import eligibility barriers. For Investors and Strategic Acquirers: IEC 60034-17 standard convergence reshapes the acquisition landscape by filtering non-compliant suppliers from European project channels. Long-term viability favors targets with integrated drive-motor platforms and regional service density. Watch for winding technician scarcity in North America and Western Europe as an inflection signal for aftermarket service rollup opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Foundry Capacity | WEG's Brazilian casting operations demonstrate how upstream control insulates Latin American supply against regional energy rationing events. |
| Digital Twin Platform Development | Siemens extends service revenue beyond hardware shipment through motor thermal modeling integrated with drive parameter optimization. |
| Dual Refrigerant-Motor Testing Certification | German and Italian HVAC OEMs consolidate supplier lists to vendors qualified for lower-global-warming-potential working fluids under EU F-Gas phase-down schedules. |
| Regional Service Subsidiary Expansion | Unbundled procurement in Texas and Louisiana sour gas processing corridors forces manufacturers to establish local predictive maintenance capabilities or cede margin to third-party integrators. |
| Magnet-Free Topology R&D Investment | Switched reluctance configurations decompose permanent magnet cost structures in compressor and conveyor applications where neodymium supply volatility threatens margin stability. |
Research Approach
Initial hypotheses were tested against primary input from maintenance directors at water treatment facilities, OEM procurement teams in oil and gas processing, plant engineers in automotive component manufacturing, and aftermarket service heads at industrial distributors, then refined against secondary validation from FERC pump efficiency filings, EU Ecodesign regulatory databases, SEC 10-K disclosures by listed motor manufacturers, and customs trade data on copper and rare earth magnet flows. Bottom-up unit demand estimates were triangulated against top-down industrial automation capex projections.
Variance decomposition across the projection horizon isolates volume drivers by motor type, application intensity, end-user vertical, and control architecture complexity. CAGRs were derived from segmented growth trajectory analysis incorporating GB 18613 efficiency tier enforcement timelines, MIIT industrial automation investment patterns, and desalination project development pipelines in Gulf Cooperation Authority markets.
Forecasts assume regulatory continuity in EPA emissions monitoring mandates, EU Ecodesign rules, and India's BIS certification expansion; material policy shifts would require re-modeling. Neodymium supply concentration risk and winding technician scarcity represent specific revision triggers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Global Energy Efficient Motor Market
Industrial Motors
Vietnam Air Compressor Market
Industrial Motors
AC Motor Market
Industrial Motors
Japan AC Motor Market
Industrial Motors
Industrial Motor Brakes Market
Industrial Motors
Global Induction Motors Market
Industrial Motors
Global Brushed DC Motor Market
Industrial Motors
Explosion Proof Motor Market
Industrial Motors
Brushless DC Motor Market
Industrial Motors
China AC Motor Market
Industrial Motors
Charging Nitrogen Gas Systems Market
Industrial Motors
Middle East and Africa Variable Frequency Drive (VFD) Market
Industrial Motors
Nuclear Polar Crane Market
Industrial Motors
Gear Reduction Motors Market
Industrial Motors
Power Scraper Market
Industrial Motors
North America Induction Motor Market