
 Liquid Nitrogen Purge Systems Market | 2026-2036
Liquid Nitrogen Purge Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Nitrogen Purge Systems Market Foresight
Closed-loop cryogenic recovery is reshaping how liquid nitrogen purge systems are engineered for industrial deployment. Linde PLC leverages its captive air separation network to anchor supply security across European electronics corridors. Air Products and Chemicals, Inc. sustains R&D intensity in vacuum-insulated transfer lines, differentiating its fixed system portfolio from commodity tank suppliers. Taiyo Nippon Sanso Corporation dominates cryogenic infrastructure buildouts across East Asian semiconductor foundries, where uptime requirements exceed standard service intervals.
Liquid nitrogen purge systems are engineered assemblies that deliver ultra-cold inert gas through vacuum-insulated piping to displace oxygen, moisture, or reactive contaminants from process vessels, pipelines, and controlled environments; operating temperatures typically reach minus 196 degrees Celsius, requiring multi-layer insulation and pressure-rated cryogenic valves to prevent flash vaporization and thermal loss. Fixed systems command the largest installed base in continuous-process industries such as food freezing and chemical synthesis, where capital-intensive infrastructure amortizes across decade-long operational lifecycles. Portable systems represent the fastest-expanding segment, driven by maintenance turnarounds in oilfield services and temporary inerting during aerospace component testing, though margin pools remain thinner due to rental-model pricing and higher fleet utilization risk.
The EPA enforces emissions tracking for cryogenic venting under Clean Air Act permitting, while OSHA mandates confined-space protocols for nitrogen-enriched environments that shape system design and operator training requirements. REACH compliance in Europe restricts certain elastomer seals and lubricants used in cryogenic valves, compelling material substitutions that extend qualification timelines for component suppliers. Stakeholders must monitor evolving semiconductor fabrication standards from SEMI and country-level industrial gas safety codes, as harmonization gaps between jurisdictions complicate multinational deployment strategies and aftermarket service architectures.
Market Dynamics
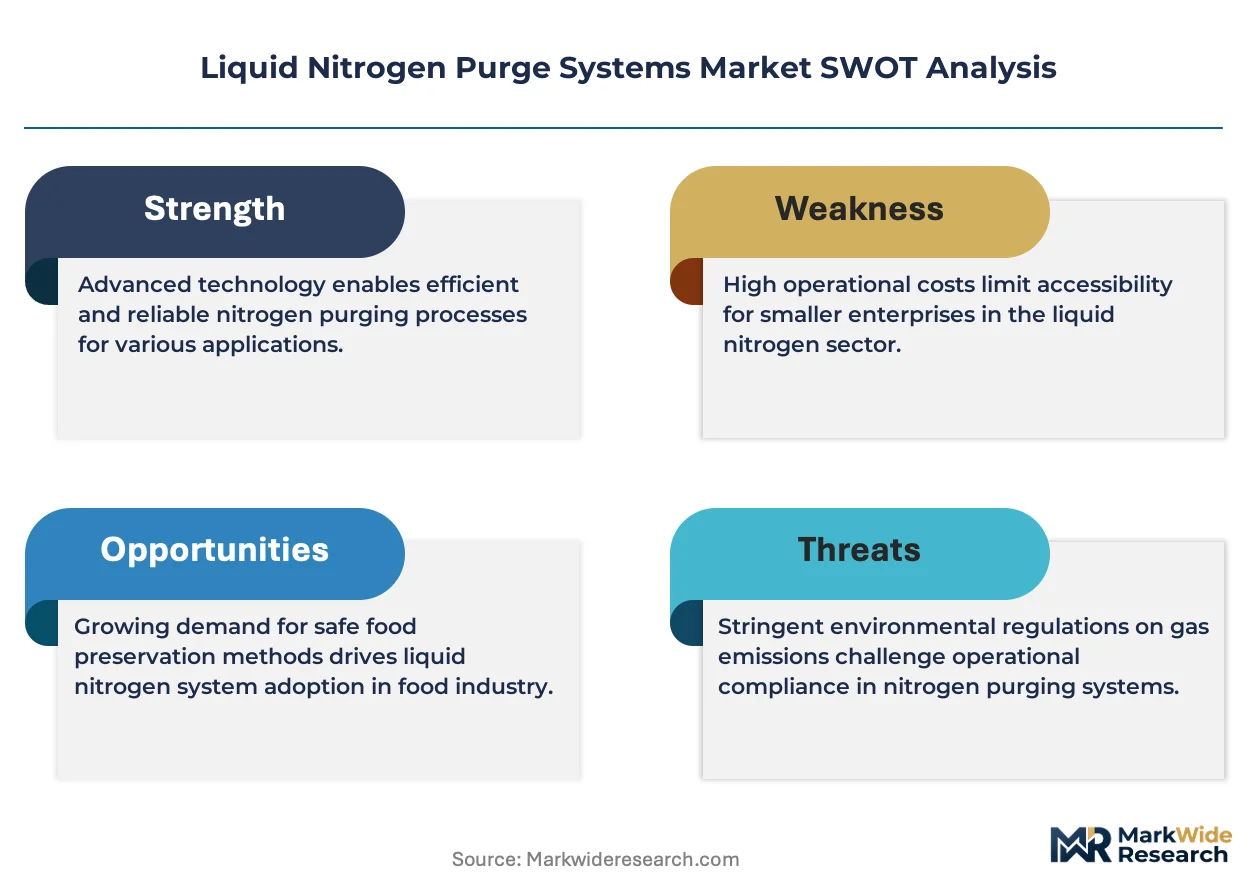
Semiconductor fabrication scaling toward sub-3nm nodes is intensifying demand for ultra-high-purity cryogenic purge infrastructure, forcing equipment suppliers to engineer systems capable of sustaining minus 196 degrees Celsius across extended duty cycles without thermal degradation.
Growth Catalysts
- Advanced Node Semiconductor Production:Taiwan and South Korea foundries are commissioning dedicated liquid nitrogen distribution networks to support EUV lithography chambers requiring continuous inert atmosphere maintenance.
- REACH Material Compliance:Europe's phased restrictions on perfluorinated elastomers are accelerating qualification of cryogenic-rated fluorosilicone seals that withstand repeated thermal cycling.
- Modular System Architecture:Plug-and-play vacuum-insulated skid designs are reducing field installation timelines from weeks to days for chemical processing turnarounds.
Market Restraints
- Helium Supply Concentration:Qatar and the United States control over 80 percent of global helium refining capacity, creating input cost volatility for hybrid cryogenic systems requiring helium-neon purge mixtures.
- Cryogenic Valve Technical Limitations:Current metal-to-metal sealing technologies exhibit fatigue failure after approximately 10,000 thermal cycles, constraining maintenance intervals in continuous-process environments.
- EPA Permitting Friction:Clean Air Act Title V requirements for cryogenic venting impose 18-24 month approval timelines for new installations in Texas and Louisiana chemical corridors.
Strategic Opportunities
- India Pharmaceutical Cold Chain:CDSCO-mandated temperature integrity requirements for biologics distribution are creating first-mover openings for mobile liquid nitrogen units in Mumbai and Hyderabad logistics hubs.
- Green Hydrogen Electrolysis:PEM electrolyzer stack manufacturers require cryogenic purge protocols for catalyst activation, representing an emerging application vertical with limited incumbent penetration.
- Japan METI Carbon Neutrality Roadmap:Subsidies for industrial gas recovery systems are incentivizing closed-loop nitrogen capture retrofits in Osaka-Kobe chemical manufacturing clusters.
Industry Challenges
- Cryogenic Welding Certification Gap:Qualified technicians for orbital welding of 304L stainless vacuum-jacketed piping command 40 percent wage premiums, constraining deployment velocity for large-scale projects.
- Legacy DCS Integration Complexity:Semiconductor fabs operating 1990s-era distributed control systems face protocol translation failures when connecting modern nitrogen purity sensors to existing SCADA architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Nitrogen Purge Systems Market |
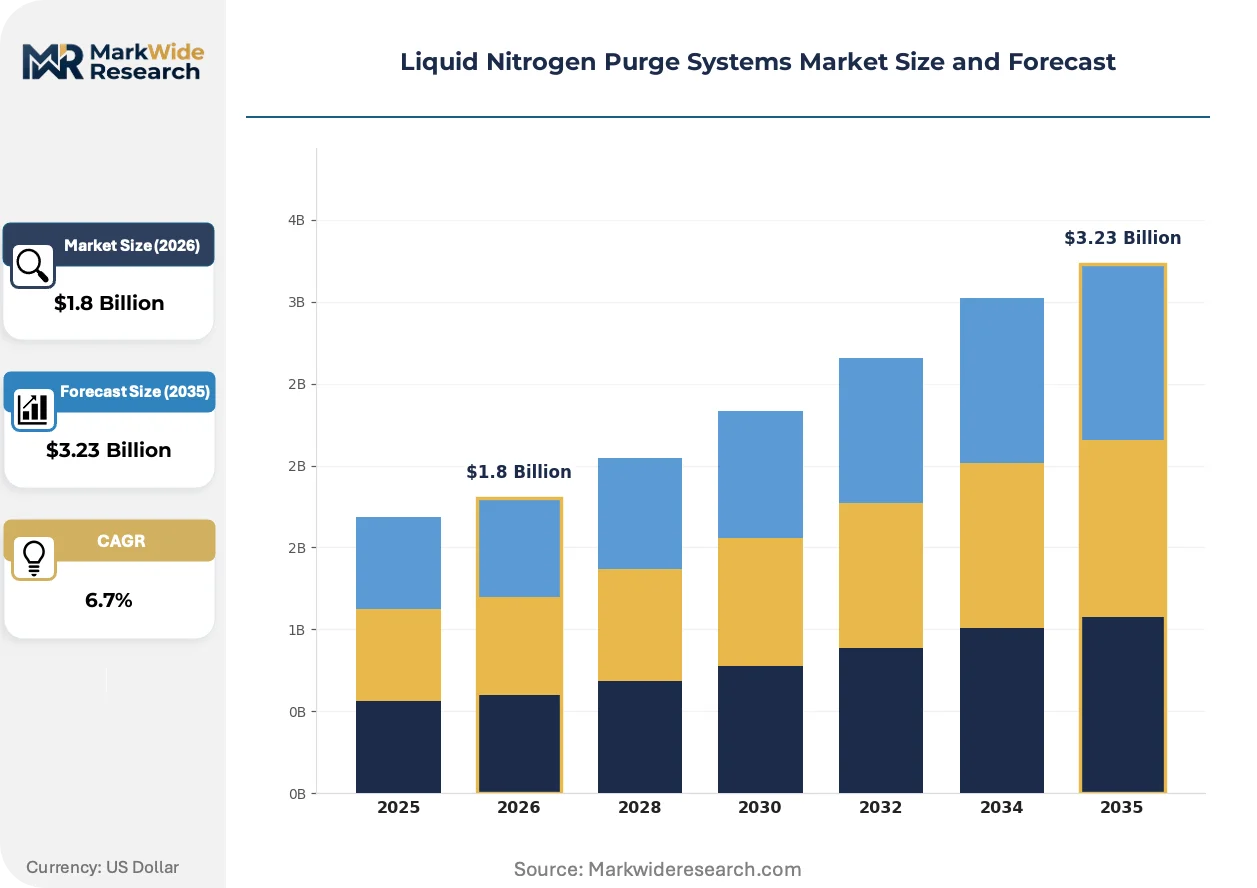
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Systems, Fixed Systems, Custom Systems, Cryogenic Tanks Industry Vertical: Food Processing, Electronics Manufacturing, Aerospace, Pharmaceuticals Technology: Vacuum Insulation, Gas Purification, Automation Solutions, Control Systems End User: Manufacturers, Research Institutions, Laboratories, Food Distributors |
| Companies Covered | Linde PLC, Air Products and Chemicals, Inc., Praxair Technology, Inc., Air Liquide, Taiyo Nippon Sanso Corporation, Liquid Packaging Solutions, Halliburton, Airgas, IKM Testing UK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Nitrogen Purge Systems Market Shifts & Advancements
Vacuum-insulated transfer technology and closed-loop recovery architectures are compressing operating costs while tightening purity thresholds. Equipment suppliers are reconfiguring service models around uptime guarantees rather than capital sales.
Multi-layer insulation (MLI) systems employing alternating aluminized Mylar and fiberglass mesh are migrating from aerospace heritage applications into semiconductor fab nitrogen distribution. Samsung and TSMC process engineering teams specify MLI-lined transfer lines for new 2nm-capable facilities. The technology is enabling 40 percent reduction in boil-off losses compared to conventional perlite-insulated piping, compressing total cost of ownership calculations for fixed installation buyers.
EPA's 2024 amendments to National Emission Standards for Hazardous Air Pollutants (NESHAP) Subpart HHH impose continuous monitoring requirements on cryogenic venting events exceeding 500 pounds per hour. Chemical manufacturers in the Gulf Coast corridor are deploying automated diverter valves to capture vent streams for recompression. Fixed system suppliers are bundling emissions compliance dashboards into service contracts to secure decade-long maintenance relationships.
Equipment-as-a-service contracting is displacing outright purchase for portable nitrogen purge fleets in North American oilfield services. Halliburton and Schlumberger maintenance divisions now specify availability-based pricing with penalty clauses for purity excursions. The model concentrates fleet ownership with Linde and Air Products, compressing margins for regional rental specialists unable to guarantee 99.999 percent uptime across dispersed wellhead locations.
Liquid Nitrogen Purge Systems Market Segmentation
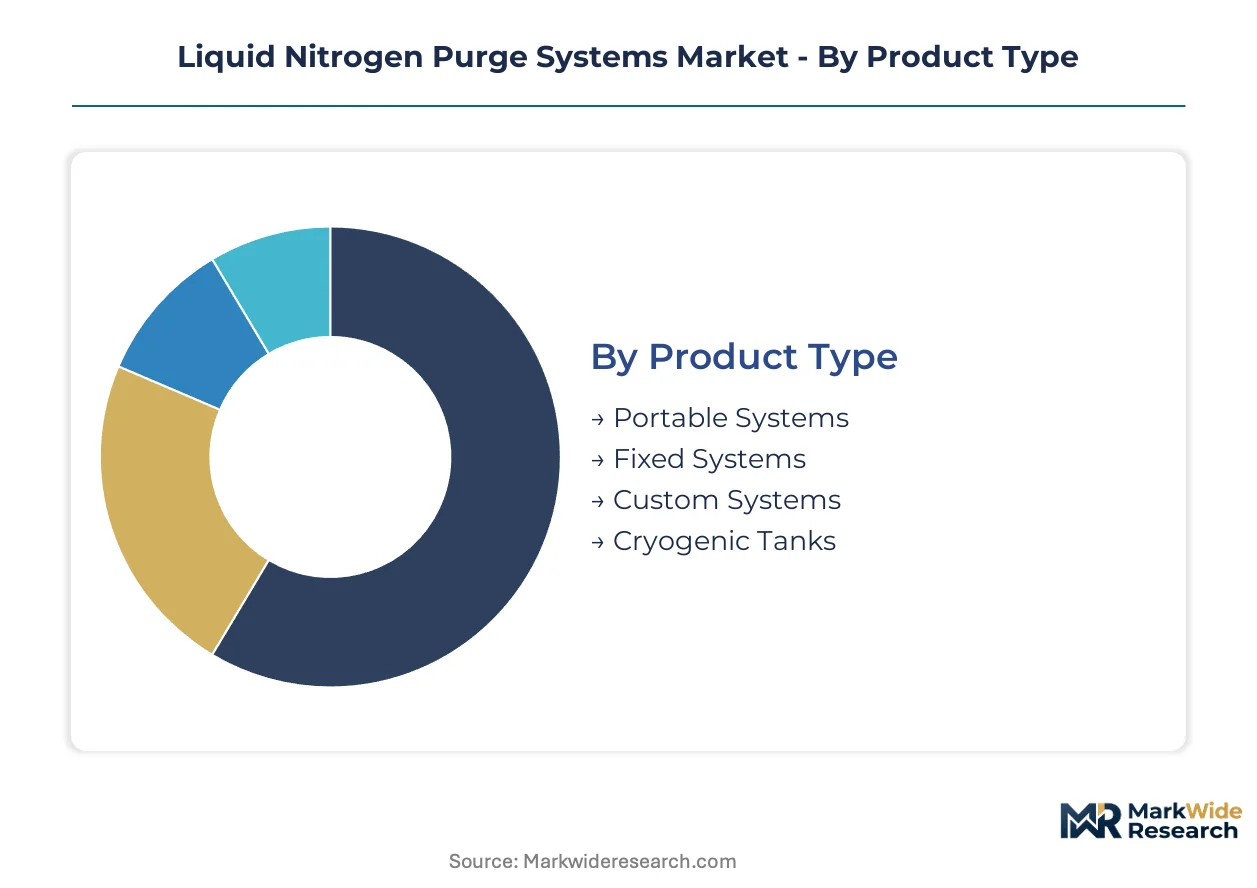
Liquid nitrogen purge systems serve divergent operational rhythms across industrial deployments. Cycle-time differentials between continuous-process installations and intermittent maintenance applications dictate capital allocation patterns and service model design.
Product Type:
Fixed installations amortize across decade-long operational lifecycles while portable fleets turn over every 3-5 years under rental depreciation schedules.
- Fixed Systems:Permanent vacuum-insulated distribution networks integrate with facility cryogenic infrastructure. BASF and Bayer operate such integrated systems across Germany's chemical corridor for continuous process inerting. These installations command the largest capital commitments and longest replacement cycles.
- Portable Systems:Mobile skid-mounted units deploy for maintenance turnarounds and temporary inerting. Oilfield services in Texas and Louisiana drive fleet utilization, though rental-model pricing compresses margin pools relative to fixed installations.
- Custom Systems:Engineered-to-order configurations address site-specific thermal loads and purity thresholds.
- Cryogenic Tanks:Bulk storage vessels with multi-layer insulation anchor supply security for high-volume consumers.
Fixed systems anchor the volume base while portable systems gain share at the steepest rate.
Industry Vertical:
Cost tiers stratify sharply between semiconductor-grade purity requirements and food-freezing commodity applications.
- Electronics Manufacturing:Sub-3nm node production demands ultra-high-purity cryogenic infrastructure sustaining minus 196 degrees Celsius across extended duty cycles. Taiwan and South Korea foundries commission dedicated distribution networks for EUV lithography chambers.
- Pharmaceuticals:CDSCO-mandated temperature integrity for biologics distribution creates demand for mobile liquid nitrogen units in Mumbai and Hyderabad logistics hubs.
- Food Processing:Continuous freezing tunnels represent mature installed base with thinner technology differentiation.
- Aerospace:Component testing protocols require intermittent high-flow purge capacity for thermal shock validation.
Electronics manufacturing commands premium pricing tiers while pharmaceuticals climbs fastest on regulatory tailwinds.
Technology:
Supply concentration in vacuum insulation expertise shapes competitive moats more than gas purification commoditization.
- Vacuum Insulation:Multi-layer insulation systems with alternating aluminized Mylar and fiberglass mesh enable 40 percent reduction in boil-off losses. Samsung and TSMC specify MLI-lined transfer lines for 2nm-capable facilities.
- Automation Solutions:Automated diverter valves capture vent streams for recompression under EPA NESHAP Subpart HHH compliance requirements.
- Gas Purification:Filtration and drying subsystems ensure 99.999 percent purity for semiconductor process chambers.
- Control Systems:Protocol translation layers bridge modern nitrogen purity sensors to legacy 1990s-era distributed control architectures.
Vacuum insulation anchors technical differentiation while automation solutions expands most quickly on emissions compliance mandates.
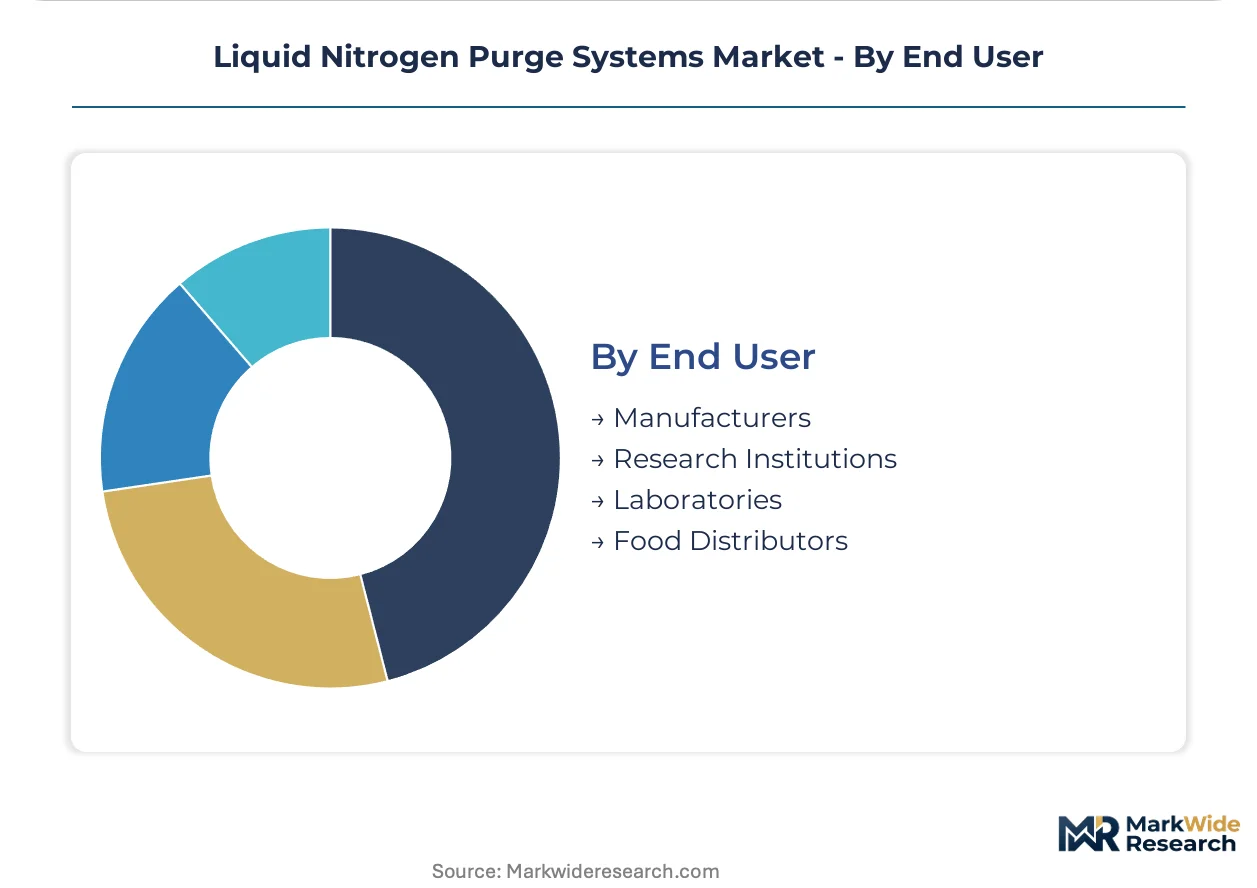
End User:
Procurement authority separates capital-intensive manufacturers from grant-dependent research institutions.
- Manufacturers:Continuous-process industries amortize infrastructure across operational lifecycles with multi-year service contracts bundling maintenance and compliance dashboards.
- Research Institutions:Grant-funded capital cycles concentrate demand in Q2-Q3 fiscal windows with stringent uptime requirements.
- Laboratories:Smaller-scale point-of-use installations prioritize footprint minimization over flow rate optimization.
- Food Distributors:Cold chain integrity requirements drive mobile unit deployment for temporary backup during primary system maintenance.
Manufacturers dominate current installed value while research institutions show steepest expansion trajectory on federal funding priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor foundries and chemical manufacturers concentrate procurement authority across East Asia, North America, and Europe, with national industrial policies dictating infrastructure investment timelines and compliance stringency.
United States
EPA's 2024 NESHAP Subpart HHH amendments impose continuous monitoring on cryogenic venting events exceeding 500 pounds per hour. Gulf Coast chemical manufacturers in Texas and Louisiana deploy automated diverter valves for vent stream capture. Houston and Lake Charles host the densest concentrations of retrofit activity as operators seek to compress 18-24 month permitting timelines.
Taiwan
TSMC and domestic foundry peers commission dedicated liquid nitrogen distribution networks for EUV lithography chambers at sub-3nm nodes. The island's national semiconductor strategy channels capital toward cryogenic infrastructure buildouts. Hsinchu Science Park anchors the highest-density cluster of ultra-high-purity purge system installations.
South Korea
Samsung Electronics specifies multi-layer insulation transfer lines for 2nm-capable fabrication facilities. METI-aligned carbon neutrality roadmaps in neighboring Japan create competitive pressure for domestic recovery system adoption. Pyeongtaek and Giheung house the primary foundry complexes driving specification requirements.
Germany
REACH phased restrictions on perfluorinated elastomers accelerate qualification of cryogenic-rated fluorosilicone seals. BASF and Bayer operate integrated cryogenic networks across the chemical corridor for continuous process inerting. Ludwigshafen and Leverkusen concentrate the heaviest fixed installation demand in European process industries.
India
CDSCO-mandated temperature integrity requirements for biologics distribution create first-mover openings for mobile liquid nitrogen units. Mumbai and Hyderabad logistics hubs concentrate pharmaceutical cold chain investment. Central government PLI schemes for specialty chemicals extend subsidy eligibility to cryogenic infrastructure.
Liquid Nitrogen Purge Systems Market Competitive Landscape
Channel-controlling players compete with product-specialist players for specification authority in semiconductor fabs and chemical complexes. The structure concentrates around captive industrial gas networks and independent equipment fabricators serving maintenance-intensive segments. Two archetypes dominate: integrated gas majors leveraging air separation assets, and vacuum-insulation specialists defending technical differentiation. Competitive moves center on service contract bundling and modular system architecture licensing.
Among integrated gas majors, Linde PLC and Air Products and Chemicals, Inc. anchor positions through captive supply networks and R&D intensity in transfer line engineering. Taiyo Nippon Sanso Corporation exemplifies the East Asian specialist archetype, occupying a position tied to semiconductor foundry uptime requirements. These three represent the strategic poles around which regional specialists and rental fleet operators organize.
| Leading Market Players |
|---|
| Linde PLC |
| Air Products and Chemicals, Inc. |
| Praxair Technology, Inc. |
| Air Liquide |
| Taiyo Nippon Sanso Corporation |
| Liquid Packaging Solutions |
| Halliburton |
| Airgas |
| IKM Testing UK |
| Others |
Supply & Pricing Matrix
Helium supply concentration between Qatar and the United States determines both pricing tier spreads and supply chain shape for hybrid cryogenic systems, forcing buyers into long-term offtake contracts with indexation clauses while compressing margins for operators unable to secure captive feedstock.
Pricing Analysis
Cost-plus contracts with natural gas indexation dominate procurement for bulk liquid nitrogen, with semiconductor fabs paying premiums for 99.999 percent purity guarantees while food processors accept standard-grade product at volume-scaled discounts. Price differentiation hinges on certification tier—SEMI-compliant systems command substantial uplifts over industrial-grade equivalents—and geographic delivery cost to remote wellhead locations. Cost compression in portable rental fleets is intensifying because oilfield service providers now demand availability-based pricing with uptime penalties. Research institutions exhibit highest price sensitivity due to grant-funded capital cycles, whereas continuous-process chemical manufacturers prioritize supply security over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for cryogenic valve components and vacuum-jacketed piping materials. Manufacturing concentrates in Germany for precision-engineered seals, the United States for automated diverter valves, and Japan for multi-layer insulation systems. Raw material dependencies draw from nickel alloys for cryogenic-rated piping, specialized elastomers for thermal cycling resilience, and high-purity aluminum for MLI substrates. Single-source vulnerability persists for qualified orbital welding technicians commanding wage premiums. Distribution runs through integrated gas majors with captive air separation networks rather than independent equipment fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from closed-loop gas recovery systems that displace vent-and-purge models; defending market position requires building structural barriers against this technical displacement.
For Market Incumbents: Build regulatory compliance moats by bundling EPA NESHAP Subpart HHH emissions dashboards into decade-long service contracts, locking out competitors during Gulf Coast retrofit cycles. Deepen backward integration into captive air separation capacity to secure feedstock cost advantages against regional rental specialists. Counter closed-loop recovery substitutes by positioning fixed installations as the proven baseline for uptime-critical semiconductor fabs. For New Entrants and Emerging Players: Pursue modular skid architecture licensing to chemical processors seeking compressed field installation timelines for turnaround windows. Target India's pharmaceutical cold chain as the most penetrable vertical, where CDSCO mandates create first-mover openings without incumbent saturation. Lead with equipment-as-a-service contracting to capture fleet ownership concentration from oilfield maintenance divisions. For Investors and Strategic Acquirers: The market sits at a substitution defense phase that favors vertically integrated gas majors with captive supply networks over standalone equipment fabricators. Long-term viability rests on service contract bundling rather than capital sales, favoring targets with established maintenance infrastructures. Monitor Japan METI subsidy disbursement velocity as the signal for closed-loop retrofit adoption rates across Osaka-Kobe chemical clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Air Separation | Captive feedstock supply secures cost position against Qatari helium volatility. |
| Modular Skid Architecture Licensing | Plug-and-play designs compress German chemical corridor installation timelines from weeks to days. |
| Emissions Compliance Dashboard Bundling | EPA NESHAP monitoring capabilities lock in decade-long maintenance relationships with Gulf Coast operators. |
| Closed-Loop Recovery System Deployment | Japan METI subsidies accelerate Osaka-Kobe nitrogen capture retrofits ahead of carbon neutrality deadlines. |
| Orbital Welding Technician Certification Programs | Address 40 percent wage premiums constraining large-scale project deployment velocity. |
Research Methodology
The analysis maps fixed installations, portable fleets, cryogenic tanks, and custom engineered systems, each validated through interviews with plant engineers at semiconductor fabs, procurement leads at chemical manufacturers, aftermarket service heads at integrated gas majors, and maintenance directors at oilfield service divisions. Secondary sources include EPA Clean Air Act permitting databases, SEMI fabrication standards documentation, ECHA REACH restriction timelines, and SEC filings from industrial gas suppliers. Bottom-up segment sizing triangulates against top-down macroeconomic indicators.
Forecast assumptions hold semiconductor node migration timelines and EPA enforcement intensity as fixed parameters while varying helium supply disruption scenarios and Japan METI subsidy uptake rates across the projection horizon. Segmentation dimensions modeled include product architecture, industry vertical purity requirements, insulation technology tier, and end-user procurement authority. CAGRs derive from installed base turnover analysis and capital expenditure pipeline tracking, with specific weighting for EUV lithography chamber specifications and biologics cold chain regulatory mandates.
Macroeconomic conditions sit as an overlay; deviation in industrial gas demand cycles, semiconductor capital expenditure patterns, or Gulf Coast chemical production rates would shift the trajectory. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Hydraulic Motors Market
Industrial Motors
Synchronous Electric Motor Market
Industrial Motors
Europe Hazardous Location Motors Market
Industrial Motors
Crude Heater Market
Industrial Motors
HVAC Motors Market
Industrial Motors
Hoist and Elevator Motors Market
Industrial Motors
Global Energy Efficient Motor Market
Industrial Motors
Global Permanent Magnet Motor Market
Industrial Motors
Global Direct Current (DC) Motor Market
Industrial Motors
Flatwire & HAIR-PIN Motor Market
Industrial Motors
Cryogenic Air Separation Units (Asus) Market
Industrial Motors
Industrial Motor Market
Industrial Motors
Europe Induction Motor Market
Industrial Motors
Explosion Proof Electric Motors and Actuators Sales Market
Industrial Motors
Elevator Motors Market
Industrial Motors
North America Refrigeration Oil Market