
 United Kingdom AC Motors Market | 2026-2036
United Kingdom AC Motors Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom AC Motors Market Insights
Software-defined motor diagnostics bundled with predictive maintenance contracts is repositioning how AC motor vendors capture lifetime value from industrial buyers. ABB Ltd leverages its digital platform ecosystem to anchor long-term service relationships across UK manufacturing sites. Siemens AG sustains competitive differentiation through integrated automation portfolios that extend from drive systems to cloud-based energy analytics. Brook Crompton specializes in bespoke low-voltage induction motors, occupying niche positions in process industries where retrofit compatibility controls procurement decisions.
An AC motor converts alternating current into mechanical rotation through electromagnetic induction, with synchronous speeds determined by supply frequency and pole count, typically operating between 750 and 3600 revolutions per minute to drive pumps, compressors, conveyors, and fans. Induction motors dominate installed base volumes across UK industry due to their rugged squirrel-cage construction and minimal maintenance requirements, though servo motor categories are gaining share in precision automation applications where closed-loop positioning justifies premium positioning. Medium power ratings capture substantial margin pools in HVAC and pumping applications, while high power segments concentrate around heavy process equipment in chemicals and water treatment infrastructure.
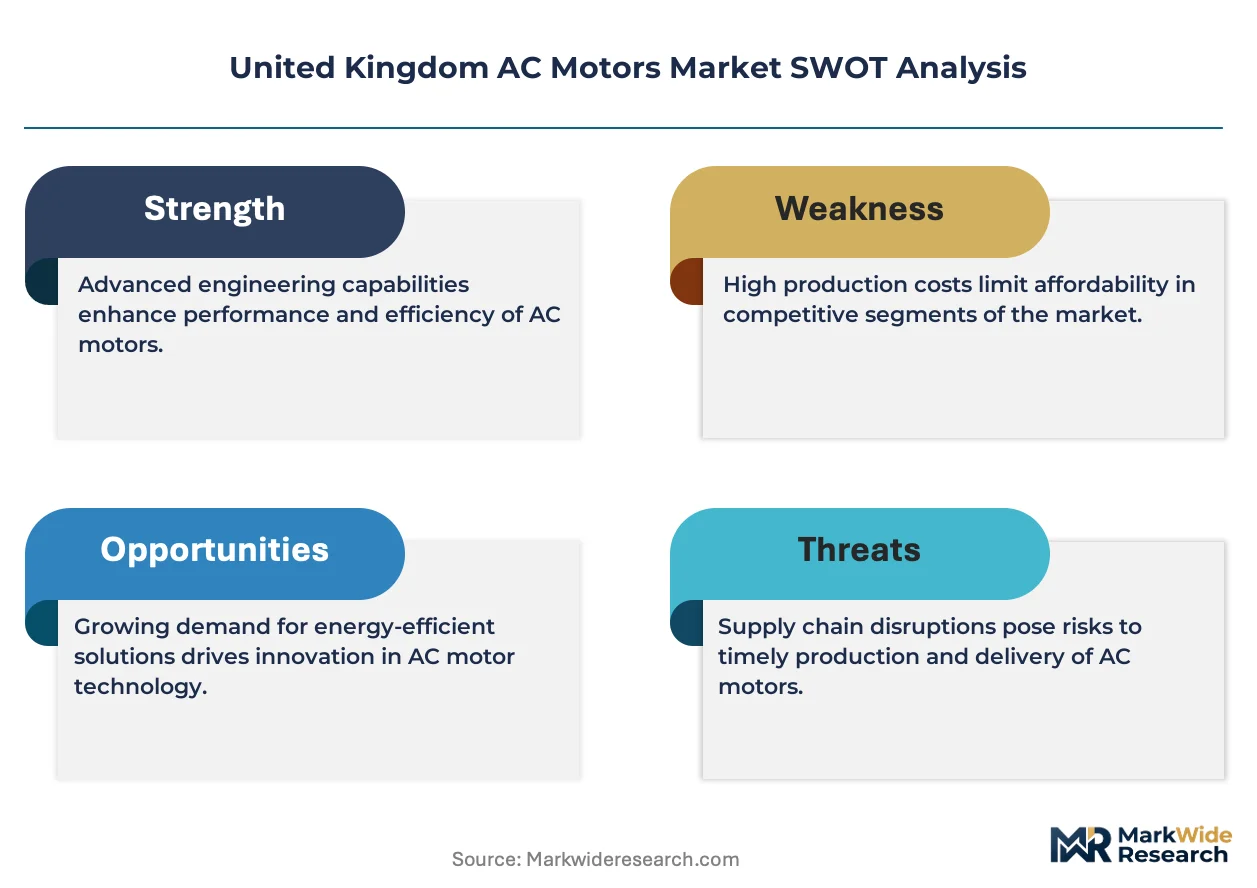
The UK government's Minimum Energy Efficiency Standards and the Environment Agency's F-Gas Regulation enforcement are tightening efficiency tiers for motor-driven systems, compelling facility operators to specify IE4 and IE5 premium efficiency units in new installations and major refurbishments. BSI certification requirements and the EU-originated Ecodesign framework retained in UK law shape product compliance pathways for domestic and imported equipment alike. Stakeholders must monitor how the UK's evolving carbon border adjustment mechanisms and potential divergence from EU harmonized standards could fragment certification costs and supplier qualification timelines.
Market Dynamics
MEES regulations and the F-Gas phase-down are compressing replacement cycles across UK commercial and industrial facilities, forcing capital deployment toward IE4 and IE5 premium efficiency motors ahead of natural end-of-life schedules.
Growth Catalysts
- MEES Compliance Deadlines:The UK's Minimum Energy Efficiency Standards mandate efficiency upgrades in leased commercial properties, accelerating motor replacement demand across England's retail and office stock.
- Heat Pump Manufacturing:Domestic production scaling for residential and commercial heat pumps requires high-efficiency compressor motors, concentrating orders in Midlands-based HVAC supply chains.
- Water Infrastructure Modernization:Thames Water and United Utilities are replacing aging pumping station motors with variable-speed drives, creating sustained demand for medium-power induction units.
Market Restraints
- Copper Price Volatility:Winding material costs fluctuate with LME copper futures, compressing margins for motor manufacturers unable to pass through input cost swings.
- Import Dependency:Premium permanent magnet materials for synchronous motors concentrate in Chinese processing facilities, exposing UK assemblers to supply concentration risk.
- IE5 Retrofit Compatibility:Existing fixed-speed infrastructure in legacy manufacturing plants requires complete drive system replacement, not motor-only swaps, extending payback periods.
Strategic Opportunities
- Scotland's Offshore Wind Supply Chain:Port infrastructure development at Aberdeen and Dundee creates demand for high-power motors in turbine nacelle assembly and maintenance vessel propulsion.
- Predictive Maintenance Bundles:Vibration monitoring and thermal analytics integrated with motor sales generate recurring revenue streams from industrial buyers seeking uptime guarantees.
- Hydrogen Compression Systems:Electrolyzer and fueling station deployments require specialized explosion-proof motors, opening niche specification work for certified suppliers.
Industry Challenges
- BSI Certification Bottlenecks:Extended testing timelines for IE5 efficiency verification delay product launches, particularly for imported equipment seeking UKCA marking.
- Electromechanical Skill Shortage:Facilities maintenance teams lack training in variable frequency drive commissioning and fault diagnosis, slowing adoption of optimized motor-drive pairings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom AC Motors Market |
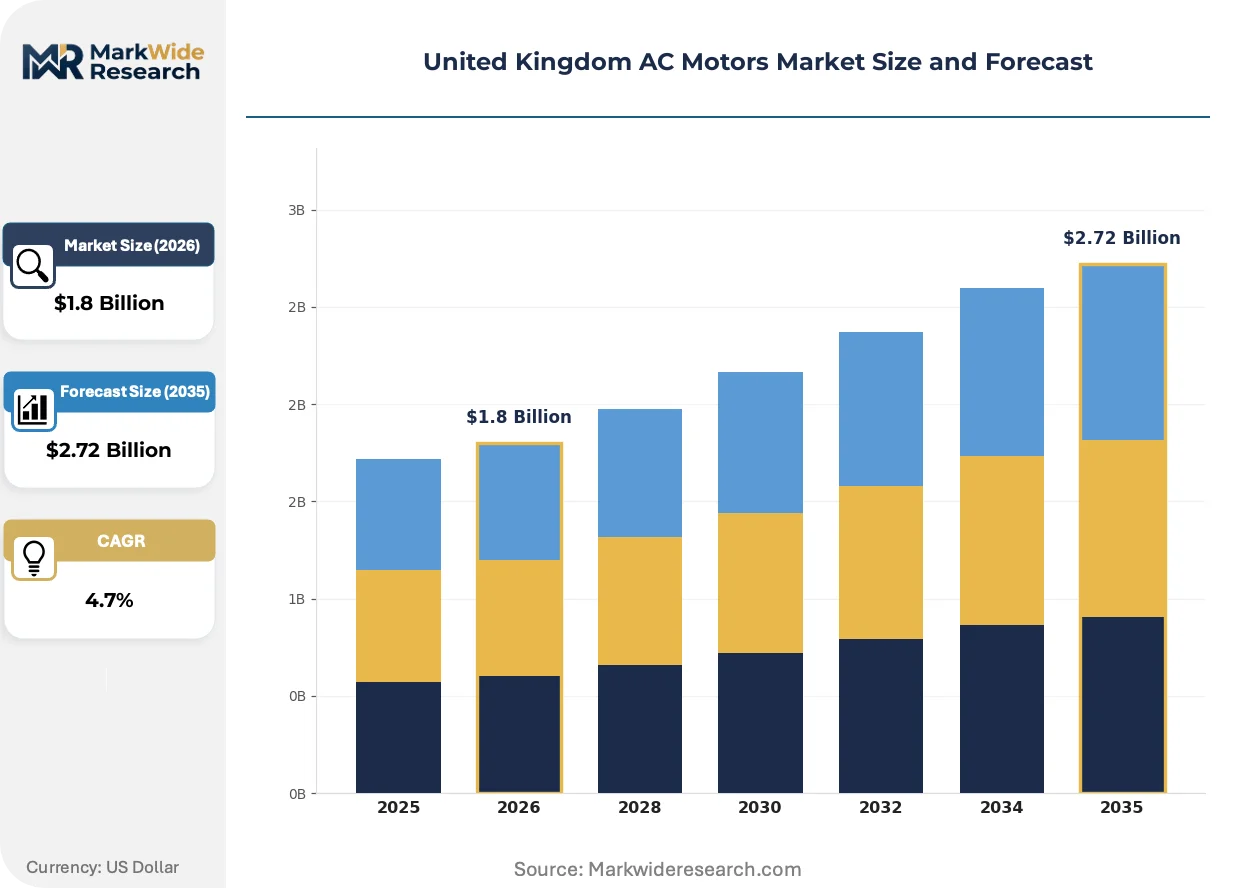
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Induction, Synchronous, Universal, Servo Application: Industrial Equipment, HVAC Systems, Home Appliances, Robotics Power Rating: Low Power, Medium Power, High Power, Special Purpose End User: Manufacturing, Automation, Construction, Transportation |
| Companies Covered | ABB Ltd, Siemens AG, Johnson Electric International (UK) Ltd, Rockwell Automation, Nidec Corporation, Brook Crompton, YASA Limited, Regal Rexnord Corporation, Toshiba Mitsubishi-Electric Industrial Systems Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom AC Motors Market Trends and Innovations
Digitalization of motor systems is rewiring how value is captured across the equipment lifecycle, with hardware margins compressing while software-enabled service contracts expand addressable revenue per installed unit.
Permanent magnet-assisted synchronous reluctance motor technology is modularizing industrial drive architectures by enabling standardized frame sizes across wider power and speed ranges. Food and beverage processors in the East Midlands are adopting these platforms to reduce spare parts inventory. The technology is modularizing supplier-customer relationships around configurable subsystems rather than fixed-product catalogs.
The Environment Agency's F-Gas Regulation enforcement tightens leak detection requirements for refrigeration compressor motors, compelling cold chain operators to specify sealed-for-life bearing systems and improved winding encapsulation. Cold storage facilities in England's logistics corridors are prioritizing motors with extended maintenance intervals to minimize refrigerant exposure risks. Process refrigeration OEMs are responding with integrated motor-compressor units that eliminate shaft seals.
Industrial buyers are consolidating vendor relationships around full-system accountability, replacing transactional motor procurement with multi-year performance contracts. Water utilities and district heating operators now require suppliers to guarantee energy consumption outcomes, not just equipment specifications. This behavioral shift concentrates contract awards among vendors with in-house automation and analytics capabilities, visible in Yorkshire's municipal infrastructure tenders.
United Kingdom AC Motors Market Segmentation
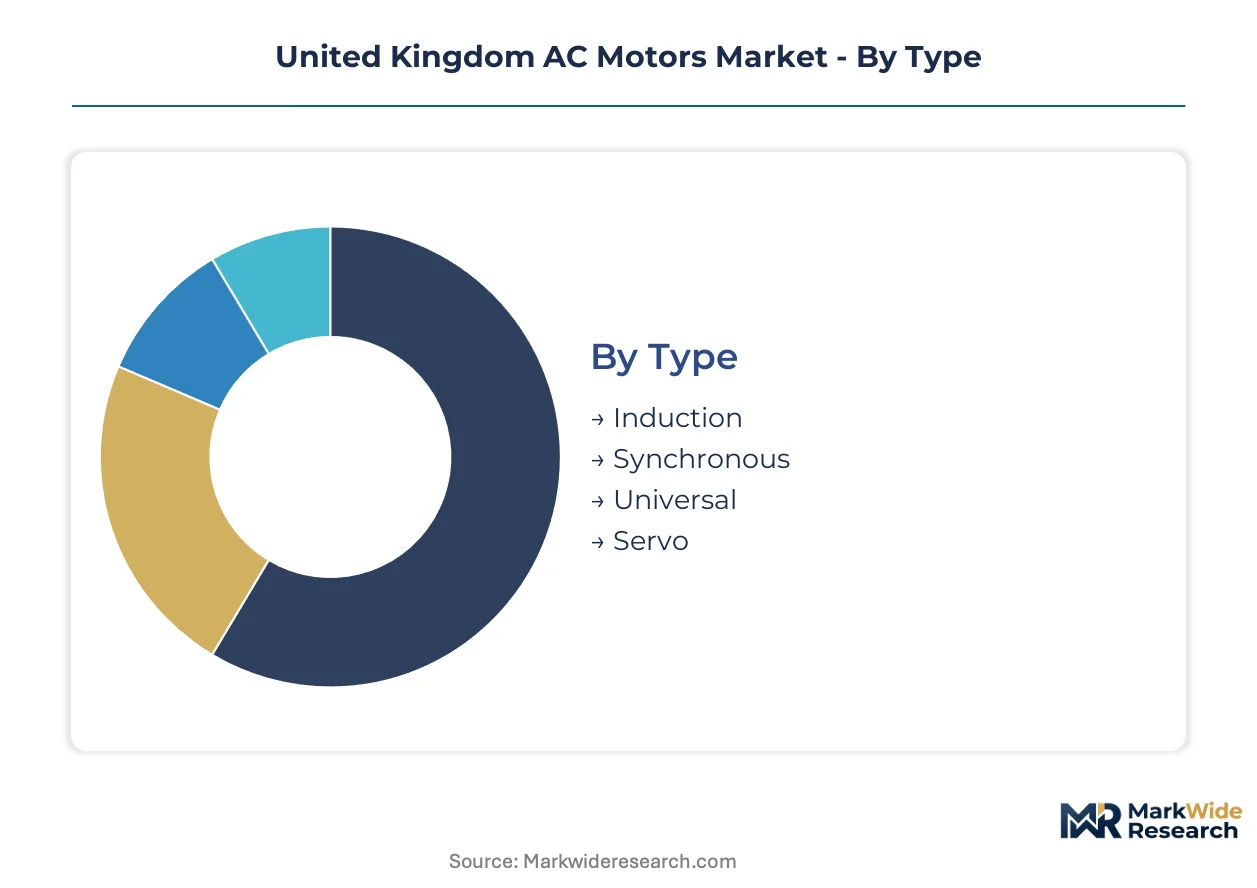
AC motor procurement in the UK diverges sharply across buyer archetypes, with industrial facilities prioritizing efficiency compliance under MEES while HVAC contractors optimize for retrofit compatibility. Understanding these segment-specific decision criteria exposes where margin pools concentrate and which specifications command pricing power.
Type:
Selection criteria pivot on torque precision requirements versus maintenance burden tolerance, with facility engineers trading off capital cost against lifecycle operating expense.
- Induction:Rugged squirrel-cage construction dominates UK manufacturing floors due to minimal servicing needs and proven reliability under dust-laden conditions. Demand concentrates in England's Midlands manufacturing belt, where automotive and metalworking plants specify these units for conveyor drives and pump stations under tight uptime constraints.
- Synchronous:Permanent magnet and reluctance variants deliver precise speed holding for process-critical applications, with water utilities specifying these for pumping stations requiring flow rate accuracy. Yorkshire's municipal infrastructure tenders increasingly mandate synchronous platforms for energy recovery guarantees.
- Universal:Series-wound commutator designs operate on AC or DC supplies, finding niche deployment in portable power tools and domestic appliances where variable speed control outweighs efficiency penalties.
- Servo:Closed-loop positioning systems with encoder feedback enable robotic workcells and CNC machinery, gaining share in precision automation corridors around Oxfordshire and Cambridgeshire.
Volume sits with Induction; growth tilts toward Servo.
Application:
End-use context dictates efficiency tier, with regulatory deadlines compressing replacement schedules in commercial building systems while industrial process lines follow asset lifecycle economics.
- Industrial Equipment:Compressors, conveyors, and material handling systems across UK manufacturing sites specify medium and high-power induction units. Scotland's offshore wind nacelle assembly facilities are creating concentrated demand for heavy-duty motors in crane and positioning systems.
- HVAC Systems:Fan, chiller, and air handling unit motors face accelerated replacement under MEES compliance deadlines. England's commercial office stock in London and Manchester is driving IE4 and IE5 specification for leased properties.
- Home Appliances:Washing machines, refrigerators, and vacuum cleaners incorporate fractional horsepower universal and induction motors, with efficiency regulations pushing toward electronically commutated alternatives.
- Robotics:Articulated arms and autonomous mobile robots deploy high-dynamic servo motors, with East Midlands food processors adopting these platforms for packaging line flexibility.
Procurement volume clusters in HVAC Systems; steepest expansion trajectory appears in Robotics.
Power Rating:
Capital allocation thresholds separate project-based infrastructure investment from maintenance-budget replacement cycles, with water utilities and district heating operators commanding largest unit sizes.
- Low Power:Fractional horsepower units below 0.75 kW serve appliances, small pumps, and ventilation fans. Domestic heat pump manufacturing scaling in the West Midlands is concentrating orders for compressor motors in this bracket.
- Medium Power:0.75 kW to 375 kW ratings capture substantial margin pools across HVAC and pumping applications, with variable-speed drive pairing now standard specification. Thames Water infrastructure renewal programs are sustaining demand for these units.
- High Power:Above 375 kW, these motors drive heavy process equipment in chemicals, steel, and water treatment. Aberdeen's port infrastructure development for offshore wind is creating demand for high-power propulsion and lifting systems.
- Special Purpose:Explosion-proof, submersible, and brake motor variants address hazardous environments and vertical mounting constraints, with hydrogen electrolyzer deployments opening specification work for certified suppliers.
Medium Power anchors revenue; Special Purpose climbs fastest on energy transition capex.
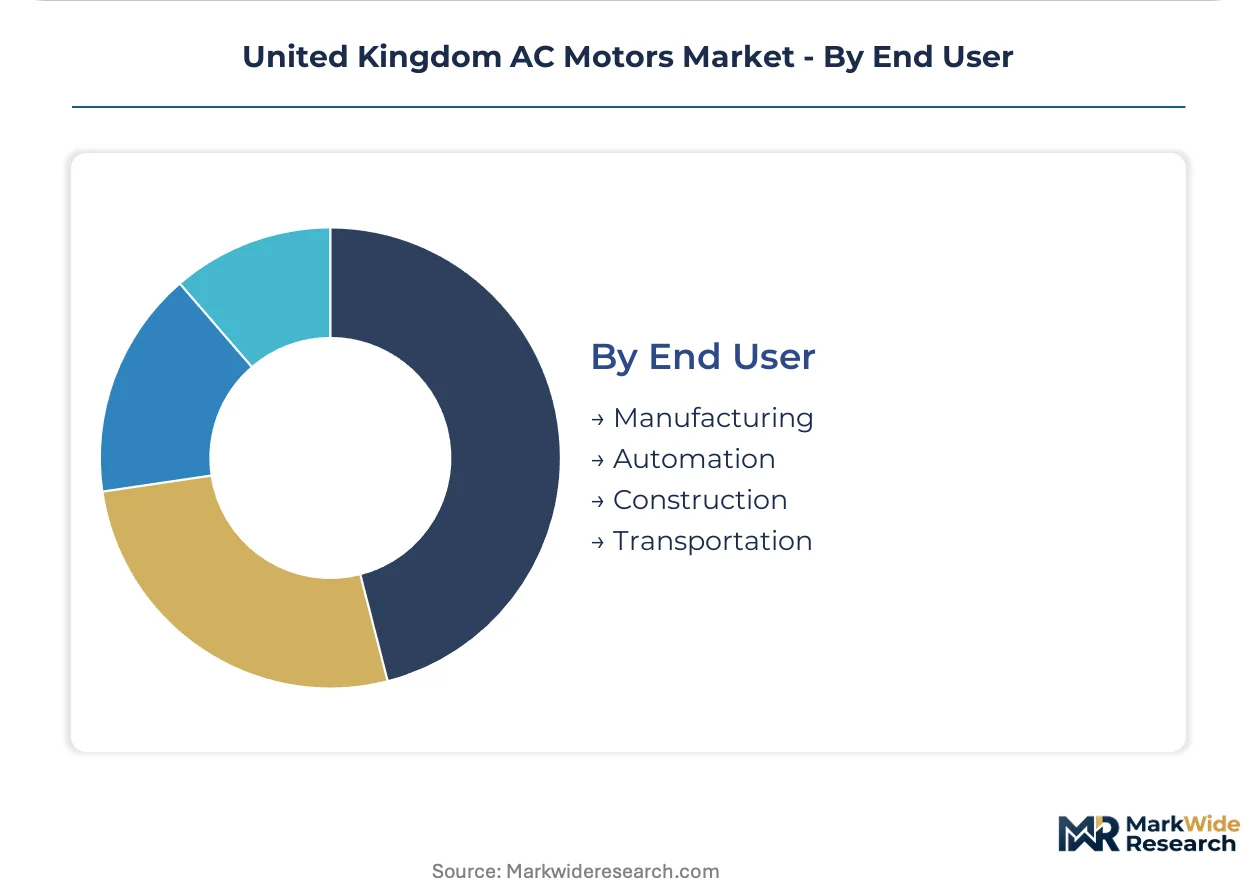
End User:
Organizational procurement maturity determines contract structure, with sophisticated buyers demanding performance guarantees while smaller operators transact on equipment specification alone.
- Manufacturing:Automotive, food and beverage, and metal fabrication facilities specify motors for production line reliability, with East Midlands processors consolidating vendor relationships around full-system accountability contracts.
- Automation:System integrators and OEM machine builders source servo and precision induction platforms, prioritizing delivery certainty and technical support over unit cost minimization.
- Construction:Temporary power and material handling equipment deploy rugged portable motors, with infrastructure project pipelines in northern England sustaining rental fleet demand.
- Transportation:Rail traction, marine propulsion, and airport ground support equipment require specialized high-reliability designs, with Scotland's offshore vessel fleet creating niche specification opportunities.
Manufacturing holds installed base dominance; Automation gains share on reshoring investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United Kingdom consumes more AC motors than it manufactures, importing premium efficiency units from European and Asian production bases while domestic assembly concentrates in England's industrial Midlands.
London and Southeast England
Commercial building modernization drives IE4 and IE5 motor demand across the capital's office stock. The Environment Agency enforces F-Gas Regulation compliance in refrigeration systems. Heathrow Airport's cargo handling expansion sustains orders for high-reliability conveyor motors.
Midlands
Automotive and metalworking plants specify rugged induction units for production line reliability. MEES regulations accelerate HVAC replacement in Birmingham's commercial property portfolio. Derbyshire food processors adopt permanent magnet-assisted synchronous reluctance platforms to reduce spare parts inventory.
North England
Water infrastructure renewal programs at United Utilities create sustained demand for medium-power pumping motors. The UK's retained Ecodesign framework shapes efficiency compliance for imported equipment. Yorkshire's municipal infrastructure tenders increasingly mandate synchronous platforms for energy recovery guarantees.
Scotland
Offshore wind supply chain development at Aberdeen and Dundee ports generates demand for high-power propulsion and lifting systems. Scotland's devolved energy efficiency programs complement UK-wide MEES standards. Glasgow's district heating operators now require suppliers to guarantee energy consumption outcomes.
Wales
Steel and chemicals processing in Port Talbot commands heavy-duty motor specifications for continuous operation. Welsh government industrial decarbonization schemes support efficiency upgrade investments. Newport's manufacturing corridor attracts automation equipment suppliers serving precision assembly applications.
United Kingdom AC Motors Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the United Kingdom AC Motors Market. Integrated automation conglomerates anchor the premium tier through bundled hardware-software offerings, while specialized motor fabricators occupy retrofit niches where compatibility constraints limit supplier switching. Component specialists and regional distributors fill gaps between these poles. Competitive positioning hardens around predictive maintenance contracts and energy performance guarantees rather than unit price alone.
Within the integrated automation tier, ABB Ltd and Siemens AG exemplify platform-scale competitors anchoring long-term service relationships through digital ecosystems. Brook Crompton occupies a specialist position in bespoke low-voltage induction motors where process industry retrofit requirements control procurement decisions. These three represent distinct archetypes: the full-system integrator, the automation platform vendor, and the application-specific fabricator.
| Leading Market Players |
|---|
| ABB Ltd |
| Siemens AG |
| Johnson Electric International (UK) Ltd |
| Rockwell Automation |
| Nidec Corporation |
| Brook Crompton |
| YASA Limited |
| Regal Rexnord Corporation |
| Toshiba Mitsubishi-Electric Industrial Systems Corporation |
| Others |
Pricing and Supply Chain Analysis
Captive winding production in Germany and Poland anchors pricing power for premium efficiency motor tiers serving UK industrial buyers, while outsourced stator assembly in Southeast Asia supports economy segments exposed to raw material volatility. This bifurcation concentrates margin protection among vertically integrated European producers while compressing returns for import-dependent distributors.
Pricing Analysis
Margin tightening in IE4 and IE5 premium tiers reflects copper and rare-earth magnet cost pass-through limitations under long-term utility contracts. Three-tier pricing structure across premium efficiency, standard efficiency, and economy levels stratifies by certification grade and predictive maintenance bundling. Pricing pressure stems from MEES-driven bulk procurement by property management firms. HVAC contractors show highest price sensitivity; water utilities with energy-guarantee contracts show lowest.
Supply Chain Analysis
UKCA marking requirements and retained Ecodesign obligations are reshaping sourcing toward EU-based final assembly with UK distribution warehousing. Manufacturing concentrates in Germany, Poland, and China. Winding copper, permanent magnet materials, and bearing assemblies constitute critical input dependencies. Single-source vulnerability sits with Chinese rare-earth processing. Distribution runs through electrical wholesalers and direct OEM supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom AC Motors Market reads as a cost-of-compliance story where MEES regulations and F-Gas phase-down timelines erect barrier-to-entry moats favoring certified incumbents with established UKCA pathways.
For Market Incumbents: Deepen predictive maintenance bundling to lock in multi-year service contracts against emerging automation-platform competitors. Expand in-house magnet recycling capabilities to offset Chinese supply concentration risk. Prioritize IE5 certification investment ahead of anticipated efficiency tier tightening. For New Entrants and Emerging Players: Begin with hydrogen compression motor specification work in Aberdeen and Teesside industrial clusters where explosion-proof certification requirements limit incumbent saturation. Target Scotland's offshore wind port infrastructure as the most penetrable geography. Pursue joint development agreements with electrolyzer OEMs rather than direct motor sales. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated automation conglomerates seeking UK service footprints. Five-to-ten-year viability favors specialists with captive digital diagnostics platforms over commodity motor assemblers. Monitor BSI certification backlog durations as the signal indicating regulatory capacity constraints that advantage established players.| Strategic Initiative | Industry Significance |
|---|---|
| IE5 Efficiency Certification Investment | BSI testing capacity constraints create first-mover advantage for compliant suppliers ahead of regulatory tightening. |
| Predictive Maintenance Platform Integration | Vibration analytics bundled with motor sales generate recurring revenue from Yorkshire water utility tenders. |
| Permanent Magnet Recycling Capability | In-house rare-earth recovery reduces exposure to Chinese supply concentration and price volatility. |
| Hydrogen Infrastructure Partnership | Explosion-proof motor development with electrolyzer OEMs opens niche specification work in Aberdeen. |
| Midlands Assembly Footprint Expansion | Domestic production proximity to Derbyshire food processors shortens retrofit lead times. |
Research Methodology
Document review covered trade association technical standards, Environment Agency enforcement notices, and customs import records, complemented by interviews with maintenance directors at Midlands manufacturing facilities, procurement leads at water utilities, HVAC contractor specification engineers, and aftermarket service heads at electrical distributors. Secondary sources included BEIS energy efficiency publications, BSI certification databases, and EU-UK Trade and Cooperation Agreement regulatory continuity documents. Bottom-up unit demand estimates triangulated against top-down industrial energy consumption projections.
Historical efficiency tier adoption curves cross-referenced against panel input from motor OEM product managers and systems integrators across the projection horizon. Segmentation modeling captured motor type, power rating, application, and end-user procurement maturity. CAGRs derived from regression analysis of replacement cycle compression under MEES deadlines and heat pump manufacturing scaling assumptions.
Copper price volatility, UK-EU regulatory divergence timelines, and offshore wind deployment pacing are the dominant revision risks to installed base and revenue forecasts. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Gearless Elevator Traction Motor Market
Industrial Motors
Servo Motors and Drives Market
Industrial Motors
Japan AC Motor Market
Industrial Motors
Inverter Duty Motors Market
Industrial Motors
Industrial Motor Market
Industrial Motors
AC Servo Motors and Drives Market
Industrial Motors
Global Refrigeration Oil Market
Industrial Motors
Spargers Market
Industrial Motors
Crude Heater Market
Industrial Motors
Europe Tank Insulation Market
Industrial Motors
Variable Speed Drive Market
Industrial Motors
Power Scraper Market
Industrial Motors
Flatwire & HAIR-PIN Motor Market
Industrial Motors
Gear Reduction Motors Market
Industrial Motors
Smart Motors Market
Industrial Motors
North America Induction Motor Market