
 Global Emergency Medical Service (EMS) Products Market | 2026-2036
Global Emergency Medical Service (EMS) Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global Emergency Medical Service (EMS) Products Market Intelligence
The European Union's Green Deal, with its focus on sustainable product lifecycles, is realigning procurement criteria for EMS equipment. Large-scale operators like Global Medical Response influence product development through extensive procurement contracts for their fleets. Falck A/S competes on service integration, demanding interoperable diagnostic and patient monitoring systems across its international operations. PHI Air Medical, a key player in aeromedical services, drives demand for compact ventilators and ruggedized defibrillators.
Emergency Medical Service (EMS) products encompass a range of durable and disposable medical equipment used in pre-hospital care settings. These devices, including defibrillators and patient monitors, must often meet stringent standards for portability, durability, and electromagnetic compatibility, such as IEC 60601. Defibrillators and patient monitors represent mature product categories, but innovation in cardiac care applications continues to drive value. The fastest-growing demand comes from air ambulance services and disaster response teams, which require specialized emergency kits and patient transport stretchers.
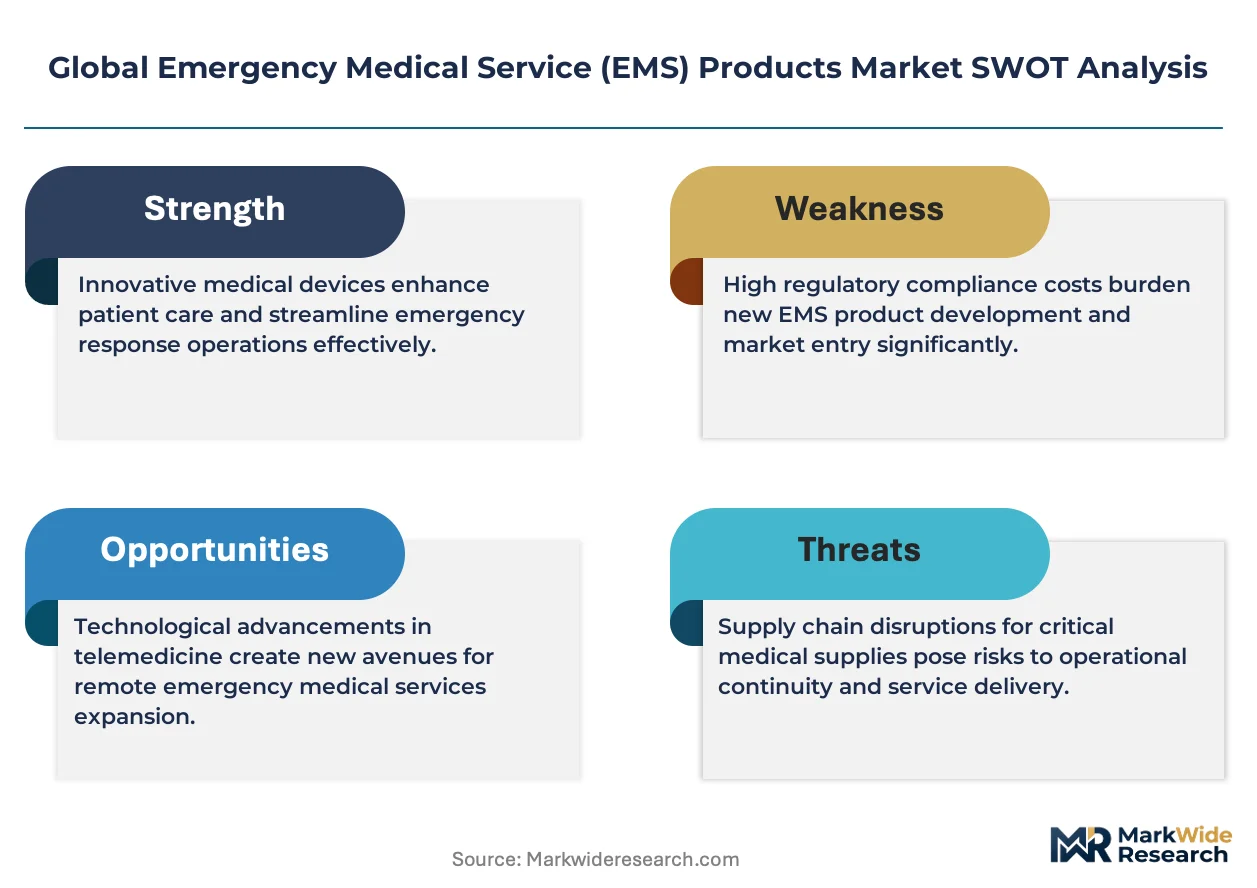
Regulatory oversight from bodies like the U.S. Food and Drug Administration (FDA) and compliance with Europe's CE marking requirements under the MDR are critical for market access. In Japan, the PMDA imposes similar stringent approval processes. These frameworks mandate rigorous testing for device safety and clinical efficacy, directly shaping product design. Stakeholders must now decide how to balance investment in next-generation connectivity features against the rising costs of global regulatory compliance.
Market Dynamics
The central tension in the EMS products market is the conflict between escalating global regulatory compliance costs, such as those from the EU's MDR, and the simultaneous demand from providers for more advanced, data-connected, and interoperable emergency medical equipment.
Growth Catalysts
- Geographic Expansion:China's initiative to upgrade its national first-aid network creates substantial demand for pre-hospital equipment across urban and rural settings.
- Aeromedical Requirements:Growth in air ambulance services drives the market for specialized lightweight, compact, and flight-certified patient monitors and ventilators.
- Sustainable Procurement:The EU Green Deal influences purchasing criteria, favoring manufacturers who design for recyclability and reduced environmental impact.
Market Restraints
- Regulatory Fragmentation:Navigating divergent approval processes from the FDA, EU MDR, and Japan's PMDA increases development costs and time-to-market.
- Interoperability Barriers:A lack of universal communication standards hinders the integration of devices, impeding seamless patient data flow for large EMS providers.
- High Compliance Costs:Meeting rigorous standards like IEC 60601 for durability requires extensive testing, adding significant overhead to product development.
Strategic Opportunities
- Predictive Diagnostics:Integrating AI into patient monitors for predictive cardiac event alerts offers a new value proposition in pre-hospital care.
- Mission-Specific Kits:Developing customized equipment for disaster response and tactical emergency medical support (TEMS) units addresses a high-value niche.
- Rural Network Expansion:Targeting markets like India with solutions for building new rural emergency response networks presents a major growth opportunity.
Industry Challenges
- Legacy System Integration:Ensuring new connected devices are compatible with the varied and outdated IT infrastructure of EMS agencies remains a significant hurdle.
- Certification Delays:Extensive documentation required by Europe's MDR and the FDA's 510(k) process creates unpredictable timelines for bringing products to market.
- Talent Scarcity:A shortage of engineers skilled in both ruggedized hardware and secure IoT connectivity constrains new product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Emergency Medical Service (EMS) Products Market |
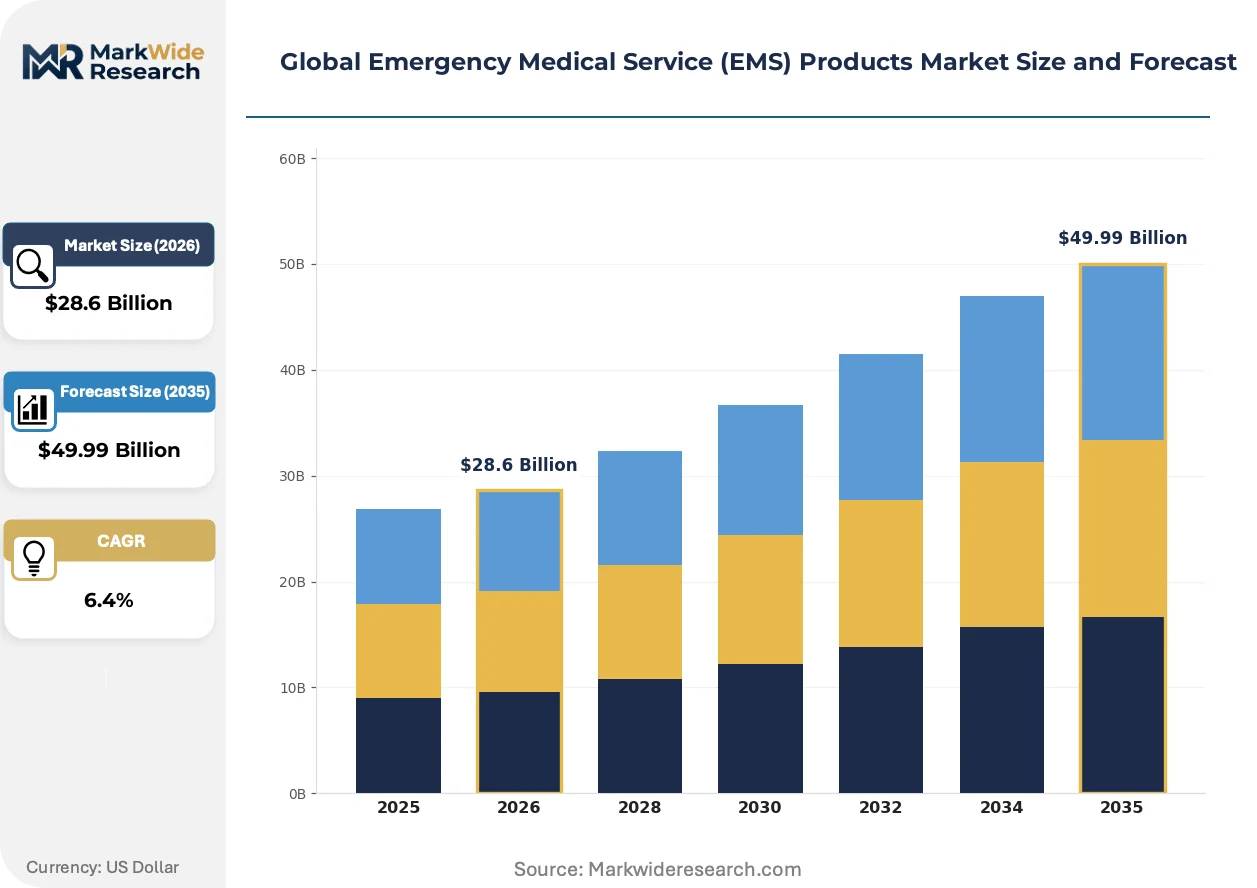
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $49.99 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Defibrillators, Ventilators, Stretchers, Patient Monitors, Emergency Kits, Diagnostic Devices Application: Trauma Response, Cardiac Care, Respiratory Assistance, Patient Transport, First Aid, Disaster Management End User: EMS Providers, Fire Departments, Law Enforcement, Disaster Response Teams, Military Medical Units, Air Ambulance Services Deployment: Mobile Ambulances, Emergency Rooms, Field Hospitals, Helicopter EMS, Rapid Response Vehicles, Community Health Centers |
| Companies Covered | PHI Air Medical, Falck A/S, Global Medical Response, Rural/Metro Corporation, Air Methods Corporation, American Medical Response, Babcock International Group PLC, Medstar, Acadian Ambulance Service, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Emergency Medical Service (EMS) Products Market Strategic Shifts & Innovations
Product evolution is defined by the dual pressures of data connectivity and extreme environmental resilience. The market is shifting from standalone hardware to integrated, data-centric ecosystems that must perform reliably in uncontrolled pre-hospital settings.
Miniaturization through advanced composite materials and compact electronics is a primary technological driver. Aeromedical services and rapid response teams are the fastest adopters, demanding smaller and lighter equipment. This trend is rewriting the form factor and portability standards for entire product categories, including transport ventilators and ruggedized patient monitors.
Europe's Medical Device Regulation (MDR) has fundamentally altered market access requirements. The regulation mandates more stringent clinical evidence and continuous post-market surveillance for all devices. Manufacturers of higher-risk products like defibrillators face the greatest impact, forcing portfolio reviews and increased investment in regulatory affairs.
A shift from transactional device sales toward integrated system procurement is altering buying patterns. Large EMS operators are increasingly seeking single-vendor solutions that bundle hardware, software, data management, and long-term service. This model is most prominent in North America, where network-wide interoperability is a critical decision factor.
Global Emergency Medical Service (EMS) Products Market Segmentation
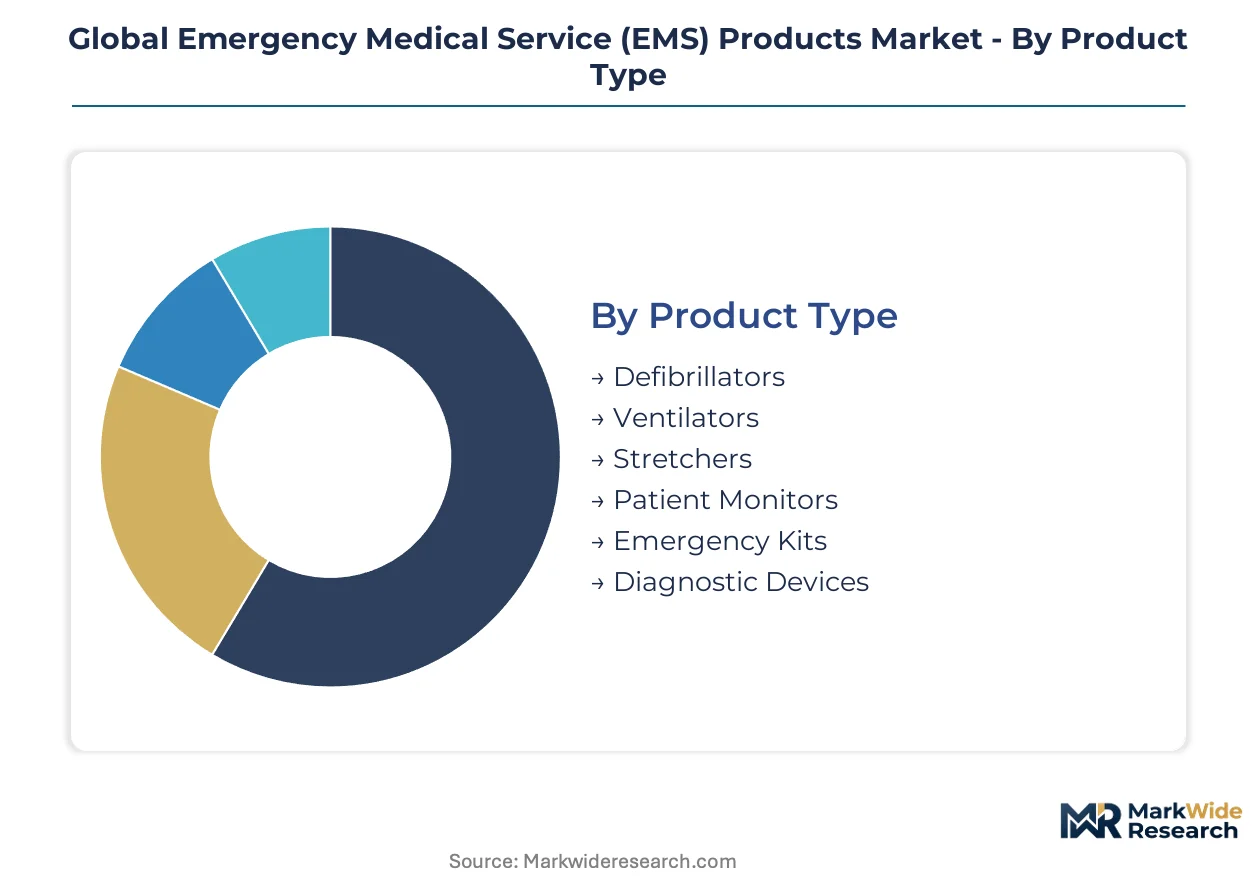
Understanding the varied requirements of pre-hospital care necessitates a detailed segmentation of the EMS products market. This segmentation clarifies how different product types, applications, end-users, and deployment settings influence product design and procurement strategies. Analyzing these distinct segments helps manufacturers tailor offerings to specific operational demands and regulatory landscapes.
Product Type:
Supply concentration for EMS products often depends on the complexity of manufacturing and regulatory hurdles for each device category.
- Defibrillators:These critical devices deliver controlled electrical shocks to restore normal heart rhythm during sudden cardiac arrest. Innovation in compact, automated external defibrillators (AEDs) drives demand in public access and aeromedical services across countries like Germany and Japan.
- Ventilators:Portable and compact ventilators provide respiratory support for patients in pre-hospital settings, often featuring advanced modes for complex medical conditions. Demand for flight-certified models is accelerating within air ambulance fleets in the United States and Australia.
- Stretchers:Patient transport stretchers are designed for safe and efficient movement of individuals, ranging from basic models to advanced power-lift systems.
- Patient Monitors:These devices track vital signs such as heart rate, blood pressure, and oxygen saturation during transport and initial assessment.
- Emergency Kits:Pre-assembled kits contain essential medical supplies and instruments for various emergency scenarios, including trauma and first aid.
- Diagnostic Devices:This category includes portable equipment like glucometers, ECG machines, and point-of-care ultrasound systems for rapid assessment.
Today's leader: Defibrillators. Tomorrow's challenger: Ventilators.
Application:
Application-specific complexity dictates specialized product features and training requirements across the EMS product landscape.
- Cardiac Care:Products for cardiac care focus on rapid diagnosis and intervention for heart-related emergencies, including advanced life support equipment. Innovation in predictive diagnostics for pre-hospital cardiac events is a significant value driver for EMS providers in the UK.
- Disaster Management:Equipment for disaster management emphasizes ruggedness, portability, and rapid deployment in challenging environments, often involving large-scale casualties. Demand for modular emergency kits is high from national disaster response teams in China and India.
- Trauma Response:This segment includes equipment for managing severe injuries, such as splints, bandages, and hemorrhage control devices.
- Respiratory Assistance:Products supporting respiratory function range from basic oxygen delivery systems to advanced non-invasive ventilation solutions.
- Patient Transport:This application focuses on devices ensuring patient safety and comfort during movement, including specialized stretchers and immobilization equipment.
- First Aid:Basic medical supplies and simple devices for immediate care at the scene of minor incidents fall into this category.
The Cardiac Care segment drives the largest share, while Disaster Management exhibits the steepest expansion trajectory.
End User:
Customer type and procurement influence shape product development, with large-scale operators often dictating specific design parameters for EMS products.
- Air Ambulance Services:These specialized units require lightweight, compact, and flight-certified equipment capable of operating under extreme conditions and limited space. PHI Air Medical's procurement patterns influence compact ventilator and ruggedized defibrillator designs.
- EMS Providers:This broad category includes public and private ambulance services that demand reliable, interoperable equipment for daily emergency response operations. Global Medical Response's extensive contracts drive product development for connected patient monitoring systems.
- Fire Departments:Often first responders, fire departments require durable and easy-to-use medical equipment for initial assessment and stabilization.
- Disaster Response Teams:These teams need highly portable, rugged, and self-sufficient medical equipment for deployment in remote or infrastructure-damaged areas.
- Military Medical Units:Military operations necessitate robust, field-ready medical devices designed for tactical environments and diverse injury patterns.
- Law Enforcement:Police units increasingly carry basic life support equipment for immediate intervention in critical incidents before EMS arrival.
Air Ambulance Services end-users command significant procurement, with EMS Providers demonstrating accelerated demand.
Deployment:
Environmental resilience requirements are paramount across deployment settings, influencing material selection and device ruggedization for EMS products.
- Helicopter EMS:Deployment in helicopters demands ultra-compact, lightweight, and vibration-resistant equipment to maximize patient care efficiency in confined spaces. Specialized patient monitors are designed to withstand altitude and electromagnetic interference.
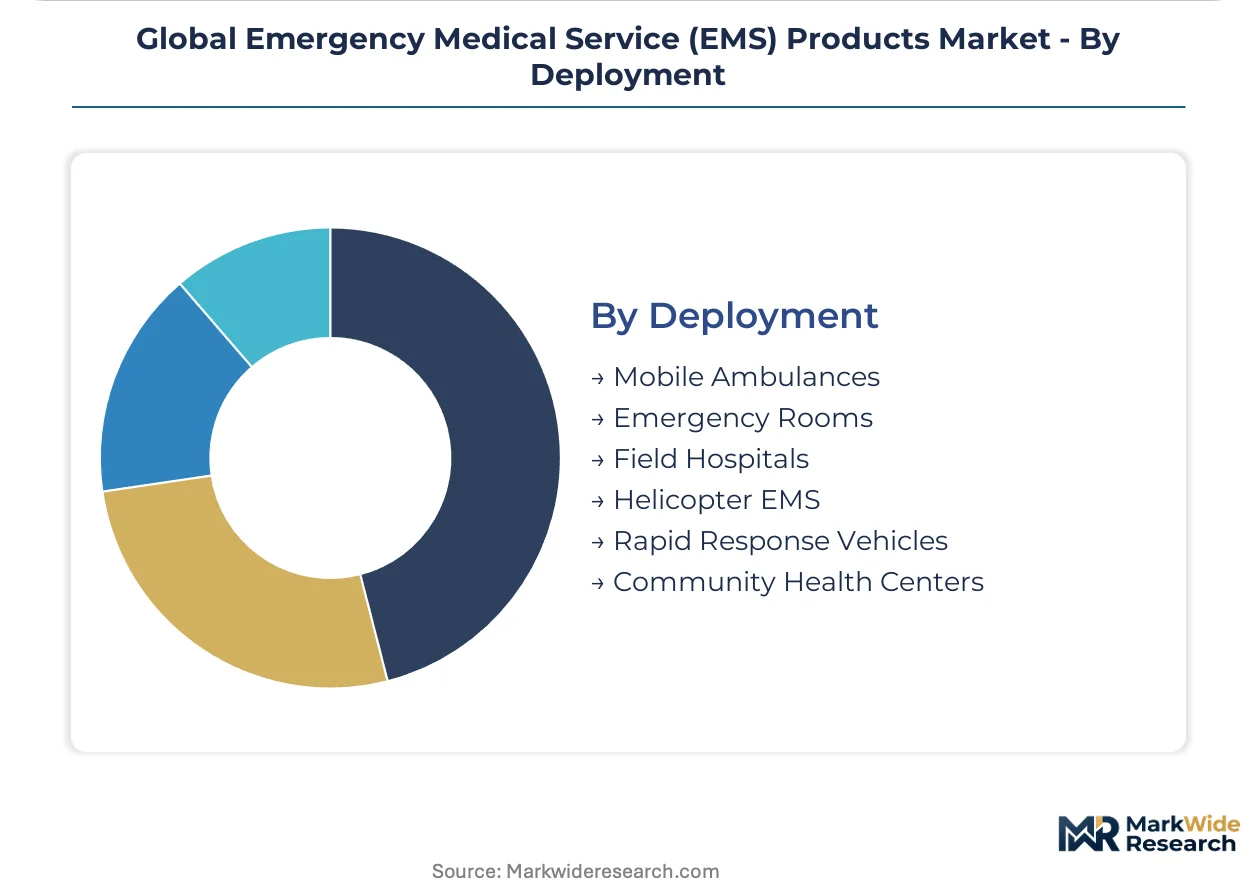
- Mobile Ambulances:These vehicles serve as the primary pre-hospital care environment, requiring durable, easily accessible, and integrated medical devices for a wide range of emergencies. China's national first-aid network upgrade creates substantial demand for robust ambulance equipment.
- Emergency Rooms:While not strictly pre-hospital, ERs serve as the immediate destination for many EMS transports, influencing device compatibility and data transfer protocols.
- Rapid Response Vehicles:Smaller, quicker vehicles often carry essential equipment for initial assessment and stabilization, prioritizing portability and rapid deployment.
- Field Hospitals:Temporary medical facilities require scalable and robust equipment solutions for mass casualty incidents or remote operations.
- Community Health Centers:These local centers use basic EMS products for immediate care and stabilization before transfer to higher-level facilities.
Deployment in Mobile Ambulances remains foundational, as Helicopter EMS environments demand specialized solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The emergency medical service products market historically scaled alongside advancements in military field medicine and the professionalization of pre-hospital care. Early innovations in medical transport and battlefield triage in the United States and Europe laid the groundwork for modern EMS systems. This foundational development shapes regional market dynamics.
United States
Demand for flight-certified equipment from air ambulance services, coupled with robust disaster response initiatives, drives the US market. The U.S. Food and Drug Administration (FDA) imposes rigorous 510(k) approval processes, influencing product design. Major medical device clusters in California and Massachusetts foster innovation in connectivity features.
Germany
Germany's market is characterized by strong demand for advanced pre-hospital cardiac care and public access defibrillators. Compliance with the European Union's Medical Device Regulation (MDR) dictates stringent certification requirements for medical devices. The Bavaria region, with its strong engineering base, is a hub for medical technology manufacturing.
China
China's ambitious national first-aid network upgrade generates significant demand for robust pre-hospital equipment across urban and rural settings. The National Medical Products Administration (NMPA) oversees device approvals, aligning with national health goals. The Yangtze River Delta economic zone leads in domestic medical device production and procurement.
Japan
Japan's market sees consistent demand for compact, automated external defibrillators (AEDs) and advanced patient monitoring systems, driven by its aging population. The Pharmaceuticals and Medical Devices Agency (PMDA) enforces stringent approval processes, emphasizing safety and efficacy. Tokyo and the Kansai region serve as key centers for medical technology research.
India
India exhibits substantial growth potential due to its focus on expanding rural emergency response networks and disaster management capabilities. The Central Drugs Standard Control Organization (CDSCO) regulates medical device imports and manufacturing, ensuring quality standards. States like Maharashtra and Karnataka are emerging as significant procurement and assembly hubs.
Global Emergency Medical Service (EMS) Products Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the EMS products market, creating a tiered competitive landscape. This market structure includes large-scale service operators, specialized medical device manufacturers, and technology innovators focusing on data integration. Strategic partnerships for interoperable solutions and targeted M&A activities dominate competitive moves. Companies aim to offer bundled hardware, software, and long-term service packages.
At the scale-driven end, Global Medical Response, a major US-based operator, exemplifies the influence of extensive procurement contracts on product development, particularly for connected patient monitoring systems. Denmark-based Falck A/S represents a significant integrated service provider, demanding interoperable diagnostic and patient monitoring systems across its international operations. PHI Air Medical, a key US-based player in aeromedical services, occupies a specialized niche, driving demand for compact ventilators and ruggedized defibrillators tailored for flight. These large operators shape the market through their specific fleet requirements.
| Leading Market Players |
|---|
| PHI Air Medical |
| Falck A/S |
| Global Medical Response |
| Rural/Metro Corporation |
| Air Methods Corporation |
| American Medical Response |
| Babcock International Group PLC |
| Medstar |
| Acadian Ambulance Service |
Cost & Logistics Intelligence
Large EMS operators, especially those with extensive fleets, dictate long-term contract pricing structures for integrated product and service bundles. This concentration influences how manufacturers approach product development and market positioning.
Pricing Analysis
Contract-based long-term offtake agreements define pricing for large EMS product procurements. Price differentiation stems from rigorous flight-certification requirements and extensive after-sales service packages. Pricing pressure intensifies for standard devices due to global regulatory compliance costs, while specialized, data-connected equipment commands premium pricing. Air ambulance services exhibit lower price sensitivity for mission-critical devices compared to community health centers purchasing basic first aid supplies.
Supply Chain Analysis
Direct-to-provider contracts manage distribution for major EMS operators, complemented by specialized distributors serving smaller agencies. Supply concentration for advanced medical electronics draws from Germany, the United States, and China's growing manufacturing base. Raw material dependencies include advanced composite materials for miniaturization and compact electronics for connectivity features. Regulatory fragmentation across diverse markets like the EU and Japan presents a structural risk, creating compliance bottlenecks for global manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EMS products market presents a margin-expansion story, driven by the premiumization of data-connected, specialized equipment for aeromedical and disaster response applications. Manufacturers can leverage advanced composite materials for cost-down efficiency while commanding higher prices for enhanced functionality.
For Market Incumbents: Anticipate rising regulatory costs from the EU's MDR by investing early in compliance and robust clinical evidence generation. Deepen vertical integration into secure IoT connectivity solutions to counter fragmentation from niche tech entrants. Reinforce procurement contracts with large operators like Global Medical Response by offering bundled hardware, software, and long-term service agreements. This strategy mitigates margin pressure from commoditization in mature product categories.
For New Entrants and Emerging Players: Launch via mission-specific kits tailored for disaster response teams, a high-value niche with less entrenched competition. Target India's expanding rural emergency response networks with cost-effective, ruggedized diagnostic devices. A go-to-market angle focusing on interoperable, open-standard device architecture can attract EMS providers frustrated by legacy system integration challenges. Focus on regions with less stringent initial regulatory hurdles for quicker market entry.
For Investors and Strategic Acquirers: Integrated service providers are the most active acquirers in this space, seeking to consolidate capabilities for a 5-10 year horizon. Target archetype: mid-sized manufacturers specializing in compact, flight-certified patient monitors or AI-driven predictive diagnostic software. The signal to watch is the adoption rate of universal communication standards for EMS devices, indicating a shift towards a more integrated ecosystem. This will unlock significant value through data monetization and operational efficiency.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in MDR/FDA Certification | Ensures market access and commands premium pricing for compliant medical devices. |
| Develop AI-Driven Predictive Diagnostics | Creates new value propositions for pre-hospital care, improving patient outcomes. |
| Partner for IoT Connectivity Standards | Facilitates seamless data flow and interoperability across diverse EMS equipment. |
| Expand into Rural Emergency Networks | Addresses significant growth opportunities in underserved regions like India and China. |
| Design for Sustainable Product Lifecycles | Aligns with EU Green Deal procurement criteria, enhancing competitive advantage. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with extensive secondary validation. Engagements included EMS medical directors, hospital procurement managers, device R&D engineers, and regulatory affairs specialists. Secondary data drew from FDA 510(k) databases, CE marking registries, national health expenditure reports, and medical device association publications. This approach facilitated bottom-up market sizing and top-down validation of segment projections.
Segment-weighting models underpinned the forecast framework, disaggregating the market by product type, application, end-user, deployment setting, and regional regulatory environment. Compound annual growth rates derived from historical data trends and projected shifts in healthcare infrastructure investment across the analysis window. Key forecast inputs included anticipated regulatory approval timelines for new device categories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under unforeseen regulatory changes or global supply chain disruptions. Projections reflect current market assumptions, acknowledging potential shifts from evolving pre-hospital care models. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency and Disaster Management
EHS Market
Emergency and Disaster Management
Emergency Shutdown System Market
Emergency and Disaster Management
Emergency Location Transmitter Market
Emergency and Disaster Management
Hazard Control Market
Emergency and Disaster Management
Advanced Disaster Management Simulator Market
Emergency and Disaster Management
Cyber Crisis Management Market
Emergency and Disaster Management
Earthquake Early Warning System Market
Emergency and Disaster Management
Global Emergency Beacon Transmitter Market
Emergency and Disaster Management
Crisis Emergency and Incident Management Platform Market
Emergency and Disaster Management
Automatic Floodgate Market
Emergency and Disaster Management
North America Homeland Security and Emergency Management Market
Emergency and Disaster Management
Survival Tools Market
Emergency and Disaster Management
Intelligent Evacuation System Market
Emergency and Disaster Management
Incident and Emergency Management Market
Emergency and Disaster Management
Global Emergency Notification Software Market
Emergency and Disaster Management
Emergency and Disaster Response Market