
 Global Personal Emergency Response Systems (PERS) Market | 2026-2036
Global Personal Emergency Response Systems (PERS) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Personal Emergency Response Systems (PERS) Market Foresight
Silicon-based microelectromechanical systems (MEMS) accelerometers are broadening cost-performance boundaries in fall-detection wearables, displacing legacy mechanical tilt sensors across mid-tier product lines. Koninklijke Philips N.V. leverages integrated health informatics platforms to sustain premium positioning in hospital-to-home transition programs. Bay Alarm Medical anchors direct-to-consumer subscription economics through vertically owned monitoring centers in California and Arizona. Tunstall Healthcare Group Ltd. competes on European public-sector procurement frameworks with localized language support and national health service contracts.
Personal Emergency Response Systems comprise wearable pendants, wristbands, wall-mounted consoles, and smartphone-connected hubs that transmit alarm signals through cellular, Bluetooth, or satellite networks to centralized monitoring stations staffed by trained response coordinators, with typical device battery life spanning 24 to 72 hours of active signaling. These systems serve primarily to reduce mortality and morbidity from unwitnessed falls, medication emergencies, and cardiovascular events among solitary-dwelling vulnerable populations. Wearable Devices command the largest revenue share due to miniaturization advances in GPS and biometrics integration, while Hybrid Systems represent the fastest-expanding category as users demand seamless transitions between fixed-home and mobile-away coverage. Cellular technology dominates connectivity architecture given 4G and 5G network densification, though Satellite is gaining traction in rural and mountainous terrains where terrestrial coverage remains inconsistent.
The FDA classifies PERS hardware as Class II medical devices requiring 510(k) premarket notification, while the EU MDR imposes stricter clinical evidence and post-market surveillance obligations on manufacturers seeking CE marking for European distribution. Japan's PMDA enforces JIS standards for electromagnetic compatibility and battery safety that create incremental certification burdens for foreign entrants. Stakeholders must monitor evolving reimbursement codes in national health systems and calibrate product portfolios between subsidized basic alert functionality and unsubsidized premium biometric monitoring tiers.
Market Dynamics
Cellular network densification and MEMS sensor cost curves are compressing hardware margins while expanding addressable populations beyond institutional purchasers into direct-to-consumer channels.
Growth Catalysts
- Medicare Advantage supplemental benefit expansion:United States reimbursement codes now cover monitored emergency response services, broadening access for aging-in-place seniors.
- EU Medical Device Regulation (MDR) compliance investments:Stricter clinical evidence requirements for CE marking are consolidating vendor bases and favoring scaled manufacturers with regulatory infrastructure.
- Silicon MEMS accelerometer adoption:Miniaturized fall-detection sensors are displacing mechanical tilt sensors across mid-tier wearable lines, enabling biometric integration at lower unit economics.
Market Restraints
- Lithium-ion battery supply concentration:Cathode material processing clusters in East Asia create input cost volatility and geopolitical exposure for device manufacturers.
- FDA 510(k) notification timelines:Class II medical device clearance processes extend product launch windows by 12-18 months, compressing first-mover advantages.
- Smartphone-native emergency features:Built-in fall detection and SOS protocols in mass-market handsets substitute basic PERS functionality for price-sensitive consumers.
Strategic Opportunities
- Rural satellite connectivity penetration:Mountainous and remote terrain in the United States and Alpine Europe remains underserved by terrestrial cellular, opening niche positioning for hybrid satellite-cellular hubs.
- Hospital-to-home transition programs:Post-acute care discharge protocols in Germany and the Netherlands are embedding PERS into bundled reimbursement for cardiac and orthopedic recovery.
- AI-enabled predictive analytics convergence:Machine learning models applied to accelerometer and heart rate variability data are enabling pre-fall intervention alerts before physical incidents occur.
Industry Challenges
- Embedded firmware cybersecurity certification:IEC 62304 medical device software lifecycle standards require specialized engineering talent scarce outside established health technology clusters.
- Legacy landline infrastructure dependency:Plain old telephone service (POTS) sunset mandates in the United States force hardware refreshes for installed base units, straining customer retention economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Personal Emergency Response Systems (PERS) Market |
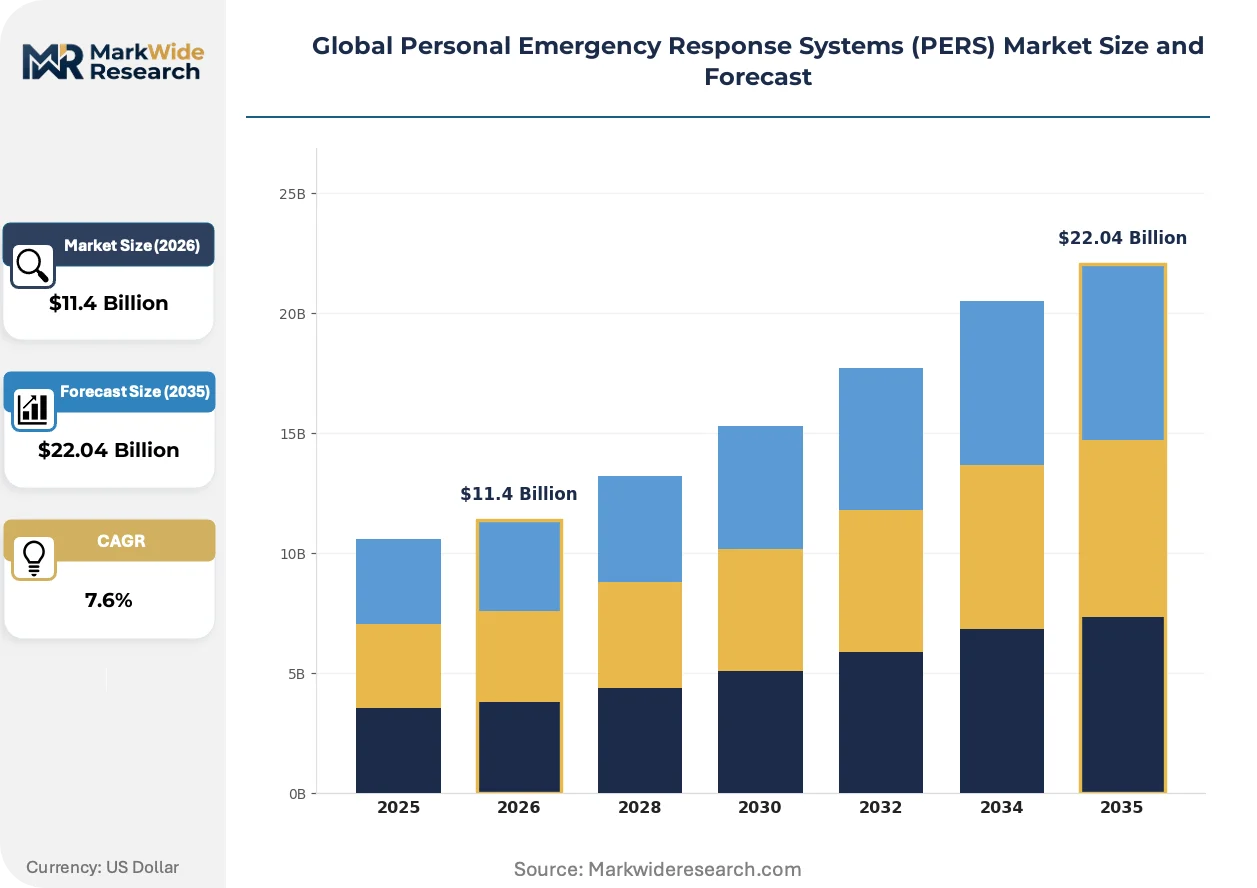
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $22.04 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Fixed Devices, Mobile Apps, Hybrid Systems Technology: Bluetooth, Cellular, Wi-Fi, Satellite End User: Senior Citizens, Disabled Individuals, Caregivers, Healthcare Facilities Service Type: Monitoring Services, Emergency Response, Maintenance, Installation |
| Companies Covered | ADT Inc., Life Alert Emergency Response Inc., Bay Alarm Medical, Koninklijke Philips N.V., Tunstall Healthcare Group Ltd., Medical Guardian, ConnectAmerica LLC, AlertONE Services Inc., MobileHelp LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Personal Emergency Response Systems (PERS) Market Shifts & Advancements
Edge computing architectures and biometric sensor fusion are redefining what constitutes a medical-grade alert versus a wellness notification, blurring traditional regulatory boundaries.
Bluetooth Low Energy mesh networking is decentralizing home coverage architecture. Senior housing operators and multi-generational households are adopting distributed beacon arrays that eliminate single-point-of-failure console dependencies. This topology reduces per-unit hardware costs while enabling room-level location precision for response dispatch.
The EU MDR's post-market surveillance obligations are extending clinical evidence requirements beyond premarket submission. Manufacturers must now maintain active safety registries and periodic safety update reports, increasing regulatory affairs headcount. Small and mid-cap vendors without European notified body relationships are exiting the market or partnering with larger CE-mark holders.
Subscription unbundling is fragmenting the traditional monitored service model. Direct-to-consumer purchasers in the United States increasingly favor self-monitored apps with optional dispatch upgrades over mandatory 24/7 center contracts. This shift compresses recurring revenue per subscriber while expanding total addressable user volume through lower entry price points.
Global Personal Emergency Response Systems (PERS) Market Segmentation
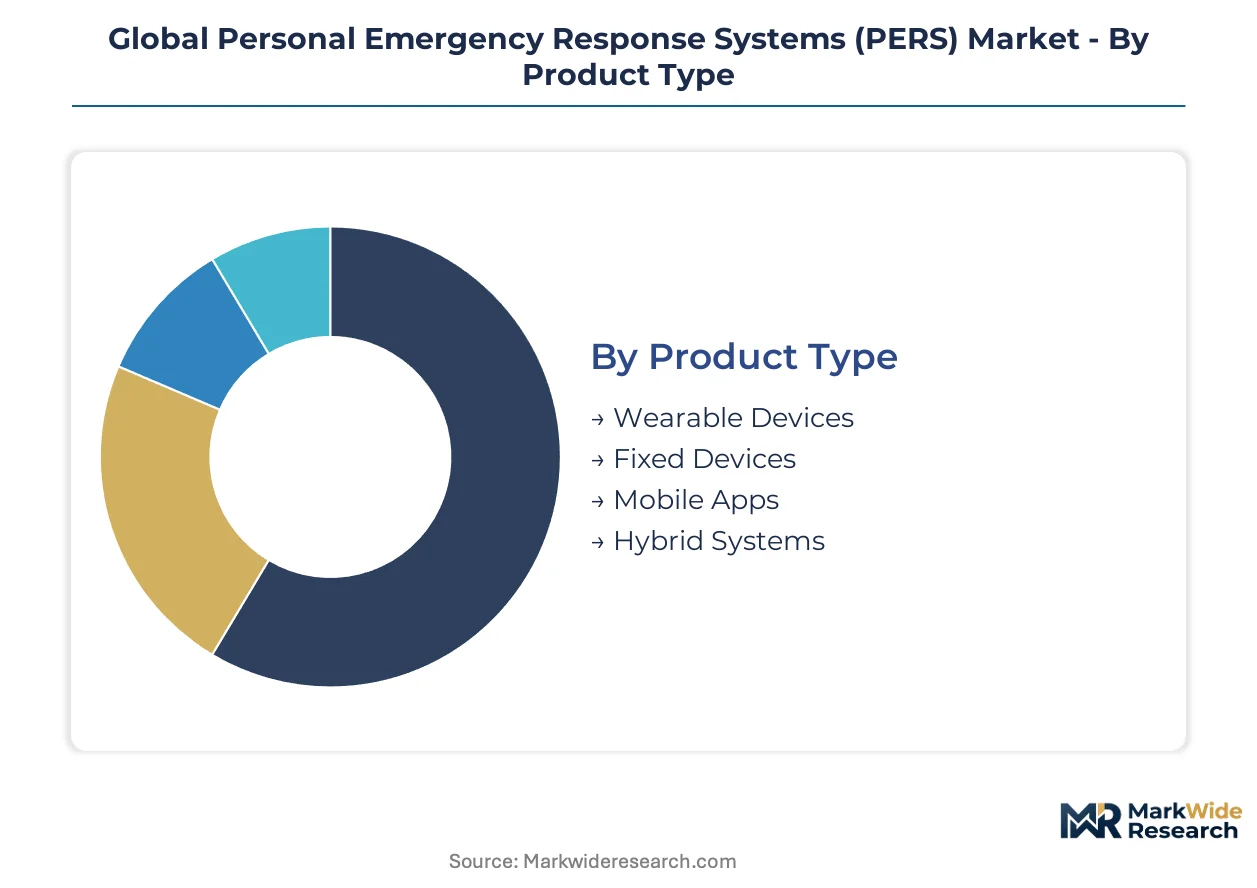
PERS market segmentation reveals divergent margin structures across hardware, connectivity, and service layers. Product type and technology choices determine whether vendors compete on subscription lifetime value or upfront equipment sales.
Product Type:
Volume concentrates in entry-level wearables while premium economics flow to integrated hybrid architectures.
- Wearable Devices:Miniaturized pendants and wristbands integrate GPS, accelerometers, and biometrics for mobile fall detection. Demand clusters in United States Medicare Advantage enrollees seeking aging-in-place solutions, driven by supplemental benefit reimbursement expansion.
- Hybrid Systems:Dual-mode hubs transition seamlessly between fixed-home cellular coverage and mobile-away satellite backup. Germany and Alpine European territories show concentration as rural connectivity gaps persist, with users paying premiums for uninterrupted geographic coverage.
- Fixed Devices:Wall-mounted consoles with speakerphone connectivity serve budget-conscious institutional purchasers.
- Mobile Apps:Smartphone-native solutions leverage existing device ownership for self-monitored alert functionality.
Today's leader: Wearable Devices. Tomorrow's challenger: Hybrid Systems.
Technology:
Connectivity economics split between ubiquitous terrestrial networks and specialized satellite overlays for coverage gaps.
- Cellular:4G and 5G network densification enables reliable alarm transmission with minimal infrastructure investment. United States and Japanese deployments dominate volume as carrier partnerships reduce subscriber acquisition costs for monitoring centers.
- Satellite:Low-earth orbit and geostationary links serve mountainous United States regions and Nordic rural zones where cellular towers remain uneconomical. Hardware premiums of 40-60% over cellular-only units limit addressable population.
- Bluetooth:Low-energy mesh networks enable room-level precision in senior housing without cellular subscription dependency.
- Wi-Fi:Home-bound connectivity for cost-sensitive users with reliable broadband infrastructure.
Cellular commands installed base; satellite gains where geography blocks terrestrial signals.
End User:
Customer economics range from subsidized institutional procurement to full-fare direct-to-consumer subscription.
- Senior Citizens:Solitary-dwelling adults over 65 constitute the core addressable population, with United States aging-in-place preferences strengthening residential adoption. Medicare Advantage supplemental benefits now cover monitored services, reducing out-of-pocket barriers.
- Healthcare Facilities:Skilled nursing and assisted living operators purchase enterprise-grade systems with centralized monitoring dashboards. Netherlands and German post-acute discharge protocols are embedding PERS into bundled cardiac and orthopedic recovery reimbursement.
- Disabled Individuals:Users with mobility or cognitive impairments require specialized interface adaptations.
- Caregivers:Family members purchasing on behalf of dependents favor app-integrated notification systems.
Senior Citizens anchor revenue; Healthcare Facilities offer enterprise contract scale.
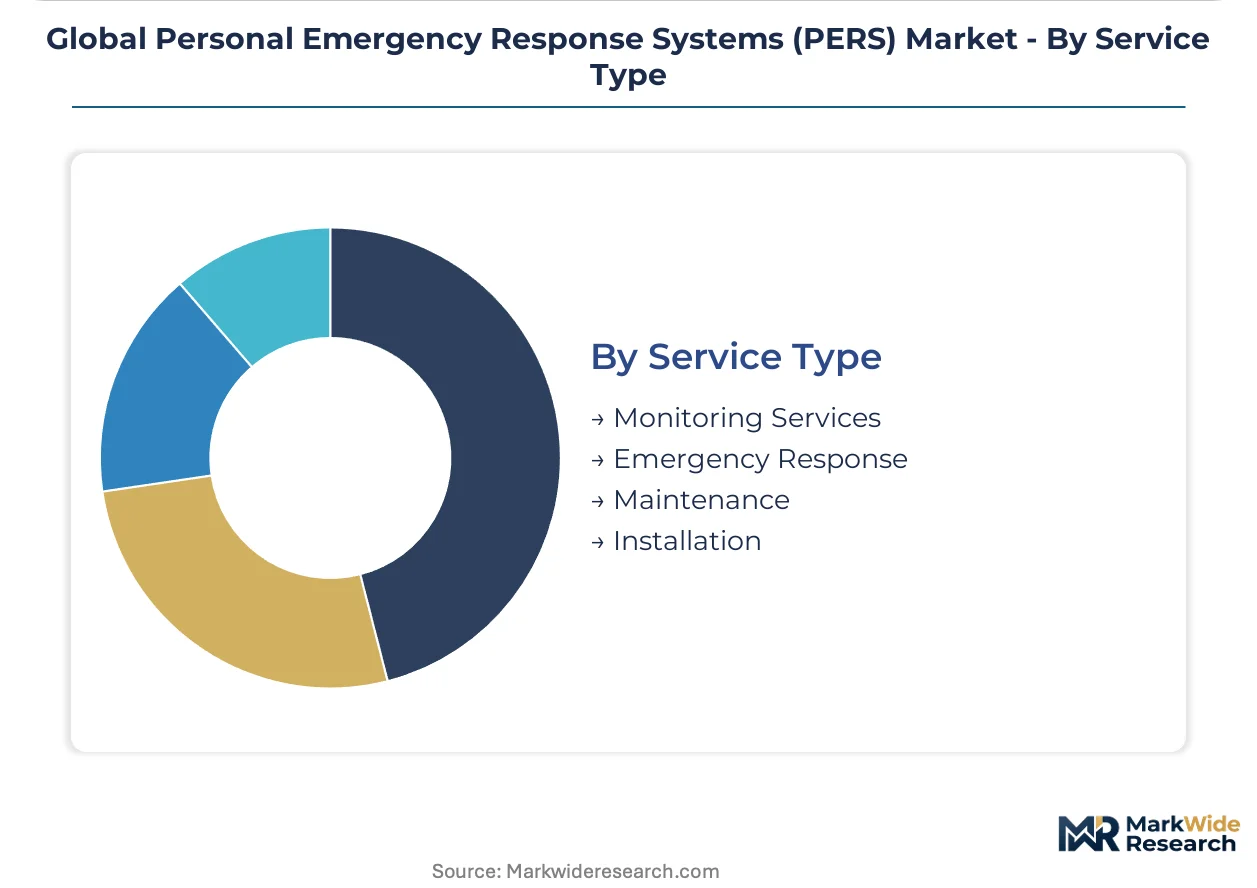
Service Type:
Margin structures invert between recurring monitoring revenue and one-time installation transactions.
- Monitoring Services:24/7 staffed response centers generate predictable monthly recurring revenue with 85%+ gross margins. Bay Alarm Medical and Tunstall Healthcare Group compete on vertical integration versus public-sector procurement relationships.
- Emergency Response:Dispatch coordination with EMS and designated contacts represents the core value proposition. FDA 510(k) and EU MDR compliance requirements create regulatory moats against unlicensed competitors.
- Maintenance:Firmware updates and battery replacement programs extend hardware lifecycle.
- Installation:Professional setup services command one-time fees for complex hybrid or fixed-device deployments.
Monitoring Services lock in lifetime value; Emergency Response differentiates on regulatory certification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bay Area and Boston corridors concentrate PERS innovation capital, with Medicare Advantage reimbursement expansion driving United States residential adoption while EU MDR compliance investments reshape European vendor bases.
United States
Medicare Advantage supplemental benefits now cover monitored emergency response services, eliminating out-of-pocket barriers for aging-in-place seniors. FDA 510(k) premarket notification requirements extend product launch windows by 12-18 months, compressing first-mover advantages for new entrants. Silicon Valley and Greater Boston clusters dominate MEMS accelerometer integration and AI-enabled predictive analytics development.
Germany
Post-acute cardiac and orthopedic discharge protocols embed PERS into bundled reimbursement frameworks, creating institutional procurement scale. The EU MDR imposes stricter clinical evidence and post-market surveillance obligations on manufacturers seeking CE marking. Bavaria and North Rhine-Westphalia host established medical device engineering clusters with notified body relationships.
Japan
PMDA enforcement of JIS standards for electromagnetic compatibility and battery safety creates incremental certification burdens for foreign device manufacturers. METI aging-in-place policy initiatives expand residential subsidy eligibility for monitored alert systems. Kanto and Kansai metropolitan corridors concentrate domestic PERS distribution partnerships with regional carriers.
United Kingdom
National Health Service procurement frameworks favor vendors with localized language support and established clinical evidence registries. MHRA post-Brexit regulatory divergence from EU MDR creates parallel compliance pathways for GB and CE marking. London and Southeast England clusters anchor telehealth platform integration with emergency response services.
Netherlands
Hospital-to-home transition programs in cardiac recovery embed PERS into standardized discharge bundles, generating enterprise contract volume. EMA-aligned medical device oversight maintains CE marking as the operative regulatory threshold. Randstad urban corridor concentrates health informatics platform development for integrated care coordination.
Global Personal Emergency Response Systems (PERS) Market Competitive Landscape
Strategic partnerships dominate the current landscape as scaled manufacturers seek regulatory infrastructure and monitoring center capabilities. The vendor base concentrates around three tiers: integrated health technology conglomerates with health informatics platforms, vertically owned monitoring center operators with direct-to-consumer subscription economics, and specialized European public-sector procurement contractors. Consolidation pressures intensify as EU MDR compliance investments favor scaled players with notified body relationships and active safety registry maintenance capacity.
Within the integrated health technology tier, Koninklijke Philips N.V. exemplifies platform-centric positioning through hospital-to-home transition program embedding. Bay Alarm Medical and Tunstall Healthcare Group Ltd. anchor opposing geographic vectors—California-Arizona vertical integration against European NHS procurement frameworks—representing divergent scale strategies for recurring revenue capture. These three occupy positions spanning premium integrated systems, direct-to-consumer subscription density, and public-sector contract specialization.
| Leading Market Players |
|---|
| ADT Inc. |
| Life Alert Emergency Response Inc. |
| Bay Alarm Medical |
| Koninklijke Philips N.V. |
| Tunstall Healthcare Group Ltd. |
| Medical Guardian |
| ConnectAmerica LLC |
| AlertONE Services Inc. |
| MobileHelp LLC |
| Others |
Supply & Pricing Matrix
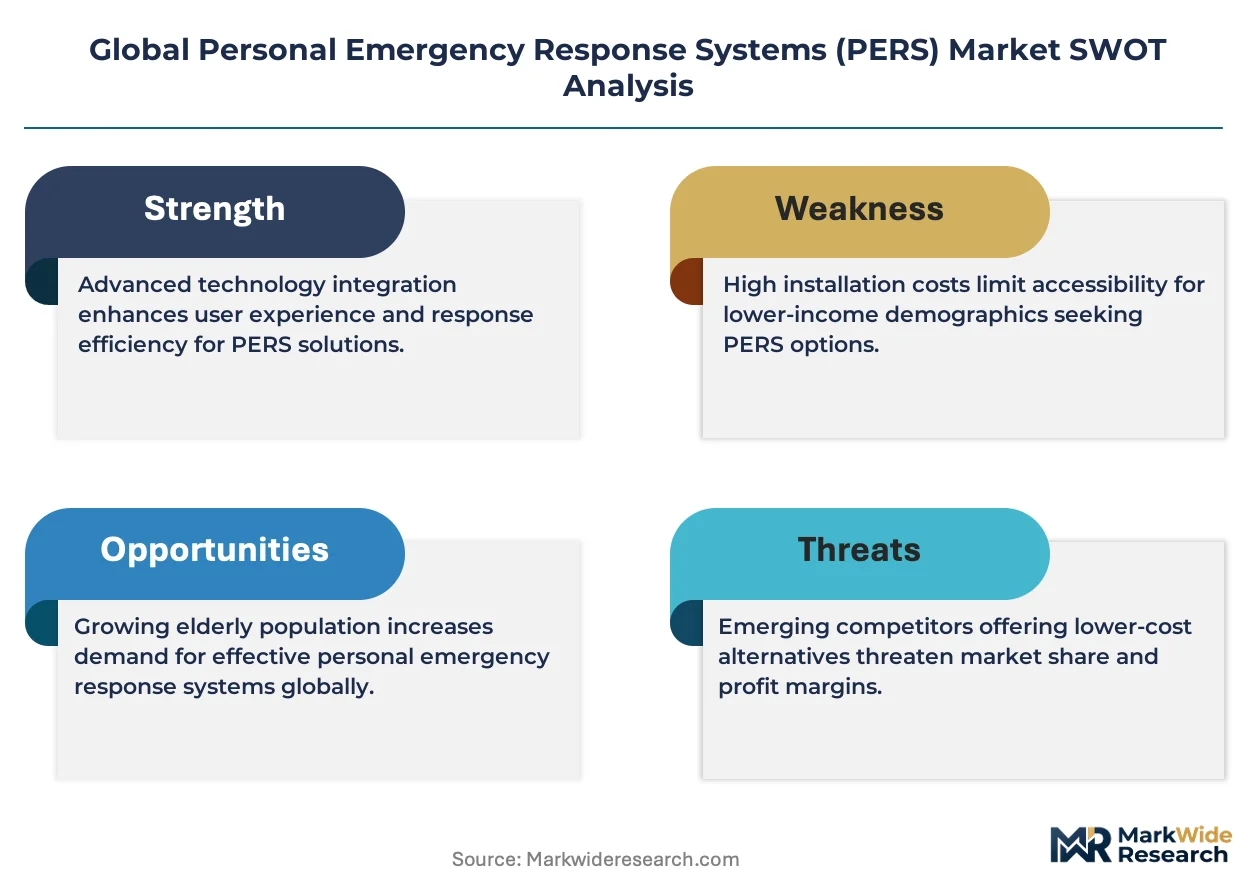
Captive monitoring center ownership anchors pricing power for vertically integrated operators, insulating subscription margins from third-party dispatch cost volatility while concentrating supply risk in cellular modem and MEMS sensor procurement clusters. This integration pattern separates premium-tier vendors with owned response infrastructure from hardware-as-transaction competitors exposed to commoditization pressure.
Pricing Analysis
Input-cost pass-through from lithium-ion cathode materials and cellular modem chipsets compresses hardware margins without proportional subscription pricing relief. Three-tier pricing structure across premium biometric-integrated, standard GPS-enabled, and economy pendant-only levels segments buyer willingness-to-pay by feature depth. Pricing pressure stems from smartphone-native fall detection substituting basic alert functionality for price-sensitive direct-to-consumer purchasers. Healthcare facility procurement committees exhibit lowest price sensitivity given bundled reimbursement economics, while uninsured individual buyers drive entry-tier volume through self-monitored app alternatives.
Supply Chain Analysis
Reverse-logistics flows for battery replacement and firmware-refreshed hardware units create secondary revenue streams while extending installed base retention. Component sourcing concentrates in China for lithium-ion cells, Taiwan for cellular baseband modems, and Japan for high-precision MEMS accelerometers. Single-source vulnerability in East Asian cathode material processing creates geopolitical exposure for device manufacturers. Distribution runs through vertically owned monitoring centers for subscription-heavy operators and consumer electronics retail channels for hardware-focused entrants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Personal Emergency Response Systems Market functions as a stable compounder, with aging-in-place demographic tailwinds generating predictable replacement demand across decade-long user lifecycles.
For Market Incumbents: Acquire regulatory certification assets to consolidate EU MDR compliance infrastructure against smaller competitors lacking notified body relationships. Bay Alarm Medical's California-Arizona monitoring center footprint demonstrates how geographic concentration of dispatch operations defends margin structure against third-party service cost inflation. Lock in cellular carrier partnership exclusivity to raise subscriber acquisition barriers for hardware-only entrants.
For New Entrants and Emerging Players: The mid-tier price-point gap between Philips-integrated premium systems and economy pendant vendors opens positioning for AI-enabled predictive analytics at standard-tier pricing. Target rural United States and Alpine European territories with hybrid satellite-cellular architectures where terrestrial coverage gaps persist. Pursue hospital-to-home discharge partnership channels rather than direct-to-consumer advertising spend.
For Investors and Strategic Acquirers: Roll-up economics work for regional monitoring center operators because fragmented local dispatch assets command valuation premiums when integrated into national coverage networks. Five-to-ten year viability hinges on Medicare Advantage reimbursement durability and EU MDR enforcement consistency. Monitor FDA 510(k) clearance timeline extensions as inflection signals for new entrant cost structures.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR compliance infrastructure consolidates vendor base toward scaled manufacturers with notified body relationships. |
| Hospital System Partnership | German and Dutch post-acute discharge protocols embed PERS into bundled cardiac and orthopedic recovery reimbursement. |
| Software Companion Development | AI-enabled predictive analytics applied to accelerometer data enables pre-fall intervention alerts before physical incidents. |
| Reimbursement Strategy | Medicare Advantage supplemental benefit expansion eliminates out-of-pocket barriers for aging-in-place senior enrollment. |
| Strategic Partnership | Cellular carrier alliances reduce subscriber acquisition costs for monitoring center operators competing on recurring revenue. |
Research Methodology
Bottom-up senior citizen and healthcare facility demand modeling reconciled against top-down MEMS sensor and cellular module supply tracking forms the analytical core. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and monitoring center operations directors combined with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, EU MDR notified body registries, and cellular carrier partnership disclosures. Triangulation between installed base estimates and component shipment data ensures volume consistency.
Historical trendline analysis across device category adoption curves and subscription renewal rate trajectories informs projection elasticity. Segmentation dimensions span product architecture, connectivity technology, end-user setting, and service model type. CAGRs derive from logistic diffusion modeling of aging-in-place policy penetration and reimbursement code expansion. Forecast inputs incorporate MEMS accelerometer cost curve trajectories and cellular network densification timelines.
Caveats apply where FDA 510(k) timeline extensions, EU MDR enforcement intensity shifts, or lithium-ion supply chain disruptions could materially shift the outlook. Practitioners should monitor Medicare Advantage benefit expansion velocity and POTS sunset implementation pace for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Safety
Personal Safety Apps for Women Market
Personal Safety
Life Jacket Market
Personal Safety
Child Safety Seat Market
Personal Safety
Body Armor and Personal Protection Market
Personal Safety
Global Fall Protection Market
Personal Safety
Pedestrian Protection Airbag Market
Personal Safety
China Travel Safety Kits Market
Personal Safety
Smart Home Safety Market
Personal Safety
Personal Safety Alarms Market
Personal Safety
Global Medical Alert System/Personal Emergency Response System Market
Personal Safety
Road Safety Market
Personal Safety
Smart Personal Safety and Security Device Market
Personal Safety
Global Self Defense Products Market
Personal Safety
Child Leash Market
Personal Safety
Rearward Facing Type Child Safety Seats Market
Personal Safety
Concealable Vest Market