
 Earthquake Early Warning System Market | 2026-2036
Earthquake Early Warning System Market Size, Share, and Industry Trends Forecast 2026-2036
Earthquake Early Warning System Market Intelligence
The traditional barrier between seismological expertise and data science proficiency is collapsing as system development requires hybrid teams. Kinemetrics Inc. leverages its long-standing geophysical instrumentation experience to serve research institutions. Nanometrics specializes in high-precision seismic monitoring solutions for both public and industrial clients. Valcom Inc. differentiates through its focus on integrated public alert and communication systems.
An earthquake early warning system is a network of sensors designed to detect the initial, non-destructive P-waves of an earthquake. This detection provides seconds to minutes of warning before the more damaging S-waves and surface waves arrive, enabling automated safety responses. Hybrid systems combining seismic sensor networks and GPS-based monitoring are gaining traction over standalone solutions. Within applications, infrastructure protection and public alerting represent the largest use cases for government agencies.
Public safety mandates from entities like the United States Geological Survey (USGS) and the Japan Meteorological Agency (JMA) drive national-level deployments. Concurrently, ISO standards for seismic instrumentation ensure data quality and interoperability between different vendors' sensor networks. The key decision for system operators now centers on balancing the cost of network densification against the incremental improvements in warning time and accuracy.
Market Dynamics
The central force shaping the market is the expansion of public safety mandates from national governments. These policies, particularly in seismically active nations, compel investment in nationwide sensor networks and public alerting infrastructure, driving both technology development and market volume.
Growth Catalysts
- Public Safety Mandates:National-level deployments are driven by government directives, such as those from the United States Geological Survey (USGS) and the Japan Meteorological Agency (JMA), which require the establishment and modernization of early warning capabilities to protect citizens and infrastructure.
- AI and Machine Learning Integration:The incorporation of artificial intelligence into seismic analysis improves prediction accuracy and significantly reduces the rate of false alarms, increasing the reliability and trustworthiness of warning systems for both public and industrial applications.
- Critical Infrastructure Protection:Demand from operators of power grids, transportation networks, and industrial plants for automated shutdown and safety protocols provides a strong commercial incentive for system adoption, independent of public-sector initiatives.
Market Restraints
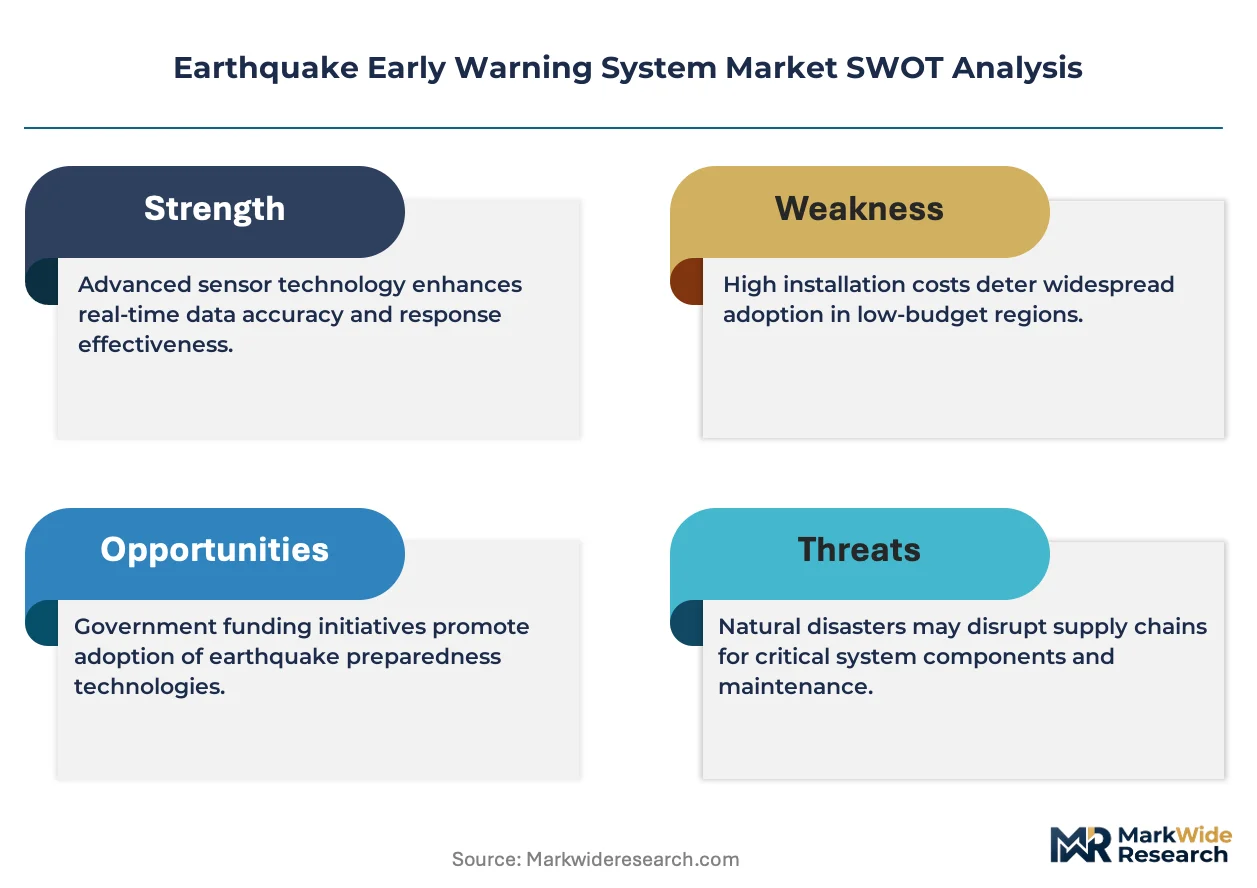
- High Initial Capital Expenditure:The significant upfront cost associated with deploying and maintaining dense networks of high-precision seismic sensors and communication infrastructure presents a substantial barrier to entry, especially for developing economies in earthquake-prone zones.
- Risk of False Alarms:The potential for false warnings, which can cause unnecessary panic, economic disruption, and a loss of public trust, acts as a structural restraint, forcing operators to balance warning speed against system sensitivity.
- Data Interoperability Standards:A lack of universal standardization across all vendor equipment creates friction in integrating disparate sensor networks. While ISO standards provide a baseline, proprietary data formats can complicate the creation of unified national systems.
Strategic Opportunities
- Underpenetrated Seismic Regions:Significant white space exists in seismically active but less-developed markets across Southeast Asia, Latin America, and the Middle East, where national warning systems are nascent or non-existent.
- Private Sector Business Continuity:An opportunity lies in marketing systems directly to large corporations for protecting high-value assets like data centers, manufacturing plants, and logistics hubs, focusing on business continuity and risk mitigation.
- Hybrid System Development:The convergence of seismic sensor networks with real-time GPS monitoring offers an opportunity to create more accurate hybrid systems that better distinguish earthquake characteristics and improve warning reliability over standalone solutions.
Industry Challenges
- Specialized Talent Scarcity:A key operational challenge is the limited availability of professionals possessing the hybrid expertise in both seismology and data science required for advanced system development, algorithm tuning, and network management.
- Public Education and Communication:Effectively educating the public on how to interpret and react to warnings is a persistent challenge. Misunderstanding system limitations can lead to improper responses or diminished public confidence over time.
- Network Maintenance and Uptime:Ensuring the continuous operation and calibration of geographically dispersed sensor networks, often in remote or difficult-to-access locations, poses a significant logistical and financial challenge for system operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Earthquake Early Warning System Market |
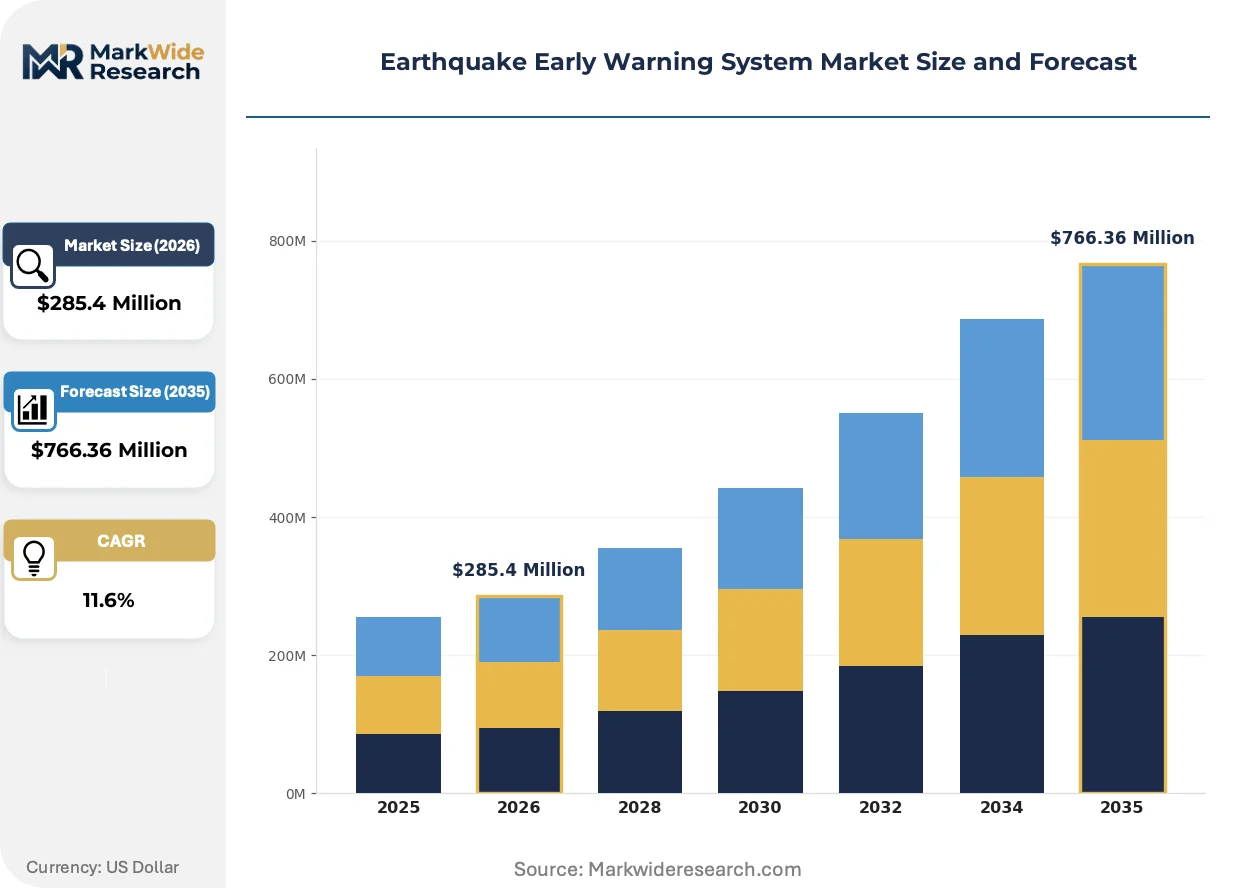
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $766.36 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Seismic Sensor Network, GPS-Based Monitoring, IoT-Enabled Detection, Satellite Observation, Hybrid Systems Application: Disaster Management, Infrastructure Protection, Transportation Safety, Public Alerting, Utility Continuity Deployment Mode: Cloud-Based, On-Premise, Edge Computing, Hybrid Cloud, Dedicated Server End User: Government Agencies, Emergency Responders, Public Safety Organizations, Research Institutions, Communication Providers |
| Companies Covered | Valcom Inc., Reftek Systems Inc., Early Warning Labs, Kinemetrics Inc., SkyAlert, Nanometrics, Jenlogix, SeismicAI, GeoSIG Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Earthquake Early Warning System Market Strategic Shifts & Innovations
System development is shifting from a focus on pure P-wave detection toward integrated, intelligent response frameworks. This evolution prioritizes not just the warning itself, but the accuracy of impact prediction and the automation of safety measures in critical infrastructure.
Artificial intelligence algorithms analyze initial P-wave signatures to predict the intensity and arrival time of subsequent damaging waves. Government agencies and critical infrastructure operators are adopting this technology to improve decision-making and minimize false alerts. This algorithmic intelligence is supplanting older, fixed-threshold detection methods that lacked the nuance to differentiate between minor tremors and major seismic events effectively.
International Organization for Standardization (ISO) guidelines for seismic instrumentation are becoming a de facto requirement in public tenders. These standards enforce a baseline for sensor performance, data quality, and network interoperability. The government procurement segment is most affected, as agencies increasingly mandate ISO compliance to ensure that equipment from multiple vendors can be integrated into a cohesive national warning network.
Demand is moving away from one-time hardware sales toward integrated, long-term service contracts that bundle system installation with ongoing maintenance, software updates, and performance monitoring. This trend disrupts traditional component suppliers, favoring system integrators who provide end-to-end lifecycle management. This shift is most pronounced in public-sector projects in Japan and the United States, where agencies prioritize long-term reliability.
Earthquake Early Warning System Market Segmentation
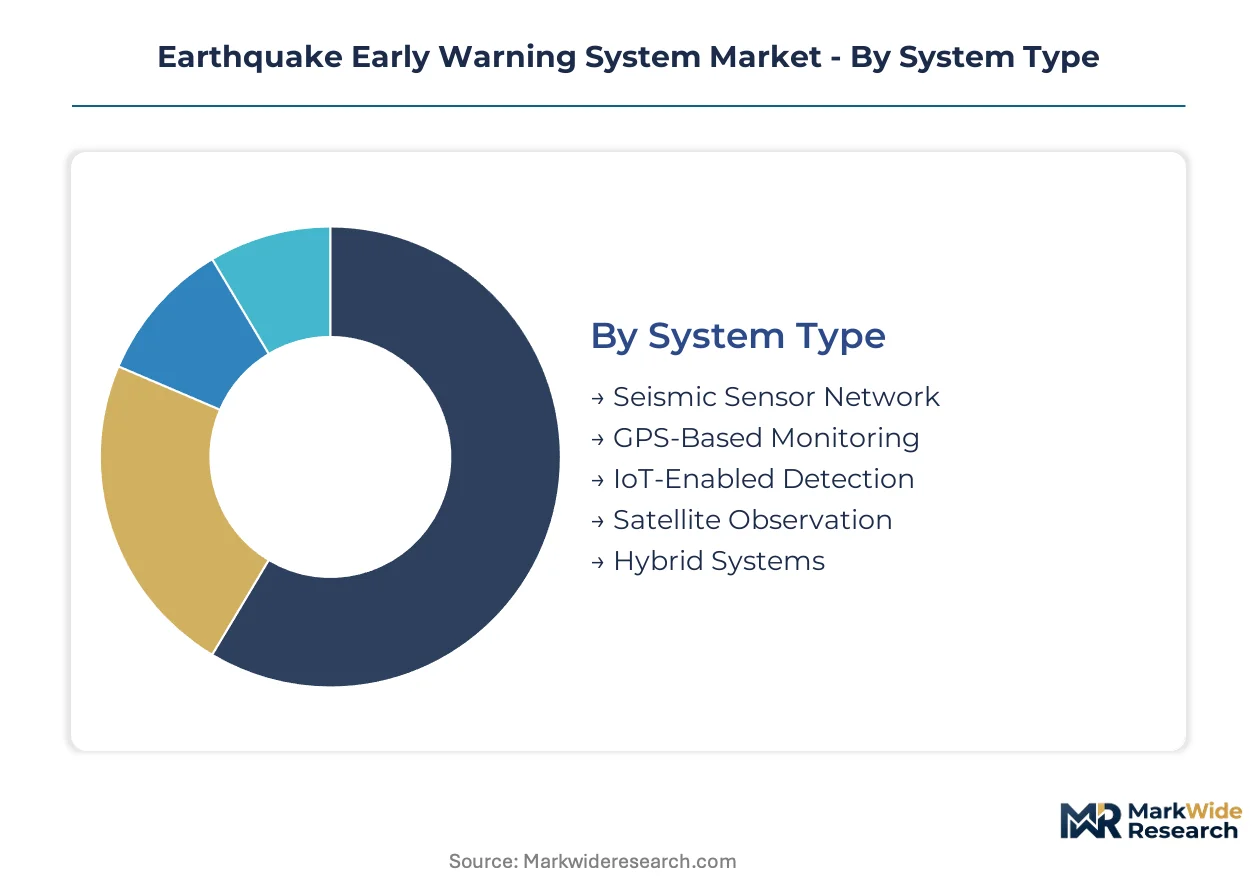
Market segmentation for earthquake early warning systems reveals distinct technological and application-specific demands. Understanding these segments helps providers tailor solutions to diverse end-user requirements, from national public safety mandates to specific industrial infrastructure protection needs. This granular view highlights where innovation and investment are most critical for system efficacy.
System Type:
Margin pools within system types are influenced by the complexity of data integration and the precision required for warning dissemination.
- Hybrid Systems:These advanced configurations combine seismic sensor networks with real-time GPS-based monitoring, offering enhanced accuracy and reliability in earthquake characterization. Demand is concentrating in high-risk regions like Japan, driven by the need for robust, multi-source data fusion to improve warning reliability.
- Seismic Sensor Network:These foundational systems detect initial P-waves through ground motion sensors strategically deployed across a geographical region, providing the primary source of seismic data. Government agencies in nations such as the United States prioritize these networks for broad-area coverage and fundamental early detection capabilities.
- GPS-Based Monitoring:This method utilizes high-precision GPS receivers to measure ground deformation, providing crucial data for earthquake magnitude and slip estimation.
- IoT-Enabled Detection:Integrates smart devices and localized sensors into broader networks, enabling community-level alerts and micro-zonation responses.
- Satellite Observation:Employs satellite imagery and remote sensing technologies to monitor crustal deformation and assess ground changes post-event.
Seismic Sensor Network holds installed capacity. Hybrid Systems are rotating up the share rankings.
Application:
Applications differentiate based on the critical assets or populations protected and the speed of automated response required.
- Infrastructure Protection:This application focuses on safeguarding critical assets like power grids, industrial facilities, and communication hubs through automated shutdown protocols. Demand from utilities and industrial operators in Germany drives investment to minimize operational disruption during seismic events.
- Public Alerting:This involves disseminating warnings to the general population via various channels, including mobile applications, broadcast systems, and public address networks. Mandates from agencies like the Japan Meteorological Agency compel nationwide deployments for comprehensive citizen safety.
- Disaster Management:Supports emergency services with real-time data for resource allocation, evacuation planning, and post-event recovery efforts.
- Transportation Safety:Implements warnings for trains, bridges, and tunnels, enabling automated slowdowns or stops to prevent accidents during seismic activity.
- Utility Continuity:Ensures the uninterrupted operation of essential services, including water supply, gas pipelines, and telecommunications networks, through preemptive actions.
Infrastructure Protection maintains a significant share. Public Alerting is gaining share fastest.
Deployment Mode:
Operational flexibility and data sovereignty considerations drive choices across deployment modes.
- On-Premise:Systems are installed and managed directly within the user's physical infrastructure, offering maximum data control, security, and customization. Large government entities in the United States often prefer this mode for sensitive national security applications.
- Cloud-Based:Leverages remote servers and internet connectivity for data processing, storage, and warning dissemination, providing scalability, accessibility, and reduced hardware overhead. Startups and smaller municipalities in Canada adopt cloud solutions for cost-effectiveness and rapid deployment.
- Edge Computing:Processes data closer to the sensor source, reducing latency for rapid local warning generation and response initiation.
- Hybrid Cloud:Combines elements of both on-premise and cloud environments, balancing the security of local infrastructure with the scalability of remote services.
- Dedicated Server:Provides exclusive server resources for single-tenant operations, ensuring consistent performance, enhanced security, and isolation from other users.
On-Premise solutions represent mature deployments. Cloud-Based offerings are seeing accelerated adoption.
End User:
Purchasing influence among end users is shaped by regulatory mandates and budgetary allocations for public safety.
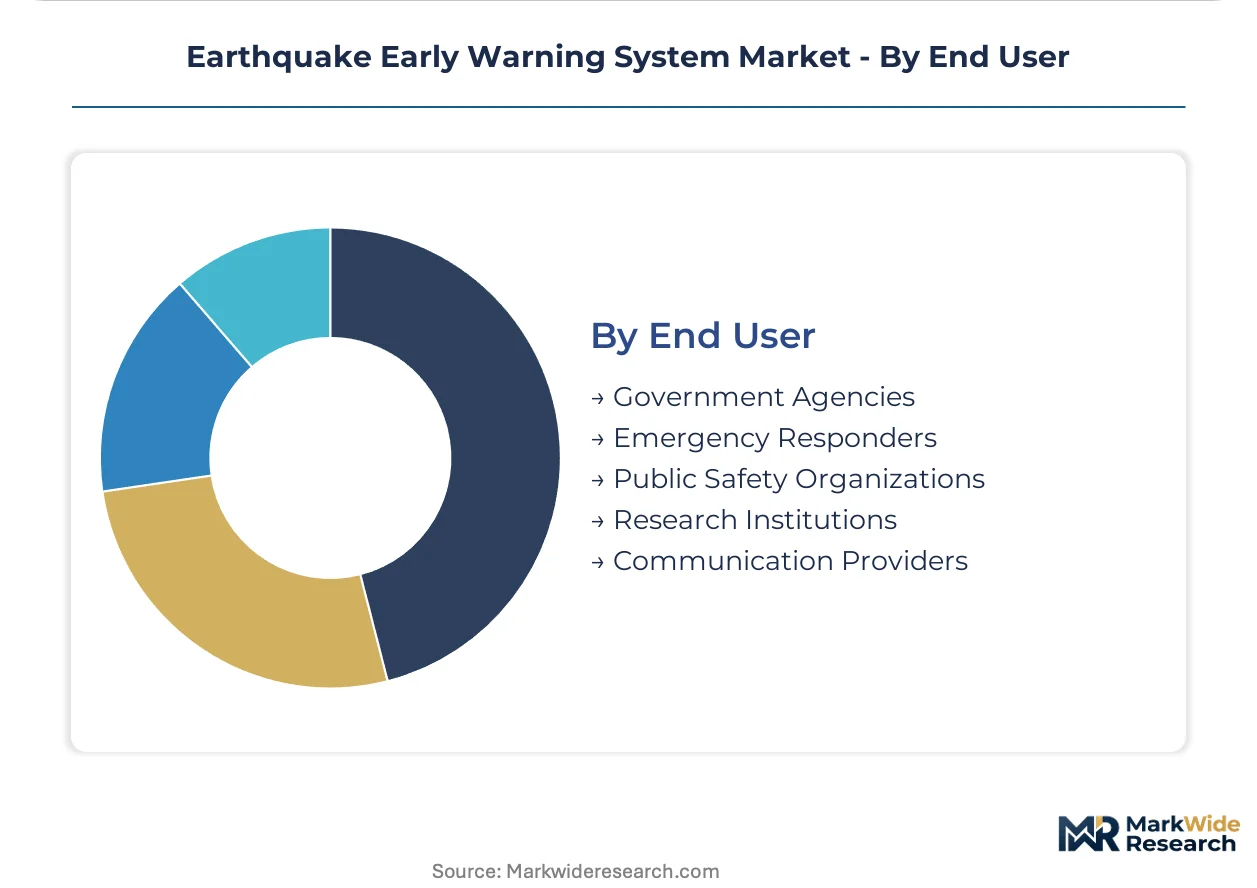
- Government Agencies:These entities, such as the United States Geological Survey (USGS) and the Japan Meteorological Agency (JMA), are primary drivers for large-scale national early warning system deployments. They fund infrastructure development and set public safety mandates.
- Public Safety Organizations:Tasked with direct implementation and coordination of warnings, these groups include civil defense and disaster response units. Their demand in countries like Italy focuses on reliable communication and rapid response capabilities for citizen protection.
- Emergency Responders:Utilize warning systems to pre-position resources, activate protocols, and optimize response efforts during and immediately after seismic events.
- Research Institutions:Employ advanced systems for seismological study, algorithm development, and predictive modeling to enhance warning capabilities.
- Communication Providers:Integrate warning dissemination into their existing networks, leveraging infrastructure for broad public reach through various alert channels.
Government Agencies drive the foundational market. Research Institutions are advancing future system capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Earthquake Early Warning System market displays distinct consumption patterns across global regions. Japan prioritizes comprehensive public alerting and rapid response due to its high seismic activity. In contrast, the United States balances critical infrastructure protection with broader public safety mandates, driving diverse system deployments.
Japan
Demand in Japan is exceptionally strong, driven by its high seismic activity and stringent public safety mandates. The Japan Meteorological Agency (JMA) actively promotes nationwide deployments for comprehensive citizen safety. Major cities like Tokyo and Osaka are hubs for advanced system integration, focusing on rapid warning dissemination and automated safety responses.
United States
The United States sees significant investment in early warning systems, particularly for infrastructure protection and public alerting. The United States Geological Survey (USGS) plays a central role in driving national-level deployments and research initiatives. California, with its high seismic risk, represents a key region for the implementation of advanced sensor networks and public alert systems.
Germany
Germany's market for earthquake early warning systems focuses primarily on infrastructure protection for critical industrial assets. Industrial operators and utilities drive demand to minimize operational disruption during seismic events, even in regions with moderate seismicity. Compliance with ISO standards for seismic instrumentation is a key consideration for system procurement in industrial centers like the Ruhr Valley.
India
India represents a significant underpenetrated market with growing awareness of seismic risk and the need for early warning capabilities. Government initiatives are emerging to bolster disaster management and protect critical infrastructure across seismically active zones. Research institutions in cities like Delhi and Hyderabad are contributing to algorithm development and sensor network optimization for local conditions.
Chile
Chile, situated in a highly seismically active zone, has a strong imperative for robust earthquake early warning systems. Public safety mandates from national authorities compel investment in advanced sensor networks and public alerting infrastructure. The capital Santiago and coastal regions are focal points for deploying and upgrading systems to protect populations and critical infrastructure.
Earthquake Early Warning System Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the Earthquake Early Warning System market. This structure combines established geophysical instrumentation providers with newer AI-driven software specialists, creating a diverse competitive landscape. Strategic archetypes include foundational hardware manufacturers, advanced software and algorithm integrators, and comprehensive full-service solution providers. Market participants frequently pursue strategic partnerships to expand their technological capabilities and geographic reach, alongside targeted portfolio diversification.
Specialists in seismic monitoring and data analysis include Kinemetrics Inc., which leverages its long-standing geophysical instrumentation experience primarily to serve research institutions and scientific endeavors. Nanometrics occupies a strong position as a provider of high-precision seismic monitoring solutions, catering to both public sector agencies and industrial clients with advanced sensing technology. Valcom Inc. exemplifies providers focused on integrated public alert and communication systems, differentiating through its comprehensive approach to warning dissemination and public education. These companies collectively demonstrate the market's need for both foundational data acquisition and sophisticated, reliable communication infrastructure.
| Leading Market Players |
|---|
| Valcom Inc. |
| Reftek Systems Inc. |
| Early Warning Labs |
| Kinemetrics Inc. |
| SkyAlert |
| Nanometrics |
| Jenlogix |
| SeismicAI |
| GeoSIG Ltd |
| Others |
Cost & Logistics Intelligence
ISO standards for seismic instrumentation, which ensure data quality, gate both sensor network supply qualification and influence price differentiation for compliant equipment.
Pricing Analysis
Project-based contracts dominate the procurement landscape for earthquake early warning systems. Price differentiation stems from system complexity, including hybrid configurations, and the level of integrated after-sales support. Cost compression is intensifying for standalone seismic sensors due to increased competition among component manufacturers. Government agencies and critical infrastructure operators demonstrate lower price sensitivity, prioritizing reliability and comprehensive service agreements.
Supply Chain Analysis
Inbound logistics costs, particularly for high-precision sensor components, are impacted by specialized freight requirements and global trade lane stability. Supply concentration for advanced seismic sensors and data processing units centers in countries like Japan, the United States, and Germany. Key component dependencies include specialized accelerometers and high-bandwidth communication modules. Single-source vulnerability for proprietary sensor technology represents a structural risk. Distribution runs through a mix of direct sales to government entities and specialized system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is experiencing a cyclical recovery, driven by renewed government investment in disaster preparedness following recent high-profile seismic events.
For Market Incumbents:Fortify existing market positions by deepening vertical integration into specialized sensor manufacturing and advanced AI algorithm development. This mitigates the threat from emerging software-centric entrants who could disrupt traditional hardware-focused revenue streams. Invest in R&D for next-generation hybrid systems, combining seismic and GPS data for superior accuracy. Expand channel control through long-term service contracts with government agencies and critical infrastructure operators.
For New Entrants and Emerging Players:Anchor in underpenetrated seismic regions across Southeast Asia and Latin America, where national warning systems are nascent. The most penetrable segment lies in IoT-enabled localized detection for community-level alerts. A compelling go-to-market angle involves offering cloud-based, subscription-model solutions that reduce initial capital expenditure for smaller municipalities and private sector clients.
For Investors and Strategic Acquirers:Secondary-cycle assets sit with mid-sized, PE-backed system integrators specializing in public alerting infrastructure. The long-term viability for this market spans a 5-10 year window, sustained by ongoing public safety mandates and infrastructure modernization cycles. Target acquisition archetypes include companies with strong intellectual property in AI-driven seismic analysis or established service contracts with national meteorological agencies. A signal to watch is the increasing adoption rate of ISO-compliant hybrid systems in developing economies.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: AI-driven Hybrid System | Enhances prediction accuracy for critical infrastructure in Japan. |
| Strategic Partnership: With telecommunication providers | Expands public alerting reach to citizens in the United States. |
| Geographic Expansion: Into Southeast Asian markets | Captures demand from underpenetrated regions with high seismic risk. |
| Capacity Expansion: For advanced sensor manufacturing | Ensures supply chain resilience for government agency deployments. |
| Certification Investment: For ISO 9001 and ISO 14001 | Strengthens competitive positioning for tenders in Germany. |
Research Approach
A spread of perspectives from seismologists, disaster management officials, infrastructure engineers, and sensor manufacturers converged on the working assumptions for this market. Primary interviews with industry stakeholders were triangulated with secondary validation from USGS reports, JMA publications, academic journals, and ISO standards documents. This approach utilized both bottom-up market sizing and top-down revenue validation.
Segmentation dimensions modeled include system type, application, deployment mode, and end-user, alongside regional seismic activity levels. Compound annual growth rates were derived from historical trends and projected technological advancements across the analysis window. Key forecast inputs included government budget allocations for public safety and critical infrastructure investment plans.
Underlying assumptions cover stable regulatory environments and consistent public safety funding, with deviation risk concentrated in unforeseen geopolitical events or rapid technological obsolescence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency and Disaster Management
Global Emergency Beacon Transmitter Market
Emergency and Disaster Management
Emergency Shower and Eyewash Station Market
Emergency and Disaster Management
Emergency Location Transmitter Market
Emergency and Disaster Management
Emergency Blankets Market
Emergency and Disaster Management
Cyber Crisis Management Market
Emergency and Disaster Management
Outdoor Emergency Safety Shower Market
Emergency and Disaster Management
Hazard Control Market
Emergency and Disaster Management
Global Emergency Medical Service (EMS) Products Market
Emergency and Disaster Management
Disaster Restoration Services Market
Emergency and Disaster Management
Emergency Lighting Market
Emergency and Disaster Management
Asia-Pacific Process Safety Services Market
Emergency and Disaster Management
Advanced Disaster Management Simulator Market
Emergency and Disaster Management
Global Emergency Notification Software Market
Emergency and Disaster Management
Incident and Emergency Management Market
Emergency and Disaster Management
Automatic Floodgate Market
Emergency and Disaster Management
Lifeboat Market