
 Automatic Floodgate Market | 2026-2036
Automatic Floodgate Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Floodgate Market Analysis
Aluminum alloy is restructuring product economics across the automatic floodgate landscape as fabricators replace heavier steel formulations to reduce deployment weight and corrosion susceptibility. Garrison Flood Control leverages in-house extrusion capabilities to anchor its position in permanent municipal installations. FloodBreak competes through rapid-deployment designs that occupy the temporary installation segment. AWMA Water Control Solutions specializes in hydraulic actuation systems for large-scale water control infrastructure.
An automatic floodgate is a vertically or horizontally actuated barrier system engineered to seal openings against hydrostatic pressure, typically rated for water heights from 0.5 to 6 meters and activated by sensor-triggered hydraulic, pneumatic, or electromechanical drives to protect built assets from inundation. Barrier gates lead product type demand due to their prevalence in transportation network applications, while smart control systems represent the fastest-expanding technology category as IoT-enabled remote monitoring becomes standard specification. Municipalities channel the largest end-user investment, though industrial facilities are emerging as a concentrated margin pool given their willingness to pay for customized retrofit solutions.
The US Army Corps of Engineers and FEMA shape domestic demand through certified flood-proofing requirements for structures in designated flood hazard zones, while the EU Green Deal and national adaptation strategies in the Netherlands and Germany mandate climate-resilient infrastructure procurement. China's Ministry of Water Resources enforces GB standards for hydraulic structures that govern import eligibility and local product certification. Stakeholders must monitor how evolving building code harmonization across jurisdictions will reshape certification costs and competitive access.
Market Dynamics
Sensor-triggered hydraulic actuation is compressing deployment timelines across municipal flood protection contracts, forcing fabricators to restructure production workflows around rapid-install specifications. Rotterdam's climate adaptation programs demonstrate how smart-controlled systems now dictate procurement terms.
Growth Catalysts
- EU Green Deal infrastructure mandates:National adaptation strategies in the Netherlands and Germany mandate climate-resilient procurement, directing public investment toward automated barrier systems.
- Subway network protection:Coastal municipalities specify vertically actuated barriers for transportation assets exposed to combined storm surge and tidal flooding.
- Aluminum alloy substitution:Fabricators replace steel formulations to reduce deployment weight and corrosion susceptibility in permanent installations.
Market Restraints
- Hydraulic actuator supply concentration:Precision component sourcing clusters in German and Japanese industrial zones, creating vulnerability to regional disruption.
- GB standards compliance costs:China's Ministry of Water Resources enforces certification requirements that extend import eligibility timelines for foreign suppliers.
- Electromechanical drive competition:Pneumatic alternatives capture temporary installation segments where rapid redeployment outweighs precision control requirements.
Strategic Opportunities
- Industrial retrofit customization:Manufacturing facilities outside floodplains seek bespoke solutions protecting critical equipment rooms and loading docks.
- IoT-enabled predictive maintenance:Convergence of remote monitoring platforms with hydraulic diagnostics creates service revenue streams beyond hardware sales.
- FEMA-certified flood-proofing expansion:US hazard zone designation updates extend mandatory protection requirements to commercial structures previously exempt.
Industry Challenges
- Hydraulic systems engineering talent scarcity:Municipal project managers lack technical depth to evaluate actuator specifications against hydrostatic pressure ratings.
- Multi-jurisdiction certification stacking:Products serving cross-border infrastructure must satisfy divergent national standards simultaneously, extending validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Floodgate Market |
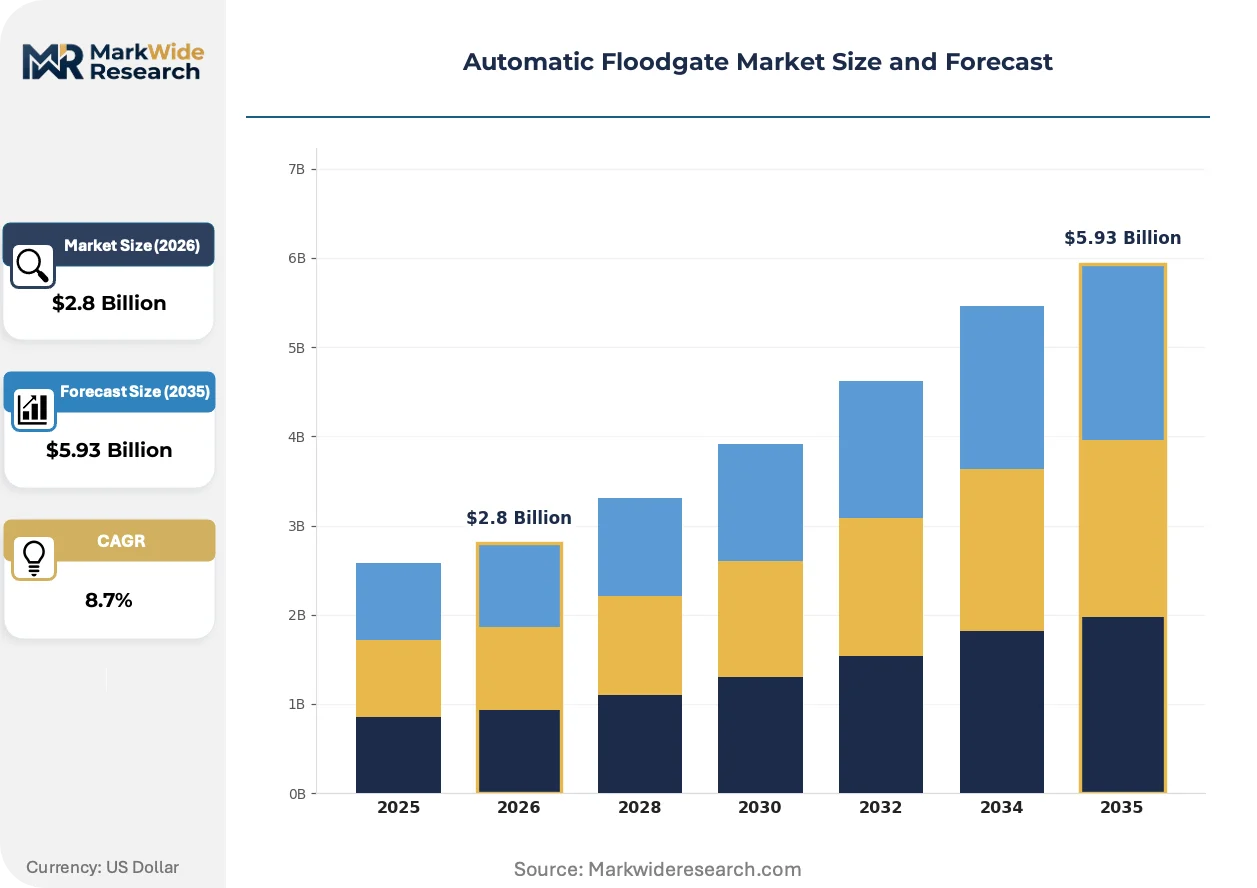
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Barrier Gates, Lever Gates, Swing Gates, Roller Gates Technology: Hydraulic Systems, Pneumatic Systems, Mechanical Systems, Smart Control Systems End User: Municipalities, Industrial Facilities, Transportation Networks, Residential Areas Installation Type: Permanent Installations, Temporary Installations, Mobile Units, Retrofit Solutions |
| Companies Covered | Garrison Flood Control, Flood Control America, Flood Control International, Hebei Jinshi Industrial Metal, Foshan LiTong FanPeng, FloodBreak, AquaFence, Flood Risk America, AWMA Water Control Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Floodgate Market Emerging Trajectories
Smart control architectures are rewriting competitive requirements across flood protection procurement. Municipal buyers now specify remote monitoring capabilities as baseline functionality, compressing margins for suppliers lacking telemetry integration.
Electromechanical linear actuators is overtaking pneumatic drives in permanent municipal installations. Rotterdam's climate adaptation programs specify these systems for their precision positioning under variable hydrostatic loads. Municipal engineering departments in Hamburg and Venice have accelerated specification timelines, compressing the window for suppliers to certify competing drive technologies.
REACH substance restrictions are forcing reformulation of hydraulic fluids and seal compounds used in submersible actuator assemblies. European fabricators face reformulation costs that Asian competitors avoid through export-focused production lines. Barrier gate systems rated for 4-6 meter water heights experience the most acute compliance pressure, as these specifications rely heavily on high-performance elastomer compounds.
Lifecycle service contracting is displacing transactional equipment sales in municipal procurement. Dutch water boards now structure ten-year maintenance agreements into initial capital awards, locking out suppliers without regional service infrastructure. German municipal utilities have replicated this model, prioritizing vendors with certified technician networks over lowest-capital-cost bids.
Automatic Floodgate Market Segmentation
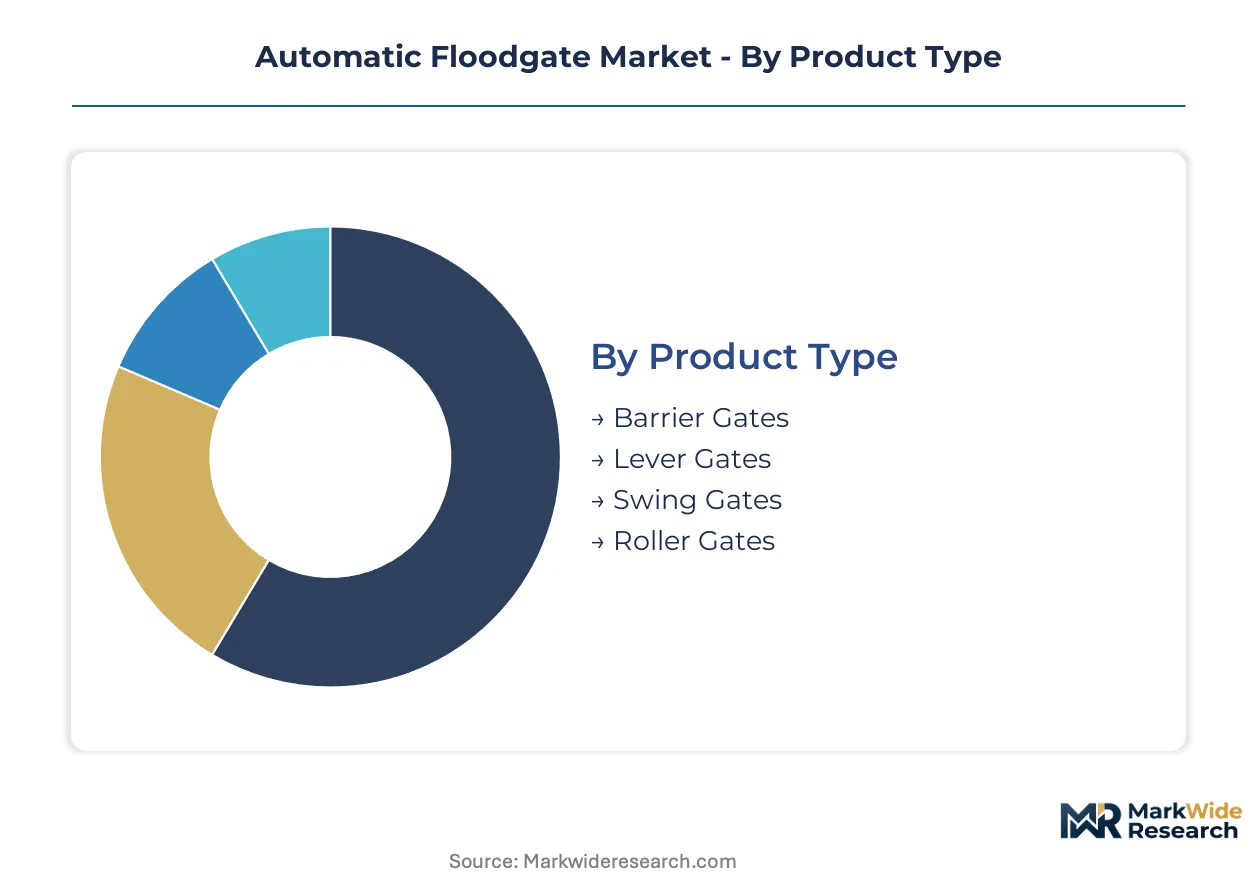
Automatic floodgate procurement decisions hinge on integration depth—whether systems operate as standalone barriers or embed within broader infrastructure networks. Each segmentation dimension reveals distinct specification patterns across municipal, industrial, and transportation end-uses.
Product Type:
Integration depth varies sharply: barrier and lever gates function as standalone perimeter defenses, while swing and roller gates embed within existing structural openings requiring coordinated actuation.
- Barrier Gates:Vertically actuated drop-down systems engineered for roadway and subway portal sealing against hydrostatic pressure. Rotterdam's climate adaptation programs specify these for transportation network protection where combined storm surge and tidal flooding threaten critical access points.
- Lever Gates:Horizontally pivoting assemblies utilizing counterweighted mechanical advantage for manual or powered operation. German municipal utilities favor lever configurations for permanent installations along Rhine tributaries where precision positioning under variable loads remains essential.
- Swing Gates:Hinged panel designs suited to narrow channel applications and secondary flood walls.
- Roller Gates:Bottom-tracked horizontal systems deployed where overhead clearance constraints prohibit vertical actuation.
Barrier gates lead volumes today; smart-controlled variants are gaining share fastest.
Technology:
Cost tiers separate precision hydraulic systems from simpler mechanical alternatives, with electromechanical drives occupying the mid-market position between premium sensor-integrated platforms and economy pneumatic deployments.
- Hydraulic Systems:Fluid-powered actuation delivering precise force modulation for barriers rated 4-6 meter water heights. REACH substance restrictions force European fabricators to reformulate hydraulic fluids and seal compounds, creating compliance cost exposure that Asian competitors avoid.
- Smart Control Systems:IoT-enabled architectures integrating remote monitoring, predictive diagnostics, and automated sensor triggering. Dutch water boards now mandate telemetry integration as baseline functionality, compressing margins for suppliers lacking platform connectivity.
- Pneumatic Systems:Compressed-air drives favored for temporary installations where rapid redeployment outweighs precision requirements.
- Mechanical Systems:Manual or motorized screw-jack configurations serving cost-constrained retrofit applications.
Hydraulic systems dominate permanent municipal awards; smart control platforms are expanding most quickly.
End User:
Application context dictates specification rigor—transportation networks demand certified flood-proofing compliance, while industrial facilities prioritize customized equipment protection outside designated hazard zones.
- Municipalities:Public infrastructure authorities procuring certified barriers for subway, roadway, and utility protection. The US Army Corps of Engineers mandates flood-proofing standards that tighten product compliance requirements for structures in designated hazard zones.
- Industrial Facilities:Manufacturing and logistics operations seeking bespoke retrofit solutions for critical equipment rooms and loading docks. These buyers demonstrate concentrated willingness to pay for customization, creating margin pools unavailable in standardized municipal tenders.
- Transportation Networks:Rail and transit operators specifying vertically actuated barriers for portal protection.
- Residential Areas:Individual property owners and homeowner associations deploying smaller-scale barrier systems.
Municipalities channel the largest capital investment; industrial facilities are climbing the fastest.
Installation Type:
Customer type and project duration determine whether procurement favors capital-intensive permanent foundations or operational-expense-oriented temporary and mobile alternatives.
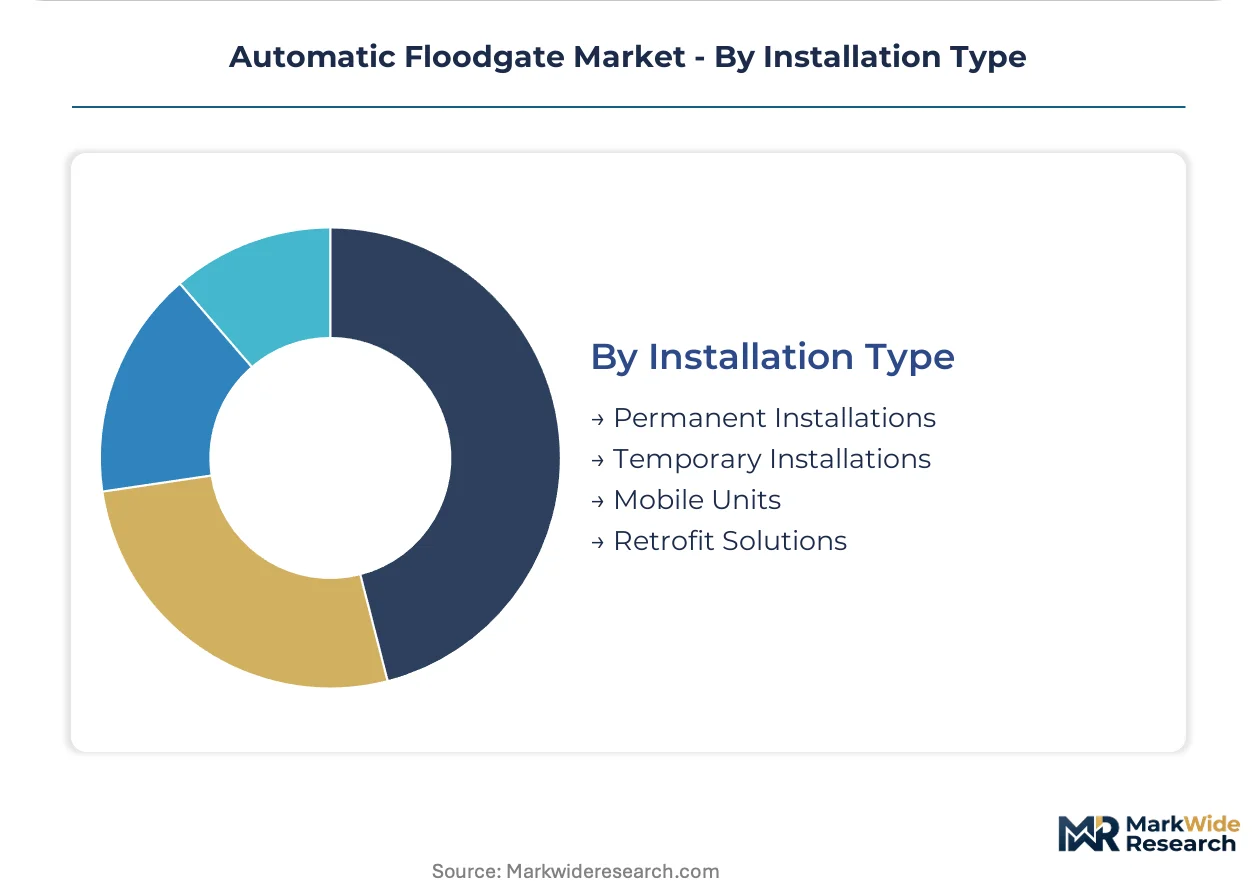
- Permanent Installations:Fixed concrete-anchored systems designed for multi-decade service life with integrated maintenance access. Aluminum alloy substitution is restructuring economics as fabricators replace steel formulations to reduce deployment weight and corrosion susceptibility.
- Temporary Installations:Rapid-deployment barriers occupying the event-driven and seasonal protection segment. FloodBreak competes specifically through designs optimized for this category where speed of emplacement outweighs long-term durability specifications.
- Mobile Units:Trailer-mounted or modular systems redeployable across multiple sites.
- Retrofit Solutions:Custom-engineered adaptations for existing structural openings.
Permanent installations anchor revenue today; retrofit solutions are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotterdam's climate adaptation programs anchor the automatic floodgate landscape, with Dutch water boards setting procurement standards that ripple across North Sea and Atlantic coastal markets. Fabricators in the Netherlands, Germany, and United States now compete to supply sensor-integrated barrier systems for subway and roadway protection.
United States
Subway network operators in New York and Miami specify vertically actuated barriers for portal protection against combined storm surge and tidal flooding. FEMA-certified flood-proofing requirements extend mandatory protection to commercial structures in designated hazard zones. The US Army Corps of Engineers mandates compliance standards that tighten product certification timelines for critical infrastructure awards.
Netherlands
Rotterdam's climate adaptation programs drive specification of smart-controlled floodgate systems with IoT-enabled remote monitoring as baseline functionality. Dutch water boards structure ten-year maintenance agreements into initial capital awards, locking out suppliers without regional service infrastructure. Randstad municipalities channel public investment toward automated barrier systems through national adaptation strategies mandated under EU Green Deal frameworks.
Germany
Rhine tributary municipalities favor lever gate configurations for permanent installations where precision positioning under variable hydrostatic loads remains essential. Hamburg engineering departments accelerated specification timelines for electromechanical linear actuators, compressing windows for competing drive technologies. German municipal utilities replicate Dutch lifecycle service contracting models, prioritizing vendors with certified technician networks.
China
Ministry of Water Resources GB standards enforcement governs import eligibility and local product certification for hydraulic structures. Yangtze River Delta infrastructure authorities procure automated barriers for transportation network protection in flood-prone metropolitan corridors. Domestic fabricators leverage reformulation cost advantages as REACH substance restrictions force European competitors to adapt hydraulic fluids and seal compounds.
United Kingdom
Thames Estuary flood defense programs specify barrier gate systems for critical transportation and utility assets exposed to tidal surge risks. Environment Agency procurement frameworks emphasize climate-resilient infrastructure standards aligned with national adaptation strategies. London and Southeast water authorities integrate smart control architectures into capital planning, compressing margins for suppliers lacking telemetry integration capabilities.
Automatic Floodgate Market Vendor Landscape
Global majors compete with regional champions across permanent municipal installations versus temporary deployment segments. Market structure tilts toward specialization, with fabricators clustering around material formulation advantages—aluminum alloy extrusion capabilities versus rapid-deployment design expertise. Three archetypes dominate: vertically integrated metal formers with in-house extrusion, hydraulic actuation specialists, and event-driven temporary barrier suppliers. Competitive moves concentrate on lifecycle service contracting capture and multi-jurisdiction certification stacking to accelerate cross-border infrastructure awards.
Among North American fabricators, Garrison Flood Control and FloodBreak occupy distinct positioning vectors—Garrison anchors permanent municipal installations through aluminum alloy formulation advantages, while FloodBreak exemplifies rapid-deployment specialization for temporary protection segments. AWMA Water Control Solutions represents the hydraulic actuation archetype, with Australian origin signaling southern hemisphere water infrastructure expertise. Chinese metal formers Hebei Jinshi Industrial Metal and Foshan LiTong FanPeng compete on GB standards compliance and reformulation cost structures that European REACH restrictions disadvantage.
| Leading Market Players |
|---|
| Garrison Flood Control |
| Flood Control America |
| Flood Control International |
| Hebei Jinshi Industrial Metal |
| Foshan LiTong FanPeng |
| FloodBreak |
| AquaFence |
| Flood Risk America |
| AWMA Water Control Solutions |
| Others |
Supply Flow & Price Mechanics
EU Green Deal infrastructure mandates gate qualified supply and premium-tier pricing access, as REACH substance restrictions force European fabricators to reformulate hydraulic fluids and seal compounds while Asian competitors avoid these compliance costs. Municipal buyers in Rotterdam and Hamburg now specify IoT-enabled remote monitoring as baseline functionality, compressing margins for suppliers lacking telemetry integration and creating tiered pricing stratification based on certification depth.
Pricing Analysis
Input-cost pass-through from aluminum alloy substitution and precision actuator sourcing drives pricing stratification across premium, standard, and economy tiers. Price differentiation hinges on certification grade—FEMA-certified flood-proofing commands substantial premiums over uncertified alternatives—and geographic delivery cost to coastal municipalities. Pricing pressure stems from electromechanical drive competition in temporary installation segments where rapid redeployment outweighs precision requirements. Industrial facilities demonstrate lowest price sensitivity given their willingness to pay for customized retrofit solutions, while cost-constrained residential buyers anchor the economy tier.
Supply Chain Analysis
Reverse-logistics flows for hydraulic actuator refurbishment and seal compound replacement create aftermarket revenue streams that European fabricators exploit through regional service infrastructure. Precision component sourcing concentrates in Germany and Japan, with aluminum alloy extrusion capabilities anchoring production in the Netherlands and United States. Raw material dependencies include high-performance elastomer compounds, precision-machined hydraulic cylinders, and sensor-integrated control modules. Supply chain risk centers on single-source vulnerability for electromechanical linear actuators rated for 4-6 meter water heights. Distribution runs through municipal procurement frameworks and industrial direct-sales channels, with lifecycle service contracting displacing transactional equipment sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aluminum alloy substitution and IoT-enabled predictive maintenance create margin-expansion pathways as fabricators reduce deployment weight while capturing recurring service revenue beyond hardware sales.
For Market Incumbents: Extend regional service infrastructure to capture lifecycle service contracting, as Dutch water boards and German municipal utilities now structure ten-year maintenance agreements into initial capital awards. Deepen backward integration into aluminum alloy extrusion capabilities to defend formulation advantages against Chinese metal formers. Counter electromechanical drive competition by accelerating certification timelines for smart control architectures in permanent municipal installations. For New Entrants and Emerging Players: Begin with industrial retrofit customization outside designated floodplains, where manufacturing facilities seek bespoke solutions for critical equipment rooms and loading docks and demonstrate concentrated willingness to pay premium pricing. Target the temporary installation segment where FloodBreak's rapid-deployment designs indicate viable white-space for event-driven and seasonal protection solutions. Pursue channel partnerships with municipal engineering consultants to bypass entrenched procurement relationships. For Investors and Strategic Acquirers: Roll-up economics work for hydraulic actuation specialists with certified technician networks because lifecycle service contracting is displacing transactional equipment sales and locking out suppliers without regional maintenance infrastructure. Five-to-ten year viability favors fabricators combining aluminum alloy formulation advantages with IoT platform connectivity. Monitor FEMA hazard zone designation updates as inflection indicators for mandatory protection requirements extending to commercial structures previously exempt.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | Garrison Flood Control leverages in-house capabilities to anchor permanent municipal installation economics. |
| Smart Control Platform Certification | Rotterdam's climate adaptation programs mandate IoT-enabled remote monitoring as baseline procurement functionality. |
| Lifecycle Service Contracting | Dutch water boards structure ten-year maintenance agreements that lock out suppliers lacking regional technician networks. |
| GB Standards Compliance Investment | China's Ministry of Water Resources governs import eligibility timelines for hydraulic structures in Yangtze River Delta corridors. |
| Industrial Retrofit Customization | Manufacturing facilities outside floodplains seek bespoke solutions protecting critical equipment rooms and loading docks. |
Methodological Framework
Coverage spans the Netherlands, Germany, United States, China, and United Kingdom, with primary inputs from each market combining interviews with municipal engineering directors, flood control procurement officers, hydraulic systems integrators, and aluminum alloy fabricators. Secondary validation draws from US Army Corps of Engineers certification databases, EU Green Deal infrastructure procurement records, China's Ministry of Water Resources GB standards filings, and FEMA flood hazard zone designations. Bottom-up project pipeline analysis triangulates against top-down infrastructure spending forecasts across transportation network protection and climate adaptation programs.
Rate-of-change decomposition separates volume drivers—municipal procurement acceleration, industrial retrofit penetration—from value drivers including aluminum alloy substitution premiums and smart control system attach rates. Segmentation dimensions span product type, actuation technology, end-user archetype, and installation permanence, with additional granularity on water height ratings and certification tiers. CAGRs were derived from regression analysis against infrastructure investment cycles and regulatory mandate implementation timelines, incorporating sensor-triggered deployment adoption curves and REACH compliance cost trajectories.
Several conditions sit outside the modeled scope, including sudden shifts in hydraulic actuator supply concentration, harmonization of building codes across jurisdictions, and commodity volatility in aluminum alloy feedstocks. Forecasts reflect documented assumptions about municipal budget continuity and climate adaptation program funding. Practitioners should monitor FEMA hazard zone designation updates, EU Green Deal procurement mandate expansions, and GB standards enforcement intensity for early signals of forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency and Disaster Management
Earthquake Early Warning System Market
Emergency and Disaster Management
Emergency Lighting Market
Emergency and Disaster Management
Free Fall Lifeboats Market
Emergency and Disaster Management
Advanced Disaster Management Simulator Market
Emergency and Disaster Management
Crisis Emergency and Incident Management Platform Market
Emergency and Disaster Management
Survival Tools Market
Emergency and Disaster Management
Disaster Restoration Services Market
Emergency and Disaster Management
Outdoor Emergency Safety Shower Market
Emergency and Disaster Management
Incident and Emergency Management Market
Emergency and Disaster Management
Lifeboat Market
Emergency and Disaster Management
Global Emergency Medical Service (EMS) Products Market
Emergency and Disaster Management
Emergency Blankets Market
Emergency and Disaster Management
Hazard Control Market
Emergency and Disaster Management
Homeland Security and Emergency Management Market
Emergency and Disaster Management
Emergency Location Transmitter Market
Emergency and Disaster Management
North America Homeland Security and Emergency Management Market