
 Outdoor Emergency Safety Shower Market | 2026-2036
Outdoor Emergency Safety Shower Market Size, Share, and Industry Trends Forecast 2026-2036
Outdoor Emergency Safety Shower Market Insights
The industrial distributor channel is narrowing as direct procurement from manufacturers gains share among large facility operators. Hughes Safety Showers leverages its British manufacturing base to sustain European market presence. Bradley Corporation anchors North American demand through deep relationships with institutional buyers. Haws Corporation differentiates through specialized thermostatic mixing valve technology.
An outdoor emergency safety shower is a plumbed or self-contained drenching fixture designed to deliver a minimum flow rate of 75.7 liters per minute for fifteen minutes to neutralize chemical splashes or thermal burns. These units typically incorporate galvanized steel or stainless steel construction with corrosion-resistant coatings to withstand continuous environmental exposure. Fixed shower stations dominate product type demand due to permanent installation at high-risk process points, while portable shower units represent the fastest-growing segment as construction and remote site operators prioritize mobility. Stainless steel material grades command premium positioning given ANSI Z358.1 compliance requirements for corrosion resistance in coastal and chemical environments.
OSHA workplace safety standards, ANSI Z358.1 emergency equipment specifications, and EPA chemical handling regulations collectively shape product design and facility compliance obligations across the United States. The EPA's Risk Management Program amendments are forcing facility upgrades at chemical processing sites. Stakeholders must monitor evolving state-level environmental enforcement intensity to anticipate replacement cycle timing and specification shifts.
Market Dynamics
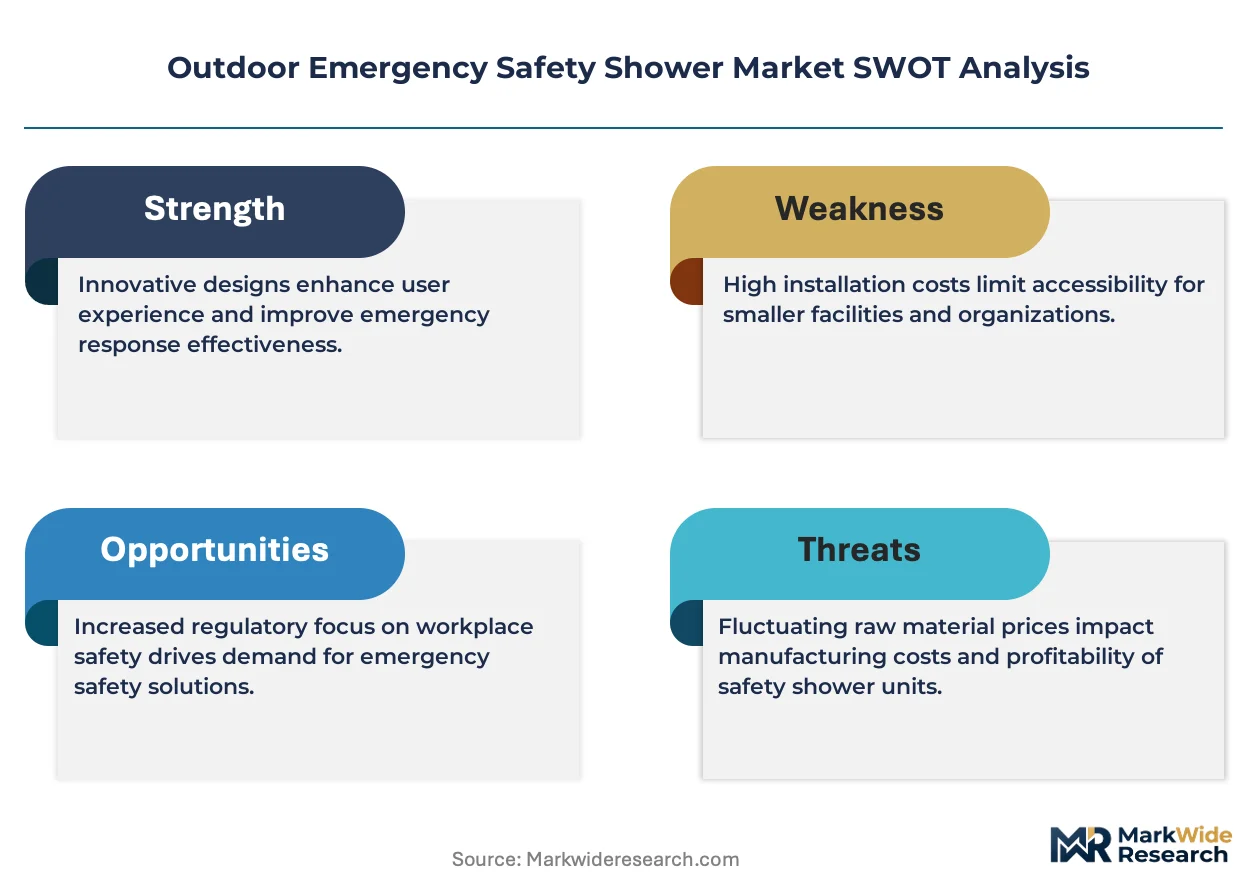
OSHA's updated workplace safety mandates are tightening compliance requirements across chemical processing facilities, forcing replacement cycles and specification upgrades that concentrate demand among large facility operators with direct manufacturer relationships.
Growth Catalysts
- ANSI Z358.1 specification updates:Revised corrosion resistance standards are mandating stainless steel upgrades at coastal petrochemical facilities, accelerating replacement demand for non-compliant galvanized installations.
- Gulf Coast petrochemical corridor expansion:New ethylene cracker and derivative plant construction across Texas and Louisiana is embedding permanent shower infrastructure at high-risk process points.
- Portable unit technology maturation:Self-contained tank systems with integrated heating are enabling construction and remote site operators to meet OSHA requirements without plumbed infrastructure.
Market Restraints
- Stainless steel price volatility:Nickel and molybdenum input cost swings compress margins for ANSI-compliant grade 316L construction, forcing suppliers to absorb fluctuations or risk volume loss.
- Regional supply concentration:Thermostatic mixing valve manufacturing clusters in the Midwest create single-source vulnerability for temperature-controlled shower systems.
- Technical limitation in freeze protection:Electric trace heating requirements in northern climates add installation complexity and ongoing energy costs that deter budget-constrained buyers.
Strategic Opportunities
- EPA Risk Management Program amendments:Chemical facility upgrade mandates are creating replacement windows for integrated shower and eyewash systems at high-hazard sites.
- Underpenetrated upstream oilfield services:Remote drilling and completion sites in the Permian Basin lack permanent infrastructure, creating demand for ruggedized portable units with extended tank capacity.
- Smart monitoring convergence:IoT flow sensors and automated testing logs are enabling predictive maintenance contracts that shift revenue from equipment sales to recurring service streams.
Industry Challenges
- Certification timeline compression:Third-party ANSI Z358.1 testing backlog at accredited laboratories is delaying product launches and contract fulfillment for new entrants.
- Integration complexity with legacy water systems:Retrofitting thermostatic mixing valves into existing plant infrastructure requires custom engineering that extends project timelines and strains field technician availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Outdoor Emergency Safety Shower Market |
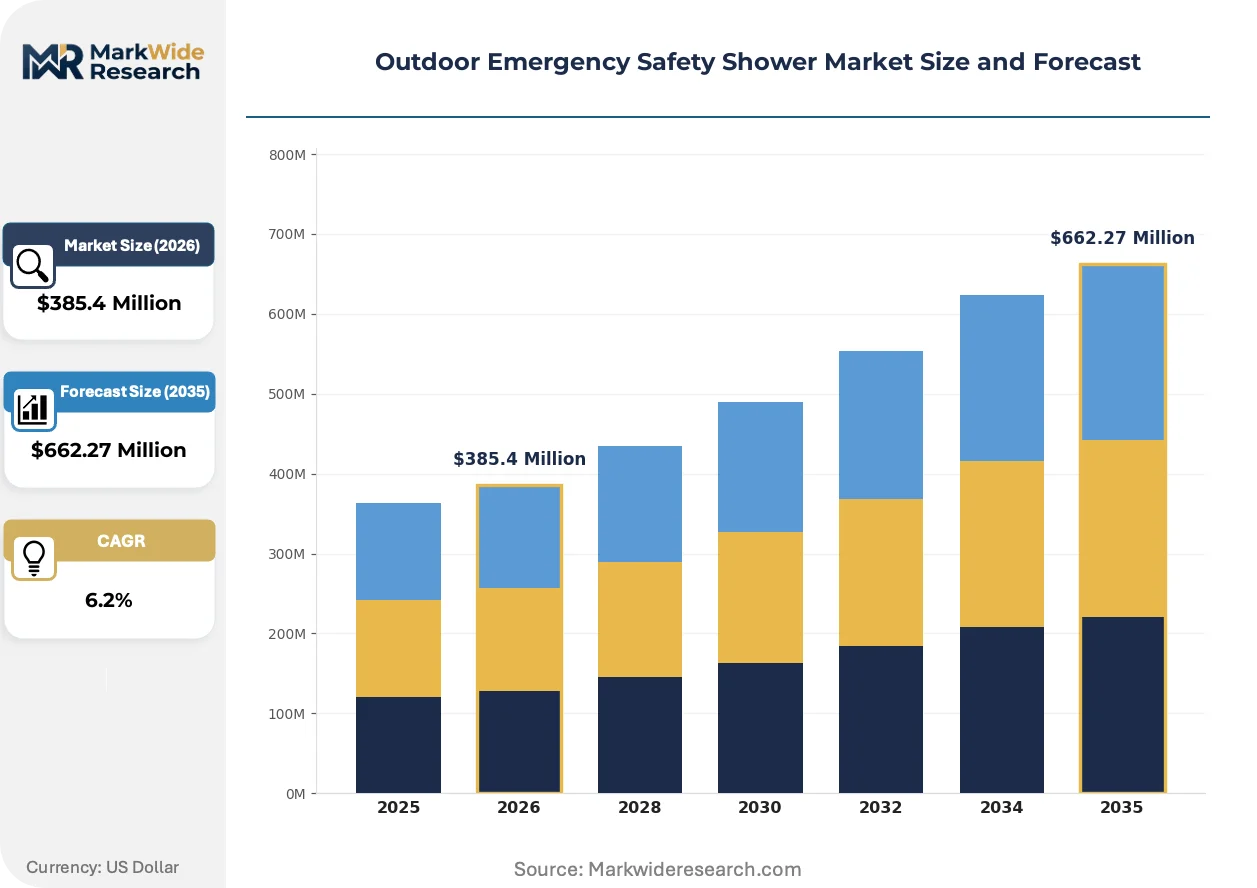
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $662.27 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Contained Units, Portable Showers, Emergency Shower Stations, Fixed Showers Material: Stainless Steel, Plastic, Aluminum, Fiberglass Installation Type: Temporary Installations, Permanent Installations, Wall-Mounted, Ground-Mounted End User: Industrial Facilities, Construction Sites, Laboratories, Public Spaces |
| Companies Covered | Hughes Safety Showers, Bradley Corporation, Haws Corporation, Guardian Equipment, Aqua Safety Showers, Encon Safety Products, Drägerwerk, Speakman Company, Justrite Safety Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outdoor Emergency Safety Shower Market Trends and Innovations
Product development is pivoting toward connected infrastructure and material durability, while procurement patterns favor direct manufacturer engagement over traditional distribution channels.
Thermostatic mixing valve technology with digital temperature logging is rendering obsolete manual testing protocols that relied on facility staff documentation. Large chemical processors are adopting these systems to automate compliance record-keeping for OSHA inspections. The shift is compressing aftermarket service margins as predictive diagnostics reduce emergency callout frequency.
EPA Risk Management Program amendments are forcing facility-wide emergency equipment audits at chemical processing sites. These mandates are triggering coordinated replacement cycles rather than piecemeal upgrades. Gulf Coast refineries are responding by bundling shower, eyewash, and deluge system procurement into single-source contracts.
Direct procurement from manufacturers is displacing industrial distributor relationships among facility operators with internal engineering teams. Large petrochemical buyers are consolidating vendor lists to secure volume pricing and dedicated technical support. This pattern is most visible across Texas and Louisiana, where major operators have established preferred supplier agreements bypassing traditional MRO channels.
Outdoor Emergency Safety Shower Market Segmentation
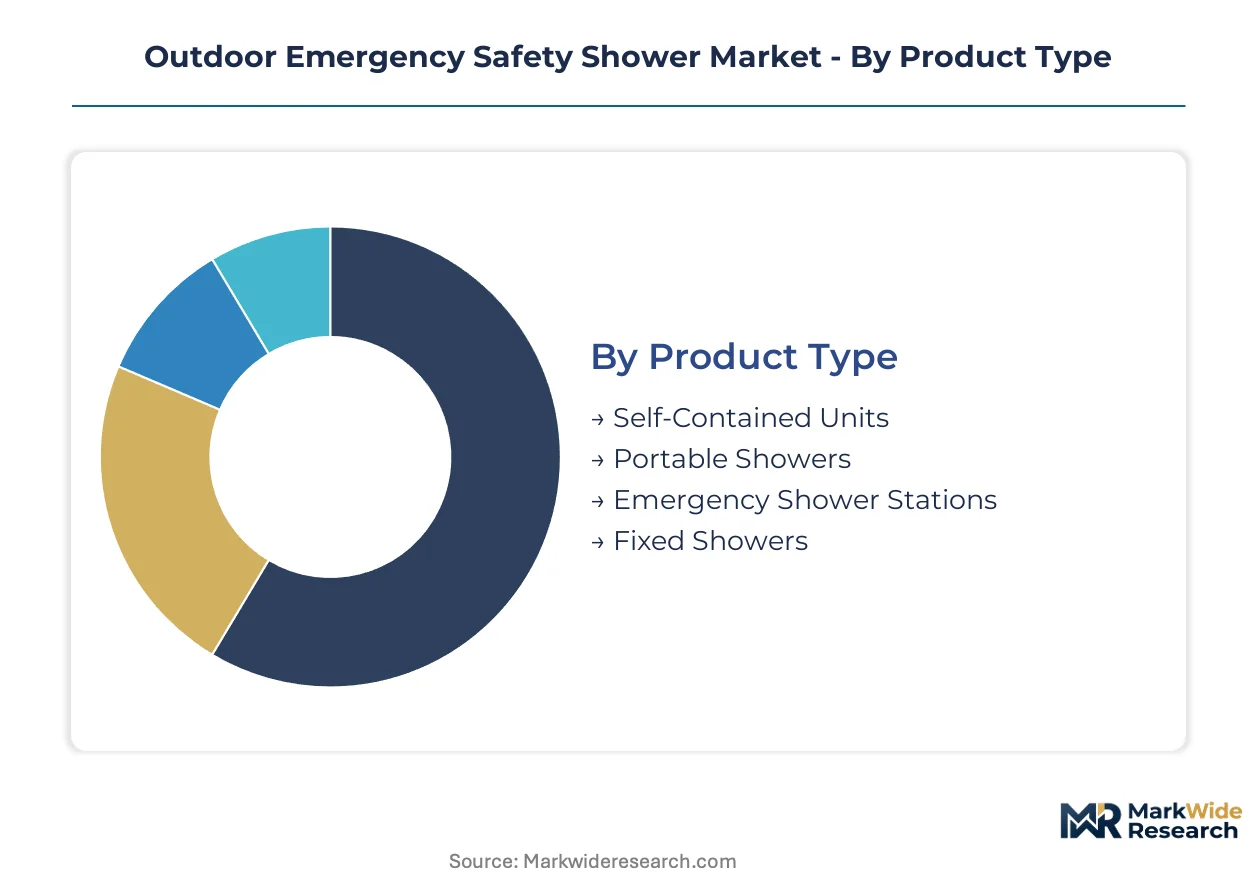
Emergency safety shower procurement varies sharply across facility types, with chemical processors prioritizing permanent stainless-steel infrastructure while construction operators favor portable mobility. Material selection and installation approach directly determine compliance audit outcomes and replacement cycle timing.
Product Type:
After-sales service intensity runs highest for self-contained and portable units requiring tank refills, heating system maintenance, and seasonal winterization protocols.
- Fixed Showers:Permanent plumbed installations deliver continuous water supply at 75.7 liters per minute through galvanized or stainless-steel riser assemblies. Demand concentrates at Texas and Louisiana petrochemical facilities where OSHA mandates embed these at high-risk process points adjacent to chemical handling zones.
- Portable Showers:Self-contained tank systems with integrated heating and pressurized delivery enable compliance without permanent infrastructure. Construction sites across the Permian Basin and remote upstream oilfield locations are expanding adoption as project-based safety requirements intensify.
- Emergency Shower Stations:Combined shower-eyewash units with shared water supply and activation mechanisms.
- Self-Contained Units:Tank-fed systems with onboard water storage and gravity or pump-driven flow.
By volume, Fixed Showers lead. By growth pace, Portable Showers is ahead.
Material:
Cost tier stratification separates premium corrosion-resistant grades from budget alternatives suited to benign indoor environments.
- Stainless Steel:Grade 316L and 304 alloys provide ANSI Z358.1-mandated corrosion resistance for coastal chemical facilities and outdoor exposure. Gulf Coast refineries specify this material exclusively given salt-air degradation risks that compromise galvanized alternatives.
- Plastic:Polyethylene and PVC constructions reduce weight and capital cost for temporary installations and low-corrosion indoor settings.
- Aluminum:Lightweight metal options for weight-sensitive portable applications and aircraft maintenance facilities.
- Fiberglass:Reinforced polymer composites offering chemical resistance with reduced thermal conductivity.
Stainless Steel commands the revenue share. Plastic is gaining share fastest in cost-constrained segments.
Installation Type:
Application environment dictates mounting approach, with freeze protection requirements and soil conditions driving specification divergence between northern and southern geographies.
- Permanent Installations:Concrete-anchored systems with buried supply lines and integrated drainage. Chemical processing plants across Louisiana and Texas embed these at fixed process points where hazardous material exposure risk is constant.
- Wall-Mounted:Bracket-attached units conserving floor space in congested process areas and indoor laboratory settings.
- Ground-Mounted:Freestanding pedestal designs for outdoor yards and tank farm perimeters.
- Temporary Installations:Non-anchored systems for construction phases and turnaround maintenance periods.
Permanent Installations anchor replacement demand. Temporary Installations show the steepest expansion trajectory in construction-linked procurement.
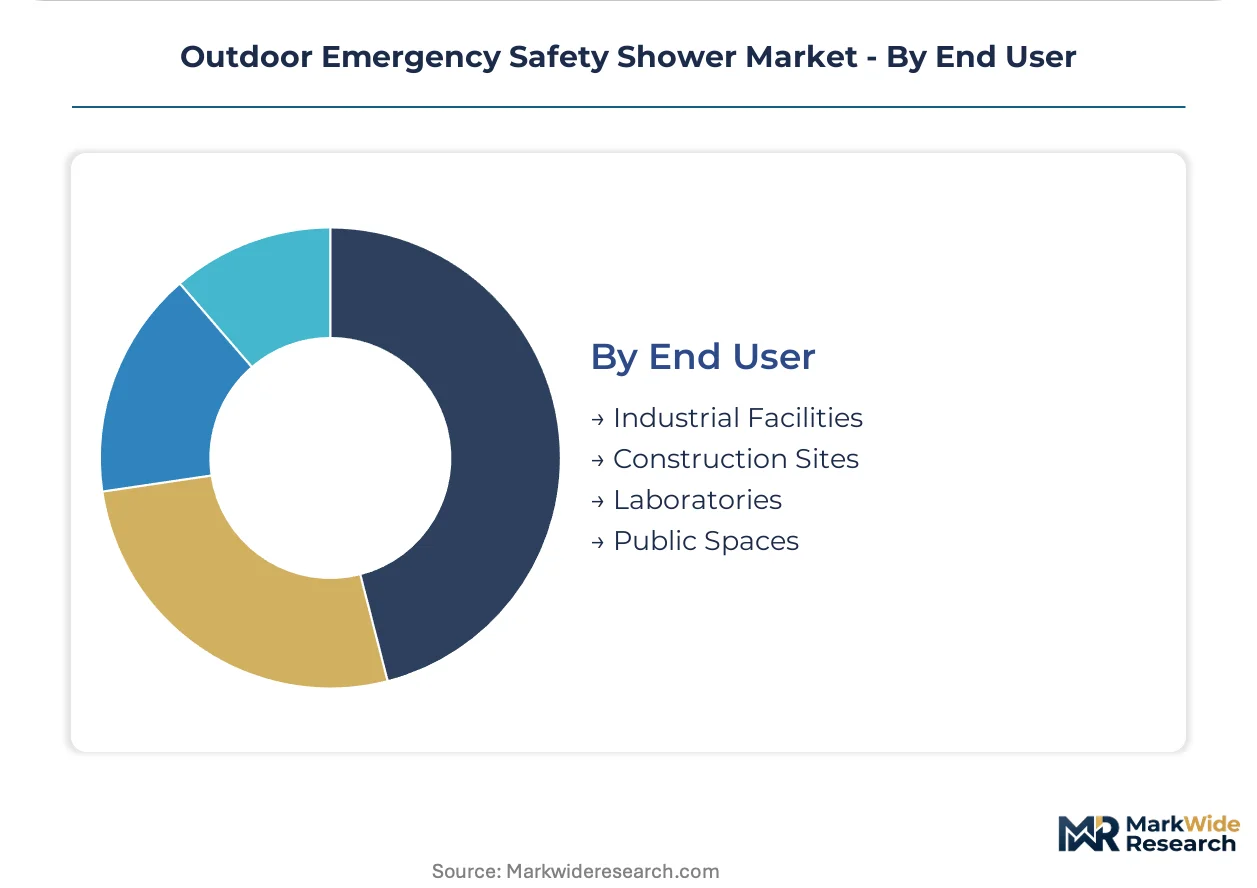
End User:
Customer type determines specification stringency, with industrial processors driving premium material adoption and public sector buyers emphasizing first-cost minimization.
- Industrial Facilities:Petrochemical refineries, chemical manufacturing plants, and bulk storage terminals requiring full ANSI Z358.1 compliance with documented testing protocols. Gulf Coast ethylene crackers and derivative plants are embedding integrated shower-eyewash-deluge systems under EPA Risk Management Program mandates.
- Construction Sites:Project-based operators lacking permanent infrastructure prioritize portable self-contained units with rapid deployment capability.
- Laboratories:Research and quality control facilities with lower flow requirements and indoor-only exposure profiles.
- Public Spaces:Municipal and institutional buyers with standardized specifications and competitive bidding procurement.
Industrial Facilities generate the largest volume. Construction Sites are expanding most quickly as remote site safety enforcement tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA workplace safety mandates and EPA Risk Management Program amendments are tightening compliance requirements across industrial corridors, concentrating replacement demand in petrochemical-intensive geographies with aging infrastructure.
United States
Gulf Coast petrochemical expansion drives fixed shower installations at new ethylene crackers and derivative plants. EPA Risk Management Program audits are forcing facility-wide emergency equipment upgrades at Texas and Louisiana refineries. Houston-Beaumont-Port Arthur corridor operators are consolidating vendor lists to secure volume pricing on ANSI Z358.1-compliant stainless steel systems.
Germany
Chemical manufacturing clusters along the Rhine require corrosion-resistant outdoor emergency infrastructure under REACH chemical handling protocols. ECHA enforcement of environmental exposure limits is accelerating replacement cycles at BASF-Ludwigshafen scale facilities. Ruhr industrial belt operators are adopting thermostatic mixing valve technology to automate temperature compliance documentation.
China
Petrochemical capacity expansion in Ningbo-Zhoushan and Dalian is embedding permanent shower stations at new integrated refining complexes. MIIT safety standard harmonization with ISO protocols is raising specification stringency for coastal installations. Yangtze River Delta chemical parks are mandating stainless steel construction to withstand humid subtropical exposure.
Saudi Arabia
Jubail Industrial City and Yanbu petrochemical complexes are upgrading emergency infrastructure under Saudi Aramco contractor safety requirements. SABIC supplier qualification programs are specifying ANSI Z358.1-equivalent performance for new plant construction. Eastern Province megaproject development is creating bundled procurement opportunities for integrated shower-eyewash-deluge systems.
India
Gujarat's Dahej and Hazira chemical zones are expanding emergency equipment deployment under Factory Act hazardous process regulations. CDSCO-aligned industrial safety inspections are identifying non-compliant galvanized installations for replacement. Maharashtra's Mumbai-Pune industrial corridor is seeing demand concentration from pharmaceutical API manufacturers upgrading outdoor tank farm protection.
Outdoor Emergency Safety Shower Market Competitive Landscape
On the supply side, the industry is moderately consolidated around established safety equipment specialists with deep regulatory compliance expertise. Tiered competitive positioning separates premium-grade stainless steel fabricators from cost-optimized galvanized alternatives. Two strategic archetypes dominate: integrated safety conglomerates with broad personal protective equipment portfolios, and focused shower specialists with ANSI certification depth. Geographic expansion through distributor partnerships and direct procurement channel development represent the dominant competitive moves.
Among North American institutional suppliers, Bradley Corporation and Haws Corporation exemplify the specialist archetype with concentrated expertise in thermostatic mixing valve technology and ANSI Z358.1 compliance documentation. Hughes Safety Showers occupies a position representing British manufacturing-based European market presence. These three anchors illustrate how regulatory certification depth and regional manufacturing footprint shape competitive positioning in a specification-driven procurement environment.
| Leading Market Players |
|---|
| Hughes Safety Showers |
| Bradley Corporation |
| Haws Corporation |
| Guardian Equipment |
| Aqua Safety Showers |
| Encon Safety Products |
| Drägerwerk |
| Speakman Company |
| Justrite Safety Group |
| Others |
Pricing and Supply Chain Analysis
Midwest thermostatic mixing valve manufacturing clusters concentrate upstream supply for temperature-controlled shower systems, anchoring margin pools with ANSI-certified fabricators who command premium positioning against galvanized alternatives. Large petrochemical buyers leverage direct procurement relationships to compress distributor markups while securing volume-tier pricing on grade 316L stainless steel installations.
Pricing Analysis
Volume-discount tiering structures separate procurement brackets for large facility operators from project-based construction buyers. Pricing stratifies across ANSI Z358.1-certified premium systems, standard galvanized fixed installations, and economy portable units for temporary sites. Cost compression in the standard tier is intensifying because nickel and molybdenum input volatility forces suppliers to absorb margin erosion or risk volume loss to backward-integrated competitors. Construction site operators exhibit the highest price sensitivity due to project-based budgeting, while Gulf Coast refineries prioritize certification compliance over first-cost minimization.
Supply Chain Analysis
Upstream feedstock for grade 316L stainless steel draws from Chinese nickel processing, Indonesian ore refining, and European mill production. Component assembly rests on Midwest valve manufacturing, Southeast Asian electronics for IoT sensors, and regional steel fabrication. Single-source vulnerability concentrates in thermostatic mixing valve production where limited accredited suppliers create chokepoints. Distribution runs through direct manufacturer channels displacing traditional industrial distributors among large chemical processors with internal engineering teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory certification entrenchment creates switching costs that lock in incumbent positions. ANSI Z358.1 compliance documentation requirements and third-party testing backlogs erect barriers that delay new entrant product launches.
For Market Incumbents: Build certification depth moats by expanding ANSI-accredited testing laboratory partnerships to compress product launch timelines. Anchor backward integration into grade 316L stainless steel fabrication to capture margin pools currently flowing to external metal suppliers. Defend against emerging IoT-enabled shower specialists by accelerating predictive maintenance service bundling that shifts revenue toward recurring streams.
For New Entrants and Emerging Players: Establish a beachhead in underpenetrated Permian Basin upstream oilfield services where remote drilling sites lack permanent infrastructure and incumbent presence is thin. Target ruggedized portable units with extended tank capacity as the most penetrable segment given project-based procurement patterns and lower certification stringency. Pursue distributor partnerships with regional safety equipment specialists serving construction operators outside Gulf Coast petrochemical corridors.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed industrial safety conglomerates seeking platform consolidation to broaden personal protective equipment portfolios. Long-term viability hinges on regulatory enforcement durability rather than cyclical capital expenditure patterns. Monitor EPA Risk Management Program audit frequency as the inflection indicator for coordinated replacement cycle timing at chemical processing facilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Steel Fabrication | Captures margin pools from nickel volatility while securing grade 316L supply for coastal installations. |
| IoT Sensor Platform Development | Enables predictive maintenance contracts that shift revenue from equipment sales to recurring service streams. |
| ANSI Testing Laboratory Partnership Expansion | Compresses certification timelines that currently delay product launches and contract fulfillment. |
| Direct Procurement Channel Investment | Bypasses industrial distributors to capture volume pricing relationships with large petrochemical operators. |
| Portable Unit Heating System Innovation | Extends addressable market into northern climates where electric trace heating complexity deters adoption. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of OSHA enforcement databases, ANSI Z358.1 certification records, and EPA Risk Management Program audit disclosures. Plant managers, procurement leads at downstream chemical processors, distribution channel partners, and aftermarket service directors provided operational perspective. Customs trade data, SEC filings from listed safety equipment manufacturers, and industry association reports supplied validation anchors. Bottom-up unit economics triangulate against top-down market sizing across product type and material segmentation dimensions.
Forecast inputs include installation base aging curves, regulatory amendment timelines, and petrochemical capacity expansion project pipelines. Modeled dimensions span product type, material grade, installation approach, and end-user facility category. CAGRs derive from replacement cycle velocity projections and new construction embedding rates. Nickel price trajectory assumptions and thermostatic mixing valve supply capacity constraints inform scenario boundaries across the analysis window.
Sensitivities concentrate around OSHA enforcement intensity variations, stainless steel input cost swings, and third-party testing laboratory backlog durations. Cross-checking against chemical industry capital expenditure survey data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency and Disaster Management
Advanced Disaster Management Simulator Market
Emergency and Disaster Management
Emergency Blankets Market
Emergency and Disaster Management
Global Emergency Beacon Transmitter Market
Emergency and Disaster Management
Cyber Crisis Management Market
Emergency and Disaster Management
Emergency Shower and Eyewash Station Market
Emergency and Disaster Management
Survival Tools Market
Emergency and Disaster Management
Asia-Pacific Process Safety Services Market
Emergency and Disaster Management
North America Homeland Security and Emergency Management Market
Emergency and Disaster Management
North America Emergency Shower and Eye Wash Station Market
Emergency and Disaster Management
Lifeboat Market
Emergency and Disaster Management
Hazard Control Market
Emergency and Disaster Management
Emergency and Disaster Response Market
Emergency and Disaster Management
Emergency Lighting Market
Emergency and Disaster Management
Global Emergency Medical Service (EMS) Products Market
Emergency and Disaster Management
Disaster Restoration Services Market
Emergency and Disaster Management
Automatic Floodgate Market