
 Emergency Shutdown System Market | 2026-2036
Emergency Shutdown System Market Size, Share, and Industry Trends Forecast 2026-2036
Emergency Shutdown System Market Intelligence
Software-defined safety logic and predictive maintenance subscriptions are shifting the commercial model from one-time hardware sales to long-term service contracts. This transition favors vendors with extensive digital platforms and field service networks. Siemens AG leverages its Totally Integrated Automation portal to offer comprehensive lifecycle services. Meanwhile, Emerson Electric Co. specializes in integrated solutions for final control elements, particularly within the challenging environments of offshore oil and gas production in countries like Norway and Brazil.
An emergency shutdown system is an automated safety instrumented system designed to bring an industrial process to a safe state during a hazardous event. These systems operate on a principle of de-energize-to-trip, ensuring fail-safe performance by closing valves and shutting down equipment. The core purpose is to prevent equipment damage, environmental release, and harm to personnel. Within the product mix, integrated control systems command the highest value, while sensors are seeing rapid adoption due to improved diagnostic capabilities. The oil and gas end user segment remains the largest source of demand.
Regulatory frameworks are the primary market enablers, mandating the use of certified safety systems. In the United States, OSHA's Process Safety Management (PSM) standards define requirements for highly hazardous chemical facilities. The European Union enforces compliance through the Seveso III Directive and mandatory CE marking for safety components. Globally, the IEC 61508 and IEC 61511 standards provide the foundational framework for functional safety. The key decision for asset owners now is how to balance the cost of upgrading legacy systems against the operational risks of non-compliance.
Market Dynamics
The central market dynamic is the structural shift from hardware-centric compliance to software-defined, service-oriented safety models. This transition is propelled by the digitalization of process industries and stringent adherence to functional safety standards like IEC 61511.
Growth Catalysts
- Regulatory Enforcement:Heightened enforcement of functional safety standards, notably IEC 61511 in the global oil and gas sector and OSHA's PSM in the United States, compels investment in certified systems.
- Infrastructure Investment:Large-scale capital projects in the chemical and energy sectors across the Middle East, particularly in Saudi Arabia and the UAE, create baseline demand for new safety system installations.
- Digitalization in Operations:The integration of IIoT sensors and predictive analytics into process control allows for enhanced diagnostic coverage and proactive maintenance, justifying upgrades to smarter emergency shutdown systems.
Market Restraints
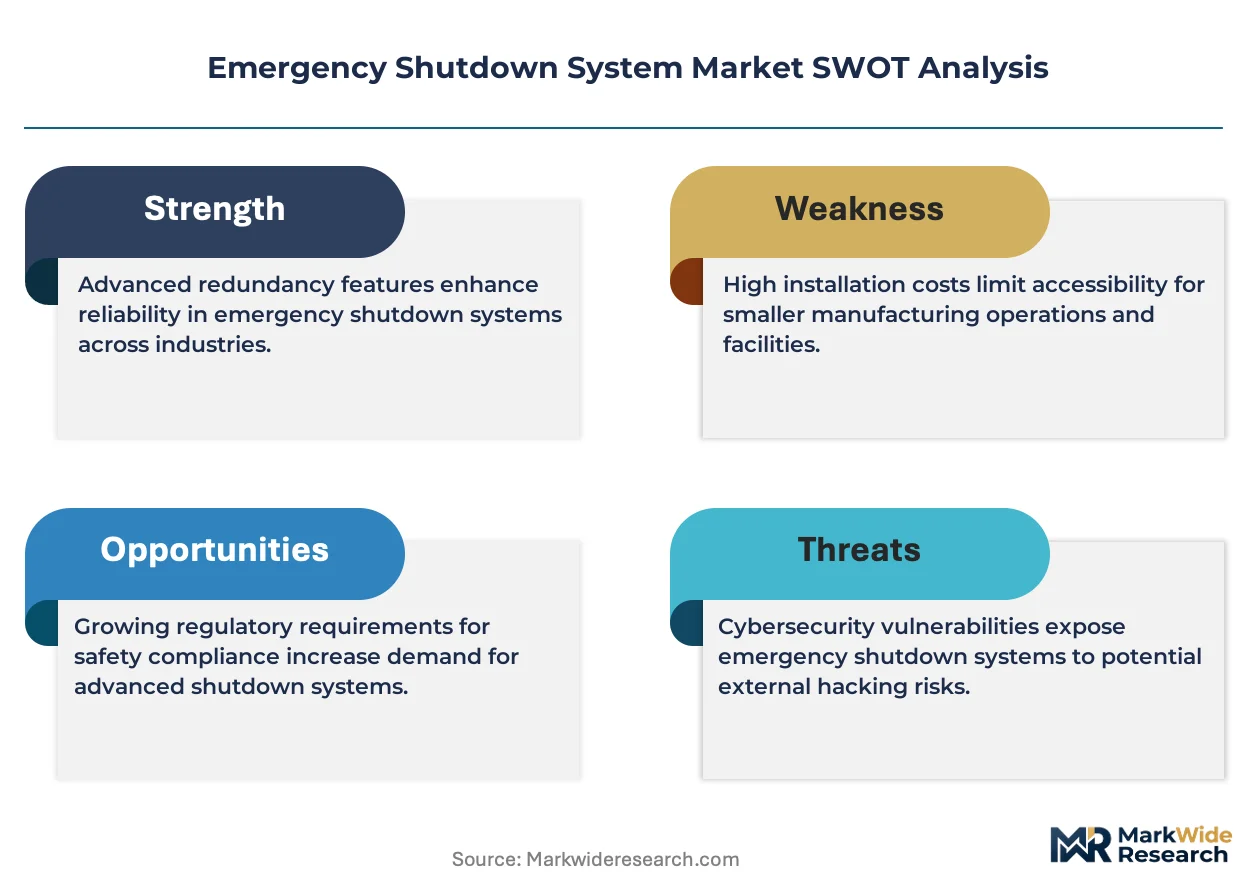
- High Capital Costs:The significant upfront investment required to replace or upgrade legacy, non-compliant ESD systems in brownfield facilities presents a major barrier for asset owners with constrained budgets.
- Integration Complexity:Technical difficulties in integrating modern, digital ESD systems with a diverse installed base of older, proprietary distributed control systems (DCS) can lead to project delays and cost overruns.
- Certification Bottlenecks:Obtaining Safety Integrity Level (SIL) certification for new components and software is a time-consuming and expensive process, slowing the introduction of innovative hardware and software.
Strategic Opportunities
- Lifecycle Service Models:Developing subscription-based offerings for predictive maintenance, remote monitoring, and safety logic management creates recurring revenue streams beyond initial hardware sales.
- New Energy Applications:Adapting ESD principles and technologies for emerging industrial processes, such as green hydrogen production and large-scale battery energy storage systems (BESS), opens new vertical markets.
- Cybersecurity for SIS:Providing specialized cybersecurity services tailored for Safety Instrumented Systems (SIS) addresses a critical vulnerability and creates a high-value service niche for qualified vendors.
Industry Challenges
- Talent Scarcity:A persistent shortage of certified functional safety engineers and technicians creates bottlenecks in project execution, commissioning, and long-term maintenance of complex safety systems.
- Legacy System Migration Risk:Managing the operational risks and potential for extended production downtime during the migration from outdated relay-based logic to modern programmable safety systems is a primary concern for plant operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emergency Shutdown System Market |
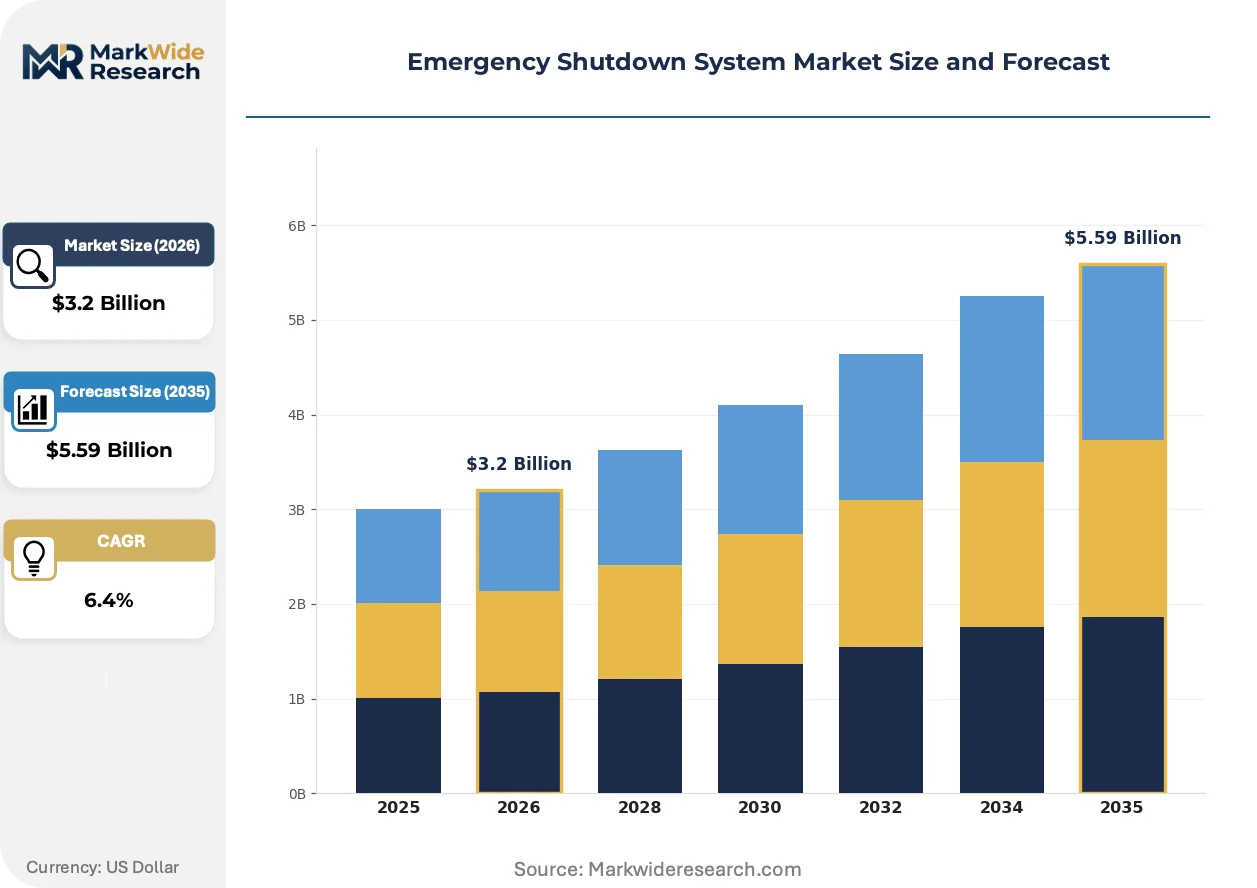
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $5.59 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Control Systems, Actuators, Sensors, Valves Technology: Hydraulic, Pneumatic, Electrical, Mechanical End User: Oil & Gas, Chemicals, Power Plants, Manufacturing Application: Process Safety, Equipment Protection, Fire Safety, Emergency Handling |
| Companies Covered | ABB Ltd, Emerson Electric Co., Honeywell International Inc., Schneider Electric SE, General Electric Company, Siemens AG, Rockwell Automation Inc, Yokogawa Electric Corporation, HIMA Paul Hildebrandt GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emergency Shutdown System Market Strategic Shifts & Innovations
The convergence of operational technology with information technology is redefining system architecture and performance expectations. This evolution prioritizes data-driven safety insights and total lifecycle cost over the initial capital expense of standalone hardware components, favoring integrated digital platforms.
Software-defined safety logic provides the ability to program and validate safety functions independently of the underlying hardware. Process industries like chemical manufacturing and refining are adopting this approach to decouple hardware and software refresh cycles. This separation of concerns is rewriting the traditional vendor lock-in model, granting asset owners greater flexibility and control over system upgrades.
Europe's Seveso III Directive imposes stringent risk assessment and public information mandates for sites handling hazardous substances. This regulation directly increases the burden of proof for safety measures, compelling operators to invest in systems with better diagnostics and auditable performance records. The chemical and petrochemical sectors across the European Union are most affected, upgrading ESD systems to bolster their safety case reports for regulatory authorities.
Asset owners are moving from one-time capital expenditures to long-term service contracts that guarantee system availability and performance. This model displaces the traditional sale of standalone safety PLCs and final control elements with comprehensive lifecycle management agreements. The shift is most pronounced in the capital-intensive offshore oil and gas sector, especially in the North Sea and Brazil, where maximizing operational uptime is paramount.
Emergency Shutdown System Market Segmentation
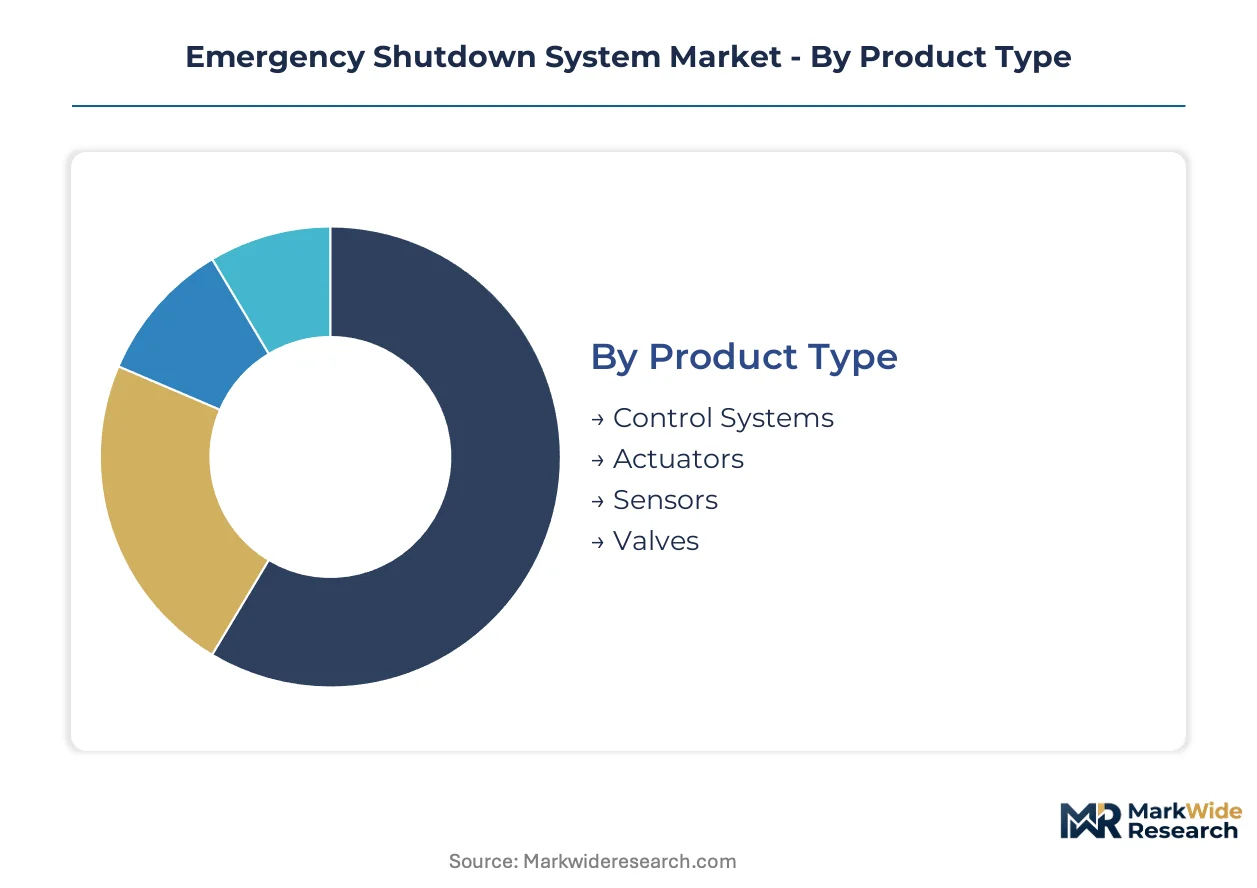
Market segmentation provides a granular view of the Emergency Shutdown System market, dissecting it into core components, operational technologies, primary end-use sectors, and specific safety applications. This detailed breakdown helps identify areas of concentrated demand and emerging growth trajectories within the industrial safety landscape.
Product Type:
Product type segmentation highlights the specific hardware and software components that constitute an emergency shutdown system, defined by their functional specification and integration capabilities.
- Control Systems:These integrated platforms manage safety logic, process inputs, and execute shutdown sequences, forming the central intelligence of an ESD. Demand concentrates in complex industrial facilities like refineries in Saudi Arabia, driven by the need for centralized, auditable safety management.
- Sensors:These devices detect abnormal process conditions, providing critical diagnostic data for system activation and performance monitoring. Rapid adoption is occurring in offshore oil and gas operations in Norway, where enhanced diagnostic capabilities improve early hazard detection and reduce false trips.
- Actuators:These mechanical devices convert control signals into physical motion, primarily used for opening or closing valves and dampers in a safety sequence.
- Valves:Critical components that physically isolate process sections or vent hazardous materials, ensuring process containment during an emergency shutdown.
Mature deployment sits with Valves. Newer deployment is concentrated in Sensors.
Technology:
The technology segmentation delineates the underlying physical principles by which emergency shutdown systems operate, directly influencing their suitability for specific industrial applications.
- Electrical:These systems utilize electrical signals and circuits for control and actuation, offering precise, high-speed responses and extensive diagnostic capabilities. Demand is strong in modern chemical plants across the European Union, where complex interlocks and rapid shutdown are critical for safety compliance.
- Hydraulic:Employing fluid pressure to generate force, hydraulic systems are robust and deliver high torque for operating large valves in heavy-duty industrial environments. They see significant use in offshore platforms in Brazil, addressing the need for powerful and reliable actuation in harsh conditions.
- Pneumatic:These systems use compressed air for control and actuation, valued for their intrinsic safety in hazardous atmospheres and simplicity of design.
- Mechanical:Relying on physical linkages and levers, mechanical systems offer straightforward operation and are often used in simpler, fail-safe applications.
Electrical technologies are gaining share fastest due to their advanced diagnostic capabilities. Mechanical systems maintain a niche for basic, fail-safe functions.
End User:
End-user segmentation illustrates where the primary demand for emergency shutdown systems originates, reflecting the distinct safety requirements and operational scales of various industrial sectors.
- Oil & Gas:This sector represents the largest source of demand, requiring highly robust and certified ESD systems for drilling, production, and refining operations. Stringent functional safety standards like IEC 61511 drive investment in new installations and upgrades across the Middle East.
- Chemicals:Facilities handling highly hazardous substances, such as those in Germany, demand advanced ESD solutions to prevent runaway reactions and manage toxic releases. OSHA's PSM standards in the United States mandate comprehensive safety instrumented systems for these operations.
- Power Plants:These facilities, including nuclear and thermal power generation, deploy ESD systems to prevent equipment damage and ensure grid stability during critical operational upsets.
- Manufacturing:Diverse manufacturing operations, particularly those involving automated processes and hazardous materials, utilize ESD systems for personnel and equipment protection.
Regulatory frameworks significantly influence demand in the Oil & Gas sector, while the Chemicals segment responds to evolving process safety management requirements.
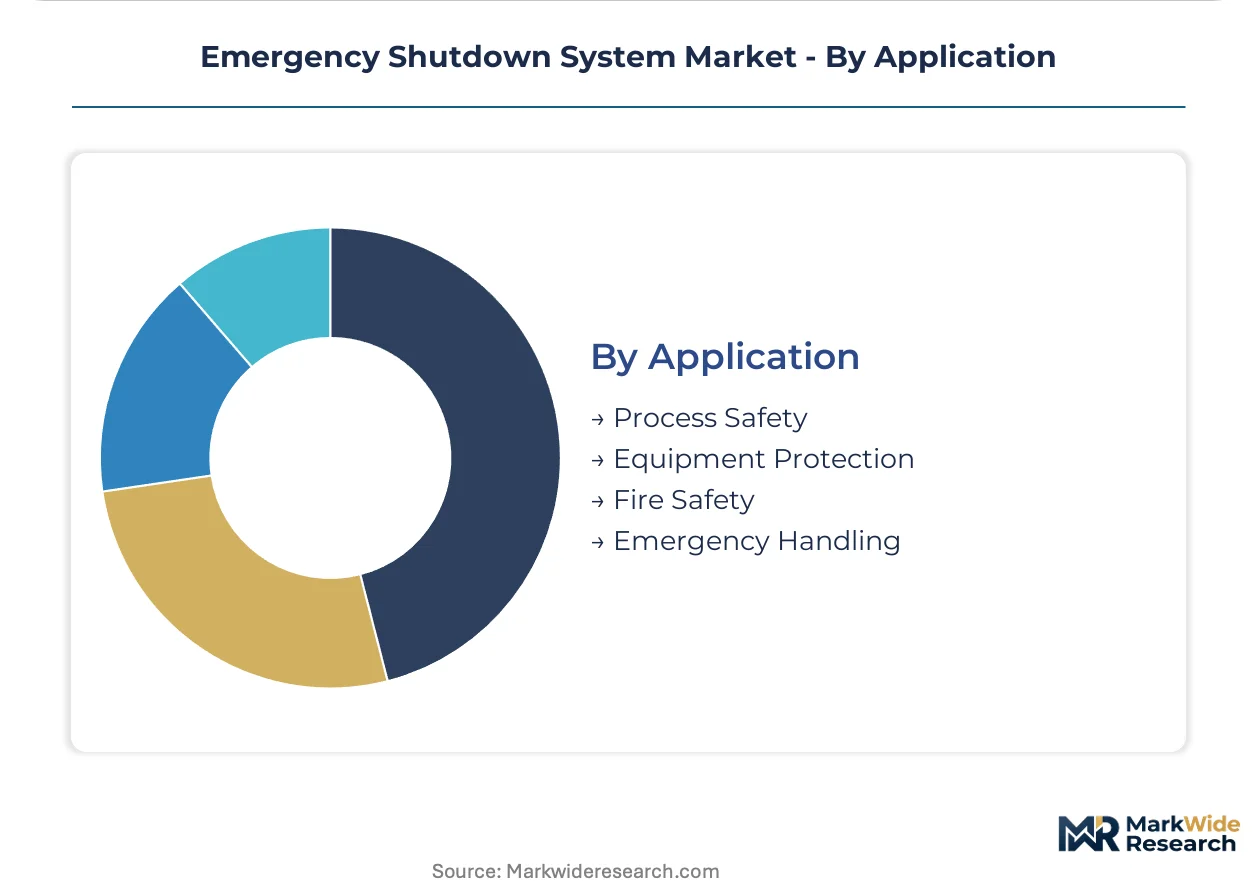
Application:
The application segmentation categorizes emergency shutdown systems based on their primary function within an industrial facility, highlighting the specific hazards they are designed to mitigate.
- Process Safety:These applications focus on preventing catastrophic events like explosions or toxic releases by bringing a process to a safe state during abnormal conditions. European chemical manufacturers prioritize these systems to comply with the Seveso III Directive and minimize environmental impact.
- Equipment Protection:ESD systems in this application safeguard critical machinery from damage due to overpressure, overheating, or other operational excursions, extending asset lifespan. This is particularly relevant for high-value turbines in power generation facilities.
- Fire Safety:These applications integrate ESD functions with fire detection systems, automatically initiating shutdowns and isolation procedures upon fire detection.
- Emergency Handling:Broader emergency response scenarios, including facility-wide evacuations or natural disaster preparedness, often incorporate ESD elements for controlled shutdowns.
Process Safety applications often integrate multiple ESD functions, while Emergency Handling requires broader system interoperability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Emergency Shutdown System market exhibits a distinct production-consumption divide, with advanced manufacturing hubs supplying sophisticated safety technologies to regions with extensive industrial infrastructure. Demand for certified systems is particularly high in energy-rich countries and those with stringent process safety regulations. This global dynamic drives investment in both new installations and upgrades across diverse geographies.
Saudi Arabia
Saudi Arabia's Vision 2030 initiatives drive significant investments in new petrochemical complexes and oil & gas facilities. The Saudi Food and Drug Authority (SFDA) enforces rigorous safety standards for industrial processes. Jubail Industrial City, a major hub, sees continuous demand for integrated safety systems in its expanding refining and chemical operations.
United States
United States demand for ESD systems stems from robust industrial activity across chemicals, refining, and power generation sectors. OSHA's Process Safety Management (PSM) standards mandate comprehensive safety instrumented systems for hazardous chemical facilities. The Gulf Coast region, encompassing states like Texas and Louisiana, remains a primary center for new system deployments and upgrades.
Germany
Germany, a leader in advanced manufacturing and chemical production, requires sophisticated ESD solutions to comply with European directives. The Seveso III Directive and mandatory CE marking ensure high safety integrity levels for industrial sites. The Rhine-Ruhr area, with its dense concentration of chemical parks, is a focal point for modern safety system implementations.
Norway
Offshore oil and gas operations in Norway necessitate highly resilient and certified emergency shutdown systems due to extreme environmental conditions. Petroleum Safety Authority Norway (PSA) regulations enforce stringent requirements for functional safety on platforms. The North Sea basin, a mature production area, drives continuous upgrades to enhance operational reliability and safety.
Brazil
Brazil's expanding deepwater oil and gas exploration and production activities generate substantial demand for specialized hydraulic ESD systems. The National Agency of Petroleum, Natural Gas and Biofuels (ANP) regulates safety and environmental protection in the energy sector. The Campos Basin off the coast of Rio de Janeiro concentrates investments in robust safety solutions for complex offshore installations.
Emergency Shutdown System Market Key Industry Players
Capital-heavy producers compete with asset-light designers for market share in the Emergency Shutdown System sector. The market exhibits a tiered structure, with established industrial automation giants alongside specialized safety technology providers. Strategic archetypes include integrated solution providers and niche component specialists, driving competitive moves such as portfolio diversification and strategic partnerships.
Integrated solution providers such as Siemens AG, a German AG, leverage extensive digital platforms to offer comprehensive lifecycle services. Emerson Electric Co., an American Inc., occupies a position as a specialist in integrated solutions for final control elements within challenging environments. HIMA Paul Hildebrandt GmbH, a German GmbH, exemplifies a focused safety technology provider, concentrating on high-integrity safety systems.
| Leading Market Players |
|---|
| ABB Ltd |
| Emerson Electric Co. |
| Honeywell International Inc. |
| Schneider Electric SE |
| General Electric Company |
| Siemens AG |
| Rockwell Automation Inc |
| Yokogawa Electric Corporation |
| HIMA Paul Hildebrandt GmbH |
| Others |
Cost & Logistics Intelligence
The Seveso III Directive and similar functional safety mandates gate both qualified supply and premium-tier pricing access for emergency shutdown systems. These regulations compel manufacturers to invest heavily in certification and compliance, directly influencing component availability and driving up costs for highly specialized, safety-critical hardware and software.
Pricing Analysis
Cost-down pressure on standard ESD components accelerates as asset owners seek to extend the lifecycle of legacy systems. The dominant pricing structure shifts from one-time transactional sales to project-based implementation with long-term service contracts. Price differentiation stems from Safety Integrity Level (SIL) certification, the level of integration with existing plant infrastructure, and comprehensive lifecycle support. The oil and gas sector, particularly for offshore installations, exhibits lower price sensitivity due to paramount uptime requirements, while manufacturing facilities often demonstrate higher cost sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with highly specialized component manufacturers for certified safety PLCs and diagnostic sensors. Geographic supply concentration for advanced ESD components centers on Germany, the United States, and Japan. Raw material dependencies include specialized semiconductors for controllers and high-grade alloys for critical valves. Certification bottlenecks represent a significant structural risk, delaying the introduction of innovative solutions. Distribution runs through a network of specialized system integrators and direct sales channels, especially for complex, large-scale projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a technology-transition phase, with software-defined safety logic steadily replacing traditional hardware-centric systems.
For Market Incumbents: Lock in existing customer bases by transitioning them to comprehensive lifecycle service contracts that include predictive maintenance and software updates. Leverage extensive field service networks and digital platforms, like Siemens' Totally Integrated Automation, to offer total cost of ownership advantages. Invest in R&D for IIoT integration and AI-driven diagnostics to counter emerging specialized software providers. Maintain robust certification pathways for all new components.
For New Entrants and Emerging Players: Begin with niche applications in emerging industrial processes, such as green hydrogen production or large-scale battery energy storage systems, where legacy systems are absent. Target brownfield facilities with cost-effective, modular software-based upgrade solutions that integrate with diverse installed bases. A strong go-to-market angle involves offering subscription-based safety logic management and specialized cybersecurity services for Safety Instrumented Systems.
For Investors and Strategic Acquirers: Widespread adoption of AI/ML in predictive maintenance for SIS is the leading indicator that the market is ready for a new wave of consolidation. The long-term viability remains strong, driven by continuous regulatory enforcement and the inherent need for process safety across industries over the next five to ten years. Target specialized software firms focusing on safety logic, cybersecurity for OT, or functional safety engineering consultancies with strong talent pools.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Lifecycle Service Models | Creates recurring revenue streams and deepens customer relationships beyond initial hardware sales. |
| Invest in Software-Defined Safety Logic | Decouples hardware and software refresh cycles, offering asset owners greater system flexibility. |
| Expand into New Energy Applications | Opens new vertical markets for ESD principles in sectors like green hydrogen production. |
| Strengthen Cybersecurity for SIS Offerings | Addresses a critical vulnerability for asset owners, establishing a high-value service niche. |
| Acquire Functional Safety Engineering Firms | Mitigates talent scarcity and enhances project execution capabilities for complex installations. |
Research Approach
Independent corroboration across primary interviews, industry standards, and government safety reports underwrites the qualitative findings and quantitative projections. The methodology combined in-depth discussions with plant operators, functional safety engineers, procurement leads, and regulatory compliance officers. Secondary validation drew from IEC 61511 guidelines, OSHA PSM standards, and Petroleum Safety Authority Norway regulations, ensuring a robust data foundation for bottom-up and top-down triangulation.
The analytical framework anchored the forecast window to comparable historical periods, assessing market drivers, restraints, and opportunities across the modeling period. Segmentation dimensions modeled included product type, technology, end user, application, and regional regulatory environment. Compound annual growth rates were derived from historical trends and projected market dynamics, with key inputs including regulatory enforcement levels and capital project spending in the global energy sectors.
Regulatory changes, global economic shifts, and technological breakthroughs in safety are the dominant revision risks for the market projections. Forecasts reflect assumptions documented through extensive research and analysis. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency and Disaster Management
Advanced Disaster Management Simulator Market
Emergency and Disaster Management
North America Homeland Security and Emergency Management Market
Emergency and Disaster Management
Emergency Shower and Eyewash Station Market
Emergency and Disaster Management
Earthquake Early Warning System Market
Emergency and Disaster Management
Intelligent Evacuation System Market
Emergency and Disaster Management
EHS Market
Emergency and Disaster Management
Incident and Emergency Management Market
Emergency and Disaster Management
Automatic Floodgate Market
Emergency and Disaster Management
Disaster Restoration Services Market
Emergency and Disaster Management
Lifeboat Market
Emergency and Disaster Management
Emergency Blankets Market
Emergency and Disaster Management
Emergency Location Transmitter Market
Emergency and Disaster Management
Cyber Crisis Management Market
Emergency and Disaster Management
Global Emergency Beacon Transmitter Market
Emergency and Disaster Management
Emergency Lighting Market
Emergency and Disaster Management
Crisis Emergency and Incident Management Platform Market