
 EHS Market | 2026-2036
EHS Market Size, Share, and Industry Trends Forecast 2026-2036
EHS Market Intelligence
EPA enforcement escalation is decoupling EHS software procurement from purely reactive compliance budgets. VelocityEHS leverages cloud-native architecture to capture mid-market manufacturing accounts that legacy systems cannot serve profitably. Sphera anchors its position through deep chemical sector specialization and integrated risk modeling capabilities. Cority Software Inc. competes by extending platform breadth across occupational health and environmental compliance modules.
Environmental Health and Safety encompasses software platforms, consulting services, and monitoring technologies that systematically identify, assess, and mitigate workplace hazards and environmental impacts. These systems integrate incident logging, chemical inventory tracking, air emissions calculations, and audit trail documentation to prevent regulatory violations and occupational injuries. Cloud-based deployment models are capturing the fastest expansion as energy and utilities firms abandon capital-intensive on-premises infrastructure for scalable SaaS architectures. Risk management solutions dominate current revenue pools, though incident management modules are gaining traction in construction and chemicals where real-time field reporting reduces liability exposure.
OSHA, EPA, and ISO 45001 collectively reshape product requirements by mandating auditable documentation, predictive hazard analysis, and standardized occupational health protocols across operating jurisdictions. FDA overlap in pharmaceuticals and food manufacturing adds Good Manufacturing Practice alignment burdens that EHS platforms must address. Stakeholders should monitor how AI-driven predictive safety analytics reconfigures competitive advantage between established compliance suites and emerging specialized vendors.
Market Dynamics
Cloud-native SaaS architectures are compressing deployment timelines from months to weeks, forcing legacy on-premises EHS vendors into defensive platform rebuilds or niche retreat. This infrastructure shift simultaneously expands addressable markets to mid-tier manufacturers previously priced out of enterprise compliance systems.
Growth Catalysts
- OSHA Process Safety Management:Chemical manufacturers face intensified audit scrutiny around hazardous process documentation, driving automated workflow adoption for incident logging and corrective action tracking.
- ISO 45001 harmonization:Multinational industrial firms standardize occupational health protocols across facilities, creating demand for unified platforms that span air quality monitoring, ergonomic assessments, and training certification.
- Predictive analytics integration:Energy sector operators deploy AI-driven hazard forecasting to reduce unplanned shutdowns and workers' compensation exposure in high-risk maintenance environments.
Market Restraints
- Data sovereignty fragmentation:Cross-border EHS data residency requirements in Germany, China, and Saudi Arabia force redundant infrastructure investments that erode SaaS margin advantages.
- Specialized systems lock-in:Chemical facilities retain legacy chemical inventory databases with decade-long amortization cycles, delaying full-platform consolidation.
- Skills scarcity:Industrial hygienists with both domain expertise and cloud platform administration capabilities command compensation premiums that inflate implementation costs.
Strategic Opportunities
- Construction sector digitization:Real-time field reporting via mobile-native platforms addresses chronic underreporting of near-miss incidents on distributed job sites.
- EU CSRD alignment:Sustainability reporting mandates create new revenue streams for EHS vendors that integrate environmental performance metrics with financial disclosure workflows.
- Wearable sensor convergence:Biometric monitoring devices and location-aware safety badges merge with incident management systems to enable proactive intervention before injury occurrence.
Industry Challenges
- Legacy system integration:Manufacturing plants with 1990s-era SCADA infrastructure struggle to extract machine safety data into modern EHS platforms without expensive middleware development.
- Certification timeline compression:ISO 45001 migration deadlines force parallel audit preparation across multiple facilities, straining internal EHS team capacity and external consultant availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EHS Market |
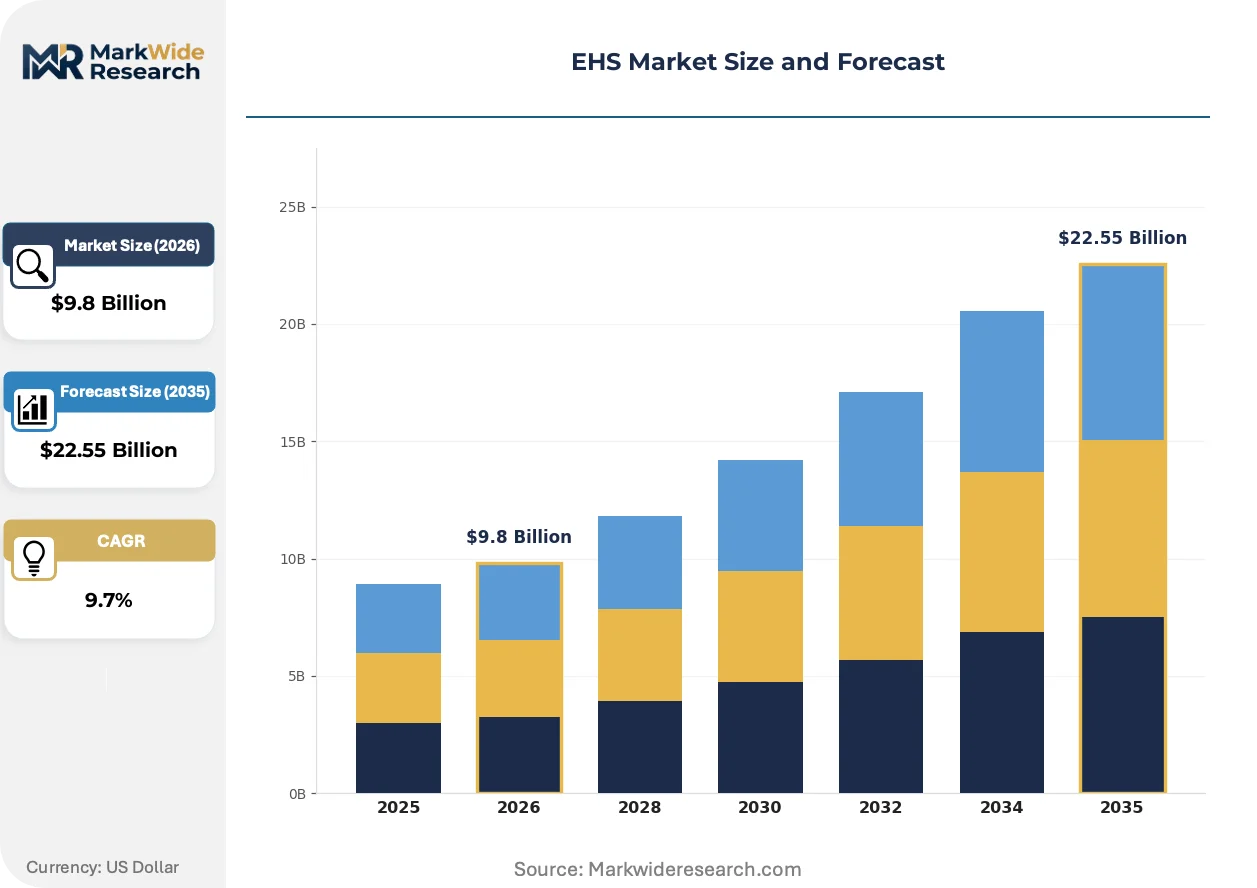
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $22.55 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Risk Management, Compliance Management, Incident Management, Audit Management, Training Management Deployment Model: On-Premises, Cloud-Based, Hybrid, SaaS, Hosted End User Industry: Manufacturing, Construction, Pharmaceuticals, Energy & Utilities, Chemicals Application Area: Workplace Safety, Environmental Compliance, Occupational Health, Waste Management, Incident Reporting |
| Companies Covered | Cority Software Inc., Benchmark ESG, VelocityEHS, Quentic, Intertek, Wolters Kluwer, Sphera, Enablon, Intelex Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EHS Market Strategic Shifts & Innovations
Artificial intelligence and edge computing are reconfiguring how industrial safety data flows from field sensors to executive dashboards, collapsing the latency between hazard detection and organizational response. These capabilities are shifting competitive advantage toward vendors with native data science infrastructure rather than compliance checklist features.
Computer vision systems trained on facility video feeds are electrifying automated hazard recognition in heavy manufacturing environments. Automotive assembly plants in Michigan and Tennessee deploy these tools to flag PPE violations and machinery proximity breaches in real time. The technology compresses incident investigation cycles from weeks to hours by auto-generating timestamped evidence packages.
REACH authorization expansion across the European Union is forcing chemical manufacturers to reconstruct supply chain substance tracking. ECHA's candidate list updates trigger mandatory downstream communication obligations that legacy spreadsheet systems cannot satisfy. Specialty chemical producers in Germany and the Netherlands are prioritizing platforms with automated SVHC screening and SCIP database integration.
Subscription-based pricing for predictive safety modules is displacing perpetual license models in North American oil and gas operations. Midstream pipeline operators now procure fatigue management and vehicle telematics as bundled monthly services rather than capital projects. This consumption pattern concentrates vendor selection authority with regional operations managers rather than centralized IT procurement functions.
EHS Market Segmentation
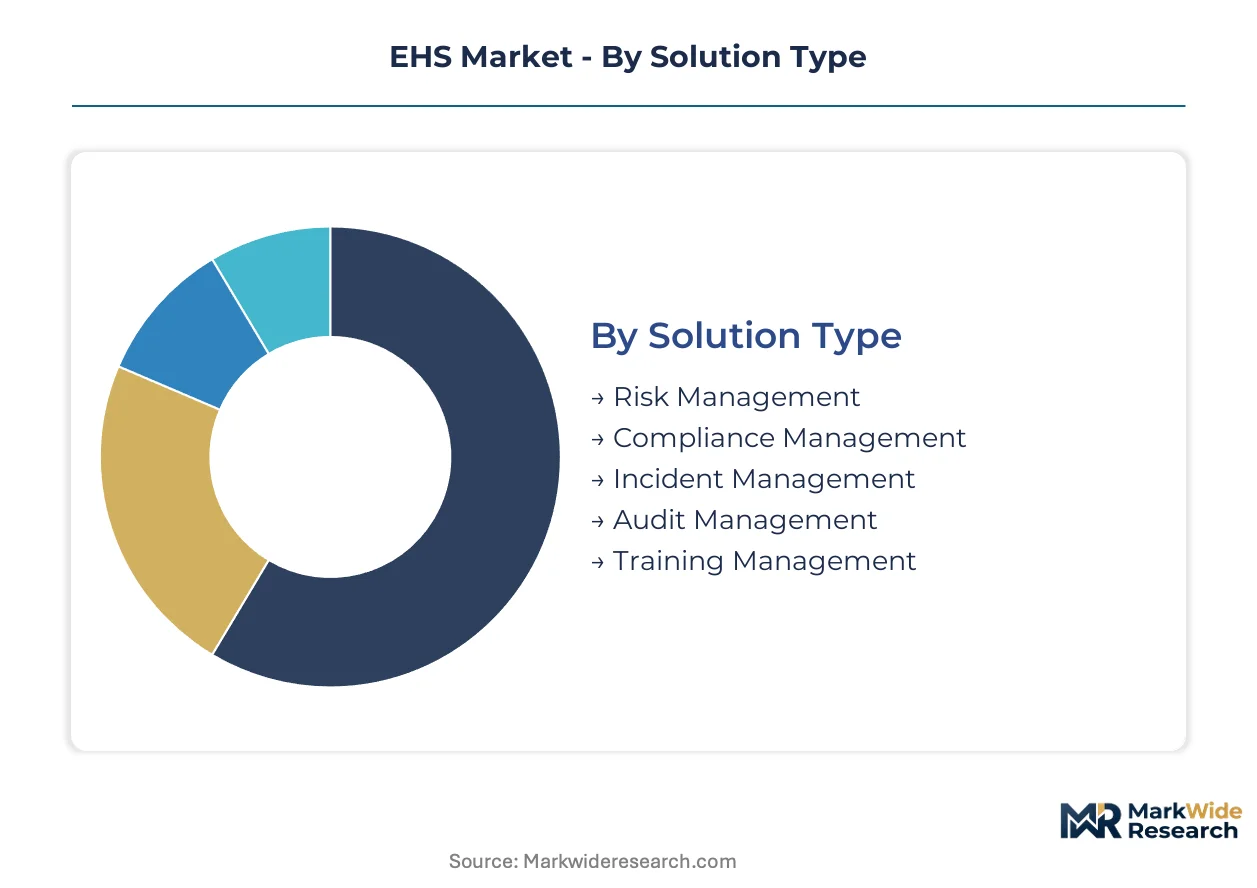
EHS procurement decisions hinge on regulatory exposure severity and operational complexity. Buyers prioritize solution architectures that compress audit preparation cycles and unify fragmented compliance workflows across multinational facility footprints.
Solution Type:
Procurement authority concentrates with risk officers who mandate predictive capabilities over retrospective documentation.
- Risk Management:Platforms integrate quantitative hazard scoring with scenario modeling for process safety. Chemical manufacturers in the United States deploy these systems to satisfy OSHA PSM requirements for facility siting and consequence analysis.
- Compliance Management:Automated regulatory tracking maps jurisdiction-specific obligations to internal controls. Energy firms operating across EPA, state environmental agencies, and ISO 45001 jurisdictions consolidate audit evidence through unified dashboards.
- Incident Management:Real-time field reporting with mobile-native interfaces accelerates near-miss capture.
- Audit Management:Digital trail documentation satisfies ISO certification body evidence requirements.
- Training Management:Competency tracking aligns operator certification with machinery access permissions.
Risk Management leads on scale; Incident Management leads on momentum.
Deployment Model:
Total cost of ownership calculations now favor subscription economics over capital amortization schedules.
- Cloud-Based:Scalable infrastructure eliminates server maintenance burdens and accelerates multi-site rollouts. Mid-market manufacturers previously excluded from enterprise EHS suites access predictive analytics through consumption-based pricing.
- SaaS:Vendor-managed updates ensure continuous regulatory content refresh without client IT intervention. Construction contractors with distributed project portfolios prioritize browser-native access over VPN-dependent architectures.
- On-Premises:Air-gapped installations persist in defense and critical infrastructure sectors.
- Hybrid:Sensitive incident data remains local while analytics processing shifts to cloud.
- Hosted:Dedicated single-tenant environments address data residency constraints in Germany and China.
SaaS captures the steepest expansion trajectory; On-Premises retains highest retention among legacy accounts.
End User Industry:
Sector-specific regulatory intensity determines module prioritization and implementation sequencing.
- Chemicals:Process safety management mandates drive automated workflow adoption for hazardous chemical inventory tracking and MOC documentation. EPA enforcement escalation and OSHA NEP inspections create sustained procurement urgency.
- Energy & Utilities:Predictive maintenance integration with safety systems reduces unplanned outage exposure. Pipeline operators deploy fatigue management and vehicle telematics as bundled operational services.
- Manufacturing:Automotive and electronics producers prioritize ergonomic assessment modules.
- Construction:Mobile-native platforms address chronic underreporting through simplified field interfaces.
- Pharmaceuticals:FDA overlap requires GMP alignment alongside occupational health protocols.
Chemicals dominates current revenue; Construction is climbing the fastest.
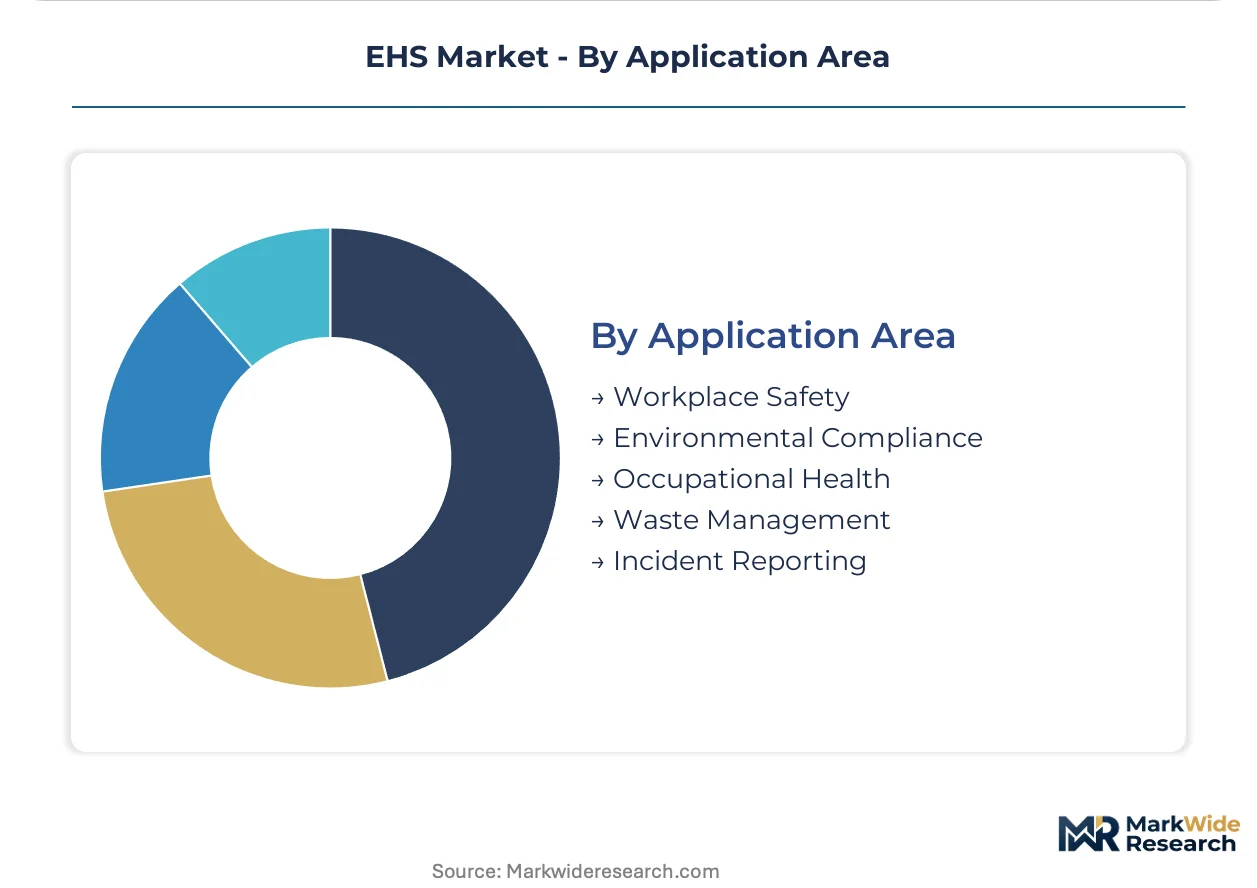
Application Area:
Functional module selection follows incident frequency patterns and regulatory penalty exposure.
- Environmental Compliance:Air emissions calculation engines and waste manifest tracking satisfy EPA Clean Air Act and RCRA obligations. REACH authorization expansion in Europe forces supply chain substance reconstruction with automated SVHC screening.
- Workplace Safety:PPE compliance monitoring and lockout/tagout procedure digitization reduce lost-time injury rates. Computer vision deployment in heavy manufacturing automates hazard recognition from facility video feeds.
- Occupational Health:Medical surveillance scheduling and exposure limit tracking protect against cumulative hazard liability.
- Waste Management:Cradle-to-grave tracking satisfies generator responsibility mandates.
- Incident Reporting:Root cause analysis templates accelerate corrective action closure.
Environmental Compliance leads on scale; Workplace Safety leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EHS software industry traces its commercial origins to United States industrial safety consultancies that digitized OSHA compliance workflows during the 1990s. European chemical hubs subsequently adopted these platforms to manage REACH substance tracking. Cloud delivery models now enable mid-market manufacturers across multiple geographies to access enterprise-grade compliance infrastructure.
United States
EPA enforcement escalation and OSHA National Emphasis Program inspections drive procurement urgency among chemical manufacturers and energy operators. The Inflation Reduction Act channels funding toward environmental monitoring infrastructure at industrial facilities. Houston's petrochemical corridor and Louisiana's process manufacturing clusters deploy predictive analytics platforms to satisfy PSM documentation mandates.
Germany
REACH authorization expansion and ECHA candidate list updates force specialty chemical producers to reconstruct supply chain substance tracking. The country's dual carbon goals accelerate emissions calculation engine adoption across industrial Mittelstand firms. BASF's Ludwigshafen complex and Bayer's Leverkusen operations anchor demand for automated SVHC screening and SCIP database integration.
China
MEE enforcement intensification and GB standard harmonization create compliance spending among state-owned energy and chemical enterprises. The country's dual carbon targets mandate air emissions monitoring at manufacturing facilities. Shanghai's Yangtze River Delta chemical parks and Sinopec's Beijing headquarters drive platform procurement for multi-site environmental data consolidation.
United Kingdom
Post-Brexit regulatory divergence from EU REACH requires reconstructed chemical inventory systems for cross-border trade. HSE workplace safety mandates sustain occupational health software demand. Scotland's North Sea oil operations and Teesside's chemical manufacturing cluster prioritize incident management modules for offshore and process safety applications.
India
Factory Act modernization and state-level pollution control board digitization create compliance software opportunities. The PLI scheme for chemicals and pharmaceuticals channels investment toward automated environmental reporting. Gujarat's Dahej PCPIR and Maharashtra's Taloja industrial estate anchor EHS platform deployment among export-oriented manufacturers.
EHS Market Key Industry Players
The competitive structure tilts toward cloud-native specialists with vertical chemical sector expertise. Market concentration remains moderate, with established compliance suites defending against agile SaaS entrants through platform breadth expansion. Three archetypes dominate: legacy on-premises vendors executing defensive cloud migrations, pure-play SaaS providers capturing mid-market share, and diversified risk consultancies bundling software with advisory services. Competitive dynamics center on M&A activity consolidating point solutions into unified platforms and strategic partnerships integrating wearable sensor data into incident management workflows.
Within the cloud-native tier, VelocityEHS exemplifies the mid-market manufacturing focus that legacy systems cannot serve profitably. Sphera occupies a position representing deep chemical sector specialization and integrated risk modeling capabilities. Cority Software Inc. anchors the platform breadth archetype, extending across occupational health and environmental compliance modules to compete against point solutions.
| Leading Market Players |
|---|
| Cority Software Inc. |
| Benchmark ESG |
| VelocityEHS |
| Quentic |
| Intertek |
| Wolters Kluwer |
| Sphera |
| Enablon |
| Intelex Technologies |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up software specialists now control the dominant EHS platform portfolios, compressing vendor margins through aggressive cross-selling while simultaneously tightening pricing discipline across mid-market accounts. This ownership structure concentrates supply-side negotiating power with three buyout-backed entities that dictate SaaS pricing floors and cloud infrastructure sourcing terms.
Pricing Analysis
Consumption-based subscription tiers stratify across enterprise, professional, and essential levels, with differentiation anchored in predictive analytics depth and multi-site deployment scale. ISO 45001 certification alignment commands premium positioning in chemical and energy verticals where audit-ready documentation justifies higher per-seat rates. Pricing pressure stems from mid-market manufacturers demanding modular procurement rather than bundled suites, forcing vendors to unbundle risk management from incident logging. Construction contractors exhibit highest price sensitivity due to project-based budgeting, while pharmaceutical firms show lowest sensitivity given FDA compliance penalty exposure.
Supply Chain Analysis
Certification gating through ISO 27001 and SOC 2 Type II compliance restricts viable cloud infrastructure partners to hyperscale providers in the United States, Ireland, and Singapore. Platform development draws from specialized machine-learning engineering talent pools concentrated in Bangalore, Berlin, and Boston, with user experience design increasingly sourced from Eastern European studios. Single-source vulnerability concentrates in AI model training data licensed from exclusive industrial safety incident repositories. Distribution runs through direct enterprise sales teams for accounts above five hundred seats, with value-added resellers covering mid-market manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EHS software margins are expanding through cloud infrastructure cost compression and predictive analytics premium-tier adoption, as buyers prioritize outcome-based pricing over perpetual licenses.
For Market Incumbents: Deploy API-first architecture strategies to defend against point-solution disaggregation, integrating wearable sensor data streams and computer vision feeds into unified incident management workflows. Consolidate position through targeted acquisition of construction-focused mobile-native platforms that threaten mid-market share. ISO 45001 content refresh velocity serves as the critical retention lever against cloud-native entrants. For New Entrants and Emerging Players: Begin with construction sector field-reporting modules where chronic underreporting creates immediate ROI visibility and limited incumbent specialization. Target European Mittelstand manufacturers underserved by US-centric compliance content, leveraging automated REACH SVHC screening as differentiation. Partner with regional EHS consultancies for implementation credibility rather than building direct sales infrastructure. For Investors and Strategic Acquirers: Private-equity firms with industrial software portfolios are the most active acquirer in this space, seeking tuck-in platforms that extend vertical coverage or geographic data residency capabilities. Long-term viability hinges on AI-driven predictive safety analytics ownership rather than compliance checklist features. Watch for OSHA National Emphasis Program expansion into new sectors as inflection signal for procurement urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies incident management with predictive risk modeling for OSHA PSM compliance. |
| Acquisition of Specialist Firm | Adds construction mobile-native capabilities to capture distributed job site reporting. |
| Strategic Partnership | Integrates wearable biometric sensors for proactive intervention before injury occurrence. |
| Geographic Expansion | Establishes data residency infrastructure for Germany and China sovereignty requirements. |
| Product Launch | Introduces EU CSRD-aligned sustainability disclosure modules for integrated reporting. |
Research Approach
Direct dialogue with EHS directors, plant safety managers, cloud procurement officers, and regulatory compliance leads grounds qualitative findings in operational reality. Secondary validation draws from OSHA enforcement databases, EPA violation records, ISO certification registries, and vendor SEC filings. Bottom-up sizing of module-level deployments triangulates against top-down industry technology spending estimates across the analysis window.
Segmented outputs across deployment model, end-user industry, solution type, and regional regulatory cluster inform the projection framework. CAGRs derive from fitted growth curves calibrated to historical compliance spending elasticity and cloud migration velocity. Forecast inputs incorporate OSHA inspection frequency trends and REACH authorization timeline acceleration.
Several conditions sit outside the modeled scope, including sovereign data localization mandates beyond Germany and China, and AI liability framework shifts. Forecasts reflect documented assumptions around regulatory enforcement continuity. A model refresh is warranted upon material change in EPA penalty escalation patterns or ISO 45001 certification deadline extensions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency and Disaster Management
Intelligent Evacuation System Market
Emergency and Disaster Management
Hazard Control Market
Emergency and Disaster Management
North America Emergency Shower and Eye Wash Station Market
Emergency and Disaster Management
North America Homeland Security and Emergency Management Market
Emergency and Disaster Management
Global Emergency Medical Service (EMS) Products Market
Emergency and Disaster Management
Asia-Pacific Process Safety Services Market
Emergency and Disaster Management
Homeland Security and Emergency Management Market
Emergency and Disaster Management
Emergency Shutdown System Market
Emergency and Disaster Management
Emergency and Disaster Response Market
Emergency and Disaster Management
Survival Tools Market
Emergency and Disaster Management
Global Emergency Beacon Transmitter Market
Emergency and Disaster Management
Advanced Disaster Management Simulator Market
Emergency and Disaster Management
Emergency Location Transmitter Market
Emergency and Disaster Management
Automatic Floodgate Market
Emergency and Disaster Management
Crisis Emergency and Incident Management Platform Market
Emergency and Disaster Management
Emergency Lighting Market