
 Global Emergency Beacon Transmitter Market | 2026-2036
Global Emergency Beacon Transmitter Market Size, Share, and Industry Trends Forecast 2026-2036
Global Emergency Beacon Transmitter Market Intelligence
Southeast Asian manufacturing capacity is tilting toward satellite-compatible beacon assembly as regional electronics clusters mature. ACR Electronics leverages vertical integration in RF module production to sustain margin control across its aviation and maritime lines. McMurdo Group anchors its position through Cospas-Sarsat protocol certification breadth, while Orolia SA specializes in multi-constellation GPS timing integration for defense-grade applications.
An emergency beacon transmitter is a self-contained radio device that transmits distress signals on standardized frequencies, typically 406 MHz for satellite detection and 121.5 MHz for homing, incorporating GNSS coordinates and vessel or personal identification data. Its primary commercial purpose is to alert search-and-rescue coordination centers and enable precise geolocation during aviation, maritime, or remote-terrain emergencies. Maritime emergency beacons command the largest installed base due to SOLAS-mandated carriage on commercial vessels, while personal locator beacons represent the fastest-expanding category as backcountry recreation participation rises and unit costs fall. GPS-enabled technology segments capture premium positioning through dual-frequency reception, whereas RF-only configurations occupy economy tiers in legacy aviation retrofit markets.
FCC Part 87 and FAA Technical Standard Orders govern aviation beacon certification in the United States, while ETSI standards and the EU Radio Equipment Directive shape European market access and interoperability requirements. Cospas-Sarsat Secretariat specifications for 406 MHz messaging protocols create a de facto global compliance floor that manufacturers must meet for international distribution. Stakeholders should monitor frequency re-farming decisions by national spectrum regulators and the pace of MEOSAR satellite constellation deployment, as these will determine next-generation hardware refresh cycles and retrofit obligations across installed fleets.
Market Dynamics
MEOSAR satellite constellation deployment is compressing hardware refresh cycles across aviation and maritime installed bases, forcing manufacturers to accelerate 406 MHz beacon redesigns for dual-compatibility with legacy LEOSAR and next-generation mid-Earth orbit networks.
Growth Catalysts
- SOLAS Mandate Expansion:Commercial shipping fleets above 300 gross tonnage must carry satellite EPIRBs under International Maritime Organization protocols, sustaining replacement demand across Greek, Japanese, and Norwegian vessel registries.
- Return-to-Flight Aviation Activity:Commercial air transport recovery is accelerating 121.5/406 MHz ELT retrofit programs for narrow-body fleets operating under FAA Technical Standard Order C126.
- Remote Worker Safety Legislation:Australia's Work Health and Safety regulations now mandate lone-worker distress signaling for offshore energy and mining contractors, expanding PLB procurement beyond recreational users.
Market Restraints
- Rare Earth Magnet Supply Concentration:Neodymium-iron-boron magnet sourcing for RF oscillator stabilization remains concentrated in Chinese processing facilities, exposing margin volatility to export quota adjustments.
- Cospas-Sarsat Certification Backlogs:Type approval queues at the Secretariat's beacon verification facility extend hardware launch timelines by 8-14 months for new 406 MHz protocol implementations.
- Smartphone Satellite Connectivity:Direct-to-satellite messaging in Apple Emergency SOS and Android Satellite SOS is creating functional substitution pressure on recreational PLB categories in North American and European backcountry markets.
Strategic Opportunities
- Indonesian Archipelago Deployment:The country's 17,000-island geography and patchy terrestrial coverage create structural demand for fishing fleet and inter-island ferry distress beacons under national maritime safety directives.
- Multi-Constellation GNSS Integration:Beacons incorporating Galileo, BeiDou, and GLONASS alongside GPS are capturing premium positioning in defense and government search-and-rescue tenders requiring redundancy.
- Subscription-Based Monitoring Services:406 MHz message relay providers are unbundling hardware from annual service contracts, creating recurring revenue streams through private rescue coordination center memberships.
Industry Challenges
- RF Engineering Talent Scarcity:Design of 406 MHz power amplifiers with MEOSAR burst repetition timing requires specialized microwave expertise concentrated in defense-aerospace labor pools.
- Legacy Fleet Integration Complexity:Maritime operators face mechanical and electrical incompatibility when retrofitting second-generation beacons onto 1990s-era vessel bridge architectures.
- Battery Chemistry Certification Delays:Lithium-sulfur chloride primary cells must pass UN 38.3 transport testing and Cospas-Sarsat thermal runaway protocols, extending new product qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Emergency Beacon Transmitter Market |
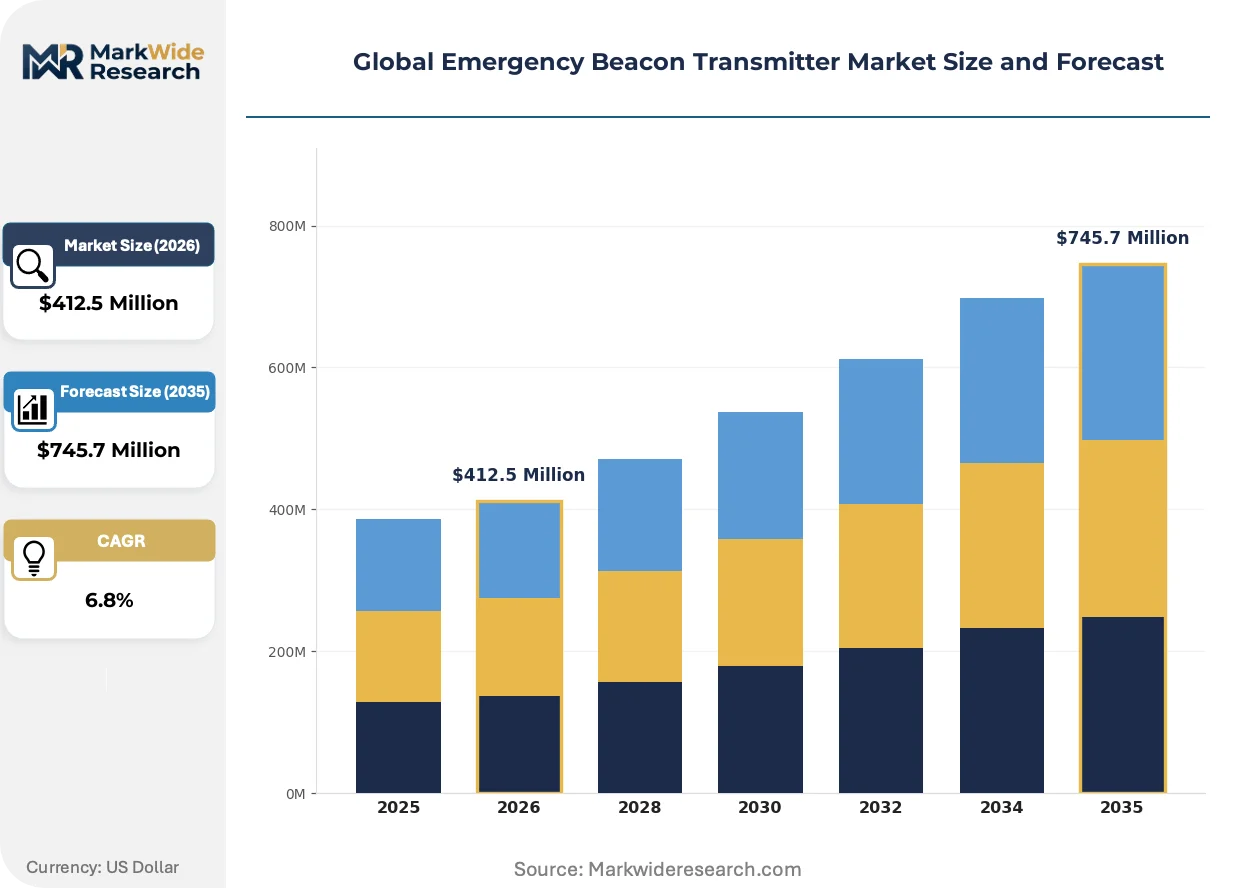
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Personal Locator Beacons, Aviation Emergency Beacons, Maritime Emergency Beacons, Satellite Emergency Beacons Technology: GPS, RF, Satellite, Cellular, Bluetooth Application: Aviation, Maritime, Outdoor Recreation, Search and Rescue, Mining End User: Emergency Response Teams, Outdoor Enthusiasts, Commercial Operators, Government Agencies |
| Companies Covered | Emergency Beacon Corporation, ACK Technologies, Inc., ACR Electronics, Inc., Orolia SA, Honeywell International, Inc., McMurdo Group, Cobham Plc, Ocean Signal, HR Smith Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Emergency Beacon Transmitter Market Strategic Shifts & Innovations
Beacon architecture is converging around software-defined radio platforms that enable post-manufacture protocol updates, reducing hardware obsolescence risk as Cospas-Sarsat messaging standards evolve.
Return-link service capability is collapsing the distinction between one-way distress alerting and two-way rescue coordination. Second-generation MEOSAR payloads enable confirmation messages back to activated beacons, and aviation operators are prioritizing this function for remote-area flight operations. The technology is collapsing procurement evaluation criteria toward messaging protocol flexibility rather than static hardware specifications.
ETSI EN 302 152-1 revision 2.1.1 is mandating enhanced 406 MHz waveform discrimination and reduced spurious emissions for European market access. Manufacturers must redesign RF front-ends to meet tighter adjacent-channel power limits, with commercial shipping and fishing vessel segments facing mandatory retrofit deadlines under EU Radio Equipment Directive compliance windows. German and Dutch maritime regulators are enforcing phased transition timelines that accelerate fleet replacement rates.
Aviation maintenance, repair, and overhaul providers are unbundling ELT inspection from scheduled airframe checks. Airlines now source standalone 121.5/406 MHz beacon testing through specialized avionics shops rather than bundled airframe contracts, compressing service intervals and fragmenting supplier relationships. This pattern is most visible in US Part 135 commuter operations and European business jet fleets seeking operational flexibility.
Global Emergency Beacon Transmitter Market Segmentation
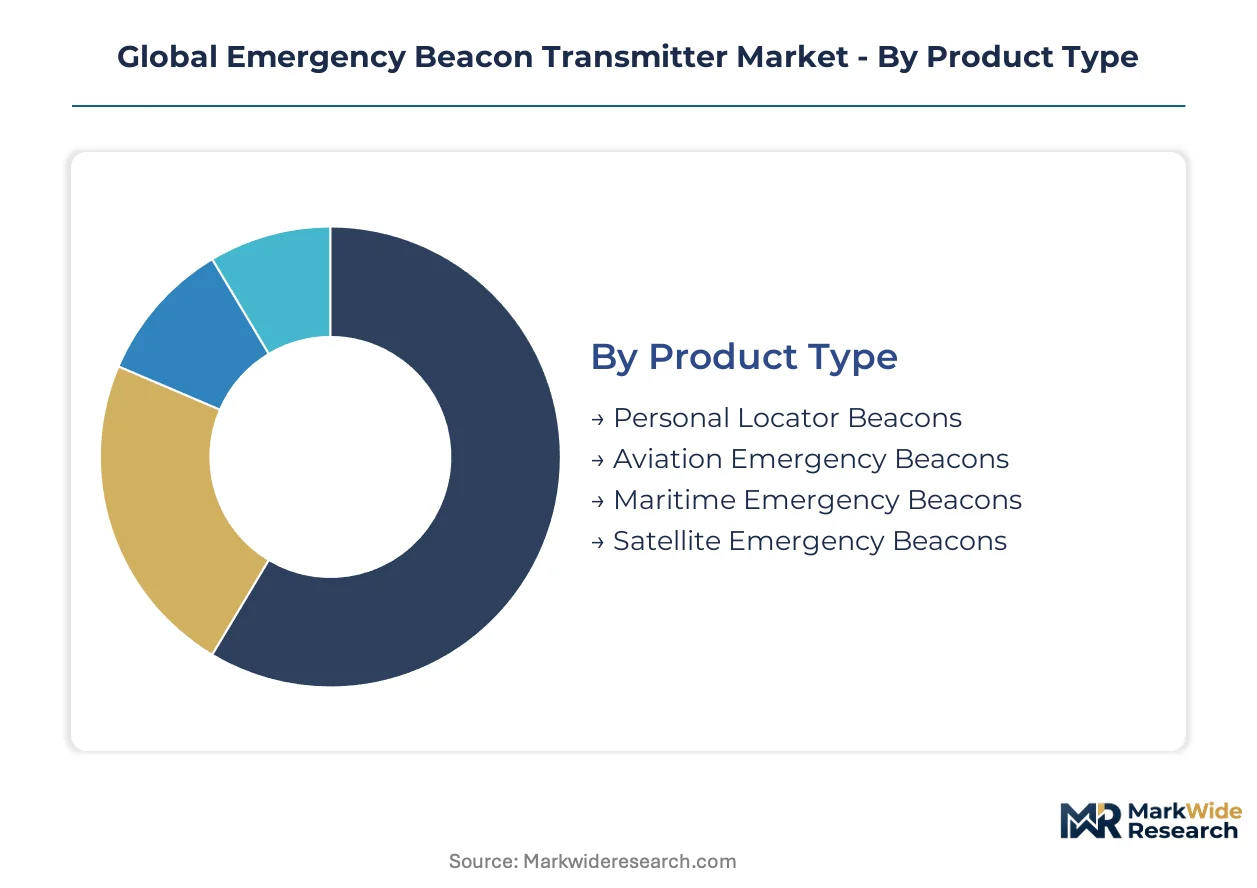
Beacon transmitter procurement patterns diverge sharply across user profiles, with maritime operators prioritizing SOLAS-compliant durability while outdoor enthusiasts trade battery longevity for weight reduction. After-sales service intensity varies from mandatory annual inspections for aviation ELTs to essentially zero-touch replacement cycles for recreational PLBs.
Product Type:
Service intensity maps directly to regulatory inspection schedules, with aviation and maritime segments demanding recurring certification maintenance while personal units operate on replace-when-triggered economics.
- Maritime Emergency Beacons:SOLAS-mandated 406 MHz EPIRBs with hydrostatic release mechanisms and 48-hour minimum transmission endurance. Greek, Japanese, and Norwegian vessel registries sustain replacement demand through mandatory carriage requirements on commercial fleets above 300 gross tonnage.
- Personal Locator Beacons:Compact 406 MHz units with integrated GNSS and 24-hour operational life, designed for manual activation in backcountry environments. Australia's Work Health and Safety regulations now mandate lone-worker distress signaling for offshore energy contractors, expanding procurement beyond recreational users into commercial industrial safety.
- Aviation Emergency Beacons:Crash-hardened 121.5/406 MHz ELTs meeting FAA Technical Standard Order C126 for automatic activation on impact.
- Satellite Emergency Beacons:Dedicated Cospas-Sarsat messaging hardware with return-link service capability for two-way rescue coordination.
Maritime Emergency Beacons holds the largest share; momentum sits with Personal Locator Beacons.
Technology:
Cost tier stratification separates premium multi-constellation GNSS integration from economy RF-only configurations in legacy retrofit markets.
- GPS:Dual-frequency L1/L5 reception enabling 3-meter position accuracy for MEOSAR constellation compatibility. Defense and government search-and-rescue tenders in Germany and France require Galileo, BeiDou, and GLONASS redundancy alongside GPS.
- Satellite:Dedicated 406 MHz burst transmission with LEOSAR/MEOSAR dual-compatibility and return-link message reception. Return-link service capability is collapsing procurement evaluation criteria toward messaging protocol flexibility rather than static hardware specifications.
- RF:Legacy 121.5 MHz homing signal transmission for final approach guidance without position encoding.
- Cellular:Network-dependent alerting leveraging terrestrial infrastructure where coverage exists.
- Bluetooth:Short-range pairing with smartphones for configuration and status monitoring.
GPS-enabled segments command premium positioning; Satellite technology is climbing the fastest as MEOSAR deployment accelerates hardware refresh cycles.
Application:
Volume concentration aligns with regulatory mandate density, creating stark differences between compulsory carriage segments and discretionary purchase categories.
- Maritime:Commercial shipping, fishing fleets, and inter-island ferry operations under SOLAS and national maritime safety directives. Indonesia's 17,000-island geography and patchy terrestrial coverage create structural demand for fishing fleet distress beacons.
- Aviation:Commercial air transport, business jets, and Part 135 commuter operations requiring ELT retrofit programs. US Part 135 operators and European business jet fleets now source standalone beacon testing through specialized avionics shops rather than bundled airframe contracts.
- Outdoor Recreation:Backcountry hiking, mountaineering, and remote wilderness access where smartphone satellite connectivity creates functional substitution pressure.
- Search and Rescue:Professional coordination center equipment and volunteer response team mobilization systems.
- Mining:Underground and open-pit operations with lone-worker safety protocols and blast-zone evacuation requirements.
Maritime application holds the largest share; momentum sits with Outdoor Recreation as unit costs fall and participation rises.
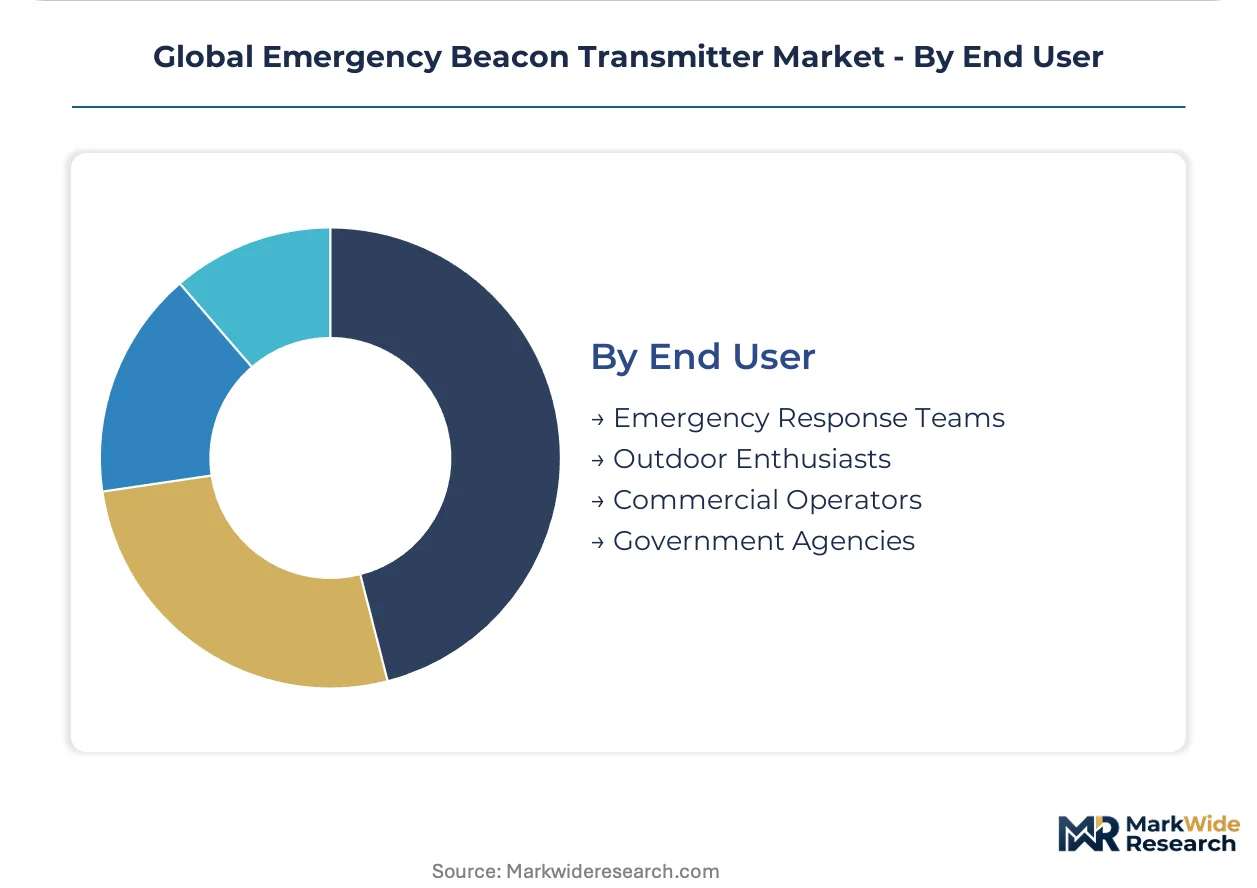
End User:
Customer type determines procurement channel and pricing power, with government tenders demanding multi-constellation redundancy while commercial operators prioritize total cost of ownership.
- Government Agencies:Coast guard, military search-and-rescue, and civil defense organizations requiring defense-grade multi-constellation GNSS timing integration. Singapore and surrounding Southeast Asian archipelago markets concentrate demand for coastal economies with heavy vessel traffic.
- Commercial Operators:Shipping companies, airlines, and mining contractors managing fleet-scale beacon deployment with subscription-based monitoring service contracts. 406 MHz message relay providers are unbundling hardware from annual service contracts, creating recurring revenue streams through private rescue coordination center memberships.
- Emergency Response Teams:Professional and volunteer search-and-rescue organizations with rapid-deployment requirements.
- Outdoor Enthusiasts:Individual recreational users purchasing through retail channels with minimal technical support expectations.
Government Agencies holds the largest share; Commercial Operators represent the steepest expansion trajectory as service unbundling proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA Technical Standard Orders and FCC Part 87 regulations anchor the United States as the dominant geography for aviation beacon certification and maritime safety equipment deployment. Commercial shipping registries in Greece, Japan, and Norway drive replacement cycles under SOLAS mandates. Southeast Asian electronics clusters are maturing toward satellite-compatible beacon assembly.
United States
Commercial air transport recovery accelerates 121.5/406 MHz ELT retrofit programs for narrow-body fleets. FAA Technical Standard Order C126 governs automatic activation requirements for crash-hardened aviation emergency beacons. Dallas-Fort Worth and Seattle-Tacoma aerospace corridors concentrate avionics maintenance, repair, and overhaul providers now unbundling ELT inspection from scheduled airframe checks.
Germany
German maritime regulators enforce phased transition timelines under EU Radio Equipment Directive compliance windows for enhanced 406 MHz waveform discrimination. ETSI EN 302 152-1 revision 2.1.1 mandates reduced spurious emissions for European market access. Hamburg and Bremen port clusters drive commercial shipping fleet replacement demand for SOLAS-mandated EPIRBs above 300 gross tonnage.
Japan
Japanese vessel registries sustain replacement demand for satellite distress signaling equipment on commercial fleets. METI standards shape domestic certification thresholds for Cospas-Sarsat compatibility. Yokohama and Nagoya maritime industrial zones concentrate hydrostatic release mechanism manufacturing and 48-hour transmission endurance testing facilities.
Singapore
Coastal economies with heavy vessel traffic concentrate procurement for government search-and-rescue coordination centers. National maritime safety directives expand mandatory carriage requirements across inter-island ferry operations. Jurong electronics clusters tilt toward satellite-compatible beacon assembly as regional RF module production matures.
Indonesia
The archipelago's 17,000-island geography and patchy terrestrial coverage create structural demand for fishing fleet distress beacons. National maritime safety directives expand procurement beyond commercial shipping into artisanal vessel segments. Surabaya and Makassar port zones anchor inter-island ferry retrofit programs under SOLAS-aligned national regulations.
Global Emergency Beacon Transmitter Market Key Industry Players
Defense-aerospace conglomerates and specialized maritime safety fabricators split the market across certification-intensive segments. The vendor base concentrates around Cospas-Sarsat protocol expertise and multi-constellation GNSS timing integration. Three archetypes dominate: vertically integrated RF module producers, protocol certification specialists, and multi-constellation defense-grade integrators. Competitive moves center on backward integration into oscillator stabilization components and geographic expansion into Indonesian and Vietnamese fishing fleet markets.
Among United States-based defense-aerospace conglomerates, Honeywell International, Inc. exemplifies scale-driven certification breadth across aviation and maritime lines. ACR Electronics, Inc. anchors the vertically integrated tier through captive RF module production. McMurdo Group occupies a position within the protocol certification specialist archetype, while Orolia SA represents multi-constellation GPS timing integration for defense-grade applications.
| Leading Market Players |
|---|
| Emergency Beacon Corporation |
| ACK Technologies, Inc. |
| ACR Electronics, Inc. |
| Orolia SA |
| Honeywell International, Inc. |
| McMurdo Group |
| Cobham Plc |
| Ocean Signal |
| HR Smith Group |
| Others |
Cost & Logistics Intelligence
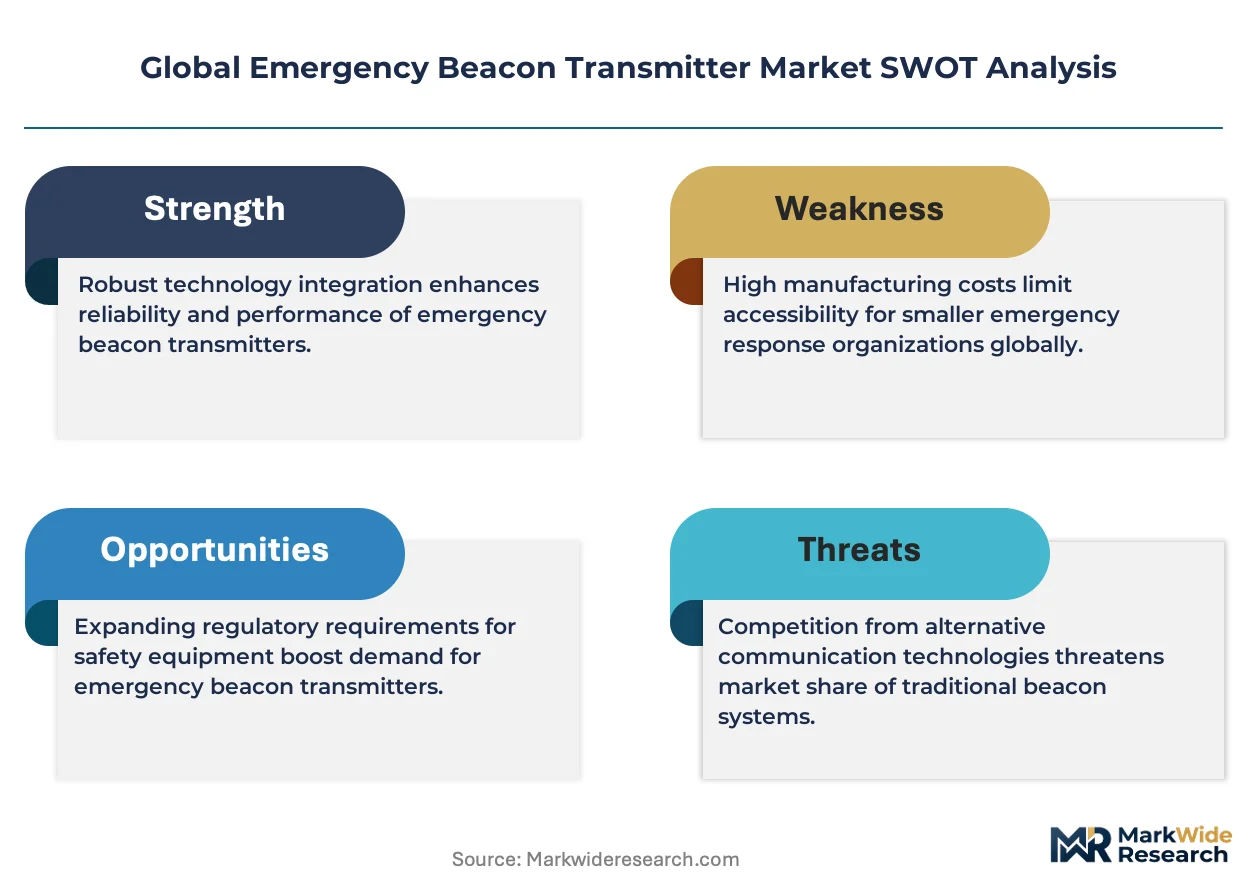
Neodymium-iron-boron magnet export quota volatility from Chinese processing facilities compresses margin buffers across RF oscillator stabilization tiers while simultaneously forcing manufacturers toward dual-sourcing strategies that reshape procurement geography. This raw material chokepoint generates pricing spreads between premium multi-constellation GNSS units and economy RF-only configurations, with certification-grade battery chemistry further stratifying cost structures.
Pricing Analysis
Price spreads between German maritime markets and Indonesian fishing fleet procurement run 40-60% for equivalent 406 MHz EPIRB specifications, reflecting SOLAS compliance overhead versus national directive minimums. Three-tier pricing structure across premium, standard, and economy levels segments on GNSS constellation count and return-link service capability, with aviation ELT retrofit programs showing least price sensitivity due to FAA TSO-C126 mandate urgency. Cost compression in economy tiers intensifies because smartphone satellite connectivity erodes recreational PLB willingness-to-pay, while defense-grade multi-constellation timing integration sustains premium positioning.
Supply Chain Analysis
Export control restrictions on gallium nitride RF power amplifier technology limit component flows from US and Japanese defense-aerospace suppliers to civilian beacon manufacturers. Manufacturing concentrates in Malaysia, Thailand, and Vietnam for final assembly, while lithium-sulfur chloride primary cells draw from South Korean and Japanese chemical suppliers. Single-source vulnerability sits with Cospas-Sarsat Secretariat type approval testing, where 8-14 month certification queues create launch timeline risk. Distribution runs through maritime safety equipment distributors in Rotterdam, Singapore, and Houston, with direct OEM relationships dominating aviation retrofit channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commercial aviation fleet recovery and MEOSAR constellation deployment create a cyclical upswing in hardware refresh demand, compressing replacement cycles across installed bases.
For Market Incumbents: Insulate certification moats by accelerating MEOSAR dual-compatibility redesigns ahead of Cospas-Sarsat protocol evolution, while securing captive lithium-sulfur chloride cell supply through backward integration into Japanese chemical partnerships. Smartphone satellite substitution threats in North American recreational markets demand defensive pricing in PLB tiers. For New Entrants and Emerging Players: Pursue Indonesian artisanal fishing fleet segments where national maritime safety directives expand mandatory carriage below SOLAS tonnage thresholds, leveraging Surabaya port zone proximity for service infrastructure. Unbundled 406 MHz message relay subscription contracts offer recurring revenue entry without upfront certification backlog exposure. For Investors and Strategic Acquirers: The market sits at a hardware refresh phase that favors protocol certification specialists with Cospas-Sarsat verification track records. Long-term viability over the next decade hinges on software-defined radio platform investments enabling post-manufacture protocol updates. Watch MEOSAR satellite payload deployment schedules as the inflection signal for next-generation beacon procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| MEOSAR Dual-Compatibility Redesign | Secures Cospas-Sarsat certification breadth before legacy LEOSAR phase-out deadlines. |
| Multi-Constellation GNSS Integration | Captures German and French defense tender requirements for Galileo-BeiDou-GLONASS redundancy. |
| Software-Defined Radio Platform Migration | Enables post-manufacture firmware updates reducing hardware obsolescence risk. |
| Indonesian Fishing Fleet Channel Buildout | Accesses 17,000-island geography with patchy terrestrial coverage under national directives. |
| Subscription-Based Monitoring Service Unbundling | Creates recurring revenue streams through private rescue coordination center memberships. |
Research Approach
Findings reconcile primary fieldwork against secondary review of Cospas-Sarsat Secretariat documentation, ETSI EN 302 152 regulatory filings, and maritime safety equipment customs records. Interviews with avionics maintenance directors, maritime fleet procurement managers, RF module design engineers, and search-and-rescue coordination center operators combined with bottom-up vessel registry analysis and top-down electronics manufacturing output data.
Forecast inputs include MEOSAR satellite constellation deployment timelines, SOLAS mandate expansion trajectories across Greek and Norwegian registries, and aviation fleet retrofit cycle modeling. Segmentation dimensions span beacon product type, GNSS technology tier, application vertical, and end-user procurement channel. CAGRs derive from installed base replacement rates and new carriage requirement penetration curves, with lithium-sulfur chloride battery chemistry certification cycles and RF engineering labor scarcity as industry-specific modifiers.
Macroeconomic conditions sit as an overlay; deviation in commercial shipping freight rates or aviation passenger recovery would shift hardware procurement trajectories. Forecasts reflect assumptions on regulatory deadline adherence and satellite payload launch schedules. Cross-checking against Cospas-Sarsat Secretariat beacon registration databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency and Disaster Management
Automatic Floodgate Market
Emergency and Disaster Management
North America Homeland Security and Emergency Management Market
Emergency and Disaster Management
Emergency Shower and Eyewash Station Market
Emergency and Disaster Management
Global Emergency Notification Software Market
Emergency and Disaster Management
Emergency and Disaster Response Market
Emergency and Disaster Management
Homeland Security and Emergency Management Market
Emergency and Disaster Management
Free Fall Lifeboats Market
Emergency and Disaster Management
Lifeboat Market
Emergency and Disaster Management
Outdoor Emergency Safety Shower Market
Emergency and Disaster Management
Emergency Blankets Market
Emergency and Disaster Management
Incident and Emergency Management Market
Emergency and Disaster Management
Hazard Control Market
Emergency and Disaster Management
Emergency Location Transmitter Market
Emergency and Disaster Management
EHS Market
Emergency and Disaster Management
Crisis Emergency and Incident Management Platform Market
Emergency and Disaster Management
Earthquake Early Warning System Market