
 Crisis Emergency and Incident Management Platform Market | 2026-2036
Crisis Emergency and Incident Management Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Crisis Emergency and Incident Management Platform Market Analytics
ISO 22320 certification for incident management is bifurcating vendor eligibility between certified enterprise providers and uncertified regional software houses. Motorola Solutions leverages its FirstNet integration to sustain dominance in North American public safety networks. Honeywell International anchors its position through in-house production of command-and-control hardware paired with proprietary software stacks. IBM Corporation differentiates via AI-powered threat correlation engines that process multi-source intelligence feeds in real time.
A crisis emergency and incident management platform integrates real-time data ingestion, geospatial visualization, and multi-channel communication protocols into a unified command environment, typically processing incident data with sub-second latency to enable coordinated response across distributed agencies. The system serves primary commercial purpose by collapsing decision cycles during critical events through automated escalation workflows and resource dispatch algorithms. Cloud-based deployment is capturing the fastest expansion as municipal buyers abandon capital-intensive on-premises infrastructure for subscription models with elastic scaling. Communication platforms command the deepest margin pools because public safety agencies mandate encrypted, carrier-agnostic messaging with 99.999% uptime guarantees. Incident response software remains the largest revenue category, though growth rates in data analysis solutions are accelerating as predictive risk modeling becomes standard in enterprise continuity planning.
FEMA certification requirements and NIST cybersecurity frameworks shape procurement eligibility for U.S. government buyers, while the EU Critical Entities Resilience Directive mandates standardized incident reporting across member states. Product standards now require Common Criteria EAL4+ evaluation for platforms handling classified or sensitive infrastructure data. Stakeholders must monitor how evolving sovereign data residency rules fragment cloud architecture choices and force localization investments that alter total cost of ownership calculations.
Market Dynamics
Federal procurement mandates for interoperability are compressing vendor selection criteria across public safety agencies, forcing consolidation around platforms that satisfy Common Criteria EAL4+ certification and real-time data fusion capabilities.
Growth Catalysts
- NIST SP 800-34:Business continuity guidelines in the United States are accelerating compliance investments among state and municipal emergency management departments.
- AI-powered threat correlation:Machine learning engines processing multi-source intelligence feeds are collapsing decision cycles during critical infrastructure events.
- Germany:Federal civil protection modernization programs are driving platform upgrades across Bundesländer emergency response networks.
Market Restraints
- Cloud infrastructure concentration:Hyperscaler dominance in Western Europe creates single-point-of-failure risks for sovereign data residency requirements.
- Encrypted hardware costs:Carrier-agnostic communication modules with 99.999% uptime guarantees command premium input pricing that strains municipal budgets.
- Legacy system entrenchment:Decades-old dispatch protocols in aging public safety answering points block seamless API integration with modern platforms.
Strategic Opportunities
- EU Critical Entities Resilience Directive:Standardized incident reporting mandates across member states are opening procurement pathways for certified platform providers.
- Edge computing convergence:Integration of on-premise inference engines with satellite backhaul is enabling disconnected-operation resilience for remote infrastructure monitoring.
- Subscription elasticity:Small and mid-sized municipalities in France and Italy are abandoning capital-intensive on-premises infrastructure for consumption-based scaling models.
Industry Challenges
- ISO 22320 certification timelines:The 12-18 month evaluation window for incident management standards delays product launches and freezes competitive repositioning.
- Interoperability skill scarcity:Shortages of systems engineers fluent in both legacy CAD protocols and modern REST API architectures constrain deployment velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crisis Emergency and Incident Management Platform Market |
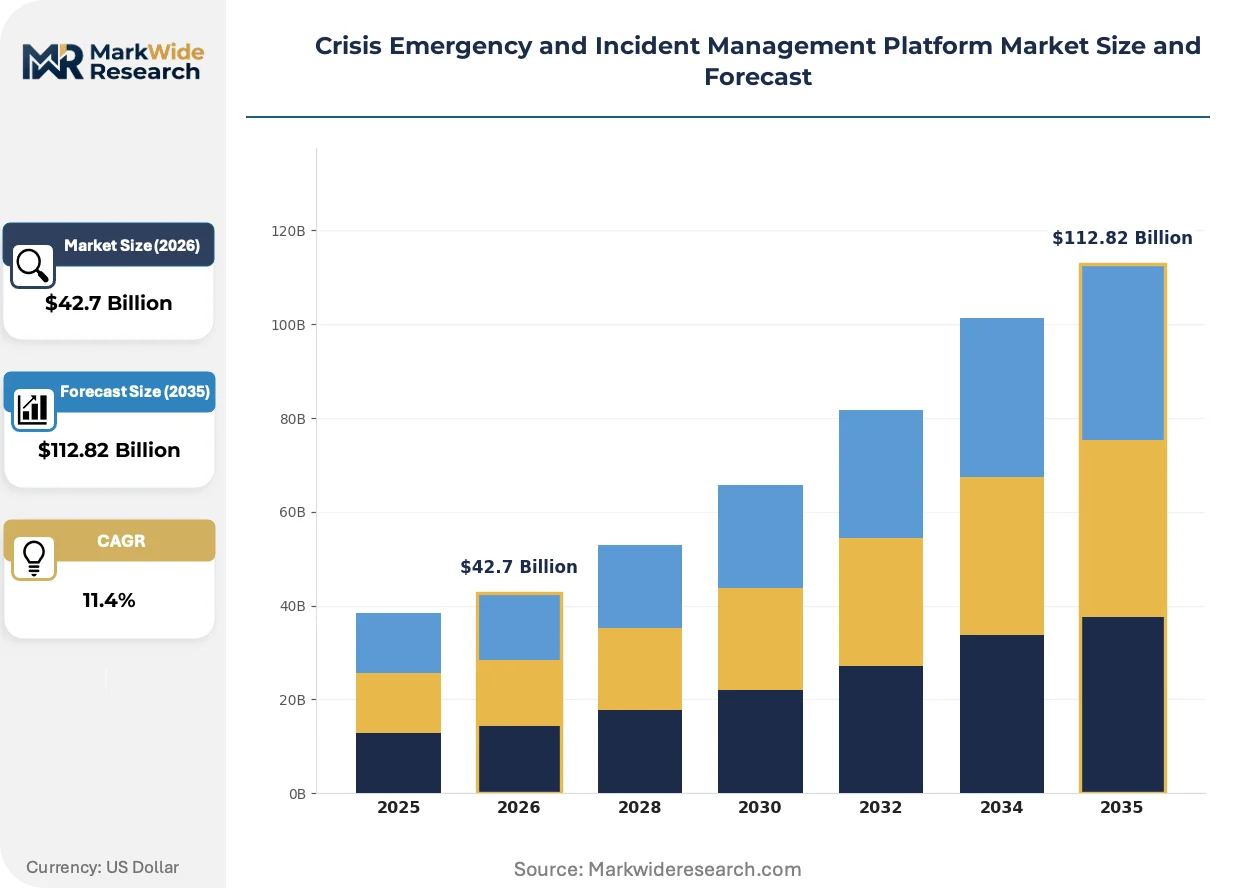
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $112.82 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Incident Response Software, Crisis Management Tools, Communication Platforms, Data Analysis Solutions Deployment: On-Premises, Cloud-Based, Hybrid, Mobile Solutions End User: Government Agencies, Healthcare Providers, Educational Institutions, Corporations Application: Disaster Recovery, Emergency Preparedness, Risk Management, Business Continuity |
| Companies Covered | Motorola Solutions, Honeywell International, IBM Corporation, Siemens AG, Lockheed Martin Corporation, Everbridge, ESRI, Johnson Controls International, Hexagon AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crisis Emergency and Incident Management Platform Market Evolving Landscape
Real-time data ingestion architectures are displacing batch-processing legacy systems, while regulatory fragmentation around sovereign cloud mandates is forcing architectural bets on localized edge stacks versus centralized hyperscaler deployments.
Digital twin environments for critical infrastructure are displacing static tabletop exercises as the primary preparedness methodology. Power utilities and transportation authorities in the United States and Germany are deploying these simulations at scale. The technology is compressing training cycles from quarterly drills to continuous virtual stress-testing, fundamentally altering how agencies budget for readiness.
The EU AI Act's risk classification framework for automated decision systems is reshaping procurement specifications for resource dispatch algorithms. Vendors must now document explainability pathways for AI-driven recommendations. Public safety agencies in France and the Netherlands are rewriting RFP language to mandate algorithmic audit trails before contract award.
Municipal buyers are consolidating vendor relationships around full-stack providers that bundle command hardware, proprietary software, and encrypted communication layers. This pattern is most pronounced in North American public safety networks where FirstNet integration has become a non-negotiable evaluation criterion. The shift is squeezing point-solution vendors out of primary procurement channels and forcing partnerships with integrated platform holders.
Crisis Emergency and Incident Management Platform Market Segmentation
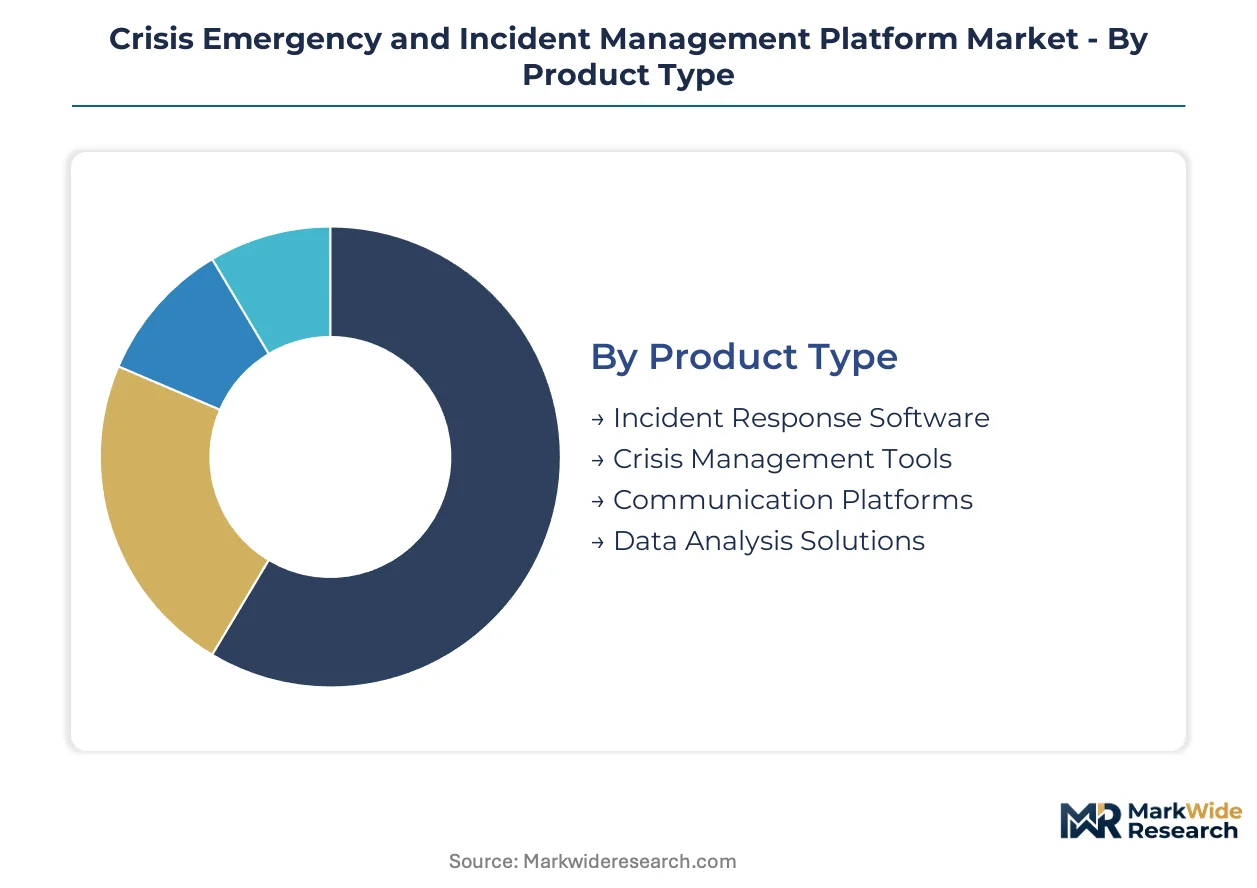
Crisis emergency and incident management platforms segment across four critical dimensions that determine procurement eligibility, deployment architecture, and compliance pathways. Each category carries distinct regulatory requirements and margin profiles that reshape vendor positioning.
Product Type:
NIST SP 800-34 and ISO 22320 certification requirements bifurcate vendor eligibility between enterprise-grade platforms and uncertified regional alternatives.
- Incident Response Software:Core platforms automate escalation workflows and resource dispatch algorithms with sub-second latency. Demand concentrates in U.S. state emergency management departments where FEMA certification mandates compress vendor selection criteria around Common Criteria EAL4+ evaluation.
- Communication Platforms:Encrypted, carrier-agnostic messaging systems with 99.999% uptime guarantees command premium pricing. Public safety agencies in Germany's Bundesländer networks mandate these for federal civil protection modernization programs.
- Crisis Management Tools:Coordination dashboards integrating multi-agency command hierarchies.
- Data Analysis Solutions:Predictive risk modeling engines processing multi-source intelligence feeds.
Incident Response Software handles the majority of throughput; Data Analysis Solutions is the fastest mover on share.
Deployment:
Total cost of ownership calculations diverge sharply between capital-intensive infrastructure and consumption-based scaling models.
- Cloud-Based:Subscription models with elastic scaling capture municipal buyers abandoning on-premises capital expenditure. Small and mid-sized municipalities in France and Italy are expanding procurement fastest here.
- On-Premises:Sovereign data residency requirements in Western Europe sustain demand despite higher upfront investment.
- Hybrid:Architectures balancing localized edge stacks with centralized hyperscaler resources.
- Mobile Solutions:Satellite backhaul-enabled platforms for disconnected-operation resilience in remote infrastructure monitoring.
Cloud-Based deployment captures the deepest margin expansion; Mobile Solutions shows the steepest adoption trajectory among new buyers.
End User:
Procurement authority and budget scale segment buyer sophistication across public and private sectors.
- Government Agencies:Federal, state, and municipal emergency management departments with standardized RFP processes. U.S. agencies prioritize FirstNet integration; EU buyers align with Critical Entities Resilience Directive reporting mandates.
- Corporations:Enterprise continuity planning drives predictive risk modeling adoption. Power utilities and transportation authorities in the United States and Germany deploy digital twin simulations at scale.
- Healthcare Providers:HIPAA compliance requirements shape encrypted communication specifications.
- Educational Institutions:Campus safety mandates drive multi-channel alert system procurement.
Government Agencies anchor procurement volume; Corporations are climbing the fastest on technology refresh cycles.
Application:
Functional use cases determine integration depth with legacy dispatch protocols and modern API architectures.
- Business Continuity:NIST cybersecurity frameworks and business continuity guidelines accelerate compliance investments. Automated workflow engines collapse decision cycles during critical infrastructure events.
- Disaster Recovery:Real-time data fusion capabilities coordinate distributed agency response across jurisdictions.
- Emergency Preparedness:Digital twin environments displace static tabletop exercises for continuous virtual stress-testing.
- Risk Management:AI-powered threat correlation engines process multi-source intelligence feeds with explainability pathways mandated by EU AI Act risk classification frameworks.
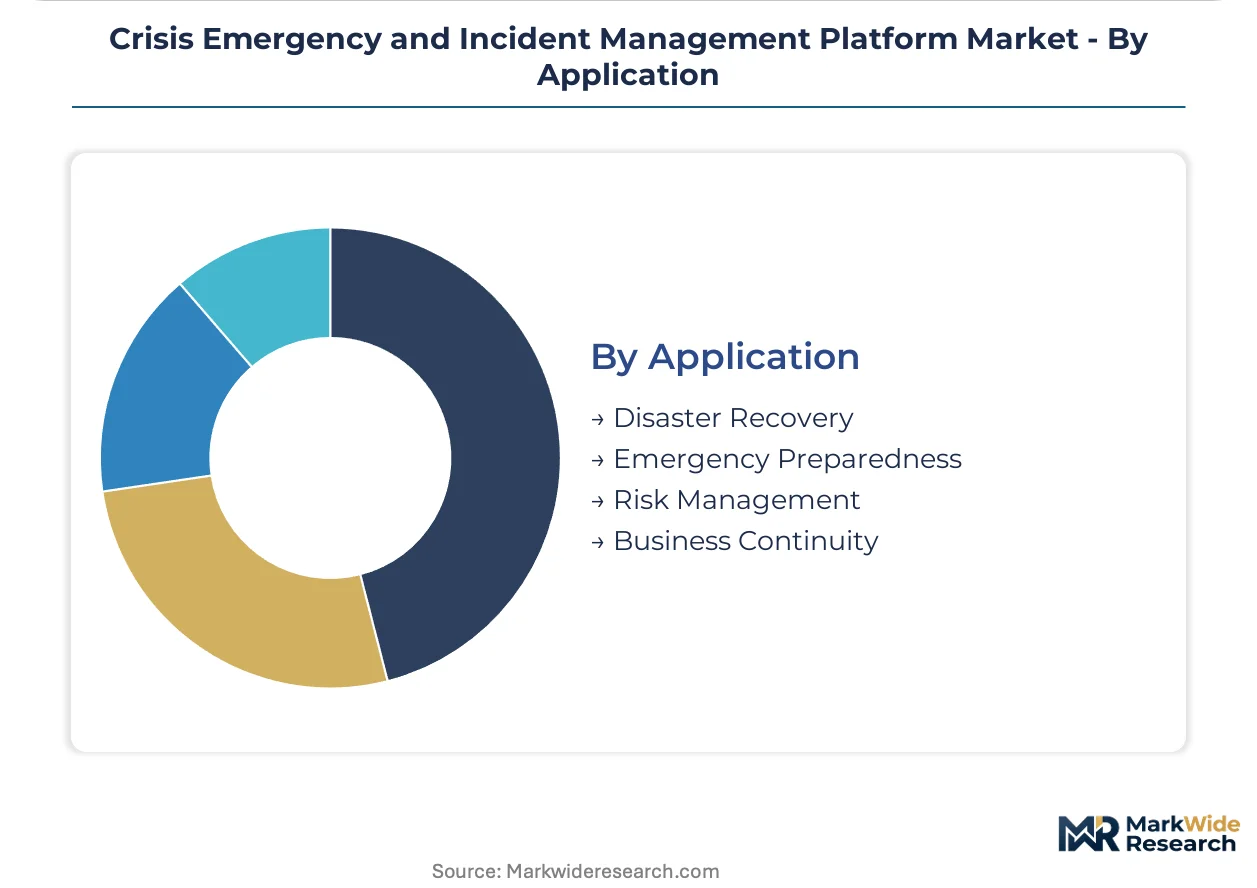
Business Continuity commands the largest implementation base; Risk Management is expanding most quickly on algorithmic audit trail requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government emergency management departments concentrate procurement authority in five national markets where federal certification mandates and civil protection modernization programs drive platform adoption.
United States
FEMA certification requirements and NIST SP 800-34 business continuity guidelines compress vendor selection criteria around Common Criteria EAL4+ evaluation. State emergency management departments in California, Texas, and Florida anchor procurement volume for incident response software with FirstNet integration mandates. Municipal buyers in the Northeast Corridor are abandoning capital-intensive on-premises infrastructure for cloud-based subscription models.
Germany
Federal civil protection modernization programs across Bundesländer emergency response networks drive platform upgrades for encrypted communication systems. The country's national cybersecurity regulator mandates standardized incident reporting aligned with EU Critical Entities Resilience Directive requirements. Industrial clusters in Bavaria and North Rhine-Westphalia deploy digital twin simulations for critical infrastructure stress-testing.
France
Small and mid-sized municipalities accelerate cloud-based procurement fastest among Western European buyers seeking consumption-based scaling models. The national data protection regulator enforces sovereign data residency rules that fragment cloud architecture choices and force localization investments. The Île-de-France region concentrates demand for AI-powered threat correlation engines with algorithmic audit trail documentation.
United Kingdom
Enterprise continuity planning in London's financial services sector drives predictive risk modeling adoption for business continuity applications. The national cyber security centre mandates encryption standards for multi-agency command hierarchies. Greater Manchester and West Midlands emergency response networks prioritize real-time data fusion capabilities for distributed agency coordination.
Japan
Power utilities and transportation authorities in the Kanto and Kansai regions deploy satellite backhaul-enabled platforms for disconnected-operation resilience. The Ministry of Economy, Trade and Industry promotes edge computing convergence for remote infrastructure monitoring. Tokyo's metropolitan government leads municipal procurement for crisis management tools integrating multi-channel alert systems.
Crisis Emergency and Incident Management Platform Market Competitive Landscape
Player mix skews toward integrated platform holders with in-house command hardware production and proprietary software stacks. Tiered vendor eligibility separates certified enterprise providers meeting ISO 22320 and Common Criteria standards from uncertified regional alternatives. Dominant competitive moves include strategic partnerships with hyperscaler cloud providers and portfolio diversification into AI-powered threat correlation engines.
Within the integrated platform tier, Motorola Solutions and Honeywell International exemplify full-stack providers bundling command hardware with encrypted communication layers. IBM Corporation occupies a position among AI-native vendors differentiating through real-time multi-source intelligence processing. These three anchors represent distinct competitive vectors: carrier-agnostic public safety network integration, captive manufacturing of command-and-control infrastructure, and machine learning-driven decision automation.
| Leading Market Players |
|---|
| Motorola Solutions |
| Honeywell International |
| IBM Corporation |
| Siemens AG |
| Lockheed Martin Corporation |
| Everbridge |
| ESRI |
| Johnson Controls International |
| Hexagon AB |
| Others |
Value Network & Pricing Analysis
Long-term subscription contracts with annual indexation clauses lock municipal buyers into predictable cost structures while securing vendor access to encrypted communication module supply. These arrangements tie pricing visibility to FEMA certification timelines and ISO 22320 evaluation windows that stretch 12-18 months.
Pricing Analysis
Cost-plus contracts indexed to semiconductor component costs dominate municipal procurement, with pricing stratifying across Common Criteria EAL4+ certified tiers and uncertified alternatives. Certification grade and encrypted hardware integration depth drive price differentiation between enterprise platforms and regional software houses. Cost compression in cloud-based deployment tiers is intensifying because hyperscaler volume discounts erode on-premises margin premiums. Small and mid-sized municipalities in France and Italy exhibit highest price sensitivity, while U.S. federal agencies with FirstNet mandates show least elasticity.
Supply Chain Analysis
The United States and Germany anchor production of command-and-control hardware with integrated encryption layers, while Taiwan and South Korea supply carrier-agnostic communication chipsets. Supply chains draw from gallium nitride semiconductors, satellite backhaul terminals, and hardened server chassis. Single-source vulnerability concentrates in hyperscaler cloud infrastructure for Western European sovereign data requirements. Distribution runs through federal procurement channels and GSA schedules for U.S. government buyers, with direct enterprise sales for critical infrastructure operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from AI-powered threat correlation engines and predictive risk modeling subscriptions is expanding faster than hardware sales, creating recurring-revenue platforms that deepen customer switching costs.
For Market Incumbents: Fortify certification moats by accelerating ISO 22320 and Common Criteria EAL4+ evaluation investments before EU Critical Entities Resilience Directive procurement windows open. Hyperscaler partnership dependency threatens margin control; captive supply of edge computing hardware restores pricing power over municipal buyers. For New Entrants and Emerging Players: Anchor in small and mid-sized municipalities across France and Italy where cloud-based subscription elasticity displaces legacy on-premises infrastructure. Digital twin simulation modules for power utilities represent the most penetrable application layer. Partner with established command hardware manufacturers to bypass 18-month certification barriers. For Investors and Strategic Acquirers: AI-native vendors with real-time multi-source intelligence processing capabilities offer the strongest long-term viability through the projection horizon. Watch for algorithmic audit trail mandates under EU AI Act risk classification frameworks as the inflection signal for explainable AI platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 22320 Certification Investment | Unlocks EU Critical Entities Resilience Directive procurement pathways across member states. |
| FirstNet Integration Partnership | Secures non-negotiable evaluation criteria for U.S. state emergency management departments. |
| Edge Computing Hardware Production | Enables disconnected-operation resilience for remote infrastructure monitoring deployments. |
| AI Explainability Module Development | Satisfies EU AI Act algorithmic audit trail mandates for resource dispatch algorithms. |
| Cloud Subscription Elasticity Program | Captures municipal buyers abandoning capital-intensive on-premises infrastructure models. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with emergency management directors, federal procurement officers, platform engineers, and critical infrastructure security chiefs. Secondary validation drew from FEMA certification databases, NIST SP 800-34 documentation, EU Critical Entities Resilience Directive filings, and hyperscaler capex disclosures. Bottom-up and top-down triangulation cross-referenced municipal procurement records with vendor revenue segmentation.
Across the analysis window, forecasts model deployment architecture, end-user sector, application function, and product certification tier as primary segmentation dimensions. CAGRs derive from elasticity-adjusted adoption curves incorporating NIST compliance investment cycles and Bundesländer modernization program schedules. AI-powered threat correlation engine penetration and digital twin simulation deployment velocity serve as industry-specific forecast inputs.
Material uncertainties — sovereign data residency rule fragmentation, ISO 22320 evaluation timeline extensions, and hyperscaler concentration risks — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and certification backlog clearance. Recalibration cycles align with material shifts in federal procurement mandates and EU directive implementation schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency and Disaster Management
EHS Market
Emergency and Disaster Management
Asia-Pacific Process Safety Services Market
Emergency and Disaster Management
Lifeboat Market
Emergency and Disaster Management
Free Fall Lifeboats Market
Emergency and Disaster Management
Disaster Restoration Services Market
Emergency and Disaster Management
North America Homeland Security and Emergency Management Market
Emergency and Disaster Management
Hazard Control Market
Emergency and Disaster Management
Intelligent Evacuation System Market
Emergency and Disaster Management
Homeland Security and Emergency Management Market
Emergency and Disaster Management
Survival Tools Market
Emergency and Disaster Management
Emergency Location Transmitter Market
Emergency and Disaster Management
Outdoor Emergency Safety Shower Market
Emergency and Disaster Management
Automatic Floodgate Market
Emergency and Disaster Management
Emergency Shutdown System Market
Emergency and Disaster Management
Cyber Crisis Management Market
Emergency and Disaster Management
Earthquake Early Warning System Market