
 Incident and Emergency Management Market | 2026-2036
Incident and Emergency Management Market Size, Share, and Industry Trends Forecast 2026-2036
Incident and Emergency Management Market Intelligence
The integration of AI-driven predictive analytics into cloud-based platforms is tilting the market away from reactive, on-premises systems toward proactive threat identification. Honeywell International Inc. leverages its building management systems to integrate emergency response. Motorola Solutions specializes in mission-critical communication networks essential for first responders. IBM Corporation provides advanced analytics and cognitive computing capabilities for large-scale crisis management.
Incident and emergency management encompasses integrated platforms that enable organizations to prepare for, respond to, and recover from disruptive events. These systems process multi-source real-time data, including IoT sensor inputs and GIS mapping, to create a common operational picture. Within the solution stack, Crisis Intelligence and Risk Assessment tools are gaining prominence over basic notification systems. Government agencies continue to represent the largest end-user segment, although demand from corporate security and utilities providers is expanding rapidly.
Regulatory frameworks, including OSHA standards in the United States and directives linked to the EU Green Deal, mandate robust safety and response protocols for public and private entities. These regulations directly influence the required capabilities of response management solutions. For organizations, the critical decision revolves around adopting fully integrated platforms from major vendors versus assembling best-of-breed solutions from specialized providers.
Market Dynamics
The central dynamic in the incident and emergency management market is the structural shift from reactive response to proactive, predictive risk mitigation. This change is driven by regulatory pressure for resilience reporting and the increasing frequency of climate-related disruptions.
Growth Catalysts
- Regulatory Mandates:The European Union's CSRD requires comprehensive risk and emergency preparedness disclosures, compelling corporations to adopt formal management platforms to ensure compliance and report accurately on their resilience measures.
- Climate-Related Events:An escalation in extreme weather events is forcing utilities providers and government agencies, particularly in the United States, to invest heavily in modernizing their response and recovery systems to protect critical infrastructure.
- Technology Proliferation:The widespread deployment of IoT sensors and GIS mapping in smart city initiatives and industrial environments provides the high-volume, real-time data necessary for creating a sophisticated common operational picture.
Market Restraints
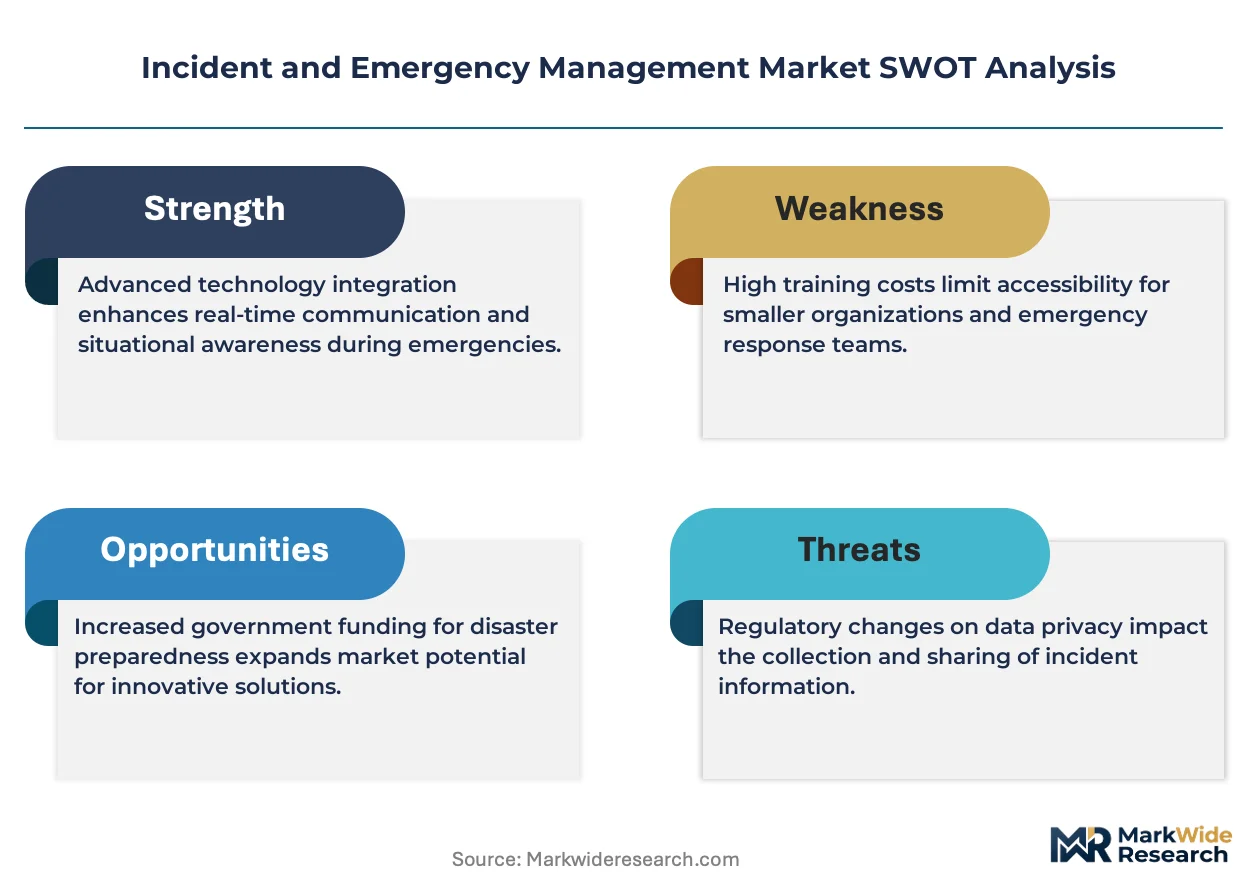
- High Implementation Cost:The significant capital investment required for integrated, enterprise-grade platforms with advanced analytics presents a substantial adoption barrier for smaller municipalities and medium-sized businesses with limited budgets.
- Data Silos:Information remains fragmented across disparate departmental systems within large organizations and government agencies, impeding the aggregation required for a unified, real-time operational view and effective cross-functional response.
- Interoperability Deficits:A lack of universal standards for data exchange between solutions from different vendors complicates integration, creating communication gaps for first responders who rely on multiple systems during an emergency.
Strategic Opportunities
- SME Solution Scaling:Developing modular, subscription-based incident management platforms offers a significant opportunity to penetrate the underserved market of small and medium-sized enterprises that lack dedicated crisis management resources.
- Supply Chain Resilience Analytics:Expanding crisis intelligence tools to specifically model and predict disruptions within complex global supply chains addresses a growing need from the manufacturing and logistics sectors.
- Public-Private Collaboration Platforms:There is a clear opening for solutions that facilitate secure, real-time data sharing and coordinated response efforts between public sector emergency agencies and private sector operators of critical infrastructure.
Industry Challenges
- Specialized Talent Shortage:A scarcity of professionals who possess a dual expertise in both crisis management protocols and data science hinders the ability of organizations to fully leverage the advanced analytical capabilities of new platforms.
- Legacy System Integration:Connecting modern, cloud-based incident management systems with entrenched legacy infrastructure, such as analog radio networks or outdated dispatch software, poses a significant and costly technical hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Incident and Emergency Management Market |
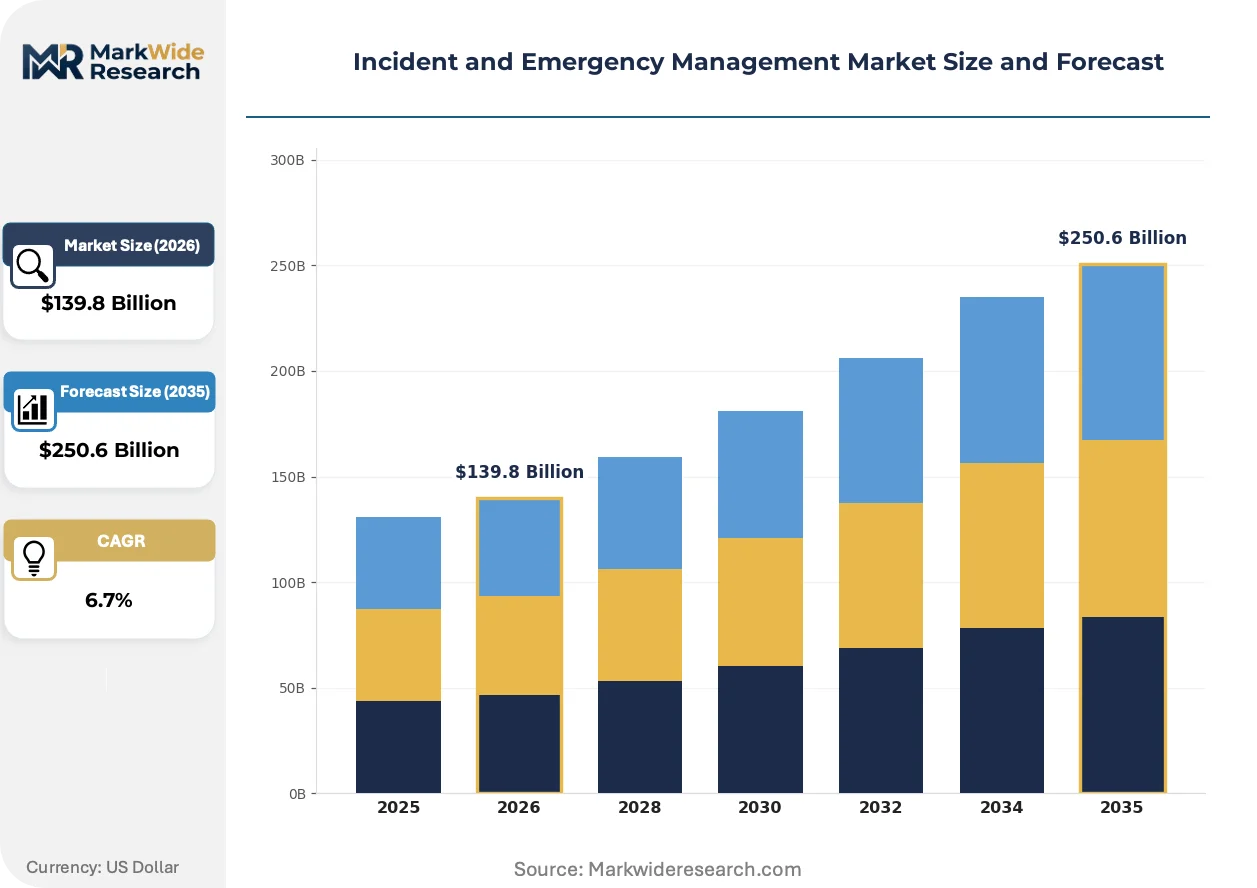
| Market Size in 2026 | $139.8 Billion |
| Market Size in 2035 | $250.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Incident Notification, Crisis Intelligence, Resource Coordination, Response Management, Risk Assessment, Recovery Planning Deployment: Cloud-Based, On-Premises, Hybrid, Hosted, Software-as-a-Service, Managed Services Application: Natural Disaster Response, Public Safety, Industrial Accident Control, Transportation Safety, Event Security, Cyber Incident Response End User: Emergency Services, Government Agencies, Corporate Security, Educational Institutions, Non-Governmental Organizations, Utilities Providers |
| Companies Covered | Honeywell International Inc., Motorola Solutions, Lockheed Martin, IBM Corporation, Hexagon AB, NEC Corporation, Johnson Controls, Collins Aerospace, Esri, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Incident and Emergency Management Market Strategic Shifts & Innovations
The market's evolution is defined by a move toward integrated, data-driven resilience. This transition prioritizes predictive insights and a unified operational view over siloed, reactive alerting tools, fundamentally changing organizational approaches to risk and crisis.
AI-powered predictive analytics, often layered with GIS mapping, form the core of next-generation platforms. Government agencies and corporate security departments are the primary adopters, seeking to anticipate threats rather than just react to them. This technology is digitizing threat assessment, transforming it from a static, periodic review into a continuous, automated process that identifies potential disruptions before they escalate.
Regulatory mandates, particularly the EU's Corporate Sustainability Reporting Directive, are setting new standards for organizational resilience. This directive forces a broad range of companies to publicly report on their risk management processes, including preparedness for climate-related and operational incidents. Consequently, corporate security and risk management departments must invest in platforms that can document, measure, and report on response capabilities to meet these disclosure requirements.
A fundamental shift in acquisition strategy is visible among buyers. Organizations are moving away from procuring disparate point solutions, such as standalone mass notification systems, in favor of unified platforms that integrate risk assessment, response coordination, and recovery planning. This trend toward platform-based procurement is most pronounced among utilities and government agencies in North America seeking a single source of truth.
Incident and Emergency Management Market Segmentation
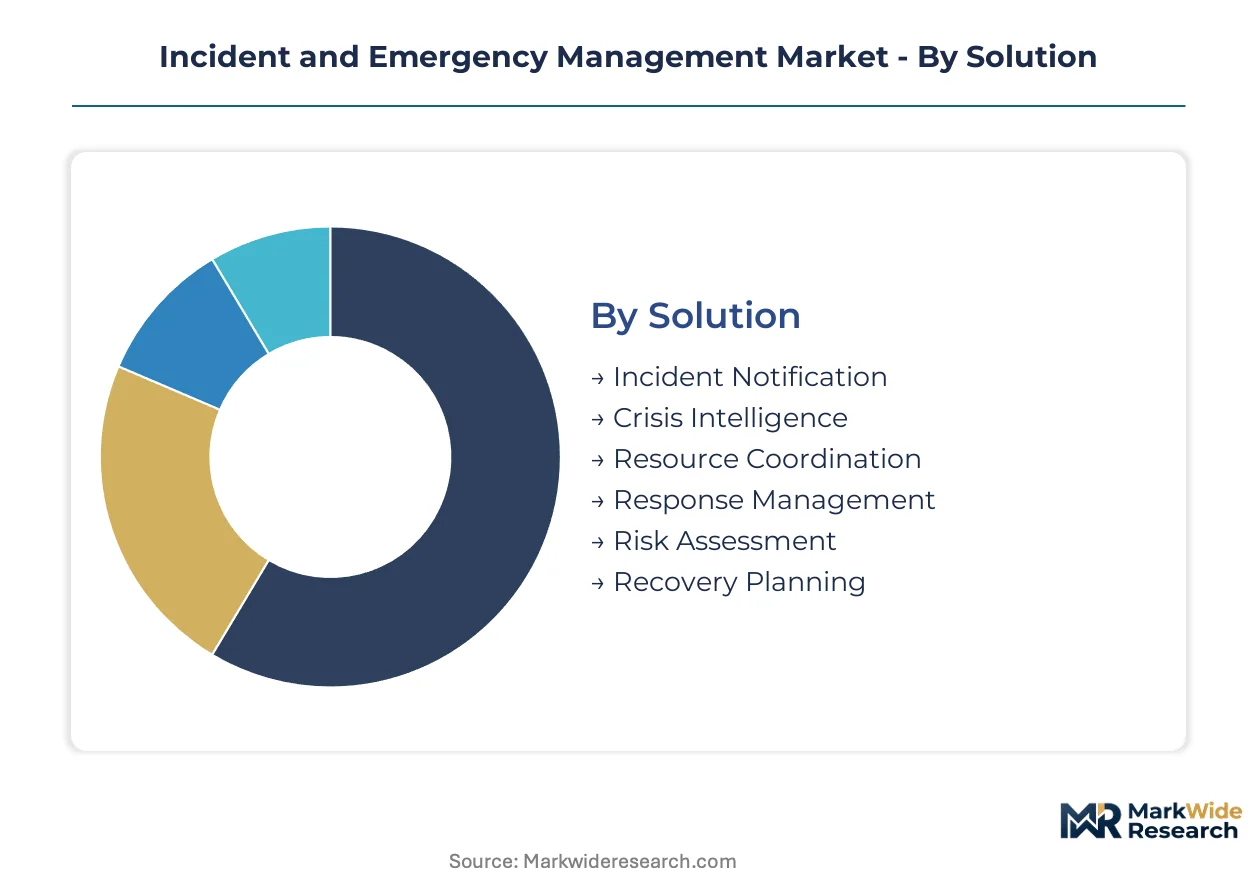
Market segmentation provides a critical framework for understanding the diverse needs and operational contexts within the incident and emergency management landscape. This detailed classification highlights where investment is concentrated, which technologies are gaining traction, and the specific challenges faced by various user groups, enabling targeted solution development and strategic market entry.
Solution:
The spectrum of solutions addresses diverse incident management requirements, ranging from immediate alerts to long-term recovery strategies.
- Crisis Intelligence:These advanced platforms collect and analyze multi-source real-time data, including IoT sensor inputs and GIS mapping, to provide actionable insights for proactive threat identification. Corporate security departments and government agencies in the United States increasingly adopt these tools to anticipate disruptions.
- Risk Assessment:Tools in this category evaluate potential threats and vulnerabilities, helping organizations quantify and prioritize risks to inform preparedness strategies. Demand is significant among utilities providers in Europe, driven by EU Green Deal directives requiring robust risk protocols.
- Incident Notification:These systems deliver alerts and instructions to affected personnel and stakeholders through various communication channels, ensuring rapid dissemination of critical information.
- Resource Coordination:Platforms designed to manage and allocate personnel, equipment, and other assets efficiently during an emergency, optimizing response efforts.
- Response Management:These integrated systems orchestrate all aspects of an emergency response, from initial assessment to execution of pre-defined protocols.
- Recovery Planning:Solutions that assist organizations in developing and implementing strategies to restore operations and mitigate long-term impacts following a disruptive event.
The dominant share belongs to Response Management, while Crisis Intelligence is closing the gap fastest.
Deployment:
Maturity of infrastructure and operational preferences define the various deployment models.
- Cloud-Based:These solutions are hosted on remote servers and accessed over the internet, offering scalability, flexibility, and reduced infrastructure costs. Government agencies and large enterprises globally are increasingly migrating to cloud-based systems for enhanced accessibility.
- On-Premises:Software and hardware are installed and run on the organization's own servers, providing complete control over data and security. Certain critical infrastructure operators in Germany maintain on-premises systems for stringent data sovereignty requirements.
- Hybrid:This model combines elements of both cloud-based and on-premises deployments, allowing organizations to leverage the benefits of each.
- Hosted:Third-party providers host and manage the software and infrastructure, offering a balance between control and operational ease.
- Software-as-a-Service:A subscription-based model where software is centrally hosted and licensed on a pay-per-use basis, reducing upfront capital expenditure.
- Managed Services:External providers take responsibility for managing and maintaining the entire incident management system, including software, hardware, and support.
Cloud-Based deployments are rapidly expanding, with Hybrid models offering a balanced approach for many organizations.
Application:
The scale and nature of potential disruptions drive the diverse application areas for these systems.
- Natural Disaster Response:These applications support preparedness, response, and recovery efforts for events such as hurricanes, earthquakes, and floods. Utilities providers in the United States invest heavily in these systems to protect critical infrastructure from climate-related events.
- Public Safety:Systems designed to enhance the safety and security of communities, encompassing law enforcement, fire services, and emergency medical response. Government agencies in Canada utilize these platforms for coordinated urban safety initiatives.
- Industrial Accident Control:Solutions tailored for managing incidents in industrial settings, including chemical spills, equipment failures, and workplace safety breaches.
- Transportation Safety:Applications focused on improving safety and managing incidents across various transportation modes, such as road, rail, air, and maritime.
- Event Security:Platforms used to plan and execute security measures for large public gatherings, including concerts, sports events, and conferences.
- Cyber Incident Response:Tools and processes for detecting, analyzing, and mitigating cyberattacks and data breaches, protecting digital assets.
Natural Disaster Response remains a significant segment, and Cyber Incident Response is experiencing considerable expansion.
End User:
Organizational mandates and risk profiles differentiate the demand patterns across end-user segments.
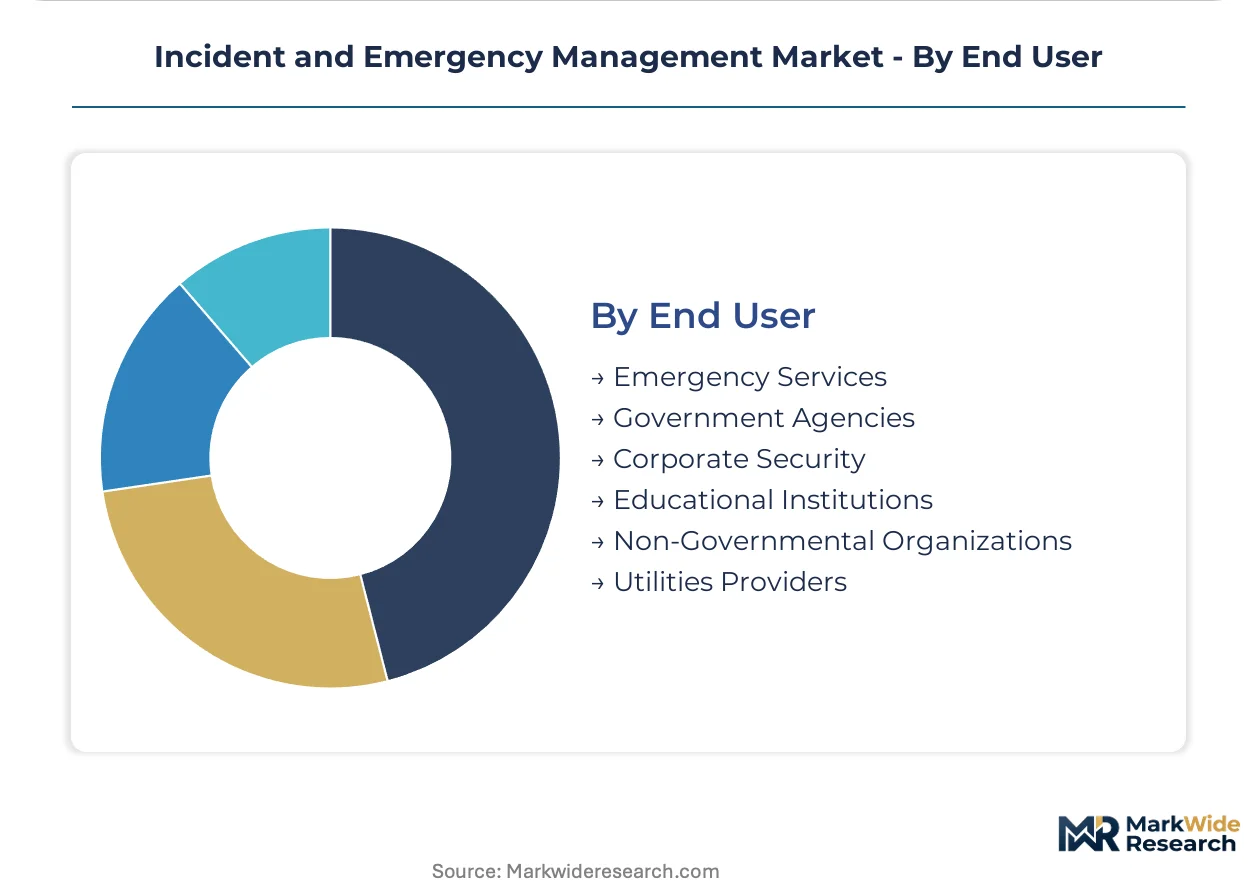
- Government Agencies:This segment includes federal, state, and local government bodies responsible for public safety, defense, and infrastructure protection. These agencies, particularly in the United States, constitute the largest end-user segment due to broad mandates.
- Utilities Providers:Companies managing essential services like electricity, water, and gas, requiring robust systems to maintain operational continuity and protect critical infrastructure. European utilities are significantly increasing investment due to EU regulatory pressures.
- Emergency Services:This category encompasses police, fire departments, and emergency medical services, which rely on incident management systems for coordinated response.
- Corporate Security:Departments within private enterprises that manage internal and external security threats, operational risks, and business continuity.
- Educational Institutions:Schools, colleges, and universities implement these systems for campus safety, emergency notifications, and crisis management protocols.
- Non-Governmental Organizations:Humanitarian and aid organizations use these platforms for disaster relief coordination and field operations management.
Government Agencies continue to represent the largest user base, with Utilities Providers showing substantial investment growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for incident and emergency management platforms concentrates heavily among government agencies and utilities providers globally. These key buyer archetypes invest in sophisticated systems to enhance public safety, protect critical infrastructure, and comply with evolving regulatory mandates. Regional investment patterns reflect specific risk profiles and policy priorities.
United States
Utilities providers and government agencies in the United States drive substantial demand for incident and emergency management solutions. These entities prioritize resilience against escalating climate-related events and natural disasters. OSHA standards mandate robust safety and response protocols across various industries. Major coastal cities and states, such as Florida and California, significantly invest in disaster preparedness and response infrastructure.
Germany
Critical infrastructure operators in Germany maintain stringent requirements for data sovereignty and operational control, often preferring on-premises incident management systems. The EU Green Deal directives compel utilities and industrial firms to enhance their risk assessment and preparedness capabilities. Industrial complexes within North Rhine-Westphalia frequently implement advanced response management solutions to mitigate industrial accident risks.
Canada
Government agencies across Canada utilize incident management systems for coordinated public safety initiatives and emergency medical services. Public Safety Canada emphasizes integrated response platforms for national security and disaster mitigation. Major urban centers like Toronto and Vancouver deploy advanced solutions to manage large-scale events and enhance urban resilience.
Japan
Japan's high susceptibility to natural disasters, including earthquakes and tsunamis, drives significant investment in advanced emergency management technologies. The National Resilience Plan outlines strategies for strengthening infrastructure and response capabilities. Smart city initiatives in Tokyo and other metropolitan areas integrate IoT sensors and GIS mapping for real-time threat identification.
France
Regulatory pressures, particularly the EU's Corporate Sustainability Reporting Directive (CSRD), compel French corporations to adopt formal incident management platforms. Corporate security departments increasingly leverage these systems for comprehensive risk and emergency preparedness reporting. Major companies headquartered in Île-de-France prioritize integrated platforms to ensure compliance and enhance their operational resilience.
Incident and Emergency Management Market Key Industry Players
Channel-controlling players compete with product-specialist players across the incident and emergency management market. The market features a blend of large, diversified technology conglomerates offering integrated platforms and specialized vendors focusing on niche solutions. Strategic archetypes include comprehensive platform providers, mission-critical communication specialists, and advanced analytics firms. Competitive moves frequently involve strategic partnerships to expand solution ecosystems and portfolio diversification to address broader client needs.
Within the diversified technology giant archetype, IBM Corporation offers advanced analytics and cognitive computing capabilities for large-scale crisis management. Honeywell International Inc. represents integrated platform providers, leveraging its extensive building management systems to enhance emergency response. Motorola Solutions exemplifies mission-critical communication specialists, delivering essential networks for first responders globally.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Motorola Solutions |
| Lockheed Martin |
| IBM Corporation |
| Hexagon AB |
| NEC Corporation |
| Johnson Controls |
| Collins Aerospace |
| Esri |
| Others |
Cost & Logistics Intelligence
Underutilized cloud infrastructure capacity, particularly in regions like the United States, drives competitive pricing among platform providers. This influences vendor strategies for securing long-term service contracts with government agencies.
Pricing Analysis
Cost-plus contract patterns, often indexed to infrastructure maintenance costs, define pricing for bespoke incident management platforms. Subscription-based SaaS models dominate for smaller enterprises, offering tiered access based on user count and feature sets. Customization for specific regulatory compliance, like EU CSRD reporting, drives premium pricing. Pricing softness affects basic notification systems due to increased commoditization, with government agencies exhibiting lower price sensitivity than cost-conscious SMEs.
Supply Chain Analysis
Extended payment terms are common for large-scale government contracts, influencing the financial stability of hardware and software component suppliers. The supply of advanced analytics software and cloud infrastructure draws from technology hubs in the United States, Germany, and Ireland. Key dependencies include specialized IoT sensors and secure communication chipsets, where single-source vulnerability presents a structural risk. Distribution primarily runs through direct sales teams for large enterprises and channel partners for SMEs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The incident and emergency management market presents significant fragmentation opportunities due to the diverse regulatory compliance needs of corporate security departments. This demand-side shift creates specific niches for specialized reporting and risk assessment tools.
For Market Incumbents:Entrench existing client relationships by aggressively integrating AI-driven predictive analytics into core platforms, countering the threat from specialized analytics startups. Deepen vertical integration into secure cloud hosting to ensure data sovereignty requirements, especially for critical infrastructure operators in Germany. Invest in R&D for interoperability standards to mitigate data silo challenges. Expand service offerings to include comprehensive training and simulation exercises for corporate security teams.
For New Entrants and Emerging Players:Modular, subscription-based incident management platforms for small and medium-sized enterprises represent the most penetrable entry point. Target underserved municipalities in the United States with cost-effective, cloud-based solutions for basic notification and resource coordination. A freemium model for essential features, coupled with premium upgrades for advanced analytics, offers a compelling go-to-market angle. Focus on specific compliance reporting for EU CSRD to gain initial traction.
For Investors and Strategic Acquirers:Capital-intensity ratios are inflecting upwards across advanced analytics and AI integration within incident management platforms, signaling long-term value creation. Companies specializing in crisis intelligence and supply chain resilience analytics represent attractive acquisition targets. The continued consolidation of cloud-based platform providers is a key signal to watch for market maturity. Focus on firms with strong intellectual property in predictive threat identification.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifying disparate systems enhances operational efficiency for government agencies. |
| AI-Driven Predictive Analytics | Anticipating threats proactively strengthens resilience for utilities providers. |
| Cyber Incident Response Expansion | Addressing digital asset protection meets growing corporate security needs. |
| SaaS Model Development | Lowering entry barriers expands market reach to smaller organizations. |
| Interoperability Standard Participation | Facilitating data exchange improves multi-agency coordinated response. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, industry whitepapers, and technology trend reports. Interviews with corporate security directors, government emergency managers, utility operations leads, and software architects informed market dynamics. This analysis integrated both bottom-up demand assessments and top-down supply-side validations. Data triangulation ensured robust market sizing and forecast accuracy.
Forecast inputs considered regulatory mandate impacts, technology adoption rates, and climate-related event frequency across the analysis window. The analytical framework modeled segments by solution type, deployment model, application, and end-user. Compound annual growth rates were derived from historical trends and projected technological advancements. Key industry-specific inputs included IoT sensor proliferation and smart city initiative rollouts.
Macroeconomic conditions sit as an overlay; deviation in global GDP growth or geopolitical stability would shift the trajectory. Forecasts reflect assumptions regarding technology integration and regulatory enforcement. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency and Disaster Management
Emergency Lighting Market
Emergency and Disaster Management
Emergency Shutdown System Market
Emergency and Disaster Management
Emergency Shower and Eyewash Station Market
Emergency and Disaster Management
Hazard Control Market
Emergency and Disaster Management
North America Homeland Security and Emergency Management Market
Emergency and Disaster Management
Outdoor Emergency Safety Shower Market
Emergency and Disaster Management
Crisis Emergency and Incident Management Platform Market
Emergency and Disaster Management
Intelligent Evacuation System Market
Emergency and Disaster Management
Global Emergency Medical Service (EMS) Products Market
Emergency and Disaster Management
Free Fall Lifeboats Market
Emergency and Disaster Management
Advanced Disaster Management Simulator Market
Emergency and Disaster Management
Lifeboat Market
Emergency and Disaster Management
Emergency and Disaster Response Market
Emergency and Disaster Management
Cyber Crisis Management Market
Emergency and Disaster Management
Earthquake Early Warning System Market
Emergency and Disaster Management
EHS Market